
 ECG Patch and Holter Monitor Market | 2026-2036
ECG Patch and Holter Monitor Market Size, Share, and Industry Trends Forecast 2026-2036
ECG Patch and Holter Monitor Market Intelligence
Flexible polymer substrates are expanding their share in ECG patch construction as manufacturers abandon rigid printed circuit boards to improve patient comfort and extend wear duration beyond fourteen days. Medtronic plc leverages its integrated manufacturing footprint to control electrode material sourcing and final assembly quality across multiple continents. iRhythm Technologies, Inc. differentiates through algorithm-intensive arrhythmia detection workflows that reduce clinician interpretation burden. Koninklijke Philips N.V. anchors its position in hospital telemetry through combined hardware and informatics platforms that span inpatient and ambulatory settings.
An ECG patch and Holter monitor comprises adhesive-backed electrodes, signal acquisition circuitry, and data storage or transmission modules designed to capture cardiac electrical activity over extended periods without restricting patient mobility. Typical devices sample at 128–1000 Hz with resolution of 12–16 bits, storing 1–14 days of single-lead to multi-lead data for subsequent clinician review or automated algorithmic analysis. Wireless patch products command attention for fastest expansion due to elimination of patient-carried recorders and direct cloud transmission, while continuous monitor segments sustain higher average selling prices in critical care environments where real-time alarm capability justifies premium positioning. Homecare settings represent an emerging demand vector as reimbursement shifts favor remote patient monitoring over facility-based testing.
The FDA governs device clearance through 510(k) and De Novo pathways, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for software-as-a-medical-device components that classify many algorithm-enhanced patches as Class IIa or higher. Japan's PMDA maintains distinct standards for electromagnetic compatibility and biocompatibility testing that shape product design for Asian market entry. Stakeholders must monitor evolving cybersecurity guidance from multiple regulators, as Bluetooth-enabled patches face escalating scrutiny for data integrity and patient privacy protection across connected health ecosystems.
Market Dynamics
Flexible printed circuit substrates are compressing device form factors while extending wear duration, fundamentally restructuring procurement criteria for ambulatory cardiac monitoring programs.
Growth Catalysts
- Extended Holter CPT codes:Medicare reimbursement pathways in the United States now cover fourteen-day patch monitoring, incentivizing hospital systems to shift diagnostic volume from inpatient telemetry to outpatient settings.
- Flexible polymer electrodes:Advances in biocompatible adhesive formulations enable seven-to-fourteen-day continuous skin contact without irritation, expanding candidacy for patients with sensitive skin or active lifestyles.
- Value-based care penalties:CMS readmission reduction programs push health systems toward proactive arrhythmia detection to avoid penalty exposure for cardiac-related returns.
Market Restraints
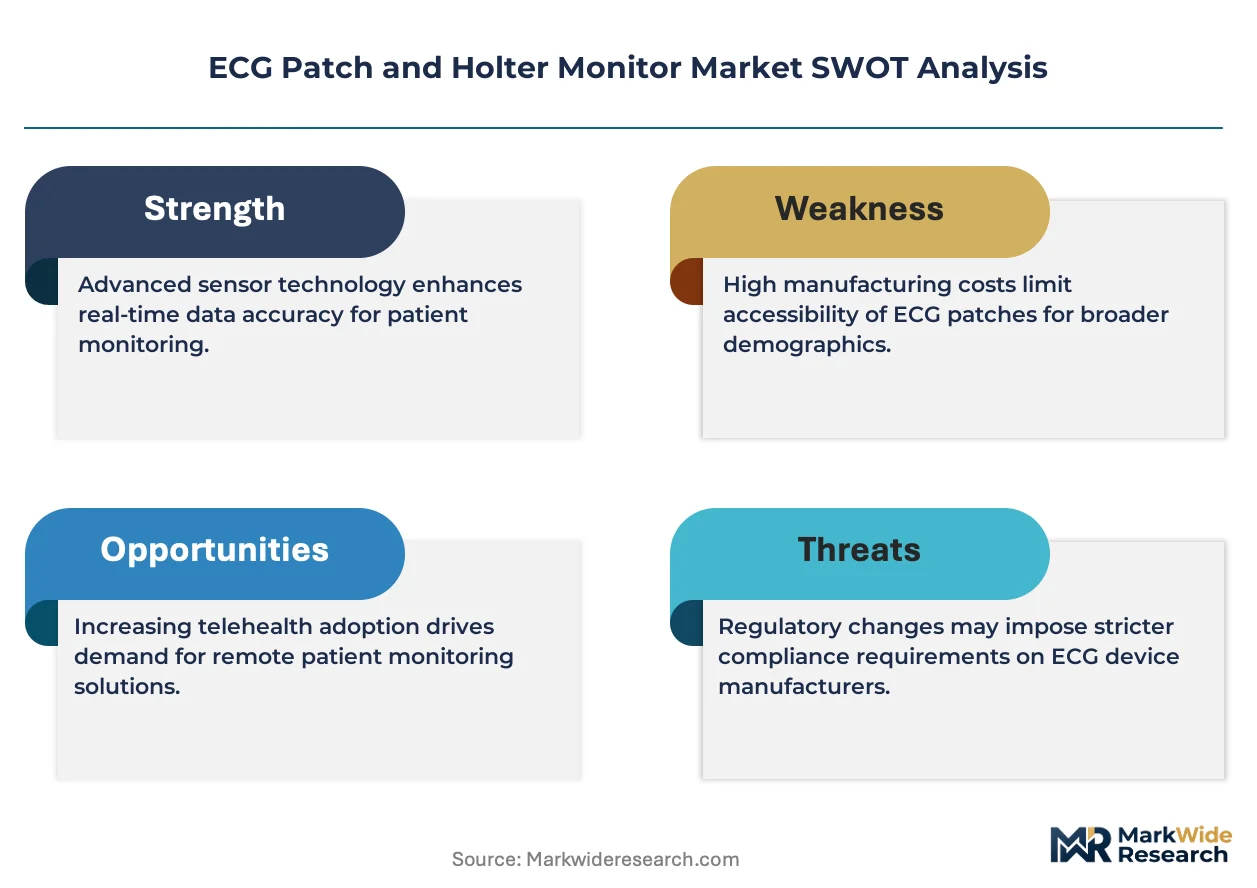
- Silver-silver chloride electrode cost volatility:Raw material price swings for conductive gel and electrode substrates compress margin structures for disposable patch manufacturers.
- Single-source ASIC dependency:Analog front-end integrated circuits for ECG signal conditioning concentrate among a handful of semiconductor foundries, creating supply vulnerability.
- EU MDR clinical evidence requirements:Stricter documentation burdens for algorithm-enhanced patches delay market entry and inflate regulatory compliance spend.
Strategic Opportunities
- Home-based post-ablation monitoring:Atrial fibrillation procedure growth creates demand for patient-managed rhythm surveillance outside traditional Holter lab workflows.
- AI-ECG pattern recognition:Machine learning integration with single-lead patch data enables predictive heart failure alerts before symptomatic decompensation.
- Direct-to-patient subscription channels:Telehealth platforms bypass traditional durable medical equipment distribution to capture recurring revenue from chronic disease management.
Industry Challenges
- Firmware validation timelines:FDA software-as-medical-device guidance requires extensive algorithm retraining documentation, stretching 510(k) clearance cycles.
- Bluetooth Low Energy security hardening:Cybersecurity guidance from multiple regulators demands encryption architecture redesigns for legacy patch platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ECG Patch and Holter Monitor Market |
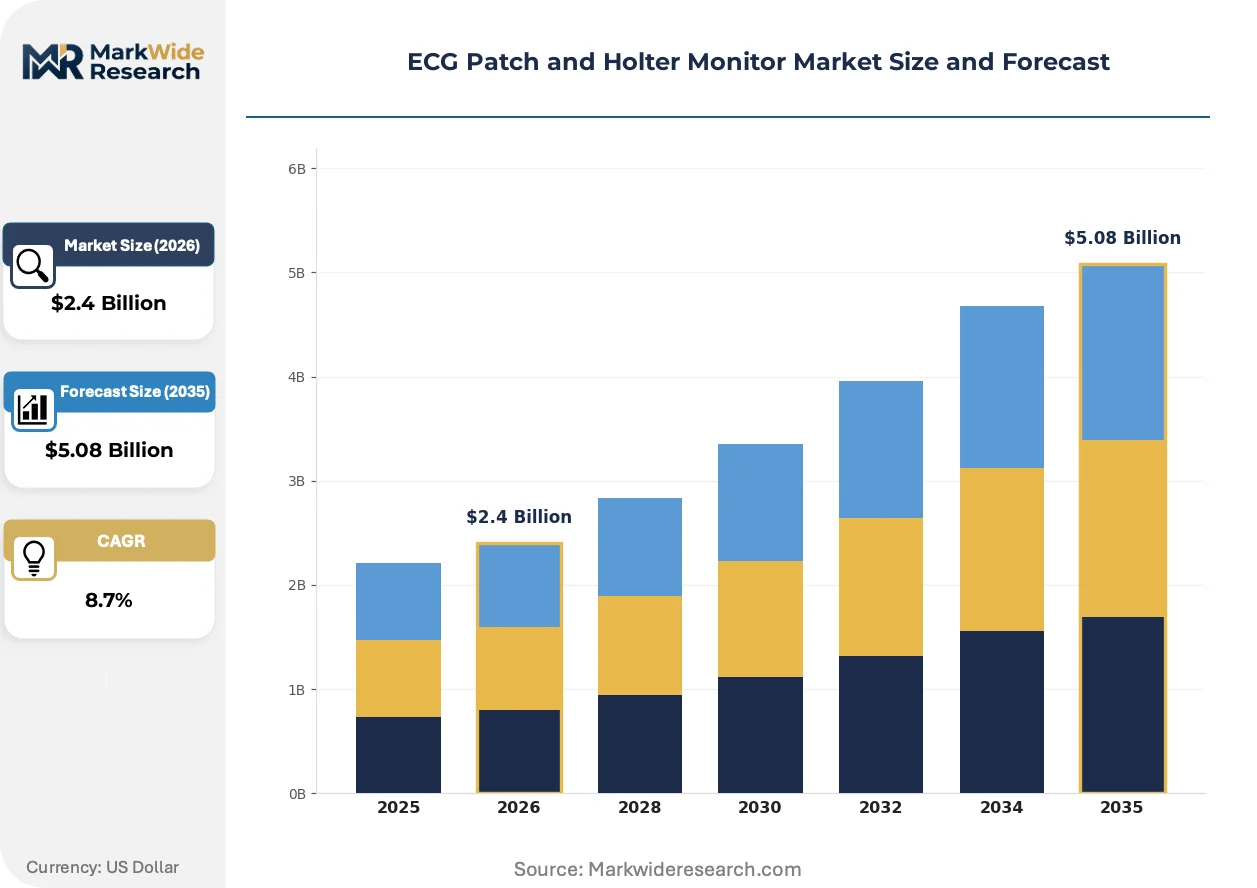
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Monitor, Continuous Monitor, Wireless Patch, Portable Device Application: Cardiac Monitoring, Arrhythmia Detection, Post-Surgery Recovery, Long-term Monitoring End User: Hospitals, Homecare Settings, Diagnostic Centers, Research Institutions Technology: Bluetooth, Telemedicine, Remote Monitoring, Data Analytics |
| Companies Covered | Medtronic plc, iRhythm Technologies, Inc., Hill-Rom, GE Healthcare, Koninklijke Philips N.V., Nihon Kohden Corporation, Fukuda Denshi Co., Ltd., Nissha Medical Technologies, Schiller AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ECG Patch and Holter Monitor Market Strategic Shifts & Innovations
Convergence of disposable hardware with cloud-native analytics is collapsing the traditional separation between data capture and clinical interpretation workflows.
Multi-lead flexible printed circuit assemblies are unifying spatial resolution with wearability by embedding three to six electrodes in a single adhesive substrate. Cardiology outpatient departments are piloting these configurations for ischemia detection previously requiring wired Holter systems. The technology is unifying diagnostic capability across ambulatory and acute settings, compressing capital equipment requirements for smaller hospitals.
The EU Medical Device Regulation's software classification rules are redefining algorithm-enhanced patches as Class IIa or higher devices, mandating clinical performance studies that legacy 510(k) clearances did not require. Manufacturers are restructuring quality management systems to address post-market surveillance obligations for machine learning components. Cardiac monitoring specialists with EU market exposure face the steepest compliance cost inflation.
Health system procurement departments are consolidating vendor relationships around platforms that combine hardware, cloud storage, and interpretation services in single contracts. Independent Holter scanning services face displacement as hospitals favor integrated solutions with guaranteed turnaround times. This concentration is most visible in United States integrated delivery networks consolidating spend across dozens of affiliated facilities.
ECG Patch and Holter Monitor Market Segmentation
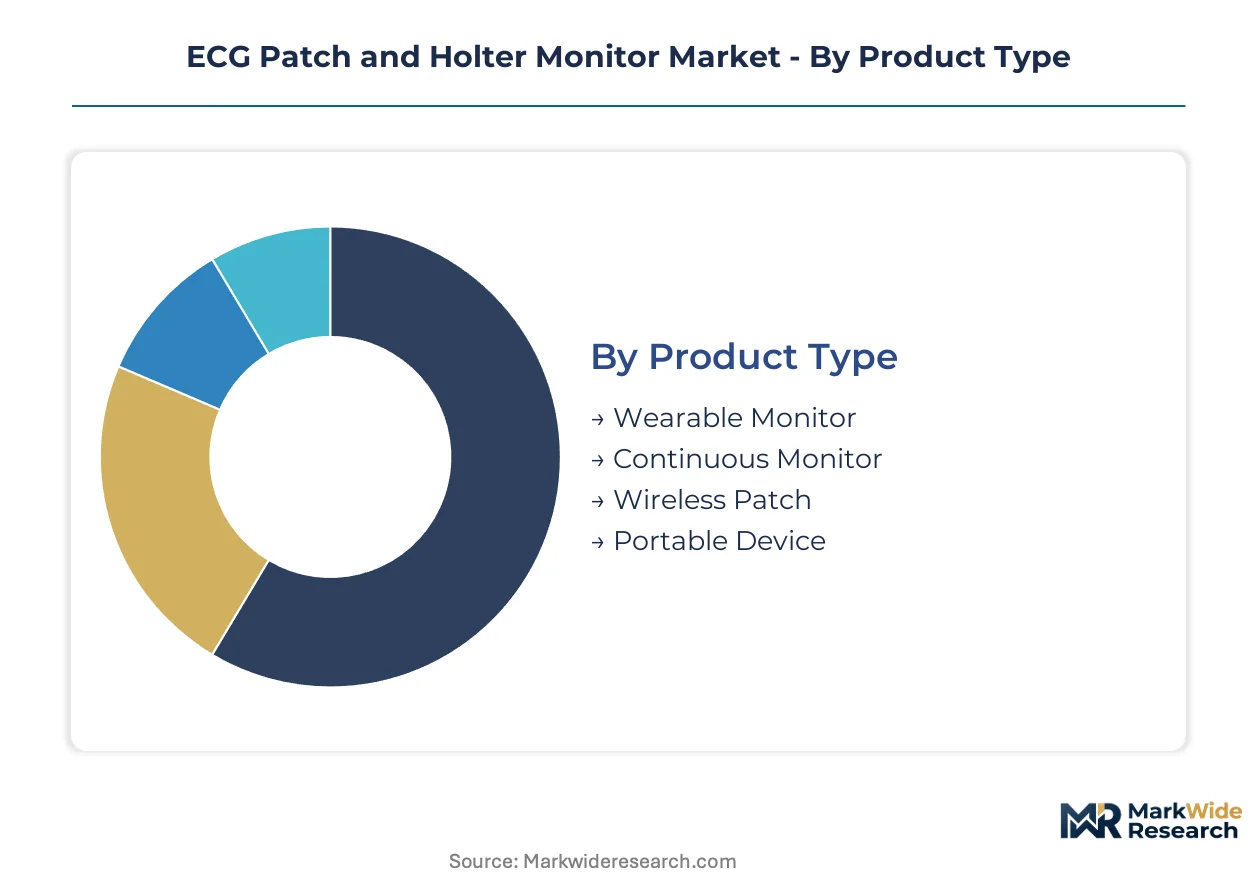
Procurement decisions in cardiac monitoring diverge sharply across care settings, with reimbursement pathways and patient mobility requirements dictating hardware specifications. Understanding how product architectures, clinical applications, and connectivity technologies partition demand enables vendors to align R&D investment with purchasing authority concentration.
Product Type:
Hospital procurement committees weight initial capital outlay against per-test operational economics when selecting device formats for ambulatory programs.
- Wearable Monitor:These devices integrate adhesive electrodes with patient-carried recorders, sampling at 128–1000 Hz across 24–48 hour studies. Demand concentrates in United States diagnostic centers where Medicare reimbursement for traditional Holter monitoring maintains favorable economics against patch alternatives.
- Wireless Patch:Single-use adhesive assemblies transmit encrypted ECG data directly to cloud platforms via Bluetooth Low Energy, eliminating patient-managed hardware. Homecare settings in Germany and the United Kingdom are expanding fastest here, driven by National Health Service pilot programs for post-discharge arrhythmia surveillance.
- Continuous Monitor:Multi-lead bedside systems with real-time alarm capability serve critical care units requiring immediate clinician notification of rhythm disturbances.
- Portable Device:Handheld or pocket-sized recorders with patient-activated symptom correlation target episodic palpitation documentation outside continuous monitoring protocols.
Volume sits with Wearable Monitors; growth tilts toward Wireless Patch configurations.
Application:
Clinical indication determines sensor array complexity, algorithm training requirements, and regulatory evidence thresholds for market authorization.
- Cardiac Monitoring:Broad-spectrum surveillance for known coronary disease or pre-operative clearance, typically employing single-lead configurations with 7–14 day wear duration. United States hospital systems facing CMS readmission penalties are deploying these for post-MI discharge protocols.
- Arrhythmia Detection:Algorithm-intensive workflows targeting atrial fibrillation burden quantification and cryptogenic stroke evaluation. Japanese cardiology departments are adopting AI-enhanced patches here, though PMDA software-as-medical-device classification extends clearance timelines versus FDA 510(k) pathways.
- Post-Surgery Recovery:Rhythm surveillance following cardiac ablation, valve replacement, or coronary bypass to detect procedural complications before symptomatic presentation.
- Long-term Monitoring:Extended surveillance exceeding 30 days for infrequent symptomatic events, bridging to implantable loop recorders when non-invasive methods fail.
Cardiac Monitoring commands installed base; Arrhythmia Detection is climbing the fastest as machine learning integration improves diagnostic yield per monitoring day.
End User:
Capital availability and reimbursement sophistication create distinct purchasing patterns across institutional and consumer-directed channels.
- Hospitals:Integrated delivery networks negotiate enterprise contracts spanning hardware, cloud storage, and interpretation services. These buyers prioritize alarm integration with existing telemetry infrastructure and guaranteed report turnaround times.
- Homecare Settings:Patient-managed monitoring outside facility walls requires simplified onboarding and robust connectivity. France's ANSM has streamlined clearance for Bluetooth-enabled patches here, accelerating telehealth platform adoption.
- Diagnostic Centers:Independent Holter laboratories focus on per-test cost minimization and technician workflow efficiency for high-volume scanning operations.
- Research Institutions:Academic medical centers demand raw data export capabilities and algorithm transparency for validation studies and proprietary analytics development.
Procurement concentrates in Hospitals; expansion tilts toward Homecare Settings as remote patient monitoring reimbursement matures.
Technology:
Connectivity architecture and data processing location determine cybersecurity exposure and regulatory classification complexity.
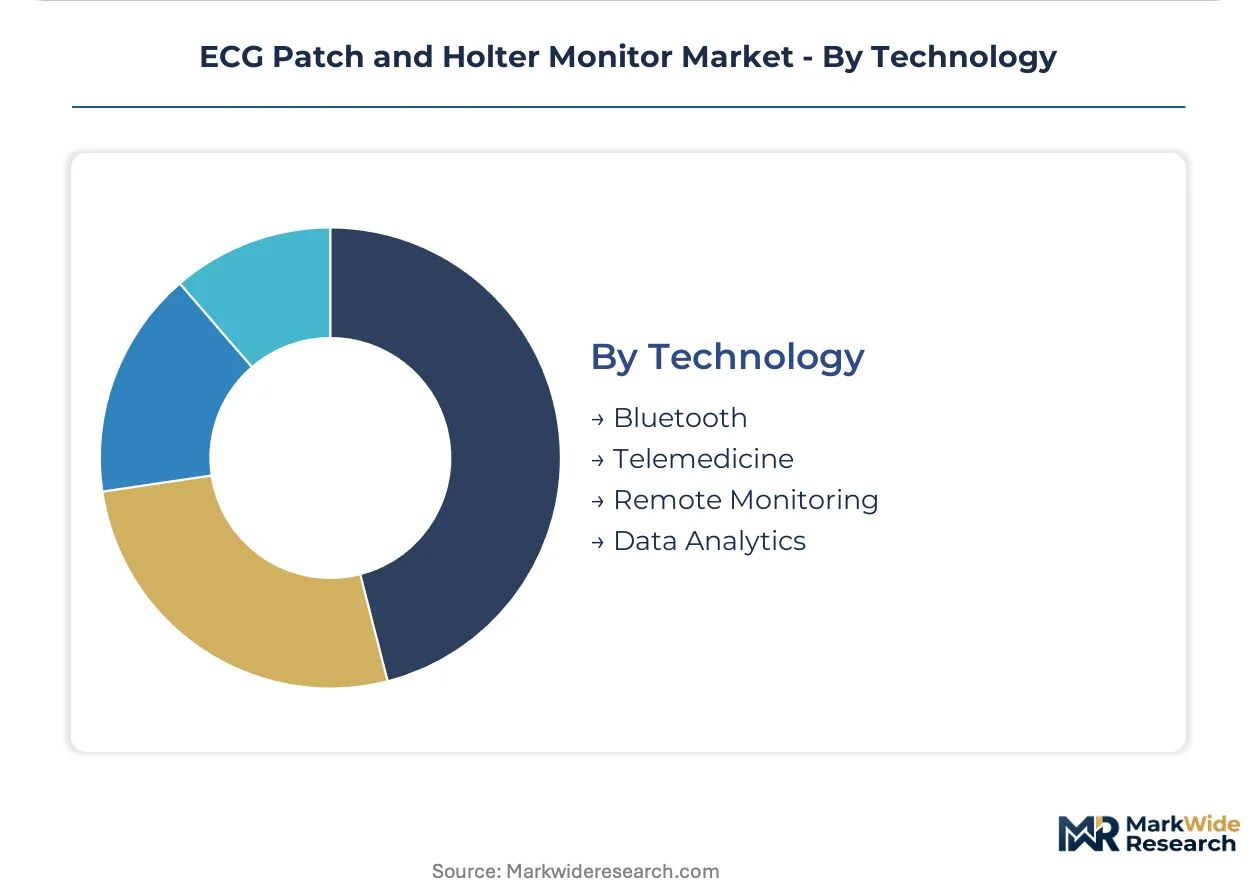
- Bluetooth:Short-range wireless transmission to patient smartphones or dedicated hubs. FDA cybersecurity guidance for premarket submissions has hardened encryption requirements here, forcing firmware redesigns for legacy platforms.
- Telemedicine:Integration with synchronous video consultation platforms enables real-time clinician-patient interaction during symptomatic episodes. United Kingdom NHS Digital certification programs are standardizing interoperability requirements.
- Remote Monitoring:Asynchronous data transmission to centralized interpretation services with structured reporting to ordering physicians.
- Data Analytics:Cloud-based algorithm execution for automated arrhythmia detection and trend analysis, triggering EU MDR Class IIa classification for software-as-medical-device components.
Bluetooth dominates device connectivity; Data Analytics is gaining share fastest as algorithmic interpretation displaces manual scanning workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized medical device zones in Massachusetts and Minnesota concentrate ECG patch and Holter monitor development, with tax incentives drawing electrode material suppliers and algorithm developers into tight geographic clusters.
United States
Medicare reimbursement codes for extended Holter monitoring drive hospital procurement of wireless patch systems. FDA 510(k) and De Novo pathways govern device clearance, with cybersecurity guidance hardening Bluetooth encryption requirements. The Minneapolis-St. Paul corridor hosts major electrode manufacturing and final assembly operations.
Germany
Hospital systems in Bavaria and North Rhine-Westphalia expand ambulatory cardiac monitoring to reduce readmission penalties under value-based care frameworks. EU Medical Device Regulation imposes Class IIa classification for algorithm-enhanced patches, mandating clinical performance studies. The Munich medical technology cluster integrates flexible printed circuit substrate development with cloud analytics platforms.
Japan
Aging demographics and atrial fibrillation procedure growth create demand for patient-managed rhythm surveillance. PMDA maintains distinct standards for electromagnetic compatibility and biocompatibility testing that shape product design for domestic market entry. The Osaka-Kobe manufacturing belt concentrates adhesive electrode production for Asian distribution.
United Kingdom
NHS Digital certification programs standardize interoperability requirements for Bluetooth-enabled patches in post-discharge arrhythmia surveillance. National Health Service pilot programs for remote patient monitoring accelerate telehealth platform adoption. The Cambridge life sciences cluster advances machine learning integration with single-lead patch data.
France
ANSM streamlined clearance pathways for Bluetooth-enabled patches accelerate homecare setting deployment outside traditional Holter lab workflows. Telehealth platforms bypass durable medical equipment distribution to capture recurring revenue from chronic disease management. The Paris-Saclay medical technology hub concentrates algorithm-intensive arrhythmia detection development.
ECG Patch and Holter Monitor Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated device makers commanding premium positioning in hospital telemetry while disposable patch fabricators compete on per-unit economics. The vendor base organizes around three archetypes: diversified medical technology conglomerates with captive distribution, algorithm-native digital health specialists, and component-focused electrode material suppliers. M&A activity concentrates on cloud analytics capabilities and flexible circuit manufacturing assets. Geographic expansion into Asia-Pacific markets represents the dominant competitive move as reimbursement frameworks mature outside North America and Europe.
Within the diversified medical technology tier, Medtronic plc and Koninklijke Philips N.V. exemplify integrated platform strategies spanning hardware, informatics, and interpretation services. iRhythm Technologies, Inc. occupies a distinct position as an algorithm-native specialist. These three entities represent contrasting approaches to value capture: captive electrode supply chains, combined inpatient-ambulatory telemetry ecosystems, and machine learning-intensive diagnostic workflows respectively.
| Leading Market Players |
|---|
| Medtronic plc |
| iRhythm Technologies, Inc. |
| Hill-Rom |
| GE Healthcare |
| Koninklijke Philips N.V. |
| Nihon Kohden Corporation |
| Fukuda Denshi Co., Ltd. |
| Nissha Medical Technologies |
| Schiller AG |
| Others |
Cost & Logistics Intelligence
Flexible-rigid substrate bifurcation separates premium multi-day wearable patches from commodity 24-hour Holter configurations, concentrating margin capture with electrode material suppliers in Minnesota and Massachusetts while disposable patch assemblers in Mexico and Malaysia compete on unit economics. FDA cybersecurity tiers and EU MDR software classification create compliance cost ladders that reshape procurement decisions across hospital systems and homecare channels alike.
Pricing Analysis
Volume concentrates in per-unit transactional models for disposable wireless patches, while subscription-based SaaS tiers for cloud analytics and algorithmic interpretation command sustained margin expansion. Price differentiation rests on FDA clearance tier and algorithm training dataset scale, with 510(k) pathways separating premium AI-enhanced offerings from standard event-detection configurations. Cost compression in silver-silver chloride electrode sourcing is intensifying as conductive gel suppliers consolidate, pressuring disposable manufacturers. Diagnostic centers exhibit highest price sensitivity due to per-test reimbursement economics, whereas integrated delivery networks prioritize guaranteed turnaround over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from hospital procurement committees require qualified backup suppliers for analog front-end ASICs, forcing relationships with both domestic and Asian semiconductor foundries. Manufacturing gravity centers on the United States, Germany, and Japan for final assembly, while China and South Korea dominate flexible printed circuit substrate fabrication. Raw material dependencies span silver-silver chloride electrodes, biocompatible adhesives, and lithium-polymer cells. Single-source vulnerability in signal conditioning chip supply creates qualification bottlenecks. Distribution runs through group purchasing organizations and direct hospital contracts in North America, with European channels emphasizing telehealth platform integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ECG patch and Holter monitor sector sits at a substrate-transition inflection, with flexible printed circuit assemblies displacing rigid PCB legacy platforms across ambulatory monitoring programs.
For Market Incumbents: Hedge electrode material cost exposure through backward integration into silver-silver chloride sourcing or long-term offtake agreements with Minnesota-based suppliers. Consolidate algorithm development capabilities to defend against AI-native entrants exploiting FDA software-as-medical-device guidance gaps. Prioritize EU MDR quality management system restructuring to maintain market access as Class IIa classification tightens. For New Entrants and Emerging Players: Direct-to-patient subscription channels offer the most penetrable route, bypassing GPO-dominated hospital procurement and capturing recurring revenue from chronic atrial fibrillation management. Target post-ablation home monitoring workflows where patient onboarding simplicity outweighs established brand recognition. Pursue ANSM streamlined clearance pathways in France to accelerate European market entry ahead of MDR compliance cost inflation. For Investors and Strategic Acquirers: Re-rating potential sits with algorithm-native specialists given Medicare reimbursement expansion for extended Holter monitoring and AI-ECG pattern recognition adoption. Long-term viability favors entities with integrated hardware-software platforms spanning inpatient telemetry and ambulatory settings. Watch FDA De Novo clearance velocity for multi-lead flexible patches as inflection indicator for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Quality System Restructuring | Class IIa software classification mandates clinical performance studies for algorithm-enhanced patches. |
| FDA Cybersecurity Premarket Hardening | Bluetooth Low Energy encryption redesigns extend 510(k) clearance cycles for legacy platforms. |
| Flexible Circuit Manufacturing Acquisition | Multi-day wearability requirements compress form factors beyond rigid PCB capabilities. |
| Hospital System Enterprise Contracting | Integrated delivery networks consolidate spend across hardware, cloud storage, and interpretation services. |
| Direct-to-Patient Subscription Launch | Telehealth platforms bypass durable medical equipment distribution for chronic disease management revenue. |
Research Approach
Independent corroboration across hospital purchasing committee interviews, biomedical engineer consultations, and GPO contracts managers underwrites the qualitative findings. Primary fieldwork engaged regulatory affairs specialists at FDA-cleared manufacturers and reimbursement strategists navigating CMS code updates. Secondary validation drew from FDA 510(k) and De Novo databases, EU MDR notified body documentation, and CMS Medicare reimbursement schedules. Bottom-up patch shipment estimates triangulated against top-down hospital telemetry capital expenditure surveys.
Rate-of-change decomposition across the analysis window isolates volume drivers by product architecture, connectivity technology, and end-user procurement sophistication. Segmentation modeling spans wearable monitor, wireless patch, continuous monitor, and portable device formats, crossed with cardiac monitoring, arrhythmia detection, and post-surgery recovery applications. CAGRs derive from fitted adoption curves incorporating reimbursement pathway maturation and algorithmic diagnostic yield improvements. Forecast inputs include silver electrode material cost indices and PMDA software classification timeline assumptions.
The model holds under stable Medicare reimbursement and EU MDR implementation pace; deviation in FDA cybersecurity guidance stringency or conductive gel supply disruption would shift volume and value projections materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Supraglottic Airway Devices Market
Medical Devices
France Spinal Surgery Devices Market
Medical Devices
Hearing Aid Dehumidifier Market
Medical Devices
Global Robotic Assisted Surgery Systems Market
Medical Devices
Wheelchair and Components Market
Medical Devices
Seizure Detection Devices Market
Medical Devices
Ventilation Devices Market
Medical Devices
Europe Viscosupplementation Market
Medical Devices
Corneal Cross Linking Devices Market
Medical Devices
Gastric Space-Occupying Devices Market
Medical Devices
Needle-Free IV Connectors Market
Medical Devices
Asia-Pacific Antimicrobial Coating for Medical Devices Market
Medical Devices
Baby Warmer Devices Market
Medical Devices
Skull Clamp Market
Medical Devices
Mhealth (Mobile Health) Devices Market
Medical Devices
Epidural Anesthesia Sets Market