
 Asia-Pacific Antimicrobial Coating for Medical Devices Market | 2026-2036
Asia-Pacific Antimicrobial Coating for Medical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Antimicrobial Coating for Medical Devices Market Outlook
Chinese coating formulators is expanding production capacity for silver-ion antimicrobial layers serving domestic catheter and implant manufacturers. DSM Biomedical leverages its polymer science heritage to anchor premium positions in implantable device coatings across Japan and South Korea. PPG Industries competes through industrial-scale spray and dip coating infrastructure that sustains cost advantages for high-volume surgical instrument programs. Akzo Nobel specializes in copper-based formulations that differentiate against silver-dominant portfolios in price-sensitive Indian hospital procurement.
Asia-Pacific antimicrobial coating for medical devices comprises functional surface treatments engineered with silver ions, copper particles, zinc oxide, or quaternary ammonium polymers deposited at thicknesses typically ranging from 1 to 10 micrometers to inhibit bacterial colonization on implanted or inserted medical equipment. These coatings are manufactured through spray, dip, electrophoretic, or vapor deposition methods to achieve conformal coverage on complex geometries such as catheter lumens and orthopedic fixation hardware. Silver-based coatings occupy the largest revenue share due to established clinical efficacy against gram-positive and gram-negative pathogens, while polymer-based alternatives represent the fastest-expanding category as drug-eluting and combination therapies gain traction in cardiovascular and orthopedic applications. Catheters generate the highest absolute coating volume, though implant applications command superior margin pools because of longer regulatory validation cycles and higher performance specifications.
Japan's PMDA enforces biocompatibility standards under the Pharmaceutical and Medical Device Act that require extensive cytotoxicity and sensitization testing before coating modifications reach clinical use. China's NMPA aligns with GB/T 16886 biological evaluation protocols and accelerates review pathways for domestically manufactured antimicrobial devices under national innovation policies. India's CDSCO mandates import licensing and local clinical data for coated implants, creating compliance thresholds that favor regional coating suppliers with established regulatory dossiers. Stakeholders must monitor divergence between national pharmacopeia standards and harmonized ISO 10993 frameworks to anticipate where testing redundancy will add cost or delay market entry.
Market Dynamics
Catheter manufacturers across China, India, and Japan are accelerating procurement of silver-ion and polymer-based antimicrobial layers as hospital-acquired infection protocols tighten and domestic production scales.
Growth Catalysts
- Silver-ion coating efficacy:Established clinical performance against gram-positive and gram-negative pathogens drives catheter and implant adoption across tertiary hospitals in China and Japan.
- NMPA accelerated review pathways:China's national innovation policies compress regulatory timelines for domestically manufactured antimicrobial devices, incentivizing local coating capacity expansion.
- Eastern province manufacturing clusters:Concentrated medical device production in Jiangsu and Zhejiang provinces generates concentrated demand for regional coating supply.
Market Restraints
- Silver price volatility:Fluctuations in precious metal commodity markets compress margins for silver-dominant coating portfolios.
- PMDA biocompatibility testing:Extensive cytotoxicity and sensitization requirements under Japan's Pharmaceutical and Medical Device Act extend validation cycles for coating modifications.
- Copper-based substitution pressure:Price-sensitive Indian hospital procurement increasingly favors copper formulations that undercut silver-based alternatives on unit cost.
Strategic Opportunities
- Drug-eluting polymer convergence:Combination therapies integrating antimicrobial and pharmaceutical release functions open premium positioning in cardiovascular applications.
- South Korean implant market:Underpenetrated orthopedic fixation hardware coating demand offers expansion paths for suppliers with ISO 10993 dossiers.
- CDSCO local clinical data requirements:India's import licensing mandates for coated implants create first-mover advantages for regional suppliers establishing regulatory dossiers.
Industry Challenges
- ISO 10993 testing redundancy:Divergence between national pharmacopeia standards and harmonized frameworks adds cost and delays multi-country market entry.
- Electrophoretic deposition capex:Conformal coating of complex catheter lumens requires specialized equipment that strains mid-tier formulator balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Antimicrobial Coating for Medical Devices Market |
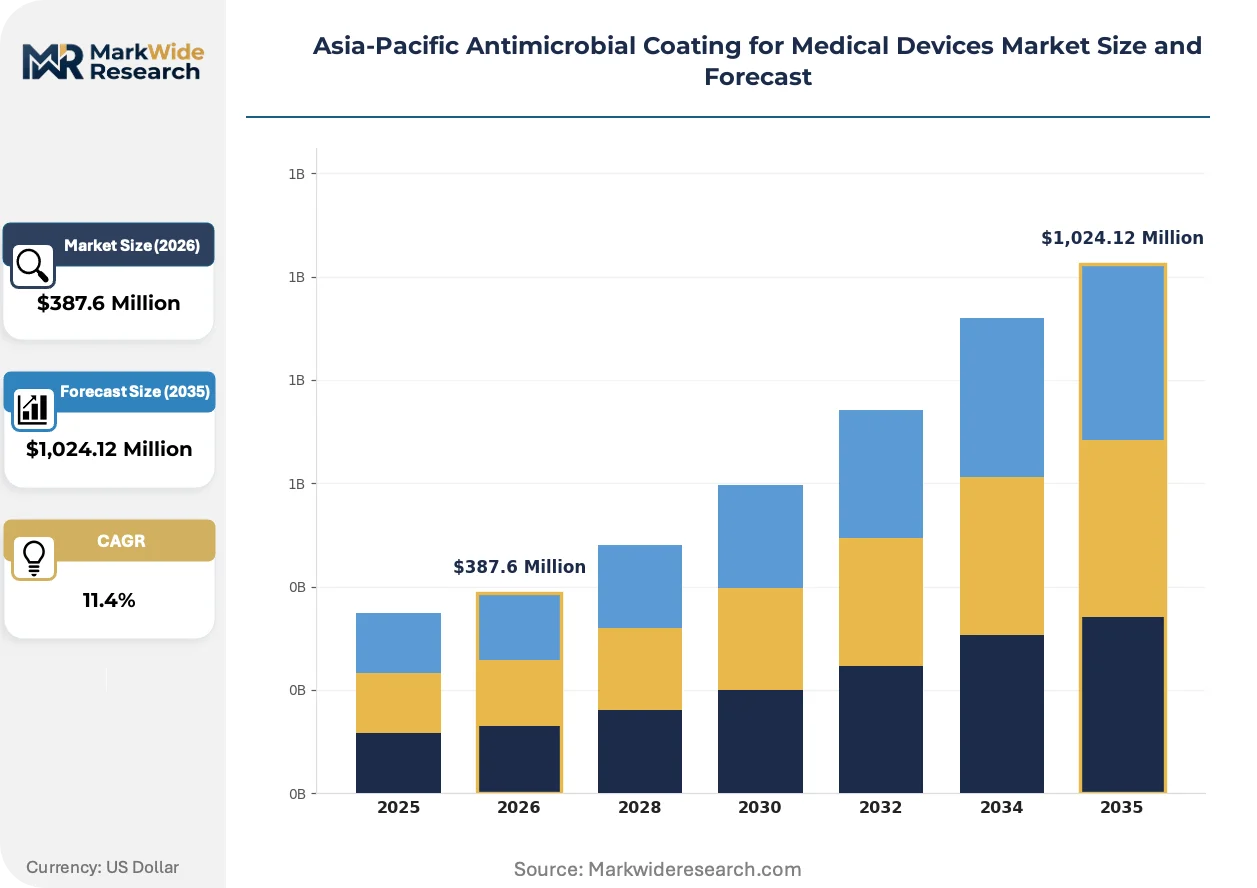
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silver-based Coatings, Copper-based Coatings, Zinc-based Coatings, Polymer-based Coatings End User: Hospitals, Clinics, Nursing Homes, Outpatient Surgical Centers Delivery Mode: Spray Coating, Dip Coating, Electrophoretic Deposition, Vapor Deposition Application: Implants, Surgical Instruments, Catheters, Diagnostic Devices |
| Companies Covered | DSM Biomedical, PPG Industries, Covalon Technologies, AST Products, Akzo Nobel, Specialty Coating Systems, Hydromer, BioInteractions, Sciessent, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Antimicrobial Coating for Medical Devices Market Strategic Shifts
Coating chemistry is converging with pharmaceutical delivery systems while regulatory frameworks fragment across national jurisdictions, compressing product development timelines and reshaping competitive positioning.
Quaternary ammonium polymer coatings are integrating drug-eluting functionalities to deliver sustained antimicrobial release from cardiovascular stents and orthopedic implants. Japanese and South Korean device manufacturers are piloting these hybrid formulations in coronary applications. This convergence is integrating coating suppliers deeper into pharmaceutical supply chains and extending validation requirements beyond traditional surface engineering.
China's NMPA alignment with GB/T 16886 biological evaluation protocols is tightening while maintaining accelerated domestic innovation pathways. Device makers must now navigate parallel testing requirements that exceed ISO 10993 baselines for imported coatings. Catheter programs targeting Chinese hospitals face extended pre-market timelines unless sourcing from pre-qualified regional suppliers.
Hospital procurement committees in India and Southeast Asia are unbundling coating specifications from device tenders, enabling direct supplier relationships previously intermediated by OEMs. This disintermediation concentrates purchasing power in group purchasing organizations and demands coating formulators build clinical sales capabilities. The shift is most visible in Indian tertiary hospital networks negotiating copper-based coating supply agreements independent of catheter manufacturers.
Asia-Pacific Antimicrobial Coating for Medical Devices Market Segmentation
Antimicrobial coating procurement patterns diverge sharply across product chemistries, end-user settings, and application requirements. Suppliers must align formulation portfolios with the specific sterilization protocols, regulatory pathways, and performance specifications that dominate each segment.
Product Type:
Silver-ion formulations concentrate manufacturing capacity among Jiangsu and Zhejiang chemical clusters serving domestic catheter producers.
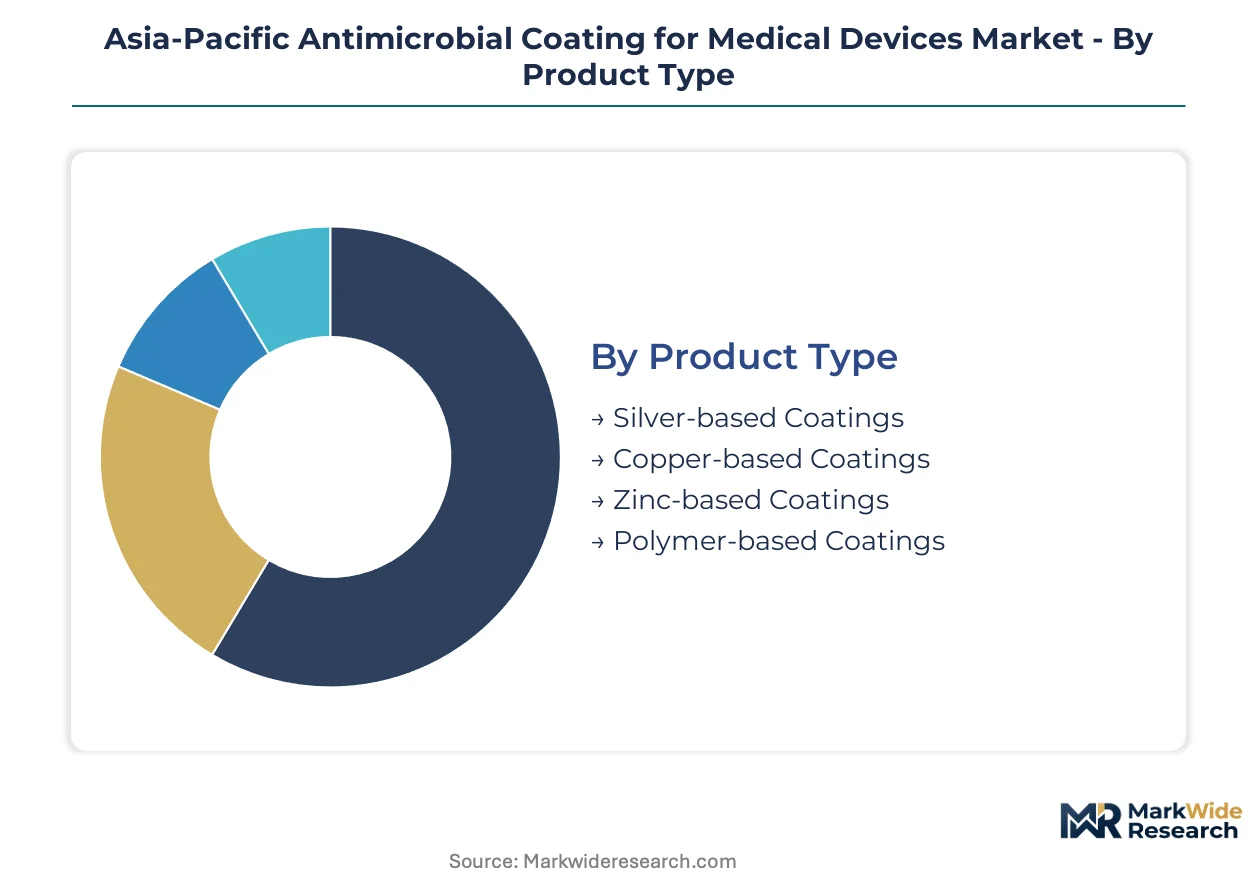
- Silver-based Coatings:Ion-release mechanisms engineered at 1-10 micrometer thicknesses deliver sustained antimicrobial efficacy against gram-positive and gram-negative pathogens. Jiangsu province chemical manufacturers supply tertiary hospitals across China and Japan where catheter-associated infection protocols mandate proven clinical track records.
- Polymer-based Coatings:Quaternary ammonium and drug-eluting matrices enable combination therapies releasing both antimicrobial and pharmaceutical agents. South Korean cardiovascular stent manufacturers and Japanese orthopedic implant producers drive fastest adoption as hybrid formulations integrate into next-generation device platforms.
- Copper-based Coatings:Particle-embedded formulations priced below silver alternatives attract Indian hospital procurement committees.
- Zinc-based Coatings:Oxide nanoparticle dispersions serve niche diagnostic device applications requiring optical transparency.
Today's leader: Silver-based Coatings. Tomorrow's challenger: Polymer-based Coatings.
End User:
Procurement authority concentrates in tertiary hospital networks with dedicated infection control committees and bulk purchasing leverage.
- Hospitals:Tertiary medical centers in China's eastern provinces and Japan's urban corridors generate highest absolute coating volume through catheter and implant programs. NMPA and PMDA biocompatibility requirements favor suppliers with pre-qualified regulatory dossiers.
- Outpatient Surgical Centers:Ambulatory facilities across India and Southeast Asia represent expanding demand as same-day procedures multiply and coating specifications unbundle from device tenders into direct supplier relationships.
- Clinics:Primary care settings in rural China and India prioritize cost-minimized copper formulations over premium silver alternatives.
- Nursing Homes:Long-term care facilities in Japan's aging prefectures adopt coated urinary catheters under national infection prevention guidelines.
Volume concentrates in Hospitals. Growth accelerates fastest in Outpatient Surgical Centers.
Delivery Mode:
Equipment capital requirements stratify the supplier base between industrial-scale coaters and specialized deposition specialists.
- Spray Coating:Automated line systems achieve high-throughput coverage of surgical instrument surfaces at thickness tolerances suitable for non-implant applications. PPG Industries and similar industrial coaters dominate this segment through scale economies.
- Electrophoretic Deposition:Conformal coating of complex catheter lumens and orthopedic hardware geometries requires specialized rectifier systems and bath chemistry control. Mid-tier formulators face balance sheet strain from seven-figure capital equipment investments.
- Dip Coating:Batch-process immersion suits low-volume implant programs and prototyping cycles.
- Vapor Deposition:Physical and chemical vapor methods deliver ultra-thin films for diagnostic device optical components.
Spray Coating commands current volume. Electrophoretic Deposition captures premium positioning.
Application:
Margin pools diverge between high-volume consumables and validated implant platforms with extended regulatory cycles.
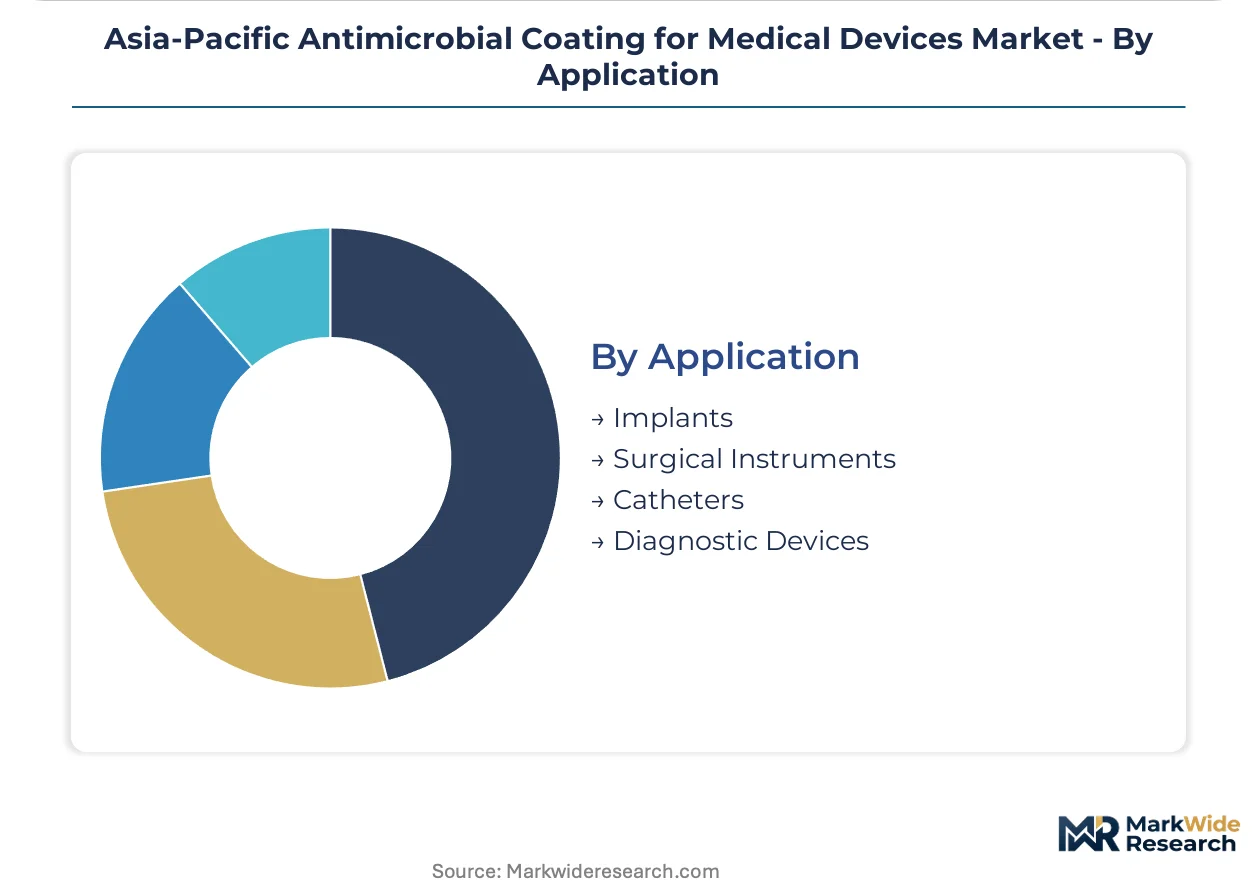
- Catheters:Urinary and vascular catheter programs generate largest absolute coating consumption across China, India, and Japan. Silver-ion formulations dominate as hospitals implement catheter-associated urinary tract infection reduction protocols.
- Implants:Orthopedic fixation hardware and cardiovascular stents command superior margins due to ISO 10993 validation requirements and longer regulatory timelines. South Korean and Japanese device makers drive demand for drug-eluting polymer convergence.
- Surgical Instruments:Scalpel and forceps coating programs prioritize spray-applied cost efficiency over pharmaceutical integration.
- Diagnostic Devices:Endoscope and sensor applications require optically transparent zinc oxide formulations.
Catheters dominate volume. Implants dominate value capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are pulling antimicrobial coating production toward jurisdictions where NMPA accelerated pathways offset PMDA validation burdens, concentrating investment in China's eastern manufacturing corridors while Japanese device makers source premium formulations domestically.
China
Jiangsu and Zhejiang province chemical clusters supply silver-ion formulations to domestic catheter manufacturers scaling under NMPA innovation policies. The regulator compresses review timelines for domestically produced antimicrobial devices, incentivizing local coating capacity expansion. Suzhou and Hangzhou medical device production zones generate concentrated procurement demand as hospital-acquired infection protocols tighten across tertiary hospitals.
Japan
PMDA biocompatibility requirements under the Pharmaceutical and Medical Device Act extend validation cycles for coating modifications, favoring incumbent suppliers with established cytotoxicity dossiers. Tokyo and Osaka medical device manufacturers anchor premium implant coating demand. Kansai region orthopedic and cardiovascular producers drive adoption of drug-eluting polymer convergence technologies.
India
CDSCO import licensing mandates and local clinical data requirements for coated implants create compliance thresholds favoring regional suppliers with regulatory dossiers. Mumbai and Delhi tertiary hospital procurement committees unbundle coating specifications from device tenders, enabling direct supplier relationships. Price-sensitive purchasing increasingly favors copper-based formulations over silver alternatives.
South Korea
MFDS alignment with ISO 10993 frameworks supports underpenetrated orthopedic fixation hardware coating demand. Seoul Capital Area device manufacturers pilot quaternary ammonium polymer drug-eluting formulations in cardiovascular applications. Busan-Ulsan chemical processing infrastructure enables regional coating formulator expansion.
Australia
TGA biological evaluation protocols for antimicrobial device coatings maintain harmonized testing requirements with ISO 10993 baselines. Sydney and Melbourne hospital networks implement catheter-associated infection reduction protocols driving silver-based coating procurement. Local production remains limited, with supply dependence on Asian import channels.
Asia-Pacific Antimicrobial Coating for Medical Devices Market Competitive Environment
Chinese chemical manufacturers anchor volume-tier supply; Japanese and European specialists hold premium-tier positions through polymer science heritage and regulatory dossier depth. The supplier base stratifies between industrial-scale coaters with spray and dip infrastructure and specialized deposition shops serving complex catheter geometries. Three archetypes dominate: commodity silver-ion formulators, drug-eluting polymer integrators, and copper-based cost competitors. Capacity expansion and strategic partnerships with device OEMs constitute the dominant competitive vectors.
Within the premium polymer tier, DSM Biomedical occupies a position exemplifying science-driven implant coating heritage across Japan and South Korea. PPG Industries anchors industrial-scale spray and dip coating supply for high-volume surgical instrument programs. Akzo Nobel represents copper-based formulation specialization targeting price-sensitive Indian hospital procurement. These three entities illustrate how geographic origin and stated industrial focus map onto divergent market tiers without requiring specific operational claims.
| Leading Market Players |
|---|
| DSM Biomedical |
| PPG Industries |
| Covalon Technologies |
| AST Products |
| Akzo Nobel |
| Specialty Coating Systems |
| Hydromer |
| BioInteractions |
| Sciessent |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between ISO 10993-validated implant coatings and commodity silver-ion catheter layers manifests in parallel supply chain configurations across the Asia-Pacific antimicrobial coating market. Jiangsu and Zhejiang chemical clusters feed price-sensitive domestic catheter producers while Japanese and South Korean device makers source premium polymer formulations through qualified supplier networks with established PMDA and MFDS dossiers.
Pricing Analysis
Distributor margins for imported coatings in India and Southeast Asia compress landed costs by 12-18 percent against direct OEM supply arrangements in China and Japan. Three-tier pricing structure across premium, standard, and economy levels tracks ISO 10993 validation depth, with drug-eluting polymer coatings commanding substantial premiums over silver-ion alternatives. Cost compression in copper-based formulations is intensifying because Indian hospital procurement committees unbundle coating specifications from device tenders. Primary care clinics in rural China and India exhibit highest price sensitivity, while Japanese orthopedic implant manufacturers demonstrate lowest elasticity due to regulatory switching costs.
Supply Chain Analysis
China's NMPA domestic-content mandates for accelerated antimicrobial device approvals are reshaping sourcing patterns toward Jiangsu and Zhejiang chemical manufacturers. Raw material flows draw from Australian silver concentrate, Chilean copper cathode, and domestic Chinese zinc oxide refineries. Single-source vulnerability concentrates in silver-ion precursor supply where Jiangsu province formulators control regional capacity. Distribution runs through medical device OEM procurement departments in tertiary hospital corridors, with emerging direct-supplier relationships penetrating Indian outpatient surgical networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where catheter-associated infection protocol tightening across Chinese and Japanese tertiary hospitals shifts procurement authority toward coating suppliers with pre-qualified regulatory dossiers.
For Market Incumbents: Deploy ISO 10993 dossier depth as a switching-cost barrier against emerging Chinese chemical manufacturers. Incumbents should anchor capacity expansion in South Korean orthopedic fixation corridors where MFDS alignment creates first-mover advantages, while simultaneously deepening polymer science R&D to defend margin pools against copper-based substitution pressure in Indian procurement.
For New Entrants and Emerging Players: Begin with electrophoretic deposition specialization for complex catheter lumen geometries where mid-tier formulators face balance sheet constraints. South Korean cardiovascular stent manufacturers represent the most penetrable white-space target given underpenetrated drug-eluting polymer demand. A direct clinical sales capability build-out targeting Indian tertiary hospital procurement committees offers the strongest go-to-market angle.
For Investors and Strategic Acquirers: Consolidation pressure builds where regulatory dossier redundancy across PMDA, NMPA, and CDSCO frameworks strains mid-cap balance sheets. Long-term viability centers on acquiring formulators with validated implant coating platforms and existing OEM partnerships rather than commodity silver-ion capacity. The signal to watch is NMPA acceleration pathway tightening that would disadvantage import-dependent coating suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Dossier Expansion | Pre-qualified NMPA and PMDA submissions compress hospital procurement validation timelines for coating suppliers. |
| Polymer Science R&D Investment | Drug-eluting antimicrobial convergence opens premium positioning in Japanese cardiovascular stent applications. |
| Electrophoretic Deposition Capacity | Conformal catheter lumen coating capability addresses ISO 10993 testing redundancy cost pressures. |
| Direct Hospital Procurement Relationships | Unbundled coating specifications in Indian tertiary networks disintermediate traditional OEM channel control. |
| Copper Formulation Scale-Up | Price-sensitive Indian hospital procurement creates volume-tier positioning against silver-dominant competitors. |
Study Parameters
Direct dialogue with catheter procurement managers, biomedical engineers at tertiary hospital networks, coating formulator technical directors, and GPO contracts specialists grounded qualitative assessment. Secondary validation drew from NMPA approval databases, PMDA biocompatibility guidance documents, CDSCO import licensing records, and hospital procurement tender archives. Bottom-up coating volume estimates triangulated against top-down medical device production data across the analysis window.
Bottom-up modeling anchored forecasts in catheter and implant device production trajectories across China, Japan, India, and South Korea. Segmentation dimensions spanned coating chemistry, application type, delivery mode, and end-user facility tier. CAGRs were derived from regression analysis against hospital-acquired infection protocol implementation timelines and regulatory review pathway adjustments. Silver commodity price volatility and electrophoretic deposition equipment capex cycles served as industry-specific forecast sensitivity inputs.
Several conditions sit outside the modeled scope, including unforeseen PMDA biocompatibility standard revisions, abrupt silver price dislocations, and novel antimicrobial technologies displacing established ion-release mechanisms. Forecasts reflect documented assumptions regarding NMPA acceleration pathway continuity and CDSCO import licensing stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
North America Medical Devices Market
Medical Devices
Electroencephalogram (EEG) Caps Market
Medical Devices
Drug Device Combination Products Market
Medical Devices
Left Atrial Appendage Devices Market
Medical Devices
Spinal Trauma Devices Market
Medical Devices
France Ophthalmic Devices Market
Medical Devices
Brachytherapy Afterloaders Market
Medical Devices
Middle East Ultrasound Devices Market
Medical Devices
Coated Endotracheal Tube Market
Medical Devices
Saudi Arabia Anesthesia Devices Market
Medical Devices
Catheter Coatings Market
Medical Devices
Drainage Catheters Market
Medical Devices
North America Sperm Separation Devices Market
Medical Devices
Spinal Cord Stimulators Market
Medical Devices
Intravaginal Device Market
Medical Devices
Robotic Angiography Systems Market