
 France Spinal Surgery Devices Market | 2026-2036
France Spinal Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
France Spinal Surgery Devices Market Foresight
Consolidation among public hospital purchasing groups is recalibrating vendor negotiation dynamics across France's spinal device supply chain. Medtronic plc leverages its broad fusion portfolio to sustain multi-year supply agreements with the country's largest university hospital networks. Stryker Corporation competes through specialized navigation and imaging guidance systems that anchor its position in high-complexity deformity centers.
France spinal surgery devices encompass implantable hardware, instrumentation, and intraoperative technologies engineered from titanium alloys, polyetheretherketone, and biocompatible ceramics to stabilize, decompress, or preserve motion in the vertebral column. These systems integrate with neuromonitoring platforms to reduce iatrogenic nerve injury during thoracolumbar approaches. Spinal fusion implants dominate current procedural volumes, while robotic assistance systems represent the fastest-growing technology segment as French teaching hospitals expand capital budgets for precision instrumentation. Motion preservation devices occupy a narrower but higher-margin niche serving younger patient cohorts with isolated disc pathology.
ANSM enforces CE marking under the EU Medical Device Regulation alongside France-specific vigilance reporting for implantable spinal constructs, tightening market access for non-compliant manufacturers. The EU Green Deal's sustainable procurement criteria now influence hospital tender evaluations, favoring suppliers with validated recycling pathways for metallic implant waste. Stakeholders must monitor how France's national health insurance reimbursement revisions for outpatient spinal procedures reshape site-of-care economics and device selection criteria.
Market Dynamics
Public hospital procurement consolidation across Île-de-France and Auvergne-Rhône-Alpes is compressing vendor margins and forcing suppliers to restructure pricing frameworks around multi-year framework agreements rather than transactional sales.
Growth Catalysts
- EU Medical Device Regulation (MDR):Enhanced CE marking requirements for implantable spinal constructs are filtering out marginal competitors and concentrating volume among compliant manufacturers with established notified body relationships.
- Academic medical institutes:Complex deformity correction and revision surgery volumes are rising as France's aging population drives degenerative spinal condition prevalence, expanding addressable procedural demand.
- Robotic assistance systems:French teaching hospitals are deploying capital budgets toward precision instrumentation platforms that reduce screw malposition rates and enable minimally invasive approaches.
Market Restraints
- Titanium alloy input volatility:Aerospace and defense sector competition for high-grade titanium sponge is pressuring implant raw material costs and compressing hardware margins.
- ANSM post-market surveillance mandates:France-specific vigilance reporting requirements for implantable spinal hardware extend compliance timelines and elevate documentation burdens for market entrants.
- Motion preservation device reimbursement gaps:France's national health insurance maintains limited coverage for disc arthroplasty relative to fusion, constraining adoption in younger patient cohorts.
Strategic Opportunities
- Outpatient spinal procedure expansion:Reimbursement revisions enabling ambulatory surgery center coverage for select decompressions create channel diversification beyond traditional inpatient procurement.
- EU Green Deal sustainable procurement:Hospital tender evaluations now weight validated metallic implant recycling pathways, favoring suppliers with closed-loop waste recovery infrastructure.
- Neuromonitoring platform convergence:Integration of intraoperative neurophysiological monitoring with navigation systems addresses unmet safety needs in thoracolumbar deformity corrections.
Industry Challenges
- Specialized surgical workforce scarcity:Complex spinal deformity correction requires fellowship-trained surgeons, and France's academic medical centers face competition for this limited talent pool.
- Legacy hospital information system integration:Robotic navigation platforms must interface with heterogeneous electronic health record architectures across France's public hospital networks, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Spinal Surgery Devices Market |
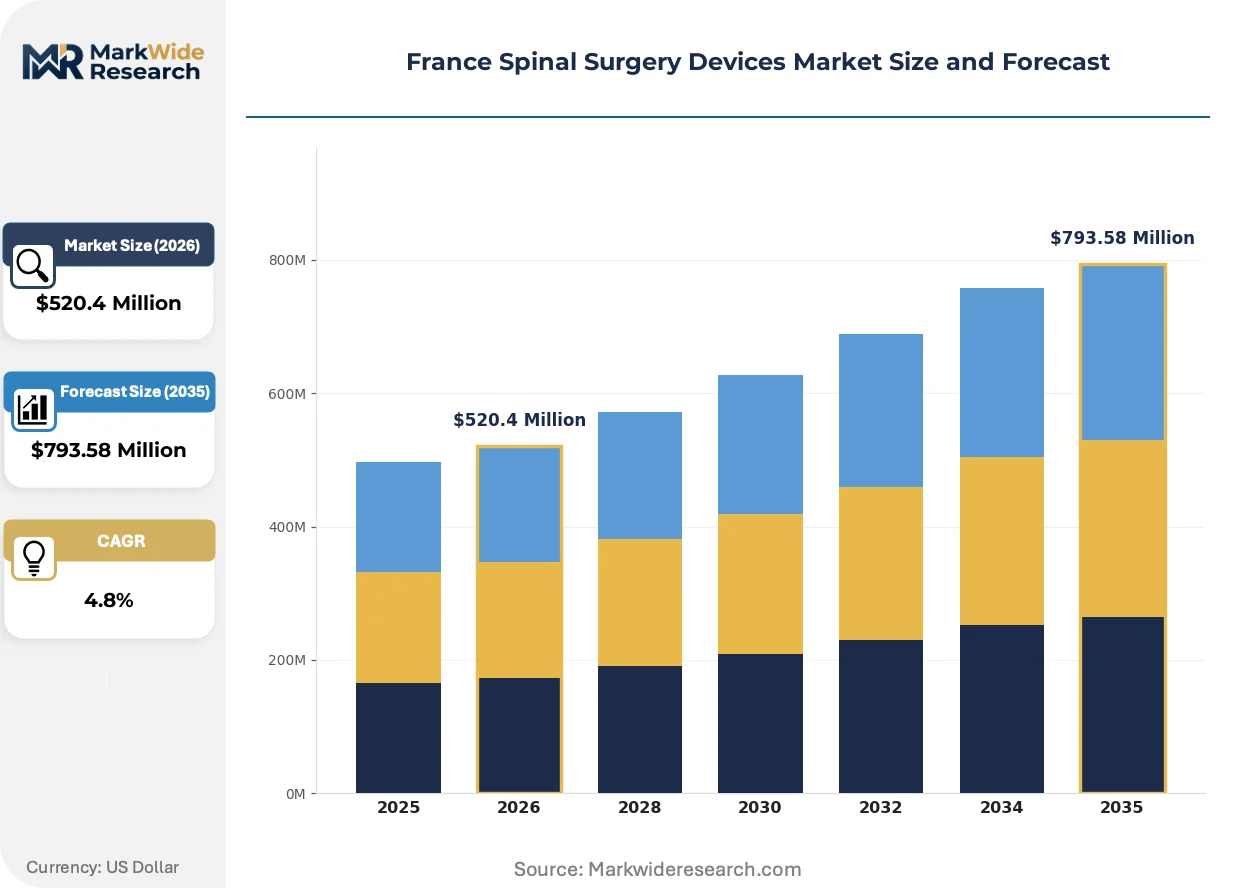
| Market Size in 2026 | $520.4 Million |
| Market Size in 2035 | $793.58 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spinal Fusion Implants, Decompression Systems, Motion Preservation Devices, Bone Graft Substitutes, Neuromonitoring Equipment Technology: Minimally Invasive Surgery, Navigation Systems, 3D Printing, Robotic Assistance, Imaging Guidance Application: Degenerative Disc Disease, Spinal Deformities, Traumatic Injuries, Spinal Tumors, Infection Management End User: Specialty Surgical Centers, Academic Medical Institutes, Rehabilitation Clinics, Neurosurgery Units, Orthopedic Clinics |
| Companies Covered | Medtronic plc, Stryker Corporation, Zimmer Biomet, Johnson & Johnson, Globus Medical, DePuy Synthes, NuVasive, Medicrea, Clariance, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Spinal Surgery Devices Market Shifts & Advancements
Three interconnected developments are restructuring how spinal devices are engineered, procured, and deployed across French healthcare infrastructure. Technology convergence, regulatory stringency, and buyer consolidation are the defining forces.
Polyetheretherketone (PEEK) interbody cages are integrating radiolucent properties with bone-like modulus to reduce subsidence and improve fusion assessment. University hospital networks in Lyon and Paris are standardizing on PEEK-titanium composite constructs for lumbar interbody fusions. This material transition is integrating advanced polymer processing capabilities into supplier manufacturing footprints, compressing traditional metals-only value chains.
ANSM's enforcement of MDR Article 10 post-market clinical follow-up requirements is extending implant lifecycle documentation obligations. Manufacturers must now maintain active surveillance registries for spinal constructs beyond initial CE marking approval. High-volume fusion systems face the steepest compliance cost escalation, prompting portfolio rationalization toward platforms with established long-term safety data.
Regional hospital group purchasing organizations are consolidating tender specifications around total procedure cost rather than device unit pricing. The Assistance Publique-Hôpitaux de Paris network now bundles implant, navigation, and disposable costs into single-lot awards. This purchasing behavior change is most visible in Île-de-France, where framework agreements span three-year cycles with performance-linked renewal clauses.
France Spinal Surgery Devices Market Segmentation
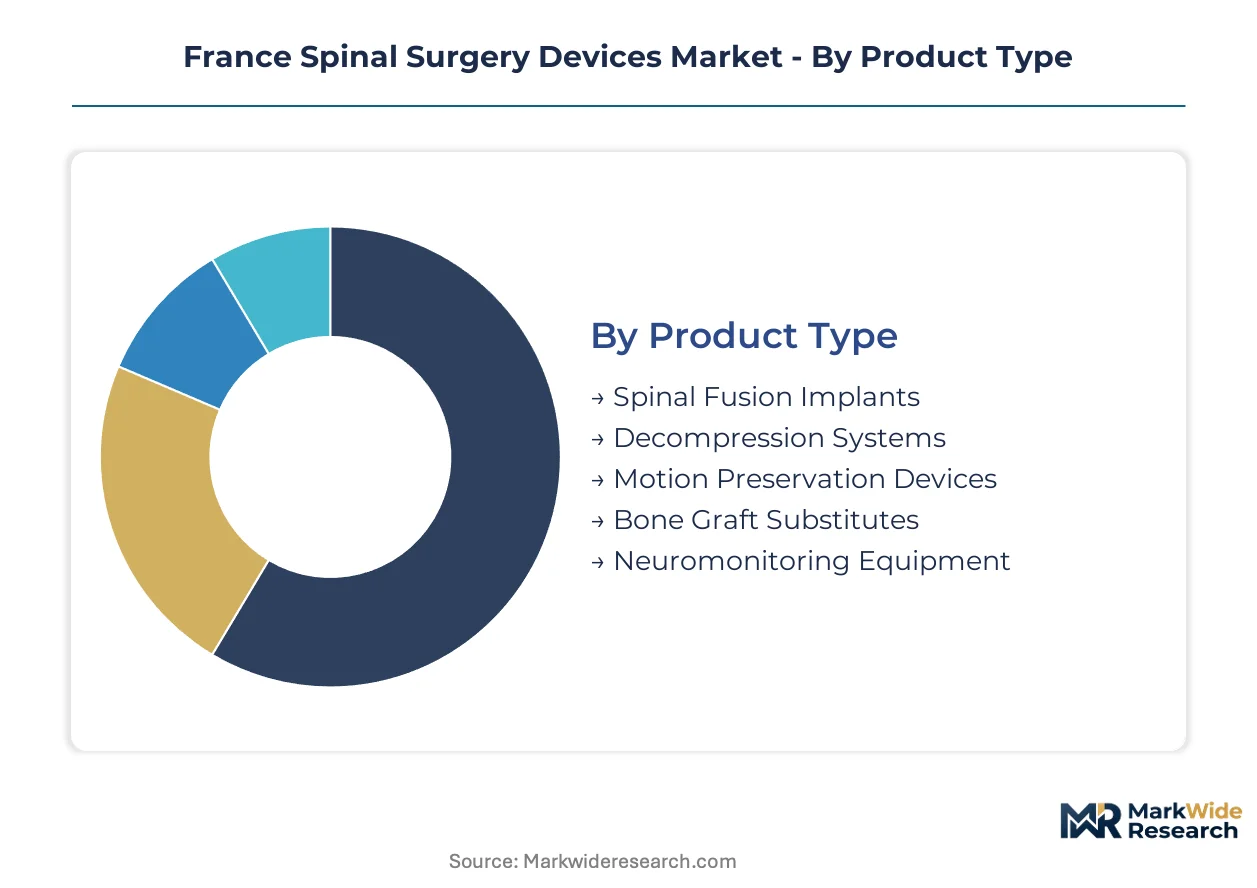
France's spinal surgery devices market segments across hardware, technology, and care settings that command distinct procurement pathways. Academic medical institutes in Lyon and Paris drive premium technology adoption, while regional hospitals optimize around standardized fusion platforms.
Product Type:
Upgrade cycles for implantable hardware accelerate as ANSM vigilance requirements force portfolio refreshes and safety documentation updates.
- Spinal Fusion Implants:Titanium alloy and PEEK interbody cages, pedicle screw systems, and anterior cervical plates dominate procedural volumes across France's public hospital networks. Assistance Publique-Hôpitaux de Paris procurement frameworks prioritize multi-year supply agreements for these platforms, compressing vendor margins through consolidated purchasing power.
- Decompression Systems:Laminectomy retractors, interspinous spacers, and microscopic discectomy instruments enable neural element preservation during stenosis correction. Demand concentrates in Auvergne-Rhône-Alpes specialty centers performing high-volume outpatient decompressions under evolving reimbursement protocols.
- Motion Preservation Devices:Cervical and lumbar disc arthroplasty systems serve younger patient cohorts with isolated disc pathology, though constrained by limited national health insurance coverage relative to fusion alternatives.
- Bone Graft Substitutes:Demineralized bone matrix and synthetic ceramic scaffolds reduce autograft harvest morbidity in multi-level fusions.
- Neuromonitoring Equipment:Intraoperative neurophysiological monitoring platforms integrate with navigation systems to reduce iatrogenic nerve injury during thoracolumbar approaches.
Spinal fusion implants sit at the top of the volume ranking, with neuromonitoring equipment climbing the fastest as safety integration becomes mandatory in deformity centers.
Technology:
Capital deployment patterns across French teaching hospitals favor platforms that reduce revision rates and enable same-day discharge.
- Minimally Invasive Surgery:Tubular retractor systems and percutaneous screw placement reduce paraspinal muscle disruption and accelerate recovery timelines.
- Navigation Systems:Optical and electromagnetic tracking platforms enable real-time instrument localization relative to preoperative imaging.
- 3D Printing:Patient-specific drill guides and anatomical models support complex deformity planning at Île-de-France academic centers.
- Robotic Assistance:Precision instrumentation platforms reduce screw malposition rates and enable minimally invasive approaches. French teaching hospitals are expanding capital budgets for these systems, with framework agreements now bundling robotic navigation into multi-year procurement awards.
- Imaging Guidance:Intraoperative CT and fluoroscopy systems anchor high-complexity deformity workflows, with demand concentrating in Paris and Lyon university hospital networks seeking to minimize revision burden.
Minimally invasive surgery commands the largest installed base, while robotic assistance gains share fastest through capital budget prioritization in academic centers.
Application:
Procedure mix shifts as France's aging population expands degenerative condition prevalence while trauma volumes stabilize.
- Degenerative Disc Disease:Lumbar and cervical spondylosis drives the majority of fusion and decompression procedures across French public hospitals.
- Spinal Deformities:Scoliosis and kyphosis corrections require specialized instrumentation and extended operative times, concentrating in academic medical institutes with fellowship-trained surgical staff.
- Traumatic Injuries:Fracture stabilization and spinal cord decompression following vertebral column trauma.
- Spinal Tumors:En bloc resection and palliative decompression procedures demand navigation-integrated approaches for safe margin definition.
- Infection Management:Debridement and stabilization for spondylodiscitis, with antibiotic-impregnated implants gaining traction in complex cases.
Degenerative disc disease leads procedural volume, with spinal deformity applications expanding most quickly as correction complexity migrates to specialized centers.
End User:
Site-of-care economics reshape device selection as reimbursement revisions enable ambulatory procedure expansion.
- Specialty Surgical Centers:Focused orthopedic and neurosurgical facilities performing high-volume decompressions with streamlined supply chains.
- Academic Medical Institutes:University hospital networks in Paris, Lyon, and Marseille anchor complex deformity and revision surgery volumes, driving adoption of navigation-integrated and robotic-assisted platforms.
- Rehabilitation Clinics:Postoperative recovery facilities with limited intraoperative device procurement.
- Neurosurgery Units:Hospital-based departments combining spinal and cranial procedures, prioritizing neuromonitoring platform convergence.
- Orthopedic Clinics:Private and public sector musculoskeletal specialists, increasingly eligible for outpatient spinal procedure reimbursement under evolving national health insurance protocols.
Academic medical institutes dominate premium technology procurement, with orthopedic clinics ascending fastest through ambulatory surgery center authorization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's spinal device procurement frameworks emphasize value-based contracting more aggressively than France's hospital consolidation model, creating divergent vendor negotiation dynamics across continental Europe.
Germany
University hospital networks in Berlin and Munich drive adoption of navigation-integrated platforms for complex deformity corrections. The Federal Institute for Drugs and Medical Devices enforces stringent post-market surveillance parallel to EU MDR requirements, extending documentation timelines for implantable constructs. The Baden-Württemberg medical technology cluster anchors precision manufacturing capabilities for titanium alloy spinal hardware.
United Kingdom
NHS England's specialized spinal surgery centers concentrate complex revision procedures in London and Manchester, expanding addressable demand for premium instrumentation. The Medicines and Healthcare products Regulatory Agency mandates UKCA marking alongside residual CE recognition, creating dual compliance pathways for market entrants. The Oxford-Cambridge arc hosts emerging neuromonitoring platform developers integrating with surgical navigation systems.
Italy
Lombardy's regional health system consolidates procurement for spinal implants across Milan's university hospital network, compressing vendor margins through volume aggregation. The Italian Ministry of Health enforces AIFA medical device vigilance reporting for implantable spinal constructs, adding national layers to EU regulatory compliance. The Emilia-Romagna medical device district supports subcontract manufacturing for European spinal hardware suppliers.
Spain
Catalonia's public hospital networks prioritize minimally invasive spinal platforms to reduce length-of-stay metrics under regional health budget pressures. The Spanish Agency for Medicines and Health Products enforces enhanced clinical evidence requirements for high-risk implantable devices under national transposition of EU MDR. Madrid's La Paz University Hospital anchors complex deformity correction volumes and robotic-assisted surgery adoption.
Switzerland
University hospitals in Zurich and Geneva maintain independent procurement frameworks outside EU consolidation trends, preserving premium pricing for specialized spinal platforms. Swissmedic enforces medical device regulations that exceed EU MDR baseline requirements for implantable spinal constructs, particularly for motion preservation devices. The Basel biotech corridor hosts orthopedic biomaterials research supporting next-generation interbody fusion technologies.
France Spinal Surgery Devices Market Competitive Landscape
United States producers anchor one tier; European specialists hold differentiated positions in navigation and imaging guidance. Market structure concentrates around diversified orthopedic conglomerates with broad fusion portfolios and specialized robotics developers with precision instrumentation platforms. Three archetypes dominate: full-line suppliers with multi-year hospital framework agreements, navigation-integrated technology specialists, and emerging robotics platforms seeking academic center validation. Competitive moves center on portfolio rationalization toward MDR-compliant platforms and strategic partnerships bundling hardware with intraoperative monitoring systems.
Within the full-line supplier tier, Medtronic plc and Stryker Corporation exemplify divergent strategic positioning. Medtronic plc occupies a position anchored by breadth across fusion implants and neuromonitoring integration. Stryker Corporation represents the navigation-specialist archetype, with emphasis on imaging guidance systems for deformity centers. Zimmer Biomet sits within the diversified orthopedic conglomerate category, leveraging scale across joint reconstruction and spinal hardware procurement negotiations.
| Leading Market Players |
|---|
| Medtronic plc |
| Stryker Corporation |
| Zimmer Biomet |
| Johnson & Johnson |
| Globus Medical |
| DePuy Synthes |
| NuVasive |
| Medicrea |
| Clariance |
| Others |
Supply & Pricing Matrix
Robotic assistance platform adoption across Île-de-France teaching hospitals is compressing per-procedure implant costs while concentrating procurement leverage within consolidated hospital networks. This technology shift forces suppliers to restructure pricing around multi-year framework agreements rather than transactional sales, embedding navigation and disposable bundles into single-lot awards that erase standalone hardware premiums.
Pricing Analysis
Capacity additions in PEEK polymer processing across Germany and Switzerland are reshaping price floors for interbody fusion cages in France. Three-tier pricing structure across premium navigation-integrated, standard instrumented, and economy basic fusion levels anchors the market, with ANSM MDR compliance tier and volume scale driving differentiation. Cost compression in standard titanium pedicle screw systems is intensifying because Assistance Publique-Hôpitaux de Paris procurement frameworks consolidate purchasing across multi-year cycles. Regional hospital networks exhibit highest price sensitivity, while academic deformity centers retain leverage for premium robotic platform premiums.
Supply Chain Analysis
Regional distribution centers in Lyon and Paris operate hub-and-spoke patterns that feed sterilization facilities across Auvergne-Rhône-Alpes and Île-de-France hospital networks. Manufacturing concentrates in Germany, Switzerland, and the United States for precision-machined titanium implants and navigation electronics. Raw material flows draw from high-grade titanium sponge sources, polyetheretherketone resin suppliers, and biocompatible ceramic feedstocks. Single-source vulnerability in aerospace-qualified titanium alloy supply creates exposure to defense sector demand spikes. Distribution runs through manufacturer-direct sales teams and specialized orthopedic distributors serving public hospital procurement consortiums.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's spinal device market functions as a regulatory compounder where EU MDR enforcement and ANSM post-market surveillance mandates continuously elevate compliance barriers that filter marginal competitors and concentrate volume among established notified body relationships.
For Market Incumbents: Extend framework agreement coverage across emerging ambulatory surgery center networks before reimbursement revisions fully mature, securing channel position against specialized orthopedic clinic entrants. Deepen backward integration into PEEK polymer processing capabilities to capture margin from material transitions in lumbar interbody fusion platforms. Anchor multi-year contracts with performance-linked renewal clauses tied to revision rate documentation. For New Entrants and Emerging Players: Enter via neuromonitoring platform convergence partnerships that address unmet safety integration needs in thoracolumbar deformity corrections, bypassing capital-intensive robotic system competition. Target outpatient decompression procedure segments where evolving national health insurance coverage creates procurement access without requiring full-line fusion portfolios. Pursue software companion development pathways that attach to existing navigation installations. For Investors and Strategic Acquirers: Roll-up economics work for navigation-integrated technology specialists because ANSM vigilance documentation requirements create scale advantages in post-market clinical follow-up registry maintenance. Five-to-ten year viability hinges on portfolio breadth across MDR-compliant platforms with established long-term safety data. Monitor hospital GPO consolidation velocity in Île-de-France as inflection indicator for pricing power erosion.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | ANSM MDR Article 10 compliance secures access to consolidated public hospital procurement frameworks. |
| Hospital System Partnership | Assistance Publique-Hôpitaux de Paris framework agreements lock in multi-year supply volumes. |
| Software Companion Development | Navigation platform integration addresses neuromonitoring convergence demand in deformity centers. |
| Reimbursement Strategy | National health insurance outpatient procedure coverage expansion enables ambulatory channel diversification. |
| Backward Integration | In-house PEEK polymer processing captures margin from material transition in interbody fusion. |
Research Methodology
Coverage spans France, Germany, Switzerland, and the United States, with primary inputs from each territory's regulatory and procurement stakeholders. The analysis combines structured interviews with hospital purchasing committee directors, biomedical engineers, GPO contracts managers, and spinal surgeons with secondary validation from ANSM vigilance databases, EU MDR notified body registries, hospital procurement frameworks, and CE marking documentation. Bottom-up procedure volume modeling triangulates against top-down manufacturer revenue segmentation.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon. Segmentation dimensions include product type, technology platform, application severity, and end-user site-of-care category. CAGRs derive from installed base growth curves, replacement cycle analysis, and capital budget prioritization patterns in academic medical institutes. Forecast inputs incorporate ANSM regulatory timeline assumptions and EU Green Deal sustainable procurement weighting evolution.
The model holds under stable MDR enforcement intensity and continued hospital procurement consolidation; deviation in reimbursement policy acceleration or titanium supply disruption would shift trajectory. Forecasts reflect documented assumptions regarding procedure migration to outpatient settings. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Europe Smart Medical Devices Market
Medical Devices
Focused Ultrasound System Market
Medical Devices
Veterinary Injectable Devices Market
Medical Devices
Medical Goggle Market
Medical Devices
Digital Stethoscope Market
Medical Devices
Bone Allografts Market
Medical Devices
Asthma Inhaler Device Market
Medical Devices
Thoracolumbar Stabilization Devices Market
Medical Devices
Global Cerebral Somatic Oximeters Market
Medical Devices
Japan Minimally Invasive Surgery Devices Market
Medical Devices
Intubation Accessories Market
Medical Devices
Morcellators Market
Medical Devices
Foot Massage Machine Market
Medical Devices
Chile Ultrasound Devices Market
Medical Devices
Asia-Pacific Electrophysiology Market
Medical Devices
Global Gastrointestinal Devices Market