
 Needle-Free IV Connectors Market | 2026-2036
Needle-Free IV Connectors Market Size, Share, and Industry Trends Forecast 2026-2036
Needle-Free IV Connectors Market Analytics
Home healthcare buyers are unwinding the historical dominance of hospital procurement committees in connector selection. ICU Medical Inc. leverages direct-to-provider channel control to sustain premium positioning in closed-system formats. B. Braun Melsungen AG anchors European manufacturing scale for swabable designs, while Baxter International Inc. competes across the full application spectrum from acute care to home infusion.
Needle-free IV connectors are mechanical valved devices that eliminate sharp cannula exposure during vascular access, typically incorporating silicone seals or elastomeric membranes rated for repeated activation cycles exceeding one hundred connections. Their primary purpose is to prevent needlestick injuries and reduce catheter-related bloodstream infections during fluid administration, blood draws, and drug delivery. Closed system formats command margin pools through superior infection control performance, while swabable designs lead volume in home healthcare applications where disinfection protocols vary. Hospital end users still represent the largest installed base, though long-term care segments show the fastest structural shift as aging populations transition from acute settings.
FDA enforcement of the Needlestick Safety and Prevention Act shapes product design mandates for US manufacturers, while ISO 80369-7 small-bore connector standards govern dimensional interoperability across jurisdictions. The EU MDR intensifies clinical evidence requirements for devices claiming infection reduction benefits, tightening market access for new entrants. Stakeholders must monitor evolving home healthcare reimbursement codes and ambulatory site accreditation standards to anticipate where connector specification authority will migrate next.
Market Dynamics
Home healthcare migration is dismantling the hospital procurement monopoly that historically dictated connector specifications, transferring buying authority to ambulatory networks and direct-to-patient channels. This power shift is compressing traditional distribution tiers and forcing manufacturers to reconfigure pricing and service architectures around decentralized clinical sites.
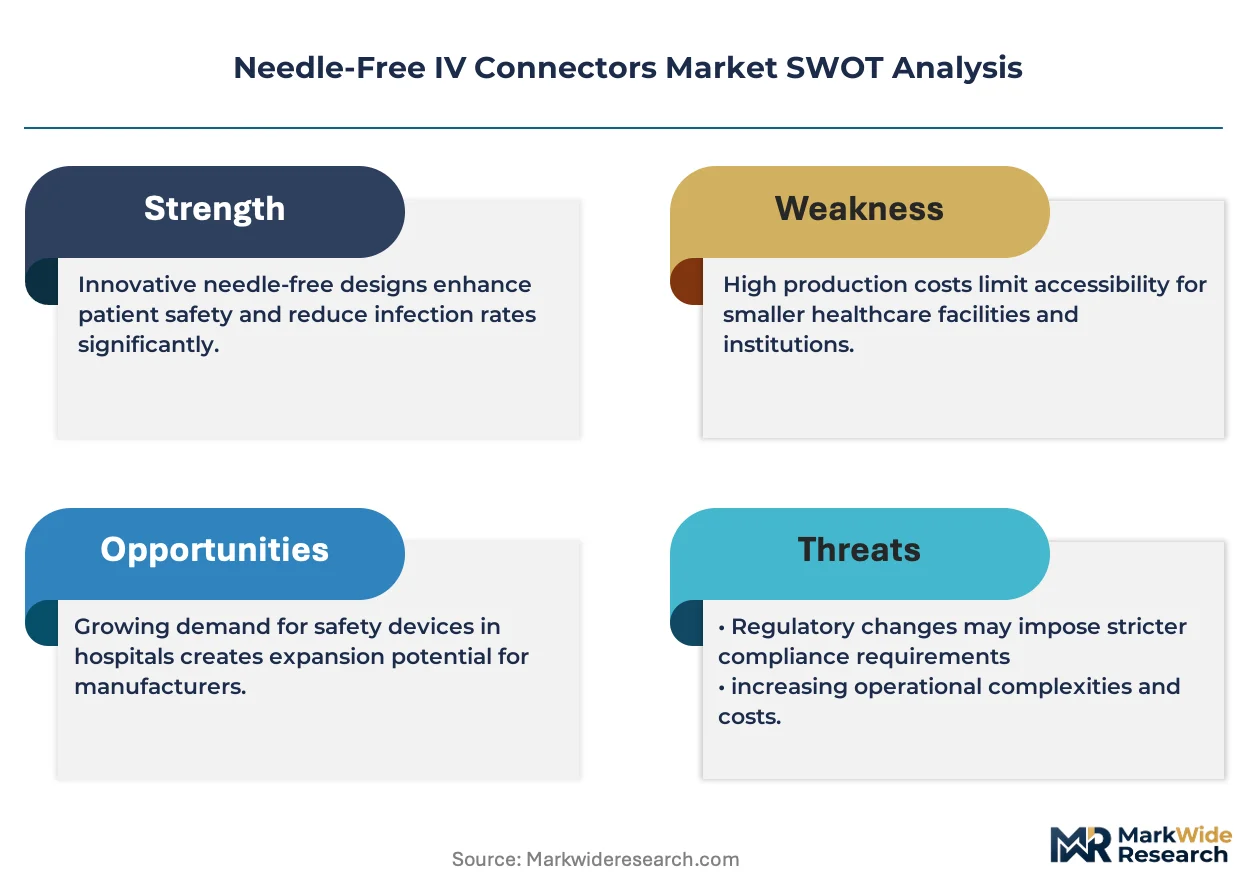
Growth Catalysts
- FDA Needlestick Safety and Prevention Act:Federal enforcement mandates drive replacement of legacy sharp-cannula devices across US acute care facilities, creating baseline demand for mechanical valve connectors.
- Silicone seal elastomers:Advanced elastomeric membrane materials rated for 100+ activation cycles enable closed-system performance in compact formats suitable for home infusion pumps.
- Ambulatory infusion center networks:Rapid expansion of non-hospital infusion sites across the United States generates recurring replacement volume outside traditional health system procurement.
Market Restraints
- Medical-grade silicone price volatility:Raw material costs for biocompatible elastomers fluctuate with petrochemical feedstock markets, squeezing margin on swabable connector lines.
- EU MDR clinical evidence requirements:Stricter documentation burdens for infection-reduction claims extend time-to-market for novel connector designs seeking CE marking.
- Catheter-related bloodstream infection liability:Persistent litigation exposure around connector-associated infections limits willingness to adopt unproven valve mechanisms in high-acuity settings.
Strategic Opportunities
- Long-term care facility penetration:Skilled nursing and assisted living operators in the United States lag hospitals in closed-system adoption, representing white space for infection-control differentiated products.
- ISO 80369-7 standardization:Dimensional interoperability mandates create openings for manufacturers offering cross-compatible designs that reduce hospital inventory complexity.
- Remote patient monitoring integration:Convergence of mechanical connectors with digital flow sensors enables smart infusion systems for home-based chemotherapy and immunotherapy delivery.
Industry Challenges
- Biomedical engineering talent scarcity:Specialized expertise in fluid dynamics and elastomeric sealing is concentrated among legacy device manufacturers, constraining new entrant R&D velocity.
- Legacy Luer lock infrastructure:Hospital capital equipment and existing catheter inventories create switching friction against novel connector geometries despite superior safety profiles.
- Multi-site accreditation variance:Divergent Joint Commission and state-level standards for ambulatory infusion centers complicate nationwide product qualification and training protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Needle-Free IV Connectors Market |
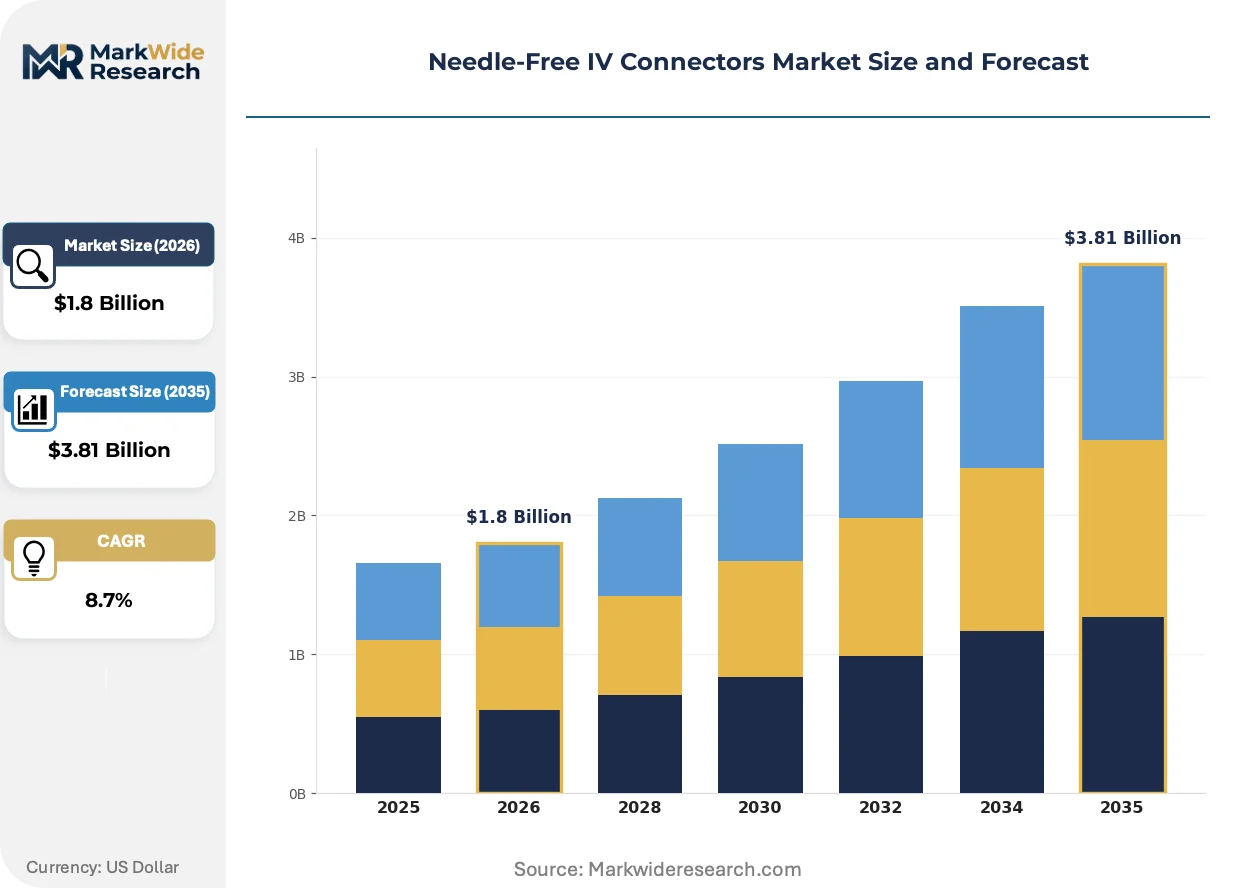
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Swabable, Non-Swabable, Closed System, Open System Application: Hospitals, Home Healthcare, Clinics, Long-Term Care End User: Healthcare Professionals, Patients, Caregivers, Technicians Distribution Channel: Online, Offline, Direct Sales, Medical Supply Distributors |
| Companies Covered | BD, Baxter International Inc., B. Braun Melsungen AG, ICU Medical Inc., CareFusion Corporation, Vygon SA, Cardinal Health, RyMed Technologies LLC, Nexus Medical LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Needle-Free IV Connectors Market Evolving Landscape
Valve mechanism miniaturization and materials science advances are collapsing the performance gap between hospital-grade closed systems and cost-optimized swabable designs. Regulatory pressure on infection metrics and the physical decentralization of infusion therapy are accelerating product iteration cycles.
Closed-system mechanical valves incorporating dual-seal silicone architectures are supplanting simple split-septum designs in mid-tier acute care segments previously dominated by basic swabable connectors. Oncology and parenteral nutrition units in US hospital systems are adopting these formats at replacement cycle velocities matching traditional ICU procurement. This technology compression is eroding the premium tier's insulation from standard-product price competition.
The EU MDR's intensified clinical evidence requirements for infection-prevention claims are extending regulatory timelines for novel connector submissions seeking European market access. Manufacturers must now generate prospective clinical data or systematic literature reviews to support CE marking for devices marketed on reduced bloodstream infection risk. Swabable design entrants with limited post-market surveillance infrastructure face the steepest compliance burden, advantaging established players with legacy clinical databases.
Buying committees at ambulatory infusion networks are consolidating supplier relationships around full-line vendors capable of spanning acute, long-term care, and home settings with unified product families. Distributor disintermediation is accelerating as manufacturers like ICU Medical build direct field service organizations to capture service revenue and specification influence. This channel restructuring is most pronounced in the southwestern and southeastern United States, where independent infusion center chains are expanding fastest outside legacy health system umbrellas.
Needle-Free IV Connectors Market Segmentation
Needle-free IV connector procurement patterns fragment sharply across clinical settings and user capabilities. Product design priorities diverge between infection-control-intensive acute environments and cost-sensitive decentralized care sites.
Product Type:
Closed-system formats capture premium margin pools through superior bloodstream infection prevention, while swabable designs dominate volume in price-sensitive channels.
- Swabable:These connectors incorporate disinfectable external surfaces compatible with alcohol-based cleaning protocols. Demand concentrates in United States home healthcare and long-term care facilities where caregiver training varies and simplified disinfection reduces protocol failure risk.
- Closed System:Dual-seal silicone architectures mechanically isolate the fluid pathway from environmental contamination. United States hospital oncology and parenteral nutrition units drive replacement cycles here, prioritizing infection metrics over per-unit cost in reimbursement-sensitive service lines.
- Non-Swabable:Basic valved designs without dedicated disinfection surfaces serve legacy equipment compatibility requirements in budget-constrained clinical settings.
- Open System:Simple split-septum formats without mechanical valves persist in low-acuity applications and developing market price tiers.
Closed System holds installed capacity in acute care. Swabable is rotating up the share rankings as home infusion expands.
Application:
Volume concentration tilts toward institutional procurement, though structural growth vectors sit outside hospital walls.
- Hospitals:Centralized purchasing committees specify mechanical valve performance standards across ICU, oncology, and surgical units. FDA needlestick prevention enforcement sustains baseline replacement demand across United States health systems regardless of equipment age.
- Home Healthcare:Patient and caregiver-administered infusion therapy requires compact, intuitive connector designs with clear activation feedback. Ambulatory chemotherapy and immunotherapy networks in the southwestern and southeastern United States are expanding procurement autonomy fastest.
- Clinics:Outpatient infusion centers balance infection control requirements against throughput efficiency in high-volume drug administration settings.
- Long-Term Care:Skilled nursing facilities lag hospitals in closed-system adoption, creating specification white space for vendors with training-intensive service models.
Hospitals retain specification authority. Home Healthcare is climbing the fastest as reimbursement shifts site of care.
End User:
Technical sophistication requirements stratify sharply between trained clinical operators and lay caregivers.
- Healthcare Professionals:Nurses and physicians in United States acute care settings prioritize reliable seal integrity and compatibility with existing catheter inventories. Their institutional purchasing influence remains strongest in hospital and ambulatory network procurement.
- Patients:Self-administering home infusion therapy demands intuitive mechanical interfaces with audible or tactile connection confirmation. Direct-to-patient channels are compressing traditional distribution tiers.
- Caregivers:Family members assisting elderly patients in long-term care settings require simplified disinfection protocols and error-resistant designs.
- Technicians:Biomedical engineering staff influence capital equipment compatibility decisions and preventive maintenance scheduling.
Healthcare Professionals hold installed capacity. Patients are gaining share fastest as self-administration protocols proliferate.
Distribution Channel:
Channel control is fragmenting as manufacturers build direct field organizations to capture specification influence.
- Direct Sales:ICU Medical and comparable vendors deploy dedicated clinical specialists to ambulatory infusion networks. This channel captures service revenue and bypasses distributor margin extraction in high-growth United States regions.
- Medical Supply Distributors:Traditional tiered distribution retains relevance for smaller hospital systems and long-term care chains lacking procurement scale.
- Online:E-commerce platforms serve home healthcare patients and small clinical practices with standardized product configurations and rapid replenishment.
- Offline:Remaining brick-and-mortar medical supply outlets concentrate in geographic pockets with limited digital infrastructure access.
Direct Sales holds installed capacity. Online is rotating up the share rankings as home-based procurement normalizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold-chain infrastructure anchors European distribution for needle-free IV connector manufacturers serving North Sea markets. German rail corridors and the Rhine waterway network distribute finished devices to Central European hospital systems.
United States
Ambulatory infusion center networks in Texas and Florida drive replacement volume outside traditional health system procurement. FDA enforcement of the Needlestick Safety and Prevention Act sustains baseline demand across acute care facilities. The Research Triangle Park corridor in North Carolina hosts biomedical device engineering clusters developing next-generation elastomeric sealing technologies.
Germany
Swabable connector manufacturing scales from Baden-Württemberg production facilities serving EU hospital networks. The EU MDR intensifies clinical evidence requirements for infection-reduction claims, extending regulatory timelines for CE marking. Frankfurt's logistics hub concentrates distribution for Central and Eastern European markets.
Japan
Home healthcare adoption accelerates in Kansai metropolitan corridors as aging populations transition from acute settings. PMDA review standards for mechanical valve devices align with ISO 80369-7 dimensional interoperability mandates. Osaka's medical device manufacturing belt specializes in compact connector formats for portable infusion pumps.
China
Domestic production capacity expands in Jiangsu province to serve hospital procurement consolidation under national health system reforms. NMPA biocompatibility testing requirements for silicone elastomers create compliance barriers for imported devices. Shanghai's Yangshan port infrastructure supports raw material imports for medical-grade polymer processing.
Needle-Free IV Connectors Market Competitive Landscape
Concentration sits with diversified medical device conglomerates possessing integrated elastomer compounding and sterilization infrastructure. The vendor base spans three tiers: multinational hospital suppliers with direct field service organizations, regional specialists in swabable formats, and contract manufacturers serving private-label distributors. Strategic moves center on distributor disintermediation through direct clinical specialist deployment and backward integration into medical-grade silicone compounding to secure margin against petrochemical feedstock volatility.
Among US-based diversified suppliers, BD and Baxter International Inc. occupy positions spanning acute care through home infusion channels. ICU Medical Inc. exemplifies the direct-to-provider archetype with dedicated field service organizations capturing specification influence in ambulatory networks. B. Braun Melsungen AG anchors European manufacturing scale for swabable designs serving cost-sensitive decentralized care settings.
| Leading Market Players |
|---|
| BD |
| Baxter International Inc. |
| B. Braun Melsungen AG |
| ICU Medical Inc. |
| CareFusion Corporation |
| Vygon SA |
| Cardinal Health |
| RyMed Technologies LLC |
| Nexus Medical LLC |
| Others |
Value Network & Pricing Analysis
Silicone elastomer substitution for conventional rubber seals is redrawing manufacturing geography toward petrochemical-adjacent regions while compressing margin pools across connector tiers. This materials transition simultaneously elevates FDA biocompatibility testing burdens and intensifies price competition between hospital-grade closed systems and home healthcare swabable formats.
Pricing Analysis
Volume-discount tiering separates health system GPO contracts from ambulatory network spot purchasing and direct-to-patient retail channels. Price differentiation rests on ISO 80369-7 certification grade and silicone seal cycle durability ratings. Cost compression in swabable lines is intensifying because medical-grade silicone feedstock volatility squeezes compounders without backward integration. Home healthcare patients exhibit highest price sensitivity; oncology units in integrated delivery networks show lowest.
Supply Chain Analysis
Container availability fluctuations on Asia-North America trade lanes are elevating inbound logistics costs for medical-grade polymer resin shipments. Manufacturing concentrates in Germany, the United States, and China, with compounding expertise anchored in Baden-Württemberg and the Research Triangle Park corridor. Raw material sourcing draws from petrochemical feedstocks, platinum-cured silicone catalysts, and precision-molded plastic housings. Single-source vulnerability sits with specialized elastomer compounders serving FDA master file holders. Distribution runs through manufacturer-direct field organizations, traditional medical supply distributors, and e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The needle-free IV connector market functions as a regulatory-moat business where FDA 510(k) clearance databases and ISO 80369-7 dimensional standards create entrenched switching costs against unproven entrants.
For Market Incumbents: Consolidate specification influence by embedding clinical specialists within ambulatory infusion networks in Texas and Florida, where distributor disintermediation is accelerating. Deepen backward integration into medical-grade silicone compounding to neutralize petrochemical feedstock volatility threatening swabable connector margins. Prioritize CE marking database investments before EU MDR clinical evidence requirements harden. For New Entrants and Emerging Players: Service-layer gaps in long-term care facility training and closed-system protocol implementation offer white-space entry points. Skilled nursing operators in the United States lag hospitals in infection-control differentiated procurement, representing the most penetrable segment. Pursue direct-to-provider channel development bypassing traditional GPO contracts. For Investors and Strategic Acquirers: EU MDR enforcement reshapes the acquisition landscape toward targets with legacy clinical databases supporting infection-reduction claims. Five-to-ten year viability favors manufacturers with integrated elastomer compounding and sterilization infrastructure. Monitor ambulatory infusion center accreditation standard convergence as inflection signal for specification authority migration.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence requirements extend timelines for infection-prevention claims. |
| Backward Integration into Silicone Compounding | Captive supply of medical-grade elastomers insulates margin from petrochemical volatility. |
| Hospital System Partnership | GPO contract consolidation favors vendors spanning acute, long-term care, and home settings. |
| Software Companion Development | Digital flow sensor integration enables smart infusion systems for home chemotherapy delivery. |
| Reimbursement Strategy | Home healthcare code alignment determines connector specification authority outside hospital walls. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with hospital purchasing committees, biomedical engineers, GPO contracts managers, and home infusion network operators; and secondary validation against FDA 510(k) filings, ISO 80369-7 technical documentation, hospital procurement databases, and CMS reimbursement code updates. Bottom-up installed base estimates and top-down market sizing triangulated volume and value outputs.
Across the analysis window, forecasts incorporate product type segmentation by seal architecture, application tier from ICU through home healthcare, and end-user technical sophistication. CAGRs derive from replacement cycle velocity modeling and site-of-care migration patterns. Elastomeric membrane durability ratings and ambulatory infusion center expansion trajectories serve as industry-specific demand inputs.
Underlying assumptions cover FDA enforcement continuity and ISO 80369-7 interoperability adoption, with deviation risk concentrated in EU MDR clinical evidence timeline extensions and medical-grade silicone supply disruptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Bone Cement Mixers Market
Medical Devices
Medical Device Tester Market
Medical Devices
Pleural Catheters Market
Medical Devices
Global Cosmetic Implants Market
Medical Devices
Nano Healthcare Technology Market
Medical Devices
Non-Rebreathing Oxygen Mask Market
Medical Devices
Medical Coatings Market
Medical Devices
Argentina Aesthetic Devices Market
Medical Devices
US Digital Pregnancy Test Kits Market
Medical Devices
Assisted Walking Devices Market
Medical Devices
Global Prosthetics Market
Medical Devices
High Pressure Contrast Media Injectors Market
Medical Devices
Drug and Gene Delivery Devices Market
Medical Devices
South Africa Artificial Organs and Bionic Implants Market
Medical Devices
Global Anti-Snoring Devices and Snoring Surgery Market
Medical Devices
Global Photobiostimulation Market