
 Mhealth (Mobile Health) Devices Market | 2026-2036
Mhealth (Mobile Health) Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Mhealth (Mobile Health) Devices Market Foresight
Edge-to-cloud architecture is fragmenting across mHealth device ecosystems as manufacturers split data processing between on-device sensors and remote analytics platforms. Apple Inc. leverages its vertically integrated HealthKit framework to anchor consumer-grade biometric collection. Samsung Electronics Co., Ltd. competes through open Galaxy ecosystem partnerships with clinical software vendors. Medtronic PLC dominates regulated continuous glucose monitoring with FDA-cleared algorithms that sustain hospital trust.
MHealth (Mobile Health) Devices comprise portable electronic systems—typically incorporating MEMS accelerometers, photoplethysmography optical sensors, and sub-1mA BLE transceivers—that capture, transmit, and analyze physiological data for preventive, diagnostic, or therapeutic purposes. These systems operate at 2.4 GHz ISM bands with power budgets under 100mW to enable multi-day wearable deployment. Wearable Devices and Remote Monitoring Tools command the dominant margin pools as reimbursement codes solidify for ambulatory patient data. Mobile Apps face structural pressure from platform gatekeeping fees, while Telehealth Platforms attract enterprise investment as health systems consolidate virtual care contracts.
FDA digital health pre-certification, EU MDR Class IIa requirements, and Japan's PMDA Software as a Medical Device guidance collectively raise compliance barriers for cross-border mHealth deployment. These frameworks shape demand by determining which sensor-software combinations qualify for insurance reimbursement and clinical workflow integration. Stakeholders must monitor evolving interoperability mandates from ONC and the European Health Data Space as these rules will determine which platform architectures achieve scalable market access.
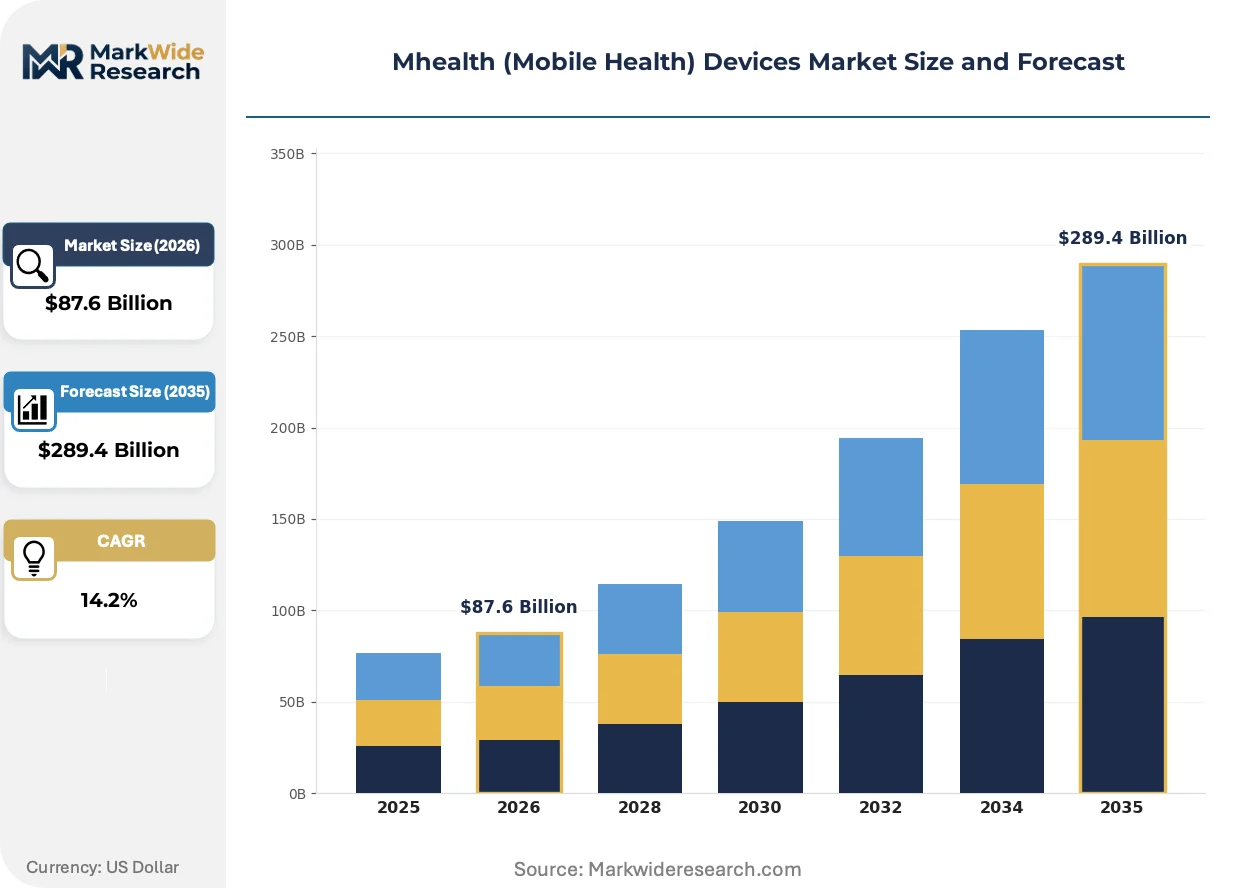
Market Dynamics
Edge-to-cloud data fragmentation is forcing mHealth manufacturers to rearchitect sensor-software stacks as reimbursement codes increasingly require validated clinical endpoints rather than raw biometric streams.
Growth Catalysts
- FDA Pre-Certification Pathway:The FDA's Digital Health Pre-Cert Program accelerates algorithm updates for continuous glucose monitors and cardiac wearables without full 510(k) resubmission, compressing product iteration cycles.
- EU MDR Class IIa Alignment:Software-as-a-Medical-Device classification under EU MDR creates harmonized certification routes that enable cross-border deployment across Germany, France, and the Netherlands.
- Photoplethysmography Advancement:Multi-wavelength PPG sensors now extract blood pressure and arterial stiffness indices from consumer wristbands, expanding addressable clinical applications beyond heart rate.
Market Restraints
- MEMS Foundry Concentration:Taiwan Semiconductor Manufacturing and Bosch Sensortec control over 70% of high-precision accelerometer wafer supply, creating single-source vulnerability for fall-detection algorithms.
- EU AI Act Compliance Burden:Risk-classification requirements for diagnostic algorithms impose documentation costs that disproportionately burden mid-tier wearable vendors lacking regulatory affairs infrastructure.
- Clinical Validation Timelines:Prospective studies for FDA-cleared arrhythmia detection require 12-18 month enrollment periods, delaying revenue recognition against compressed consumer electronics product cycles.
Strategic Opportunities
- Japan's PMDA Software Guidance:Streamlined SaMD approval for Class I devices enables rapid market entry for sleep apnea screening applications, with reimbursement codes expanding under the Ministry of Health's 2024 fee schedule revisions.
- Rural US Telehealth Integration:Federally Qualified Health Centers in Mississippi and Alabama are deploying cellular-enabled remote patient monitoring kits to satisfy CMS chronic care management billing requirements.
- BLE-AI Convergence:On-device neural network inference at sub-1mA power budgets enables real-time anomaly detection without cloud dependency, addressing latency-critical cardiac event classification.
Industry Challenges
- Biomedical Signal Processing Talent Scarcity:The intersection of embedded systems engineering and clinical physiology expertise remains underdeveloped, with universities producing fewer than 400 qualified graduates annually across the United States.
- Legacy EHR Integration Friction:HL7 FHIR implementation gaps between consumer wearable APIs and Epic Systems' hospital databases force manual data reconciliation, degrading clinician workflow adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mhealth (Mobile Health) Devices Market |
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $289.4 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Mobile Apps, Telehealth Platforms, Remote Monitoring Tools End User: Patients, Healthcare Providers, Insurers, Clinical Researchers Technology: Bluetooth, Wi-Fi, Cellular, NFC Application: Chronic Disease Management, Fitness Tracking, Medication Adherence, Wellness Monitoring |
| Companies Covered | Apple Inc., Samsung Electronics Co., Ltd., Fitbit Inc., Koninklijke Philips N.V., Medtronic PLC, Abbott, Boston Scientific Corporation, Omron Healthcare, Inc., Dexcom Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mhealth (Mobile Health) Devices Market Shifts & Advancements
Sensor fusion architectures are collapsing distinct hardware categories as single devices absorb multiple biomarker streams, while regulatory frameworks race to validate algorithmic outputs rather than physical components.
Multi-wavelength photoplethysmography is digitizing cardiovascular assessment by extracting pulse wave velocity and vascular age estimates from standard wrist-worn form factors. Cardiology departments at Cleveland Clinic and Mayo Clinic are piloting these metrics for hypertension management protocols. This capability is digitizing the traditional sphygmomanometer market by enabling continuous rather than episodic blood pressure surveillance.
EU MDR's post-market surveillance requirements for Class IIa software are mandating real-world performance dashboards that feed back into algorithm retraining loops. Manufacturers must now maintain clinical evidence registries spanning multiple member states. Germany's notified bodies are experiencing 14-month backlog queues, forcing vendors to prioritize BSI UK and TÜV SÜD for initial certification.
Hospital procurement departments are unbundling hardware acquisition from algorithm licensing, treating predictive analytics as renewable SaaS subscriptions rather than capital equipment. This shift pressures device OEMs to maintain recurring revenue engineering teams alongside hardware operations. The transformation is most visible in United States health systems consolidating virtual care contracts under single-vendor telehealth platforms.
Mhealth (Mobile Health) Devices Market Segmentation
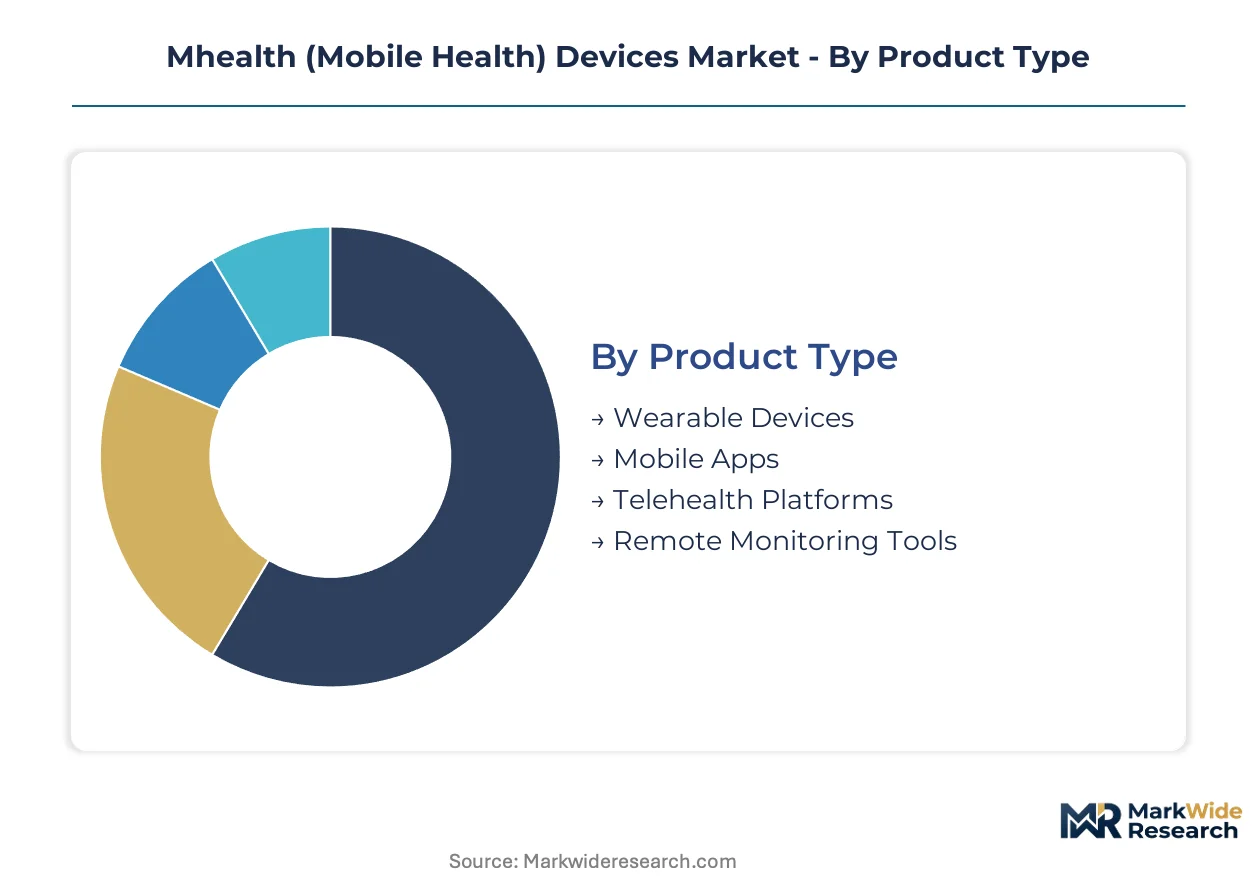
Segmentation in mHealth devices determines reimbursement eligibility, regulatory pathway complexity, and the intensity of post-deployment algorithm maintenance required to sustain clinical validation.
Product Type:
After-sales-service intensity varies dramatically across hardware-software combinations, with regulated devices demanding continuous algorithm recertification and consumer wearables requiring minimal ongoing clinical support.
- Wearable Devices:MEMS accelerometers and photoplethysmography optical sensors operate at sub-100mW power budgets for multi-day deployment. Demand concentrates among healthcare providers in the United States and Germany as CMS and BfArM reimbursement codes solidify for ambulatory cardiac monitoring.
- Remote Monitoring Tools:Cellular-enabled kits integrate FDA-cleared sensors with cloud analytics for chronic care management billing. Federally Qualified Health Centers in Mississippi and Alabama deploy these systems to satisfy CMS documentation requirements for rural patient populations.
- Telehealth Platforms:Enterprise virtual care contracts consolidate under single-vendor arrangements with recurring SaaS revenue models.
- Mobile Apps:Platform gatekeeping fees from Apple and Google create structural margin pressure independent of clinical utility.
Wearable Devices hold the largest share; momentum sits with Remote Monitoring Tools.
End User:
Cost tier differentiation separates enterprise procurement with dedicated regulatory affairs teams from individual consumers purchasing direct-to-retail.
- Healthcare Providers:Hospital systems and physician practices require FDA-cleared algorithms with documented clinical endpoints for EHR integration. Epic Systems implementations in Cleveland Clinic and Mayo Clinic demand HL7 FHIR compliance for workflow adoption.
- Patients:Direct-to-consumer purchasers drive volume in fitness-oriented wearables with minimal clinical validation requirements.
- Insurers:UnitedHealth and CVS Aetna are expanding coverage for continuous glucose monitors with demonstrated HbA1c reduction outcomes.
- Clinical Researchers:Academic medical centers require 21 CFR Part 11 compliant data exports for prospective trial enrollment.
Healthcare Providers dominate procurement value; Patients generate the steepest volume expansion.
Technology:
Application requirements dictate connectivity selection, with latency-critical cardiac alerts demanding on-device inference while routine wellness data tolerates cloud relay.
- Bluetooth:BLE transceivers at 2.4 GHz ISM bands enable sub-1mA power budgets for wrist-worn form factors with multi-day battery life.
- Cellular:LTE-M and NB-IoT modules support remote patient monitoring kits in rural geographies lacking Wi-Fi infrastructure.
- Wi-Fi:Home-based stationary devices leverage existing broadband for high-bandwidth video telehealth encounters.
- NFC:Short-range pairing simplifies device onboarding for elderly patient populations with limited technical literacy.
Bluetooth captures the highest shipment volume; Cellular connectivity is climbing the fastest as reimbursement expands to rural deployments.
Application:
Margin concentration follows regulatory burden, with disease management applications commanding premium pricing validated through prospective clinical trials.
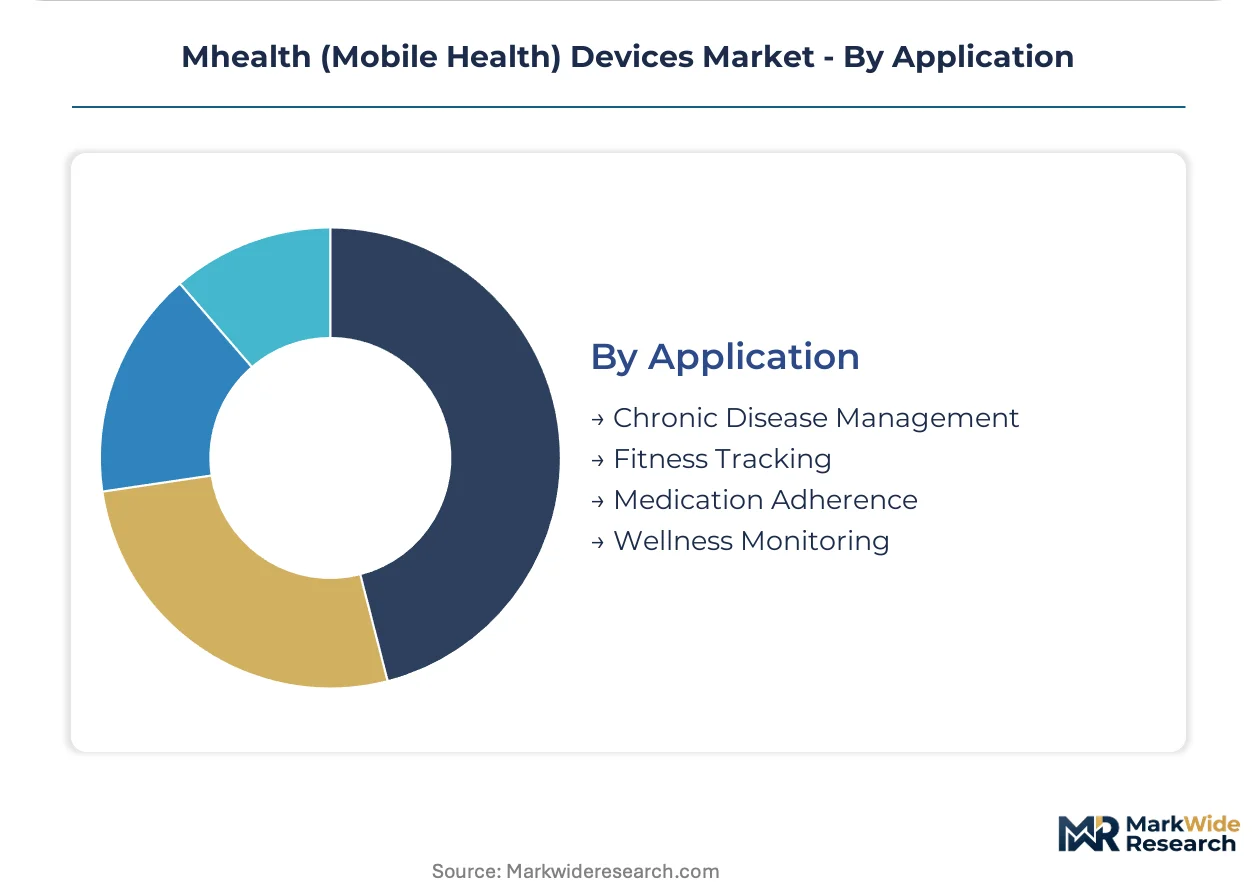
- Chronic Disease Management:Continuous glucose monitoring and cardiac arrhythmia detection require FDA 510(k) clearance with 12-18 month validation timelines. Medtronic and Abbott Laboratories dominate this segment with hospital-anchored distribution.
- Fitness Tracking:Consumer-grade step counting and calorie estimation operate without medical device classification, enabling rapid product cycles.
- Medication Adherence:Smart pill dispensers with cellular connectivity target polypharmacy patients in Medicare Advantage plans.
- Wellness Monitoring:Sleep staging and stress indices occupy a regulatory gray zone between consumer wellness and clinical diagnosis.
Chronic Disease Management commands the highest revenue per unit; Fitness Tracking delivers the broadest addressable population.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision sensor components to United States health systems integrating remote patient monitoring infrastructure. Japanese semiconductor foundries supply BLE transceivers to wearable device manufacturers across European markets. South Korean display technology flows into Chinese assembly plants producing consumer-facing fitness bands.
United States
Federally Qualified Health Centers in Mississippi and Alabama deploy cellular-enabled remote patient monitoring kits to satisfy CMS chronic care management billing requirements. FDA digital health pre-certification accelerates algorithm updates for continuous glucose monitors without full 510(k) resubmission. Cleveland Clinic and Mayo Clinic anchor hospital procurement demand for HL7 FHIR-compliant cardiac wearables.
Germany
BfArM reimbursement codes solidify for ambulatory cardiac monitoring devices prescribed through statutory health insurance. EU MDR Class IIa requirements for Software-as-a-Medical-Device create harmonized certification routes enabling cross-border deployment into France and the Netherlands. Notified bodies in Berlin and Munich experience 14-month backlog queues, forcing vendors toward BSI UK and TÜV SÜD for initial certification.
Japan
Ministry of Health fee schedule revisions expand reimbursement codes for sleep apnea screening applications. PMDA Software as a Medical Device guidance streamlines Class I device approvals, enabling rapid market entry for wellness monitoring platforms. Tokyo-based health technology clusters pilot multi-wavelength photoplethysmography wristbands for hypertension management protocols.
China
Domestic MEMS foundries scale accelerometer production for fall-detection algorithms in elderly care facilities. NMPA medical device classification determines which sensor-software combinations qualify for hospital procurement tenders. Shenzhen assembly ecosystems integrate Korean display modules with domestic BLE chipsets for export-oriented fitness tracker manufacturing.
India
CDSCO medical device rules increasingly classify diagnostic mobile apps requiring clinical validation for hospital adoption. Telemedicine platforms target tier-2 cities with low-bandwidth-optimized remote consultation interfaces. Karnataka and Telangana health technology clusters attract venture investment for diabetes management applications serving polypharmacy patient populations.
Mhealth (Mobile Health) Devices Market Competitive Landscape
Channel-controlling players compete with product-specialist players for procurement contracts across hospital systems and direct-to-consumer retail. The vendor base concentrates around vertically integrated consumer electronics conglomerates, regulated medical device incumbents, and component-specialist sensor manufacturers. Three archetypes dominate: platform-anchored technology giants, FDA-cleared therapeutic device specialists, and MEMS foundry-dependent hardware OEMs. Competitive moves center on strategic partnerships with clinical software vendors and backward integration into sensor wafer supply.
Within the platform-anchored tier, Apple Inc. and Samsung Electronics Co., Ltd. exemplify vertically integrated ecosystem strategies that bind biometric collection to cloud analytics infrastructure. Medtronic PLC occupies a position representing the regulated therapeutic specialist archetype, with hospital-anchored distribution sustaining premium pricing for continuous glucose monitoring systems. These three entities anchor competitive dynamics by determining which sensor-software combinations achieve clinical workflow integration and insurance reimbursement eligibility.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics Co., Ltd. |
| Fitbit Inc. |
| Koninklijke Philips N.V. |
| Medtronic PLC |
| Abbott |
| Boston Scientific Corporation |
| Omron Healthcare, Inc. |
| Dexcom Inc. |
| Others |
Supply & Pricing Matrix
Undercapacity at Taiwan Semiconductor Manufacturing's MEMS foundry lines is tightening accelerometer wafer availability and pushing device OEMs toward long-term offtake contracts with indexed pricing clauses. This utilization squeeze concentrates supplier leverage while forcing mid-tier wearable vendors to absorb cost pass-through or cede margin.
Pricing Analysis
Cost-plus contracts with silicon wafer indexation dominate procurement agreements for MEMS sensors and BLE chipsets, insulating foundry partners from commodity volatility while exposing OEMs to raw material swings. Pricing stratifies across FDA-cleared premium tiers, CE-marked standard tiers, and unregulated economy tiers based on clinical validation depth and after-sales service bundling. Cost compression in consumer-grade fitness bands is intensifying because platform gatekeeping fees from Apple and Google extract fixed revenue shares regardless of hardware margins. Healthcare providers exhibit the lowest price sensitivity due to reimbursement code anchoring, while direct-to-consumer purchasers drive steep volume discounts through retail channel consolidation.
Supply Chain Analysis
Silicon wafer feedstock draws from Taiwan Semiconductor Manufacturing, Bosch Sensortec, and domestic Chinese foundries expanding accelerometer capacity for elderly care applications. Critical inputs span 300mm silicon wafers, multi-wavelength PPG optical modules, and sub-1mA BLE transceivers from Japanese semiconductor houses. Single-source vulnerability concentrates in high-precision fall-detection accelerometers where Taiwan and Germany control specialized MEMS etching capabilities. Distribution runs through hospital GPO contracts for regulated devices and consumer electronics retail chains for wellness-oriented wearables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where HealthKit and Galaxy ecosystem lock-in is displacing standalone device margins, and HL7 FHIR interoperability mandates are rewriting procurement criteria for hospital system adoption.
For Market Incumbents: Insulate algorithm revenue streams by embedding predictive analytics as renewable SaaS subscriptions rather than capital equipment, and deepen backward integration into photoplethysmography optical sensor supply to offset MEMS foundry concentration. FDA pre-certification pathways and EU MDR Class IIa compliance investments anchor hospital trust against consumer electronics entrants lacking regulatory affairs infrastructure. For New Entrants and Emerging Players: Establish a beachhead in Japan's sleep apnea screening segment where PMDA Class I streamlined approvals enable rapid market entry ahead of EU MDR backlog queues. Rural US Federally Qualified Health Centers present the most penetrable geography for cellular-enabled remote patient monitoring kits satisfying CMS chronic care management billing requirements. A direct-to-clinic go-to-market angle bypasses retail channel margin extraction. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among telehealth platform operators consolidating virtual care contracts under single-vendor arrangements with health systems. Long-term viability over a multi-year horizon favors FDA-cleared therapeutic device specialists with hospital-anchored distribution and documented clinical endpoints. Watch for reimbursement code expansion signals from CMS and BfArM as inflection indicators for ambulatory cardiac monitoring demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Pre-Certification Pathway | Accelerates algorithm updates for Medtronic and Abbott glucose monitors without full 510(k) resubmission cycles. |
| EU MDR Class IIa Certification | Enables cross-border deployment into Germany, France, and Netherlands through harmonized Software-as-a-Medical-Device routes. |
| Hospital System Partnership | Cleveland Clinic and Mayo Clinic procurement anchors demand for HL7 FHIR-compliant cardiac wearables with EHR integration. |
| Software Companion Development | On-device neural network inference at sub-1mA power budgets enables real-time anomaly detection without cloud dependency. |
| Reimbursement Strategy | CMS chronic care management billing codes and BfArM statutory insurance coverage determine addressable market expansion. |
Research Methodology
Cross-validation between primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists anchors the qualitative findings against secondary validation from FDA 510(k) filings, EMA MDR submissions, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up shipment estimates for MEMS sensors and BLE modules were triangulated against top-down health system IT spending allocations across the analysis window.
Calibration against historical adoption curves for continuous glucose monitors and cardiac wearables shaped the projection framework, with segmentation across product type, end user, connectivity technology, and application driving the analytical structure. CAGRs were derived from elasticity modeling against reimbursement code expansion and regulatory pathway timelines, incorporating photoplethysmography sensor cost curves and foundry capacity utilization as industry-specific forecast inputs.
Stress conditions across FDA pre-certification throughput, EU notified body backlog duration, and MEMS wafer supply concentration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding interoperability mandate implementation and chronic disease management billing code stability. Material shifts in EU AI Act risk-classification enforcement or Taiwan semiconductor export restrictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Cast Removal Devices Market
Medical Devices
Global Cardiac Pacemakers Market
Medical Devices
Anti-Fatigue Lenses Market
Medical Devices
Soft Tissue Release Systems Market
Medical Devices
Direct-Skin Wearable Medical Devices Market
Medical Devices
Phakic Intraocular Lenses (IOL) Market
Medical Devices
USA Artificial Organs and Bionic Implants Market
Medical Devices
Automated CPR Devices Market
Medical Devices
IV Poles Market
Medical Devices
Engine-Driven Endodontic File Market
Medical Devices
Surgical Mesh Market
Medical Devices
Surgical Loupes and Cameras Market
Medical Devices
Pen Injectors Market
Medical Devices
Ear Tube Devices Market
Medical Devices
Anti-Infective Endotracheal Tube Market
Medical Devices
Japan Electric Wheelchair Market