
 Brain Ischemia Market | 2026-2036
Brain Ischemia Market Size, Share, and Industry Trends Forecast 2026-2036
Brain Ischemia Market Analysis
Acute intervention revenue is rewriting profitability profiles across the neurovascular landscape. Boehringer Ingelheim International GmbH anchors European thrombolytic drug supply through manufacturing scale in Germany. Penumbra Inc. specializes in aspiration thrombectomy systems that compete on procedural speed against stent-retriever alternatives. Medtronic controls the broadest geographic distribution footprint for stroke devices across North American and Asian markets.
Brain ischemia denotes inadequate cerebral blood flow causing neuronal injury, typically from thrombotic or embolic vessel occlusion, with tissue plasminogen activator remaining the standard pharmacologic intervention for eligible patients within hours of symptom onset. Thrombectomy Devices command the largest product-type margin pool due to procedural reimbursement premiums and disposable catheter economics. AI Diagnostics represents the fastest-expanding technology segment as machine-learning algorithms compress image interpretation time for emergency department triage decisions.
The FDA regulates neurointerventional devices through premarket approval pathways while the EMA's Medical Device Regulation imposes stricter clinical evidence requirements for CE-marked thrombectomy platforms in Europe. Japan's PMDA maintains distinct review timelines that shape product launch sequencing across developed markets. Stakeholders must weigh regulatory investment against the concentration of stroke incidence in aging populations when prioritizing geographic expansion decisions.
Market Dynamics
The Brain Ischemia Market pivots on acute intervention revenue models where thrombectomy reimbursement premiums compress hospital purchasing cycles and disposable catheter economics reshape vendor profitability structures.
Growth Catalysts
- Comprehensive Stroke Center Certification:The Joint Commission's certification mandates in the United States drive infrastructure investment in neurointerventional suites across tertiary hospitals.
- AI-Enabled Triage:Machine-learning algorithms for emergency department image interpretation compress door-to-treatment timelines and expand eligible patient pools.
- Japan's PMDA Accelerated Pathways:Distinct review timelines for breakthrough neurointerventional devices enable earlier commercial access compared to standard PMA routes.
Market Restraints
- Platinum-Iridium Alloy Concentration:Catheter electrode and guidewire production depends on South African and Russian refined metal supply subject to export volatility.
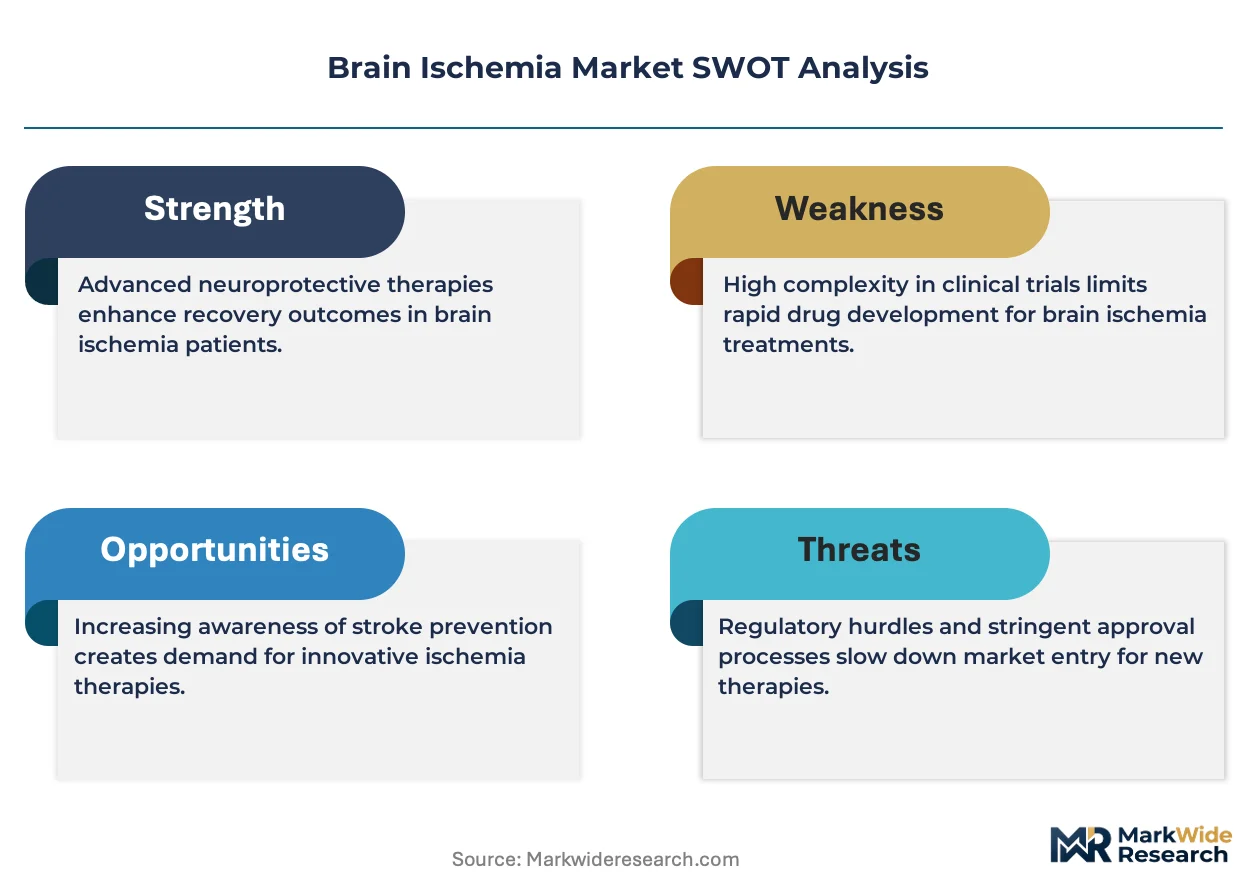
- EMA MDR Clinical Evidence Burden:Stricter post-market surveillance requirements for CE-marked thrombectomy platforms extend European launch timelines by eighteen to twenty-four months.
- Pharmacologic Substitution Ceiling:Tissue plasminogen activator remains the standard of care for non-large-vessel occlusions, limiting mechanical intervention penetration in mild stroke presentations.
Strategic Opportunities
- Mobile Stroke Unit Deployment:Prehospital CT-equipped ambulances in Germany and the Netherlands enable field thrombolysis and direct-to-angiography routing.
- Telestroke Network Expansion:Hub-and-spoke models connecting rural emergency departments to academic comprehensive stroke centers via real-time videoconferencing unlock undertapped geography.
- FDA Breakthrough Device Designation:Expedited access pathways for novel aspiration platforms create first-mover advantages in competitive thrombectomy segments.
Industry Challenges
- Neurointerventionalist Workforce Scarcity:Fellowship-trained physicians capable of mechanical thrombectomy remain concentrated at academic medical centers, constraining procedural capacity expansion.
- CE-MDR Technical Documentation Burden:Small and mid-cap device manufacturers face disproportionate compliance costs relative to revenue base for European market maintenance.
- Legacy PACS Integration Friction:AI diagnostic software deployment requires costly interoperability workarounds with hospital radiology information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brain Ischemia Market |
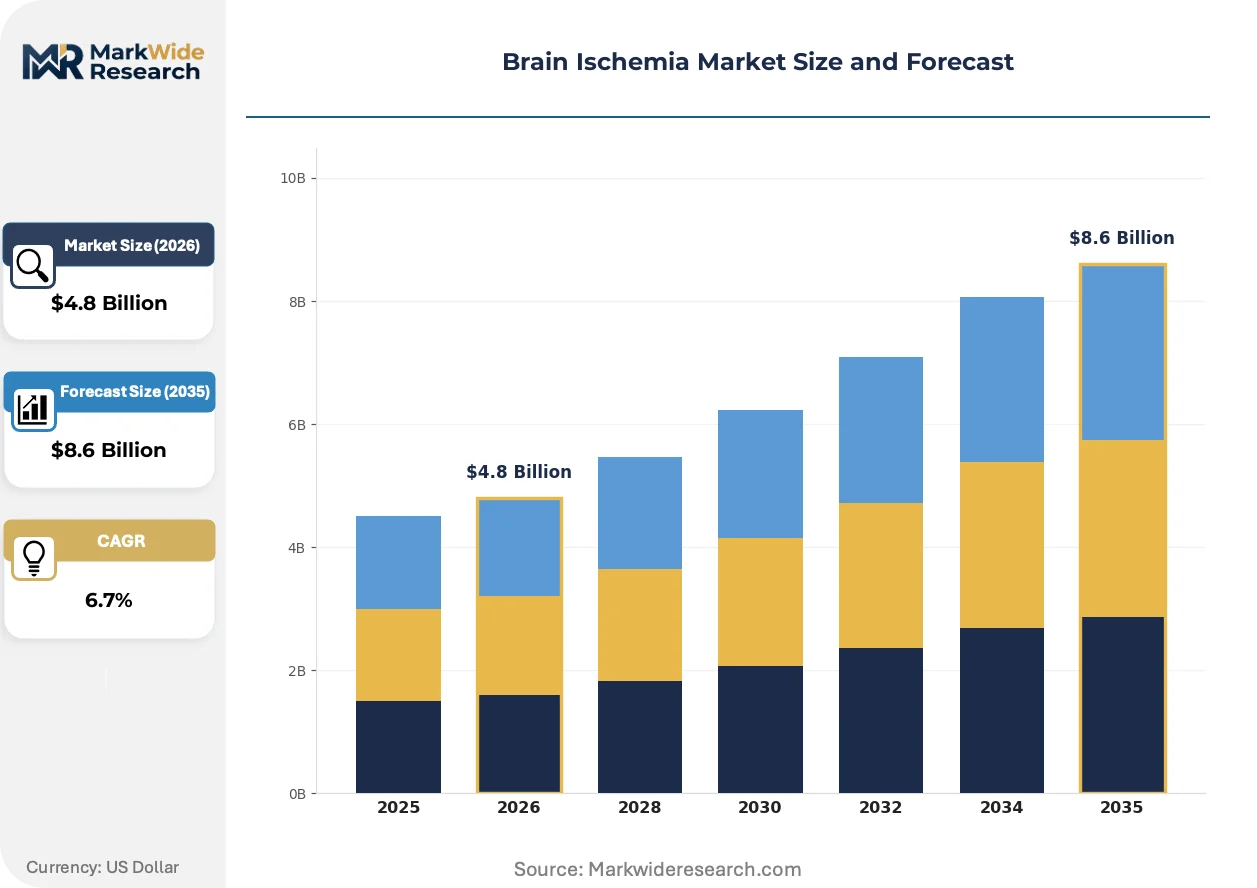
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thrombectomy Devices, Stents, Neuroprotective Agents, Imaging Equipment End User: Hospitals, Outpatient Clinics, Rehabilitation Centers, Emergency Services Treatment Method: Medical Intervention, Surgical Procedures, Drug Therapy, Physical Therapy Technology: CT Scans, MRI, Telemedicine, AI Diagnostics |
| Companies Covered | Boehringer Ingelheim International GmbH, Novartis AG, Pfizer Inc., Bristol-Myers Squibb Company, Johnson & Johnson, AstraZeneca plc, Medtronic, Abbott, Penumbra Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brain Ischemia Market Emerging Trajectories
Thrombectomy platform evolution and diagnostic algorithm deployment are compressing treatment windows and rewriting acute stroke care economics across hospital systems.
Next-generation aspiration catheters with distal tip optimization and improved trackability are rendering obsolete first-generation stent-retriever dominance in anterior circulation large vessel occlusion cases. Comprehensive stroke centers in the United States and Japan are adopting these platforms as primary mechanical intervention tools. The shift is compressing procedural times and reducing the need for combined stent-retriever and aspiration approaches.
Europe's Medical Device Regulation imposes enhanced clinical evidence requirements for CE-marked thrombectomy platforms, forcing manufacturers to sponsor prospective registry studies beyond historical predicate-based approvals. The industrial consequence is elevated R&D allocation toward European regulatory dossiers and delayed product launches relative to FDA PMA timelines. Small-cap neurovascular specialists are responding by prioritizing US-Japan launch sequencing and deferring European commercialization.
Hospital procurement committees are consolidating stroke device purchasing under value-analysis frameworks that bundle thrombectomy platforms with annual service contracts and training commitments. The traditional device-only tender model is yielding to partnership structures where vendors guarantee case volume thresholds and staff education. This behavioral shift is most visible in United States integrated delivery networks and German hospital federations seeking to standardize acute stroke protocols across multiple sites.
Brain Ischemia Market Segmentation
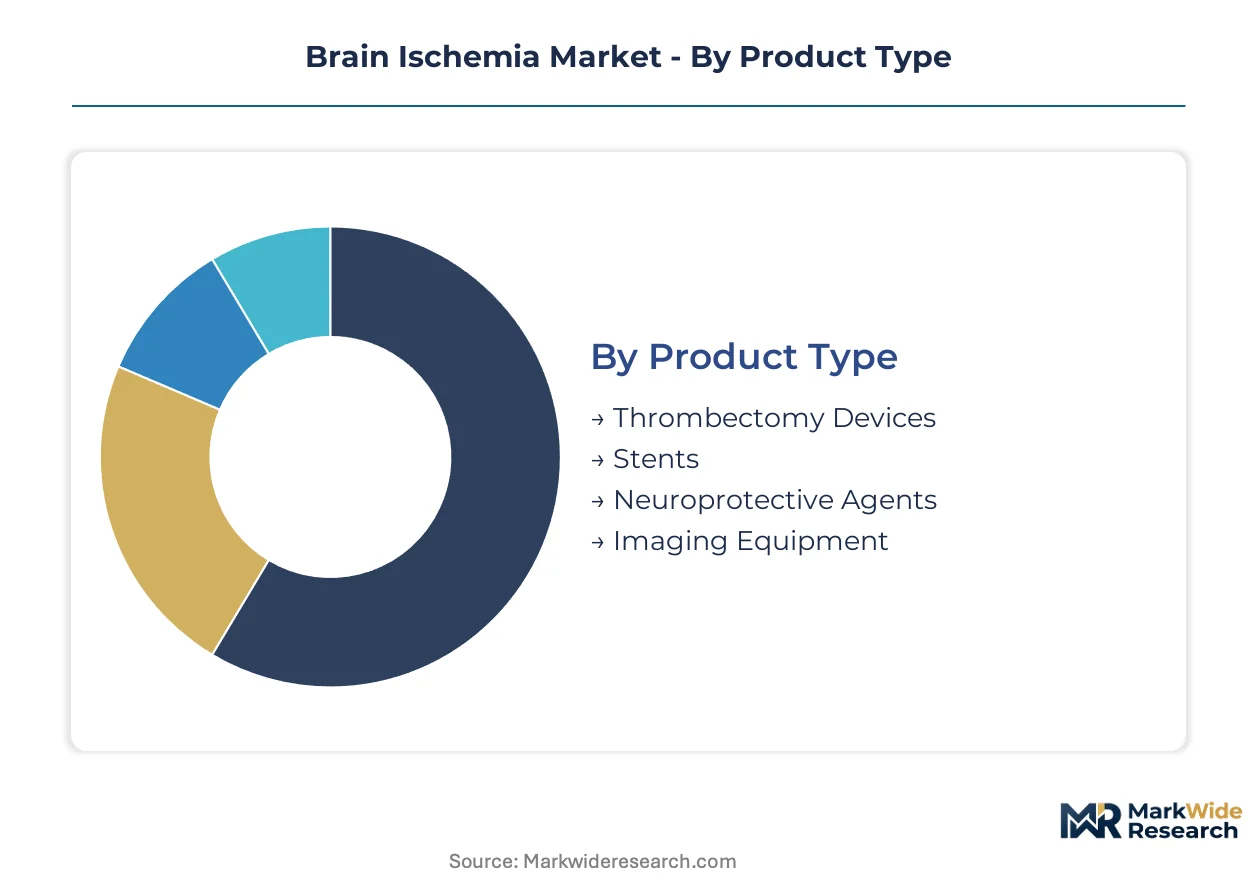
Stroke care economics diverge sharply across intervention modalities. Product-type margins concentrate in disposable mechanical devices, while technology adoption reshapes patient routing and reimbursement structures.
Product Type:
Cost tier stratification separates capital-intensive imaging platforms from high-margin disposable catheters.
- Thrombectomy Devices:Aspiration catheters and stent-retrievers designed for large vessel occlusion extraction command procedural reimbursement premiums. Tertiary hospitals in the United States and Germany prioritize platform standardization across neurointerventional suites to compress door-to-puncture times.
- Neuroprotective Agents:Pharmacologic compounds targeting ischemic cascade interruption remain investigational for most indications. Clinical trial recruitment concentrates in Japan where PMDA accelerated pathways enable earlier proof-of-concept enrollment.
- Stents:Intracranial stenting platforms address tandem occlusions and underlying stenosis.
- Imaging Equipment:Mobile CT and angiography suites enable prehospital diagnosis.
Thrombectomy Devices command the established base. The steepest expansion runs through Neuroprotective Agents.
End User:
Customer type determines purchasing authority complexity and contract structure.
- Hospitals:Comprehensive stroke centers with 24/7 neurointerventional coverage drive thrombectomy volume and device procurement. The Joint Commission certification mandates in the United States require minimum annual case volumes that concentrate purchasing power at high-throughput institutions.
- Emergency Services:Mobile stroke units equipped with CT scanners and telemedicine links enable field thrombolysis and direct-to-angiography routing. Deployment concentrates in Germany and the Netherlands where healthcare system integration supports capital-intensive prehospital infrastructure.
- Outpatient Clinics:TIA assessment and secondary prevention programs manage stroke risk stratification.
- Rehabilitation Centers:Post-acute recovery facilities address functional deficit remediation.
Hospitals anchor the revenue base. Emergency Services are climbing the fastest.
Treatment Method:
Application modality reflects the tension between pharmacologic standard-of-care and mechanical intervention expansion.
- Medical Intervention:Intravenous tissue plasminogen activator remains the time-critical default for eligible patients. Administration concentrates in emergency departments with established stroke protocols and rapid imaging turnaround.
- Surgical Procedures:Mechanical thrombectomy for large vessel occlusion requires specialized neurointerventionalist training. Procedural capacity constraints in the United States limit geographic penetration outside academic medical centers.
- Drug Therapy:Antiplatelet and anticoagulant regimens dominate secondary prevention.
- Physical Therapy:Motor and speech rehabilitation addresses post-stroke functional recovery.
Medical Intervention retains the volume base. Surgical Procedures show the steepest expansion trajectory.
Technology:
Maturity stage separates established diagnostic hardware from algorithmic software deployment.
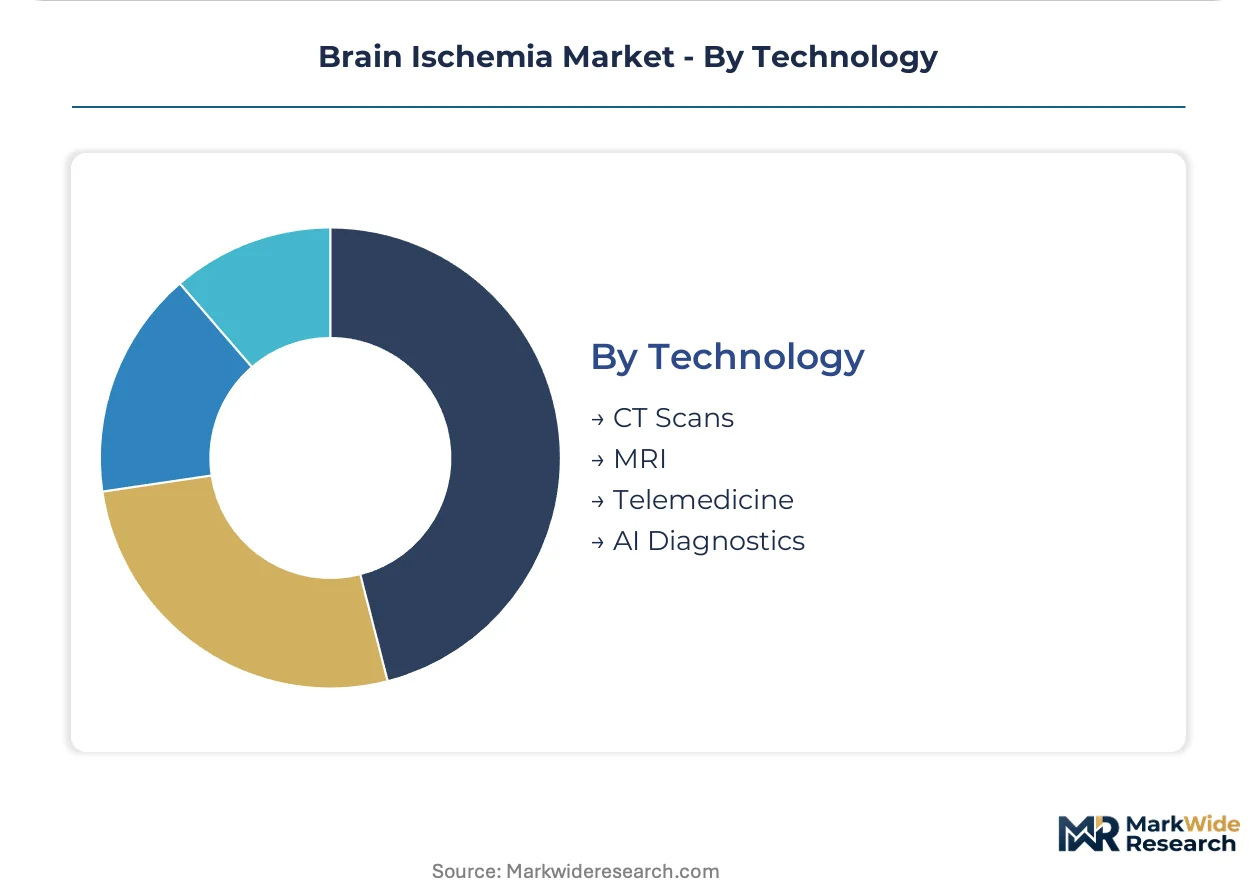
- AI Diagnostics:Machine-learning algorithms for automated large vessel occlusion detection compress image interpretation time. FDA breakthrough device designations for multiple platforms accelerate emergency department triage integration in the United States.
- Telemedicine:Real-time videoconferencing connects rural emergency departments to comprehensive stroke center expertise. Hub-and-spoke network expansion in the United States unlocks geography previously excluded from acute intervention eligibility.
- CT Scans:Non-contrast head CT remains the initial imaging standard for hemorrhage exclusion.
- MRI:Diffusion-weighted imaging provides superior tissue characterization for posterior circulation strokes.
CT Scans command the installed base. AI Diagnostics are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States stroke centers demonstrate the lowest price elasticity for thrombectomy platforms, while Japanese procurement committees negotiate aggressively on catheter unit economics. German hospital federations occupy a middle position, bundling device purchases with training commitments.
United States
The Joint Commission's comprehensive stroke center certification mandates minimum annual case volumes that concentrate purchasing power at high-throughput academic medical centers. FDA breakthrough device designations for AI-enabled triage platforms accelerate emergency department integration timelines. The Cleveland Clinic and Mayo Clinic networks in Ohio and Minnesota standardize thrombectomy protocols across multi-site systems.
Germany
Mobile stroke unit deployment concentrates in Bavaria and North Rhine-Westphalia where prehospital CT-equipped ambulances enable field thrombolysis. EMA Medical Device Regulation imposes stricter clinical evidence requirements that extend CE-mark timelines for thrombectomy platforms. The Berlin-Brandenburg hospital federation bundles stroke device procurement under value-analysis frameworks.
Japan
PMDA accelerated review pathways enable earlier commercial access for breakthrough neurointerventional devices compared to standard PMA routes. Aging demographics concentrate stroke incidence in Kanto and Kansai metropolitan regions. Tokyo University Hospital and Osaka University Medical Center anchor mechanical thrombectomy training networks.
United Kingdom
NHS England's stroke services specification mandates hyper-acute stroke unit coverage within specified travel times, driving infrastructure investment. MHRA post-Brexit regulatory autonomy permits divergence from EMA timelines for certain device categories. The Greater London stroke network consolidates thrombectomy referrals to designated comprehensive centers.
Netherlands
Healthcare system integration supports capital-intensive mobile stroke unit deployment in Randstad urban corridors. Dutch hospital procurement cooperatives negotiate standardized thrombectomy platform contracts across member institutions. The Erasmus MC in Rotterdam anchors a national telestroke network connecting peripheral emergency departments.
Brain Ischemia Market Vendor Landscape
Pharmaceutical incumbents and device specialists split the market along intervention modality lines. Boehringer Ingelheim anchors thrombolytic drug supply through German manufacturing scale, while Penumbra and Medtronic compete on procedural speed and geographic coverage respectively. Three archetypes dominate: integrated pharma-device conglomerates, pure-play neurovascular specialists, and diversified medtech platforms. Competitive dynamics center on M&A consolidation of aspiration catheter technology and strategic partnerships for AI diagnostic integration.
Among German-based pharmaceutical manufacturers, Boehringer Ingelheim International GmbH exemplifies the integrated drug-device archetype with European thrombolytic supply chain control. California-headquartered Penumbra Inc. occupies a position within the neurovascular specialist tier, while Irish-domiciled Medtronic represents the diversified medtech platform model with broad stroke device distribution. These three entities anchor distinct competitive vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| Boehringer Ingelheim International GmbH |
| Novartis AG |
| Pfizer Inc. |
| Bristol-Myers Squibb Company |
| Johnson & Johnson |
| AstraZeneca plc |
| Medtronic |
| Abbott |
| Penumbra Inc. |
| Others |
Supply Flow & Price Mechanics
Rhineland-Palatinate's Boehringer Ingelheim manufacturing complex anchors European thrombolytic drug supply, translating captive production scale into pricing leverage against contract-manufactured competitors. This geographic concentration of active pharmaceutical ingredient capacity enables volume-based contracting that compresses procurement costs for integrated hospital networks.
Pricing Analysis
After-sales revenue through training contracts and service agreements drives lifetime value for thrombectomy platform vendors. Three-tier pricing structure across premium aspiration systems, standard stent-retrievers, and economy guidewire bundles separates comprehensive stroke centers from community hospitals. Pricing pressure stems from German hospital federation bundling demands that force vendors to guarantee case volume thresholds. Community hospitals exhibit highest price sensitivity due to constrained neurointerventional case volumes.
Supply Chain Analysis
Contract manufacturing for catheter electrodes concentrates in Minnesota medical device clusters and Irish medtech facilities serving European markets. Platinum-iridium alloy feedstock draws from South African refined metal supply and Russian export channels, creating single-source vulnerability for electrode production. Distribution runs through specialized neurovascular distributors holding FDA device establishment registrations before hospital value-analysis committee review.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Stroke care economics are shifting toward platform-ecosystem models where AI diagnostic software integration determines thrombectomy device purchasing decisions. Interoperability between imaging algorithms and hospital PACS architectures is becoming the primary vendor selection criterion.
For Market Incumbents: Build installed-base moats through AI diagnostic software bundling with thrombectomy platform contracts. Consolidate market position by acquiring aspiration catheter technology specialists before FDA breakthrough designations expire. Defend against pure-play AI diagnostic entrants by embedding algorithms within existing catheter sales relationships.
For New Entrants and Emerging Players: Rural United States telestroke networks represent the most penetrable geography for hub-and-spoke AI diagnostic deployment. Target emergency services mobile stroke unit procurement in German Bavaria and Dutch Randstad corridors where prehospital CT infrastructure enables field triage algorithms. Enter through software-only partnerships with established catheter vendors lacking internal AI development.
For Investors and Strategic Acquirers: Long-term, this sits as a procedure-volume compounding play because aging demographics in Japan and Germany concentrate stroke incidence in metropolitan regions with comprehensive stroke center infrastructure. Acquisition targets should display FDA breakthrough device designation progress or PMDA accelerated pathway enrollment. Monitor thrombectomy case volume thresholds at The Joint Commission-certified centers as inflection signal for platform adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Diagnostic Software Companion Development | FDA breakthrough designation for large vessel occlusion detection accelerates emergency department integration timelines. |
| Hospital System Partnership | Comprehensive stroke center certification mandates at The Joint Commission concentrate purchasing power for multi-site contracting. |
| CE Marking Pathway | EMA MDR clinical evidence requirements extend European launch timelines and elevate R&D allocation toward registry studies. |
| Reimbursement Strategy | Procedural reimbursement premiums for mechanical thrombectomy compress hospital purchasing cycles and reshape vendor profitability. |
| Geographic Manufacturing Footprint | PMDA accelerated review pathways enable earlier commercial access in Kanto and Kansai metropolitan regions. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with neurointerventionalists, hospital purchasing committee members, and regulatory affairs specialists at device manufacturers; and secondary validation against FDA PMA filings, PMDA review summaries, ClinicalTrials.gov stroke intervention records, and CMS Medicare reimbursement databases. Bottom-up procedure volume estimates triangulated against top-down market sizing across product type and technology segments.
Forecast inputs incorporated thrombectomy device shipment data, comprehensive stroke center certification expansion trajectories, and AI diagnostic software regulatory approval timelines across the analysis window. Segmentation modeling covered product type, end user, treatment method, and technology adoption patterns. CAGRs derived from procedure volume growth assumptions anchored in aging demographic projections and neurointerventionalist workforce expansion constraints.
Practitioners should monitor PMDA accelerated pathway enrollment rates and EMA MDR technical documentation submission timelines for early signals of competitive positioning shifts. Forecasts reflect assumptions regarding platinum-iridium supply stability and The Joint Commission certification mandate enforcement. Quarterly review of thrombectomy reimbursement code valuations and mobile stroke unit deployment statistics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Central Nervous System Lymphoma Treatment Market
Neurology
Global Lambert-Eaton Myasthenic Syndrome Treatment Market
Neurology
Tourette Syndrome Market
Neurology
Neuropsychiatric Disorders and Treatment Market
Neurology
Global Acoustic Neuroma Market
Neurology
Global Vertigo Treatment Market
Neurology
Demyelinating Diseases Therapeutics Market
Neurology
Neuroprotection Market
Neurology
United Kingdom Neurology Devices Market
Neurology
Middle-East and Africa Neurology Monitoring Market
Neurology
Ulnar Nerve Treatment Market
Neurology
Central Nervous System (CNS) Therapeutics Market
Neurology
Mexico Neurology Devices Market
Neurology
Neurocutaneous Disorders Market
Neurology
Neurology Software Market
Neurology
Neuro Critical Care Market