
 Middle East and Africa Fetal and Neonatal Monitoring Market | 2026-2036
Middle East and Africa Fetal and Neonatal Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Fetal and Neonatal Monitoring Market Foresight
Maternity centers is realigning procurement priorities across the Middle East and Africa, shifting from basic delivery services toward comprehensive perinatal surveillance suites. GE Healthcare anchors its regional position through deep channel partnerships with ministry of health tender programs. Koninklijke Philips differentiates via wireless system portfolios designed for intermittent power environments common in East African facilities. Siemens Healthineers competes on magnetic sensor accuracy standards that appeal to Gulf-based tertiary referral hospitals.
Fetal and neonatal monitoring encompasses electronic systems that track maternal uterine activity, fetal heart rate patterns, and newborn vital signs through cardiotocography, pulse oximetry, and acoustic sensor modalities, typically operating at 1-30 Hz signal acquisition frequencies for obstetric decision support. Cardiotocography dominates current installed bases across Egyptian and Saudi Arabian hospitals due to established clinical training pathways and reimbursement alignment. Neonatal monitors represent the fastest-growing product category as preterm birth intervention programs expand in Ethiopia and Kenya. Wireless systems command premium positioning in South African private hospital chains where nurse mobility and infection control drive capital allocation.
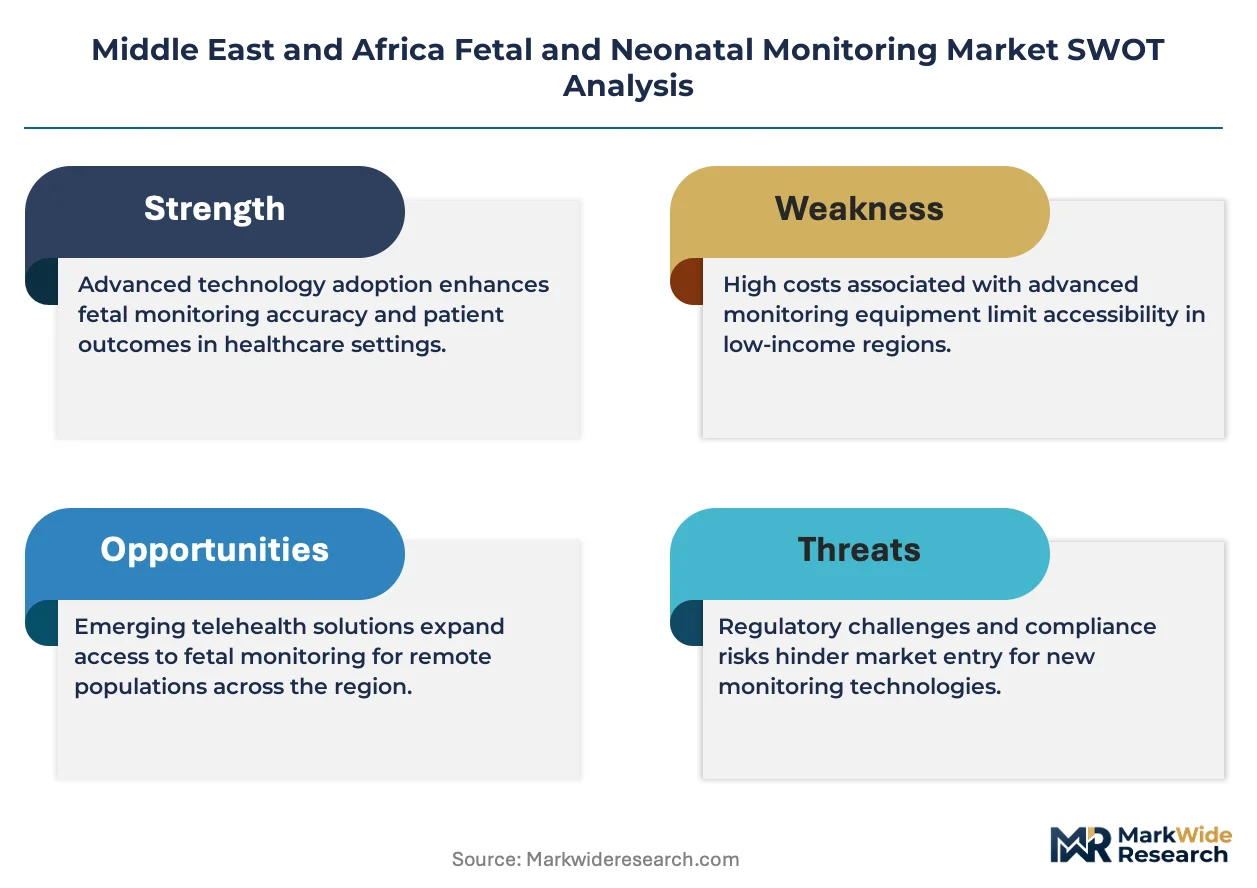
South Africa's Health Products Regulatory Authority and Saudi Food and Drug Authority enforce device registration requirements that filter out uncertified suppliers, elevating compliance costs for market entrants. The EU Medical Device Regulation exerts indirect harmonization pressure on Gulf states that reference CE marking in national procurement specifications. Stakeholders must monitor how Nigeria's proposed medical device regulatory framework reshapes West African import pathways and distributor qualification requirements.
Market Dynamics
Wireless telemetry architectures are compressing installation timelines across Middle East and Africa maternity units where infrastructure deficits previously delayed wired system deployments. This shift is redrawing competitive positioning between legacy cardiotocography vendors and portable monitoring specialists.
Growth Catalysts
- Saudi Food and Drug Authority registration pathways:Streamlined device approval processes for CE-marked products accelerate market entry timelines for European manufacturers targeting Gulf hospital tenders.
- Ethiopian preterm birth intervention programs:Government-funded neonatal intensive care unit expansions generate concentrated demand for multiparameter monitoring platforms in Addis Ababa referral hospitals.
- Cloud-native telemetry:Real-time data streaming to centralized command centers enables remote obstetric oversight across South African provincial health networks with specialist shortages.
Market Restraints
- Import duty structures:Nigerian customs classifications impose 20% levies on electronic medical devices, elevating landed costs for pulse oximetry modules against locally assembled alternatives.
- Single-source sensor dependency:Magnetic sensor cores for fetal heart rate detection concentrate among three East Asian component suppliers, exposing procurement to shipping corridor disruptions.
- Intermittent grid reliability:Power fluctuation tolerance requirements in Kenyan county hospitals necessitate costly uninterruptible power supply integration for wired monitoring installations.
Strategic Opportunities
- Ugandan referral hospital network:Underpenetrated secondary care facilities present first-mover positioning for wireless monitoring vendors ahead of Ministry of Health standardization mandates.
- Telemedicine integration:Convergence of fetal monitoring data with regional telehealth platforms creates subscription revenue streams for equipment-as-a-service models in South African private chains.
- UAE Ministry of Health and Prevention perinatal quality initiatives:Mandatory electronic fetal surveillance documentation in Dubai and Abu Dhabi tertiary centers drives replacement cycles for legacy paper-based systems.
Industry Challenges
- Biomedical engineering specialization gaps:Nigerian and Kenyan training institutions produce insufficient technicians qualified for wireless telemetry calibration and preventive maintenance protocols.
- Multi-jurisdiction registration complexity:Separate South African Health Products Regulatory Authority and Saudi Food and Drug Authority dossier requirements extend product launch timelines by 14-18 months.
- Legacy CTG integration:New wireless platforms must interface with entrenched cardiotocography workstations in Egyptian teaching hospitals, complicating data architecture standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Fetal and Neonatal Monitoring Market |
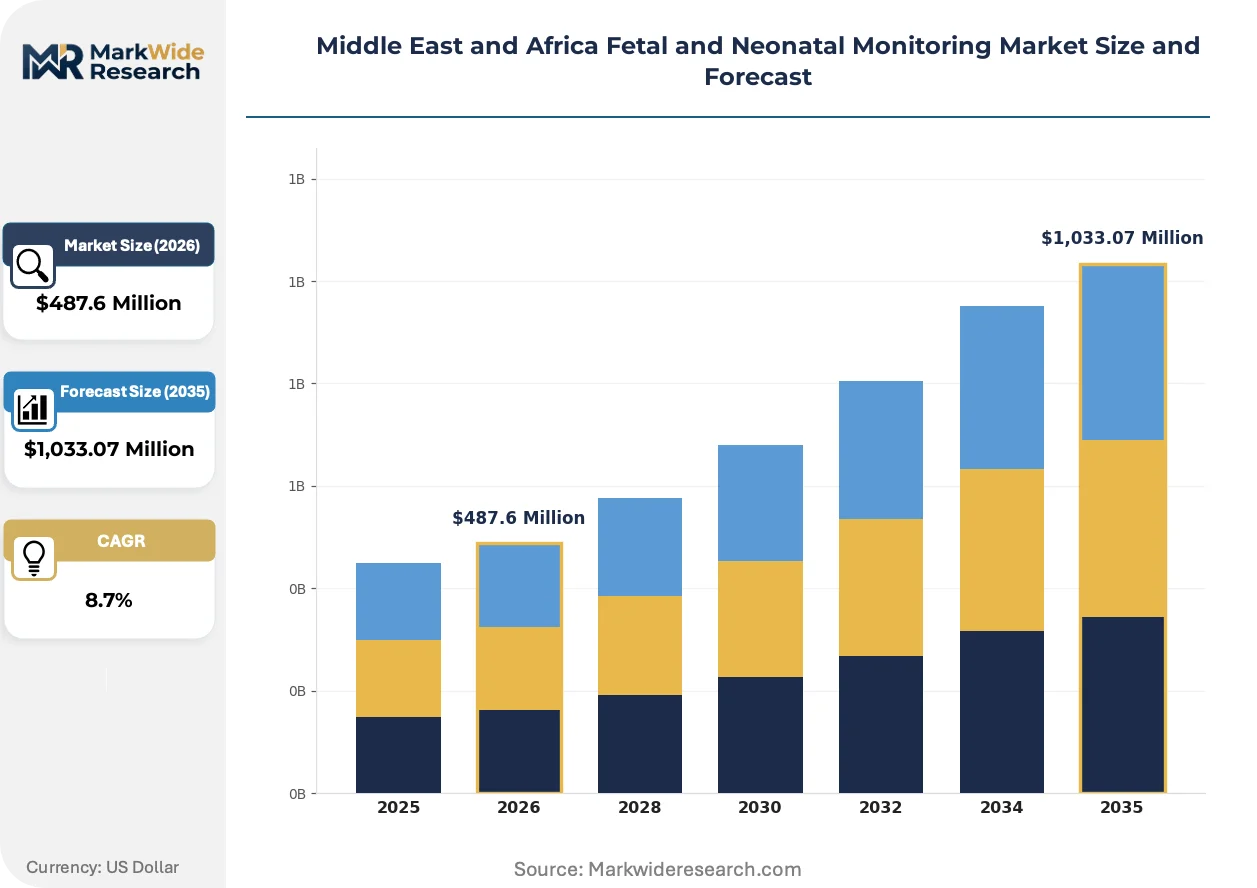
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cardiotocography, Fetal Monitors, Neonatal Monitors, Ultrasound Devices End User: Hospitals, Clinics, Homecare, Maternity Centers Technology: Wireless Systems, Portable Monitors, Magnetic Sensors, Software Solutions Application: Labor Monitoring, Fetal Heart Rate Analysis, Neonatal Care, Diagnostic Imaging |
| Companies Covered | Becton, Dickinson and Company, GE Healthcare, Koninklijke Philips, Medtronic, Siemens Healthineers, Dragerwerk, The Cooper Companies, FUJIFILM, Natus Medical, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Fetal and Neonatal Monitoring Market Shifts & Advancements
Signal processing advances and connectivity architectures are converging to reshape how perinatal data flows through clinical decision chains across Middle East and Africa health systems.
Artificial intelligence pattern recognition for fetal heart rate variability analysis is automating baseline interpretation tasks previously requiring continuous specialist oversight. South African private hospital groups deploy these systems in high-volume maternity units to reduce obstetrician alert fatigue during overnight shifts. The technology is automating triage prioritization, compressing response times for abnormal cardiotocography traces without proportional nursing staff expansion.
EU Medical Device Regulation harmonization pressure extends into Gulf Cooperation Council procurement specifications, with Saudi and UAE tender documents increasingly referencing CE marking as a technical prerequisite. This regulatory convergence elevates compliance documentation burdens for manufacturers but simultaneously streamlines multi-country registration strategies. East African facilities respond by consolidating purchasing through regional distributors holding consolidated regulatory dossiers.
Leasing and managed service arrangements displace capital purchase models among Nigerian faith-based hospital networks facing foreign exchange volatility and constrained credit access. Equipment vendors absorb utilization risk while securing predictable revenue streams through per-delivery or per-patient monitoring fees. This financing restructuring concentrates in Lagos and Abuja metropolitan corridors where private maternity volume justifies operational scale.
Middle East and Africa Fetal and Neonatal Monitoring Market Segmentation
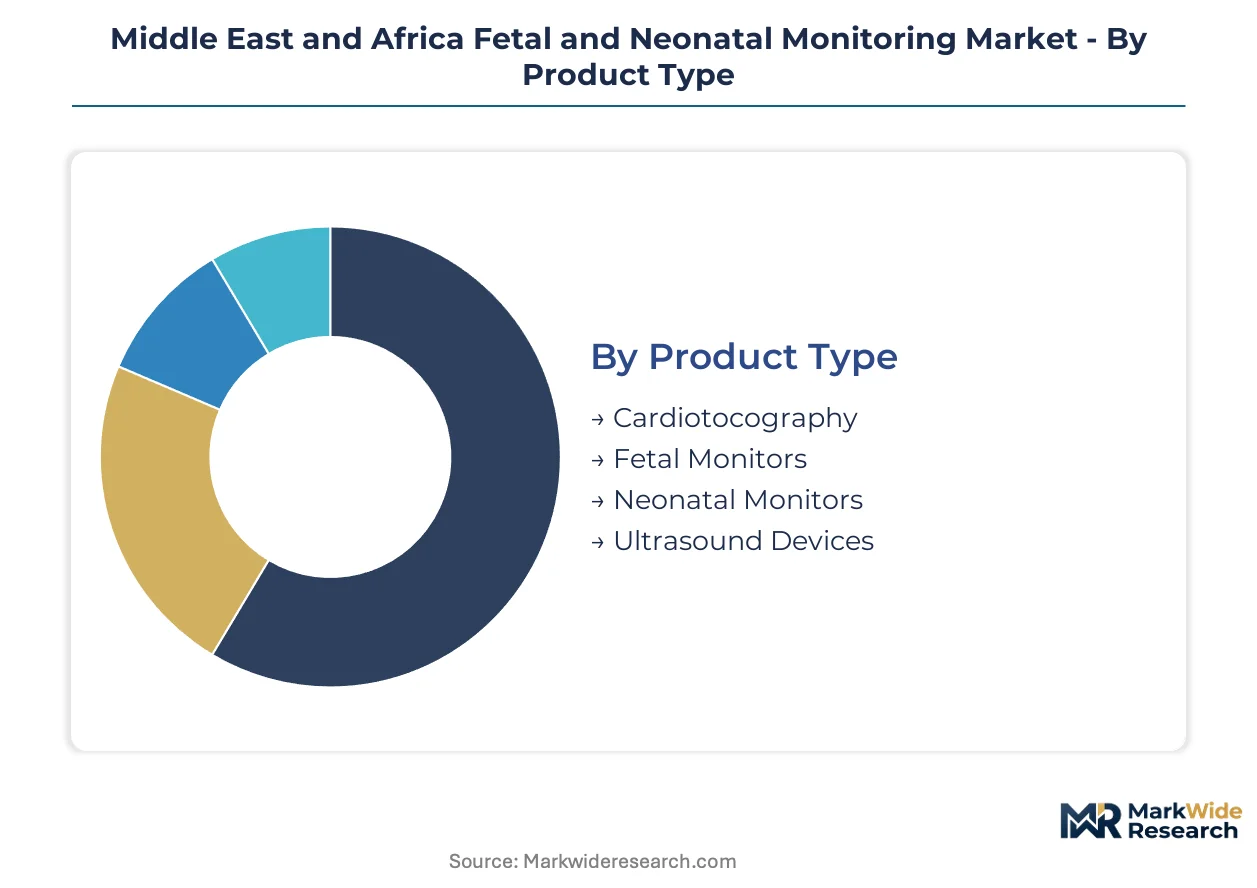
Product architecture, deployment setting, and signal acquisition method each impose distinct regulatory pathways and procurement economics across Middle East and Africa perinatal care systems. Understanding how these dimensions intersect clarifies vendor positioning and tender qualification requirements.
Product Type:
SFDA registration timelines vary by product complexity, with cardiotocography systems requiring extended clinical evidence dossiers compared to standalone pulse oximetry modules.
- Cardiotocography:Integrated uterine contraction and fetal heart rate platforms dominate Egyptian and Saudi Arabian installed bases due to established reimbursement codes and specialist training curricula. Demand concentrates in Gulf tertiary referral hospitals where electronic fetal surveillance documentation is becoming mandatory.
- Neonatal Monitors:Multiparameter vital signs platforms for preterm and low-birth-weight infants are expanding most quickly through Ethiopian government-funded NICU programs and Kenyan county hospital upgrades. These systems require harmonized CE marking and SFDA dual certification for Gulf procurement eligibility.
- Fetal Monitors:Dedicated antepartum surveillance units serve South African private maternity chains and Nigerian faith-based hospital networks.
- Ultrasound Devices:Portable imaging systems support diagnostic confirmation in Ugandan and Tanzanian district facilities with limited specialist access.
Leading the category by volume: Cardiotocography. Growing fastest: Neonatal Monitors.
End User:
Capital allocation patterns diverge sharply between public procurement channels and private maternity chains, with payment security and foreign exchange risk determining vendor participation.
- Hospitals:Tertiary academic medical centers in Cairo, Riyadh, and Johannesburg anchor demand for integrated monitoring suites with telemetry connectivity. These facilities command preferential pricing through ministry tender aggregation but impose extended warranty and biomedical training obligations.
- Maternity Centers:Specialized obstetric facilities across South Africa's private hospital groups and UAE's Dubai Healthcare City cluster are prioritizing wireless-enabled labor suites. Nurse mobility requirements and infection control protocols drive capital allocation toward cable-free architectures.
- Clinics:Secondary care facilities in Ethiopian and Kenyan regional hubs concentrate demand for portable, battery-operated monitoring.
- Homecare:Remote fetal surveillance remains nascent, constrained by reimbursement absence and connectivity gaps in rural Nigeria.
Procurement volume concentrates: Hospitals. Fastest expansion trajectory: Maternity Centers.
Technology:
Signal acquisition architecture determines power tolerance requirements and installation feasibility across grid-unreliable East African facilities.
- Wireless Systems:Telemetry-enabled platforms eliminate cable clutter and enable centralized command center oversight across South African provincial networks with specialist shortages. Battery backup integration and intermittent power tolerance command premium positioning in Nigerian tertiary hospitals.
- Magnetic Sensors:Fetal heart rate detection cores from concentrated East Asian component suppliers expose procurement to shipping corridor disruption risks. Gulf-based tertiary hospitals specify magnetic accuracy standards that filter out uncertified alternatives.
- Portable Monitors:Handheld or cart-based systems serve Ugandan referral hospitals and Tanzanian district facilities with infrastructure constraints.
- Software Solutions:AI-enabled pattern recognition for cardiotocography baseline interpretation is automating triage prioritization in high-volume South African private maternity units.
Revenue concentration: Wireless Systems. Steepest expansion trajectory: Software Solutions.
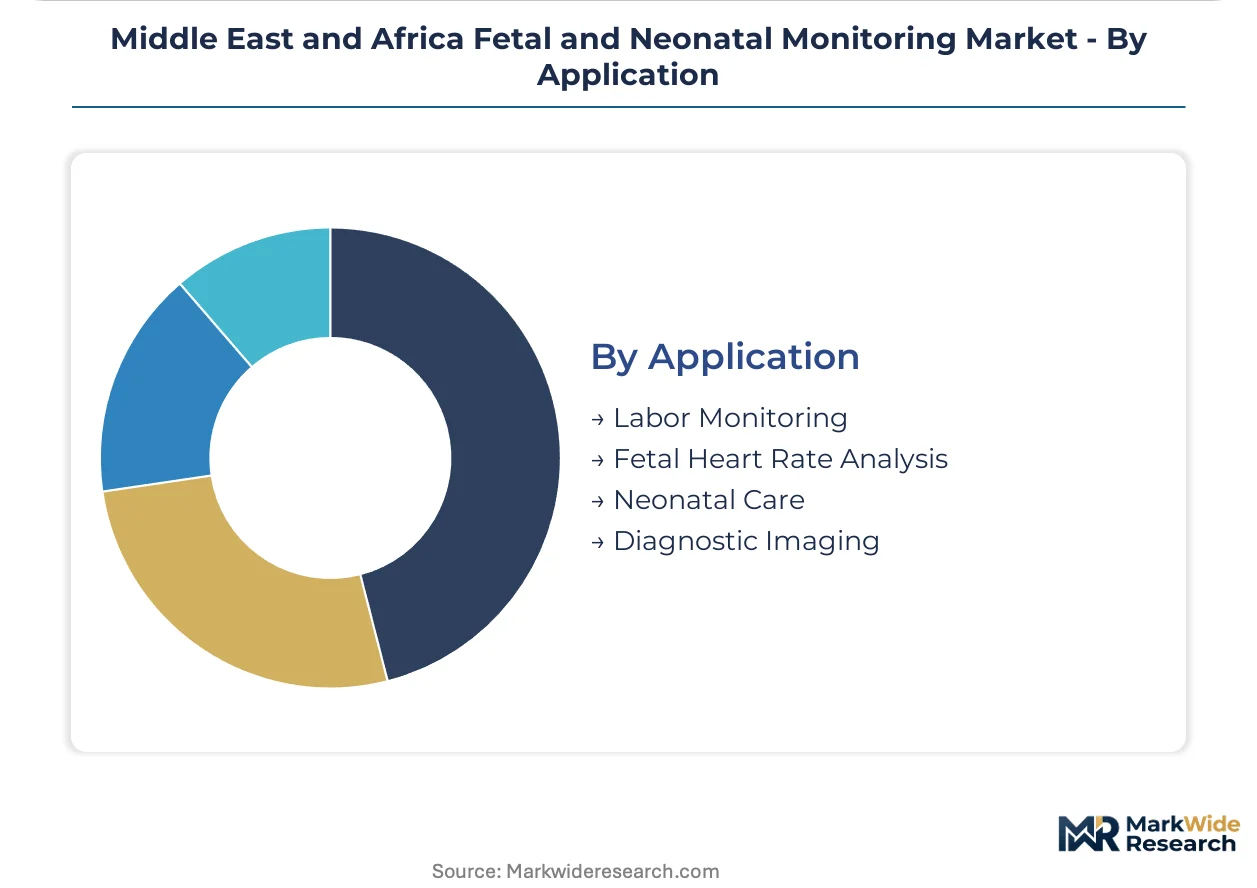
Application:
Clinical use case determines sensor modality combination and data integration requirements with existing electronic medical record architectures.
- Labor Monitoring:Intrapartum cardiotocography with real-time alerting dominates Saudi and UAE tertiary center specifications. UAE Ministry of Health and Prevention quality initiatives mandate electronic documentation, forcing replacement of paper-based legacy systems.
- Neonatal Care:Post-delivery vital signs surveillance for preterm infants is climbing the fastest through Ethiopian preterm birth intervention programs and Kenyan county hospital NICU expansions. Multiparameter platforms with pulse oximetry and temperature monitoring command procurement priority.
- Fetal Heart Rate Analysis:Antepartum non-stress testing supports high-risk pregnancy management in South African academic centers.
- Diagnostic Imaging:Ultrasound confirmation complements electronic monitoring in Egyptian teaching hospitals with entrenched cardiotocography workstations.
Volume leadership: Labor Monitoring. Gaining share fastest: Neonatal Care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai Healthcare City and South Africa's special economic zones for medical device manufacturing concentrate regional distribution and technical support infrastructure for perinatal monitoring systems.
Saudi Arabia
Government-funded tertiary hospital expansions in Riyadh and Jeddah drive demand for integrated cardiotocography suites. The Saudi Food and Drug Authority streamlined CE-marked device registration, cutting approval timelines for European manufacturers. Eastern Province referral hospitals are replacing legacy paper-based fetal surveillance with electronic documentation systems.
United Arab Emirates
Mandatory electronic fetal surveillance documentation under Ministry of Health and Prevention quality initiatives forces replacement cycles in Dubai and Abu Dhabi tertiary centers. Dubai Healthcare City clusters private maternity chains prioritizing wireless-enabled labor suites. Abu Dhabi-based procurement aggregations command preferential pricing through volume consolidation.
South Africa
Provincial health networks with specialist shortages deploy cloud-native telemetry for remote obstetric oversight. The Health Products Regulatory Authority enforces device registration requirements that filter uncertified suppliers. Johannesburg and Cape Town private hospital chains prioritize nurse mobility through cable-free monitoring architectures.
Nigeria
Faith-based hospital networks in Lagos and Abuja metropolitan corridors adopt leasing models to bypass foreign exchange volatility. Proposed medical device regulatory framework reshapes West African import pathways and distributor qualification requirements. Tertiary hospitals specify wireless systems with battery backup for intermittent grid environments.
Ethiopia
Government-funded neonatal intensive care unit expansions in Addis Ababa generate concentrated demand for multiparameter monitoring platforms. Preterm birth intervention programs climb fastest through Ministry of Health budget allocations. Regional referral hospitals in secondary cities present first-mover positioning for portable monitoring vendors.
Middle East and Africa Fetal and Neonatal Monitoring Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated system vendors commanding Gulf tertiary tenders while portable specialists penetrate East African county facilities. The vendor base concentrates among five multinational conglomerates with established ministry-of-health channel relationships. Two strategic archetypes dominate: full-suite obstetric platform providers and wireless telemetry specialists. Competitive moves center on strategic partnerships with regional distributors and portfolio diversification into AI-enabled pattern recognition software.
Among diversified health technology conglomerates, GE Healthcare, Koninklijke Philips, and Siemens Healthineers occupy positions shaped by their regional channel architectures. GE Healthcare anchors Gulf Cooperation Council positioning through deep ministry tender partnerships. Koninklijke Philips exemplifies the wireless-specialist archetype with portfolios designed for intermittent power environments. Siemens Healthineers represents the premium-tier magnetic sensor accuracy segment appealing to tertiary referral standards.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| GE Healthcare |
| Koninklijke Philips |
| Medtronic |
| Siemens Healthineers |
| Dragerwerk |
| The Cooper Companies |
| FUJIFILM |
| Natus Medical |
| Others |
Supply & Pricing Matrix
Wireless telemetry migration is compressing installation timelines while simultaneously elevating capital equipment premiums and concentrating procurement power among Gulf-based ministry tender aggregators. This dual effect tightens margins for legacy cardiotocography vendors while rewarding portable system specialists with pricing leverage in grid-unreliable East African facilities.
Pricing Analysis
Short lead-time premiums command substantial markups in Saudi Arabian and UAE tertiary hospital tenders where ministry procurement cycles compress vendor response windows. Three-tier pricing structure across premium wireless telemetry, standard wired cardiotocography, and economy portable monitors stratifies by CE marking tier and after-sales service bundling. Cost compression in the economy tier intensifies because Nigerian faith-based networks and Kenyan county hospitals prioritize spot inventory purchases over long-term service contracts. Public procurement channels exhibit highest price sensitivity due to foreign exchange volatility and budget rigidity, while South African private hospital chains demonstrate lowest sensitivity given nurse mobility and infection control priorities.
Supply Chain Analysis
Single-source vulnerability sits with East Asian magnetic sensor core suppliers, exposing fetal heart rate detection module procurement to shipping corridor disruptions through the Red Sea and Suez Canal. Manufacturing concentrates in China, South Korea, and Germany, with final assembly drawing from Taiwanese semiconductor foundries and Malaysian electronics packaging facilities. Component dependencies include rare earth magnetic materials, medical-grade pulse oximetry LEDs, and lithium-ion battery cells for wireless telemetry backup. Tariff exposure runs through Nigerian customs classifications imposing elevated levies on electronic medical devices. Distribution runs through Dubai Healthcare City logistics hubs and Johannesburg special economic zones serving regional ministry tender programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Magnetic sensor fabrication capacity constraints prop pricing premiums for certified fetal heart rate detection modules, creating durable margin structures for vendors with secured component supply.
For Market Incumbents: Extend wireless telemetry portfolios into AI-enabled pattern recognition software to defend against portable monitoring specialists capturing East African county hospital upgrades. Anchor Gulf Cooperation Council positioning through deeper ministry tender partnerships while adding local biomedical training capabilities to meet extended warranty obligations. Backward integration into magnetic sensor sourcing reduces exposure to East Asian supplier concentration. For New Entrants and Emerging Players: SFDA streamlined CE-marked device registration in Saudi Arabia opens a window for European manufacturers to penetrate Gulf tertiary hospital replacement cycles ahead of entrenched competitors. Target Ugandan referral hospital networks and Ethiopian regional secondary facilities where wireless monitoring penetration remains underdeveloped. Pursue equipment-as-a-service financing models to bypass capital purchase barriers in Nigerian faith-based hospital networks facing credit access constraints. For Investors and Strategic Acquirers: Re-rating potential sits with wireless telemetry specialists given cloud-native telemetry convergence with regional telehealth platforms. Acquisition target archetypes include portable monitoring vendors with established East African distributor relationships and consolidated regulatory dossiers spanning SAHPRA and SFDA requirements. Watch for Nigerian medical device regulatory framework finalization as inflection indicator reshaping West African import pathway economics.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | Streamlined SFDA registration accelerates Gulf hospital tender eligibility for European manufacturers. |
| Hospital System Partnership | Deep ministry relationships secure preferential pricing in Saudi and UAE tertiary center aggregations. |
| Software Companion Development | AI-enabled cardiotocography pattern recognition automates triage in South African high-volume maternity units. |
| Reimbursement Strategy | Alignment with Ethiopian government-funded NICU programs unlocks multiparameter monitor procurement channels. |
| Geographic Expansion | Ugandan referral hospital network penetration captures first-mover positioning ahead of Ministry standardization mandates. |
Research Methodology
Document review covered hospital procurement databases, GPO contracts, and ministry tender specifications, complemented by interviews with biomedical engineers, hospital purchasing committee members, and distributor regulatory affairs specialists. Secondary validation drew from SAHPRA registration filings, SFDA device approval records, and customs trade data. Bottom-up demand modeling across product segments triangulated against top-down health expenditure forecasts.
Cross-referencing historical installation data with expert panel input on technology transition timelines shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product architecture, deployment setting, signal acquisition method, and regional regulatory cluster. CAGRs were derived from weighted average growth trajectories incorporating preterm birth intervention program expansion rates and wireless telemetry adoption curves.
Caveats apply where Nigerian regulatory framework implementation delays or Red Sea shipping corridor disruptions could materially shift the outlook. Forecasts reflect assumptions on ministry budget allocation continuity and CE marking harmonization persistence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Portable Multi-Parameter Monitors Market
Patient Monitoring
United States Patient Monitoring Market
Patient Monitoring
Blood Pressure Monitors Market
Patient Monitoring
Contact-Free Sleep Monitoring Systems Market
Patient Monitoring
Asia-Pacific Fetal and Neonatal Monitoring Market
Patient Monitoring
United Kingdom Patient Monitoring Market
Patient Monitoring
Epro, E-Patient Diaries and Ecoa Market
Patient Monitoring
Critical Care Patient Monitoring Products Market
Patient Monitoring
AI in Remote Patient Monitoring Market
Patient Monitoring
Monitoring Wristband Market
Patient Monitoring
Holter Monitor Market
Patient Monitoring
Europe Respiratory Monitoring Market
Patient Monitoring
Blood Temperature Indicator Market
Patient Monitoring
Global Heart Rate Monitor Market
Patient Monitoring
South Korea Patient Monitoring Market
Patient Monitoring
South America Respiratory Monitoring Market