
 Hearing Aid Dehumidifier Market | 2026-2036
Hearing Aid Dehumidifier Market Size, Share, and Industry Trends Forecast 2026-2036
Hearing Aid Dehumidifier Market Foresight
CE marking under the EU Medical Device Regulation is reorganizing competitive access for hearing aid dehumidifier manufacturers serving European clinical channels. Dry & Store leverages its established presence in audiology practice supply chains to sustain recurring revenue from professional accounts. FlowMed anchors its position through specialized desiccant technology leadership, while PerfectDry competes on portable form factors targeting direct-to-consumer segments.
A hearing aid dehumidifier is an electromechanical or passive device designed to extract moisture from hearing instruments using desiccant media, thermoelectric cooling elements, or UV-C sterilization cycles operating at 40-60°C, preserving microphone sensitivity and battery contact integrity in humid climates or post-activity recovery protocols. Electric units dominate installed base volumes in clinical settings where overnight conditioning cycles are standard, while portable desiccant capsules capture the fastest-growing demand among travelers and active users requiring field-level moisture management. Online retail channels now occupy the highest-margin pool as subscription-based desiccant replenishment models displace one-time pharmacy purchases.
The FDA's OTC hearing aid framework and the EU MDR's expanded accessory classification are forcing manufacturers to recalibrate labeling claims and biocompatibility testing for devices marketed alongside regulated hearing instruments. ISO 10993 materials safety standards and IEC 60601 electromagnetic compatibility requirements further govern product design for electrically active dehumidifiers distributed through hospital procurement channels. Stakeholders must monitor how OTC hearing aid penetration reshapes the customer mix between professional audiologist supply and direct consumer acquisition, as this shift will determine which distribution investments yield durable returns.
Market Dynamics
The FDA's OTC Hearing Aid Act is bifurcating distribution channels, forcing dehumidifier manufacturers to simultaneously serve professional audiology supply chains and direct-to-consumer retail without cross-contaminating pricing or positioning.
Growth Catalysts
- Aging demographics in the United States:Expanded Medicare Advantage hearing benefits are driving clinical procurement of electric conditioning units for post-fitting patient protocols.
- ISO 10993 biocompatibility standards:Harmonized materials safety testing is reducing regulatory friction for manufacturers seeking hospital procurement channel access across multiple jurisdictions.
- Desiccant capsule technology:Portable moisture management solutions are capturing traveler and active-user demand previously unserved by clinical-grade electric units.
Market Restraints
- Silica gel supply concentration:Specialty desiccant production clusters in East Asian chemical processing hubs, exposing manufacturers to input cost volatility and logistics disruption.
- IEC 60601 electromagnetic compatibility testing:Electrically active dehumidifiers face extended certification timelines and third-party laboratory capacity constraints in European notified bodies.
- Passive drying substitutes:Low-cost rice-based and zeolite pouch alternatives compete on price in pharmacy and mass retail channels, compressing margin for branded desiccant systems.
Strategic Opportunities
- Subscription replenishment models:Direct-to-consumer desiccant cartridge auto-ship programs are displacing one-time pharmacy purchases and capturing recurring revenue pools.
- CE marking under EU MDR:Reorganized accessory classification creates first-mover advantage for manufacturers achieving notified body certification ahead of competitor filings.
- UV-C sterilization convergence:Integration of ultraviolet germicidal irradiation with thermoelectric drying cycles addresses infection control protocols in hospital audiology departments.
Industry Challenges
- Biocompatibility testing capacity:ISO 10993 cytotoxicity and sensitization studies face bottlenecks at contract research organizations, delaying product launches for electrically active units.
- Channel conflict management:Manufacturers must prevent professional audiology distributors from diverting inventory to unauthorized online marketplaces that undercut direct-to-consumer pricing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hearing Aid Dehumidifier Market |
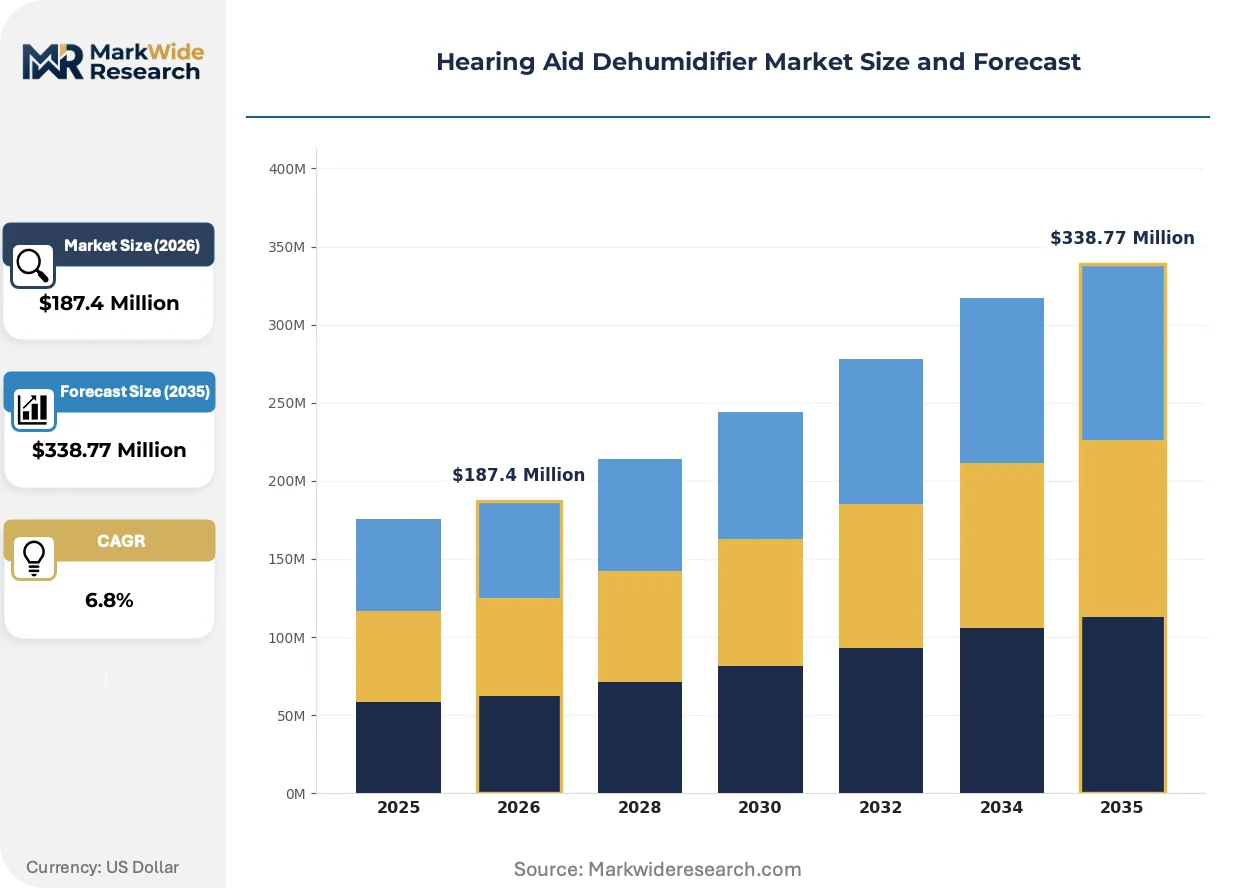
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Manual, Portable, Built-in End User: Individuals, Audiologists, Hospitals, Rehabilitation Centers Technology: Desiccant, UV Light, Thermoelectric, Passive Distribution Channel: Online Retail, Pharmacies, Direct Sales, Specialty Stores |
| Companies Covered | Dry & Store, FlowMed, HalHen, PerfectDry, Wisesorb, iQDry, Redux, Serene Innovations, ADCO Hearing Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hearing Aid Dehumidifier Market Shifts & Advancements
Product architecture is converging around connected conditioning cycles, regulatory labeling harmonization, and procurement model unbundling that separates hardware from consumable revenue streams.
Thermoelectric cooling elements with precision temperature control at 40-60°C are displacing passive desiccant systems in clinical settings where overnight conditioning protocols demand reproducible outcomes. Audiologists and hearing clinics in the United States are adopting these electric units at accelerated pace as professional fitting protocols expand. This displacement is compressing the addressable market for basic desiccant capsules within institutional procurement channels while elevating technical performance thresholds for supplier qualification.
The EU Medical Device Regulation's expanded accessory classification is reorganizing compliance pathways for dehumidifiers marketed alongside regulated hearing instruments. Manufacturers must now complete biocompatibility testing and notified body review for products previously self-certified under legacy directives. Electrically active dehumidifiers with UV-C sterilization face the most stringent scrutiny, with German and French notified bodies establishing precedent for clinical-grade accessory approval.
Audiologist supply chains are unbundling hardware procurement from desiccant replenishment, creating separate contracting relationships for device placement versus consumable fulfillment. This pattern is most visible in United States multi-site audiology practice groups negotiating enterprise pricing for electric conditioning units while sourcing desiccant capsules through group purchasing organizations. The shift fragments vendor relationships and elevates purchasing sophistication among professional buyers who previously accepted bundled offerings.
Hearing Aid Dehumidifier Market Segmentation
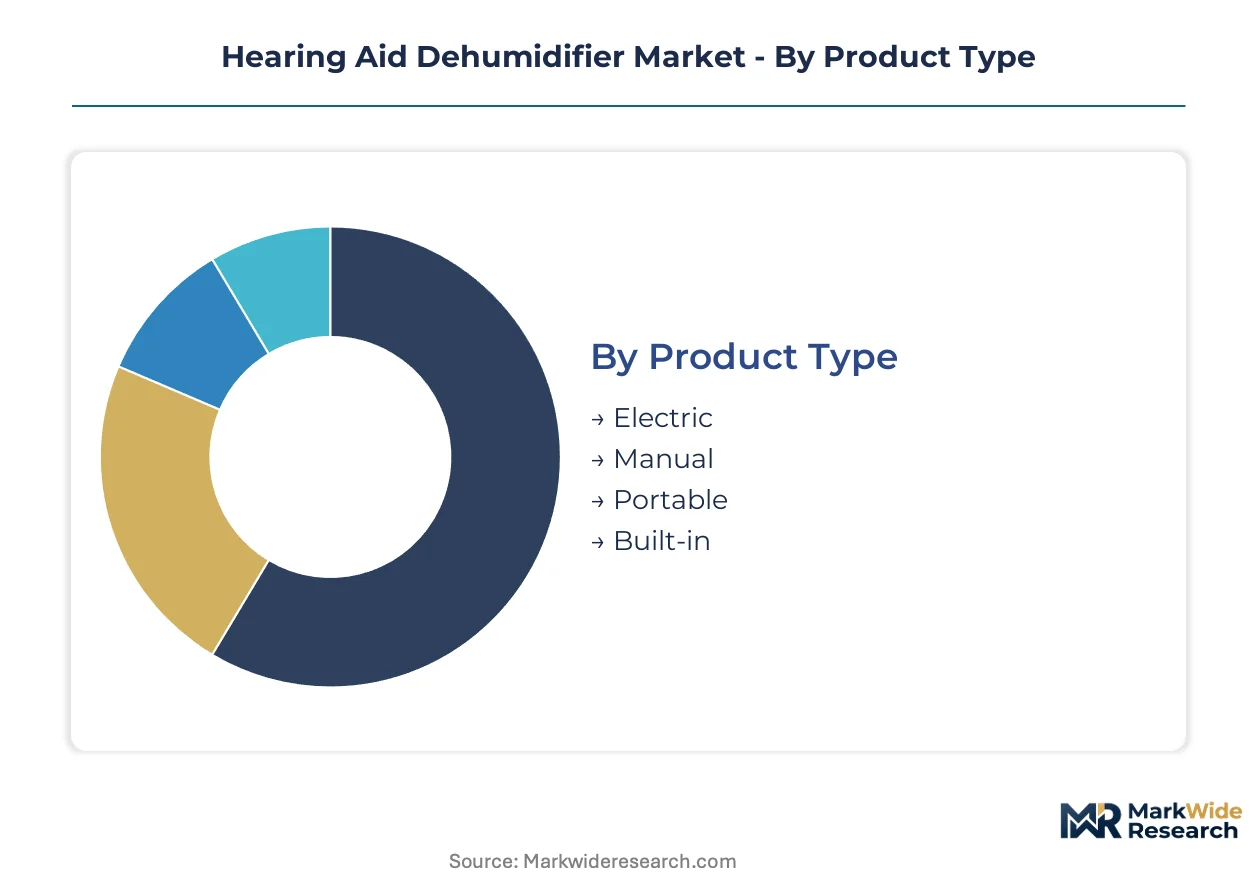
Segmentation in hearing aid dehumidifiers reveals how moisture management technology splits across professional protocols and consumer self-care. Each dimension—product architecture, user setting, drying mechanism, and purchase pathway—carries distinct regulatory, margin, and loyalty implications.
Product Type:
Electric units concentrate manufacturing in domestic US and German facilities serving clinical procurement channels, while portable and manual variants flow primarily from East Asian contract manufacturers into direct-to-consumer retail.
- Electric:Thermoelectric cooling elements with precision temperature modulation at 40-60°C dominate audiologist practice supply chains in the United States. Medicare Advantage hearing benefit expansion is accelerating clinical procurement of these units for overnight patient conditioning protocols.
- Portable:Battery-powered or passive capsule systems capture traveler and active-user demand previously unserved by clinical-grade equipment. German and Japanese consumers show strongest preference for pocket-sized desiccant solutions during humid summer months.
- Manual:Hand-activated desiccant canisters require no power source and appeal to price-sensitive users in rural markets with unreliable electricity.
- Built-in:Integrated drying compartments within hearing aid charging stations are gaining traction among premium device manufacturers seeking ecosystem lock-in.
Electric holds the largest share; momentum sits with Portable as field-level moisture management expands beyond clinical settings.
End User:
Cost tier separation is pronounced: institutional buyers negotiate enterprise pricing for electric conditioning fleets while individuals absorb premium markups on portable convenience.
- Audiologists:Professional fitting protocols in the United States increasingly mandate overnight conditioning cycles, driving bulk procurement of thermoelectric units with UV-C sterilization. FDA OTC Hearing Aid Act compliance requirements are reshaping how these practices source accessories alongside regulated devices.
- Individuals:Direct-to-consumer acquisition is climbing fastest as OTC hearing aid penetration shifts moisture management from clinical guidance to self-directed purchase. Online subscription models for desiccant replenishment are displacing one-time pharmacy transactions.
- Hospitals:Infection control protocols in audiology departments favor electric units with documented sterilization cycles meeting ISO 10993 biocompatibility standards.
- Rehabilitation Centers:Volume procurement concentrates in VA and Medicare-funded facilities managing veteran hearing health across multiple sites.
Audiologists command the revenue concentration; individuals are expanding most quickly as channel bifurcation accelerates.
Technology:
Maturity gradients separate established desiccant chemistry from emerging convergence architectures combining multiple drying mechanisms.
- Desiccant:Silica gel and molecular sieve media remain the baseline for passive moisture absorption, with supply concentration in East Asian chemical processing hubs creating input cost volatility for manufacturers.
- Thermoelectric:Peltier-effect cooling with closed-loop temperature control is displacing passive systems in clinical settings where reproducible outcomes matter. IEC 60601 electromagnetic compatibility testing creates certification bottlenecks at European notified bodies.
- UV Light:Ultraviolet germicidal irradiation integrated with drying cycles addresses hospital infection control requirements, particularly in German and French clinical procurement channels under EU MDR accessory classification.
- Passive:Zeolite and clay-based pouches compete on price in pharmacy and mass retail, compressing margin for branded systems despite inferior performance metrics.
Desiccant retains volume leadership; thermoelectric is gaining share fastest as professional protocols harden performance thresholds.
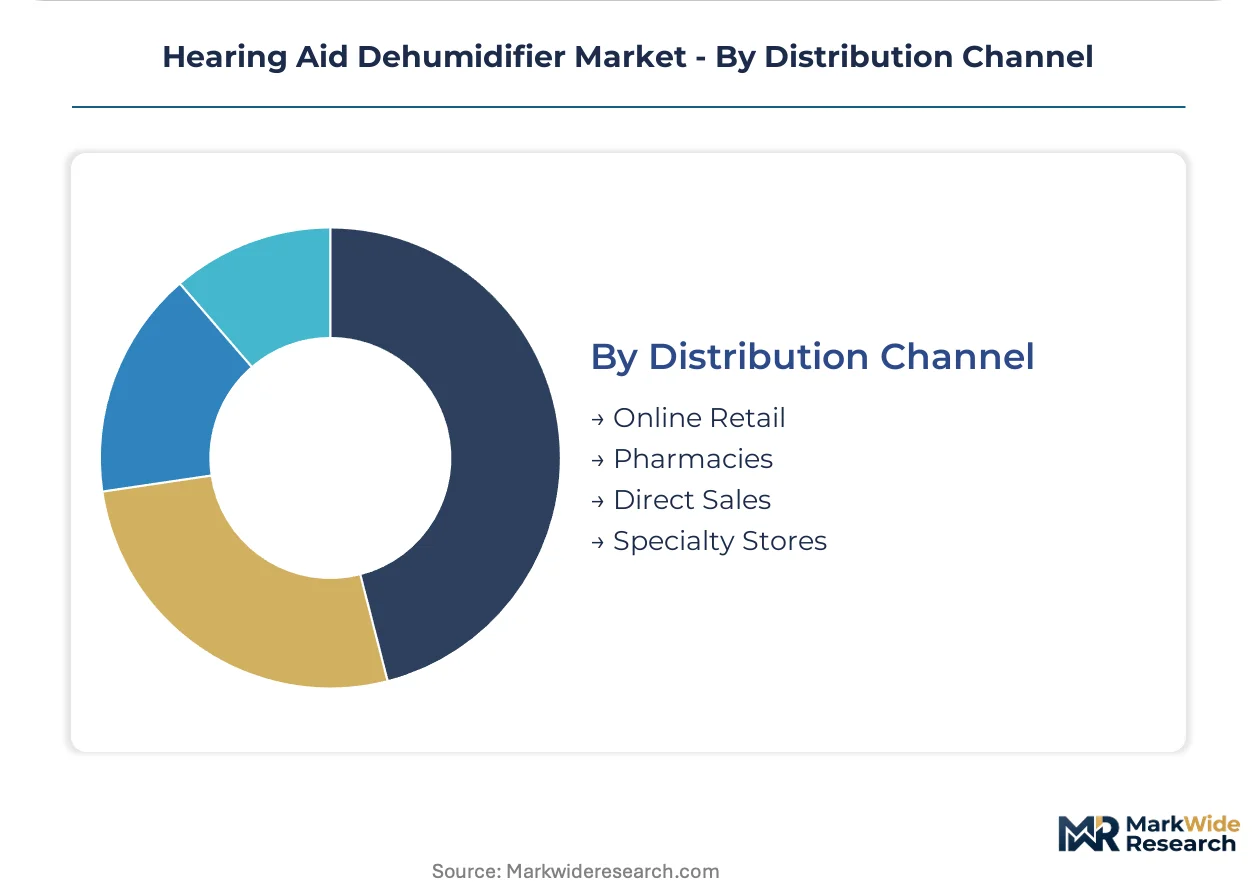
Distribution Channel:
Margin structure inverts between high-touch specialty placement and automated replenishment economics.
- Online Retail:Direct-to-consumer platforms capture the highest-margin pool through subscription-based desiccant auto-ship programs. Amazon and specialized hearing health portals dominate US consumer acquisition, with German and UK markets showing parallel trajectory.
- Direct Sales:Manufacturer relationships with multi-site audiology groups unbundle hardware from consumable fulfillment, fragmenting vendor relationships that previously accepted bundled offerings.
- Pharmacies:Mass retail chains serve price-sensitive consumers seeking immediate availability, though shelf space competition from low-cost rice-based substitutes compresses branded positioning.
- Specialty Stores:Hearing instrument retailers and audiology supply houses maintain professional-grade electric unit placement alongside fitting services.
Online retail commands margin expansion; direct sales relationships with audiology groups are climbing fastest as procurement sophistication increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical processing throughput underwrites European desiccant supply chains, while the Port of Long Beach anchors US West Coast distribution for East Asian-manufactured portable units. These maritime gateways shape regional procurement economics for hearing aid dehumidifiers.
United States
Medicare Advantage hearing benefit expansion drives clinical procurement of electric conditioning units. FDA OTC Hearing Aid Act compliance requirements reshape accessory sourcing protocols for audiology practices. Minneapolis-St. Paul audiology supply chains concentrate professional-grade distribution infrastructure.
Germany
EU MDR notified body certification creates competitive bottlenecks for electrically active dehumidifiers. CE marking under expanded accessory classification demands biocompatibility testing for hospital channel access. Munich and Stuttgart audiology equipment clusters specialize in thermoelectric precision manufacturing.
Japan
Aging demographics and JIS standards compliance elevate demand for compact portable solutions. METI medical device regulations govern electromagnetic compatibility for electric units. Osaka-based hearing instrument manufacturers integrate drying compartments into premium charging ecosystems.
United Kingdom
NHS audiology service procurement favors cost-effective desiccant systems for patient take-home protocols. MHRA post-Brexit device regulations diverge from EU MDR timelines. London and Manchester audiology practice groups negotiate enterprise pricing for conditioning hardware.
South Korea
MFDS medical device approval accelerates domestic adoption of UV-C sterilization convergence products. Seoul Capital Area hearing health clinics drive premium electric unit penetration. Busan port logistics facilitate East Asian desiccant raw material import flows.
Hearing Aid Dehumidifier Market Competitive Landscape
Listed leaders compete with private specialists across regulatory certification capacity, creating a tiered structure where scale advantages in notified body relationships separate sustainable competitors from marginal entrants. The vendor base clusters around three strategic archetypes: audiology supply chain incumbents with professional channel lock-in, direct-to-consumer specialists exploiting subscription economics, and component OEMs supplying branded house labels. Dominant competitive moves include CE marking pre-emption under EU MDR timelines and backward integration into desiccant media production to escape East Asian supply concentration.
Within the audiology supply tier, Dry & Store and FlowMed exemplify professional channel anchoring through practice supply chain relationships. PerfectDry occupies a position representing portable form factor specialization targeting traveler and active-user segments directly. These three entities collectively illustrate how regulatory compliance capacity and distribution architecture determine competitive sustainability across bifurcated professional and consumer channels.
| Leading Market Players |
|---|
| Dry & Store |
| FlowMed |
| HalHen |
| PerfectDry |
| Wisesorb |
| iQDry |
| Redux |
| Serene Innovations |
| ADCO Hearing Products |
| Others |
Supply & Pricing Matrix
Thermoelectric Peltier elements replacing passive desiccant systems in clinical procurement channels simultaneously shift manufacturing gravity toward precision electronics hubs in Germany and the United States while compressing margin pools for commodity silica gel suppliers concentrated in East Asia.
Pricing Analysis
Certification level (ISO 10993/IEC 60601/CE marking tier) creates the primary spread between hospital-grade electric units and mass-market portable capsules. Three-tier pricing structure across clinical, professional, and consumer levels reflects biocompatibility testing investment and electromagnetic compliance depth. Cost compression in the desiccant capsule tier intensifies as rice-based substitutes capture pharmacy shelf space. Individual consumers exhibit highest price sensitivity, while hospital audiology departments absorb premium markups for documented sterilization protocols.
Supply Chain Analysis
China and South Korea anchor specialty desiccant chemical production, while Germany and the United States concentrate thermoelectric precision manufacturing. Electric unit assembly draws from East Asian ceramic substrates and European temperature control modules. Single-source vulnerability in silica gel supply clusters exposes manufacturers to logistics disruption through the Port of Rotterdam. Distribution runs through audiology supply houses for clinical-grade equipment and Amazon-specialized portals for direct-to-consumer replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Channel bifurcation under the FDA OTC Hearing Aid Act fragments vendor relationships and creates service-layer niches where unified moisture management ecosystems remain underdeveloped.
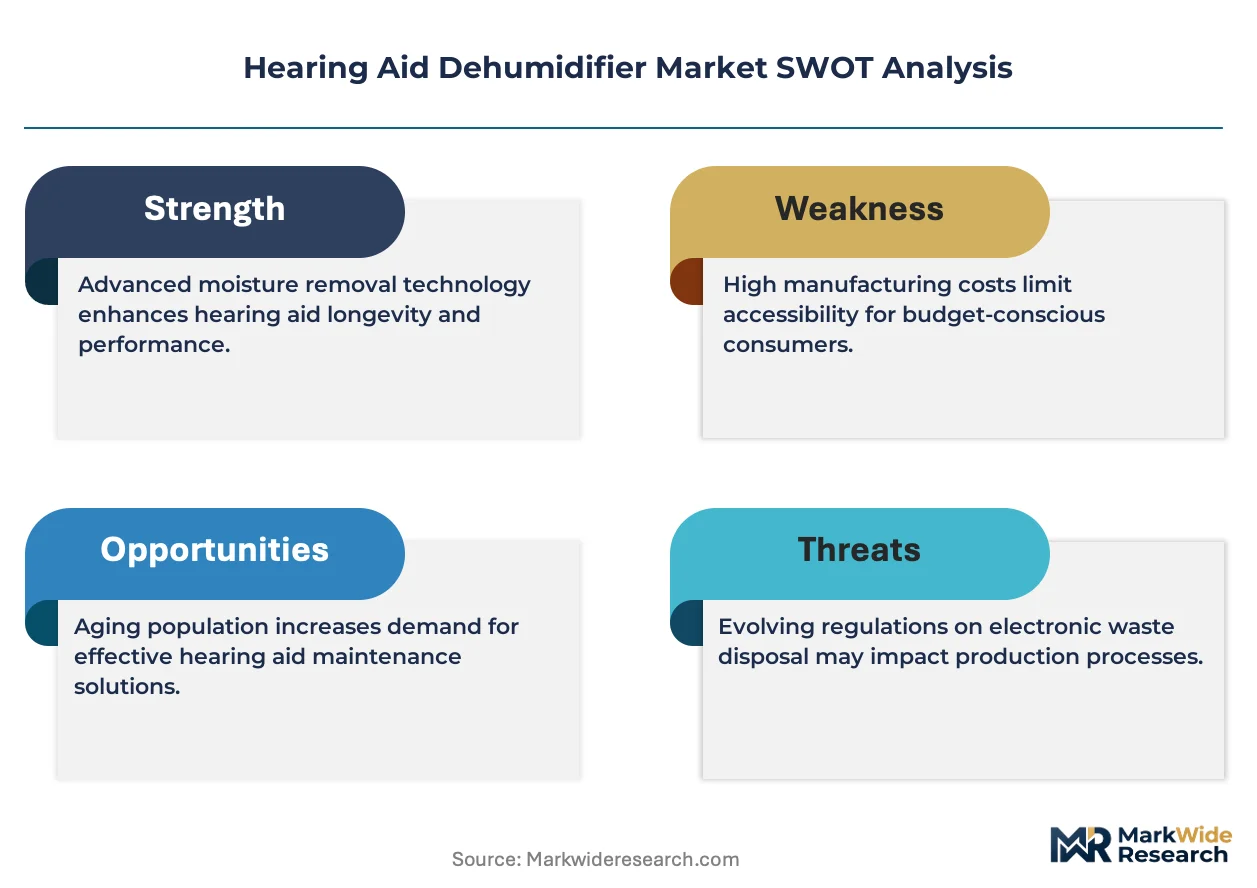
For Market Incumbents: Fortify professional channel lock-in by backward integration into desiccant media production to escape East Asian supply concentration. Deepen ISO 10993 certification portfolios ahead of EU MDR enforcement timelines to preempt competitor hospital access. Channel conflict from unauthorized online marketplace diversion threatens pricing integrity across direct-to-consumer and audiology supply relationships.
For New Entrants and Emerging Players: Subscription replenishment service gaps in the United States multi-site audiology group segment offer white-space entry where incumbents bundle hardware and consumables. Portable UV-C convergence products for traveler segments remain under-penetrated relative to clinical-grade electric units. Pursue direct-to-consumer acquisition through Amazon storefronts with auto-ship desiccant programs to bypass audiology supply chain barriers.
For Investors and Strategic Acquirers: CE marking pre-emption under EU MDR timelines reshapes the acquisition landscape toward notified body-certified manufacturers with hospital channel relationships. Mid-cap specialists with captive desiccant chemistry and thermoelectric assembly capabilities present durable 5-10 year positioning as professional protocols harden performance thresholds. Monitor OTC hearing aid penetration rates as the inflection signal determining consumer versus professional channel investment returns.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR accessory classification demands notified body review ahead of competitor filings. |
| Backward Integration into Desiccant Media | Captive silica gel production escapes East Asian supply concentration and input cost volatility. |
| Subscription Auto-Ship Program Launch | Direct-to-consumer recurring revenue displaces one-time pharmacy transactions in the United States. |
| Hospital System Partnership | Infection control protocols in German audiology departments favor UV-C sterilization convergence products. |
| Software Companion Development | Connected conditioning cycle monitoring addresses Medicare Advantage documentation requirements for patient compliance. |
Research Methodology
A standing panel of audiology practice managers, hospital biomedical engineers, GPO contracts specialists, and hearing instrument OEM procurement leads provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with secondary validation through FDA 510(k) filings, EU MDR notified body registration databases, CMS Medicare Advantage benefit expansion records, and audiology supply chain customs data. Bottom-up unit economics and top-down category spend estimates were triangulated for convergence.
Consistency checks against hospital procurement database benchmarks and audiology practice supply chain surveys validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product architecture (electric/portable/manual/built-in), end-user setting (audiologist/individual/hospital/rehabilitation center), drying mechanism technology, and distribution channel. CAGRs were derived from fitted growth curves incorporating Medicare Advantage hearing benefit expansion trajectories and OTC hearing aid penetration assumptions.
Underlying assumptions cover regulatory timeline adherence, desiccant raw material supply continuity, and audiology practice consolidation patterns, with deviation risk concentrated in EU MDR enforcement pacing and silica gel logistics disruption. Recalibration cycles align with material shifts in FDA OTC framework implementation and notified body certification precedent establishment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Saudi Arabia Respiratory Devices Market
Medical Devices
Global Interventional Neurology Devices Market
Medical Devices
Global Venous Blood Collection Devices Market
Medical Devices
Global Transcatheter Embolization and Occlusion Devices Market
Medical Devices
North America Wearable Medical Devices Market
Medical Devices
Global Automated Dispensing Machines Market
Medical Devices
France Respiratory Devices Market
Medical Devices
Anti-Snore Device Market
Medical Devices
US Clear Aligners Market
Medical Devices
Heat Therapy Units Market
Medical Devices
Mexico Respiratory Devices Market
Medical Devices
Baby Warmer Devices Market
Medical Devices
Global Canes and Crutches Market
Medical Devices
Smart Lenses Market
Medical Devices
MRI-Guided Radiation Therapy Systems Market
Medical Devices
North America Wheelchair Market