
 Corneal Cross Linking Devices Market | 2026-2036
Corneal Cross Linking Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Corneal Cross Linking Devices Market Analysis
Germany is reshaping European supply dynamics through concentrated manufacturing of precision UV-A delivery systems. Avedro, Inc leverages proprietary epithelium-off platform technology to sustain leadership in North American hospital installations. Peschke GmbH anchors its competitive position through specialized riboflavin formulation chemistry optimized for German clinical standards. Glaukos Corporation differentiates via integrated pipeline strategies spanning corneal disease management beyond standalone cross-linking.
Corneal cross linking devices employ controlled ultraviolet-A irradiation at precisely calibrated wavelengths to photochemically reinforce stromal collagen fibrils using riboflavin as a photosensitizer, primarily halting ectatic disease progression and preserving visual acuity. UV devices command the dominant installed base due to capital intensity and regulatory certification barriers, while riboflavin solutions capture recurring revenue streams tied to procedure volume. Hospitals represent the most concentrated end-user segment, though ophthalmology centers are gaining share through ambulatory surgery center expansion and same-day discharge protocols.
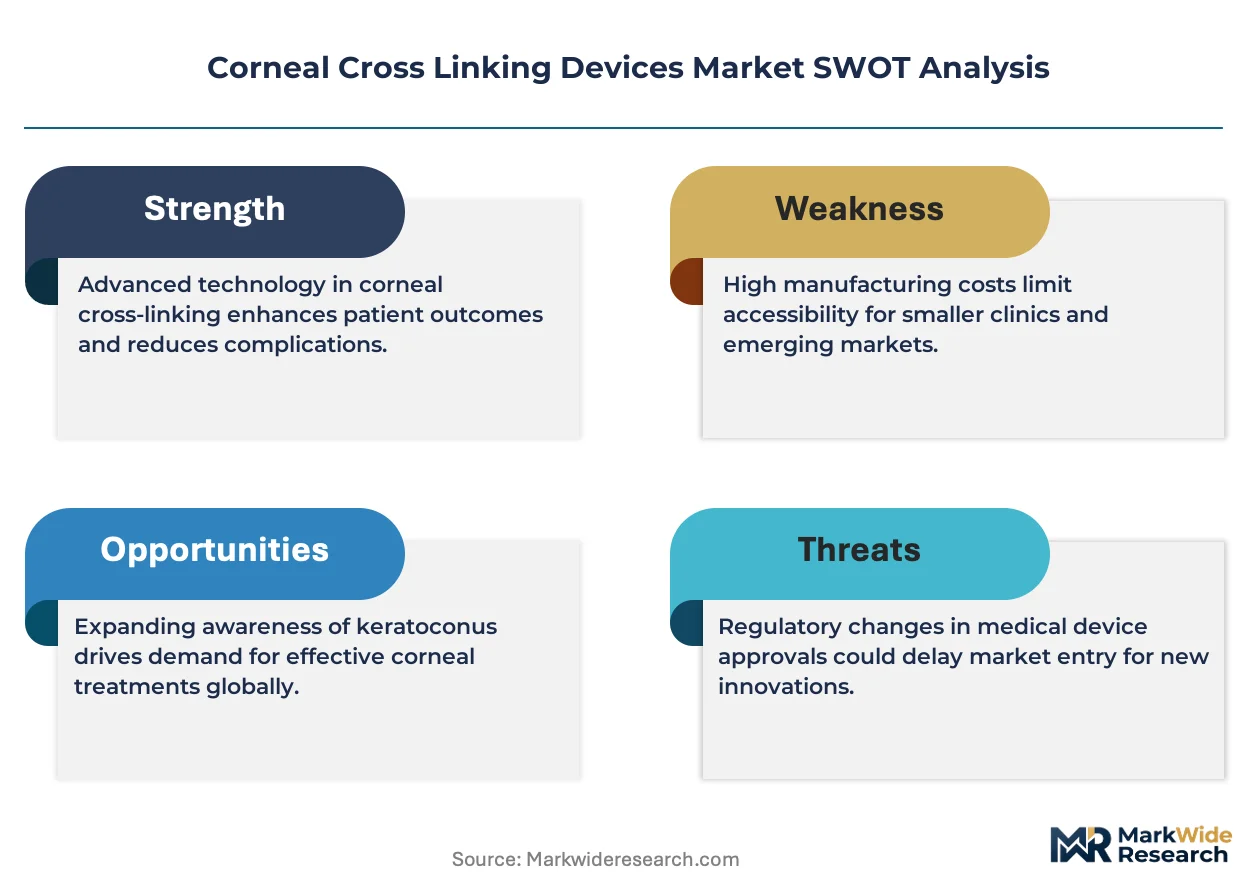
FDA 510(k) clearances and EMA Medical Device Regulation conformity assessments govern market entry, with ISO 13485 quality management certification serving as a baseline procurement filter across OECD healthcare systems. The EU AI Act introduces emerging compliance obligations for algorithmic treatment planning modules integrated into next-generation devices. Stakeholders must monitor reimbursement code stabilization in Medicare and parallel national health insurance frameworks, as payment parity with penetrating keratoplasty remains the decisive adoption inflection point.
Market Dynamics
Accelerated cross-linking protocols are compressing treatment timelines from hours to minutes, forcing capital equipment refresh cycles and reshaping clinic throughput economics across ophthalmology networks.
Growth Catalysts
- EMA Medical Device Regulation:Streamlined conformity assessment pathways for UV-A delivery systems are reducing time-to-market for German manufacturers, expanding installed base across EU member states.
- Keratoconus screening protocols:Topography-based detection programs in US academic medical centers are expanding addressable patient pools and normalizing elective cross-linking as first-line ectasia management.
- Riboflavin formulation advances:Transepithelial delivery chemistry is eliminating mechanical debridement steps, broadening candidate eligibility to thin-cornea patients previously excluded from treatment.
Market Restraints
- UV-A emitter supply concentration:Precision diode manufacturing clusters in Bavaria and Baden-Württemberg create single-source vulnerability for device OEMs outside German supply chains.
- FDA 510(k) predicate device requirements:Substantial equivalence pathways for next-generation irradiation systems impose documentation burdens that extend regulatory timelines for novel wavelength configurations.
- Penetrating keratoplasty substitution:Mature corneal transplant infrastructure in Medicare-reimbursed settings retains preference among surgeons trained in graft-based intervention models.
Strategic Opportunities
- ASC channel expansion:Ambulatory surgery centers in Florida and Texas are securing same-day discharge certifications, capturing volume migrating from hospital outpatient departments.
- EU AI Act algorithmic modules:Treatment planning software with machine learning-based fluence optimization represents a new revenue layer attachable to hardware platforms.
- Pediatric keratoconus protocols:Progressive disease interception in adolescent populations remains clinically underserved, with no approved pharmacological alternatives to mechanical stabilization.
Industry Challenges
- ISO 13485 audit capacity:Notified body backlogs for quality management recertification are delaying product line extensions for mid-tier manufacturers.
- Corneal pachymetry integration:Real-time thickness monitoring during irradiation requires hardware-software synchronization that fragments across incompatible EMR systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corneal Cross Linking Devices Market |
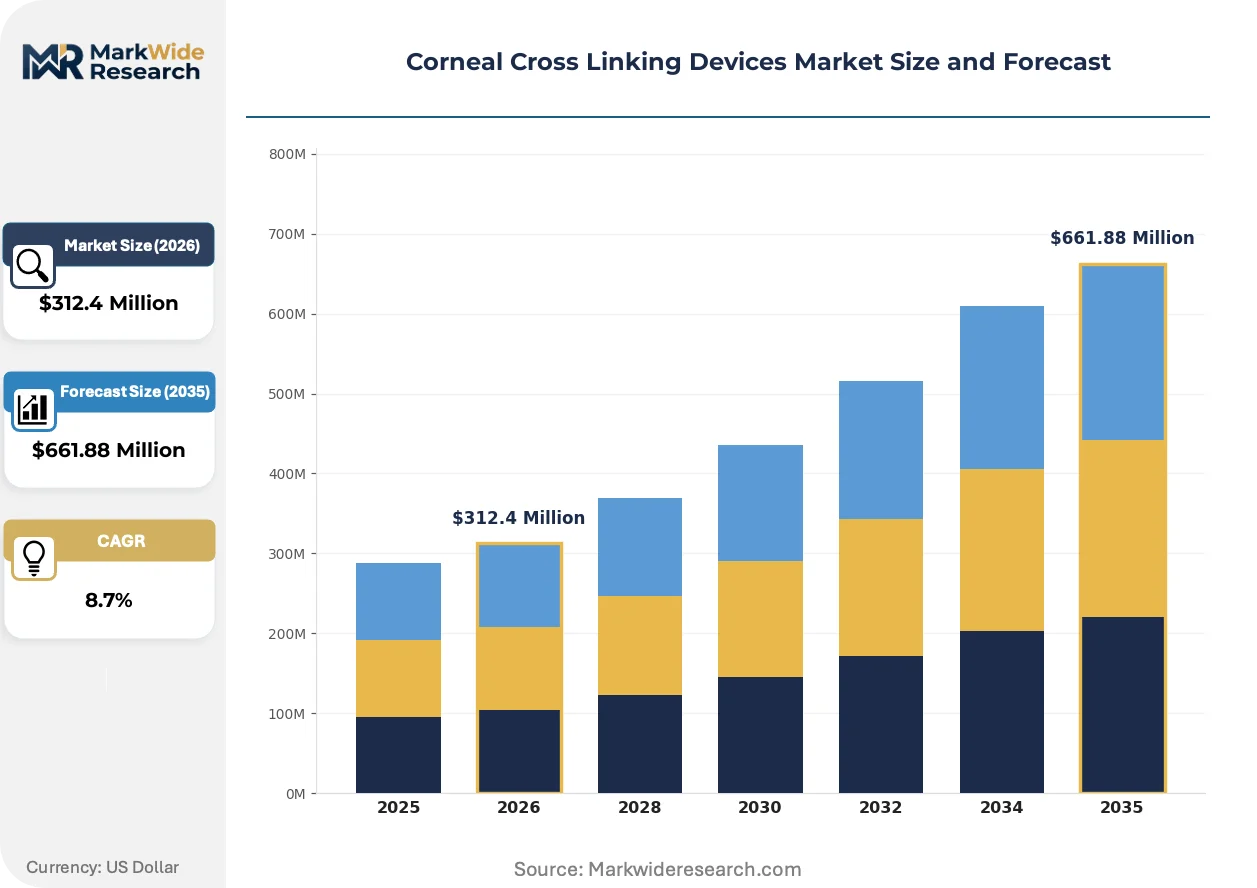
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: UV Devices, Riboflavin Solutions, Confocal Microscopes, Other Devices End User: Hospitals, Clinics, Ophthalmology Centers, Research Institutions Delivery Mode: Topical, Intracameral, Subconjunctival, Others Application: Keratoconus, Ectasia, Corneal Degeneration, Other Indications |
| Companies Covered | Avedro, Inc, Peschke GmbH, Glaukos Corporation, iVis Technologies, IROMED GROUP Srl, Bausch Health, EMAGine AG, Ziemer Ophthalmic Systems, Essilor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corneal Cross Linking Devices Market Emerging Trajectories
Digital treatment planning is virtualizing the traditional surgeon-driven protocol selection process, compressing variability and enabling outcomes-based contracting with payers.
Pulsed UV-A delivery systems with oxygen-replenishment intervals are virtualizing the continuous-irradiation paradigm established in Dresden protocol guidelines. Academic ophthalmology departments in Massachusetts and California are piloting these platforms for ultra-thin cornea cases. The technology is virtualizing reimbursement structures by enabling procedure completion in ambulatory settings previously restricted to hospital-based suites.
The EU AI Act's risk classification framework for software-as-medical-device is mandating conformity assessment upgrades for algorithmic fluence calculators integrated into next-generation systems. German notified bodies are developing specialized audit protocols for machine learning modules in ophthalmic devices. UV device manufacturers with German manufacturing footprints are prioritizing MDR technical documentation for AI-enabled product lines ahead of 2025 enforcement deadlines.
Surgeon training certification is consolidating toward manufacturer-captive education programs rather than society-accredited continuing medical education. Hospital purchasing committees are requiring procedural volume commitments tied to capital equipment leases. This concentration is most pronounced in US integrated delivery networks where standardization across affiliated clinics overrides individual surgeon preference.
Corneal Cross Linking Devices Market Segmentation
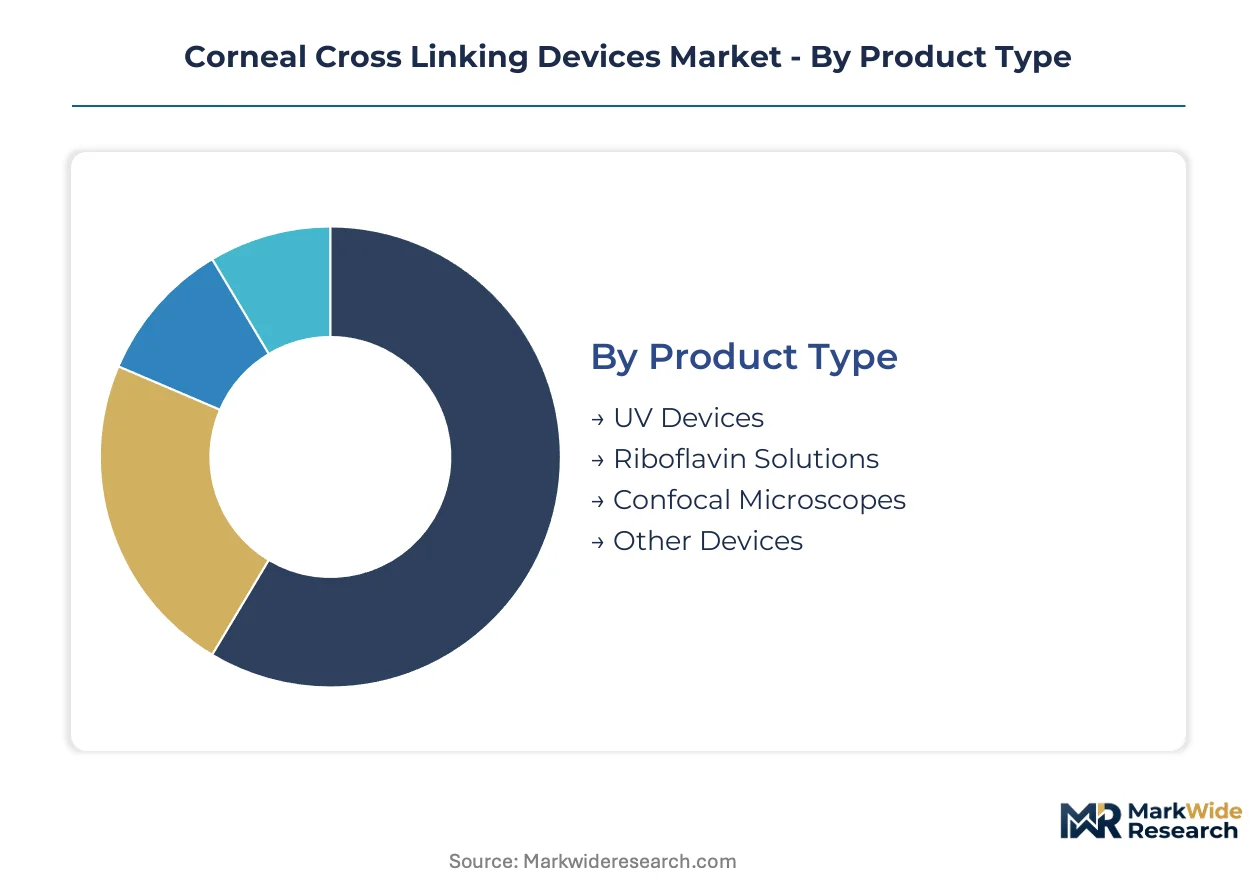
Segmentation in corneal cross linking devices reveals distinct capital cycles and recurring revenue streams. UV platforms demand decade-long replacement timelines while riboflavin solutions generate procedure-tied replenishment. Understanding these rhythms shapes procurement strategy and manufacturer positioning across ophthalmology networks.
Product Type:
UV devices lock capital budgets for seven-to-ten year cycles while riboflavin solutions turn inventory monthly, creating divergent cash flow profiles for suppliers and purchasers alike.
- UV Devices:Precision ultraviolet-A delivery systems incorporating calibrated diode arrays and real-time dosimetry controls. Demand clusters in German university hospitals and US academic medical centers where FDA 510(k) clearance anchors purchasing decisions. Capital intensity and regulatory certification barriers protect incumbent positions.
- Riboflavin Solutions:Photosensitizer formulations enabling photochemical collagen cross-linking when activated by UV-A irradiation. Ophthalmology centers in Bavaria and Texas drive volume through accelerated protocol adoption, with transepithelial formulations expanding candidate eligibility.
- Confocal Microscopes:High-resolution imaging systems for stromal morphological assessment pre- and post-procedure.
- Other Devices:Ancillary equipment including pachymetry systems and specular microscopes supporting treatment workflow.
UV devices dominate installed base. Riboflavin solutions are where expansion concentrates.
End User:
Procurement authority fragments across capital committees, individual surgeons, and centralized supply chains depending on facility scale and ownership structure.
- Hospitals:Integrated delivery networks with captive ambulatory surgery centers command largest procedure volumes. Medicare reimbursement codes and Joint Commission accreditation requirements filter vendor selection, with purchasing committees demanding procedural volume commitments tied to equipment leases.
- Ophthalmology Centers:Specialized facilities in Florida and Texas are securing same-day discharge certifications, capturing volume migrating from hospital outpatient departments through accelerated cross-linking protocols.
- Clinics:Private practice settings with lower capital absorption capacity.
- Research Institutions:Academic ophthalmology departments piloting pulsed UV-A delivery and algorithmic fluence optimization.
Hospitals anchor revenue concentration. Ophthalmology centers are climbing the fastest.
Delivery Mode:
Route selection determines corneal penetration depth, epithelial integrity, and patient eligibility thresholds.
- Topical:Standard drop-based riboflavin application requiring epithelial debridement or specialized transepithelial chemistry. US and German clinical workflows favor this route for established protocol familiarity and reimbursement clarity.
- Intracameral:Direct anterior chamber injection for advanced ectasia cases with compromised epithelial barriers.
- Subconjunctival:Perilimbal depot delivery for sustained photosensitizer release.
- Others:Investigational iontophoretic and microneedle-assisted delivery mechanisms.
Topical delivery commands procedural volume. Intracameral approaches are gaining share fastest.
Application:
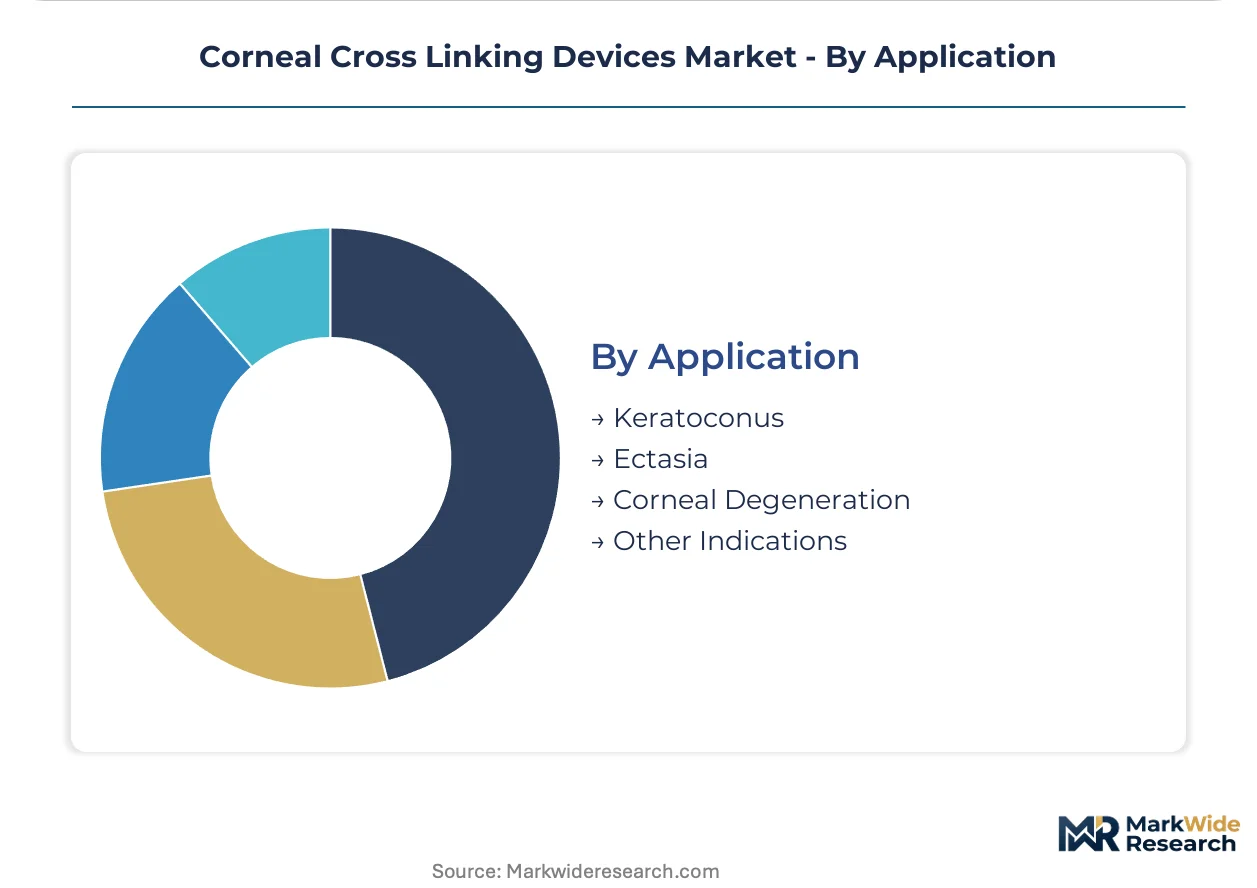
Disease severity and progression risk stratify addressable populations across pediatric, adult, and post-surgical cohorts.
- Keratoconus:Progressive ectatic disorder characterized by corneal thinning and cone-shaped protrusion. Topography-based screening programs in Massachusetts and California academic centers are expanding addressable pools and normalizing elective cross-linking as first-line management.
- Ectasia:Iatrogenic corneal instability following refractive surgery. Post-LASIK surveillance protocols in US integrated delivery networks drive detection and intervention timing.
- Corneal Degeneration:Age-related and dystrophic conditions with stromal compromise.
- Other Indications:Infectious keratitis and bullous keratopathy under investigation.
Keratoconus anchors commercial focus. Ectasia applications show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Frankfurt-Rhine-Main logistics corridor underwrites German distribution dominance for precision UV-A emitter components serving ophthalmology networks across the continent.
United States
Academic medical centers in Massachusetts and California pilot pulsed irradiation protocols for thin-cornea cases. FDA 510(k) clearance pathways anchor purchasing decisions at integrated delivery networks. The Greater Boston cluster concentrates device validation studies and surgeon training certification programs.
Germany
Bavarian precision diode manufacturers supply UV-A emitter arrays to device OEMs worldwide. EMA Medical Device Regulation conformity assessments streamline market entry for domestic producers. The Munich-Stuttgart corridor hosts specialized riboflavin formulation chemistry operations optimized for clinical standards.
Japan
Academic ophthalmology departments in Tokyo and Osaka evaluate transepithelial delivery protocols for progressive keratoconus interception. PMDA consultation procedures shape product registration timelines for imported platforms. The Kanto region concentrates regulatory strategy functions for Asia-Pacific market expansion.
United Kingdom
NHS specialized commissioning frameworks filter adoption of accelerated cross-linking within hospital eye services. MHRA post-market surveillance requirements influence device selection at teaching hospitals. The London-Oxford corridor anchors clinical trials infrastructure for next-generation irradiation systems.
Australia
TGA inclusion in the Australian Register of Therapeutic Goods determines reimbursement eligibility for UV delivery platforms. Topography-based screening programs in New South Wales and Victoria expand addressable patient pools for elective stabilization procedures. The Sydney-Melbourne axis concentrates private ophthalmology center investment in same-day discharge capabilities.
Corneal Cross Linking Devices Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in emitter and photosensitizer supply. The vendor base stratifies across three tiers: multinational ophthalmic conglomerates with cross-linking as one vertical within corneal disease portfolios; mid-cap device manufacturers with concentrated UV-A platform specialization; and regional riboflavin formulators serving localized clinical preferences. Dominant competitive moves include strategic partnerships between emitter suppliers and device OEMs, plus portfolio diversification into adjacent corneal diagnostic modalities.
Within the platform specialization tier, Avedro, Inc and Peschke GmbH exemplify divergent geographic anchoring strategies for regulatory-cleared market presence. Glaukos Corporation occupies a position spanning device and pharmaceutical integration within corneal disease management. These three entities represent distinct archetypes: the US-based FDA-first platform developer, the German EMA-anchored component specialist, and the diversified ophthalmic conglomerate building cross-category clinical workflows.
| Leading Market Players |
|---|
| Avedro, Inc |
| Peschke GmbH |
| Glaukos Corporation |
| iVis Technologies |
| IROMED GROUP Srl |
| Bausch Health |
| EMAGine AG |
| Ziemer Ophthalmic Systems |
| Essilor |
| Others |
Supply Flow & Price Mechanics
Bavarian precision diode manufacturers command upstream margin capture through specialized UV-A emitter arrays, concentrating pricing power downstream at device OEMs dependent on German-sourced optical components for FDA and EMA certification pathways.
Pricing Analysis
FDA 510(k) clearance tiers dictate the pricing structure across UV delivery platforms, with predicate-device equivalence creating three-tier pricing stratification across premium, standard, and economy certification levels. Price differentiation hinges on ISO 13485 quality tier and procedural volume commitments tied to hospital purchasing committee mandates. Cost compression in mid-tier device segments is intensifying because EMA MDR technical documentation burdens extend regulatory timelines for novel wavelength configurations. Academic medical centers demonstrate lowest price sensitivity due to research funding insulation, while ambulatory surgery centers in Florida and Texas exhibit highest sensitivity to capital equipment lease structures.
Supply Chain Analysis
Tariff exposure between Germany and US device OEMs dominates supply chain risk assessment for precision UV-A emitter arrays. Manufacturing concentration rests on Bavarian diode foundries, Baden-Württemberg optical component suppliers, and Massachusetts-based device integrators. Raw material dependencies include gallium nitride substrates, riboflavin precursor chemicals, and medical-grade sapphire windows. Single-source vulnerability in epitaxial wafer supply creates procurement fragility for non-German device manufacturers. Distribution runs through Frankfurt-Rhine-Main logistics corridors serving EU ophthalmology networks, with direct OEM-to-hospital contracting prevalent in US integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Corneal cross-linking platforms are approaching an ecosystem inflection where algorithmic fluence optimization modules interoperate with hospital EMR systems, creating winner-take-most dynamics for vendors with certified AI-enabled workflows.
For Market Incumbents: Pre-empt transepithelial formulation displacement by securing exclusive riboflavin chemistry partnerships with Bavarian suppliers before patent cliffs accelerate. Defend hospital installed base through captive surgeon training certification programs that lock procedural volume commitments. Vertical integration into pulsed UV-A emitter manufacturing mitigates Bavarian supply concentration risk. For New Entrants and Emerging Players: Pediatric keratoconus protocols in US academic medical centers represent the most penetrable entry point given absence of approved pharmacological alternatives and surgeon willingness to pilot novel stabilization approaches. Transepithelial delivery chemistry for thin-cornea patients offers differentiated positioning against established epithelium-off platforms. Go-to-market execution should prioritize GPO contracting relationships with integrated delivery networks over individual surgeon direct sales. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed German device OEMs possessing EMA MDR technical documentation packages nearing renewal deadlines. Five-to-ten year viability hinges on AI Act compliance positioning for algorithmic treatment planning modules. The signal to watch is Medicare reimbursement code stabilization for accelerated cross-linking protocols relative to penetrating keratoplasty parity.| Strategic Initiative | Industry Significance |
|---|---|
| EMA MDR Technical Documentation Upgrade | EMA notified body audit protocols for AI-enabled fluence calculators secure EU market access ahead of enforcement deadlines. |
| Algorithmic Treatment Planning Module Development | Machine learning-based oxygen-replenishment interval optimization differentiates pulsed UV-A platforms in thin-cornea segments. |
| ASC Same-Day Discharge Certification | Florida and Texas ambulatory surgery center partnerships capture volume migrating from hospital outpatient departments. |
| Transepithelial Riboflavin Formulation Partnership | Specialized chemistry licensing eliminates mechanical debridement steps and expands candidate eligibility pools. |
| Surgeon Training Certification Captivity | Manufacturer-captive education programs override society-accredited CME and standardize procurement across affiliated clinics. |
Methodological Framework
A standing panel of corneal surgeons, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA 510(k) filings, EMA MDR submission databases, CMS Medicare reimbursement code trackers, and hospital procurement system records. Bottom-up procedure volume estimates triangulated against top-down capital equipment shipment data from German and US manufacturing clusters.
Scenario-bracketing framed analytical development across the projection horizon, with segmentation modeling spanning UV device versus riboflavin solution revenue streams, hospital versus ophthalmology center end-use channels, and topical versus intracameral delivery modes. CAGRs derived from installed base refresh cycles and procedure volume elasticity to reimbursement parity assumptions. Forecast inputs incorporated EMA AI Act risk classification timelines and Medicare coverage determination trajectories for accelerated protocols.
Practitioners should monitor FDA predicate device clearance backlogs and EMA notified body audit capacity constraints for early signals of regulatory timeline compression. Forecasts reflect assumptions around reimbursement code stabilization and AI Act enforcement sequencing. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Pulse Lavage Market
Medical Devices
MRI Guided Drug Delivery Market
Medical Devices
Assisted Walking Devices Market
Medical Devices
Global Intraoral Cameras Market
Medical Devices
Ultrasound Stimulator Market
Medical Devices
Airway Management Market
Medical Devices
Alexandrite Gemstone Lasers Market
Medical Devices
Implantable Port Market
Medical Devices
Asia-Pacific Vaginal Slings Market
Medical Devices
Portable Ultrasonic Skin Scrubber Market
Medical Devices
Medical Coatings Market
Medical Devices
Global Cardiopulmonary Bypass Accessory Equipment Market
Medical Devices
Urinary Incontinence Devices Market
Medical Devices
North America Wearable Medical Devices Market
Medical Devices
Global Metal Implants and Medical Alloys Market
Medical Devices
APAC AMH Market