
 Ventilation Devices Market | 2026-2036
Ventilation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Ventilation Devices Market Outlook
The split between premium and commodity tiers is hardening in the Ventilation Devices Market. Honeywell leverages its building automation integration to command premium positioning in demand-controlled systems. Carrier Global anchors its position through captive distribution and service networks across North American commercial infrastructure. Daikin Industries differentiates through heat recovery specialization and inverter-driven efficiency gains in European and Asian markets.
Ventilation devices are electromechanical systems engineered to exchange, filter, or condition indoor air through forced or natural airflow, typically rated by air changes per hour and static pressure performance. Their primary commercial purpose centers on maintaining occupant health, controlling moisture loads, and meeting thermal load requirements in enclosed structures. Heat recovery ventilators are capturing margin pools as energy codes tighten, while demand-controlled ventilation is displacing constant-volume systems in commercial retrofits. Mechanical ventilation dominates new construction, though hybrid configurations are gaining traction in temperate climate zones where natural ventilation reduces fan energy penalties.
The U.S. Department of Energy and EPA shape product efficiency thresholds and indoor air quality benchmarks, directly influencing minimum viable specifications and market access. Europe's Ecodesign Directive and F-Gas Regulation are accelerating refrigerant transitions and fan motor efficiency upgrades across imported and domestic equipment. Stakeholders must monitor how tightening carbon performance standards in construction codes will reshape equipment specification criteria and supplier qualification requirements.
Market Dynamics
The U.S. Department of Energy's tightening efficiency mandates are compressing product lifecycles and forcing rapid equipment replacement across commercial building stock, while Germany's building retrofit programs accelerate demand-controlled ventilation adoption in residential and institutional segments.
Growth Catalysts
- Heat Recovery Ventilation Mandates:The Ecodesign Directive and F-Gas Regulation in Europe are compelling building owners to upgrade to energy-recovery systems, particularly in Nordic and German commercial retrofits where thermal efficiency thresholds now exclude constant-volume equipment.
- Hospital Infrastructure Modernization:Healthcare facilities across the United States, Germany, and Japan are replacing aging air handling units with demand-controlled systems capable of isolation room pressurization and HEPA filtration integration.
- Indoor Air Quality Codes:Stringent particulate and CO2 concentration limits in German DIN standards and California Title 24 are triggering replacement cycles in schools, driving specification of DCV systems with real-time sensor feedback.
Market Restraints
- Copper and Rare Earth Input Volatility:Permanent magnet motors and heat exchanger coils depend on concentrated supply chains, with neodymium processing concentrated in China creating price instability for high-efficiency fan assemblies.
- Technical Limitation in Cold Climates:Frost formation on energy-recovery cores below -15°C requires pre-heating or bypass configurations, adding complexity and energy penalty in Scandinavian and Canadian installations.
- Regulatory Fragmentation:Divergent testing protocols between ASHRAE standards in North America and EN standards in Europe force manufacturers to maintain dual certification inventories, inflating compliance overhead.
Strategic Opportunities
- Smart Building Integration:Convergence of ventilation controls with IoT sensor networks and building management systems creates white space for predictive maintenance and automated commissioning in U.S. and German commercial real estate.
- Residential Retrofit Penetration:Underpenetrated single-family housing stock in France and Italy presents expansion opportunity as national renovation subsidies and indoor air quality awareness campaigns accelerate homeowner upgrades.
- Data Center Cooling Hybridization:Liquid cooling and free-air economization are converging with mechanical ventilation in hyperscale facilities, opening specification pathways for heat recovery ventilators in thermal load management.
Industry Challenges
- Commissioning and Controls Integration:Facility engineering teams lack proficiency in BACnet and Modbus protocol configuration, causing performance gaps between specified and actual energy recovery effectiveness in complex building automation environments.
- Certification Timeline Compression:EPA and DOE rulemaking cycles are outpacing ASHRAE and AHRI test procedure updates, forcing manufacturers to certify against draft standards that may shift before final publication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ventilation Devices Market |
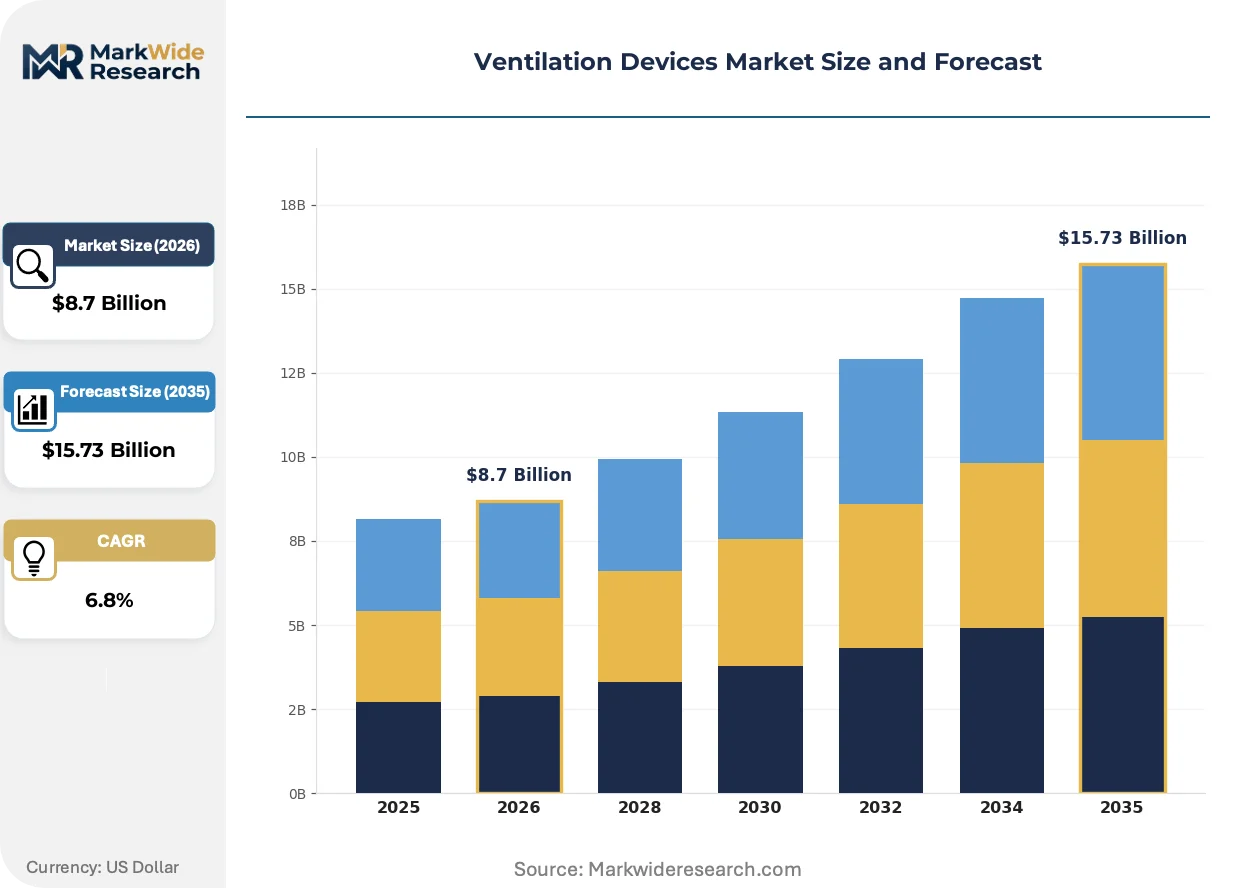
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Exhaust Fans, Air Purifiers, Heat Recovery Ventilators, Ductless Fans Technology: Mechanical Ventilation, Natural Ventilation, Hybrid Ventilation, Demand-Controlled Ventilation Application: Residential, Commercial, Industrial, Healthcare End User: Homeowners, Facility Managers, Contractors, Building Owners |
| Companies Covered | Honeywell, Johnson Controls, Daikin Industries, Trane Technologies, Mitsubishi Electric, LG Electronics, Carrier Global, Vent-Axia, Fantech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ventilation Devices Market Strategic Shifts
Digitalization of airflow management and sensor-driven control architectures are compressing the gap between specified and realized energy performance, while regulatory pressure on embodied carbon forces material and manufacturing process reinvention.
Demand-controlled ventilation with CO2 and occupancy sensing is decentralizing airflow management in commercial buildings. Property managers in U.S. office and German educational facilities are retrofitting constant-volume systems at accelerated pace. This technology is decentralizing commissioning authority from central plant operators to zone-level automation, compressing service contract structures and fragmenting supplier relationships.
The EU F-Gas Regulation and its staged refrigerant phase-down are accelerating transitions to low-global-warming-potential heat pump integration in ventilation products. Equipment manufacturers serving the German and French markets are requalifying heat recovery cores and compressors for R-32 and R-290 compatibility. Residential and light commercial segments in Northern Europe are responding fastest, with product portfolios shifting toward propane-ready architectures ahead of 2027 quota reductions.
Buying committees in institutional and healthcare verticals are unbundling equipment procurement from long-term service agreements. General contractors and facilities directors in U.S. hospital systems and German municipal buildings are separating initial capital purchase from multi-year maintenance contracts, forcing OEMs to compete on upfront price while third-party service providers capture recurring revenue. This pattern is most visible in North American healthcare infrastructure where GPOs and IDNs are standardizing equipment specifications while diversifying service vendor pools.
Ventilation Devices Market Segmentation
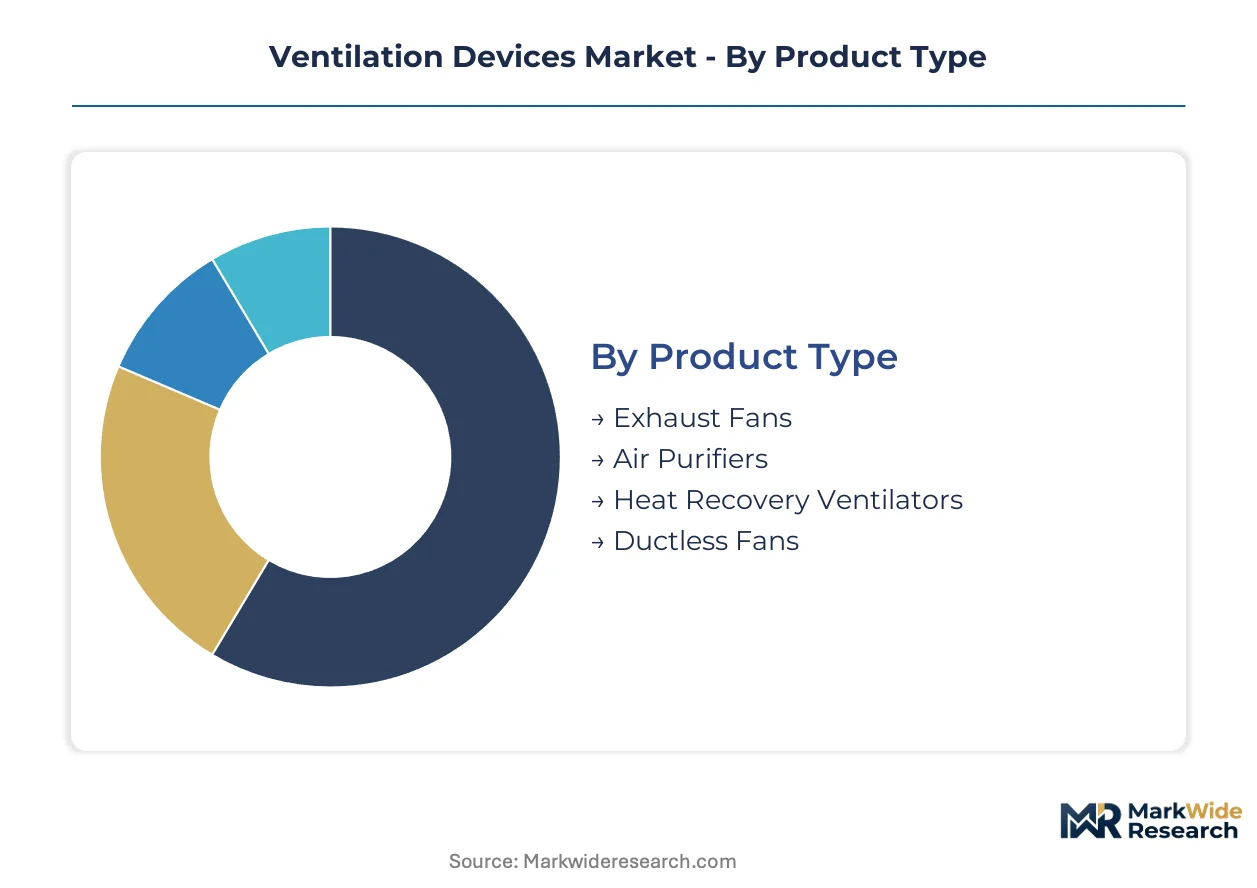
Segmentation in ventilation devices reveals how procurement patterns diverge across building typologies and regulatory environments. Product specifications vary sharply between retrofit compatibility and new construction integration, while technology choices reflect climate zone constraints and energy code stringency.
Product Type:
Customization spans from standardized residential exhaust units to engineered heat recovery systems with site-specific core configurations.
- Heat Recovery Ventilators:Counter-flow or rotary heat exchangers recover thermal energy from exhaust air streams, achieving efficiency ratings that satisfy Ecodesign Directive thresholds in German and Nordic commercial retrofits. German building retrofit programs and DIN indoor air quality codes are accelerating replacement of constant-volume equipment with these systems in schools and municipal buildings.
- Air Purifiers:Standalone filtration units with HEPA or activated carbon stages address particulate and VOC loads without ductwork modification. Demand concentrates in U.S. healthcare isolation rooms and Japanese commercial offices where supplementary air cleaning augments central mechanical systems.
- Exhaust Fans:Axial or centrifugal configurations for moisture and pollutant removal in kitchens, baths, and light commercial spaces.
- Ductless Fans:Through-wall or window-mounted units for localized ventilation without distribution infrastructure.
Leading the category by volume: Exhaust Fans. Growing fastest: Heat Recovery Ventilators.
Technology:
Cost tier separation distinguishes capital-intensive mechanical systems from low-first-cost natural ventilation architectures.
- Demand-Controlled Ventilation:Sensor networks modulate airflow based on CO2 concentration or occupancy detection, reducing fan energy penalties during unoccupied periods. U.S. office buildings and German educational facilities are retrofitting constant-volume systems at accelerated pace as California Title 24 and DIN standards mandate real-time air quality feedback.
- Mechanical Ventilation:Fan-driven supply and exhaust systems with fixed or variable air volume control dominate new construction in climates where natural ventilation cannot meet thermal load requirements.
- Hybrid Ventilation:Combined natural and mechanical modes switch based on outdoor temperature and enthalpy conditions in temperate climate zones.
- Natural Ventilation:Buoyancy and wind-driven airflow through operable openings or stack configurations in mild climates with low cooling loads.
Mechanical Ventilation retains the largest installed base. Demand-Controlled Ventilation is expanding most quickly.
Application:
Application segmentation tracks how ventilation intensity requirements scale from residential moisture control to healthcare-critical pressurization.
- Healthcare:Isolation room pressurization, operating suite laminar flow, and protective environment controls demand HEPA filtration integration and redundant air handling capacity. U.S. hospital infrastructure modernization and Japanese healthcare facility upgrades are replacing aging air handling units with demand-controlled systems capable of precise pressure differentials.
- Commercial:Office, retail, and hospitality spaces require ventilation rates tied to occupancy density and indoor air quality standards.
- Residential:Single-family and multifamily ventilation addresses moisture control, combustion safety, and basic pollutant dilution.
- Industrial:Process ventilation manages heat loads, fume capture, and contaminant control in manufacturing environments.
Commercial applications dominate current procurement volume. Healthcare shows the steepest expansion trajectory.
End User:
Customer type determines whether purchases prioritize first cost or lifecycle performance, fragmenting supplier engagement models.
- Facility Managers:Building operations teams specify equipment with integrated controls and predictive maintenance compatibility to reduce service contract overhead. U.S. and German commercial real estate operators are unbundling equipment procurement from long-term service agreements, forcing OEMs to compete on upfront price.
- Building Owners:Institutional and corporate asset holders focus on regulatory compliance and energy cost reduction across portfolio-wide retrofits.
- Contractors:Installation firms select products based on availability, ease of commissioning, and compatibility with existing ductwork.
- Homeowners:Residential purchasers respond to indoor air quality awareness campaigns and national renovation subsidies in underpenetrated single-family markets.
Facility Managers drive the largest contract value. Building Owners are gaining share fastest as portfolio decarbonization mandates expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ruhr industrial corridor concentrates German ventilation manufacturing and retrofit activity, with Dortmund and Essen hosting engineering centers serving building automation integration across Central Europe.
United States
Hospital infrastructure modernization in Texas and California drives demand-controlled ventilation procurement for isolation room pressurization. The Department of Energy's efficiency mandates compress product lifecycles in commercial building stock. Chicago and New York Metro building operators unbundle equipment procurement from service agreements, fragmenting supplier relationships.
Germany
Building retrofit programs in North Rhine-Westphalia and Bavaria accelerate heat recovery ventilator replacement in schools and municipal facilities. The Ecodesign Directive and DIN indoor air quality codes exclude constant-volume equipment from new specifications. Stuttgart engineering clusters specialize in heat recovery core manufacturing for Nordic export markets.
Japan
Healthcare facility upgrades in Tokyo and Osaka replace aging air handling units with demand-controlled systems integrating HEPA filtration. METI efficiency benchmarks tighten fan motor performance requirements. Nagoya industrial districts manufacture compact heat exchangers for residential and light commercial segments.
China
Data center construction in the Yangtze River Delta and Pearl River Delta creates specification pathways for heat recovery ventilators in thermal load management. GB standards and dual carbon goals accelerate refrigerant transitions in imported equipment. Shenzhen technology corridors develop IoT sensor networks for building automation integration.
United Kingdom
Commercial real estate decarbonization in London and the Southeast drives retrofit demand for demand-controlled ventilation with real-time CO2 feedback. Building Regulations Part F tightens ventilation rate requirements for new construction. Manchester engineering services clusters specialize in commissioning and controls integration for complex building automation environments.
Ventilation Devices Market Competitive Environment
Premium-margin players sit above commodity-margin players across building automation integration capability and heat recovery specialization. The vendor base organizes into three tiers: diversified industrial conglomerates with captive distribution, specialized climate equipment manufacturers with regional density, and component suppliers serving private-label assemblers. Consolidation pressure concentrates among mid-scale fabricators lacking controls integration expertise. Dominant competitive moves include strategic partnerships for IoT platform access and backward integration into heat exchanger core manufacturing.
Within the diversified conglomerate tier, Honeywell and Carrier Global exemplify positioning through building automation integration and captive service networks respectively. Daikin Industries occupies a specialist position in heat recovery and inverter-driven efficiency architectures. These three anchors represent distinct competitive vectors: controls-led premium positioning, distribution-captured commercial infrastructure, and climate-technology specialization across European and Asian markets.
| Leading Market Players |
|---|
| Honeywell |
| Johnson Controls |
| Daikin Industries |
| Trane Technologies |
| Mitsubishi Electric |
| LG Electronics |
| Carrier Global |
| Vent-Axia |
| Fantech |
| Others |
Value Chain & Pricing Dynamics
Copper and neodymium price indices cascade through ventilation equipment manufacturing, compressing margins on high-efficiency fan assemblies while concentrating pricing power among heat exchanger core specialists with captive magnet processing capabilities in China and Japan.
Pricing Analysis
Energy-recovery effectiveness ratings anchor value-based pricing for heat recovery ventilators serving German and Nordic commercial retrofits. Three-tier pricing structure across premium, standard, and economy levels separates certified Ecodesign-compliant systems from uncertified commodity exhaust fans. Cost compression in standard-tier mechanical ventilation is intensifying because facility managers unbundle equipment procurement from service contracts. Residential homeowners in France and Italy exhibit highest price sensitivity, while U.S. hospital GPOs prioritize lifecycle performance over first cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale data center demand in China's Yangtze River Delta, while distributor-captive networks serve North American commercial infrastructure. Permanent magnet motors and heat exchanger coils draw from concentrated rare earth processing in China, copper coil manufacturing in Germany, and compact heat exchanger fabrication in Japan. Single-source vulnerability in neodymium supply creates exposure for high-efficiency fan assembly producers. Distribution runs through building automation integrators in U.S. and German commercial real estate, with third-party service providers capturing recurring maintenance revenue.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Ventilation Devices Market functions as a cost-of-compliance story where Europe's Ecodesign Directive and F-Gas Regulation erect regulatory moats that exclude non-certified competitors from specification pathways in German and Nordic building retrofits.
For Market Incumbents: Anchor market position through backward integration into heat exchanger core manufacturing and captive distribution networks serving hospital infrastructure modernization. Consolidation pressure targets mid-scale fabricators lacking BACnet and Modbus controls integration expertise. Capacity addition in Stuttgart engineering clusters reinforces heat recovery specialization for Nordic export markets. For New Entrants and Emerging Players: E-commerce direct channels offer the lowest-friction entry path into underpenetrated French and Italian residential retrofit segments where national renovation subsidies accelerate homeowner upgrades. Target single-family housing stock with propane-ready heat recovery architectures ahead of F-Gas quota reductions. Partner with IoT platform developers for smart building integration in U.S. office retrofits. For Investors and Strategic Acquirers: Distressed-cycle entries favor controls-integrated mid-cap specialists with heat recovery core manufacturing in Germany and Japan. Long-term viability hinges on regulatory compliance certification depth across Ecodesign and ASHRAE testing protocols. Monitor EPA and DOE rulemaking acceleration as inflection signal for certification timeline compression risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat Exchanger Cores | Captive supply of rotary and counter-flow cores secures margin pools in German commercial retrofits. |
| Smart Building Platform Partnership | IoT sensor network integration with BACnet protocols opens predictive maintenance revenue in U.S. real estate. |
| R-290 Propane Refrigerant Transition | Low-global-warming-potential compatibility ahead of F-Gas quotas protects market access in Northern Europe. |
| Healthcare GPO Contract Standardization | Isolation room pressurization specifications with HEPA integration lock in U.S. hospital infrastructure demand. |
| Residential Retrofit Channel Expansion | National renovation subsidy alignment in France and Italy penetrates underdeveloped single-family ventilation stock. |
Study Parameters
Multi-period observation of hospital infrastructure procurement cycles, building retrofit program allocations, and efficiency mandate compliance timelines anchored the trend analysis, supplemented by interviews with facilities directors, HVAC contractors, building automation integrators, and heat exchanger manufacturing engineers. Secondary validation drew from EPA and DOE rulemaking dockets, Ecodesign Directive implementation reports, DIN standard revision notices, and ASHRAE guideline publications. Bottom-up equipment shipment analysis triangulated against top-down construction spending data across the analysis window.
Input-output matrices mapped product type, technology architecture, application intensity, and end-user procurement behavior against regulatory framework clusters and climate zone constraints. Segmentation dimensions modeled include heat recovery efficiency tier, control system sophistication, building typology, and geographic regulatory stringency. CAGRs derived from installed base replacement cycles, new construction permitting data, and retrofit subsidy uptake trajectories. Industry-specific forecast inputs incorporated copper and rare earth price volatility indices alongside hospital capital expenditure surveys.
The model holds under stable regulatory enforcement continuity; deviation in EPA or DOE rulemaking acceleration, F-Gas quota reduction timing, or rare earth supply disruption would shift replacement cycle assumptions. Forecasts reflect documented base-case assumptions regarding Ecodesign Directive compliance thresholds and DIN indoor air quality code adoption. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Non-Invasive Glucose Monitoring Devices Market
Medical Devices
US Digital Pregnancy Test Kits Market
Medical Devices
Global Nasal Spray Market
Medical Devices
Global Stone Retrieval Basket Market
Medical Devices
Middle East and Africa Medical Devices Market
Medical Devices
Global Diagnostic Catheter Market
Medical Devices
Global Artificial Organs and Bionics Market
Medical Devices
Global Brain Monitoring Devices Market
Medical Devices
Global Keratometers Market
Medical Devices
Mobile Operating Rooms Market
Medical Devices
Biological Microscope Market
Medical Devices
Pulse Electromagnetic Field (PEMF) Therapy Devices Market
Medical Devices
Mechanical Thrombectomy Devices Market
Medical Devices
Brazil Drug Delivery Devices Market
Medical Devices
Neurovascular Access Catheters Market
Medical Devices
Therapeutic Contact Lenses Market