
 Epidural Anesthesia Sets Market | 2026-2036
Epidural Anesthesia Sets Market Size, Share, and Industry Trends Forecast 2026-2036
Epidural Anesthesia Sets Market Foresight
Pre-bundled tray configurations is shifting procurement preferences across hospital systems and ambulatory settings. ICU Medical leverages its infusion therapy infrastructure to anchor distribution in North American integrated delivery networks. B. Braun sustains manufacturing scale across European sterile device production, while PAJUNK GmbH specializes in precision needle engineering for neuraxial applications. BD competes through deep channel control in acute care purchasing cooperatives.
Epidural anesthesia sets comprise sterile, single-use assemblies including needles, catheters, filters, syringes, and drapes designed for neuraxial drug delivery into the epidural space, typically manufactured under ISO 13485 quality systems with ethylene oxide or gamma sterilization validation. Their primary purpose is to enable controlled regional anesthesia for surgical, obstetric, and chronic pain interventions while maintaining aseptic technique. Catheter kits command durable margin pools due to extended indwelling requirements in postoperative pain protocols, whereas tray sets are gaining traction as operating room efficiency mandates consolidate vendor relationships. Labor and delivery remains the most mature application segment, with pain clinics representing the fastest-growing end user channel as outpatient epidural steroid injection volumes rise.
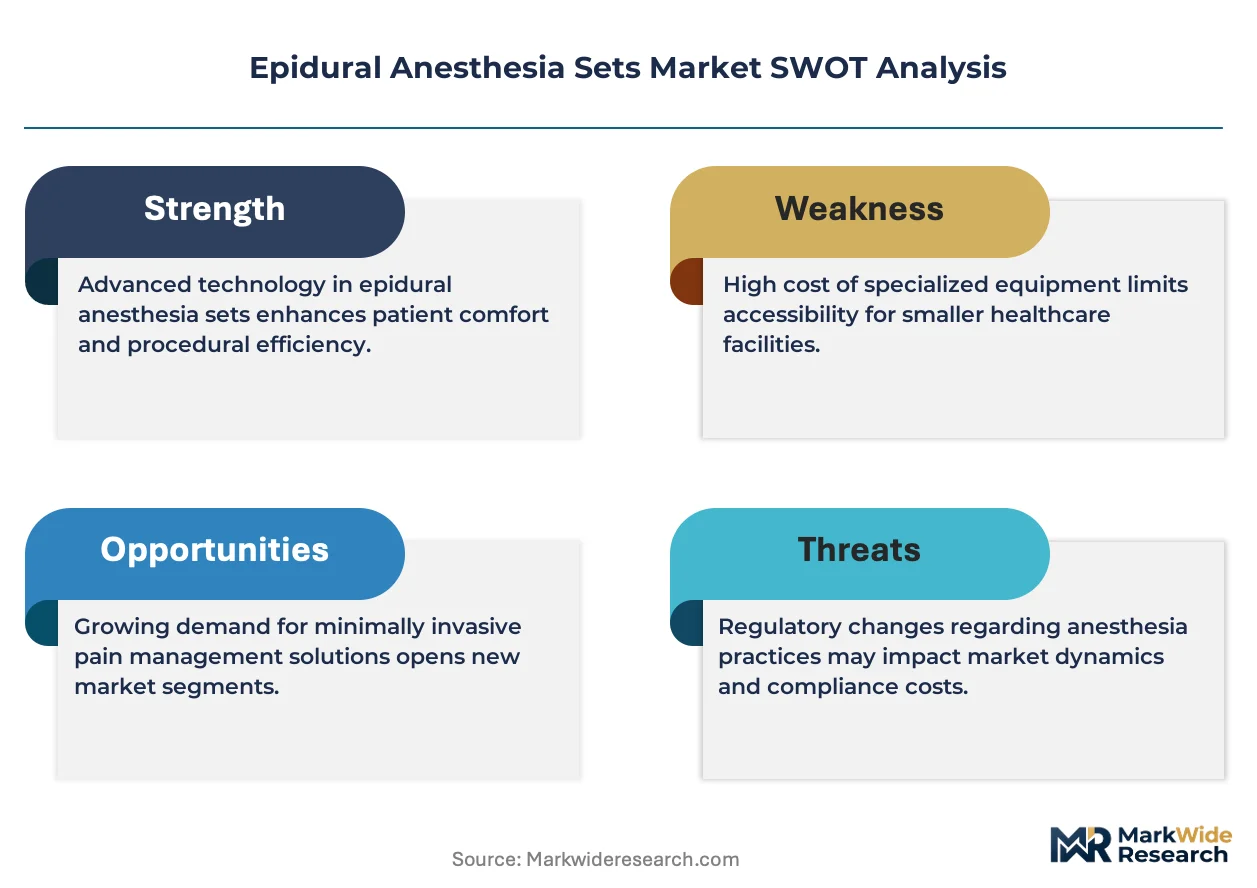
The FDA enforces 510(k) premarket notification requirements for epidural needles and catheters under product code KRA, while the EU Medical Device Regulation mandates notified body conformity assessment and unique device identification for Class IIa neuraxial devices. ISO 80369-6 small-bore connector standards are reshaping set design to prevent misconnection events with neuraxial lines. Stakeholders must monitor evolving sterilization validation requirements and catheter material biocompatibility testing protocols as regulatory scrutiny intensifies for long-dwell epidural applications.
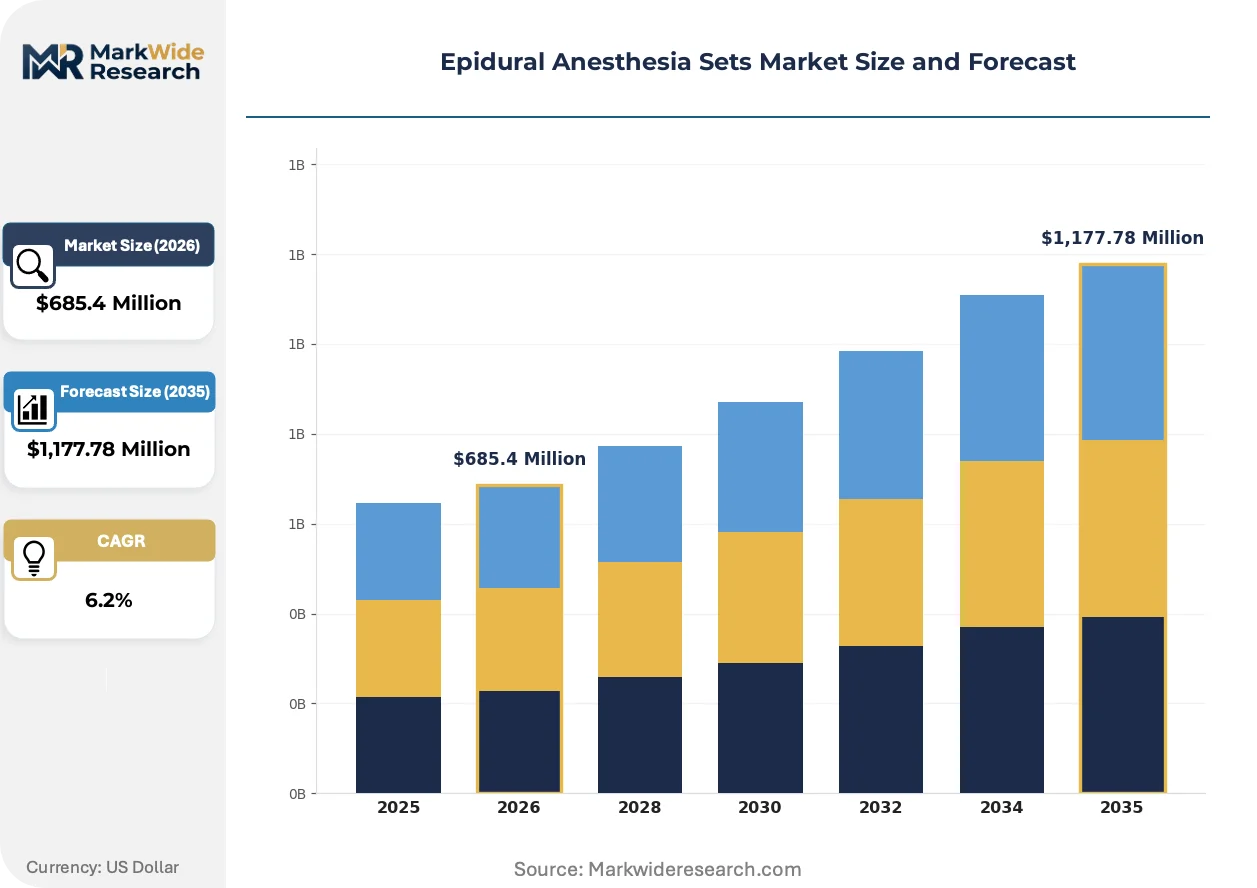
Market Dynamics
Pre-bundled tray configurations are consolidating procurement relationships across hospital systems as integrated delivery networks seek to reduce vendor complexity and standardize operating room workflows. This structural force favors suppliers capable of delivering complete sterile assemblies with validated ethylene oxide sterilization documentation.
Growth Catalysts
- ISO 80369-6 small-bore connector mandates:The FDA and EU MDR are enforcing neuraxial-specific connector standards that prevent misconnection events with intravenous lines, compelling hospital systems to replace legacy inventory.
- Ambulatory surgery center expansion:Outpatient spinal procedures and pain clinic epidural steroid injections are creating dedicated demand for single-use catheter kits designed for short-dwell protocols.
- Ethylene oxide sterilization infrastructure:Contract sterilizers in the United States and Germany have expanded capacity for temperature-sensitive polymer components, reducing kit production bottlenecks.
Market Restraints
- Polyurethane and nylon raw material concentration:Medical-grade catheter polymers rely on specialty chemical suppliers concentrated in the German and US industrial corridors, exposing manufacturers to input cost volatility.
- EU MDR notified body capacity constraints:The tightened conformity assessment timeline for Class IIa neuraxial devices is extending time-to-market for new kit configurations by twelve to eighteen months.
- Ultrasound-guided peripheral nerve blocks:Anesthesiology departments are substituting catheter-based epidural approaches with single-injection ultrasound techniques for select orthopedic procedures.
Strategic Opportunities
- Indian tertiary hospital expansion:Corporate hospital chains in Maharashtra and Karnataka are building dedicated labor and delivery towers that specify pre-configured epidural trays for standardized obstetric anesthesia protocols.
- Closed-system transfer device integration:Convergence between neuraxial drug delivery and hazardous drug handling standards is creating demand for needle-free connector systems in oncology pain management.
- Direct-to-facility distribution platforms:Digital procurement channels are enabling ambulatory surgery centers to bypass traditional distributor markups on high-volume catheter kit replenishment.
Industry Challenges
- ISO 13485 auditor shortage:Qualified quality management system auditors for sterile device manufacturing are concentrated in Western Europe and the United States, delaying certification renewals for Asian contract manufacturers.
- Legacy hospital inventory systems:Enterprise resource planning platforms at mid-sized US hospital systems lack granularity to track unique device identifiers mandated under FDA UDI rules, complicating kit traceability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Epidural Anesthesia Sets Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Needle Sets, Catheter Kits, Tray Sets, Accessories Application: Labor and Delivery, Pain Management, Surgical Procedures, Postoperative Care End User: Hospitals, Ambulatory Surgery Centers, Pain Clinics, Home Care Distribution Channel: Direct Sales, Online Platforms, Wholesalers, Distributors |
| Companies Covered | ICU Medical, PAJUNK GmbH, B. Braun, Well Lead Medical, Smiths Medical, BD, Vygon, Zhejiang Fert Medical Device, Teleflex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Epidural Anesthesia Sets Market Shifts & Advancements
Antimicrobial catheter coatings and closed-tip epidural needle designs are redefining safety benchmarks while regulatory pressure on sterilization validation intensifies. These developments are compressing product lifecycles and raising barriers for undifferentiated kit assemblers.
Closed-tip Tuohy needles with integrated catheter introducers are rewriting procedural efficiency standards in academic medical centers. Anesthesiology residency programs at US teaching hospitals are adopting these configurations for training curricula. The technology is compressing placement time and reducing dural puncture rates, forcing competitors to match engineering specifications or exit premium tier positioning.
The EU Medical Device Regulation's unique device identification requirements are mandating serialized labeling across all neuraxial device classes. Sterile device manufacturers must revalidate packaging lines for laser-etched polymer components and maintain centralized databases for post-market surveillance. Class IIa catheter kits face the most acute compliance burden, with notified bodies in Germany and the Netherlands experiencing application backlogs exceeding fourteen months.
Consolidated vendor agreements are displacing spot purchasing for operating room supplies across US integrated delivery networks. Ambulatory surgery centers affiliated with these systems must procure from contracted suppliers or absorb administrative penalties. The shift is most visible in Texas and Florida health systems, where tray standardization programs have reduced approved epidural kit SKUs by sixty percent within single-network footprints.
Epidural Anesthesia Sets Market Segmentation
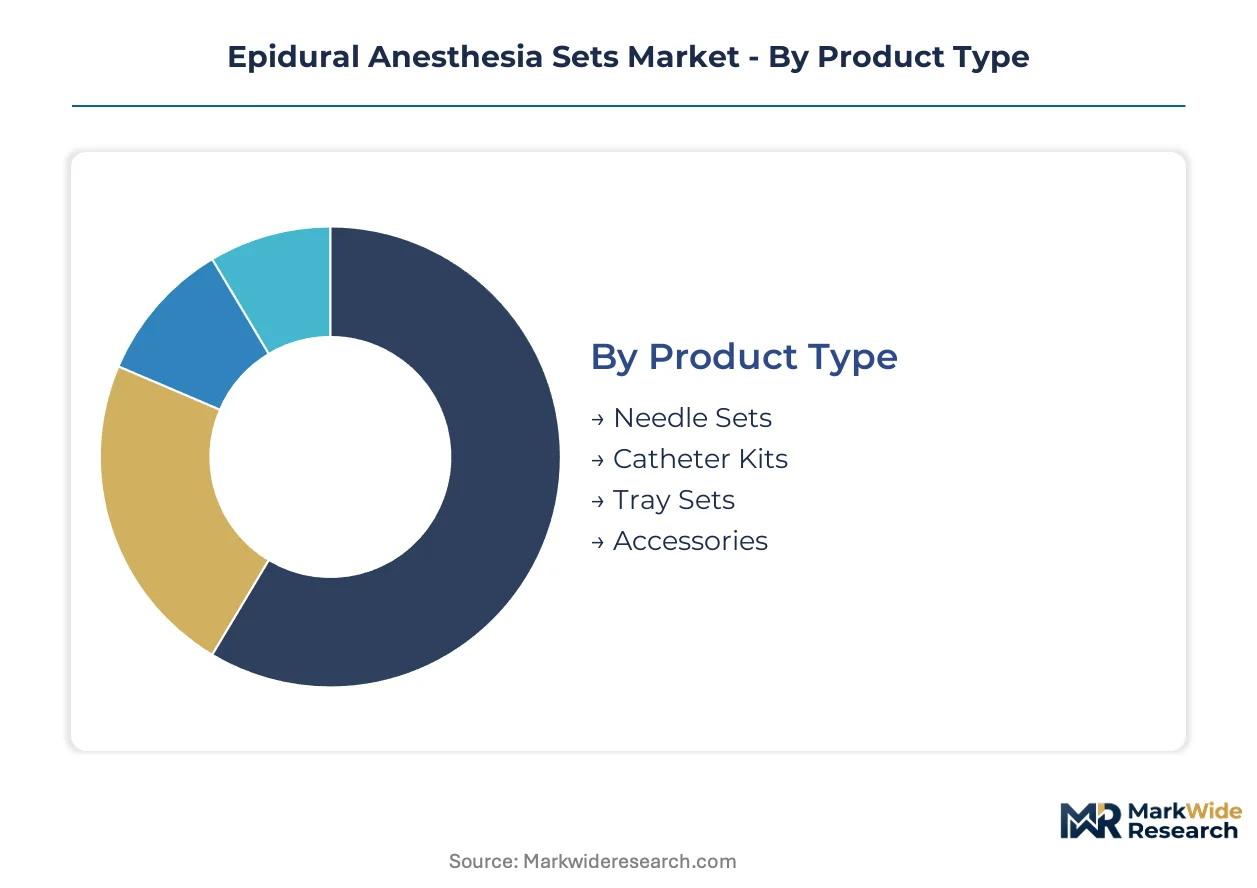
Epidural anesthesia sets fragment across four dimensions that shape capital deployment and margin capture. Product type determines sterilization infrastructure requirements. Application and end-user concentration dictate regional sales force allocation. Distribution channel selection reflects procurement centralization trends.
Product Type:
Capital intensity varies sharply across product configurations, with sterilization validation and polymer molding capabilities driving fixed cost structures.
- Catheter Kits:Multi-lumen polyurethane or nylon assemblies with radiopaque markers and closed-tip designs command premium positioning. Demand concentrates in US academic medical centers where extended indwelling protocols for postoperative pain management require biocompatible materials with validated ethylene oxide sterilization cycles.
- Tray Sets:Pre-bundled sterile assemblies integrate needles, catheters, filters, syringes, and drapes under ISO 13485 quality systems. Integrated delivery networks in Texas and Florida health systems favor these configurations to reduce operating room vendor complexity and standardize procurement workflows.
- Needle Sets:Tuohy and Crawford needle configurations with integrated introducers serve specialized neuraxial access requirements.
- Accessories:Filters, syringes, and drapes complete sterile field preparation for aseptic technique maintenance.
Catheter kits absorb the bulk of installed capacity; tray sets are expanding most quickly.
Application:
Clinical setting determines reimbursement pathways and regulatory scrutiny intensity, with hospital-based procedures facing stricter documentation requirements than ambulatory alternatives.
- Labor and Delivery:Obstetric epidural anesthesia remains the most mature application segment with established procedural protocols. Hospital systems in Maharashtra and Karnataka, India specify pre-configured trays for standardized obstetric anesthesia in dedicated labor and delivery towers.
- Pain Management:Outpatient epidural steroid injections and chronic pain interventions drive fastest expansion. Pain clinics in the United States represent the steepest expansion trajectory as procedural volumes shift from hospital settings to specialized ambulatory facilities.
- Surgical Procedures:Intraoperative neuraxial anesthesia for orthopedic and abdominal surgery maintains steady utilization in acute care settings.
- Postoperative Care:Extended catheter dwell times for multimodal pain protocols require specialized kit configurations with enhanced biocompatibility testing.
Labor and delivery maintains the largest installed base; pain management is climbing the fastest.
End User:
Facility type shapes purchasing behavior, with consolidated health systems exercising greater price leverage than independent operators.
- Hospitals:Acute care facilities with centralized materials management departments negotiate multi-year vendor agreements. FDA 510(k) premarket notification requirements under product code KRA and EU MDR Class IIa conformity assessments dominate procurement qualification criteria.
- Ambulatory Surgery Centers:Outpatient spinal procedure growth creates dedicated demand for short-dwell catheter kits. These facilities in the United States increasingly bypass traditional distributor markups through digital procurement platforms for high-volume replenishment.
- Pain Clinics:Specialized interventional pain practices prioritize procedure efficiency and inventory turnover speed.
- Home Care:Extended epidural infusion for palliative oncology pain management requires closed-system transfer device integration for hazardous drug handling compliance.
Hospitals command the dominant share of procurement volume; ambulatory surgery centers are gaining share fastest.
Distribution Channel:
Channel selection reflects customer scale and geographic concentration, with direct relationships reserved for high-volume accounts.
- Direct Sales:Manufacturer field forces serve integrated delivery networks with customized tray configurations and validated sterilization documentation. US health systems with consolidated vendor agreements impose administrative penalties on non-contracted supplier purchases.
- Distributors:Regional medical-surgical distributors maintain inventory proximity to mid-sized hospital systems lacking enterprise resource planning granularity for FDA unique device identifier tracking.
- Online Platforms:Digital procurement channels enable ambulatory surgery centers to access competitive pricing on standardized catheter kit configurations.
- Wholesalers:Broadline distributors serve fragmented customer bases with spot purchasing requirements and limited contract penetration.
Direct sales capture the majority of contracted revenue; online platforms are expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany manufactures the bulk of ethylene oxide sterilization equipment and specialty polymer feedstock, while the United States consumes the most pre-bundled tray configurations through its integrated delivery networks.
United States
Integrated delivery networks in Texas and Florida health systems drive procurement consolidation through standardized tray programs that reduced approved SKUs by sixty percent. FDA 510(k) premarket notification requirements under product code KRA govern neuraxial device clearance. Academic medical centers in the Northeast and California adopt closed-tip Tuohy needle configurations for anesthesiology residency training curricula.
Germany
Specialty chemical suppliers in the German industrial corridor concentrate medical-grade polyurethane and nylon production for catheter polymers. EU MDR notified bodies in Germany experience application backlogs exceeding fourteen months for Class IIa neuraxial device conformity assessments. Sterile device manufacturing clusters in Baden-Württemberg and North Rhine-Westphalia anchor ethylene oxide sterilization infrastructure expansion.
India
Corporate hospital chains in Maharashtra and Karnataka build dedicated labor and delivery towers specifying pre-configured epidural trays for standardized obstetric anesthesia protocols. CDSCO regulates medical device imports and domestic manufacturing under the Medical Device Rules framework. Tertiary hospital expansion in Delhi-NCR and Tamil Nadu creates procurement scale for single-use neuraxial kits.
China
NMPA oversees Class II medical device registration for epidural needles and catheters under national standards. Yangtze River Delta manufacturing clusters produce polymer components for regional kit assemblers. Zhejiang province hosts domestic medical device companies serving price-sensitive hospital procurement through distributor networks.
United Kingdom
NHS procurement frameworks favor pre-bundled sterile assemblies to reduce operating room vendor complexity. MHRA implements EU MDR-aligned regulations for neuraxial device market access. London and Southeast England academic hospitals concentrate demand for premium catheter kits with extended indwelling protocols.
Epidural Anesthesia Sets Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across sterilization validation, polymer molding, and precision needle engineering capabilities. The vendor base separates into three strategic archetypes: integrated infusion therapy suppliers leveraging hospital system relationships, European sterile device manufacturers with captive ethylene oxide infrastructure, and precision engineering specialists concentrating on neuraxial access tools. Competitive positioning hinges on M&A activity consolidating tray configuration portfolios and strategic partnerships securing polymer supply commitments.
Among diversified medical technology suppliers, BD and B. Braun exemplify scale-driven archetypes with established acute care channel control, while PAJUNK GmbH represents the precision engineering specialist tier focused on needle technology. ICU Medical occupies a position bridging infusion therapy infrastructure with neuraxial delivery systems. These three anchors illustrate how competitive advantage flows from either manufacturing scale, technical specialization, or integrated delivery network penetration.
| Leading Market Players |
|---|
| ICU Medical |
| PAJUNK GmbH |
| B. Braun |
| Well Lead Medical |
| Smiths Medical |
| BD |
| Vygon |
| Zhejiang Fert Medical Device |
| Teleflex |
| Others |
Supply & Pricing Matrix
Qualified ethylene oxide sterilization technicians in Baden-Württemberg and North Rhine-Westphalia anchor labor-cost differentials that widen pricing-tier spreads between European-manufactured premium catheter kits and Asian-assembled economy configurations. This workforce concentration forces manufacturers to absorb regional wage premiums or offshore sterilization validation, reshaping margin structures across product tiers.
Pricing Analysis
Cost-down pressure on standard catheter kits accelerates as integrated delivery networks in Texas and Florida consolidate vendor agreements and impose administrative penalties on non-contracted purchases. Three-tier pricing structure across premium, standard, and economy levels separates closed-tip Tuohy needle systems with ISO 80369-6 compliance from legacy connector inventory and unbranded Asian imports. Price differentiation hinges on FDA 510(k) clearance tier under product code KRA and ethylene oxide sterilization documentation depth. Ambulatory surgery centers exhibit highest price sensitivity due to digital procurement platform access, while academic medical centers prioritize premium catheter kits with extended indwelling protocols regardless of cost.
Supply Chain Analysis
Medical-grade polyurethane and nylon feedstock rests on specialty chemical producers concentrated in the German industrial corridor and select US Gulf Coast petrochemical clusters. Raw material dependencies include radiopaque polymer additives, precision stainless steel for Tuohy needle blanks, and ethylene oxide sterilization gas supply. Single-source vulnerability concentrates in notified body conformity assessment capacity, with German and Dutch regulators experiencing fourteen-month application backlogs for Class IIa neuraxial devices. Distribution runs through direct sales forces for integrated delivery networks, regional medical-surgical distributors for mid-sized hospital systems, and digital procurement platforms for ambulatory surgery centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The epidural anesthesia sets market sits in a technology-transition phase as closed-tip Tuohy needle designs with integrated catheter introducers displace legacy open-tip configurations across US academic medical center training curricula.
For Market Incumbents: Cement channel control within integrated delivery networks by expanding ethylene oxide sterilization documentation services and pre-bundled tray customization capabilities. Lock in multi-year vendor agreements before EU MDR notified body backlogs clear and new entrants achieve Class IIa conformity assessment. Prioritize backward integration into medical-grade polymer compounding to offset raw material cost volatility from German specialty chemical suppliers. For New Entrants and Emerging Players: Capture ambulatory surgery center procurement through digital platform partnerships offering competitive catheter kit pricing with validated short-dwell protocols. Target pain clinic expansion in US metropolitan markets where outpatient epidural steroid injection volumes climb fastest. Pursue white-label manufacturing arrangements with Indian corporate hospital chains building dedicated labor and delivery towers in Maharashtra and Karnataka. For Investors and Strategic Acquirers: Re-rating potential sits with precision needle engineering specialists given closed-tip Tuohy technology adoption acceleration across anesthesiology residency programs. Long-term viability favors manufacturers with captive ethylene oxide infrastructure and ISO 13485 certification depth over kit assemblers lacking sterilization validation capabilities. Watch EU MDR notified body capacity expansion as the inflection signal for new product launch velocity recovery.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Class IIa Conformity Assessment | Notified body clearance unlocks European market access for neuraxial device portfolios. |
| Closed-System Transfer Device Integration | Oncology pain management protocols demand needle-free connectors for hazardous drug handling compliance. |
| ISO 80369-6 Connector Compliance | Small-bore neuraxial-specific standards prevent misconnection events and force legacy inventory replacement. |
| Direct-to-Facility Distribution Platform | Digital procurement channels enable ambulatory surgery centers to bypass traditional distributor markups. |
| Antimicrobial Catheter Coating Development | Extended indwelling protocols in postoperative care require biocompatibility-validated infection prevention. |
Research Methodology
FDA 510(k) premarket notification databases, EU MDR notified body public registers, and hospital procurement contract repositories formed the secondary backbone for market sizing and regulatory pathway mapping. Primary interviews with anesthesiology department heads, GPO contracts managers, biomedical engineers, and sterile device manufacturing quality directors validated demand assumptions and pricing dynamics. Bottom-up triangulation across catheter kit configuration volumes combined with top-down cross-checks against integrated delivery network spending patterns anchored forecast reliability.
Bottom-up modeling built projections from product-type, application, end-user, and distribution channel segmentations across the analysis window. Value outputs reflected unit volume estimates multiplied by pricing tier assumptions derived from direct sales contract structures and digital platform transaction data. CAGRs were derived from logistic curve fitting to adoption saturation limits, with pain clinic expansion and ambulatory surgery center procedural growth as key demand-side inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU MDR notified body capacity resolution and raw material polymer cost trajectories. Forecasts reflect documented assumptions regarding ISO 80369-6 compliance deadlines and integrated delivery network vendor consolidation velocity. A small set of triggers—ultrasound-guided peripheral nerve block substitution rates, ethylene oxide sterilization regulatory restrictions, and Indian tertiary hospital construction pace—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Pancreatic and Biliary Stents Market
Medical Devices
Hemoconcentrators Market
Medical Devices
Global Pediatric Medical Devices Market
Medical Devices
Global Microscopy Device Market
Medical Devices
Artificial Eye Market
Medical Devices
Electroencephalography Systems/Devices Market
Medical Devices
Brazil Angioplasty Devices Market
Medical Devices
Electrosurgery Accessories Market
Medical Devices
Animal Ultrasound Market
Medical Devices
PET Injectors Market
Medical Devices
Catheter Introducer Sheaths Market
Medical Devices
Australia Insulin Delivery Devices Market
Medical Devices
Corneal Cross Linking Devices Market
Medical Devices
Contact Lens Lubricant Market
Medical Devices
Artificial Ventilation and Anesthesia Masks Market
Medical Devices
Italy Respiratory Devices Market