
 Global Atrial Fibrillation Drugs Market | 2026-2036
Global Atrial Fibrillation Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Atrial Fibrillation Drugs Market Foresight
The EU Green Deal's pharmaceutical sustainability criteria is shifting procurement standards across European hospital networks. Bristol-Myers Squibb leverages its established anticoagulant portfolio to sustain market presence in rhythm control therapies. Daiichi Sankyo anchors its competitive position through specialized direct oral anticoagulant development. Janssen Pharmaceuticals differentiates via deep channel control across hospital and specialty pharmacy networks.
Atrial fibrillation drugs comprise pharmacological agents designed to modulate cardiac electrophysiology, including anticoagulants that inhibit thrombin formation or vitamin K-dependent clotting factors, antiarrhythmics that block sodium or potassium channels, and rate-control agents that slow atrioventricular nodal conduction. These therapeutics serve to reduce stroke risk, restore sinus rhythm, or manage ventricular response rates in patients with irregular atrial depolarization. Direct oral anticoagulants command the dominant margin pool within drug class segmentation due to superior safety profiles and reduced monitoring burden versus vitamin K antagonists. Rhythm control therapies represent the fastest-expanding therapy approach segment as catheter ablation adjacency drives combination pharmacological strategies. Hospital pharmacies retain the largest volume share among distribution channels, though specialty pharmacies are capturing higher-complexity patient cohorts.
The FDA maintains stringent cardiovascular outcomes trial requirements for novel antiarrhythmic approvals, while the EMA's MDR framework governs device-drug combination product standards across European markets. Japan's PMDA imposes localized pharmacokinetic bridging studies that extend market access timelines for foreign-developed agents. Stakeholders must monitor evolving regulatory convergence between FDA and EMA on real-world evidence acceptance for label expansion decisions.
Market Dynamics
The FDA's accelerated approval pathways for cardiovascular therapies are compressing development timelines while EMA's MDR framework raises compliance thresholds, creating divergent competitive speed across Atlantic markets.
Growth Catalysts
- Aging Demographics:Hospital systems across the United States, Germany, and Japan are expanding anticoagulation protocols to manage geriatric patient volumes with elevated stroke risk profiles.
- EU Green Deal Pharmaceutical Criteria:Sustainability-linked procurement standards are reshaping tender requirements across European hospital networks, favoring manufacturers with verified environmental compliance.
- Catheter Ablation Adjacency:Rhythm control therapies are capturing expanded indication use as electrophysiology labs integrate pharmacological strategies with procedural interventions.
Market Restraints
- Specialized Manufacturing Concentration:Active pharmaceutical ingredient production for direct oral anticoagulants clusters in select Asian contract manufacturing organizations, creating single-source vulnerability.
- PMDA Bridging Study Requirements:Japan's regulator mandates localized pharmacokinetic trials that extend market access timelines by 18-24 months for foreign-developed agents.
- Warfarin Cost Floor:Generic vitamin K antagonists maintain formulary presence at price points that compress reimbursement headroom for novel therapeutic entries.
Strategic Opportunities
- Specialty Pharmacy Channel Expansion:Higher-complexity patient cohorts with polypharmacy needs are migrating toward managed care networks with integrated clinical support services.
- Real-World Evidence Label Expansion:FDA-EMA convergence on observational data standards enables post-market indication broadening without redundant placebo-controlled trials.
- Device-Drug Combination Products:Implantable sensors paired with anticoagulant dosing algorithms represent white space at the intersection of cardiac electrophysiology and digital therapeutics.
Industry Challenges
- Cardiovascular Outcomes Trial Design:FDA mandates for large-scale safety studies require recruitment of thousands of patients with documented arrhythmia burden, stretching clinical operations capacity.
- Electrophysiology Specialist Scarcity:Ablation procedure growth is outpacing fellowship training pipeline output, creating bottlenecked referral pathways that limit rhythm control therapy adjacency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Atrial Fibrillation Drugs Market |
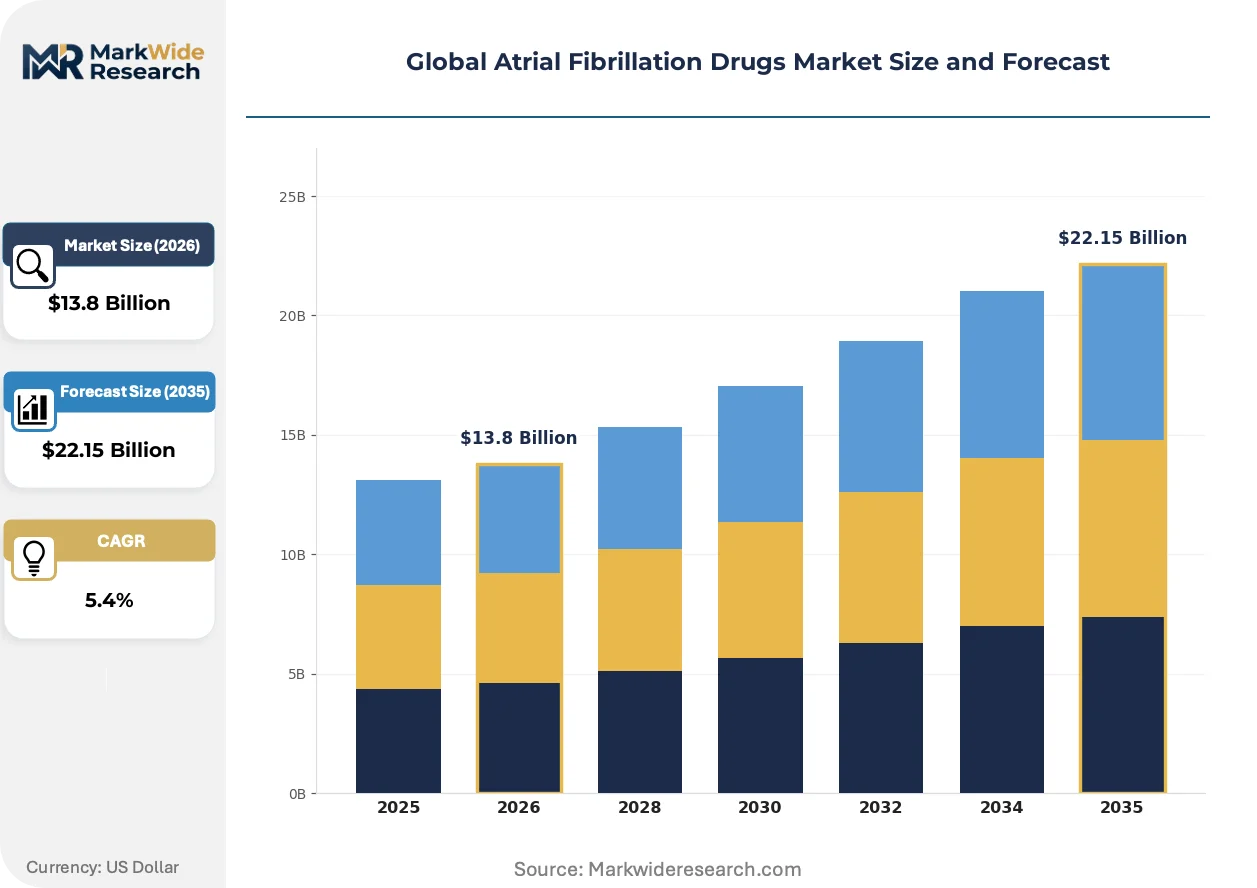
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $22.15 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Class: Vitamin K Antagonists, Direct Oral Anticoagulants, Beta Blockers, Calcium Channel Blockers, Antiarrhythmics Therapy Approach: Rate Control, Rhythm Control, Anticoagulation, Stroke Prevention, Symptom Management Patient Group: Geriatric, Adult, Pediatric, Postoperative, Comorbid Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Clinics, Specialty Pharmacies |
| Companies Covered | Boehringer Ingelheim, Bristol-Myers Squibb, Sanofi, Pfizer, Daiichi Sankyo, Janssen Pharmaceuticals, Gilead Sciences, ARCA Biopharma, HUYA Biosciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Atrial Fibrillation Drugs Market Shifts & Advancements
Digital biomarker integration and pharmacogenomic dosing algorithms are redefining therapeutic personalization in atrial fibrillation management, shifting value capture toward data-enabled care models.
Pharmacogenomic testing for CYP2C9 and VKORC1 variants is unifying anticoagulation selection with metabolic profiling in major academic medical centers. Hospital systems with embedded clinical pharmacogenomics programs are adopting genotype-guided warfarin dosing and novel agent selection at expanding scale. This convergence is compressing the trial-and-error titration period that previously delayed therapeutic optimization.
EMA's Medical Device Regulation framework is elevating documentation requirements for drug-device combination products entering European markets. Manufacturers must now submit expanded clinical evidence packages for sensor-enabled dosing systems and connected inhalation devices. Rhythm control therapy developers with integrated monitoring platforms are restructuring regulatory submissions to satisfy MDR technical documentation standards.
Hospital pharmacy procurement committees are consolidating vendor relationships through single-source contracting for anticoagulation formularies. Integrated delivery networks in the United States are replacing multi-manufacturer purchasing with exclusive agreements that bundle clinical support services. This concentration is most visible in Medicare Advantage-dominated regions where total cost of care contracts incentivize therapeutic standardization.
Global Atrial Fibrillation Drugs Market Segmentation
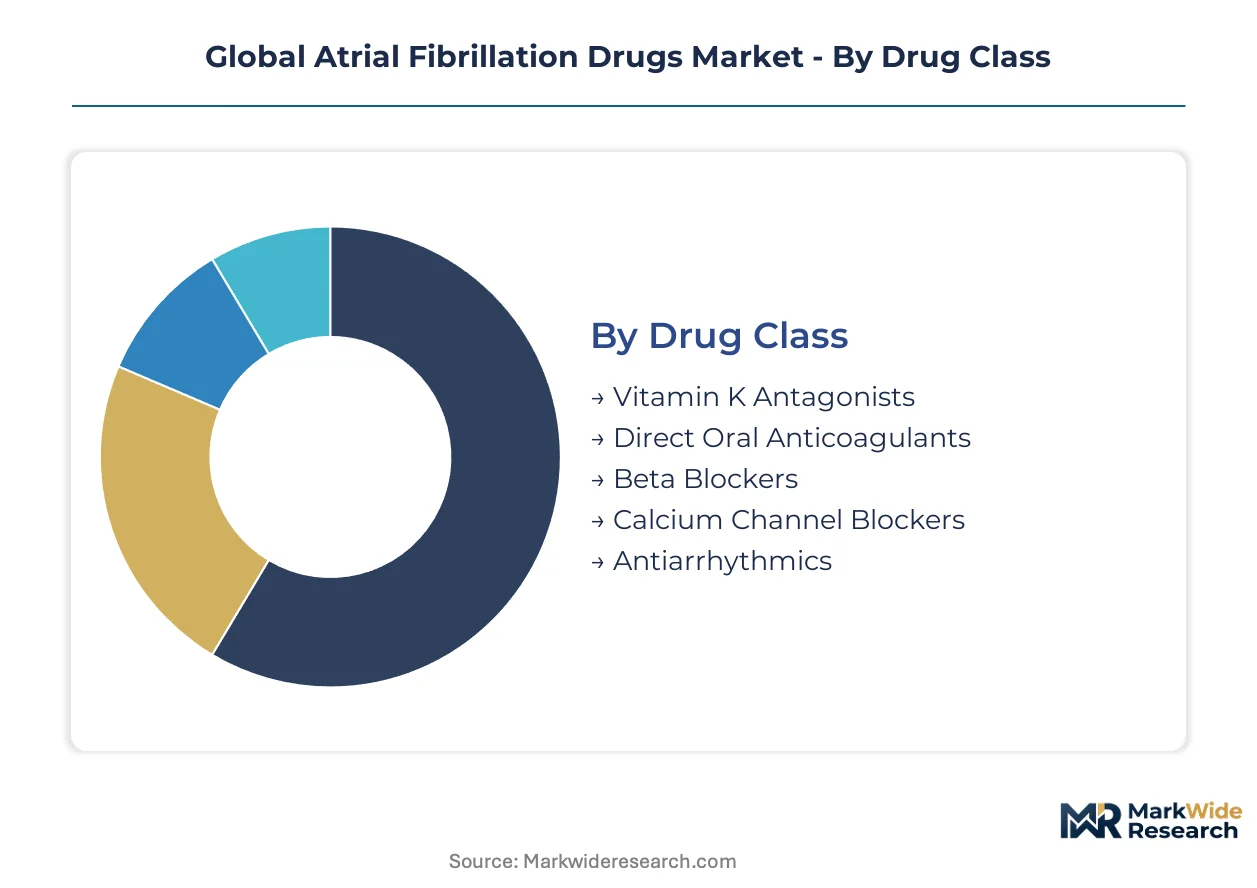
Atrial fibrillation pharmacotherapy demands precise patient stratification. Therapeutic selection hinges on comorbidity profiles, bleeding risk scores, and electrophysiology lab adjacency. Manufacturers configure portfolio investments across these axes to capture differential reimbursement and prescriber loyalty.
Drug Class:
Mechanism of action defines clinical positioning and monitoring burden.
- Direct Oral Anticoagulants:Factor Xa and direct thrombin inhibitors eliminate INR monitoring requirements. Hospital systems in the United States and Germany prioritize these agents for outpatient anticoagulation clinics. Superior safety profiles versus warfarin justify premium pricing in risk-based contracting environments.
- Antiarrhythmics:Sodium channel blockers and potassium channel blockers modulate atrial refractoriness. Electrophysiology specialists in Japan prescribe these as bridge-to-ablation or standalone rhythm control. FDA-mandated cardiovascular outcomes trials constrain new molecular entity entry.
- Vitamin K Antagonists:Warfarin maintains formulary presence through generic pricing floors. Medicare Advantage plans retain coverage for cost-sensitive patient cohorts.
- Beta Blockers:Metoprolol and carvedilol dominate first-line rate control. Cardiology practices deploy these for ventricular response management pending definitive therapy.
- Calcium Channel Blockers:Diltiazem and verapamil serve as beta blocker alternatives. Renal impairment populations drive non-dihydropyridine selection.
Direct Oral Anticoagulants lead on scale; Antiarrhythmics lead on momentum.
Therapy Approach:
Clinical objectives determine prescriber specialty and care setting.
- Anticoagulation:Stroke risk reduction drives chronic therapy initiation. The FDA's accelerated approval pathways compress development timelines for novel anticoagulant mechanisms. Integrated delivery networks bundle these with clinical pharmacy services.
- Rhythm Control:Sinus rhythm restoration targets symptomatic paroxysmal patients. Catheter ablation adjacency expands indication use across electrophysiology labs in Germany and the United States.
- Rate Control:Ventricular response management suits elderly comorbid populations. Primary care physicians initiate these in advance of cardiology referral.
- Stroke Prevention:Left atrial appendage occlusion candidates require bridging protocols. Anticoagulation clinics coordinate peri-procedural drug holidays.
- Symptom Management:Palpitation control and exercise tolerance optimization. Patient-reported outcome instruments guide titration decisions.
Anticoagulation commands the largest patient volume; Rhythm Control is climbing the fastest.
Patient Group:
Age and clinical context shape bleeding risk stratification and therapeutic intensity.
- Geriatric:Patients over 75 years carry elevated stroke and fall risk. HAS-BLED scoring drives agent selection in Japanese geriatric medicine.
- Comorbid:Heart failure, diabetes, and chronic kidney disease complicate anticoagulation. Renal function monitoring protocols vary across hospital systems.
- Adult:Working-age patients prioritize once-daily dosing and minimal dietary restrictions. Employer-sponsored plans influence prior authorization requirements.
- Postoperative:Cardiac surgery patients require transient atrial fibrillation prophylaxis. Hospital pharmacy formularies stock short-acting intravenous options.
- Pediatric:Congenital heart disease populations represent off-label use. Pediatric electrophysiology centers at academic medical centers manage these cohorts.
Geriatric populations anchor prescription volume; Comorbid segments show steepest expansion trajectory.
Distribution Channel:
Supply path determines clinical support intensity and reimbursement mechanics.
- Hospital Pharmacies:Inpatient initiation and discharge prescribing dominate anticoagulation starts. EMA's MDR framework elevates documentation for drug-device combinations stocked in European hospital networks.
- Specialty Pharmacies:High-complexity patients with polypharmacy needs migrate toward managed care networks. Prior authorization navigation and adherence monitoring justify channel premium.
- Retail Pharmacies:Maintenance refills for stable outpatients. Medicare Part D plan formularies drive generic substitution patterns.
- Clinics:Anticoagulation clinics with point-of-care INR testing retain warfarin patients. Integrated delivery networks consolidate vendor relationships through exclusive agreements.
- Online Pharmacies:90-day supply fulfillment for established chronic therapy. State pharmacy board regulations govern controlled substance limitations.
Hospital Pharmacies retain volume leadership; Specialty Pharmacies are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrophysiology specialists and clinical pharmacologists cluster in metropolitan medical centers across the United States, Germany, and Japan, anchoring regional demand concentration for rhythm control and anticoagulation therapies. Hospital pharmacy procurement power and reimbursement access determine competitive positioning in each geography.
United States
Medicare Advantage expansion and integrated delivery network consolidation drive anticoagulation protocol standardization. The FDA's accelerated approval pathways compress cardiovascular therapy development timelines. The Cleveland Clinic and Mayo Clinic anchor electrophysiology research clusters that shape prescriber behavior across Midwestern hospital systems.
Germany
Statutory health insurance reimbursement for direct oral anticoagulants sustains premium pricing acceptance among ambulatory care physicians. The EU Green Deal's pharmaceutical sustainability criteria reshape tender requirements across university hospital networks. Berlin and Munich host concentration of cardiology research institutes that influence European treatment guidelines.
Japan
Geriatric medicine specialists in Tokyo and Osaka manage elevated atrial fibrillation prevalence in aging cohorts. The PMDA mandates localized pharmacokinetic bridging studies that extend market access timelines for foreign-developed agents. The Japanese Circulation Society's guideline updates drive rhythm control therapy selection patterns.
United Kingdom
NICE technology appraisals determine formulary placement for novel antiarrhythmics across NHS trusts. The MHRA's post-Brexit regulatory autonomy enables accelerated access schemes for cardiovascular innovations. London's academic medical centers concentrate electrophysiology fellowship training that feeds specialist distribution nationally.
Switzerland
Swissmedic's streamlined marketing authorization procedures attract cardiovascular drug development investment. Cantonal hospital procurement consortiums negotiate anticoagulation formulary contracts with integrated clinical support requirements. Basel and Zurich anchor pharmaceutical research clusters with established cardiology trial infrastructure.
Global Atrial Fibrillation Drugs Market Competitive Landscape
Capital-heavy producers with integrated manufacturing footprints compete with asset-light developers licensing late-stage candidates, creating tiered competitive dynamics. The vendor base stratifies across three strategic archetypes: established anticoagulant portfolio holders, specialized direct oral anticoagulant innovators, and rhythm control therapy developers pursuing catheter ablation adjacency. Dominant competitive moves include exclusive distribution contracting with integrated delivery networks and pharmacogenomic companion diagnostic partnerships.
Within the established portfolio tier, Bristol-Myers Squibb and Pfizer occupy positions sustained by hospital formulary relationships and clinical pharmacy service bundling. Daiichi Sankyo anchors the specialized anticoagulant segment with factor Xa inhibitor development concentration. Janssen Pharmaceuticals exemplifies channel control differentiation through specialty pharmacy network integration.
| Leading Market Players |
|---|
| Boehringer Ingelheim |
| Bristol-Myers Squibb |
| Sanofi |
| Pfizer |
| Daiichi Sankyo |
| Janssen Pharmaceuticals |
| Gilead Sciences |
| ARCA Biopharma |
| HUYA Biosciences |
| Others |
Supply & Pricing Matrix
Hospital pharmacy procurement committees in the United States and Germany are consolidating anticoagulation formulary contracts through single-source exclusive agreements, forcing manufacturers to bundle clinical pharmacy services and absorb compliance costs while compressing net pricing across direct oral anticoagulant portfolios.
Pricing Analysis
Bundled clinical support services versus unbundled product-only contracting defines the pricing architecture in atrial fibrillation therapeutics. Three-tier pricing structure across premium novel agents, standard direct oral anticoagulants, and economy generic warfarin segments reflects certification grade and prescriber support intensity. Pricing pressure stems from Medicare Advantage total cost of care contracts that incentivize therapeutic standardization. Generic vitamin K antagonists capture the most price-sensitive cohorts in cost-conscious health systems, while specialty pharmacy networks serving polypharmacy patients exhibit lowest price elasticity.
Supply Chain Analysis
Reverse-logistics flows for temperature-sensitive biologics and controlled substance returns create specialized handling requirements that elevate distribution costs for antiarrhythmic agents. Active pharmaceutical ingredient production for direct oral anticoagulants concentrates in India, China, and select European contract manufacturing organizations. Manufacturing rests on heparin precursor supply, specialized fermentation capacity, and high-purity chemical synthesis infrastructure. Single-source vulnerability in factor Xa inhibitor API production exposes the supply chain to regulatory inspection disruptions. Distribution runs through hospital pharmacy central warehouses and specialty pharmacy hubs with cold-chain validation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The atrial fibrillation drugs market represents a late-cycle quality story where prescriber loyalty and integrated clinical support services command premium positioning as electrophysiology labs demand seamless pharmacological-procedural coordination.
For Market Incumbents: Acquire pharmacogenomic testing platforms and companion diagnostic capabilities to defend against biosimilar anticoagulant entrants and rhythm control therapy displacement by catheter ablation advances. Deepen backward integration into active pharmaceutical ingredient manufacturing to secure supply continuity amid regulatory scrutiny of Asian contract manufacturing organizations. Invest in embedded clinical pharmacy service teams within integrated delivery networks to lock in formulary exclusivity. For New Entrants and Emerging Players: Specialty pharmacy channel partners with integrated adherence monitoring infrastructure offer the most accessible entry vector for novel anticoagulant mechanisms seeking prescriber access outside hospital formulary gatekeepers. Target rhythm control adjacency applications in electrophysiology labs across German university hospital networks where catheter ablation procedure growth outpaces specialist training pipeline output. Pursue pharmacogenomic-guided dosing algorithms as differentiated value propositions in Medicare Advantage risk-based contracting environments. For Investors and Strategic Acquirers: Asymmetric upside sits with developers of device-drug combination products pairing implantable sensors with anticoagulant dosing algorithms, given FDA-EMA convergence on real-world evidence standards and white space at the cardiac electrophysiology-digital therapeutics intersection. Long-term viability favors asset-light developers with late-stage rhythm control candidates and established regulatory pathways rather than capital-intensive manufacturing footprints. Monitor FDA cardiovascular outcomes trial requirement modifications and EMA MDR framework enforcement intensity as inflection indicators for development timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacogenomic Companion Diagnostic Partnership | EMA's MDR framework elevates documentation requirements for sensor-enabled dosing systems entering European hospital networks. |
| Specialty Pharmacy Network Integration | Janssen Pharmaceuticals exemplifies channel control differentiation through managed care network clinical support service bundling. |
| Device-Drug Combination Product Development | FDA-EMA convergence on real-world evidence acceptance enables post-market indication broadening without redundant placebo-controlled trials. |
| Backward Integration into API Manufacturing | Specialized manufacturing concentration in Asian contract manufacturing organizations creates single-source vulnerability requiring supply security investment. |
| Electrophysiology Lab Co-Development Agreement | Cleveland Clinic and Mayo Clinic research clusters shape prescriber behavior across Midwestern hospital systems through rhythm control therapy adjacency. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient volume modeling and top-down pharmaceutical spending analysis provided triangulation across the analysis window.
Segment-weighting approaches applied drug class, therapy approach, patient group, and distribution channel dimensions across the projection horizon. CAGRs derived from procedure volume growth rates, patent expiration schedules, and reimbursement trajectory modeling. Forecast inputs incorporated electrophysiology lab capacity expansion, PMDA bridging study timeline assumptions, and EU Green Deal pharmaceutical sustainability criteria adoption curves.
Revisions become necessary when regulatory convergence between FDA and EMA stalls, when catheter ablation procedure growth decelerates, or when API manufacturing concentration triggers supply disruptions. Practitioners should monitor FDA cardiovascular outcomes trial requirement modifications, PMDA pharmacokinetic bridging study enforcement patterns, and EMA MDR technical documentation standard updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global 3D Printed Drugs Market
Pharmaceuticals
Tapentadol Market
Pharmaceuticals
Hydrocortisone Market
Pharmaceuticals
Global Anti-Infective Agents Market
Pharmaceuticals
Ampicillin Drugs Market
Pharmaceuticals
Global Ethical Pharmaceuticals Market
Pharmaceuticals
Bacteriostatic Water for Injection Market
Pharmaceuticals
Meperidine Market
Pharmaceuticals
Cognitive and Memory Enhancer Drugs Market
Pharmaceuticals
Cervical Cancer Vaccine Market
Pharmaceuticals
Diuretic Drugs Market
Pharmaceuticals
Nasal Antihistamines Market
Pharmaceuticals
Bulbospinal Muscular Atrophy Drugs Market
Pharmaceuticals
Amoxicillin Sodium Clavulanate Potassium for Injection Market
Pharmaceuticals
Global BHK Rabies Vaccine Market
Pharmaceuticals
Global Pharmerging Market