
 Skull Clamp Market | 2026-2036
Skull Clamp Market Size, Share, and Industry Trends Forecast 2026-2036
Skull Clamp Market Outlook
The EU Medical Device Regulation (MDR) is pivoting procurement standards across European hospital systems toward enhanced traceability and post-market surveillance requirements. Integra LifeSciences Holdings Corporation leverages its specialized neurosurgical portfolio to sustain premium positioning in cranial stabilization. Stryker Corporation anchors its competitive stance through broad surgical workflow integration and extensive distribution infrastructure.
A skull clamp is a mechanical fixation device designed to immobilize the patient's head during cranial surgical procedures, typically constructed from aluminum or stainless steel alloys with three-pin or four-pin configurations and torque-limiting mechanisms to prevent intracranial penetration. Its primary purpose is to provide rigid, radiolucent cranial stabilization for neurosurgical, orthopedic, and trauma interventions. Manual clamps dominate current installed bases due to proven reliability and lower capital requirements, while automatic clamps represent the fastest-expanding technology segment as surgical centers prioritize reduced setup time and standardized torque application. Hospitals command the largest end-user share by procedure volume, though surgical centers are gaining traction as outpatient cranial and spinal procedures migrate away from traditional inpatient settings.
The FDA's Class II 510(k) clearance framework governs skull clamp market entry in the United States, while the EU MDR and ISO 13485 quality management standards shape conformity requirements for manufacturers serving European purchasers. Japan's PMDA and METI oversight adds additional layers of clinical evaluation and manufacturing site inspection for Asia-Pacific market participation. Stakeholders must monitor evolving MDR transition timelines and FDA guidance on reusable device reprocessing validation to anticipate compliance costs and competitive positioning shifts.
Market Dynamics
Automatic skull clamp systems are compressing procedural setup times while the EU MDR recalibrates compliance costs and procurement timelines across European hospital networks. Manufacturers must absorb heightened post-market surveillance obligations while accelerating torque-standardization features to capture outpatient migration.
Growth Catalysts
- FDA 510(k) Streamlining:The FDA's updated Class II clearance pathways reduce time-to-market for biocompatibility-validated cranial fixation devices, accelerating manufacturer entry into US academic medical centers.
- Outpatient Procedure Migration:Ambulatory surgical centers are absorbing cranial and spinal interventions previously confined to inpatient settings, driving demand for rapid-setup automatic clamp configurations.
- Radiolucent Alloy Innovation:Carbon-fiber-reinforced polymer and titanium-aluminum hybrid materials enable intraoperative imaging without repositioning, expanding neurosurgical workflow efficiency.
Market Restraints
- Stainless Steel Input Volatility:Medical-grade 316L stainless steel and aluminum alloy pricing fluctuates with energy-intensive smelting costs, compressing margin buffers for mid-tier manufacturers.
- EU MDR Transition Friction:The Medical Device Regulation's enhanced clinical evaluation and notified body capacity constraints are extending recertification timelines for legacy product lines.
- Manual Clamp Longevity:Proven three-pin manual systems with 15-20 year service lives delay replacement cycles in cost-constrained hospital systems, slowing automatic system penetration.
Strategic Opportunities
- Japan PMDA Pathway:Japan's aging neurosurgical patient base and METI-backed hospital modernization incentives create entry points for torque-limited automatic systems with Japanese Industrial Standards certification.
- Trauma Center Integration:Emergency department cranial stabilization protocols are standardizing around rapid-application clamps, opening volume channels outside traditional operating room procurement.
- Reprocessing Validation Services:FDA guidance on reusable device sterilization validation creates aftermarket service revenue streams for manufacturers offering compliance documentation packages.
Industry Challenges
- Torque Calibration Expertise Gap:Biomedical engineering departments lack standardized training for automatic clamp force-limiting mechanism verification, elevating device malfunction risk.
- Legacy System Interoperability:Automatic clamps with proprietary data interfaces face integration friction with existing surgical navigation and imaging platforms in renovated OR suites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skull Clamp Market |
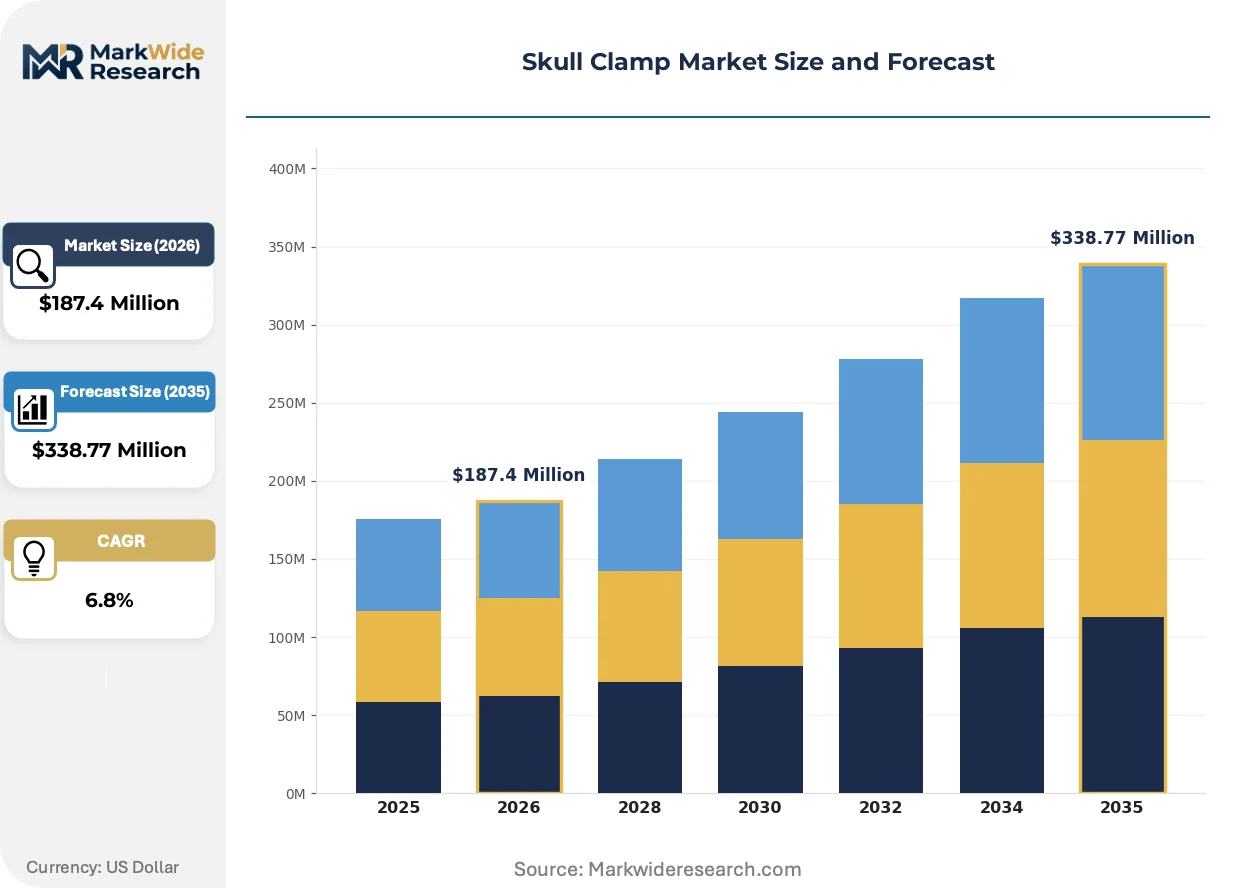
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Clamps, Automatic Clamps, Adjustable Clamps, Fixed Clamps End User: Hospitals, Surgical Centers, Emergency Rooms, Orthopedic Clinics Technology: Mechanical, Hydraulic, Pneumatic, Safety Innovations Application: Neurosurgery, Trauma Surgery, Orthopedic Procedures, Rehabilitation |
| Companies Covered | Integra LifeSciences Holdings Corporation, Becton Dickinson and Company, Pro Med Instruments GmbH, Micromar Industria e Comercio Ltda, Black Forest Medical Group, Mizuho Medical Co Ltd, Medtronic plc, Stryker Corporation, TeDan Surgical Innovations, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skull Clamp Market Strategic Shifts
Surgical workflow digitization and materials science advances are redefining cranial fixation value propositions, while regulatory frameworks on both sides of the Atlantic recalibrate competitive entry barriers.
Carbon-fiber-reinforced radiolucent skull clamps are expanding into high-volume neurosurgical departments seeking uninterrupted intraoperative CT and fluoroscopy access. Academic medical centers in Germany and the United States are piloting these systems for deep-brain stimulation and tumor resection protocols. The technology is expanding into premium pricing tiers as manufacturers bundle imaging-compatible frames with navigation system integration.
The EU MDR's Unique Device Identification and post-market clinical follow-up mandates are elevating documentation burdens for cranial fixation manufacturers. European notified bodies are prioritizing audits of torque-limiting mechanism validation data, compressing approval timelines for firms with preemptive clinical evidence packages. German and French hospital procurement consortiums are now requiring MDR-compliant technical documentation as a precondition for tender participation.
After-sales service unbundling is fragmenting traditional equipment-procurement relationships as hospital systems separate device acquisition from preventive maintenance contracts. US group purchasing organizations are negotiating clamp purchases without bundled calibration services, forcing manufacturers to compete on standalone service pricing. This pattern is most pronounced in California and Texas health systems with dedicated biomedical engineering departments capable of in-house torque verification.
Skull Clamp Market Segmentation
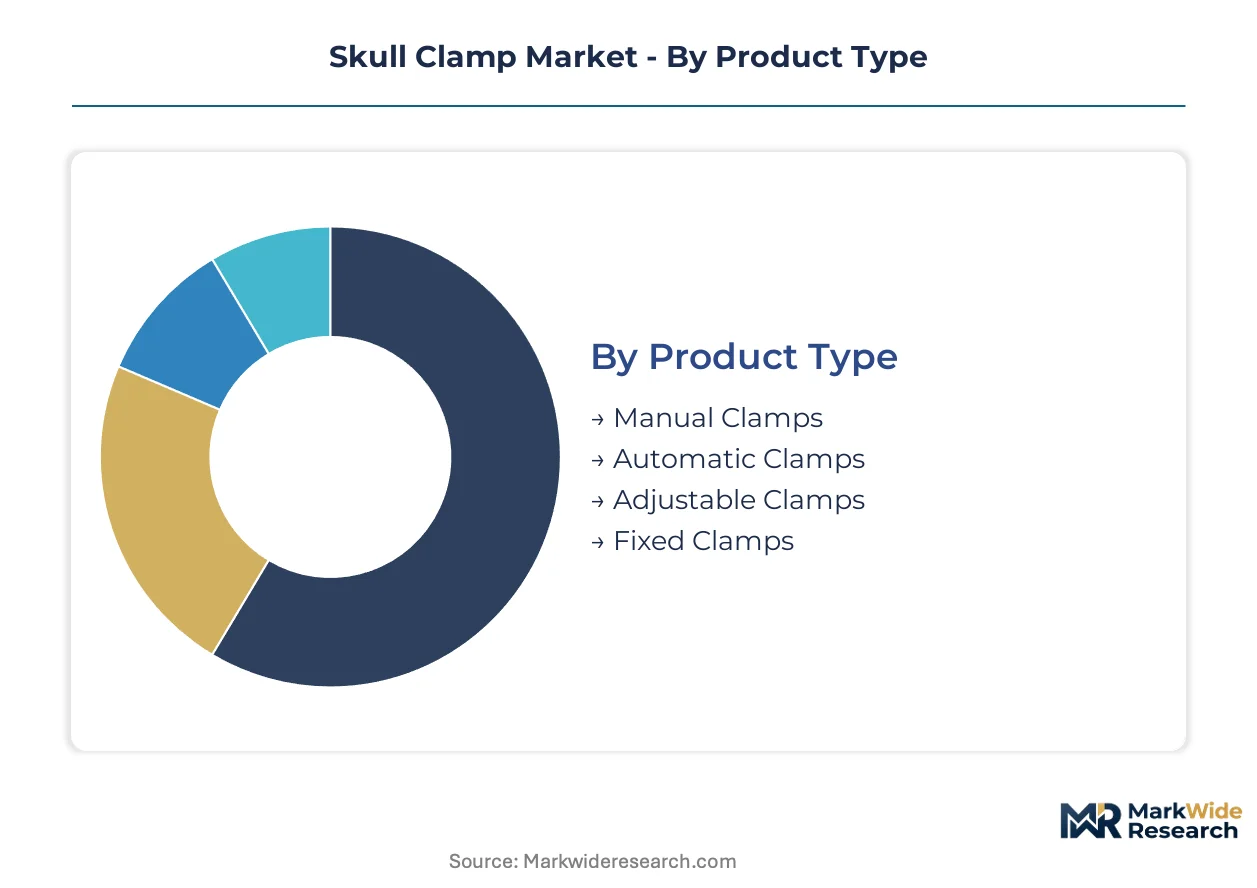
Skull clamp procurement decisions hinge on procedure setting, capital budget cycles, and regulatory compliance burdens. Manufacturers align product portfolios across four structural dimensions to capture volume in academic medical centers, ambulatory facilities, and emergency departments.
Product Type:
The customization-standardization spectrum runs from fully manual systems requiring surgeon-operated torque application to automated units with pre-programmed force limits and digital feedback loops.
- Manual Clamps:Three-pin or four-pin aluminum or stainless steel configurations rely on surgeon-applied torque with mechanical limiting mechanisms. Demand concentrates in cost-constrained hospital systems in the United States and Germany where 15-20 year service lives delay replacement cycles and capital committees prioritize proven reliability over feature expansion.
- Automatic Clamps:Electromechanical systems with standardized torque application and rapid-setup protocols reduce procedural preparation time. Demand is accelerating in United States ambulatory surgical centers and Japanese academic medical centers where METI-backed modernization incentives reward workflow efficiency gains and reduced anesthesia induction delays.
- Adjustable Clamps:Modular frame systems accommodate pediatric through adult cranial dimensions with interchangeable pin arrays.
- Fixed Clamps:Single-configuration devices for high-volume standardized procedures offer lowest capital acquisition cost.
Most installed capacity flows through Manual Clamps. Expansion is steepest in Automatic Clamps.
End User:
Procurement authority and volume scale separate institutional buyers, with procedure migration patterns reshaping channel priorities.
- Hospitals:Tertiary academic medical centers in the United States, Germany, and Japan command the largest procedure volumes for deep-brain stimulation, tumor resection, and complex trauma interventions. These institutions drive replacement cycles and technology upgrades through dedicated neurosurgical departments with standardized cranial fixation protocols.
- Surgical Centers:Ambulatory facilities in Texas and California health systems absorb outpatient spinal and cranial procedures previously confined to inpatient settings. These buyers prioritize rapid-setup automatic configurations and unbundled preventive maintenance contracts to minimize per-procedure labor costs.
- Emergency Rooms:Trauma stabilization protocols standardize around rapid-application clamps for immediate cranial immobilization.
- Orthopedic Clinics:Specialized spinal intervention facilities favor adjustable configurations for cervical and occipital access.
Revenue concentration sits with Hospitals. Volume growth is climbing fastest in Surgical Centers.
Technology:
Force transmission mechanisms differentiate capital intensity and maintenance requirements across the installed base.
- Mechanical:Direct screw-drive and cam-actuated systems dominate current installed bases due to field-serviceability and absence of pneumatic or hydraulic infrastructure requirements. Demand persists in European hospital systems navigating EU MDR transition friction where legacy system recertification delays new technology adoption.
- Hydraulic:Fluid-pressure torque multiplication enables smoother force application for delicate pediatric or geriatric cranial fixation. Demand is emerging in German and French pediatric neurosurgical departments where MDR-compliant technical documentation for safety innovations accelerates tender participation.
- Pneumatic:Compressed-air systems integrate with existing operating room infrastructure in high-volume Japanese surgical suites.
- Safety Innovations:Force-feedback sensors and automatic pressure-release mechanisms address malpractice exposure.
Mechanical systems anchor the installed base. Safety Innovations are gaining share fastest among new procurements.
Application:
Procedure complexity and reimbursement levels determine specification requirements and price tolerance.
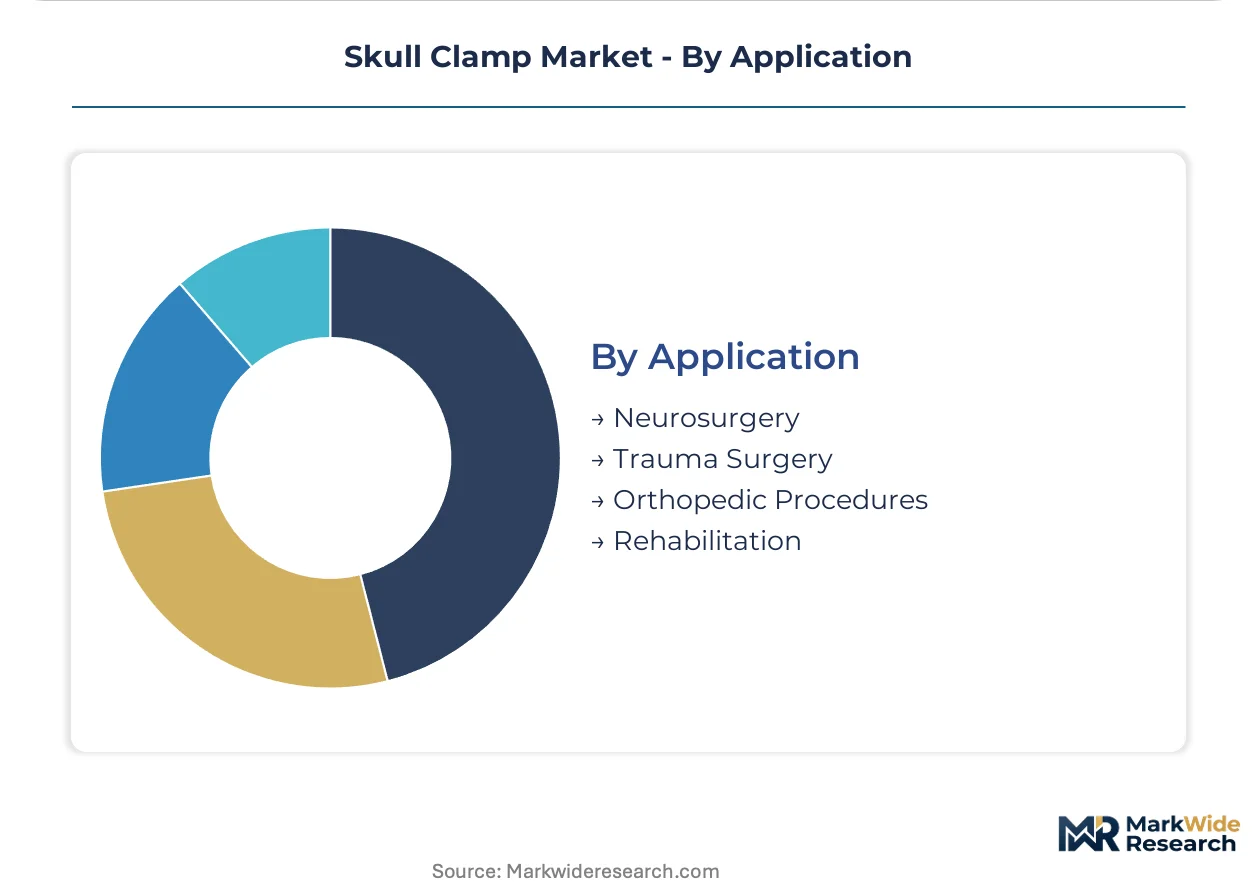
- Neurosurgery:Deep-brain stimulation, tumor resection, and cerebrovascular interventions demand radiolucent carbon-fiber-reinforced or titanium-aluminum hybrid clamps for uninterrupted intraoperative CT and fluoroscopy access. Academic medical centers in Germany and the United States pilot these systems for navigation-integrated workflows.
- Trauma Surgery:Emergency department protocols standardize around rapid-application automatic clamps with standardized torque limits to reduce setup time during critical interventions. United States trauma centers drive volume for these configurations outside traditional operating room procurement channels.
- Orthopedic Procedures:Spinal fusion and cervical fixation utilize adjustable clamps with extended reach frames.
- Rehabilitation:Post-surgical immobilization and positioning applications favor lightweight aluminum manual systems.
Neurosurgery commands premium pricing. Trauma Surgery is expanding most quickly as emergency protocols standardize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neurosurgical talent clusters in academic medical centers anchor skull clamp procurement patterns across major markets. Specialist concentration in tertiary hospitals drives technology upgrade cycles and shapes regulatory compliance investments.
United States
Academic medical centers in Boston and Houston drive replacement demand for radiolucent automatic systems. FDA 510(k) clearance pathways streamline entry for torque-validated devices. The Texas Medical Center cluster absorbs outpatient spinal procedures into ambulatory settings.
Germany
Pediatric neurosurgical departments in Heidelberg and Berlin prioritize hydraulic torque multiplication for delicate cranial fixation. EU MDR notified body audits concentrate on torque-limiting validation data. The Baden-Württemberg medical technology corridor advances carbon-fiber-reinforced clamp adoption.
Japan
Aging neurosurgical patient demographics in Tokyo and Osaka accelerate METI-backed hospital modernization. PMDA clinical evaluation requirements add manufacturing site inspection layers for automatic system entrants. The Kanto region's surgical suites integrate pneumatic systems with existing compressed-air infrastructure.
United Kingdom
NHS procurement consortiums in London and Manchester unbundle preventive maintenance from device acquisition. MHRA post-market surveillance aligns with EU MDR traceability mandates. The Oxford-Cambridge corridor pilots navigation-integrated cranial fixation workflows.
France
Hospital procurement networks in Paris and Lyon require MDR-compliant technical documentation for tender participation. ANSM oversight elevates clinical evaluation standards for legacy product recertification. The Île-de-France region concentrates deep-brain stimulation procedure volume driving premium clamp specifications.
Skull Clamp Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the skull clamp market. Established medical device conglomerates with dedicated neurosurgical divisions anchor premium pricing tiers through specialized portfolios. Mid-tier surgical instrument fabricators compete on capital acquisition cost for cost-constrained hospital systems. Competitive moves concentrate on M&A-driven portfolio expansion and strategic partnerships with surgical navigation platform developers.
Among diversified medical technology conglomerates, Integra LifeSciences Holdings Corporation and Stryker Corporation occupy positions exemplifying premium-tier neurosurgical specialization. Pro Med Instruments GmbH represents the specialized German fabricator archetype with concentrated cranial stabilization expertise. These three entities anchor distinct competitive vectors—portfolio breadth, workflow integration, and specialized engineering—shaping procurement segmentation across academic and ambulatory settings.
| Leading Market Players |
|---|
| Integra LifeSciences Holdings Corporation |
| Becton Dickinson and Company |
| Pro Med Instruments GmbH |
| Micromar Industria e Comercio Ltda |
| Black Forest Medical Group |
| Mizuho Medical Co Ltd |
| Medtronic plc |
| Stryker Corporation |
| TeDan Surgical Innovations |
| Others |
Value Chain & Pricing Dynamics
EU MDR post-market surveillance mandates gate qualified supply access and premium-tier pricing eligibility for skull clamp manufacturers serving European hospital procurement consortiums. Compliance documentation burdens compress margin buffers for mid-tier fabricators while elevating pricing power for incumbents with preemptive clinical evidence packages.
Pricing Analysis
The bundled-vs-unbundled service split separates traditional equipment-procurement relationships from emerging transactional models. Three-tier pricing structure across premium, standard, and economy levels stratifies by torque-validation certification and after-sales calibration bundling. Price differentiation hinges on ISO 13485 quality tier and radiolucent alloy specification grade. Cost compression in economy manual clamps is intensifying because US group purchasing organizations negotiate without bundled preventive maintenance. Ambulatory surgical centers in Texas and California health systems exhibit highest price sensitivity; academic medical centers in Boston and Houston demonstrate lowest sensitivity due to navigation-integration requirements.
Supply Chain Analysis
Japan's METI-backed domestic-content preferences and US Buy American provisions for VA hospital procurement are reshaping sourcing footprints for aluminum alloy and carbon-fiber-reinforced polymer inputs. Manufacturing concentration centers on Germany, the United States, and Japan for medical-grade 316L stainless steel and titanium-aluminum hybrid materials. Component sourcing draws from Italian precision-machining specialists for torque-limiting mechanisms and Swiss sensor fabricators for force-feedback systems. Single-source vulnerability concentrates in carbon-fiber-reinforced polymer resin supply. Distribution runs through specialized surgical instrument distributors with GPO contracting relationships in US health systems and direct hospital sales forces in German and French procurement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EU MDR transition timelines and FDA 510(k) clearance pathways continuously elevate compliance investment thresholds and consolidate procurement authority toward qualified incumbents.
For Market Incumbents: Extend torque-standardization feature roadmaps to capture outpatient migration while absorbing heightened post-market surveillance obligations through dedicated clinical affairs infrastructure. Consolidate position by acquiring specialized German fabricators with concentrated cranial stabilization engineering expertise. Defend against mid-tier surgical instrument competitors by embedding proprietary data interfaces with surgical navigation platform developers.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in automatic clamp configurations creates white-space entry opportunity for torque-limited systems with Japanese Industrial Standards certification. Target METI-backed hospital modernization incentives in the Kanto region where aging neurosurgical demographics accelerate replacement demand. Penetrate through rapid-setup protocol validation for ambulatory surgical center workflows in Texas and California health systems.
For Investors and Strategic Acquirers: Roll-up economics work for specialized cranial stabilization fabricators because EU MDR compliance costs disproportionately burden sub-scale European producers without dedicated regulatory affairs infrastructure. Five-to-ten year viability concentrates on firms with preemptive clinical evidence packages and notified body audit relationships. Target acquisition archetype: German precision-engineering specialists with pediatric neurosurgical department references and MDR-compliant technical documentation. Monitor FDA guidance publication on reusable device reprocessing validation as inflection indicator for aftermarket service revenue multiple expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Notified body audit readiness accelerates tender participation in German and French hospital procurement networks. |
| Torque-Standardization Feature Development | Pre-programmed force limits reduce anesthesia induction delays in US ambulatory surgical centers. |
| Japanese Industrial Standards Certification | JIS compliance unlocks METI-backed modernization incentives in Tokyo and Osaka academic medical centers. |
| Surgical Navigation Platform Integration | Proprietary data interfaces embed incumbents in renovated OR suite procurement specifications. |
| Reprocessing Validation Service Packaging | FDA guidance alignment creates aftermarket revenue streams from compliance documentation offerings. |
Study Parameters
Multiple input streams — primary interviews with neurosurgical department heads and biomedical engineering directors, secondary validation against FDA 510(k) clearance databases and EU MDR notified body audit records, and procurement contract analysis through US group purchasing organization filings — were reconciled through bottom-up and top-down triangulation. Stakeholder consultations encompassed cranial fixation protocol specialists, hospital purchasing committee administrators, GPO contracts managers, and surgical navigation platform engineers. Secondary sources included hospital procurement databases, ISO 13485 certification registries, and METI hospital modernization incentive disclosures.
Data-stream reconciliation anchored volume and value outputs across the analysis window through segmented modeling of product type, end-user institution category, force transmission technology, and application-specific procedure complexity. CAGRs were derived from replacement cycle analysis in academic medical centers and technology upgrade penetration in ambulatory settings. Industry-specific forecast inputs incorporated EU MDR transition timeline assumptions and FDA guidance evolution on reusable device sterilization validation.
Caveats apply where EU MDR notified body capacity constraints or FDA guidance revisions on biocompatibility testing could materially shift the outlook for manufacturer entry timelines and compliance cost burdens. Forecasts reflect assumptions regarding outpatient procedure migration velocity and radiolucent alloy adoption curves in navigation-integrated workflows. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Medical Manifolds Market
Medical Devices
Prefilled Syringe Contract Manufacturing Market
Medical Devices
Medical Fiber Optics Market
Medical Devices
Global Adult and Pediatric Hemoconcentrators Market
Medical Devices
Catheter Securement Devices Market
Medical Devices
Dual Chamber Prefilled Syringes Market
Medical Devices
Global Operating Microscopes Market
Medical Devices
Nerve Ablation Devices Market
Medical Devices
Peritoneal Catheter Systems Market
Medical Devices
Home-Use Water Flosser Market
Medical Devices
Asia-Pacific Electrophysiology Market
Medical Devices
Handheld Red Light Therapy Device Market
Medical Devices
Appendage Management Market
Medical Devices
Medical Tricorder Market
Medical Devices
Global Extremities Market
Medical Devices
Global Stone Retrieval Basket Market