
 Building Inspection Services Market | 2026-2036
Building Inspection Services Market Size, Share, and Industry Trends Forecast 2026-2036
Building Inspection Services Market Analysis
Cross-laminated timber is expanding its share in mid-rise commercial construction, forcing inspection protocols to adapt to moisture-vulnerability testing and connection-point verification. SGS Group leverages its global laboratory network to certify engineered wood products across multiple jurisdictions. Bureau Veritas anchors its position through specialized fire-resistance testing for mass timber assemblies. Intertek Group plc competes by integrating environmental performance verification with structural safety assessments.
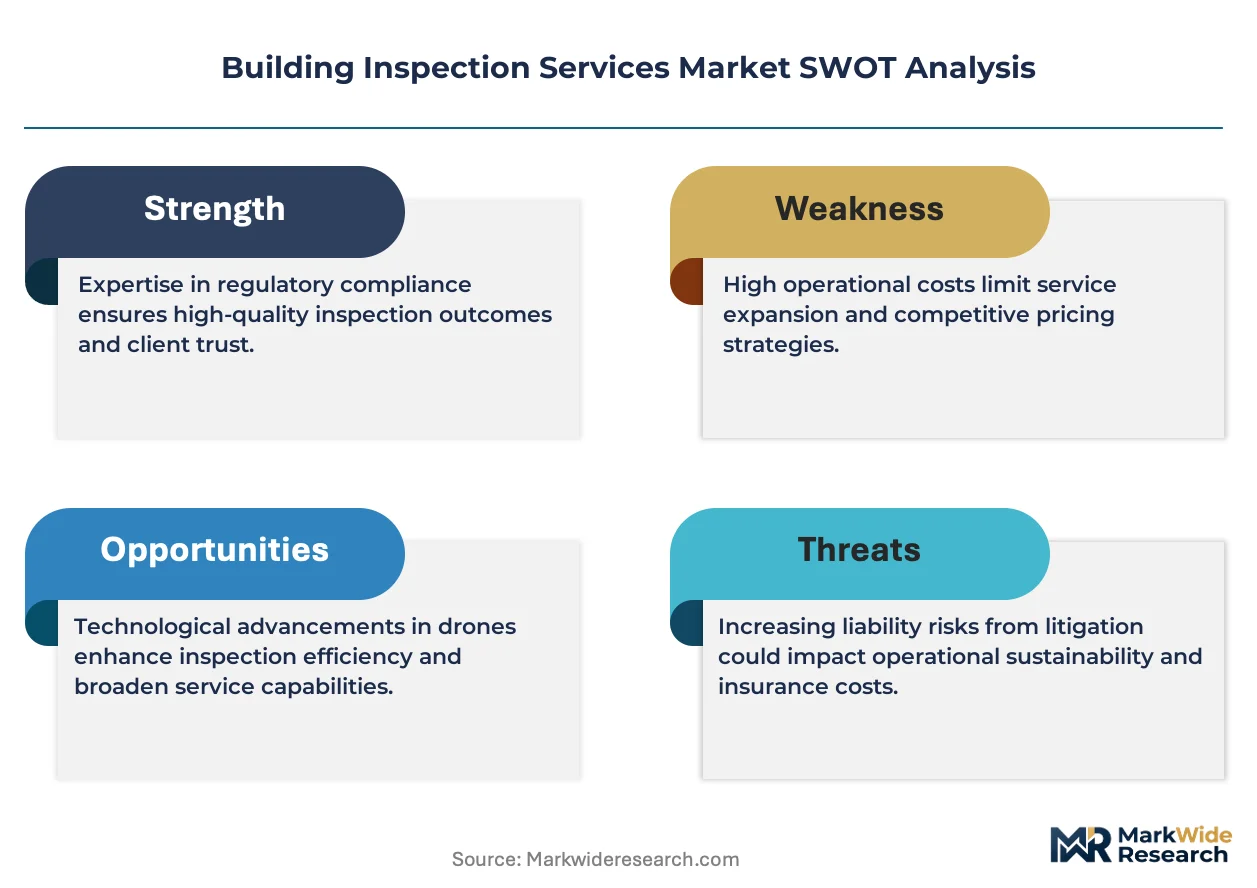
Building inspection services encompass systematic evaluation of structural integrity, mechanical systems, and environmental compliance in residential, commercial, and industrial properties, typically involving visual examination, instrumented testing, and code-reference reporting to inform transaction, maintenance, or regulatory decisions. Thermal imaging and drone-based roof assessments now supplement manual walkthroughs, compressing evaluation timelines while expanding defect-detection scope. Residential inspections occupy the largest service volume given transaction-linked demand, while commercial inspections generate superior margins through recurring facility-management contracts and specialized environmental assessments. Insurance companies represent the fastest-growing client type as carriers tighten underwriting requirements and mandate pre-policy condition documentation.
FEMA building codes, EPA lead-safe renovation standards, and OSHA worker-safety protocols collectively elevate inspection stringency and credential requirements across the United States. The EPA's Renovation, Repair, and Painting Rule mandates certified inspector involvement in pre-1978 housing transactions, directly expanding addressable service demand. Stakeholders must monitor how evolving carbon-disclosure mandates for commercial real estate reshape inspection scope from physical condition to operational performance verification.
Market Dynamics
Drone-based thermal imaging is compressing roof assessment timelines while forcing credential recalibration across inspection labor pools. Insurance underwriters now mandate instrumented documentation as a condition of policy issuance, converting episodic transaction demand into recurring facility-management relationships.
Growth Catalysts
- EPA Renovation, Repair, and Painting Rule:Certified inspector mandates for pre-1978 housing transactions directly expand addressable service demand across residential resale markets.
- Commercial energy disclosure frameworks:Operational performance verification requirements are extending inspection scope from physical condition to carbon-intensity documentation.
- Cross-laminated timber adoption:Moisture-vulnerability testing and connection-point verification protocols create specialized service revenue streams in mid-rise construction.
Market Restraints
- Qualified inspector scarcity:Licensing backlogs and training pipeline gaps constrain service capacity expansion in high-demand metropolitan corridors.
- Equipment capital intensity:Thermal imaging rigs, drone fleets, and software subscriptions elevate fixed-cost structures for independent operators.
- Seasonal demand volatility:Weather-dependent exterior assessments compress revenue recognition into narrow annual windows in northern climates.
Strategic Opportunities
- Recurring facility-management contracts:Property technology platforms are absorbing inspection data into predictive maintenance workflows, creating subscription revenue models.
- Environmental performance verification:Carbon disclosure mandates for commercial real estate are opening adjacent service lines in operational benchmarking.
- Insurance carrier direct contracting:Pre-policy condition documentation requirements enable bypass of traditional broker channels.
Industry Challenges
- Multi-jurisdictional credentialing complexity:State-level licensing reciprocity gaps force redundant certification investments for regional operators.
- Legacy system integration friction:Digital reporting platforms face adoption resistance from established inspectors reliant on paper-based workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Building Inspection Services Market |
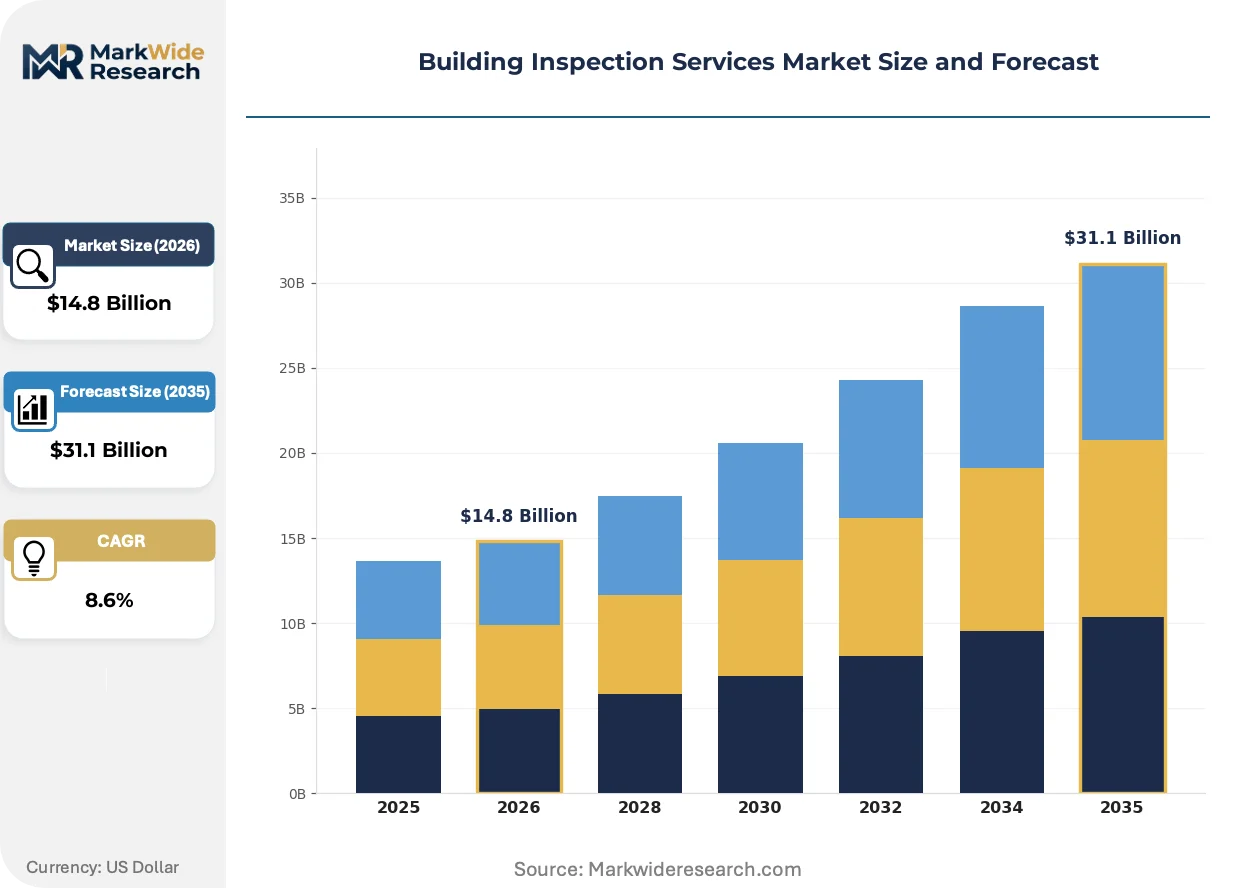
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.1 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Residential Inspections, Commercial Inspections, Industrial Inspections, Pre-Purchase Inspections Client Type: Homeowners, Real Estate Agents, Property Managers, Insurance Companies Inspection Category: Structural Assessments, Electrical Evaluations, Plumbing Inspections, Environmental Assessments Technology Used: Drone Inspections, Thermal Imaging, 3D Scanning, Manual Inspections |
| Companies Covered | HouseMaster, SGS Group, Pillar to Post, Intertek Group plc, Bureau Veritas, WIN Home Inspection, HomeTeam Inspection Service, DEKRA SE, National Property Inspections, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Building Inspection Services Market Emerging Trajectories
Inspection workflows are absorbing automation layers that compress field time while expanding defect-detection scope. Three concurrent developments are restructuring competitive positioning across residential, commercial, and industrial service lines.
Drone-mounted infrared cameras are absorbing manual roof assessment volume in North American markets. Commercial property managers deploy these systems for quarterly thermal envelope monitoring, reducing ladder-based exposure while capturing subsurface moisture intrusion patterns invisible to visual inspection. The technology is absorbing mid-tier inspection jobs previously executed by generalist contractors.
OSHA worker-safety protocols and FEMA building codes are elevating instrumented documentation requirements across the United States. Inspectors must now demonstrate competency in calibrated moisture meters, electrical testers, and structural assessment tools to maintain licensure. Multi-family residential and industrial warehouse segments face the steepest compliance cost adjustments.
Insurance carriers are consolidating vendor relationships around firms delivering standardized digital reporting formats. Underwriting departments reject narrative-only assessments, forcing inspection companies to invest in cloud-based data capture and automated report generation. This behavioral shift concentrates contract awards among technology-capable providers in Florida, Texas, and California coastal zones where climate risk pricing is most advanced.
Building Inspection Services Market Segmentation
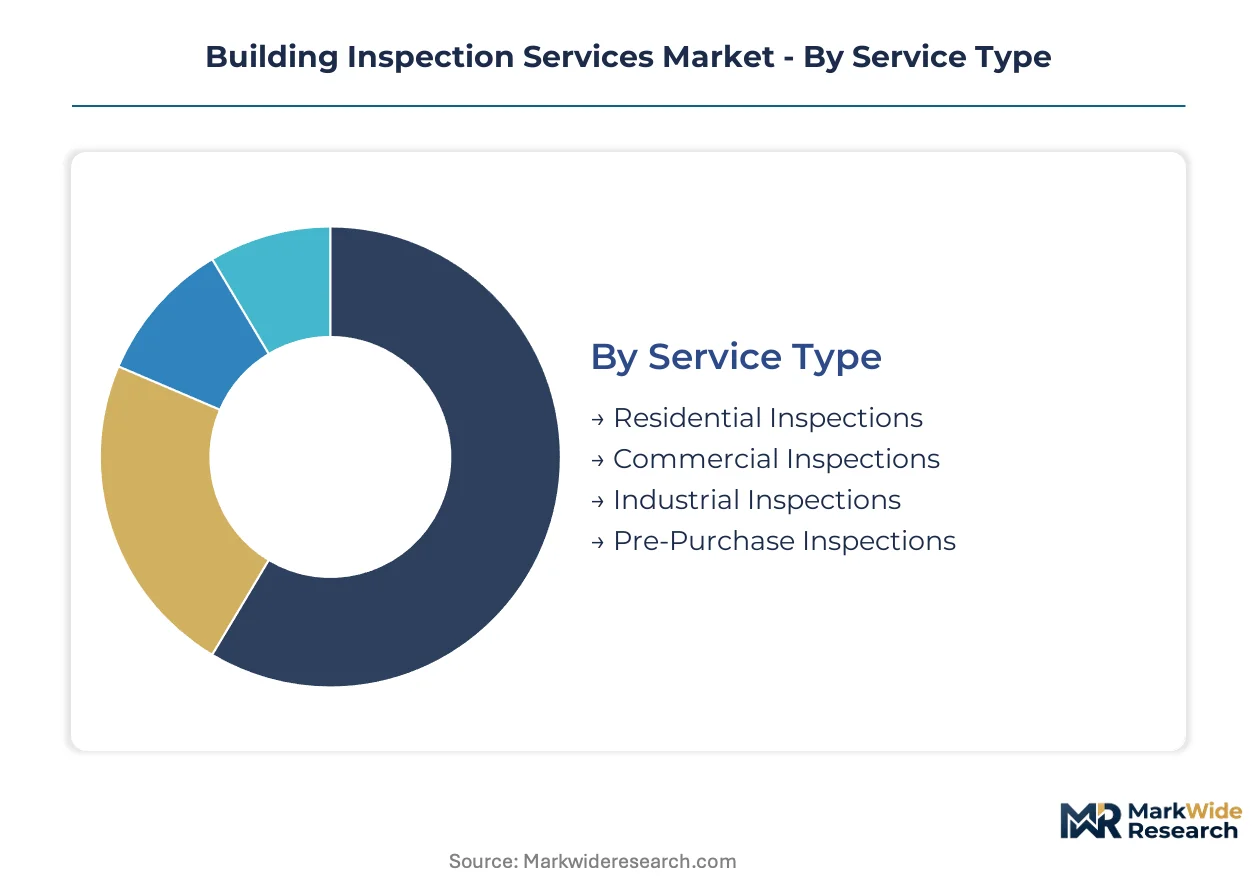
Service differentiation in building inspection markets follows distinct procurement cycles across property transaction, insurance underwriting, and facility management channels. Each segment category commands specialized credentialing requirements and technology deployment profiles that reshape competitive positioning.
Service Type:
Upgrade cycles vary sharply across property classes, with transaction-linked services refreshing faster than industrial compliance mandates.
- Residential Inspections:Visual and instrumented evaluation of single-family and multi-family dwellings for transaction closing and renovation planning. Demand clusters in metropolitan resale corridors where mortgage lenders mandate pre-closing documentation. EPA lead-safe rules for pre-1978 housing sustain recurring inspector involvement.
- Commercial Inspections:Systematic evaluation of office, retail, and hospitality assets for acquisition due diligence and ongoing facility management. Property managers in the United States deploy quarterly thermal envelope monitoring through drone fleets, converting episodic demand into subscription relationships.
- Industrial Inspections:Specialized assessment of manufacturing facilities, warehouses, and process infrastructure for OSHA compliance and insurance underwriting.
- Pre-Purchase Inspections:Transaction-triggered condition documentation serving buyer negotiation leverage and lender risk assessment.
Volume placements concentrate in Residential Inspections; the faster expansion belongs to Commercial Inspections.
Client Type:
Procurement authority is shifting from transaction intermediaries toward risk-bearing institutions with recurring inspection mandates.
- Insurance Companies:Underwriting departments mandate instrumented condition documentation as a condition of policy issuance. Coastal zone carriers in Florida, Texas, and California reject narrative-only assessments, forcing standardized digital reporting adoption.
- Property Managers:Facility operators absorb inspection data into predictive maintenance platforms, creating recurring revenue streams for technology-capable providers.
- Homeowners:Individual buyers commission pre-purchase evaluations and periodic maintenance assessments.
- Real Estate Agents:Listing professionals arrange seller-disclosure inspections to accelerate transaction velocity.
Contract concentration is heaviest with Insurance Companies; Property Managers are climbing the fastest as facility-management platforms expand.
Inspection Category:
Credential specialization deepens as code complexity fragments across structural, mechanical, and environmental domains.
- Structural Assessments:Evaluation of load-bearing elements, foundation integrity, and seismic resilience for code compliance. Cross-laminated timber adoption in mid-rise commercial construction forces moisture-vulnerability testing and connection-point verification protocols.
- Environmental Assessments:Detection of hazardous materials, indoor air quality, and carbon-intensity benchmarking. Commercial energy disclosure frameworks extend inspection scope from physical condition to operational performance verification.
- Electrical Evaluations:Code-reference testing of panel capacity, grounding integrity, and arc-fault protection.
- Plumbing Inspections:Pressure testing, leak detection, and potable water quality assessment.
Service volume clusters in Structural Assessments; Environmental Assessments are gaining share fastest under carbon disclosure mandates.
Technology Used:
Equipment capital intensity is elevating barriers for independent operators while concentrating contract awards among technology-advantaged firms.
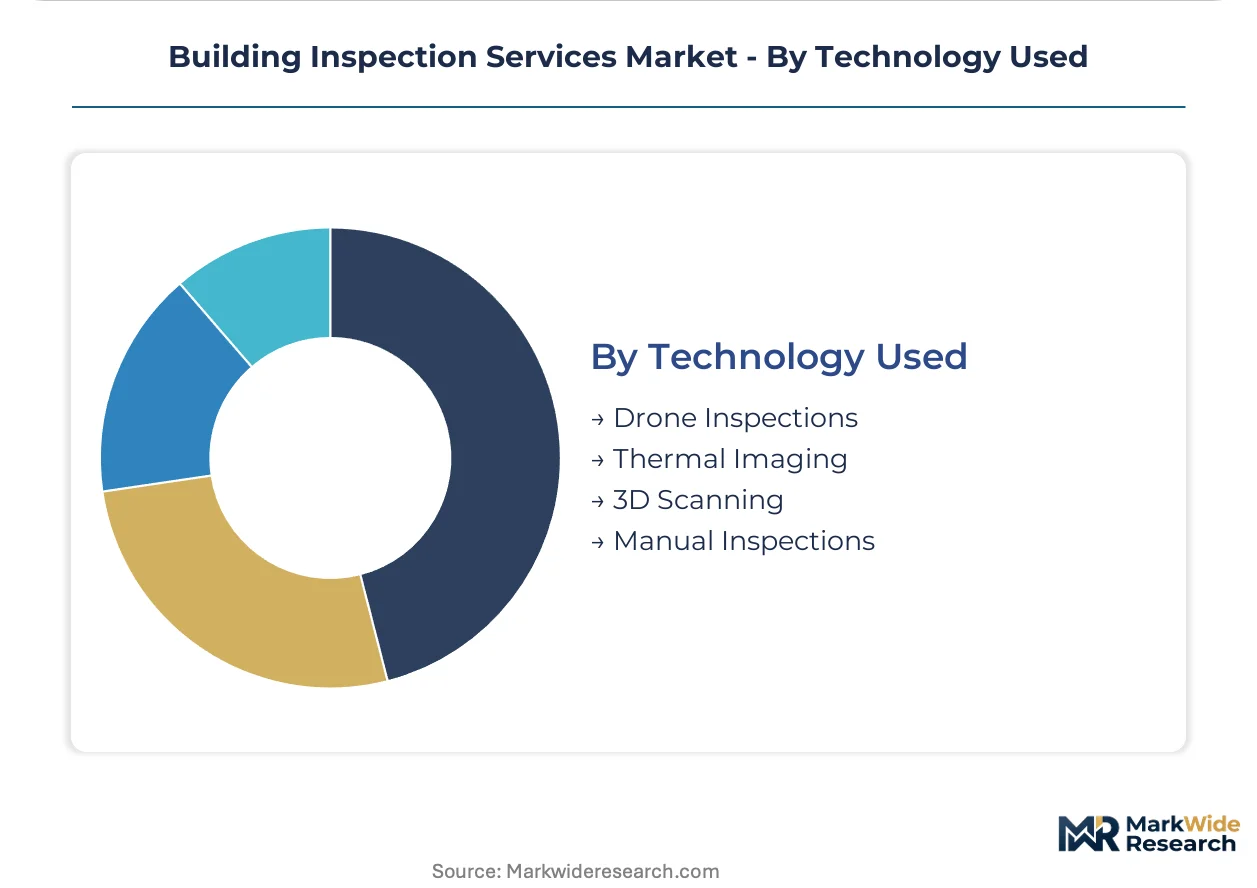
- Drone Inspections:Aerial thermal imaging and photogrammetric documentation for roof and envelope assessment. Commercial property managers deploy these systems quarterly, reducing ladder-based exposure while capturing subsurface moisture intrusion invisible to visual inspection.
- Thermal Imaging:Infrared detection of thermal bridging, moisture intrusion, and electrical hot spots. FEMA building codes and OSHA protocols elevate instrumented documentation requirements across the United States.
- 3D Scanning:LiDAR and photogrammetric capture for as-built documentation and dimensional verification.
- Manual Inspections:Visual walkthrough and handheld instrument assessment by licensed practitioners.
Deployment frequency is highest for Manual Inspections; Drone Inspections show the steepest expansion trajectory as insurance mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States where aging infrastructure and insurance underwriting requirements sustain recurring inspection volumes. Commercial property portfolios are expanding inspection mandates as energy codes tighten across developed economies. Drone-based thermal imaging is displacing manual roof assessments in North America.
United States
FEMA building codes and EPA lead-safe renovation standards elevate inspection stringency across residential and commercial portfolios. The EPA's Renovation, Repair, and Painting Rule mandates certified inspector involvement in pre-1978 housing transactions. Coastal zones in Florida, Texas, and California concentrate insurance carrier vendor consolidation around standardized digital reporting formats.
Germany
Commercial energy disclosure frameworks under the EU Green Deal extend inspection scope from physical condition to carbon-intensity documentation. The Federal Building Energy Act tightens envelope performance requirements for existing stock. Industrial clusters in North Rhine-Westphalia and Bavaria drive demand for specialized environmental assessments in manufacturing facilities.
United Kingdom
Commercial real estate carbon disclosure mandates reshape inspection protocols toward operational performance verification. The Building Safety Regulator enforces stricter structural assessment requirements for high-rise residential buildings. London's financial district property managers deploy quarterly thermal envelope monitoring through drone fleets.
Japan
Seismic resilience regulations and aging housing stock sustain structural assessment demand across metropolitan corridors. METI building energy standards mandate periodic efficiency audits for commercial properties over 2,000 square meters. The Kanto region around Tokyo concentrates certified inspector licensing and technology adoption.
Australia
Climate risk pricing in property insurance accelerates instrumented documentation requirements for coastal and bushfire-prone assets. The National Construction Code updates elevate fire-resistance testing protocols for mid-rise timber construction. New South Wales and Victoria metropolitan markets absorb drone-based roof assessment technology fastest.
Building Inspection Services Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with transaction-linked residential services fragmenting among regional operators while commercial and industrial consolidation favors multi-jurisdictional certification bodies. The vendor base organizes into three archetypes: global testing and inspection firms with laboratory networks, national franchise networks serving residential transaction demand, and specialized environmental consultancies. Competitive moves concentrate on technology licensing for drone and thermal imaging capabilities and strategic partnerships with property technology platforms.
Within the global certification tier, SGS Group, Bureau Veritas, and Intertek Group plc occupy positions anchored by multi-jurisdictional laboratory accreditation and specialized fire-resistance testing protocols. These firms exemplify the scale-driven archetype competing through integrated environmental performance verification alongside structural safety assessments. National residential franchise networks represent a contrasting archetype, with HouseMaster and Pillar to Post serving transaction-linked demand through branded inspector training and standardized reporting formats.
| Leading Market Players |
|---|
| HouseMaster |
| SGS Group |
| Pillar to Post |
| Intertek Group plc |
| Bureau Veritas |
| WIN Home Inspection |
| HomeTeam Inspection Service |
| DEKRA SE |
| National Property Inspections |
| Others |
Supply Flow & Price Mechanics
Certified inspector concentration in the United States Sun Belt and German industrial corridors creates labor-cost differentials that widen pricing-tier spreads between premium multi-jurisdictional certification bodies and regional independent operators. Equipment capital intensity for thermal imaging rigs and drone fleets compounds this stratification, forcing independent practitioners toward economy-tier positioning while technology-advantaged firms capture standard and premium contract tiers.
Pricing Analysis
Volume concentrates in transaction-linked residential inspections with compressed margins, while commercial facility-management contracts and insurance-mandated documentation generate superior pricing power. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification depth, technology deployment, and reporting format sophistication. Cost compression in the economy tier intensifies because independent operators face equipment subscription burdens without scale economies. Home buyers and small landlords exhibit highest price sensitivity; insurance underwriters and commercial property managers demonstrate lowest sensitivity due to regulatory mandate pass-through.
Supply Chain Analysis
Drone hardware supply rests on Chinese component manufacturers, Israeli sensor developers, and Taiwanese semiconductor fabricators for thermal imaging chipsets. Thermal cameras, LiDAR modules, and flight control systems constitute critical input dependencies. Single-source vulnerability concentrates in advanced infrared sensor arrays where Israeli and German specialty producers dominate. Distribution runs through direct manufacturer relationships for national inspection chains and regional equipment distributors for independent operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Drone-based thermal imaging is displacing manual roof assessments, compressing field timelines while elevating credential requirements. This technology-transition phase rewards early equipment adopters and penalizes paper-based workflow incumbents.
For Market Incumbents: Extend certification coverage across multiple state jurisdictions to capture insurance carrier vendor consolidation mandates. Deepen vertical integration into proprietary software platforms that absorb inspection data into predictive maintenance workflows, defending against pure-technology entrants. For New Entrants and Emerging Players: Mid-sized commercial property managers in secondary US metropolitan corridors represent an underserved buyer archetype with unmet demand for subscription-based thermal envelope monitoring. White-space exists in environmental performance verification adjacent to core structural assessments, particularly carbon-intensity benchmarking for commercial real estate disclosure mandates. Go-to-market through property technology platform partnerships accelerates customer acquisition without broker channel dependency. For Investors and Strategic Acquirers: The window for entry favors technology-capable regional operators with established insurance carrier relationships and drone fleet deployment. Long-term viability hinges on recurring revenue model conversion rather than transaction-linked volume exposure. Watch for EPA enforcement intensity around lead-safe renovation standards as inflection indicator for residential inspection demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Drone Fleet Expansion | Insurance underwriters in Florida and California now mandate instrumented roof documentation, displacing ladder-based assessments. |
| Software Platform Integration | Property technology platforms absorb inspection data into predictive maintenance workflows, creating subscription revenue lock-in. |
| Multi-Jurisdictional Certification Investment | State-level licensing reciprocity gaps force redundant investments that concentrate contract awards among scaled providers. |
| Environmental Performance Verification Service Launch | Commercial energy disclosure frameworks under EPA and EU Green Deal extend inspection scope to carbon-intensity benchmarking. |
| Insurance Carrier Direct Contracting | Pre-policy condition documentation requirements enable bypass of traditional broker channels and capture recurring facility mandates. |
Methodological Framework
Independent corroboration across certified inspector licensing boards, insurance underwriting departments, and property technology platform operators underwrites the qualitative findings. Primary interviews engaged commercial property managers, insurance risk engineers, drone equipment manufacturers, and multi-family housing developers. Secondary validation drew from EPA enforcement databases, FEMA building code amendments, state-level professional licensing records, and SEC filings of listed inspection service providers. Bottom-up service volume estimates triangulate against top-down construction spending and insurance premium data.
Comparable-period anchoring to historical inspection transaction volumes and equipment deployment rates structured the forecast window. Segmentation modeling spans service type, client archetype, inspection category, and technology deployment intensity. CAGRs derive from regression analysis against construction permitting trends, insurance policy issuance patterns, and regulatory mandate expansion timelines. Cross-laminated timber adoption curves and carbon disclosure mandate phase-in schedules constitute industry-specific forecast inputs.
Revisions become necessary when EPA enforcement intensity shifts, insurance carrier vendor consolidation accelerates, or drone equipment supply disruptions materialize. Forecasts reflect documented assumptions regarding regulatory mandate expansion and technology adoption elasticity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialized Building Services
Global Automated Industrial Door Market
Specialized Building Services
Horizontal Directional Drilling Market
Specialized Building Services
US and Europe Cleanrooms Market
Specialized Building Services
Portable Toilet Market
Specialized Building Services
Clean Room Pass Box Market
Specialized Building Services
Automatic Industrial Doors Market
Specialized Building Services
Portable Toilet Rental Market
Specialized Building Services
Portable Ramps Market
Specialized Building Services
Europe Stair Lift Market
Specialized Building Services
Construction Drone Market
Specialized Building Services
Street Furniture Market
Specialized Building Services
Private Bunker Market
Specialized Building Services
Global Prefabricated Bathroom Pods Market
Specialized Building Services
Industrial Access Platform Market