
 Door Frame Metal Market | 2026-2036
Door Frame Metal Market Size, Share, and Industry Trends Forecast 2026-2036
Door Frame Metal Market Analytics
NFPA 80 fire door standards is hardening certification requirements for hollow metal frame assemblies, compelling manufacturers to retool welding and finishing lines. ASSA ABLOY leverages its captive testing infrastructure to fast-track compliance across multiple jurisdictions. Allegion anchors its position through vertical control over galvanizing and coating operations. Ceco Door specializes in knock-down frame kits that reduce freight costs for remote commercial projects.
Door frame metal denotes structural perimeter assemblies fabricated from cold-formed steel, stainless steel, or aluminum extrusions, typically gauged between 16 and 20 gauge and reinforced with integrated anchors for masonry or drywall attachment. These systems provide fire containment, forced-entry resistance, and acoustic isolation in commercial and institutional envelopes. Hollow metal doors and frame components dominate current volume, while security frames capture the widest margin pools due to ballistic and blast-rated specifications. Aluminum material grades are gaining specification share in coastal commercial buildings where corrosion resistance outweighs first-cost premiums.
NFPA, UL, and ASTM standards govern fire rating, structural loading, and hardware reinforcement preparation across the United States market. The EU Construction Products Regulation and CE marking requirements enforce declared performance metrics for metal frame systems sold in European member states. Stakeholders must monitor evolving embodied carbon disclosure rules and their cascading impact on galvanized versus coated steel sourcing decisions.
Market Dynamics
The EU Green Deal's embodied carbon disclosure mandates are forcing steel door frame suppliers to requalify galvanizing and coating chemistries across their supply bases.
Growth Catalysts
- NFPA 80 fire-rating upgrades:Tighter welding certification standards in the United States are locking out non-compliant imports and consolidating specification authority among certified domestic fabricators.
- Germany's industrial corridor expansion:Automotive and logistics facility construction in Baden-Württemberg and Bavaria is pulling premium security-rated hollow metal frames into specification.
- Aluminum extrusion advances:Corrosion-resistant 6061-T6 grade frames are capturing share in coastal commercial buildings where salt exposure degrades galvanized steel.
Market Restraints
- Zinc price volatility:Hot-dip galvanizing cost swings compress margin predictability for mid-tier frame fabricators dependent on spot zinc purchases.
- Chinese steel overcapacity:Dumping investigations in North American and European markets create tariff uncertainty for imported cold-formed steel channels.
- Composite door frame substitution:Fiberglass-reinforced polymer systems are displacing metal in low-rise commercial applications where fire rating is not mandated.
Strategic Opportunities
- India's PLI scheme for construction materials:Domestic manufacturing incentives are opening greenfield capacity for cold-formed steel frame production serving South Asian commercial real estate.
- CE marking automation:Digital product passport requirements under the EU Construction Products Regulation create first-mover advantage for frame suppliers with integrated testing data infrastructure.
- Prefabricated wall panel integration:Offsite construction contractors are specifying knock-down frame kits that ship flat and assemble at modular fabrication facilities.
Industry Challenges
- Welding technician scarcity:NFPA 80-compliant continuous weld certification programs face enrollment shortfalls in North American technical colleges.
- Embodied carbon audit complexity:Scope 3 emissions tracing for galvanized steel requires supplier disclosure that many upstream mills cannot yet provide.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Door Frame Metal Market |
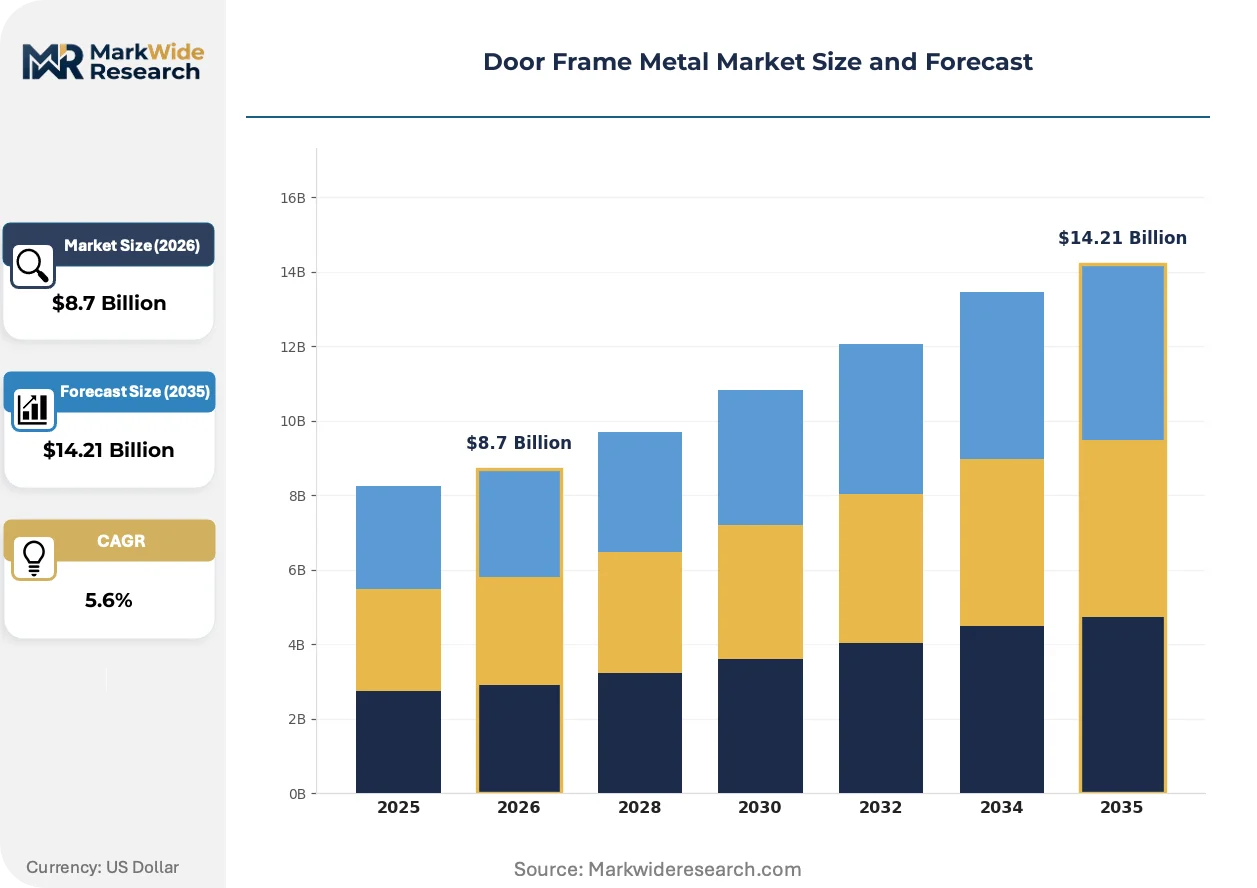
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hollow Metal Doors, Frame Components, Modular Frames, Security Frames Application: Commercial Buildings, Residential Properties, Industrial Sites, Institutional Facilities Material: Stainless Steel, Galvanized Steel, Aluminum, Coated Steel Installation Type: Pre-hung, Knocked Down, Retrofit, Custom Installations |
| Companies Covered | ASSA ABLOY, Allegion, Ceco Door, Steelcraft, Deansteel Manufacturing, Mesker Openings Group, JELD-WEN, Hormann Group, TRUDOOR, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Door Frame Metal Market Evolving Landscape
Digital specification tools and material traceability platforms are compressing the traditional architect-fabricator-contractor communication chain in commercial envelope procurement.
Light-gauge cold-formed steel framing software is modularizing hollow metal door frame design, allowing architects to parametrically adjust gauge, anchor placement, and hardware prep in BIM workflows. Large commercial contractors in Texas and Florida are adopting these platforms for multi-site retail rollouts. The technology is modularizing what was previously custom engineering into repeatable, code-compliant assemblies that reduce RFIs and field modifications.
The EU Green Deal's carbon border adjustment mechanism is reshaping sourcing decisions for galvanized steel inputs entering European member states. Declared performance metrics under the Construction Products Regulation now require Environmental Product Declarations for structural metalwork. German and Dutch frame fabricators are responding by shifting from Turkish and Ukrainian steel toward Scandinavian electric-arc-furnace suppliers with verified low-carbon credentials.
Specification authority is migrating from general contractors to owner-side facilities managers who demand lifecycle cost documentation. Healthcare and education end-users in the United States now require 20-year corrosion warranties and predictive maintenance protocols as standard bid elements. This shift is most pronounced in California and New York, where public procurement rules favor total-cost-of-ownership evaluation over first-cost bidding.
Door Frame Metal Market Segmentation
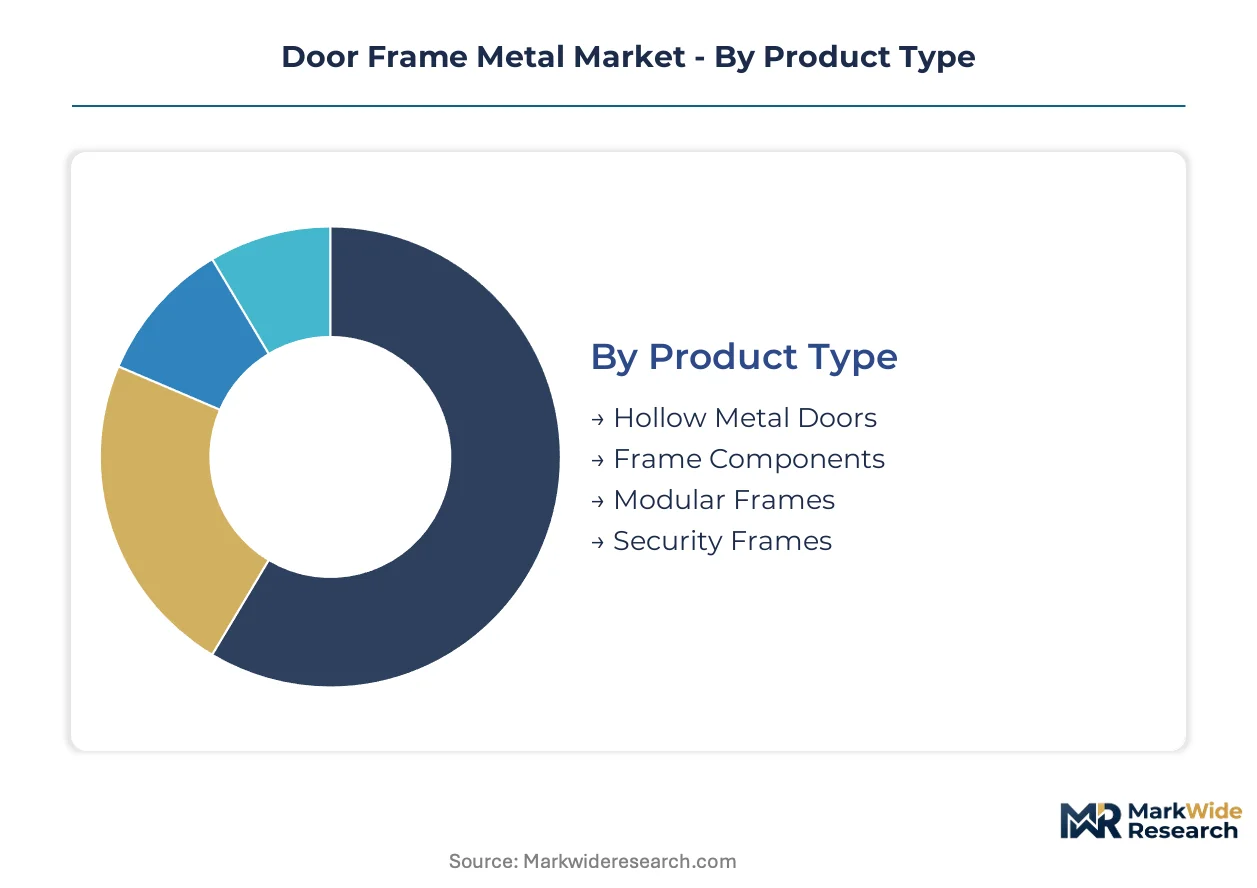
Door frame metal procurement splits sharply across fire-rating requirements, corrosion exposure, and installation logistics. Specification authority migrates toward facilities managers who weight lifecycle cost over first-cost, fragmenting traditional contractor-driven purchasing patterns.
Product Type:
Upgrade cycles for fire-rated commercial envelopes drive replacement demand, with NFPA 80 recertification forcing systematic refresh of aging hollow metal installations.
- Hollow Metal Doors:Cold-formed steel assemblies rated between 20 and 90 minutes fire resistance dominate volume in North American commercial retrofits. Healthcare and education facilities in California and New York now require 20-year corrosion warranties as standard bid elements, compressing specification authority toward certified domestic fabricators.
- Security Frames:Ballistic and blast-rated specifications capture the widest margin pools, with Baden-Württemberg automotive plants and Bavaria logistics hubs pulling premium German production. These systems integrate multi-point locking hardware prep and forced-entry reinforcement that standard hollow metal cannot accommodate.
- Frame Components:Jamb and header subassemblies ship separately for field welding in masonry openings.
- Modular Frames:Knock-down kits reduce freight costs for remote commercial projects and offsite construction integration.
Volume placements concentrate in hollow metal doors; the faster expansion belongs to security frames.
Application:
Cost tier differentiation separates specification protocols across owner types, with public procurement rules favoring total-cost-of-ownership evaluation.
- Commercial Buildings:Retail rollouts and office towers in Texas and Florida drive parametric BIM specification of gauge-adjustable frame systems. Multi-site contractors adopt light-gauge cold-formed steel software to modularize what was previously custom engineering into repeatable, code-compliant assemblies.
- Industrial Sites:Automotive and logistics construction in Germany's industrial corridor specifies corrosion-resistant 6061-T6 aluminum where salt exposure degrades galvanized steel. These facilities demand predictive maintenance protocols and embodied carbon disclosure under EU Green Deal mandates.
- Institutional Facilities:Hospitals and universities require continuous weld certification and hardware reinforcement prep that exceeds standard commercial specification.
- Residential Properties:Low-rise multifamily construction accepts composite frame substitution where fire rating is not mandated.
Commercial buildings absorb the highest absolute volume; institutional facilities are climbing the fastest as healthcare construction accelerates.
Material:
Supply concentration around electric-arc-furnace producers is reshaping sourcing decisions for galvanized and coated steel inputs.
- Galvanized Steel:Hot-dip zinc coating remains the default for interior commercial frames, though zinc price volatility compresses margin predictability for mid-tier fabricators dependent on spot purchases. Turkish and Ukrainian supply is losing share to Scandinavian low-carbon mills under EU carbon border adjustment mechanisms.
- Aluminum:6061-T6 extrusions gain specification in coastal commercial buildings where corrosion resistance outweighs first-cost premiums. Florida and Gulf Coast contractors specify these grades for exterior envelope longevity.
- Stainless Steel:304 and 316 grades serve pharmaceutical and food processing facilities requiring washdown compatibility.
- Coated Steel:Powder-coat and epoxy finishes offer intermediate corrosion protection at lower cost than full stainless specification.
Galvanized steel retains the largest installed base; aluminum is gaining share fastest in coastal geographies.
Installation Type:
Customer type fragmentation separates general contractor procurement from owner-direct specification, with facilities managers increasingly demanding lifecycle documentation.
- Knocked Down:Flat-shipped frame kits assemble at modular fabrication facilities, serving offsite construction contractors in Texas and Florida multi-site retail programs. Ceco Door and similar specialists optimize packaging density for remote commercial projects where freight costs otherwise erode margin.
- Pre-hung:Factory-assembled door and frame units reduce field labor for standard commercial openings, though limited to sizes that survive transportation without damage.
- Retrofit:Existing opening modification demands custom anchoring solutions and finish matching that pre-hung systems cannot address.
- Custom Installations:Oversized or non-rectangular openings require site-measured fabrication with extended lead times.
Knocked down shipments dominate remote project economics; pre-hung retains share in urban core construction with skilled labor constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones in the UAE and Saudi Arabia's giga-project corridors concentrate procurement for premium security-rated metal frames serving Gulf commercial construction.
United States
Texas and Florida multi-site retail rollouts drive parametric BIM specification of gauge-adjustable hollow metal systems. NFPA 80 fire-rating upgrades tighten welding certification standards, locking out non-compliant imports. Houston and Miami contractors adopt light-gauge cold-formed steel software to modularize frame engineering for repeatable commercial assemblies.
Germany
Automotive and logistics facility construction in Baden-Württemberg and Bavaria pulls premium security-rated hollow metal frames into specification. EU Green Deal embodied carbon disclosure mandates force requalification of galvanizing and coating chemistries across supply bases. Stuttgart and Munich industrial corridors specify corrosion-resistant aluminum grades where salt exposure degrades galvanized steel.
China
Coastal commercial building expansion in Shanghai and Guangzhou specifies aluminum extrusion frames for corrosion resistance in salt-air environments. GB standards and MIIT regulations govern structural metalwork performance in commercial envelopes. Yangtze River Delta fabricators face carbon border adjustment pressure on galvanized steel exports to European markets.
India
PLI scheme incentives for construction materials open greenfield cold-formed steel frame capacity serving South Asian commercial real estate. BIS certification requirements enforce declared performance metrics for structural metalwork. Maharashtra and Gujarat industrial zones concentrate new fabrication facilities targeting institutional healthcare and education construction.
United Arab Emirates
Giga-project construction in Dubai and Abu Dhabi specifies ballistic and blast-rated security frames for premium commercial and hospitality envelopes. UAE national building codes align with NFPA fire-rating standards for imported hollow metal assemblies. Dubai South Free Zone concentrates procurement for modular knock-down frame kits serving remote desert construction logistics.
Door Frame Metal Market Competitive Landscape
North American producers anchor one tier; European specialists hold certification advantages under CE marking and EU Green Deal protocols. The vendor base splits between consolidated multi-line building product groups and mid-tier fabricators concentrated in regional industrial clusters. Three archetypes dominate: vertically integrated hardware-frame combinations, galvanizing-coating captive operators, and knock-down kit specialists optimized for freight efficiency. Competitive moves center on M&A for testing infrastructure and geographic expansion into Indian PLI-subsidized manufacturing zones.
Among premium-tier fabricators, ASSA ABLOY exemplifies the integrated hardware-frame archetype through captive testing infrastructure spanning multiple jurisdictions. Allegion occupies a position within the coating-captive tier, with geographic anchoring in North American industrial corridors. Ceco Door represents the knock-down specialization vector, with positioning optimized for remote project freight economics and offsite construction integration.
| Leading Market Players |
|---|
| ASSA ABLOY |
| Allegion |
| Ceco Door |
| Steelcraft |
| Deansteel Manufacturing |
| Mesker Openings Group |
| JELD-WEN |
| Hormann Group |
| TRUDOOR |
| Others |
Value Network & Pricing Analysis
Parametric BIM specification tools are compressing hollow metal frame engineering into repeatable assemblies while simultaneously concentrating procurement power among multi-site contractors capable of standardizing gauge and anchor configurations across distributed retail rollouts. This technology transition rewards fabricators with integrated testing infrastructure and penalizes spot-market zinc purchasers facing margin unpredictability.
Pricing Analysis
Lead-time premiums for NFPA 80-certified continuous weld frames command substantial markups over spot inventory, with expedited certification timelines from captive testing facilities like those operated by ASSA ABLOY justifying price stratification. Three-tier pricing structure across premium certified, standard commercial, and economy knock-down levels separates specification authority, with healthcare and education facilities in California and New York demonstrating lowest price sensitivity due to total-cost-of-ownership procurement mandates. Cost compression in mid-tier galvanized steel frames is intensifying because zinc price volatility erodes predictability for fabricators without long-term offtake agreements. Small commercial contractors in Texas and Florida retail construction exhibit highest price sensitivity, driving adoption of flat-shipped knock-down kits that reduce freight absorption.
Supply Chain Analysis
Dual-sourcing requirements for galvanized steel inputs are now standard among German and Dutch frame fabricators responding to EU Green Deal embodied carbon disclosure mandates, with buyers mandating parallel qualification of Scandinavian electric-arc-furnace suppliers alongside traditional Turkish and Ukrainian mills. Raw material dependencies center on cold-formed steel channels, hot-dip zinc coating chemistries, and 6061-T6 aluminum extrusions for coastal specifications. Supply chain risk concentrates in tariff exposure on Chinese steel overcapacity subject to dumping investigations across North American markets. Distribution runs through regional stocking distributors serving general contractors, with direct specification from owner-side facilities managers gaining share in institutional healthcare and education construction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The door frame metal market functions as a cost-of-compliance story where NFPA 80 fire-rating certification creates a formidable barrier-to-entry moat, locking out non-compliant imports and consolidating specification authority among domestic fabricators with continuous weld infrastructure.
For Market Incumbents: To counter Chinese steel dumping and tariff uncertainty, prioritize backward integration into captive galvanizing operations and expand testing infrastructure across multiple jurisdictions to fast-track compliance recertification. Secure long-term offtake agreements with Scandinavian electric-arc-furnace suppliers to lock in low-carbon steel credentials ahead of EU carbon border adjustment mechanism enforcement. For New Entrants and Emerging Players: Launch via knock-down frame kit distribution targeting remote commercial projects and offsite construction contractors in Texas and Florida where freight economics favor flat-shipped assemblies. India's PLI-subsidized manufacturing zones offer the most penetrable geography for greenfield cold-formed steel capacity serving South Asian institutional construction. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of mid-tier fabricators with regional certification authority but lacking integrated testing infrastructure. Long-term viability hinges on compliance moat sustainability under evolving NFPA and EU Green Deal protocols. Monitor enrollment shortfalls in NFPA 80-compliant welding technician programs as inflection indicator for supply-side capacity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Infrastructure Expansion | Captive testing facilities enable fast-track NFPA 80 compliance across multiple state jurisdictions. |
| Low-Carbon Steel Sourcing Transition | Scandinavian electric-arc-furnace supply secures EU Green Deal credentialing for German fabricators. |
| Knock-Down Kit Optimization | Flat-shipped frame assemblies reduce freight costs for remote commercial projects in Texas and Florida. |
| Parametric BIM Software Integration | Light-gauge cold-formed steel platforms modularize custom engineering into repeatable code-compliant assemblies. |
| Welding Technician Pipeline Investment | Technical college certification programs address enrollment shortfalls threatening NFPA 80 compliance capacity. |
Research Methodology
Independent corroboration across primary interviews with hollow metal fabricators, facilities managers at healthcare and education institutions, and distributors serving Texas and Florida construction markets underwrites the qualitative findings. Secondary validation drew from NFPA certification records, UL testing databases, SEC filings of publicly traded building product groups, and EU Construction Products Regulation disclosure filings. Bottom-up demand modeling triangulated against top-down supply capacity assessments across galvanized steel and aluminum extrusion value chains.
Comparable-period anchoring tied projection assumptions to historical reference periods spanning NFPA 80 regulatory tightening cycles and zinc price volatility episodes. The analytical framework segmented volume and value across fire-rating tiers, material grades, installation types, and regional regulatory clusters. CAGRs were derived from regression analysis of specification intensity against commercial construction permit flows and healthcare facility capital expenditure patterns. Industry-specific forecast inputs included welding technician certification pipeline data and embodied carbon disclosure compliance timelines under EU Green Deal protocols.
Regulatory enforcement delays, zinc supply disruption, and composite frame substitution acceleration are the dominant revision risks to modeled outcomes. Deviation in NFPA 80 certification stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Recycled Concrete Aggregates Market
Building Materials
HDG Steel Pipe Market
Building Materials
Concrete Reinforcing Fiber Market
Building Materials
Cladding Market
Building Materials
Exterior Doors Market
Building Materials
US Facade Market
Building Materials
Dry Mix Mortar Market
Building Materials
Cement Tiles Market
Building Materials
Dutch Brick Market
Building Materials
Global Metal Cladding Market
Building Materials
Asia-Pacific Aluminum Door and Window Market
Building Materials
Commonwealth of Independent States (CIS) Building and Construction Sheets Market
Building Materials
Bio-Based Structural Wood Adhesives for Modular Construction Market
Building Materials
LAMEA Engineered Stone Market
Building Materials
Qatar Cement Market
Building Materials
Global Facade Market