
 Turkey Construction Equipment Market | 2026-2036
Turkey Construction Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Turkey Construction Equipment Market Insights
Aftermarket service revenue is reconfiguring profit pools away from pure equipment sales across the Turkey construction equipment sector. Caterpillar leverages its dealer network density to capture recurring maintenance contracts in Anatolian mining zones. Komatsu sustains competitive positioning through telemetry-integrated fleet management systems deployed with Turkish contractors. Hidromek anchors local manufacturing scale, producing excavators and loaders at its Konya facility for domestic and regional export markets.
Construction equipment encompasses mobile heavy machinery engineered for earthmoving, material handling, and site preparation, typically powered by diesel engines rated between 75 and 500 horsepower and built with high-tensile steel booms and reinforced undercarriages for abrasive terrain. Its primary purpose is to substitute manual labor with mechanized force multiplication across civil engineering and extractive operations. Hydraulic technology dominates installed fleets due to proven torque density and field-serviceability in Turkey's remote project sites, while electric drivetrains represent the fastest-growing technology segment as municipal contractors face tightening urban emissions protocols. Excavators command the largest product type share, driven by tunneling and foundation work for Istanbul's transit expansion, whereas rental companies emerge as the most dynamic customer type as small and mid-sized contractors shift capital from ownership to operational leasing.
Turkey's Ministry of Transport and Infrastructure mandates CE-equivalent conformity for imported machinery, while the Turkish Standards Institution enforces vibration and noise limits under harmonized EU machinery directives. These frameworks elevate compliance costs for non-European OEMs but create procurement preference for certified suppliers. The central bank's monetary policy and lira volatility directly shape equipment financing terms, influencing contractor purchase cycles. Stakeholders must monitor infrastructure tender pipelines and currency hedging instruments to align fleet investment with project award timelines.
Market Dynamics
The Turkish construction equipment sector faces a structural pivot as municipal emissions protocols force fleet electrification timelines against contractor financing constraints shaped by central bank monetary policy. Equipment procurement decisions now hinge on compliance cost amortization across project tenors rather than pure acquisition economics.
Growth Catalysts
- Istanbul Megaproject Pipeline:The Ministry of Transport and Infrastructure's transit expansion programs generate sustained excavator and tunnel boring machine demand across the Marmara corridor.
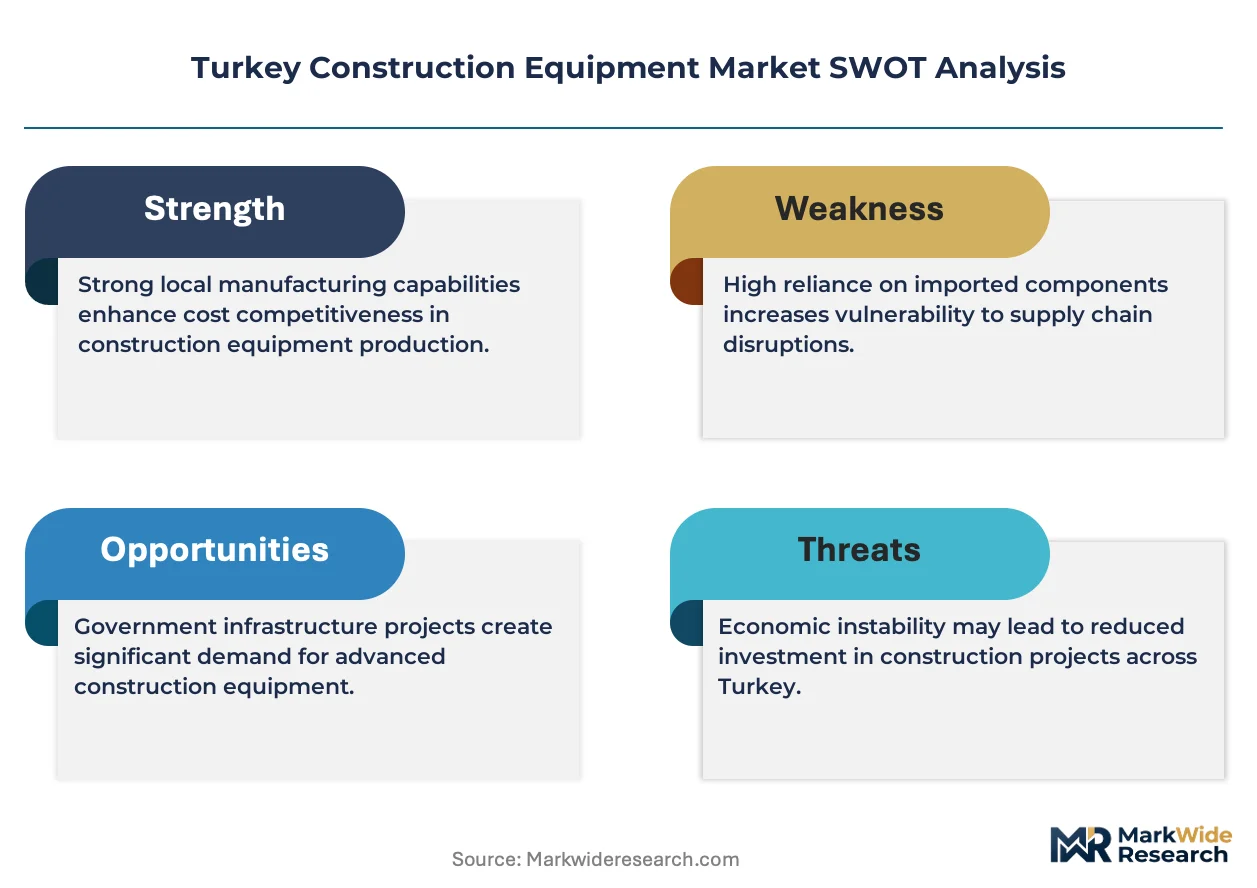
- CE-Equivalent Harmonization:Turkish Standards Institution certification alignment with EU machinery directives creates procurement preference for certified European OEMs in public tenders.
- Earthmoving Mechanization:Urban renewal demolition volumes in Ankara and Izmir accelerate hydraulic breaker and crawler loader deployment rates.
Market Restraints
- Diesel Input Cost Volatility:Lira depreciation against dollar-denominated engine and hydraulic component imports compresses distributor margins on Tier 4 final powertrain inventories.
- European Supply Concentration:Critical hydraulic pump and valve sourcing dependence on German and Italian tier-two suppliers exposes Turkish assemblers to six-month lead time extensions.
- Electric Drivetrain Technical Limitation:Battery energy density constraints below 300 watt-hours per kilogram restrict all-electric excavator duty cycles to sub-eight-hour shifts on Anatolian mining sites.
Strategic Opportunities
- Central Anatolian Mining Belt:Konya and Kayseri provinces host underpenetrated surface extraction operations requiring 30-ton class articulated dump trucks and motor graders.
- Telematics-Enabled Fleet Management:Convergence of 5G connectivity modules with hydraulic system sensors allows contractors to monetize usage-based maintenance contracts.
- Operational Leasing Channel:Rental companies capture mid-tier contractors shifting from equipment ownership to per-hour utilization models with full-service maintenance inclusion.
Industry Challenges
- Certification Timeline Compression:Ministry of Environment, Urbanization and Climate Change emissions compliance deadlines for diesel fleets outpace homologation laboratory capacity in Ankara.
- Hydraulic Technician Scarcity:Vocational training pipeline deficits for high-pressure system diagnostics force contractors into premium third-party service contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turkey Construction Equipment Market |
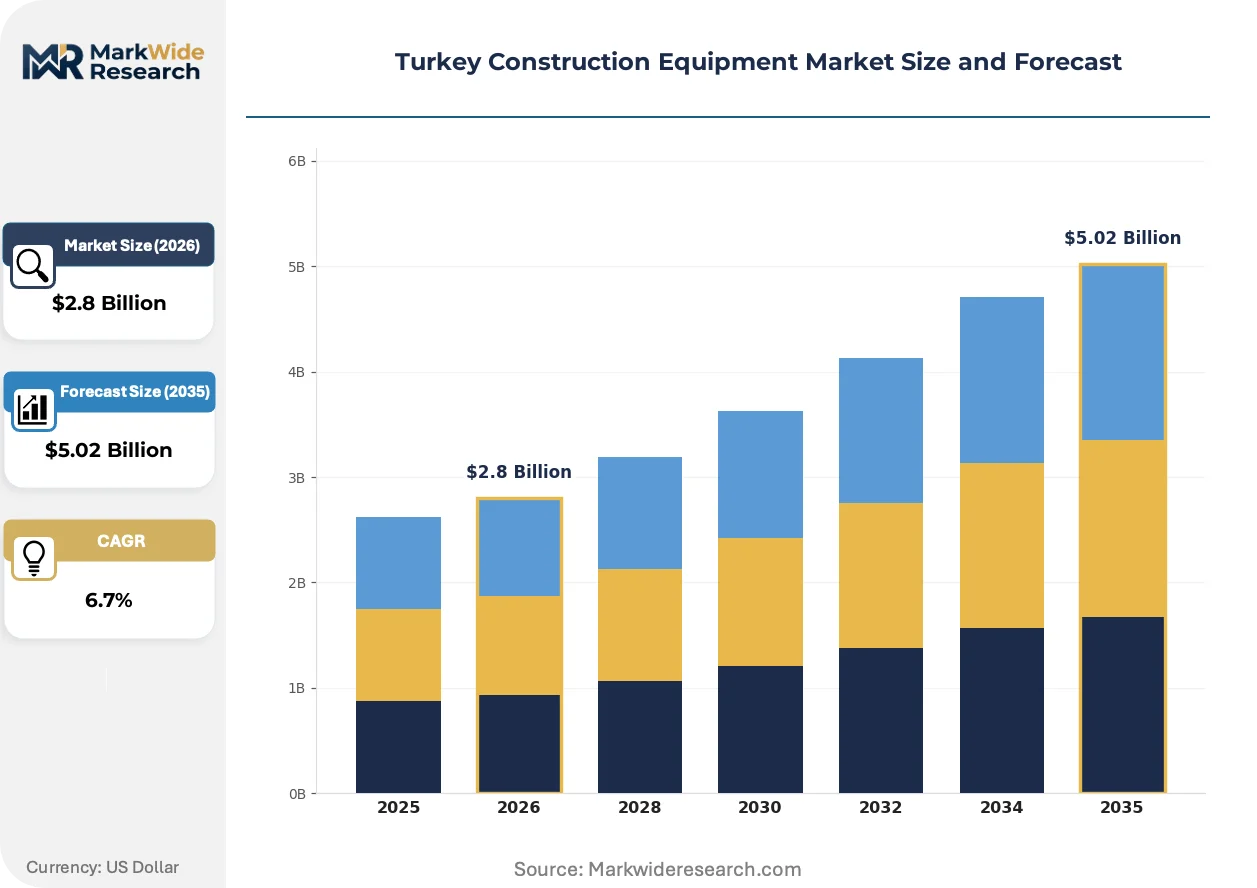
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Excavators, Loaders, Bulldozers, Graders Technology: Hydraulic, Electric, Pneumatic, Diesel Application: Infrastructure, Mining, Demolition, Roadwork Customer Type: Contractors, Government, Construction Firms, Rental Companies |
| Companies Covered | XCMG, Komatsu, Caterpillar, Volvo Construction Equipment, Liebherr, SANY, Hitachi Construction Machinery, JCB, Hidromek, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turkey Construction Equipment Market Trends and Innovations
Equipment technology trajectories in Turkey center on powertrain electrification, digital fleet integration, and procurement model restructuring. These forces collectively redefine asset lifecycle economics and competitive differentiation.
Hybrid-electric excavator architectures are migrating from demonstration units to municipal contractor fleets. Istanbul Metropolitan Municipality specifications now require idle-stop and regenerative swing braking on 20-ton class machines. This technology compression enables contractors to bid transit tunnel projects with guaranteed emissions compliance without diesel particulate filter maintenance penalties.
The Ministry of Environment, Urbanization and Climate Change enforces stricter Stage V-equivalent exhaust limits on imported diesel machinery. Industrial consequence includes accelerated write-downs of pre-2019 equipment inventories and premium pricing for compliant powertrains. Ankara-based transport infrastructure contractors respond by extending lease terms to amortize higher acquisition costs across longer project horizons.
Rental penetration accelerates as small and mid-sized contractors abandon ownership models. Equipment-as-a-service contracts with telemetry-backed utilization guarantees displace traditional bank-financed purchases. This shift concentrates most visibly in Izmir's commercial construction vertical, where project bundling and payment delays make capital preservation the dominant procurement logic.
Turkey Construction Equipment Market Segmentation
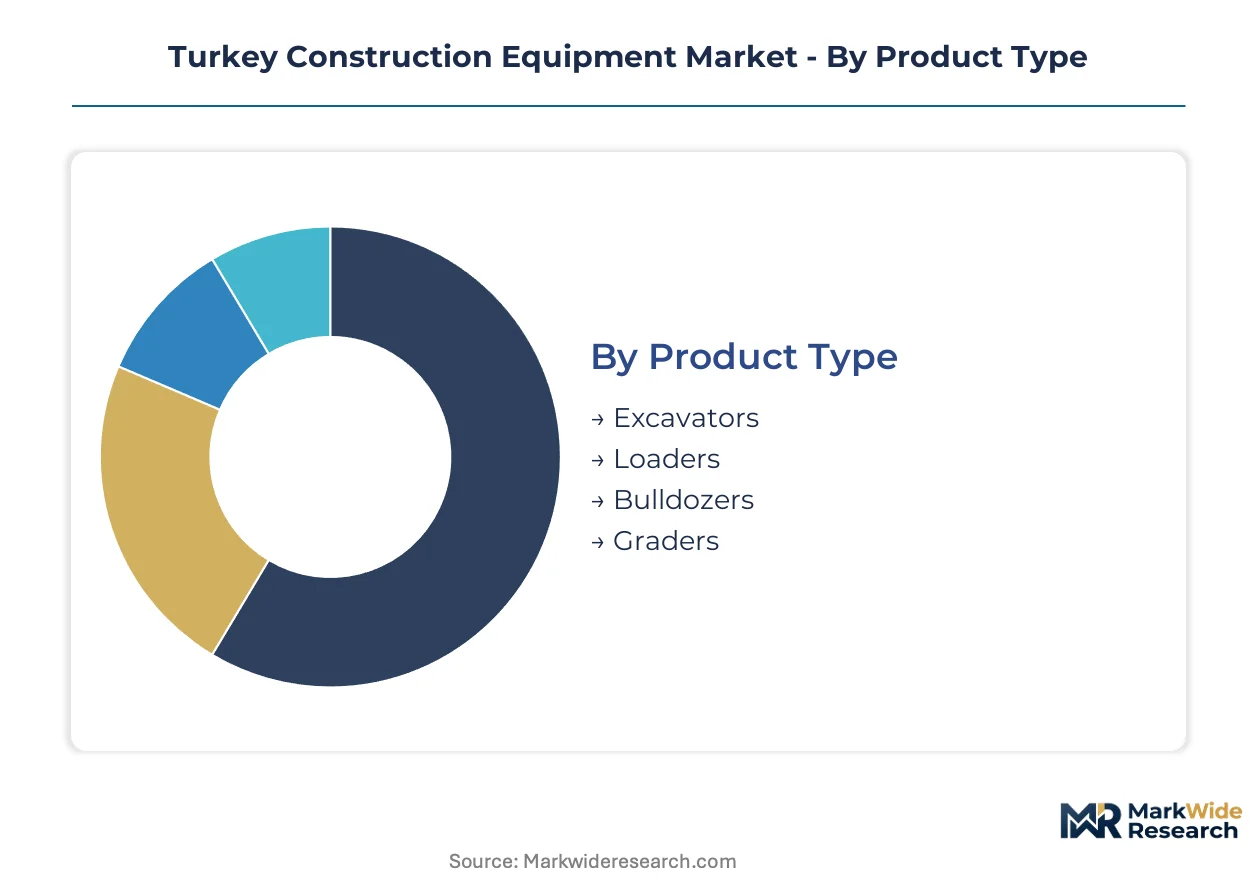
Equipment segmentation in Turkey reveals divergent replacement cycles across product categories, with high-utilization mining assets turning over faster than municipal infrastructure fleets. Understanding these velocity patterns enables suppliers to align inventory financing with contractor depreciation schedules and project award timelines.
Product Type:
Cycle times vary dramatically across equipment categories, with excavators in continuous tunneling duty requiring replacement at roughly half the interval of seasonal roadwork graders.
- Excavators:Tracked and wheeled variants with hydraulic boom systems dominate foundation work and transit tunneling across Istanbul's Marmara corridor. Istanbul Metropolitan Municipality specifications for idle-stop and regenerative swing braking on 20-ton class machines accelerate technology refresh cycles in municipal fleets.
- Loaders:Articulated and skid-steer configurations handle material stockpiling and site clearing, with crawler loader deployment rates climbing fastest in Ankara and Izmir urban renewal zones. Hidromek's Konya facility anchors domestic production capacity for this segment.
- Bulldozers:Track-type tractors with torque-converter powertrains serve surface grading and push-loading applications in Central Anatolian mining belts.
- Graders:Motor graders with articulated frames and circle-reverse mechanisms maintain haul roads and precision finish grading on transport infrastructure projects.
Excavators anchor the volume base while electric-hybrid variants within the loader category gain share at the steepest rate.
Technology:
Cost tiers separate established hydraulic systems from emerging electric architectures, with premium pricing for compliant powertrains compressing distributor margins on legacy diesel inventories.
- Hydraulic:Proven torque density and field-serviceability in remote Anatolian project sites sustain hydraulic dominance across contractor fleets. Turkish Standards Institution vibration and noise limits under harmonized EU machinery directives elevate compliance costs for system redesigns.
- Electric:Battery energy density constraints below 300 watt-hours per kilogram restrict all-electric excavator duty cycles to sub-eight-hour shifts, limiting penetration in continuous mining operations. Municipal emissions protocols in Istanbul drive fastest adoption in transit tunnel projects with guaranteed compliance requirements.
- Pneumatic:Compressed-air powertrains serve specialized underground applications with explosion-risk constraints in confined extraction environments.
- Diesel:Tier 4 final and Stage V-equivalent powertrains face accelerated write-downs of pre-2019 inventories under Ministry of Environment, Urbanization and Climate Change deadlines.
Hydraulic systems capture the installed base while electric configurations expand most quickly in municipal contracting.
Application:
Volume concentration in infrastructure contrasts with margin profiles in mining, where equipment utilization rates and service contract values run highest.
- Infrastructure:Transit expansion, bridge construction, and utility installation across Turkey's transport corridors generate sustained demand for 30-ton class articulated equipment. Ankara-based contractors extend lease terms to amortize higher acquisition costs across longer project horizons.
- Mining:Surface extraction in Konya and Kayseri provinces requires heavy-duty undercarriages and reinforced booms for abrasive terrain, with usage-based maintenance contracts monetizing telemetry data. Central bank monetary policy and lira volatility directly shape financing terms for fleet investment.
- Demolition:Hydraulic breaker attachments and specialized carrier machines process urban renewal volumes in Ankara and Izmir commercial zones.
- Roadwork:Motor graders and compactors maintain asphalt quality on national highway programs under Ministry of Transport and Infrastructure oversight.
Infrastructure commands the revenue base while mining applications deliver the steepest service margin expansion.
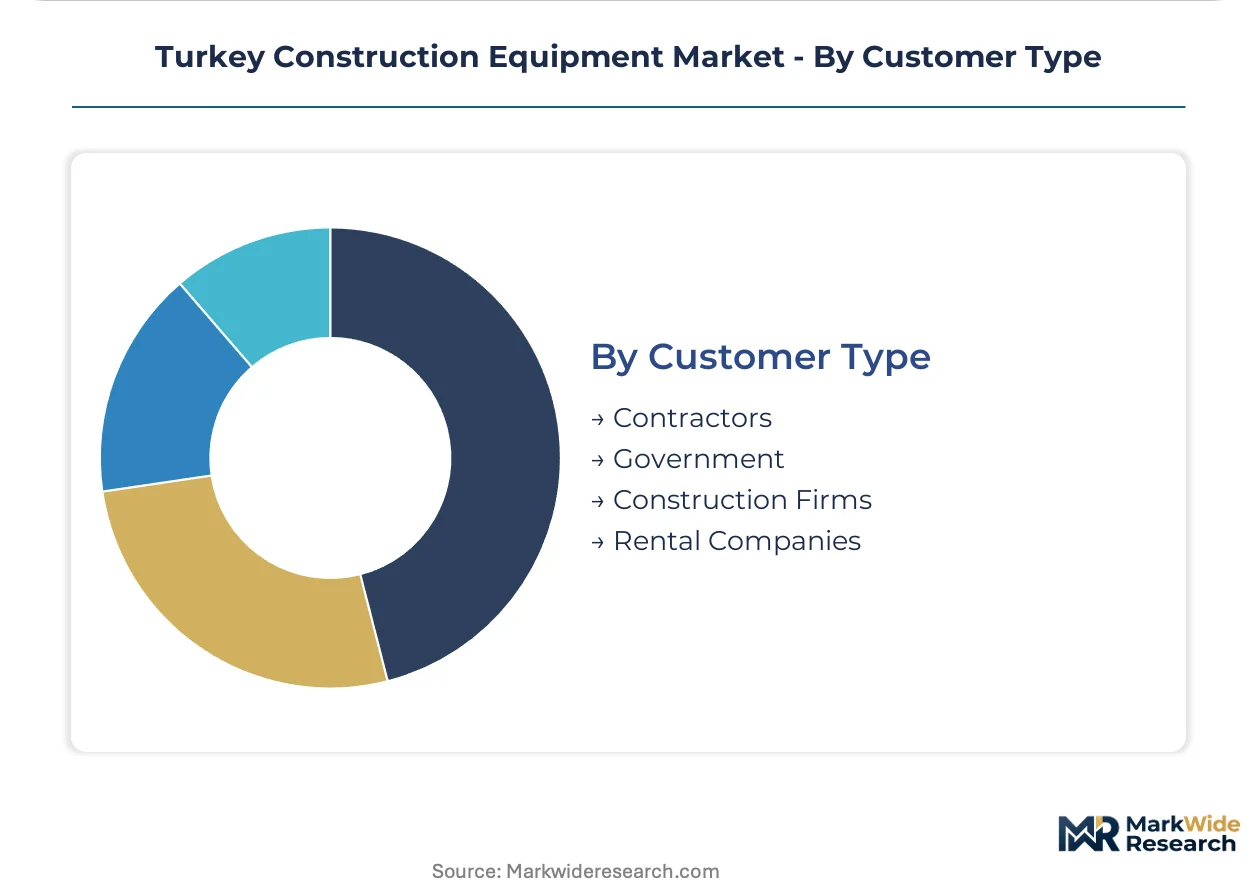
Customer Type:
Procurement patterns diverge sharply between ownership-focused government fleets and operational leasing preferences among capital-constrained mid-tier contractors.
- Contractors:Small and mid-sized civil engineering firms shift capital from ownership to per-hour utilization models with full-service maintenance inclusion. Payment delays on project bundling make capital preservation the dominant procurement logic in Izmir's commercial construction vertical.
- Rental Companies:Equipment-as-a-service contracts with telemetry-backed utilization guarantees displace traditional bank-financed purchases. 5G connectivity modules converging with hydraulic system sensors enable usage-based maintenance monetization.
- Government:Public tenders enforce CE-equivalent conformity and certified supplier preferences, creating procurement barriers for non-European OEMs.
- Construction Firms:Large integrated developers maintain captive fleets for project pipeline visibility and scheduling control.
Contractors represent the largest addressable pool while rental companies climb the fastest as procurement intermediaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Turkey's construction equipment consumption concentrates in three distinct corridors: Istanbul's transit megaprojects, Ankara's infrastructure belt, and Central Anatolia's mining extraction zones. Each geography deploys machinery toward different operational intensities and regulatory compliance thresholds.
Marmara Region
Istanbul's transit tunnel expansion and bridge construction generate continuous demand for 20-ton class excavators with idle-stop and regenerative swing braking specifications. The Istanbul Metropolitan Municipality enforces Stage V-equivalent emissions compliance on municipal contractor fleets. Gebze and Tuzla industrial zones host equipment depots serving the megaproject corridor with rapid parts logistics.
Central Anatolia
Konya and Kayseri provinces drive surface extraction demand for 30-ton articulated dump trucks and motor graders in abrasive terrain applications. The Ministry of Environment, Urbanization and Climate Change mandates accelerated diesel fleet write-downs, compressing replacement cycles. Hidromek's Konya manufacturing facility anchors domestic production capacity for regional export markets.
Aegean Region
Izmir's commercial construction vertical and urban renewal demolition volumes accelerate hydraulic breaker and crawler loader deployment. Payment delays on project bundling push contractors toward operational leasing models with full-service maintenance inclusion. The Alsancak and Bornova districts concentrate rental company fleets serving mid-tier civil engineering firms.
Black Sea Region
Rize and Trabzon provinces support hydroelectric dam construction and mountain road infrastructure requiring specialized high-altitude powertrain configurations. The Ministry of Transport and Infrastructure mandates CE-equivalent conformity for imported machinery in public tenders. Samsun port logistics clusters handle equipment imports for eastern Anatolian project sites.
Turkey Construction Equipment Market Competitive Landscape
Capability concentration sits with integrated OEMs commanding telemetry-integrated fleet management systems; scale advantage sits with regional assemblers leveraging local manufacturing footprints. The Turkish market structures around three archetypes: global full-line manufacturers, China-based cost-positioned suppliers, and domestic producers with regional export reach. Competitive moves center on dealer network density expansion and operational leasing channel partnerships.
Among global full-line manufacturers, Caterpillar, Komatsu, and Volvo Construction Equipment represent the premium-tier archetype with recurring maintenance contract capture. XCMG and SANY occupy positions within the cost-optimized import segment. Hidromek anchors the domestic manufacturing tier with Konya-based production serving Turkish and neighboring markets.
| Leading Market Players |
|---|
| XCMG |
| Komatsu |
| Caterpillar |
| Volvo Construction Equipment |
| Liebherr |
| SANY |
| Hitachi Construction Machinery |
| JCB |
| Hidromek |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in European hydraulic component foundries is compressing pricing power for Turkish equipment assemblers while simultaneously enabling favorable procurement terms on long-lead items. This utilization dynamic forces distributors to absorb margin pressure on legacy diesel inventories while negotiating volume commitments on electrified powertrains.
Pricing Analysis
Project-based contracting dominates equipment procurement, with Istanbul Metropolitan Municipality tenders specifying fixed-price frameworks for 20-ton class excavators across multi-year transit expansions. Price differentiation separates CE-certified European OEMs from non-certified imports, with after-sales service bundling commanding premiums in remote Anatolian mining zones. Cost compression in the rental channel is intensifying because operational leasing providers amortize acquisition premiums across utilization guarantees. Small and mid-sized contractors exhibit the highest price sensitivity, while government fleets prioritize compliance certification over unit economics.
Supply Chain Analysis
German and Italian tier-two suppliers hold concentrated capacity for hydraulic pumps and valves serving Turkish assemblers. Component sourcing draws from German precision manufacturers, Italian hydraulic specialists, and Chinese steel foundries. Single-source vulnerability runs through Bosch Rexroth and Parker Hannifin distribution networks, where six-month lead time extensions expose Turkish distributors to project delay penalties. Distribution runs through Gebze and Tuzla industrial zone depots with rapid parts logistics to the Marmara megaproject corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Turkey's construction equipment sector is cycling through a recovery phase anchored to Istanbul's transit megaproject pipeline and Central Anatolian mining expansion. Infrastructure tender awards and lira stabilization against dollar-denominated component imports provide the cyclical momentum.
For Market Incumbents: Pre-empt margin erosion in the diesel rental channel by accelerating backward integration into certified remanufacturing capabilities at Ankara service hubs. Defend dealer network density through exclusive telemetry-integrated fleet management contracts that lock contractors into usage-based maintenance ecosystems. The threat of Chinese cost-positioned suppliers penetrating municipal tenders demands CE-equivalent certification investment as a defensive moat.
For New Entrants and Emerging Players: Establish a beachhead in the Central Anatolian mining belt's 30-ton articulated dump truck segment, where Hidromek's domestic production leaves service coverage gaps in Kayseri surface extraction operations. Target operational leasing partnerships with Izmir-based rental companies seeking to diversify beyond European OEM dependency. A go-to-market angle through 5G-enabled telematics bundling differentiates against legacy hydraulic service contracts.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across the electric-hybrid equipment sub-segment as battery pack costs compress and municipal emissions mandates accelerate replacement cycles. Long-term viability favors acquisition targets with established service depot networks in the Marmara corridor and certified remanufacturing capabilities. The signal to watch is Ministry of Environment, Urbanization and Climate Change enforcement velocity on diesel fleet write-down deadlines.
| Strategic Initiative | Industry Significance |
|---|---|
| Dealer Network Density Expansion | Caterpillar's recurring maintenance contract capture in Anatolian mining zones demonstrates channel control value. |
| Telemetry-Integrated Fleet Management | Komatsu's competitive positioning through hydraulic sensor convergence enables usage-based monetization. |
| Operational Leasing Channel Partnership | Rental company procurement intermediation in Izmir concentrates capital preservation demand. |
| Local Manufacturing Scale | Hidromek's Konya facility anchors domestic production capacity for regional export reach. |
| CE-Equivalent Certification Investment | Turkish Standards Institution alignment creates procurement preference in public infrastructure tenders. |
Research Methodology
Operator-level perspectives from fleet maintenance directors, OEM procurement teams, rental company operations heads, and aftermarket service managers anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation through Turkish Standards Institution certification databases, Ministry of Transport and Infrastructure tender records, central bank monetary policy disclosures, and customs import data on hydraulic component trade flows. Bottom-up equipment unit economics triangulated against top-down sector revenue estimates.
Scenario-bracketing framed the analytical approach across the projection horizon, with sensitivity testing on lira volatility and emissions compliance timeline acceleration. Segmentation dimensions modeled include product type, technology architecture, application intensity, and customer procurement pattern. CAGRs were derived from equipment replacement cycle analysis and project pipeline visibility. Forecast inputs incorporated Istanbul Metropolitan Municipality specification changes and Central Anatolian mining permit issuance velocity.
Macroeconomic conditions sit as an overlay; deviation in central bank interest rate policy and lira-dollar exchange rate stability would shift the trajectory of contractor financing capacity and fleet investment timing. Forecasts reflect documented assumptions on infrastructure tender award cadence and European supplier lead time normalization. Quarterly review of Ministry of Environment emissions enforcement indicators and mining sector capital expenditure announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Laser Cladding Equipment Market
Construction Equipment
Friction Stir Welding Market
Construction Equipment
LAMEA Stud Welding Machine Market
Construction Equipment
Snow Removal Equipment Market
Construction Equipment
Global Crane and Hoist Market
Construction Equipment
Heating Roller Press Calender Machine Market
Construction Equipment
Soil Compaction Equipment Market
Construction Equipment
Vibratory Plate Compactors Market
Construction Equipment
Concrete Chain Saw Market
Construction Equipment
Trailer Winch Market
Construction Equipment
Electrofusion Welding Machines Market
Construction Equipment
Assembly Machine Market
Construction Equipment
Plastic Molding Machine Market
Construction Equipment
Asia-Pacific Completion Equipment Market
Construction Equipment
Sandblast Nozzle Market
Construction Equipment
Shot Blasting Machine Market