
 South Africa Wall Putty Market | 2026-2036
South Africa Wall Putty Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Wall Putty Market Intelligence
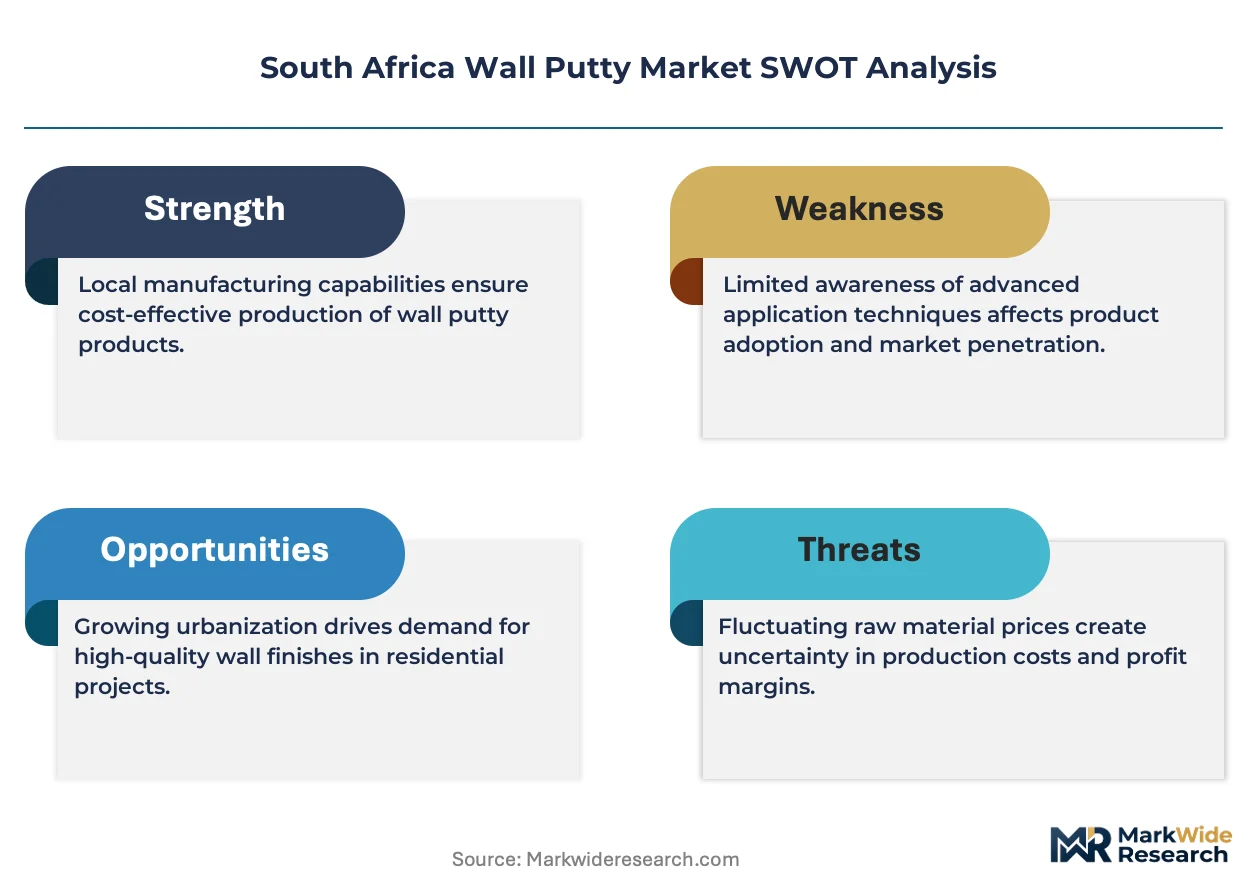
Polymer-modified binder technology is reconfiguring how wall putty achieves adhesion and crack resistance across South Africa's variable climate zones. Kansai Plascon leverages its coastal manufacturing footprint to dominate KwaZulu-Natal distribution. Sika South Africa anchors technical-grade supply through specialized construction chemical channels. Cemcrete differentiates via vertically controlled cement sourcing from its Western Cape operations.
Wall putty comprises a cementitious or acrylic-based paste applied over plastered surfaces to eliminate imperfections and create uniform substrates for paint or wallpaper, typically achieving thicknesses of one to three millimeters when properly troweled. Cement-based formulations lead volume in South Africa's mass housing segment due to cost alignment with public infrastructure budgets. Acrylic variants capture premium residential and commercial refurbishment work where faster drying and superior flexibility justify higher unit pricing. The institutional end-user segment concentrates demand in education and healthcare facilities undergoing compliance-driven upgrades.
South Africa's National Regulator for Compulsory Specifications (NRCS) mandates SABS-marked building materials for government-commissioned projects, directly filtering market access for imported and domestic suppliers alike. The South African Bureau of Standards (SABS) periodically revises coating substrate preparation protocols, pushing manufacturers toward reformulated products with enhanced alkalinity resistance. Stakeholders must monitor pending amendments to SABS 1091 and NRCS certification timelines to align inventory planning with regulatory enforcement cycles.
Market Dynamics
Polymer-modified binder chemistry is restructuring competitive advantage in South Africa's wall putty sector, compressing drying cycles and expanding crack-resistance specifications that cement-only formulations cannot match. This technical inflection is redrawing procurement criteria across Gauteng's high-density residential corridors.
Growth Catalysts
- NRCS SABS Certification Mandates:Government-commissioned construction projects require SABS-marked substrate preparation materials, filtering supplier eligibility and concentrating demand among compliant domestic manufacturers.
- Healthcare Facility Compliance Upgrades:Public hospital renovation programs in KwaZulu-Natal and Western Cape are specifying alkalinity-resistant putty systems for infection-control coating protocols.
- Acrylic Formulation Penetration:Premium residential developers in Johannesburg's northern suburbs are specifying fast-curing flexible putty for high-turnover luxury apartment completions.
Market Restraints
- Portland Cement Price Volatility:Input cost swings for clinker and limestone concentrate squeeze margin structures for cement-based putty producers serving mass housing budgets.
- Import Dependency for Acrylic Polymers:Domestic formulation capacity relies on concentrated Asian polymer supply, exposing distributors to currency fluctuation and shipping disruption risks.
- Technical Substitution by Gypsum Skimming:Drywall-intensive commercial fit-outs in Cape Town's CBD are displacing traditional putty application for speed-critical interior finishing.
Strategic Opportunities
- Eastern Cape Infrastructure Pipeline:Transnet port expansion and Coega IDZ residential zones create underpenetrated demand nodes beyond Gauteng-KwaZulu-Natal concentration.
- SABS 1091 Amendment Preparation:Anticipated protocol revisions for coating substrate alkalinity resistance create first-mover advantage for reformulated product registrations.
- Contractor Direct Digital Channels:Specialized construction chemical distributors are piloting app-based procurement platforms linking regional applicators to Western Cape manufacturing facilities.
Industry Challenges
- Skilled Applicator Shortage:Trowel-grade finish quality depends on experienced plastering crews, with training pipeline gaps constraining installation capacity in secondary cities.
- NRCS Certification Timeline Compression:Extended laboratory testing queues for SABS mark renewal are delaying product launch schedules and inventory positioning for public tender cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Wall Putty Market |
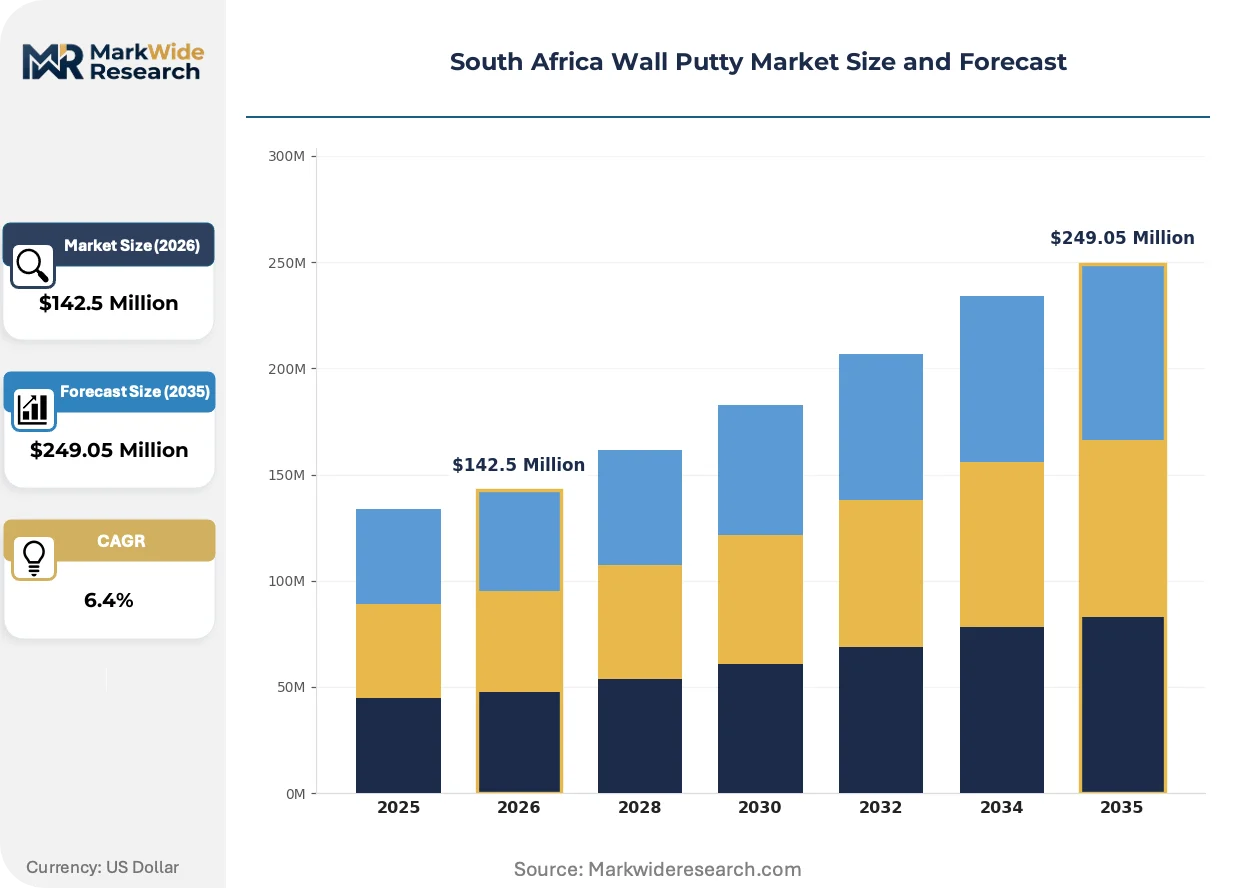
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $249.05 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Cement-based, Polymer-modified, Oil-based End User: Residential, Commercial, Industrial, Institutional Application: Interior, Exterior, Decorative, Repair Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | Kansai Plascon, Cemcrete, Sika South Africa, Dulux, Saint-Gobain Weber, PPG Coatings, Akzo Nobel, Chryso South Africa, BASF Construction Chemicals, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Wall Putty Market Strategic Shifts & Innovations
Reformulation priorities in South Africa's wall putty market center on climate-adaptive performance, with manufacturers racing to synchronize product specifications with tightening substrate preparation protocols and shifting construction procurement rhythms.
Hybrid polymer-cement binder systems are collapsing the performance gap between traditional cementitious putty and premium acrylic alternatives. Mid-market housing developers in Pretoria and Durban are specifying these intermediate formulations for cost-controlled projects requiring moderate flexibility. The technology is collapsing the historical price-performance trade-off that segmented the market into rigid economy and flexible premium tiers.
SABS 1091 substrate preparation standards are undergoing revision cycles that elevate alkalinity resistance testing thresholds. Manufacturers serving government healthcare and education tenders must recertify existing product lines against amended protocols. Johannesburg-based technical-grade suppliers are responding by accelerating in-house laboratory capacity to compress validation turnaround times.
Buying patterns among large-scale residential developers are consolidating toward specification-grade bundled procurement. Volume contractors in Gauteng are negotiating direct supply agreements with Western Cape manufacturing facilities, bypassing traditional regional distributor markups. This channel compression is most visible in Johannesburg's high-density corridor projects where single-source accountability for coating system performance is becoming a tender prerequisite.
South Africa Wall Putty Market Segmentation
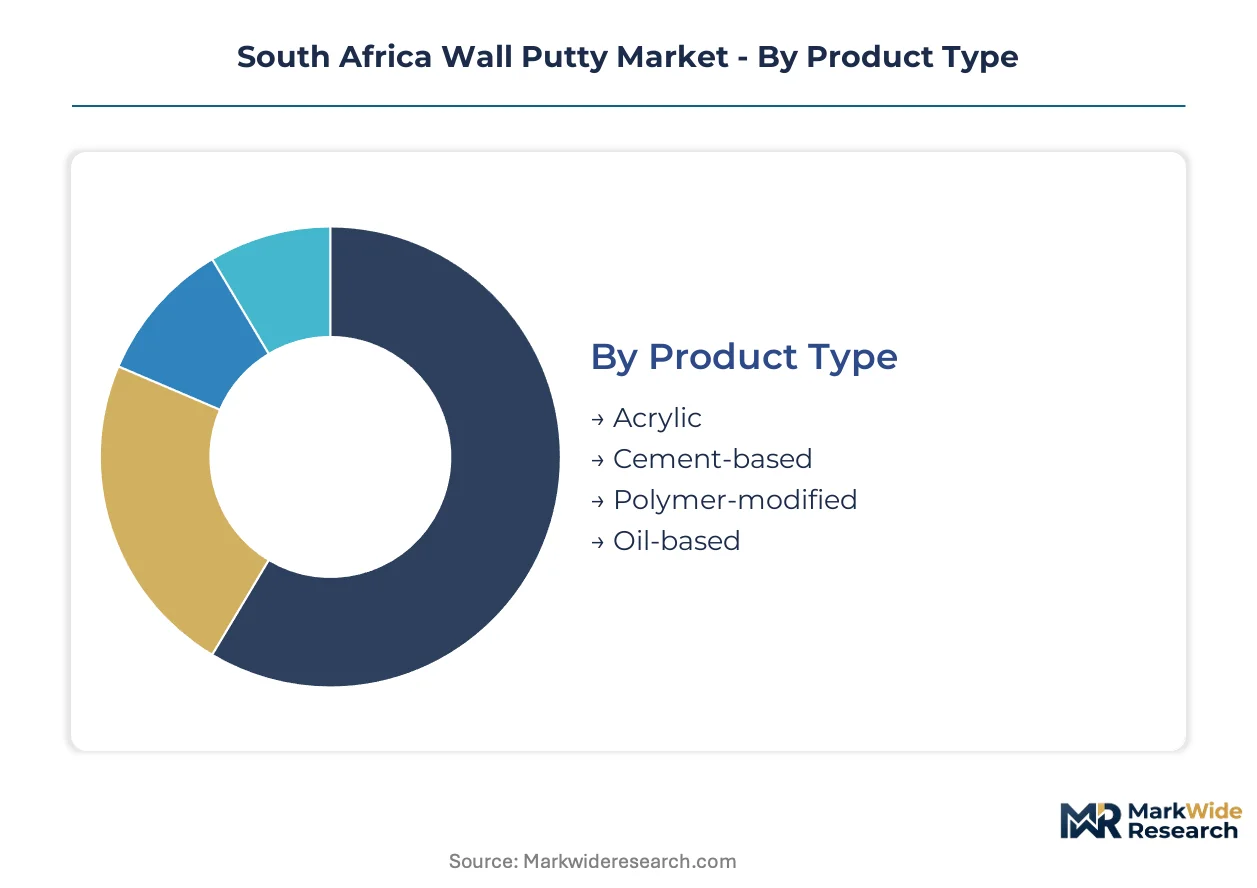
Wall putty segmentation in South Africa reflects divergent performance requirements across climate zones, budget tiers, and regulatory compliance environments. Product chemistry, end-use specifications, and channel economics create distinct competitive arenas that suppliers must navigate simultaneously.
Product Type:
Mature cement-based formulations coexist with emerging polymer-modified systems that are compressing traditional performance trade-offs.
- Cement-based:Portland cement and filler compositions dominate mass housing procurement in Johannesburg's high-density corridors. Public infrastructure budgets in Gauteng and KwaZulu-Natal specify these formulations for cost-controlled substrate preparation.
- Polymer-modified:Hybrid binder chemistry integrates acrylic or SBR latex with cementitious bases, delivering intermediate flexibility for Pretoria and Durban mid-market developers. NRCS SABS certification requirements are accelerating reformulation investments among technical-grade suppliers.
- Acrylic:Pure polymer emulsion systems serve premium residential and commercial refurbishment where rapid drying and superior crack resistance justify unit price premiums.
- Oil-based:Alkyd resin formulations retain niche demand for specialized exterior applications requiring extreme moisture resistance in coastal Western Cape conditions.
Cement-based formulations handle the majority of throughput; polymer-modified variants are climbing the fastest on specification share.
End User:
Customer concentration patterns split between volume-driven residential construction and compliance-intensive institutional procurement.
- Residential:Homeowners and developers in Gauteng and KwaZulu-Natal prioritize smooth interior finishes for paint and wallpaper substrates, driving specification-grade bundled procurement.
- Institutional:Public hospital renovation programs in KwaZulu-Natal and Western Cape mandate alkalinity-resistant putty systems for infection-control coating protocols under NRCS oversight.
- Commercial:Cape Town CBD fit-outs and Johannesburg office refurbishments specify fast-curing flexible systems for high-turnover completion schedules.
- Industrial:Manufacturing facility maintenance in Eastern Cape industrial zones demands heavy-duty formulations resistant to chemical exposure and thermal cycling.
Residential construction commands the dominant volume position; institutional upgrades are gaining specification intensity fastest.
Application:
Functional requirements diverge sharply between climate-protected interior work and weather-exposed exterior substrates.
- Interior:Smooth-finish applications for paint and wallpaper preparation concentrate in Gauteng's high-density housing corridors and Pretoria residential developments.
- Exterior:Weather-resistant formulations face alkalinity and moisture challenges across South Africa's variable climate zones, from coastal KwaZulu-Natal humidity to Highveld thermal cycling.
- Decorative:Textured and specialty finish applications serve premium residential developers in Johannesburg's northern suburbs seeking differentiated aesthetic outcomes.
- Repair:Crack remediation and surface rehabilitation work concentrates in aging building stock across Durban and Cape Town metropolitan areas.
Interior applications absorb the bulk of formulation volume; exterior specifications are expanding most quickly on performance requirements.
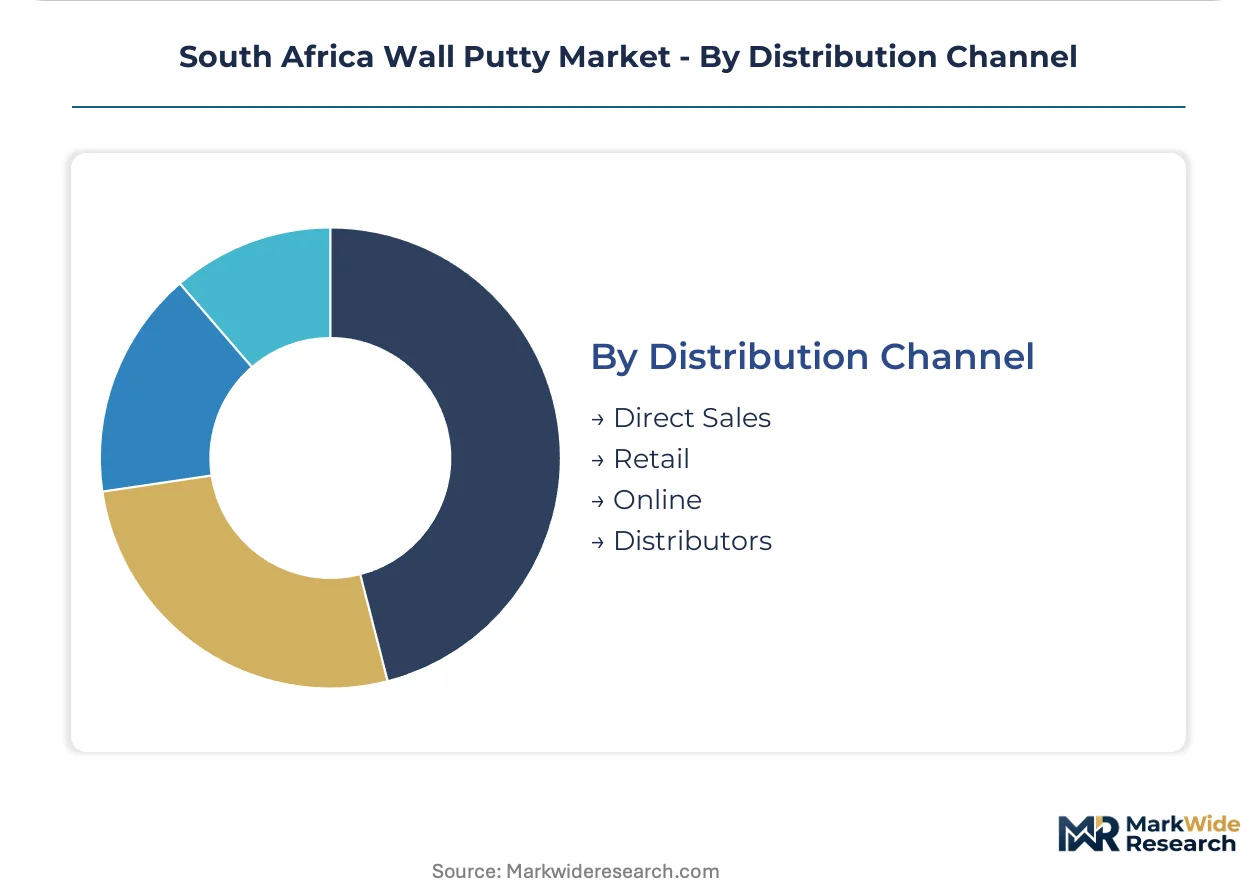
Distribution Channel:
Channel structure reflects the tension between specification control and procurement efficiency in construction chemical supply.
- Distributors:Specialized construction chemical distributors anchor technical-grade supply through regional warehousing networks serving contractor applicators nationwide.
- Direct Sales:Volume contractors in Gauteng negotiate direct supply agreements with Western Cape manufacturing facilities, bypassing traditional markups for high-density corridor projects.
- Retail:Builder merchant and hardware store channels serve small-scale residential renovators and independent applicators in secondary cities.
- Online:App-based procurement platforms are piloting digital linkages between regional applicators and manufacturing facilities, compressing order-to-delivery cycles.
Distributor networks retain the largest throughput share; direct sales channels are steepest in expansion trajectory among large-scale developers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa's wall putty trade balance tilts toward import dependency for acrylic polymer feedstocks while cement-based formulations draw on domestic clinker capacity. Regional demand concentrates in five provinces that collectively shape procurement patterns and regulatory enforcement.
Gauteng
Johannesburg's high-density housing corridors generate the dominant volume of cement-based putty consumption. The National Regulator for Compulsory Specifications enforces SABS-marked materials for government-commissioned projects in Pretoria's public infrastructure pipeline. Midrand and Tembisa industrial zones host distributor warehousing networks serving contractor applicators across the province.
KwaZulu-Natal
Durban's coastal manufacturing footprint anchors polymer-modified formulation supply for humidity-exposed exterior applications. Public hospital renovation programs mandate alkalinity-resistant putty systems under infection-control coating protocols. The Coega IDZ residential zones and Transnet port expansion create emerging demand nodes beyond metropolitan Durban.
Western Cape
Cape Town CBD commercial fit-outs specify fast-curing flexible systems for high-turnover completion schedules. Vertically controlled cement sourcing from local operations supports cost-competitive mass housing supply. Stellenbosch and Paarl construction chemical clusters concentrate technical-grade manufacturing capacity.
Eastern Cape
Port Elizabeth industrial zones demand heavy-duty formulations resistant to chemical exposure and manufacturing facility thermal cycling. Underpenetrated residential construction in Gqeberha and surrounding townships offers expansion opportunity beyond Gauteng-KwaZulu-Natal concentration. Training pipeline gaps for skilled applicators constrain installation capacity relative to project pipelines.
Free State
Bloemfontein institutional construction in education and healthcare facilities drives compliance-driven specification of SABS-certified substrate preparation materials. Secondary city procurement relies on distributor networks extending from Gauteng manufacturing facilities. Agricultural processing facility maintenance creates niche demand for moisture-resistant exterior formulations.
South Africa Wall Putty Market Key Industry Players
On the supply side, the industry is structured around three strategic tiers differentiated by formulation technology and channel access. Cement-based mass-market suppliers compete on raw material sourcing efficiency and distributor network density. Polymer-modified specialists occupy the mid-market with hybrid binder chemistry. Premium acrylic formulators target specification-grade commercial and luxury residential procurement. Competitive moves center on backward integration into cement sourcing and direct digital channel development linking manufacturing facilities to volume contractors.
Within the premium-tier vector, Kansai Plascon and Sika South Africa exemplify coastal manufacturing footprint strategies that dominate regional distribution. Cemcrete occupies a position among vertically integrated domestic suppliers with captive cement sourcing from Western Cape operations. Dulux and Akzo Nobel represent multinational coating specialists extending substrate preparation portfolios through construction chemical divisions. Saint-Gobain Weber and BASF Construction Chemicals anchor technical-grade supply through specialized construction chemical channels serving institutional and industrial end-users.
| Leading Market Players |
|---|
| Kansai Plascon |
| Cemcrete |
| Sika South Africa |
| Dulux |
| Saint-Gobain Weber |
| PPG Coatings |
| Akzo Nobel |
| Chryso South Africa |
| BASF Construction Chemicals |
| Others |
Cost & Logistics Intelligence
Import dependency for acrylic polymers from concentrated Asian supply sources determines both the pricing tier spreads between cement-based and acrylic formulations and the elongated supply chain shape that exposes distributors to currency fluctuation and shipping disruption risks. Portland cement price volatility in domestic clinker markets simultaneously compresses margins for mass-market producers while creating procurement arbitrage opportunities for vertically integrated Western Cape suppliers.
Pricing Analysis
The formulation-generation pricing gap separates legacy cement-only putty from polymer-modified hybrids and premium pure-acrylic systems. Three-tier pricing structure across premium, standard, and economy levels aligns with SABS certification grade and volume scale, with public infrastructure tenders demanding economy-tier cement-based products and luxury residential developers absorbing premium-tier acrylic unit costs. Cost compression in the standard tier is intensifying because mid-market housing developers in Pretoria and Durban are specifying hybrid formulations that collapse historical price-performance trade-offs. Mass housing contractors serving Gauteng's high-density corridors exhibit the highest price sensitivity, while institutional healthcare procurement in KwaZulu-Natal prioritizes alkalinity resistance over unit cost.
Supply Chain Analysis
Western Cape manufacturing clusters anchored by Stellenbosch and Paarl construction chemical facilities hold the dominant domestic formulation capacity for both cement-based and polymer-modified production. Raw material dependencies draw from domestic Portland cement and limestone filler supplies alongside imported acrylic polymer emulsions and SBR latex concentrates sourced from Asian chemical manufacturers. Single-source vulnerability for polymer feedstocks creates supply chain risk exposure to shipping disruption and rand-dollar exchange rate volatility. Distribution runs through specialized construction chemical distributors with regional warehousing networks, though direct sales channels linking volume contractors to Western Cape facilities are compressing traditional markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's wall putty market sits in early-cycle recovery as residential construction in Gauteng and KwaZulu-Natal accelerates from post-pandemic infrastructure backlogs and public healthcare renovation programs expand compliance-driven specification intensity.
For Market Incumbents: Build certification moats by accelerating in-house laboratory capacity to compress NRCS SABS validation turnaround times ahead of anticipated SABS 1091 amendments. Cement-based mass-market suppliers should secure captive clinker sourcing through backward integration into Western Cape limestone operations to defend margin structures against Portland cement price volatility. Polymer-modified specialists must lock in long-term acrylic polymer supply agreements with Asian manufacturers to neutralize import dependency risks. For New Entrants and Emerging Players: Eastern Cape underpenetration in Gqeberha residential zones and Coega IDZ infrastructure corridors offers white-space expansion beyond Gauteng-KwaZulu-Natal concentration. The institutional healthcare segment in Free State education and Bloemfontein hospital facilities presents the most penetrable compliance-driven specification entry point. Contractor-direct digital procurement platforms linking regional applicators to manufacturing facilities provide the optimal go-to-market angle for bypassing entrenched distributor networks. For Investors and Strategic Acquirers: The market sits at a recovery-phase inflection that favors vertically integrated domestic suppliers with captive raw material sourcing and established NRCS certification infrastructure. Acquisition targets should demonstrate Western Cape manufacturing footprint, SABS-marked product portfolios, and direct channel relationships with Gauteng volume contractors. Watch for NRCS certification timeline compression and SABS 1091 amendment publication as signals that reformulation investment cycles are accelerating.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Clinker Sourcing | Captive limestone supply from Western Cape quarries insulates margin structures against Portland cement spot price volatility. |
| Hybrid Polymer-Cement Formulation Launch | Mid-market positioning in Pretoria and Durban collapses traditional price-performance trade-offs between rigid cement and flexible acrylic tiers. |
| NRCS SABS Certification Pre-Positioning | Early laboratory validation against anticipated SABS 1091 amendments secures first-mover advantage in healthcare and education tenders. |
| Contractor-Direct Digital Channel Development | App-based procurement platforms linking regional applicators to Western Cape facilities compress order-to-delivery cycles and bypass distributor markups. |
| Eastern Cape Distribution Network Expansion | Warehousing presence in Gqeberha and Coega IDZ corridors captures underpenetrated demand beyond Gauteng-KwaZulu-Natal concentration. |
Research Approach
Operator-level perspectives from plant managers at Western Cape manufacturing facilities, procurement leads at Gauteng volume housing contractors, technical R&D directors at polymer-modified formulation specialists, and distributor channel partners anchored the qualitative base. Secondary validation drew from SABS protocol documentation, NRCS certification registry data, South African customs trade statistics for acrylic polymer imports, and construction industry association activity reports. Bottom-up demand modeling across product chemistry tiers triangulated with top-down macroeconomic construction forecasts to establish volume and value parameters.
Scenario-bracketing around regulatory amendment timing and raw material price volatility shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product chemistry tier, end-use application intensity, distribution channel structure, and provincial demand concentration. CAGRs were derived from fitted trend analysis incorporating construction sector output trajectories and specification-grade procurement pattern shifts. Key forecast inputs encompassed Portland cement price indices and NRCS certification queue lengths.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by multinational coating specialists or accelerated direct-channel development by regional distributors would shift outcomes. Quarterly review of NRCS certification timeline compression, SABS 1091 amendment publication schedules, and Eastern Cape infrastructure project pipeline activation is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Travertine Tiles Market
Building & Construction Materials
Roof Cladding Market
Building & Construction Materials
Silos Market
Building & Construction Materials
GCC Concrete Blocks Market
Building & Construction Materials
Global Floor and Wall Glazed Tiles Market
Building & Construction Materials
Timber Construction Connectors Market
Building & Construction Materials
Concrete Floating Floors System Market
Building & Construction Materials
Glazed Tiles Market
Building & Construction Materials
Gypsum and Drywall Market
Building & Construction Materials
North America Insulated Concrete Form (ICF) Market
Building & Construction Materials
Gypsum Board Market
Building & Construction Materials
Global Rainscreen Cladding Market
Building & Construction Materials
Decorative Tiles Market
Building & Construction Materials
India Faucet Market
Building & Construction Materials
Railing Market
Building & Construction Materials
Vitrified Tiles Market