
 E-Bike Market | 2026-2036
E-Bike Market Size, Share, and Industry Trends Forecast 2026-2036
E-Bike Market Analysis
Direct-to-consumer digital channels is reconfiguring how e-bike brands reach buyers, bypassing traditional bike shop intermediaries in major Western markets. Pon Bicycles Holding B.V. leverages its portfolio breadth to sustain multi-brand distribution across Europe and North America. Yadea Group Holdings anchors high-volume manufacturing in Asia, competing on cost-competitive lithium-ion integration. Giant Manufacturing Co., Ltd. differentiates through in-house frame production and vertical control over mid-drive system assembly.
An e-bike is a bicycle equipped with an integrated electric motor providing pedal assistance up to regulated speed thresholds, typically incorporating lithium-ion battery packs mounted on the downtube or rear rack for energy storage and a controller managing power delivery to hub or mid-drive motors. City E-Bikes dominate unit volumes where daily commuters replace car trips for sub-15 kilometer journeys, while Mountain E-Bikes command premium pricing from recreational riders seeking torque-rich mid-drive performance on technical terrain. Lithium-Ion battery configurations lead the Battery Type segment due to superior energy density and declining cell costs, whereas Folding E-Bikes within the Type category attract urban dwellers constrained by apartment storage limits and multimodal transit integration.
The EU's Machinery Directive and F-Gas Regulation shape product safety and refrigerant standards for thermal management systems, while the EPA in the United States oversees battery recycling mandates under emerging e-waste frameworks. China's GB standards and NMPA guidelines govern domestic motor power ratings and battery certification thresholds for road-legal operation. Stakeholders must monitor how divergent speed-limit regulations across jurisdictions influence product platform standardization and inventory allocation decisions.
Market Dynamics
Battery chemistry evolution toward solid-state architectures is compressing range anxiety thresholds while municipal procurement mandates for zero-emission last-mile fleets are institutionalizing e-bike deployment across urban logistics networks.
Growth Catalysts
- EU Green Deal transport decarbonization targets:National governments in Germany and the Netherlands are embedding e-bike subsidies into climate action plans, accelerating fleet electrification timelines for municipal services.
- Silicon-anode battery integration:Cell manufacturers are scaling production of energy-dense anode materials that extend single-charge range without increasing pack weight or frame integration complexity.
- Last-mile delivery fleet mandates:Urban logistics operators in China face binding emissions quotas under MIIT guidelines, redirecting procurement toward pedal-assist vehicles for sub-50kg payload routes.
Market Restraints
- Lithium carbonate price volatility:Raw material cost swings for cathode precursors compress OEM margin structures and complicate multi-year fleet contract pricing.
- Mid-drive motor supply concentration:German and Japanese component suppliers control torque-sensor manufacturing, creating single-source vulnerability for premium mountain e-bike assemblers.
- Speed-limit regulatory fragmentation:Divergent 25 km/h versus 32 km/h thresholds across EU member states force platform duplication and inventory segmentation.
Strategic Opportunities
- India's urban micromobility gap:Metro rail integration with folding e-bike docking remains underdeveloped in Bengaluru and Mumbai, opening first-mover channel positions.
- US IRA commercial vehicle credits:The Inflation Reduction Act's Section 45W clean commercial vehicle provisions extend to light electric utility bikes for corporate fleet purchasers.
- Direct-to-consumer subscription models:Battery-as-a-service bundling separates hardware ownership from energy access, reducing upfront capital barriers for price-sensitive urban commuters.
Industry Challenges
- Power electronics firmware certification:EU Machinery Directive compliance timelines for motor controller safety validation extend product launch cycles by 8-14 months.
- Frame welding automation skill scarcity:Aluminum hydroforming and carbon layup expertise concentrates in Taiwan and mainland China, constraining regional manufacturing diversification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Bike Market |
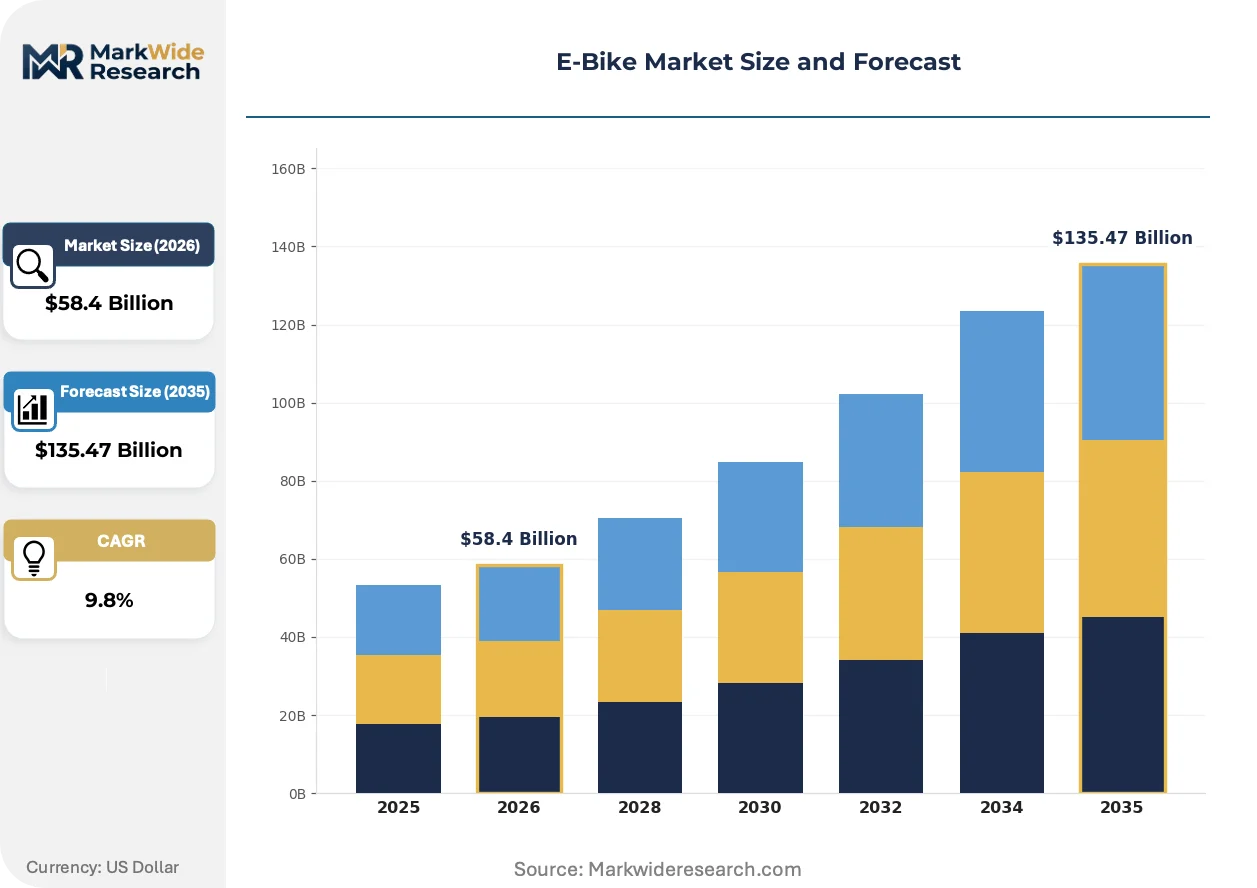
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $135.47 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: City E-Bikes, Mountain E-Bikes, Road E-Bikes, Folding E-Bikes Battery Type: Lithium-Ion, Lead-Acid, Nickel-Metal Hydride, Lithium Polymer Motor Position: Mid-Drive, Hub Motor, Front Hub, Rear Hub Target Consumer: Daily Commuters, Recreational Riders, Tourists, Fitness Enthusiasts |
| Companies Covered | Pon Bicycles Holding B.V., Yadea Group Holdings, AIMA Technology Group, Giant Manufacturing Co., Ltd., Accell Group NV, Robert Bosch GmbH, Trek Bicycle Corporation, Yamaha Motor Co., Ltd., Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Bike Market Emerging Trajectories
Solid-state battery prototyping is crossing the threshold from laboratory validation to pilot manufacturing, while thermal management architectures and procurement digitization are simultaneously restructuring how vehicles are specified, financed, and deployed.
Silicon-anode lithium-ion cells achieve 20-40% higher energy density than graphite counterparts by accommodating more lithium ions per unit volume. European premium OEMs are qualifying these packs for 2027 model year city e-bikes targeting 150+ kilometer range ratings. This chemistry transition is rendering obsolete the frame-integrated range extender batteries that previously dominated long-distance commuter segments.
The EU's F-Gas Regulation is tightening refrigerant quotas for thermal management systems in high-performance e-bike battery packs, pushing manufacturers toward phase-change material cooling or air-cooled architectures. Assembly lines in Portugal and Poland are retooling to eliminate compressor-based climate control from mid-tier product platforms. Mountain e-bike categories with sustained high-current discharge profiles face the steepest redesign timelines under these mandates.
Corporate fleet buyers are unbundling after-sales service from hardware procurement, negotiating separate contracts with third-party maintenance networks for battery health monitoring and drivetrain calibration. This purchasing pattern disrupts traditional bike shop distribution channels that relied on bundled margin structures. Germany's municipal procurement offices and Netherlands-based delivery cooperatives are piloting these disaggregated contracting frameworks most aggressively.
E-Bike Market Segmentation
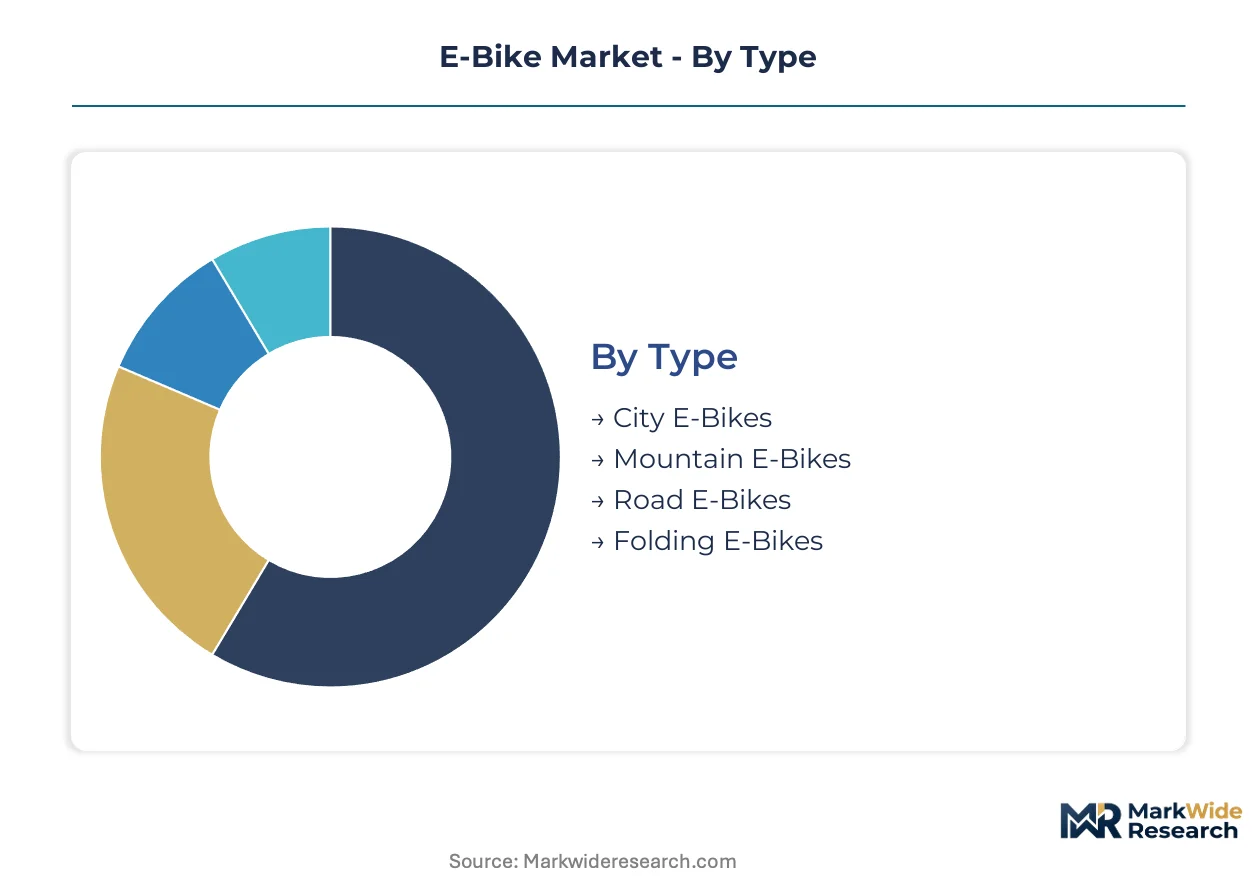
E-bike segmentation reveals distinct engineering and commercial pathways across rider profiles and infrastructure constraints. Battery chemistry and motor architecture choices cascade into pricing tiers, distribution channels, and regulatory compliance requirements.
Type:
The use-case spectrum spans utilitarian urban transport through technical off-road recreation, with frame geometry and motor tuning optimized for each mobility context.
- City E-Bikes:Step-through frames and integrated lighting dominate configurations for sub-15 kilometer commutes in Germany and the Netherlands. Municipal fleet procurement in Copenhagen and Amsterdam concentrates demand here, driven by EU Green Deal subsidy programs and congestion charging expansion.
- Mountain E-Bikes:Torque-rich mid-drive systems with 120mm+ suspension travel command premium positioning for technical terrain riding. German and Japanese component suppliers control sensor manufacturing, creating supply bottlenecks for assemblers targeting Alpine and Rocky Mountain recreation markets.
- Road E-Bikes:Drop-bar configurations with lightweight carbon frames appeal to fitness-oriented riders seeking pedal-assist on gradient-heavy routes.
- Folding E-Bikes:Hinge-frame designs with 16-20 inch wheels address apartment storage constraints and multimodal transit integration in dense Asian and European metros.
The dominant share belongs to City E-Bikes, while Folding E-Bikes are gaining share fastest as metro rail networks expand bicycle carriage allowances.
Battery Type:
Cost tier stratification separates energy-dense premium configurations from heavier legacy chemistries in price-sensitive segments.
- Lithium-Ion:NMC and LFP cell configurations achieve 250-500 Wh/kg energy density with declining cell costs from Chinese and Korean manufacturers. Yadea Group and Giant Manufacturing anchor procurement volumes here, competing on pack integration and thermal management.
- Lead-Acid:Flooded and AGM variants persist in Indian and Southeast Asian entry-level markets where upfront cost sensitivity outweighs weight and cycle-life disadvantages.
- Nickel-Metal Hydride:Intermediate energy density positions this chemistry in legacy fleet retrofits and cold-climate applications requiring stable discharge characteristics.
- Lithium Polymer:Pouch-cell form factors enable frame-integrated pack designs for premium road and mountain categories seeking minimal visual intrusion.
Lithium-Ion holds the installed base majority, though Lithium Polymer is climbing the fastest as European OEMs pursue frame-integration aesthetics.
Motor Position:
Application requirements dictate torque distribution, weight balance, and maintenance accessibility across mounting architectures.
- Mid-Drive:Crank-mounted motors leverage bicycle gearing for efficiency on steep gradients, dominating mountain and cargo categories. Bosch, Shimano, and Brose control European supply, while Chinese suppliers capture Asian volume production.
- Hub Motor:Wheel-integrated designs simplify drivetrain compatibility and reduce frame stress, standard in folding and entry-level city configurations.
- Front Hub:All-wheel-drive compatibility and simpler installation characterize this architecture for retrofit kits and budget commuter models.
- Rear Hub:Direct-drive and geared variants balance traction and efficiency, prevalent in European city bikes where frame-integrated batteries permit rear motor mounting.
Mid-Drive commands the premium tier, with Hub Motor expanding most quickly in Asian mass-market production.
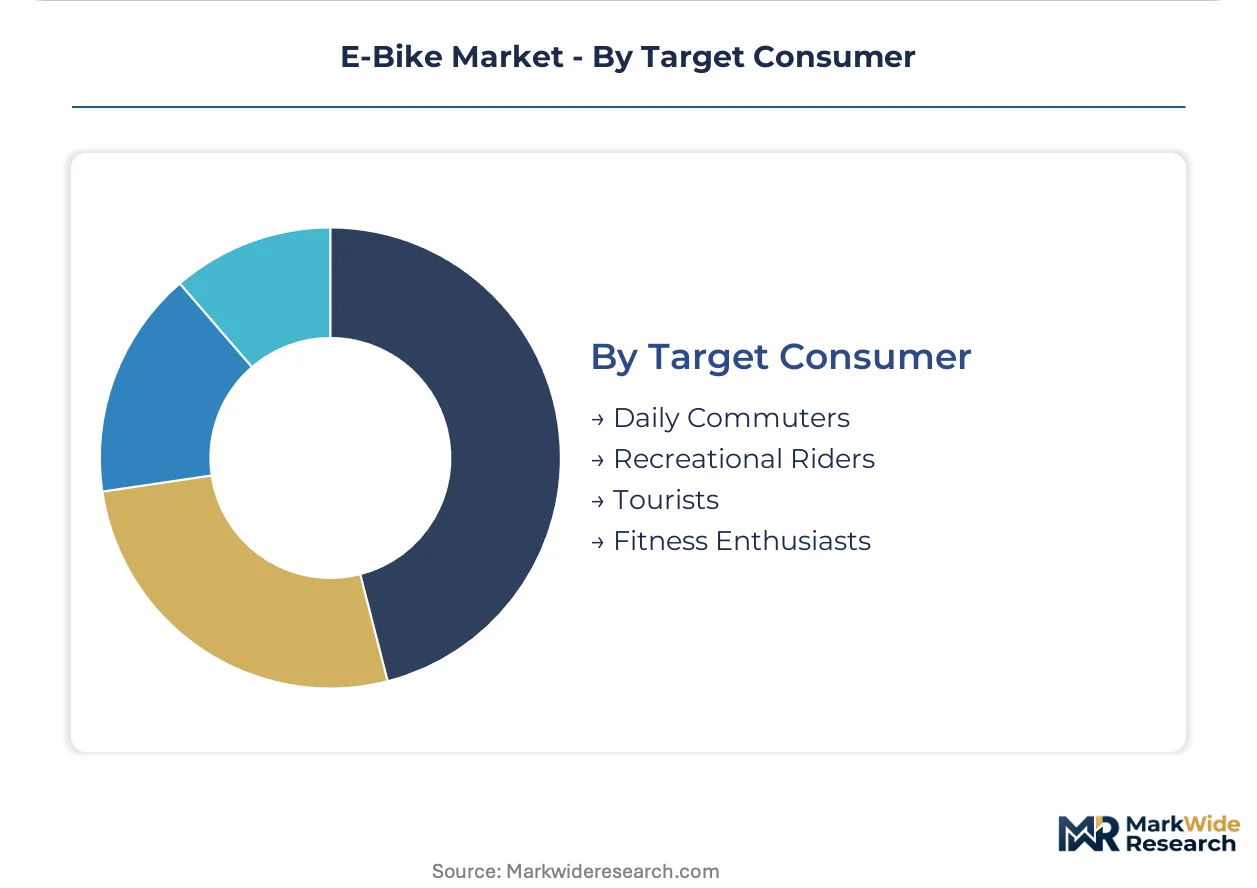
Target Consumer:
Customer type segmentation aligns distribution channels, service bundling, and financing structures with mobility behavior patterns.
- Daily Commuters:Sub-15 kilometer car replacement trips drive volume in German, Dutch, and Danish urban corridors, with employer salary-sacrifice schemes and municipal parking incentives accelerating conversion.
- Recreational Riders:Weekend trail and path riding concentrates in Alpine regions, Colorado, and Pacific Northwest markets where torque-assist extends accessible terrain range.
- Tourists:Rental fleet demand spikes in Mediterranean coastal zones, Southeast Asian heritage sites, and New Zealand adventure tourism corridors.
- Fitness Enthusiasts:Training-oriented riders seeking gradient assistance on recovery days or competitive event preparation represent a growing aftermarket for power-meter-integrated systems.
Daily Commuters generate the volume base, while Fitness Enthusiasts show the steepest expansion trajectory as power-training integration matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German OEMs command pricing premiums exceeding Chinese mass-market producers by 40-60 percent. This asymmetry reflects divergent regulatory compliance costs and brand positioning strategies across manufacturing bases.
Germany
KBA speed-limit enforcement and EU Green Deal subsidies drive municipal fleet procurement in Berlin and Hamburg. The F-Gas Regulation mandates phase-out of compressor-based thermal management in battery packs by 2027. Manufacturing clusters in Baden-Württemberg concentrate mid-drive motor assembly and torque-sensor production for Alpine-market mountain e-bikes.
China
MIIT binding emissions quotas redirect urban logistics operators toward pedal-assist vehicles for sub-50kg payload routes. GB standards govern domestic motor power ratings and battery certification thresholds for road-legal operation. Yangtze River Delta factories in Jiangsu and Zhejiang provinces anchor high-volume lithium-ion cell integration and frame welding automation.
United States
EPA battery recycling mandates under emerging e-waste frameworks reshape end-of-life economics for fleet operators. The IRA Section 45W clean commercial vehicle provisions extend to light electric utility bikes for corporate purchasers. Pacific Northwest metro areas including Seattle and Portland expand employer salary-sacrifice schemes and parking incentives for commuter conversion.
Netherlands
Congestion charging expansion in Amsterdam and Rotterdam accelerates car-trip replacement for sub-15 kilometer journeys. National cycling infrastructure investments embed dedicated lane networks and signal prioritization systems. Randstad manufacturing corridors specialize in step-through frame hydroforming and integrated lighting assemblies for urban fleet specifications.
India
Metro rail integration gaps in Bengaluru and Mumbai create first-mover channel positions for folding e-bike docking systems. BIS certification requirements and state-level electric mobility policies shape product localization timelines. Tamil Nadu and Maharashtra industrial zones develop aluminum frame welding capacity to reduce import dependency on Taiwanese supply chains.
E-Bike Market Vendor Landscape
Pan-Asian scale manufacturers and European premium assemblers split the market along cost-technology fault lines. Mid-drive motor supply concentration in German and Japanese component suppliers creates single-source vulnerability for premium mountain e-bike assemblers. Three strategic archetypes dominate: vertically integrated battery-frame specialists, component-system licensors, and direct-to-consumer digital brands. Competitive moves concentrate on silicon-anode battery qualification timelines and third-party maintenance network contracting for corporate fleet accounts.
Within the scale-driven tier, Yadea Group Holdings and AIMA Technology Group occupy positions as high-volume Asian producers competing on lithium-ion integration economics. Giant Manufacturing Co., Ltd. exemplifies the vertically integrated archetype through captive frame production and mid-drive system assembly control. These three anchors illustrate how geographic manufacturing bases stratify across cost-competitive and premium-tier market segments.
| Leading Market Players |
|---|
| Pon Bicycles Holding B.V. |
| Yadea Group Holdings |
| AIMA Technology Group |
| Giant Manufacturing Co., Ltd. |
| Accell Group NV |
| Robert Bosch GmbH |
| Trek Bicycle Corporation |
| Yamaha Motor Co., Ltd. |
| Panasonic Corporation |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta freight corridor's container cost dynamics amplify supply concentration effects in mid-drive motor sourcing while compressing margin structures for European assemblers competing against Asian volume producers. Lithium carbonate volatility feeds directly into pack pricing, forcing tiered differentiation between silicon-anode premium configurations and graphite-cell mass-market offerings.
Pricing Analysis
Configured-to-order pricing for mid-drive mountain configurations commands substantial premiums over standard hub-motor city variants, with torque-sensor calibration and frame-integrated battery aesthetics driving the spread. Three-tier pricing structure across premium, standard, and economy levels stratifies by motor position and battery chemistry grade, with EU Machinery Directive certification tiers adding compliance cost layers. Pricing pressure stems from lithium carbonate spot market swings that compress OEM margins on fixed-price fleet contracts. Daily commuters exhibit highest price sensitivity, while recreational riders purchasing through specialty retail demonstrate lowest elasticity.
Supply Chain Analysis
Supplier-financing facilities extended by Korean and Chinese cell manufacturers are reshaping working capital requirements for European frame assemblers. Manufacturing gravity centers on China, Taiwan, and Germany, with Yangtze River Delta facilities feeding global lithium-ion cell demand and Baden-Württemberg clusters anchoring torque-sensor production. Raw material dependencies span lithium carbonate from South American brine operations, rare-earth magnets from Chinese separation facilities, and aluminum extrusions from Taiwanese hydroforming specialists. Single-source vulnerability concentrates in German and Japanese mid-drive motor suppliers. Distribution runs through direct-to-consumer digital channels that disintermediate traditional bike shop networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires incumbents to defend against substitution by electric micro-cars and shared mobility services that threaten commuter-trip capture. The substitution threat intensifies as urban congestion pricing expands and subscription-based vehicle access matures.
For Market Incumbents: Build certification moats around EU Machinery Directive compliance timelines that delay challenger product launches by 8-14 months. Secure captive supply of silicon-anode cell capacity through long-term offtake agreements with Korean manufacturers. Deepen backward integration into frame welding automation to reduce dependency on Taiwanese aluminum hydroforming clusters threatened by India's emerging capacity.
For New Entrants and Emerging Players: India's metro rail integration gaps in Bengaluru and Mumbai offer first-mover positions for folding e-bike docking systems with battery-as-a-service bundling. Target corporate fleet procurement offices in Germany and the Netherlands where disaggregated service contracting disrupts incumbent distribution relationships. Pursue direct-to-consumer digital launch with subscription financing to bypass capital-intensive retail network buildout.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underutilized e-bike divisions lacking dedicated management focus. Long-term viability hinges on battery chemistry transition execution and fleet service network density rather than hardware margins alone. Monitor silicon-anode qualification timelines at European premium OEMs as inflection indicator for competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Chemistry Transition | Silicon-anode qualification timelines determine 2027 model year range competitiveness against graphite legacy. |
| Direct-to-Consumer Channel Buildout | Digital sales platforms bypass traditional bike shop intermediaries that relied on bundled service margins. |
| Third-Party Maintenance Network | Independent service contracting meets corporate fleet demands for unbundled battery health monitoring. |
| Geographic Manufacturing Diversification | India's aluminum frame welding capacity reduces single-source exposure to Taiwanese supply chains. |
| Subscription Financing Model | Battery-as-a-service bundling separates hardware ownership from energy access for price-sensitive commuters. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with e-bike OEM product managers, fleet procurement officers at urban logistics operators, component supplier sales directors, and municipal mobility planners; alongside secondary validation through MIIT emissions filings, EU Green Deal subsidy disbursement records, KBA type-approval databases, and Korean cell manufacturer capacity announcements. Bottom-up triangulation against top-down market sizing cross-validated volume assumptions.
Forecast inputs span motor position segmentation, battery chemistry tiers, and target consumer archetypes across the projection horizon. Modeled dimensions include vehicle type, battery configuration, motor mounting architecture, and regional regulatory cluster. CAGRs derived from elasticity-adjusted adoption curves incorporating infrastructure investment trajectories and subsidy phase-out schedules. Lithium carbonate price scenarios and speed-limit regulatory divergence shaped sensitivity bounds.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by Asian scale manufacturers or accelerated solid-state battery commercialization would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Oman Electric Vehicle (EV) Market
Electric Vehicles
E-Axle Market
Electric Vehicles
Battery-Only Electric Bus Market
Electric Vehicles
Mexico E-Bike Market
Electric Vehicles
India Electric Rickshaw Market
Electric Vehicles
Europe Electric Vehicle Power Inverter Market
Electric Vehicles
Germany Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
One Wheel Electric Scooter Market
Electric Vehicles
Japan E-Bike Market
Electric Vehicles
Automotive Intelligent Battery Sensor Market
Electric Vehicles
Electric Bike Kit Market
Electric Vehicles
E-SUV Market
Electric Vehicles
Electric Vehicle Battery Enclosure Market
Electric Vehicles
E-Lock for Electric Vehicle Charging Market
Electric Vehicles
India Electric Car Market
Electric Vehicles
Vehicle Battery Market