
 India Electric Car Market | 2026-2036
India Electric Car Market Size, Share, and Industry Trends Forecast 2026-2036
India Electric Car Market Outlook
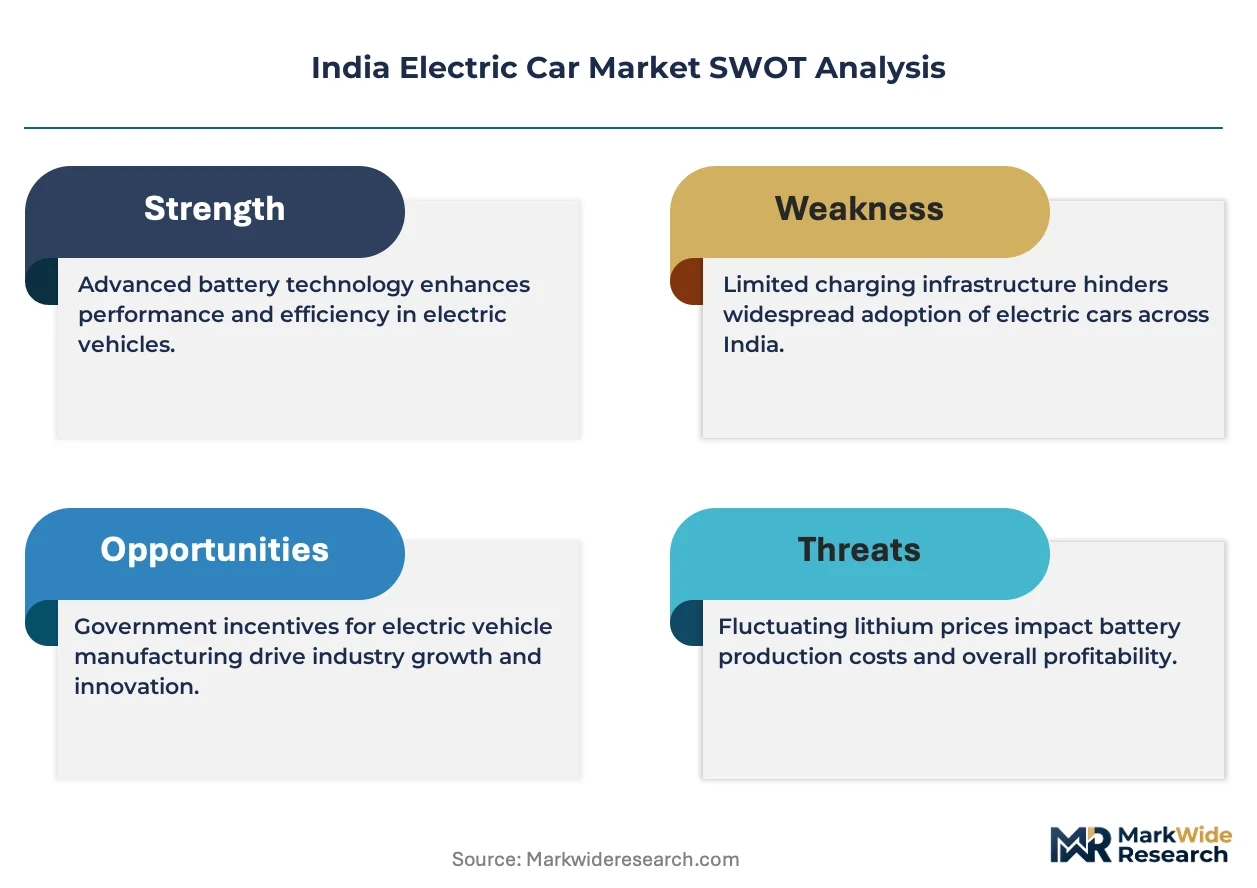
The FAME II subsidy framework is hardening the cost-of-entry calculus for imported electric vehicles versus locally assembled alternatives. Tata Motors leverages its captive battery cell partnership strategy to sustain price competitiveness across the hatchback and SUV portfolio. Mahindra Electric anchors its position in the utility vehicle segment through dedicated EV-native platforms. MG Motor India differentiates via premium feature stacking and connected-car technology in the crossover category.
An electric car is a battery-electric vehicle propelled by one or more electric motors drawing energy from rechargeable battery packs, typically lithium-ion configurations with energy densities exceeding 250 Wh/kg and operating voltages between 300-800V. Its primary commercial purpose is to deliver zero-tailpipe-emission personal mobility while reducing lifetime energy costs versus internal combustion equivalents. The SUV and crossover vehicle type captures disproportionate margin pools as Indian consumers prioritize ground clearance and cabin volume in electrified platforms. Corporate fleets and government agencies within the end user dimension expand faster than individual consumer channels due to bulk procurement protocols and mandated electrification targets for state transport undertakings. Fast charging infrastructure represents the structurally constrained segment where deployment lags vehicle sales, creating utilization bottlenecks in intercity corridors.
The Ministry of Heavy Industries administers FAME incentives while BIS enforces safety and performance standards for battery packs and charging systems. State-level EV policies in Maharashtra, Gujarat, and Karnataka layer additional demand-side subsidies and registration fee waivers atop central schemes. The Automotive Research Association of India conducts homologation testing that determines market access timelines for new electric vehicle models. Stakeholders must monitor whether PLI scheme disbursement timelines align with capacity ramp schedules and how state-level charging infrastructure tenders reshape geographic demand distribution.
Market Dynamics
The PLI scheme for automobile and auto component manufacturing is compressing effective production costs for domestic assemblers while hardening the cost-of-entry calculus for imported alternatives. Fleet operators in logistics and ride-hailing represent the fastest-expanding buyer segment as mandated electrification targets reshape procurement patterns.
Growth Catalysts
- FAME II subsidy framework:Central incentives reduce acquisition costs for locally assembled electric vehicles versus imported alternatives, tilting procurement decisions toward domestic manufacturing.
- State-level EV policies:Maharashtra, Gujarat, and Karnataka layer demand-side subsidies and registration fee waivers atop central schemes, creating concentrated demand pockets with superior infrastructure.
- Lithium-ion cell chemistry advances:Energy densities exceeding 250 Wh/kg enable extended range without proportional battery mass increases, addressing intercity range anxiety.
Market Restraints
- Fast charging infrastructure deployment lag:Utilization bottlenecks in intercity corridors constrain vehicle sales velocity despite manufacturing capacity expansion.
- Battery pack import concentration:Domestic cell production capacity trails vehicle assembly ramp schedules, creating input supply vulnerability.
- Homologation testing timelines:Automotive Research Association of India certification protocols extend market access timelines for new electric vehicle models.
Strategic Opportunities
- Corporate fleet electrification mandates:Bulk procurement protocols for state transport undertakings and logistics operators create volume commitments independent of consumer adoption curves.
- Charging infrastructure tenders:State-level deployment programs reshape geographic demand distribution toward corridor-connected districts.
- Utility vehicle platform specialization:EV-native architectures for SUVs and crossovers capture margin pools as Indian consumers prioritize ground clearance and cabin volume.
Industry Challenges
- Power electronics engineering scarcity:Inverter and motor controller design capabilities concentrate among limited specialist suppliers, constraining platform development velocity.
- High-voltage safety certification complexity:BIS standards for 300-800V operating systems require specialized testing infrastructure that extends development cycles.
- Legacy dealer network reconfiguration:Reduced after-sales service requirements for electric drivetrains disrupt traditional retail economics and technician training investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Electric Car Market |
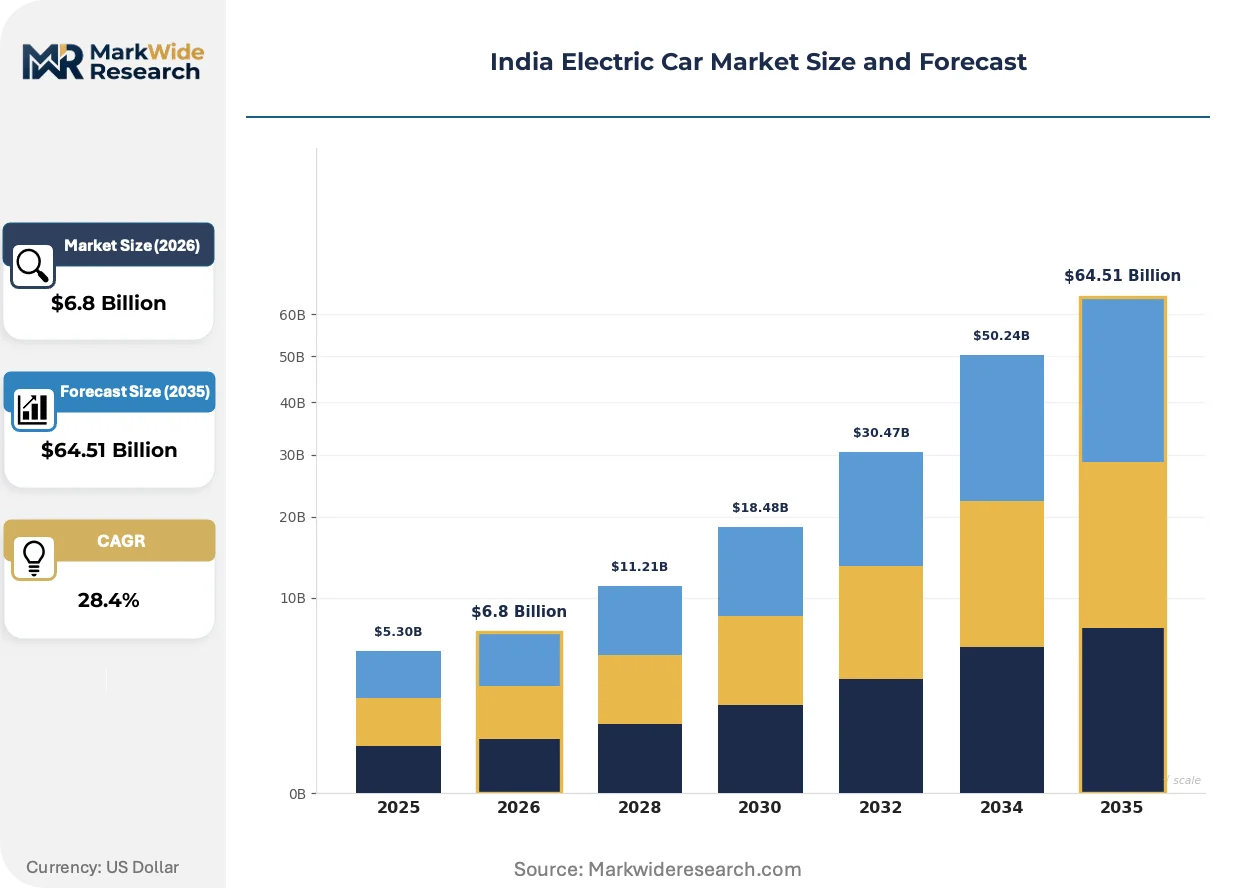
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $64.51 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, Hatchback, SUV, Crossover Battery Type: Lithium-Ion, Nickel-Metal Hydride, Lead-Acid, Solid-State Charging Infrastructure: Public Charging Stations, Home Charging, Fast Charging, Workplace Charging End User: Individual Consumers, Corporate Fleets, Car Rentals, Government Agencies |
| Companies Covered | Tata Motors, Mahindra Electric, Hyundai Motor India, MG Motor India, Kia India, Ola Electric Mobility, Ather Energy, JSW MG Motor India, TVS Motor Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Electric Car Market Strategic Shifts
Connected-car technology stacks are reshaping competitive differentiation as over-the-air updates and telematics-enabled services displace hardware specifications as primary purchase criteria. Battery-electric platforms are enabling cabin architecture reconfigurations that legacy internal combustion layouts cannot replicate.
Battery thermal management systems are converging with cabin climate control loops to reduce energy draw from traction batteries during extreme temperature conditions. Fleet operators with high daily utilization rates are adopting these integrated systems fastest. The technology is converging with predictive routing algorithms to precondition battery temperatures before charging stops, compressing effective charging duration and improving vehicle turnaround economics.
The Ministry of Heavy Industries has tightened FAME II localization requirements to mandate domestic battery pack assembly for subsidy eligibility. This industrial consequence forces importers to establish local assembly operations or forfeit price competitiveness. The SUV and crossover category is most affected as premium positioning previously justified imported powertrain costs.
Leasing structures are displacing outright purchase for corporate fleet channels as battery residual value uncertainty shifts financial risk from operators to lessors. Aggregators and logistics platforms are the segments being disrupted, with battery-as-a-service models replacing traditional vehicle finance. This shift is most visible in Maharashtra and Karnataka where state-level fleet electrification mandates coincide with established financial services infrastructure.
India Electric Car Market Segmentation
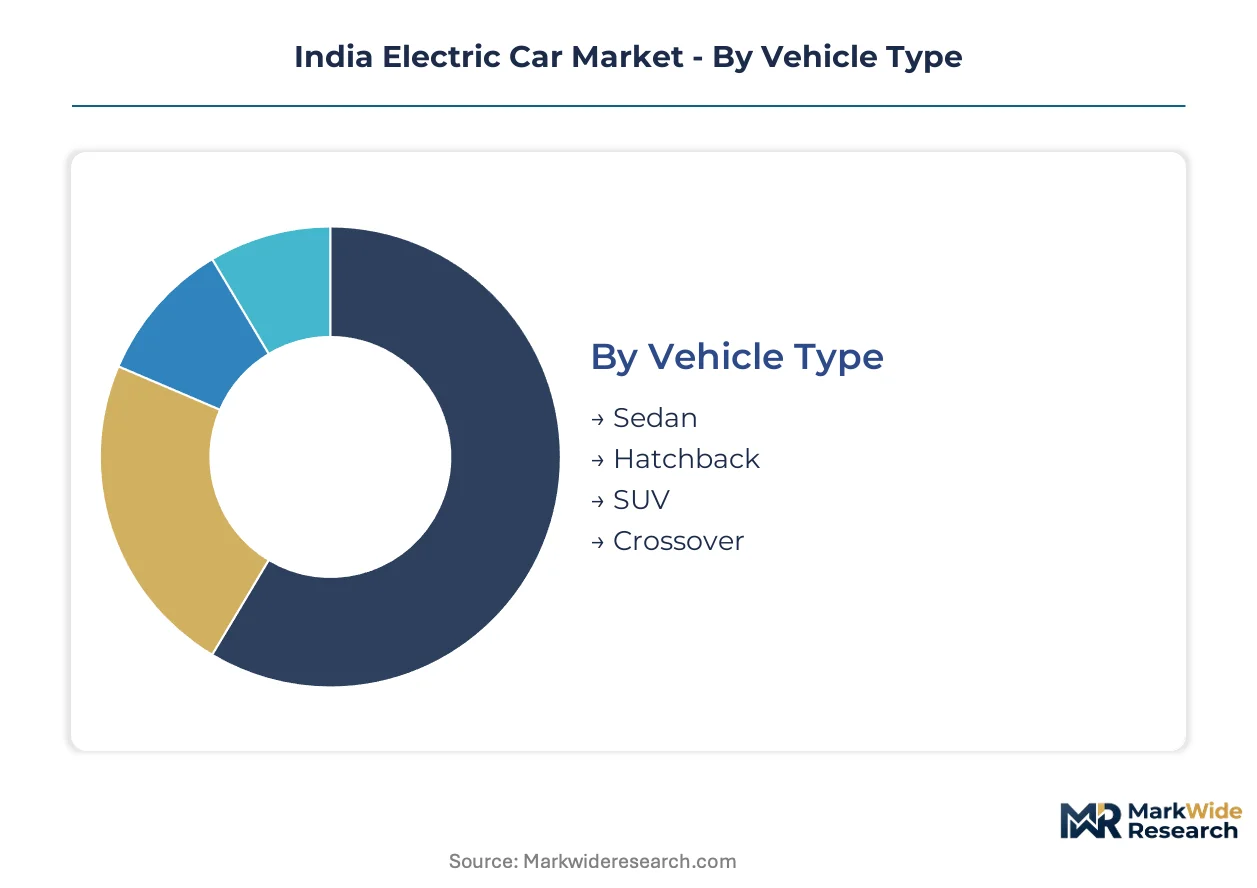
Segmentation reveals how electrification priorities diverge across use cases and infrastructure readiness in India. Vehicle type and end-user dimensions expose the deepest strategic fault lines for manufacturers and charging operators.
Vehicle Type:
The volume-premium split in India tilts toward utility-focused platforms where ground clearance and cabin space command pricing power.
- SUV:High-riding platforms with 300-800V architectures dominate margin pools. Demand concentrates in Maharashtra and Karnataka where state EV subsidies and superior highway connectivity support intercity use cases. Fleet operators in logistics prioritize these vehicles for payload flexibility and driver ergonomics.
- Hatchback:Compact battery-electric configurations with sub-40 kWh packs anchor urban penetration. Maharashtra and Gujarat absorb the highest volumes due to FAME II subsidy layering with state registration waivers. Individual consumers in dense metro corridors favor these for parking accessibility and maneuverability.
- Sedan:Three-box configurations with extended wheelbases serve premium fleet and executive mobility segments. Corporate leasing channels in Bengaluru and Mumbai drive procurement.
- Crossover:Coupe-SUV hybrids blend hatchback footprint with elevated seating position. Connected-car feature stacks differentiate offerings in this emerging category.
Mature deployment sits with hatchback platforms. Newer deployment is concentrated in SUV and crossover segments as consumer preferences shift toward commanding road presence.
Battery Type:
Chemistry selection tracks energy density requirements against localization mandates under FAME II subsidy rules.
- Lithium-Ion:NMC and LFP cell configurations exceeding 250 Wh/kg energy density power virtually all new electric car launches. Domestic pack assembly is now mandatory for subsidy eligibility, forcing importers to localize operations or forfeit price competitiveness.
- Solid-State:Next-generation electrolyte architectures promise enhanced thermal stability and faster charging rates. Pilot programs with fleet operators in high-utilization ride-hailing applications are testing pre-commercial prototypes.
- Nickel-Metal Hydride:Legacy chemistry persists in limited hybrid-electric conversions where cost sensitivity overrides performance requirements. Replacement demand is minimal.
- Lead-Acid:Low-voltage auxiliary systems and micro-hybrid starter applications represent residual demand. No traction battery deployment occurs in this segment.
Volume concentration favors lithium-ion across all vehicle classes. Technology migration is accelerating toward solid-state as BIS safety standards tighten for high-voltage systems.
Charging Infrastructure:
Access modality determines effective range utility and shapes purchase decisions across urban and intercity use patterns.
- Fast Charging:DC rapid installations with 50-350 kW output are the structurally constrained segment where deployment lags vehicle sales velocity. Utilization bottlenecks in intercity corridors constrain long-distance adoption despite manufacturing capacity expansion.
- Home Charging:AC Level 2 wallbox installations dominate residential parking in gated communities and independent housing. Apartment dwellers face access constraints that suppress adoption in dense urban cores.
- Public Charging Stations:Commercial parking-integrated infrastructure serves retail and hospitality destinations. State-level tenders in Gujarat and Maharashtra are reshaping geographic distribution toward corridor-connected districts.
- Workplace Charging:Employer-subsidized installations support commuter electric car adoption. Corporate campuses in Bengaluru and Hyderabad lead deployment.
Home charging anchors individual consumer adoption. Workplace and public infrastructure represent the fastest-expanding installation categories as fleet electrification mandates drive procurement.
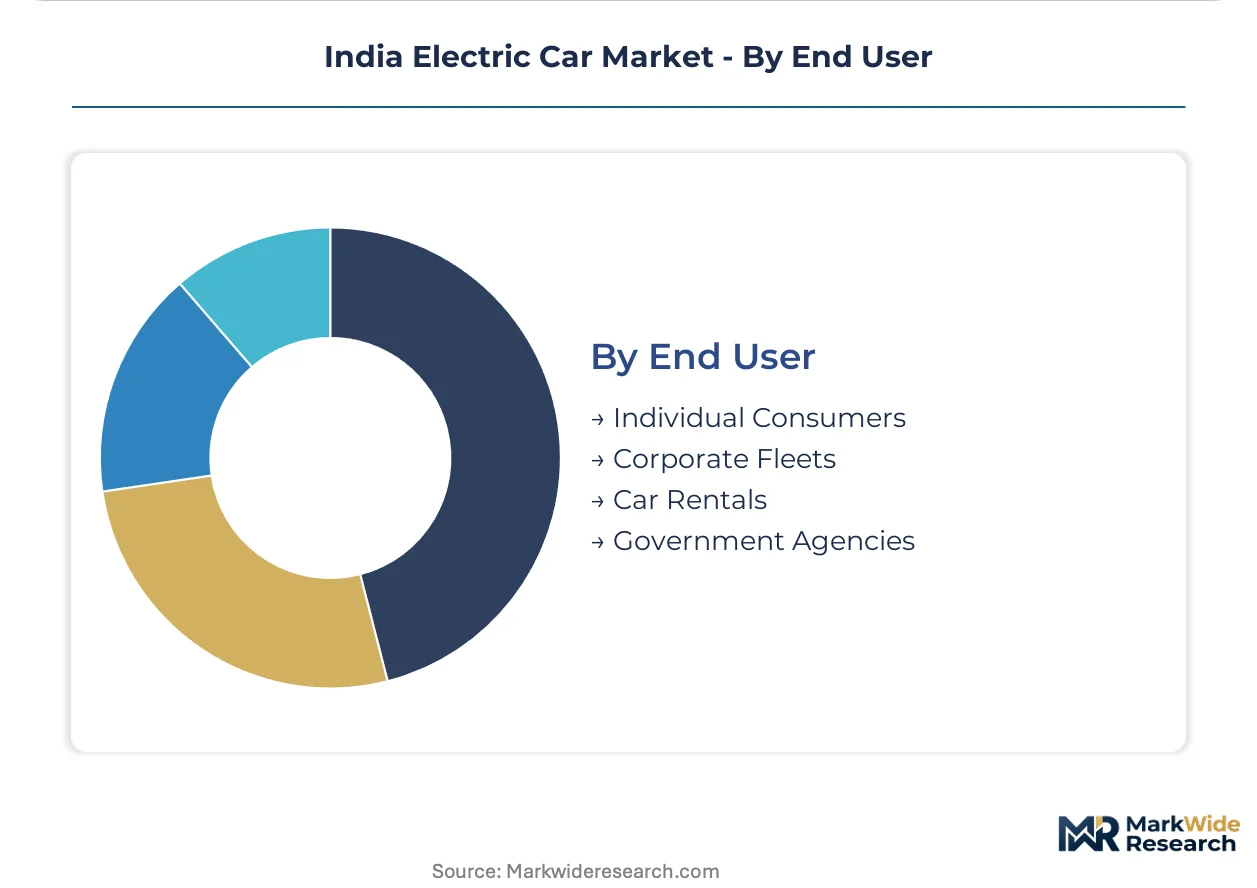
End User:
Procurement concentration diverges sharply between mandated fleet conversion and discretionary consumer purchase.
- Corporate Fleets:Logistics operators and ride-hailing aggregators with high daily utilization rates are expanding most quickly. Bulk procurement protocols and mandated electrification targets for state transport undertakings create volume commitments independent of consumer adoption curves.
- Government Agencies:Central and state vehicle replacement programs specify electric alternatives for official transport. Municipal corporations in Maharashtra and Karnataka lead tender volumes.
- Individual Consumers:Private purchase decisions remain sensitive to total cost of ownership calculations and charging access confidence. Urban professionals in metro markets drive early adoption.
- Car Rentals:Short-term mobility providers are trialing electric fleets in airport and intercity corridors. Battery residual value uncertainty constrains balance sheet deployment.
Fleet channels demonstrate mature procurement frameworks. Consumer retail is gaining traction fastest in premium SUV segments where feature differentiation offsets charging infrastructure gaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-level EV policies in Maharashtra, Gujarat, and Karnataka have established concentrated demand zones where PLI scheme benefits and registration fee waivers stack atop central FAME II incentives.
Maharashtra
Fleet electrification mandates for state transport undertakings and ride-hailing aggregators drive bulk procurement commitments. The state EV policy layers demand-side subsidies and road tax exemptions that compress total cost of ownership calculations. Mumbai-Pune corridor infrastructure deployment leads intercity charging network density.
Gujarat
Manufacturing incentives under the PLI scheme attract battery pack assembly investments from domestic and foreign automakers. State-level tenders for public charging stations reshape geographic distribution toward corridor-connected districts. Ahmedabad-Surat industrial belt concentrates EV component supplier ecosystems.
Karnataka
Corporate campuses in Bengaluru deploy workplace charging infrastructure that supports commuter electric car adoption. State EV policy registration fee waivers and FAME II subsidy stacking create concentrated demand pockets. Bengaluru-Mysuru highway fast-charging deployment addresses intercity range anxiety.
Tamil Nadu
Automotive component manufacturing heritage supports supplier base migration toward EV-native platforms. State industrial policy incentives complement central PLI scheme disbursement timelines. Chennai metropolitan charging infrastructure lags vehicle sales velocity despite manufacturing capacity expansion.
Delhi-NCR
Air quality mandates accelerate government agency vehicle replacement programs specifying electric alternatives. Municipal corporation tenders for fleet electrification create volume commitments independent of consumer adoption. Gurugram-Noida corridor workplace charging installations serve corporate commuter segments.
India Electric Car Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across vehicle assembly and component supply tiers. The market structure exhibits tiered consolidation where captive battery partnerships and EV-native platform investments separate scale leaders from follower positions. Strategic archetypes include integrated automakers with cell supply control, component specialists with power electronics capabilities, and ride-hailing aggregators with fleet deployment leverage. Capacity expansion and strategic partnerships constitute the dominant competitive moves as localization requirements harden under revised FAME II rules.
Within the integrated automaker tier, Tata Motors and Mahindra Electric anchor positions through distinct platform strategies. Tata Motors leverages captive battery cell partnerships to sustain price competitiveness across vehicle categories. Mahindra Electric occupies a position in utility vehicle segments through dedicated EV-native architectures. MG Motor India sits within the premium feature differentiation vector where connected-car technology stacks reshape purchase criteria.
| Leading Market Players |
|---|
| Tata Motors |
| Mahindra Electric |
| Hyundai Motor India |
| MG Motor India |
| Kia India |
| Ola Electric Mobility |
| Ather Energy |
| JSW MG Motor India |
| TVS Motor Company |
| Others |
Value Chain & Pricing Dynamics
Captive battery cell partnerships anchor both supply security and pricing power for domestic assemblers competing against import-dependent rivals. The PLI scheme for automobile manufacturing compresses input costs while FAME II localization mandates force pricing discipline on foreign competitors seeking subsidy access.
Pricing Analysis
Spot inventory availability commands premium positioning while extended lead-time orders trade at contracted discounts. Three-tier pricing structure across premium SUV, standard hatchback, and economy fleet segments reflects battery pack capacity and connected-car feature differentiation. Cost compression in the hatchback tier is intensifying because PLI disbursements are compressing domestic assembly economics faster than import cost structures. Fleet operators exhibit highest price sensitivity due to total cost of ownership procurement protocols, while individual consumers in premium segments show lowest sensitivity to acquisition price differentials.
Supply Chain Analysis
Lithium-ion cell supply rests on Chinese, South Korean, and Japanese specialty chemical producers with limited domestic alternatives. Battery pack assembly, power electronics, and thermal management systems represent critical input dependencies. Single-source vulnerability concentrates in high-voltage semiconductor components where inverter and motor controller design capabilities sit with limited specialist suppliers. Distribution runs through OEM captive networks for vehicle delivery and state-level tender programs for charging infrastructure deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around players with captive battery supply and EV-native platform investments. FAME II localization mandates are forcing import-dependent assemblers toward exit or partnership.
For Market Incumbents: Hedge against supply disruption by securing alternative cell chemistry partnerships beyond current NMC configurations. Deepen backward integration into battery pack assembly to maintain subsidy eligibility as BIS safety standards tighten. Threat substitution from solid-state pilot programs demands accelerated thermal management R&D investment. For New Entrants and Emerging Players: The PLI scheme in India opens a window for component specialists with power electronics capabilities to capture Tier 1 supplier positions. White-space sits in charging infrastructure deployment across corridor-connected districts in Gujarat and Tamil Nadu. Go-to-market through state-level tender participation bypasses consumer adoption uncertainty. For Investors and Strategic Acquirers: Exit pathways concentrate in platform technology licensing and charging infrastructure asset sales. Long-term viability favors specialists with EV-native architectures and captive battery partnerships over legacy internal combustion converters. Watch solid-state chemistry commercialization timelines as inflection indicator for incumbent valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Captive cell partnerships with PLI-qualified producers secure subsidy eligibility and cost competitiveness. |
| Platform Standardization | EV-native architectures reduce development cycle time and enable cabin reconfigurations impossible under legacy layouts. |
| Charging Infrastructure Partnership | State-level tender participation in Maharashtra and Karnataka reshapes geographic demand distribution. |
| Software-Defined Vehicle Investment | Over-the-air update capabilities displace hardware specifications as primary purchase criteria in premium segments. |
| Geographic Manufacturing Footprint | Gujarat and Tamil Nadu production clusters align with PLI disbursement timelines and component supplier ecosystems. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, state transport undertaking fleet managers, and charging infrastructure developers combined with secondary validation from SIAM production statistics, BIS certification databases, and FAME II disbursement records. Bottom-up vehicle registration analysis and top-down policy impact modeling provided triangulation.
Granularity-level modeling operated at vehicle class, battery chemistry, and end-user segment dimensions across the analysis window. CAGRs derived from production capacity ramp schedules, subsidy phase-out assumptions, and infrastructure deployment timelines. Industry-specific inputs included PLI scheme disbursement velocity, state-level EV policy stacking effects, and homologation testing backlog estimates.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery commercialization would alter the outlook. Forecasts reflect assumptions about FAME II localization compliance timelines and charging infrastructure deployment rates. Policy discontinuation, raw material price spikes, or grid reliability constraints warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
North America Electric Vehicle (EV) Fluids Market
Electric Vehicles
Electric Axle Drive Systems Market
Electric Vehicles
Cargo-to-Passenger Convertible eVTOL Cabin Systems Market
Electric Vehicles
Electric Passenger Cars Market
Electric Vehicles
Norway E-Bike Market
Electric Vehicles
Electric Vehicle Battery Enclosure Market
Electric Vehicles
Electric Two Wheelers MRO Market
Electric Vehicles
China Electric Vehicle Market
Electric Vehicles
Driveline Electric Vehicle Market
Electric Vehicles
EV Thermal System Market
Electric Vehicles
Lithium Battery Electric Scooters Market
Electric Vehicles
Middle-East and Africa E-Bike Market
Electric Vehicles
Premium Electric Motorcycle Market
Electric Vehicles
Electric Three Wheeler Market
Electric Vehicles
Electric Vehicle (EV) Range Extender Market
Electric Vehicles
Japan Solar E-Bike Market