
 New Zealand Used Car Market | 2026-2036
New Zealand Used Car Market Size, Share, and Industry Trends Forecast 2026-2036
New Zealand Used Car Market Insights
Rural fleet operators and agricultural contractors is pivoting toward used utes and SUVs as new vehicle lead times stretch and capital budgets tighten. Turners Cars leverages its nationwide auction network to control wholesale price discovery across the North Island. Armstrong's anchors premium certified pre-owned supply through its Auckland and Christchurch showrooms. The Colonial Motor Company competes by sustaining Toyota-certified used programmes that dominate hybrid resale values.
A used car denotes a previously registered motor vehicle sold through secondary channels, typically assessed by odometer reading, service history verification, and structural integrity inspection before resale. These vehicles serve price-sensitive buyers, fleet replacement cycles, and emission-transition pathways where new electric vehicle premiums remain prohibitive. SUV and hatchback segments lead transaction volumes as families downsize from new purchases and urban buyers prioritise parking efficiency. Hybrid fuel types capture expanding margin pools as Clean Car rebates reshape import eligibility criteria. Online platforms represent the fastest-growing sales channel, compressing dealer inventory cycles and expanding private seller reach beyond regional boundaries.
New Zealand's Clean Car Standard, administered by the Environmental Protection Authority, tightens CO2 thresholds on used imports and redirects dealer procurement toward Japanese and European low-emission stock. The NZ Transport Agency's WoF and licensing requirements enforce baseline safety standards that certified pre-owned programmes use as differentiation anchors. Stakeholders must monitor regulatory threshold adjustments and import age rule changes that could abruptly revalue eligible inventory or strand existing diesel-heavy dealer holdings.

Market Dynamics
The New Zealand Used Car Market is being fundamentally restructured by the Clean Car Standard's tightening CO2 thresholds, which redirect dealer procurement toward low-emission Japanese imports and compress the resale value of diesel-heavy inventory. This regulatory pressure cascades through auction networks, certified pre-owned programmes, and private seller channels alike.
Growth Catalysts
- Clean Car rebate scheme:The Environmental Protection Authority's incentive structure accelerates hybrid and electric used import eligibility, expanding addressable inventory for emission-transition buyers who cannot afford new EV premiums.
- Rural agricultural contractors:Fleet operators in Canterbury and Waikato regions pivot toward used utes as new vehicle lead times stretch and capital budgets tighten, sustaining wholesale auction volumes.
- Digital listing platforms:Online marketplaces compress dealer inventory cycles and extend private seller reach beyond regional boundaries, unlocking liquidity in previously isolated South Island trading nodes.
Market Restraints
- Import age restrictions:The NZ Transport Agency's vehicle entry standards strand older diesel stock in dealer holdings, forcing accelerated depreciation on non-compliant inventory before regulatory deadlines.
- Japanese auction concentration:Over 70% of used import supply originates from USS and JU Group auction houses in Japan, exposing New Zealand dealers to yen volatility and shipping bottlenecks.
- Battery degradation uncertainty:Hybrid and early electric vehicles lack standardized state-of-health certification, creating information asymmetry that suppresses resale values and extends buyer due diligence timelines.
Strategic Opportunities
- South Island expansion:Christchurch and Dunedin trading nodes remain underpenetrated relative to Auckland's metropolitan corridor, offering first-mover advantages for digital-first dealers with logistics integration.
- Warrant of Fitness data monetization:Aggregated WoF inspection histories from NZ Transport Agency records enable predictive pricing models and certified pre-owned differentiation.
- Utility vehicle electrification:Battery-electric utes entering the Japanese auction pipeline create early-adopter segments among rural contractors seeking to decarbonize fleet operations.
Industry Challenges
- Technician certification gaps:Hybrid and EV diagnostics require specialized training that traditional mechanical workshops lack, constraining after-sales service capacity for electrified used inventory.
- Cross-border title verification:Japanese export documentation inconsistencies delay NZ border clearance, extending working capital cycles for import-dependent dealers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | New Zealand Used Car Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, SUV, Hatchback, Coupe Fuel Type: Petrol, Diesel, Hybrid, Electric Condition: Certified Pre-Owned, Used, Repaired, Salvage Sales Channel: Dealerships, Private Sellers, Auctions, Online Platforms |
| Companies Covered | Turners Cars, Armstrong's, The Colonial Motor Company, Auto Trader NZ, Devonport Car Company, Auckland City Toyota, Armstrong's Certified Used, Todd Corporation, Lewis Rowe Cars, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
New Zealand Used Car Market Trends and Innovations
Digital auction infrastructure and emission-linked pricing algorithms are compressing price discovery timelines and rewiring buyer-seller matching across the New Zealand Used Car Market. These shifts favor platforms with real-time inventory visibility and regulatory compliance automation.
Telematics-enabled condition scoring is electrifying trust formation between distant buyers and sellers. Japanese auction houses now embed odometer-verification and collision-history data directly into export documentation. Canterbury fleet buyers increasingly rely on these digital proxies to transact without physical inspection. This compression of due diligence is electrifying cross-regional trade volumes that previously required dealer intermediation.
The Environmental Protection Authority's quarterly CO2 threshold adjustments create a moving compliance target for import eligibility. Dealers must recalibrate procurement algorithms monthly to avoid stranding capital in non-compliant stock. Auckland-based wholesalers respond by shortening inventory holds and accelerating auction turnover, passing compliance risk to downstream retail channels.
Rural buyers are consolidating purchasing authority through contractor cooperatives that negotiate volume discounts directly with Japanese auction agents. This disintermediation bypasses traditional North Island wholesale layers and compresses margin capture for established dealer networks. The pattern is most visible in Otago and Southland, where agricultural contractor associations now maintain dedicated import agents in Osaka.
New Zealand Used Car Market Segmentation

New Zealand's used car market segments reveal how regulatory pressure and buyer economics reshape inventory procurement. The Clean Car Standard's CO2 thresholds force dealers to recalibrate sourcing across every dimension of vehicle classification.
Vehicle Type:
Supply concentrates in utility-focused body styles that serve rural contractors and metropolitan families with divergent priorities.
- SUV:Higher ride height and cargo capacity suit Canterbury agricultural fleets and Auckland suburban households navigating deteriorating road infrastructure. Dealers prioritize Japanese auction sourcing of compact and mid-size SUVs to capture the largest transaction volume pool.
- Hatchback:Parking efficiency and fuel economy dominate urban buyer calculus in Wellington and Auckland's dense metropolitan corridors. Import eligibility under Clean Car thresholds favors smaller-displacement Japanese hatchbacks with lower CO2 ratings.
- Sedan:Declining preference among family buyers limits wholesale auction liquidity outside fleet disposal channels.
- Coupe:Niche enthusiast segment with concentrated demand in Auckland's premium certified pre-owned showrooms.
Today's leader: SUV. Tomorrow's challenger: Hatchback.
Fuel Type:
Cost tier stratification separates compliance-viable imports from depreciating diesel holdings that face regulatory stranding.
- Hybrid:Toyota Aqua and Honda Fit hybrids dominate Japanese auction pipelines eligible for Clean Car rebates. Canterbury contractor cooperatives increasingly specify hybrid utes for fleet decarbonization pathways.
- Petrol:Established service infrastructure and technician familiarity sustain liquidity across South Island rural markets where EV charging remains sparse.
- Diesel:Accelerated depreciation pressure from import age restrictions compresses resale values for non-compliant utes and SUVs.
- Electric:Battery degradation uncertainty and sparse charging infrastructure in Otago and Southland suppress secondary market liquidity despite rebate eligibility.
Hybrid holds current volume leadership. Electric presents the steepest expansion trajectory contingent on charging infrastructure rollout and battery health certification standardization.
Condition:
Volume concentrates in certified programmes that monetize WoF inspection data and service history verification.
- Certified Pre-Owned:Manufacturer-backed warranties and structured inspection protocols command pricing premiums in Auckland and Christchurch showrooms. The NZ Transport Agency's WoF requirements provide baseline differentiation anchors.
- Used:Unverified private sales dominate South Island trading nodes where digital platform penetration remains below North Island levels.
- Repaired:Structural integrity disclosure requirements limit dealer participation; concentrated in private seller channels.
- Salvage:Parts recovery and export markets absorb damaged vehicles that fail border compliance standards.
Certified Pre-Owned captures margin leadership. Used represents volume depth.
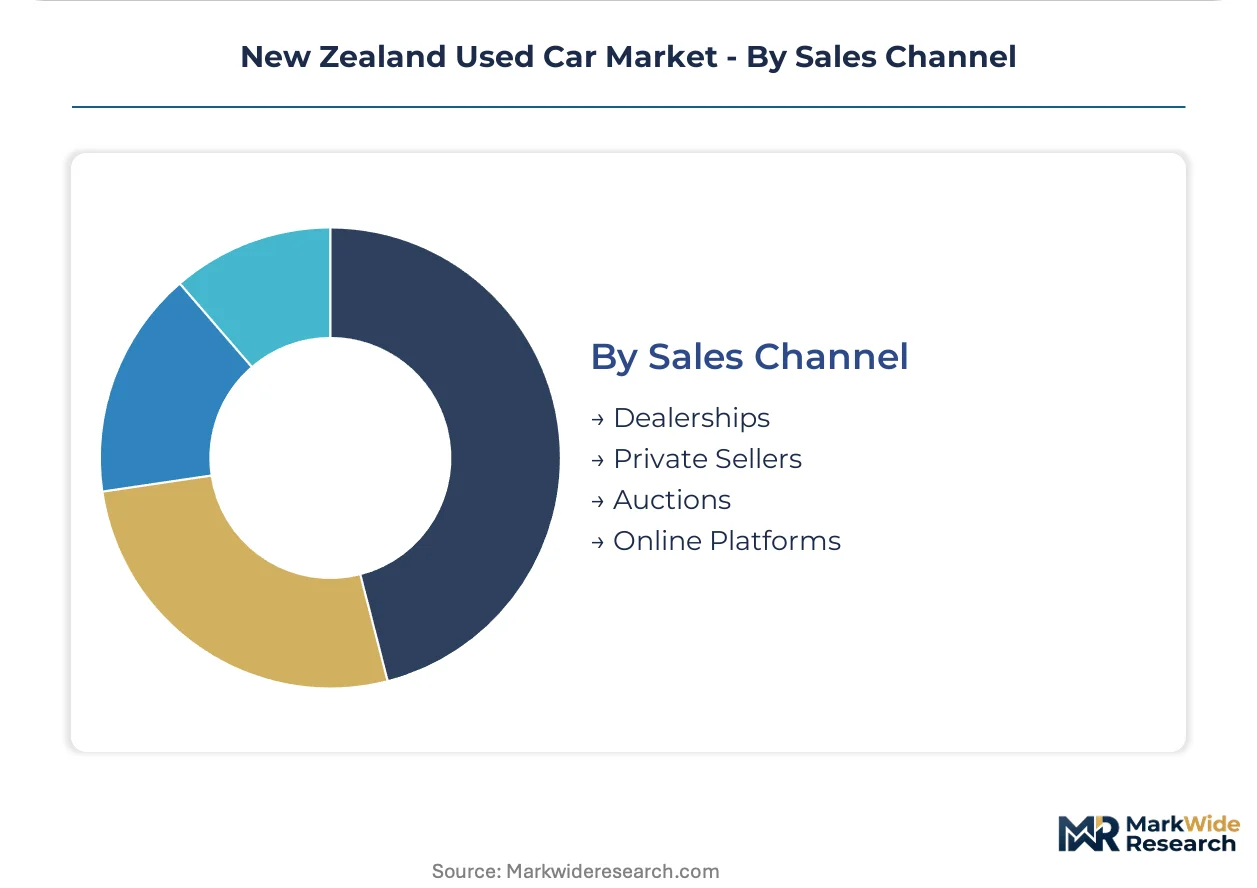
Sales Channel:
Customer type fragmentation separates institutional fleet disposal from individual buyer search behavior.
- Online Platforms:Real-time inventory visibility and regulatory compliance automation compress price discovery timelines. Turners Cars leverages nationwide auction networks to integrate digital listing with physical inspection infrastructure.
- Dealerships:Certified pre-owned programmes and trade-in facilitation sustain foot traffic in Auckland's metropolitan corridor.
- Auctions:Wholesale price discovery for dealer inventory acquisition concentrates in North Island trading nodes with Japanese auction house relationships.
- Private Sellers:Geographic isolation in South Island regions constrains liquidity without platform intermediation.
Online Platforms are gaining share fastest. Dealerships defend margin through certification differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dealer procurement algorithms recalibrate monthly as the Environmental Protection Authority's CO2 thresholds shift, redirecting import flows toward compliant Japanese auction pipelines and compressing margin capture in non-compliant diesel corridors.
Auckland Metropolitan Corridor
Auckland commands inventory turnover velocity unmatched elsewhere, with digital listing volumes and certified pre-owned showroom density concentrating wholesale price discovery. The NZ Transport Agency's WoF enforcement tightest here, enabling Armstrong's and Turners Cars to monetize inspection data as differentiation anchors. North Island auction networks route Japanese imports through Auckland before South Island distribution.
Canterbury Region
Rural agricultural contractors in Canterbury sustain demand for used utes as capital budgets tighten and new vehicle lead times stretch. The Clean Car Standard's rebate eligibility criteria redirect contractor cooperatives toward hybrid utility vehicles from Japanese auction pipelines. Christchurch anchors South Island certified pre-owned penetration, though digital platform liquidity trails Auckland benchmarks.
Waikato Region
Fleet operators across Waikato pivot toward emission-transition pathways as diesel depreciation accelerates under import age restrictions. The Environmental Protection Authority's quarterly threshold adjustments force dealers in Hamilton to shorten inventory holds. Japanese auction house relationships concentrated here facilitate direct procurement bypassing Auckland wholesale layers.
Otago and Southland
Geographic isolation constrains liquidity without platform intermediation, yet agricultural contractor cooperatives now maintain dedicated import agents in Osaka. The NZ Transport Agency's sparse regional office footprint delays border clearance documentation. Dunedin trading nodes remain underpenetrated relative to northern benchmarks, offering first-mover positioning for logistics-integrated digital dealers.
New Zealand Used Car Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with nationwide auction networks commanding wholesale price discovery while certified pre-owned programmes defend margin through manufacturer-backed warranties. Market structure tilts toward consolidated platform control in Auckland and Christchurch, fragmented private seller channels dominating South Island rural nodes. Three archetypes predominate: integrated auction-dealer hybrids, OEM-certified programme operators, and digital marketplace pure-plays. Competitive moves concentrate on logistics integration into Japanese auction pipelines and predictive pricing algorithm deployment.
Within the integrated auction-dealer tier, Turners Cars exemplifies nationwide physical infrastructure married to digital listing scale, while The Colonial Motor Company anchors OEM-certified positioning through Toyota-backed used programmes. Armstrong's occupies the premium certified pre-owned vector with Auckland and Christchurch showroom concentration. These three represent distinct margin-defense strategies against rural cooperative disintermediation and platform compression.
| Leading Market Players |
|---|
| Turners Cars |
| Armstrong's |
| The Colonial Motor Company |
| Auto Trader NZ |
| Devonport Car Company |
| Auckland City Toyota |
| Armstrong's Certified Used |
| Todd Corporation |
| Lewis Rowe Cars |
| Others |
Pricing and Supply Chain Analysis
Certified-versus-uncertified inventory divergence splits New Zealand's used car market into parallel pricing corridors, with Environmental Protection Authority compliance tiers dictating both wholesale auction premiums and Japanese import procurement priorities. Dealers holding Clean Car-eligible hybrid stock command margin pools unavailable to diesel-heavy holdings facing accelerated depreciation, while rural buyer cooperatives bypass traditional markup layers through direct Osaka auction relationships.
Pricing Analysis
Retailer markup compression dominates transaction economics as digital platforms erode geographic pricing power previously held by Auckland showroom networks. Three-tier pricing structure across certified pre-owned, auction-sourced dealer inventory, and private seller channels reflects WoF verification depth and odometer authentication rigor. Pricing pressure stems from yen volatility amplifying landed cost uncertainty for Japanese auction-dependent dealers. Fleet buyers in Canterbury agricultural cooperatives exhibit highest price sensitivity, while Auckland metropolitan households seeking hybrid SUVs show lowest elasticity.
Supply Chain Analysis
Dual-sourcing requirements from rural contractor cooperatives now mandate relationships with both USS and JU Group auction houses to secure volume allocation. New Zealand's import pipeline draws from Japan's concentrated auction infrastructure, with secondary feedstock from Australian fleet disposal channels and Singapore re-export hubs. Battery-electric utes and hybrid utility vehicles constitute critical component dependencies facing allocation competition from Japanese domestic buyers. Single-source vulnerability concentrates in yen-denominated procurement contracts. Distribution runs through Auckland port clearance before South Island rail and road forwarding.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
New Zealand's used car market functions as a regulatory compounder where Environmental Protection Authority CO2 threshold adjustments revalue inventory holdings quarterly and redirect procurement algorithms toward compliant Japanese auction pipelines.
For Market Incumbents: Deepen WoF data monetization capabilities to defend certified pre-owned premiums against digital platform disintermediation. Invest in predictive pricing algorithms that incorporate quarterly Clean Car threshold adjustments. Secure captive supply relationships with Osaka auction agents before rural cooperative buying groups consolidate import authority.
For New Entrants and Emerging Players: Battery health certification technology offers a technology-first wedge into hybrid and early electric vehicle segments where information asymmetry suppresses resale values. Target Dunedin and Invercargill trading nodes where platform penetration trails Auckland benchmarks. Deploy telematics-enabled condition scoring as a trust-formation layer for cross-regional transactions without physical inspection infrastructure.
For Investors and Strategic Acquirers: Consolidation pressure builds where logistics-integrated digital dealers can capture South Island market share from fragmented private seller channels. Long-term viability favors platforms with Japanese auction house relationships and regulatory compliance automation. Watch Environmental Protection Authority import age rule changes as the inflection signal that would abruptly revalue dealer inventory portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Japanese Auction Pipeline Integration | Direct USS and JU Group relationships secure volume allocation ahead of rural cooperative disintermediation. |
| WoF Data Monetization Platform | NZ Transport Agency inspection histories enable predictive pricing models that defend certified pre-owned premiums. |
| Battery Health Certification Service | Standardized state-of-health reporting addresses information asymmetry suppressing hybrid resale values. |
| South Island Logistics Network | Christchurch and Dunedin distribution nodes capture underpenetrated trading volumes beyond Auckland concentration. |
| Clean Car Compliance Automation | Real-time CO2 threshold monitoring prevents capital stranding in non-compliant diesel inventory holdings. |
Research Methodology
Bottom-up dealer inventory modeling reconciled against top-down Japanese auction import tracking forms the analytical core of this study. Primary interviews with auction network directors, certified pre-owned programme managers, rural fleet procurement officers, and NZ Transport Agency compliance administrators combined with secondary validation from customs clearance records, Environmental Protection Authority CO2 threshold bulletins, and vehicle registration databases. Triangulation across wholesale price indices, digital platform transaction logs, and cooperative buying group import volumes anchored volume estimates.
Input-output matrices mapped vehicle type, fuel category, condition tier, and sales channel dimensions across the projection horizon. CAGRs derived from regression analysis against Clean Car rebate uptake trajectories and rural capital expenditure cycles. Segmentation modeling incorporated propulsion architecture shifts, certification grade stratification, and regional platform penetration differentials. Forecast inputs included quarterly Environmental Protection Authority threshold adjustment schedules and yen exchange rate volatility bands.
The model holds under stable Clean Car Standard implementation; deviation in import age restriction tightening or battery health certification mandate introduction would shift the outlook materially. Forecasts reflect assumptions regarding Japanese auction house supply continuity and South Island charging infrastructure rollout pace. Deviation in rural cooperative import agent consolidation would shift wholesale margin capture toward buyer-side concentration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Used Vehicles
Indonesia Used Car Market
Used Vehicles
Canada Used Car Market
Used Vehicles
Kuwait Used Car Market
Used Vehicles
Spain Used Car Market
Used Vehicles
Italy Used Car Market
Used Vehicles
India Used Car Market
Used Vehicles
Used E-Scooter Market
Used Vehicles
Switzerland Used Car Market
Used Vehicles
Vietnam Used Car Market
Used Vehicles
Nigeria Used Car Market
Used Vehicles
North America Used Car Market
Used Vehicles
North America Used Truck Market
Used Vehicles
Used Cars in Russia Market
Used Vehicles
Russia Used Car Market
Used Vehicles
Australia Used Car Market
Used Vehicles
United Arab Emirates Used Car Market