
 Automotive Bicycle Rack Market | 2026-2036
Automotive Bicycle Rack Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Bicycle Rack Market Analysis
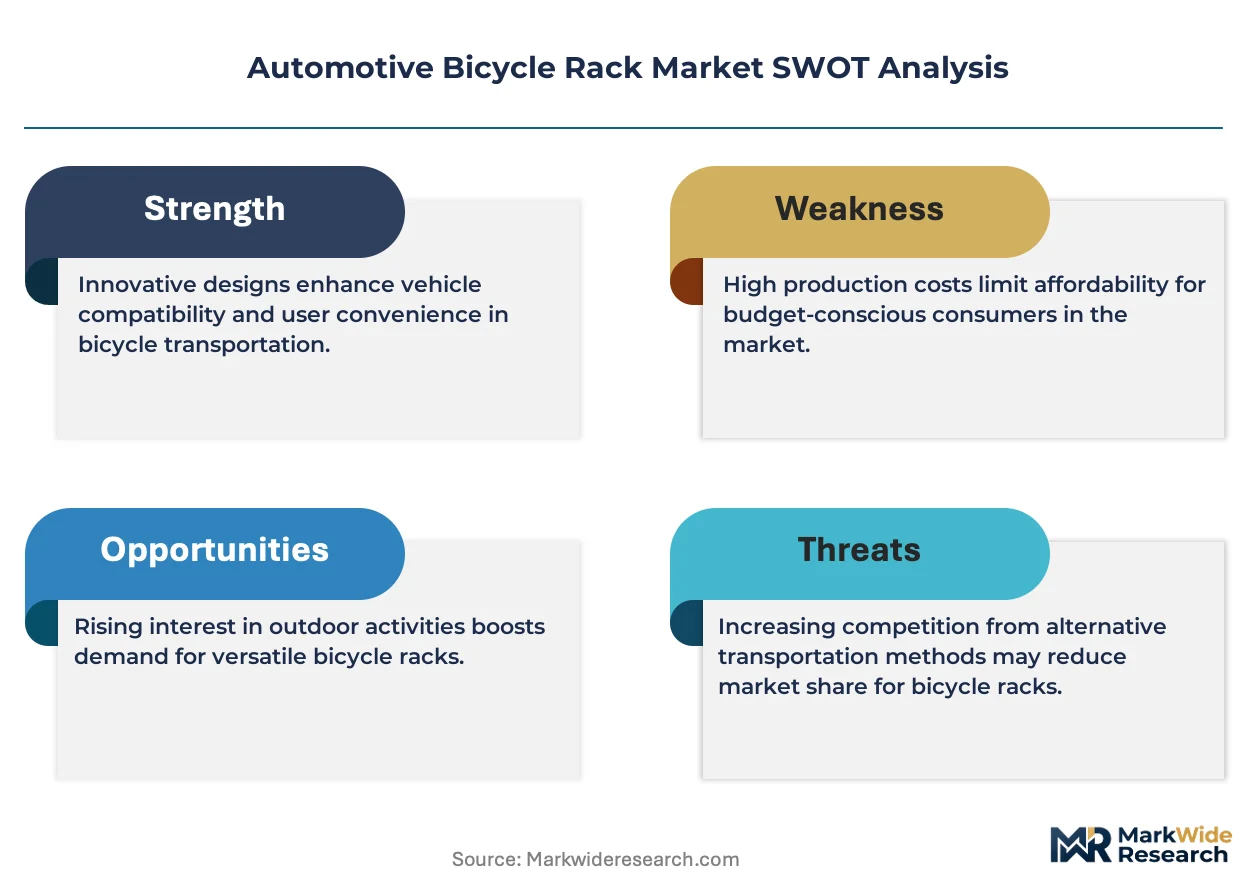
Outdoor enthusiasts is collapsing as the dominant buyer archetype while commercial fleet operators gain share in the Automotive Bicycle Rack Market. Thule Group leverages its European manufacturing footprint to sustain premium positioning across hitch-mount systems. Yakima Products competes through specialized roof-rack engineering for adventure tourism operators. Saris Cycling Group anchors its presence in the North American retail channel with removable installation designs.
An automotive bicycle rack is a vehicle-mounted carrier system, typically fabricated from aluminum extrusions or steel tubing with polymer joint components, engineered to secure bicycles during transit via clamping mechanisms or wheel trays. Hitch-mount configurations dominate volume due to load-capacity advantages, while carbon-fiber variants command concentrated margin pools in the performance segment. Aluminum racks lead material demand for weight-sensitive applications, whereas trunk-mount systems retain share among price-sensitive retail consumers seeking removable installation.
NHTSA and FMVSS standards in the United States govern dynamic load testing and crashworthiness, compelling manufacturers to validate structural integrity under simulated collision forces. The EU Green Deal and REACH chemical compliance in Europe restrict certain polymer additives and surface coatings, elevating material substitution costs for suppliers serving dual markets. Stakeholders must monitor evolving type-approval harmonization between federal motor vehicle standards and emerging e-bike weight classifications to anticipate platform redesign cycles.
Market Dynamics
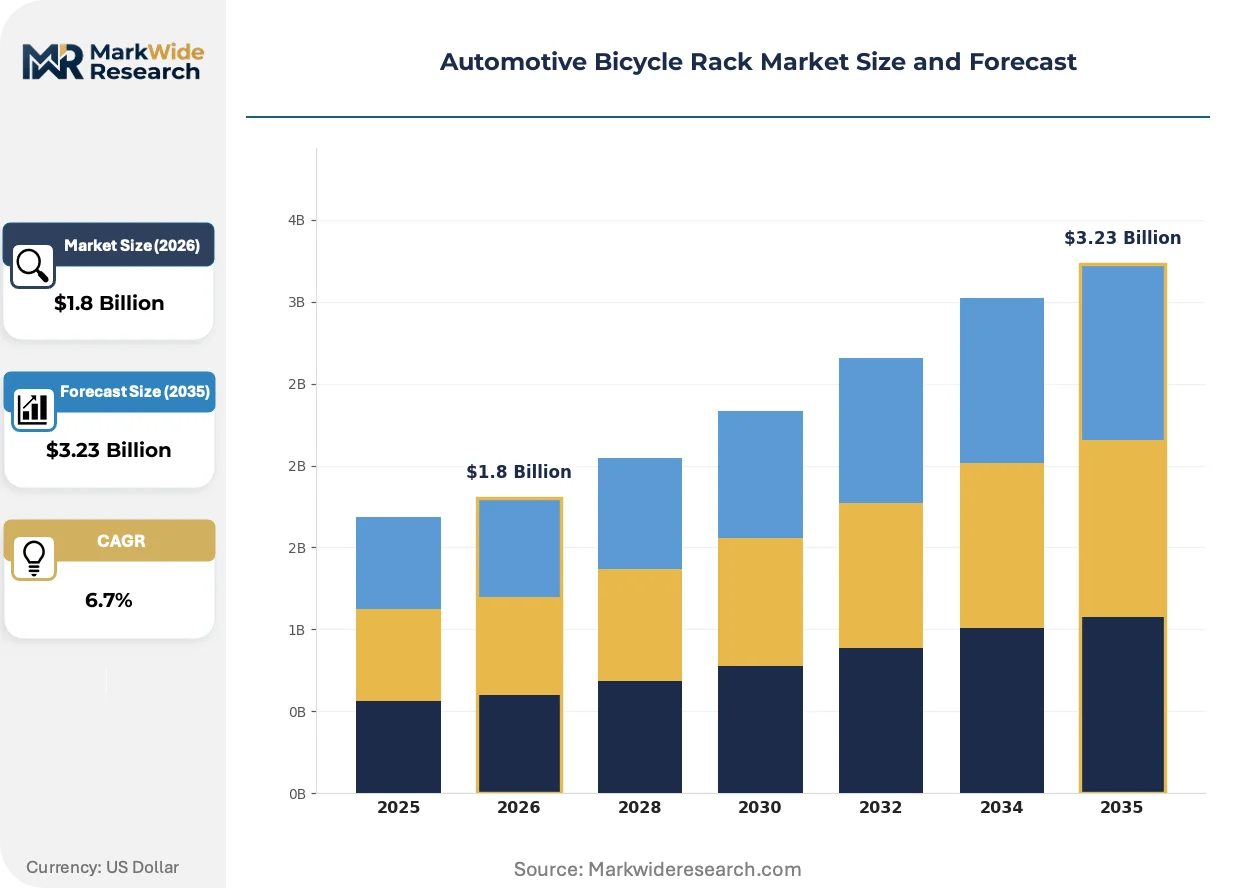
The Automotive Bicycle Rack Market pivots on e-bike weight classifications forcing platform redesigns, as manufacturers reconcile legacy hitch-mount architectures with battery-assisted bicycle loads that exceed traditional structural ratings.
Growth Catalysts
- E-bike penetration in suburban households:Battery-assisted bicycles now constitute the fastest-growing bicycle category, expanding addressable rack demand beyond traditional mechanical cycles.
- NHTSA FMVSS roof-rack provisions:Federal motor vehicle safety standards mandate dynamic load testing, creating compliance barriers that favor established engineering capabilities and consolidate procurement toward certified suppliers.
- REACH chemical compliance in Europe:Restrictions on polymer additives and surface coatings accelerate material substitution programs, rewarding suppliers with in-house polymer chemistry expertise.
Market Restraints
- Aluminum extrusion cost volatility:Primary aluminum pricing sensitivity compresses margin pools for mid-tier manufacturers lacking long-term smelter contracts.
- Supply concentration in German distribution:Thule Group and Atera GmbH anchor European logistics networks, creating channel access barriers for new entrants.
- Trunk-mount load limitations:Structural capacity caps on strap-based systems restrict adoption among e-bike owners, segmenting the market by bicycle type compatibility.
Strategic Opportunities
- Carbon-fiber performance segment expansion:Weight-sensitive applications in adventure tourism and professional cycling teams command premium pricing with limited supplier competition.
- EU Green Deal circular economy requirements:End-of-life recycling mandates for automotive accessories create first-mover advantages for rack manufacturers with disassembly-ready designs.
- Commercial fleet operator channel:Bike-share and rental fleet procurement represents an underpenetrated vertical with consolidated volume potential and multi-year contract structures.
Industry Challenges
- E-bike weight classification harmonization:Divergent national standards for battery-assisted bicycle categorization complicate platform engineering and type-approval timelines.
- Polymer joint fatigue testing:Accelerated lifecycle validation for UV-exposed polymer components extends product development cycles and increases R&D capex intensity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Bicycle Rack Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hitch Mount, Trunk Mount, Roof Mount, Spare Tire Mount Material: Aluminum, Steel, Plastic, Carbon Fiber End User: Retail Consumers, Commercial Fleets, Local Governments, Rental Services Installation Type: Permanent, Removable, Adjustable, Fixed |
| Companies Covered | Thule Group, Yakima Products, Saris Cycling Group, Kuat Innovations, Allen Sports, Hollywood Racks, RockyMounts, Atera GmbH, Rhino Rack, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Bicycle Rack Market Emerging Trajectories
Active materials substitution and regulatory chemistry constraints are restructuring competitive positioning in rack manufacturing, while procurement patterns among fleet buyers compress traditional retail channel dominance.
Carbon-fiber reinforced polymer construction is bifurcating the performance segment from mass-market aluminum systems. Professional cycling teams and adventure tourism operators adopt carbon-fiber platforms for weight-critical applications. This technology is bifurcating supplier tiers into premium engineering specialists and commodity metal fabricators with limited polymer expertise.
REACH chemical compliance and EU Green Deal circular economy mandates restrict halogenated flame retardants and certain epoxy formulations in polymer joint components. European manufacturers face elevated reformulation costs to maintain dual-market access. Germany-based suppliers respond fastest due to proximity to ECHA technical guidance and established recycling infrastructure partnerships.
Fleet procurement consolidation is displacing individual consumer purchases as the dominant volume driver. Commercial bike-share and rental operators negotiate multi-year supply agreements with integrated service provisions. North American fleet managers lead this behavioral shift, demanding predictive maintenance telemetry and rapid-swap installation systems unavailable through traditional outdoor retail channels.
Automotive Bicycle Rack Market Segmentation
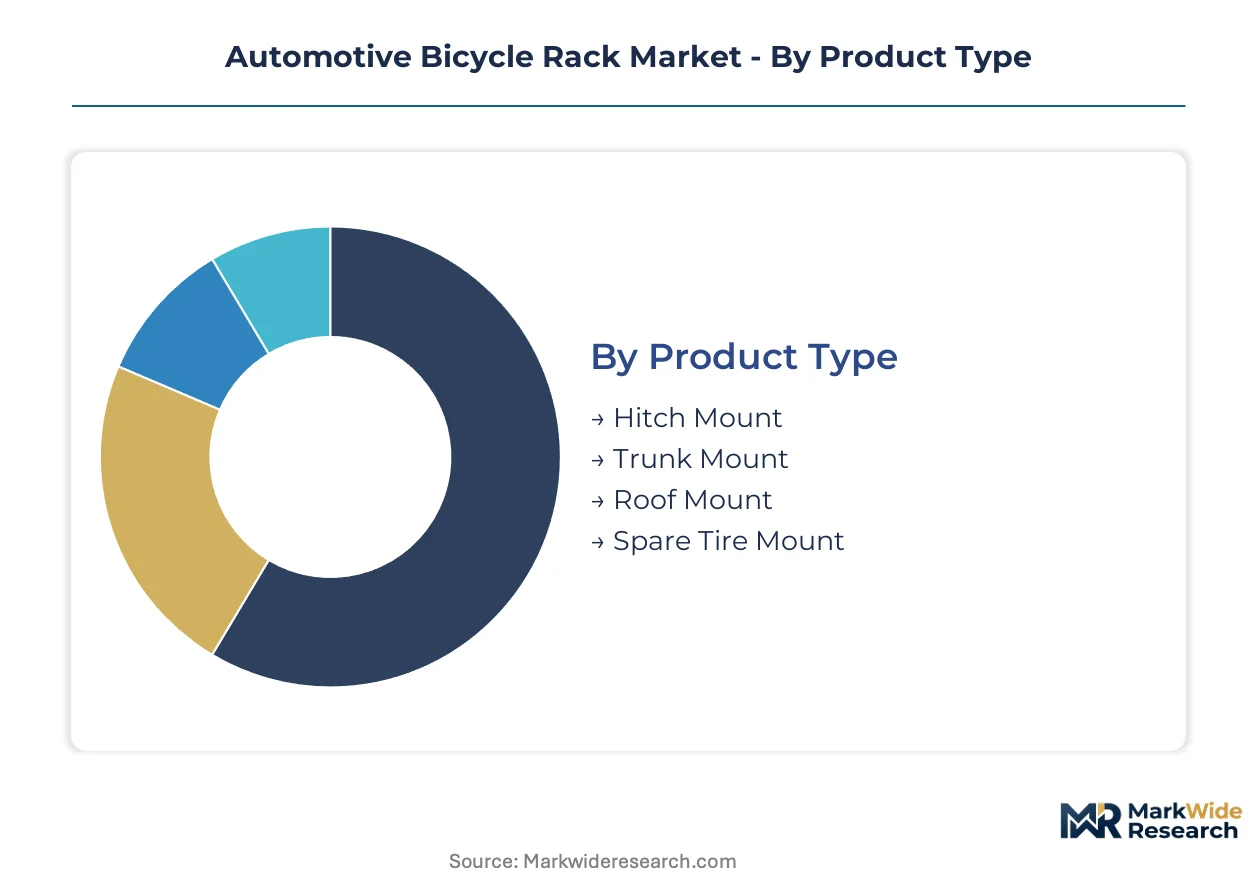
Automotive bicycle rack segmentation reveals how regulatory load-rating requirements and bicycle weight classifications reshape procurement patterns across installation methods and material choices. Manufacturers must engineer platform-specific solutions as e-bike penetration forces structural redesigns across all product categories.
Product Type:
NHTSA FMVSS provisions in the United States and Germany's KBA type-approval standards create divergent engineering requirements that favor hitch-mount architectures in North America while roof-mount systems retain preference in European urban centers with strict rear-visibility regulations.
- Hitch Mount:Fabricated from steel tubing or aluminum extrusions with receiver-tube interfaces rated for Class I through IV towing capacities. Demand concentrates among suburban households in the United States where pickup trucks and SUVs provide standard receiver hitches, driven by load-capacity advantages for e-bike transport.
- Roof Mount:Constructed from aluminum crossbars with wheel-tray or fork-mount clamping mechanisms engineered for aerodynamic efficiency. Adoption clusters in Germany and the Netherlands where underground parking height restrictions and rear-visibility regulations discourage hitch systems, constrained by lifting-height accessibility for heavier e-bikes.
- Trunk Mount:Strap-based polymer and steel frame configurations with adjustable contact points for sedan and hatchback compatibility. Popular among price-sensitive retail consumers in France and Italy seeking removable installation without vehicle modification.
- Spare Tire Mount:Hinged or fixed brackets designed for rear-mounted spare tire integration, primarily serving Jeep Wrangler and similar off-road vehicle owners in the United States with aftermarket tire carrier modifications.
Hitch Mount handles the majority of throughput; Roof Mount is the fastest mover on share.
Material:
Cost tier differentiation separates premium engineering investments from commodity fabrication, with aluminum commanding mid-market positioning and carbon fiber capturing performance-segment margins.
- Aluminum:Extruded 6061-T6 or 6005A alloys with anodized surface treatments dominate weight-sensitive applications. Demand concentrates in Germany where REACH chemical compliance elevates material substitution costs, driven by corrosion resistance requirements for year-round outdoor exposure.
- Carbon Fiber:Pre-preg layup or resin-transfer molding with epoxy matrices delivers strength-to-weight ratios critical for professional cycling team logistics. Adoption accelerates among adventure tourism operators in Switzerland and Austria where helicopter-assisted mountain biking demands minimal payload penalties.
- Steel:Powder-coated chromoly or mild steel tubing provides cost-optimized durability for entry-level hitch-mount systems serving budget-conscious consumers in Spain and Poland.
- Plastic:Glass-reinforced nylon or ABS polymer components reduce manufacturing complexity for trunk-mount strap buckles and protective contact pads, constrained by UV degradation concerns in Mediterranean climates.
Aluminum commands the largest installed base; Carbon Fiber expands most quickly on margin contribution.
End User:
Customer type stratification reveals procurement consolidation among fleet operators displacing individual retail purchases as the dominant volume driver.
- Retail Consumers:Individual household purchasers selecting racks through outdoor recreation retailers or direct-to-consumer channels, with suburban United States households driving replacement cycles as e-bike ownership rises.
- Commercial Fleets:Bike-share and rental operators negotiating multi-year supply agreements with integrated maintenance provisions, concentrated in North American urban centers demanding predictive telemetry and rapid-swap installation systems.
- Local Governments:Municipal procurement for police bicycle units, park maintenance fleets, and tourism infrastructure in German and Austrian alpine regions with standardized tender processes.
- Rental Services:Seasonal tourism operators in French and Italian coastal regions requiring corrosion-resistant platforms for beach-adjacent storage and high-frequency customer handling protocols.
Commercial Fleets capture the steepest expansion trajectory; Retail Consumers retain the deepest installed base.
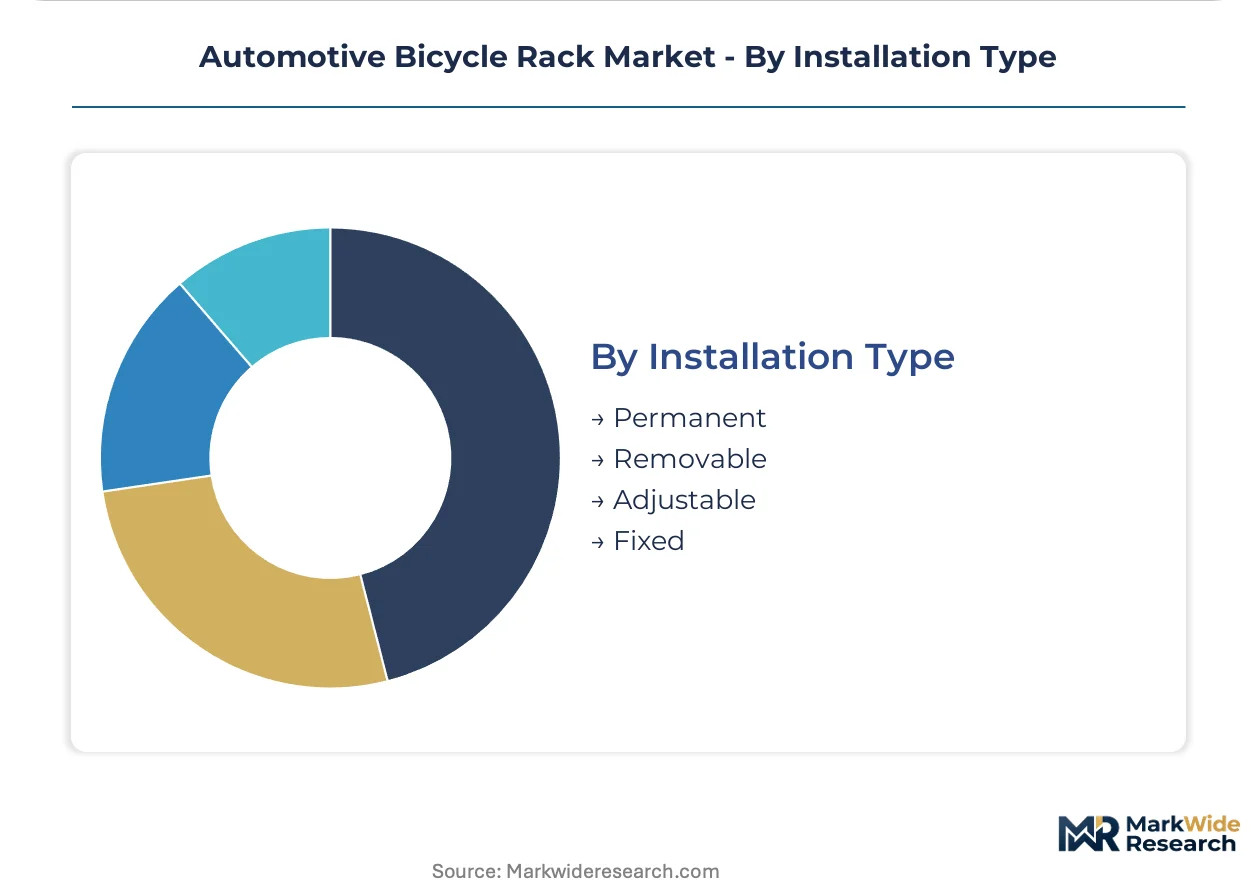
Installation Type:
Application durability requirements separate permanent fleet infrastructure from consumer convenience preferences.
- Permanent:Welded or bolted receiver-tube installations with integrated wiring for lighting and camera systems, serving commercial fleet operators in the United States with dedicated vehicle assignments.
- Removable:Tool-free hitch-pin or clamp-based attachment enabling rapid detachment for vehicle resale or seasonal use, preferred by German retail consumers with leased vehicles requiring original-condition return.
- Adjustable:Telescoping or pivoting frame architectures accommodating multiple bicycle sizes or tilt-away trunk access, concentrated in Netherlands family households with mixed adult and child bicycle transport needs.
- Fixed:Rigid non-adjustable platforms minimizing moving-part failure modes for high-cycle commercial applications in Swiss bike-share networks with standardized bicycle specifications.
Removable systems lead consumer volume; Permanent installations dominate fleet procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European distribution for aluminum extrusions and polymer components, while the Port of Long Beach handles Pacific Rim imports serving North American rack assembly. Rail intermodal links from Rotterdam to the German industrial heartland sustain just-in-time supply chains for hitch-mount system manufacturers.
United States
Suburban household e-bike ownership and SUV receiver-hitch prevalence drive hitch-mount demand. NHTSA FMVSS roof-rack provisions mandate dynamic load testing, consolidating procurement toward certified engineering suppliers. Manufacturing concentrates in Colorado's Front Range corridor, where outdoor recreation industry clustering accelerates product development cycles.
Germany
Leased-vehicle penetration and underground parking height restrictions sustain roof-mount preference in urban centers. KBA type-approval standards and REACH chemical compliance elevate material substitution costs, rewarding suppliers with in-house polymer chemistry capabilities. Thule Group anchors production in Malmö-proximate facilities serving the Hamburg-Berlin logistics axis.
Netherlands
Cycling infrastructure density and family multi-bicycle transport needs favor adjustable platform configurations. EU Green Deal circular economy mandates accelerate end-of-life recycling program development. Eindhoven-region polymer processors supply UV-stabilized joint components to rack assemblers across the Randstad.
Switzerland
Helicopter-assisted mountain tourism and professional cycling team logistics command carbon-fiber performance platforms. Swissmedic-equivalent product safety expectations and alpine climate exposure requirements drive corrosion-resistance specifications. Zurich-proximate engineering firms specialize in lightweight composite structural analysis for adventure tourism operators.
Canada
Seasonal cycling participation patterns and lease-market vehicle turnover sustain removable installation demand. Health Canada product safety guidelines align with US NHTSA provisions, enabling cross-border manufacturing scale. Vancouver and Toronto metropolitan clusters concentrate outdoor recreation retail distribution for rack procurement.
Automotive Bicycle Rack Market Vendor Landscape
Listed leaders compete with private specialists across capital access and engineering agility dimensions. The vendor base stratifies into three tiers: integrated European engineering houses with polymer chemistry capabilities, North American outdoor recreation specialists with retail channel dominance, and Asian fabricators serving cost-optimized segments. Competitive moves concentrate on portfolio diversification into e-bike-compatible platforms and strategic partnerships with commercial fleet operators seeking predictive maintenance telemetry.
Within the integrated engineering tier, Thule Group and Atera GmbH exemplify European manufacturing footprint advantages, while Yakima Products occupies a position among North American outdoor recreation channel anchors. These three companies represent divergent responses to regulatory chemistry constraints: proximity to ECHA technical guidance versus NHTSA load-testing certification versus retail distribution scale.
| Leading Market Players |
|---|
| Thule Group |
| Yakima Products |
| Saris Cycling Group |
| Kuat Innovations |
| Allen Sports |
| Hollywood Racks |
| RockyMounts |
| Atera GmbH |
| Rhino Rack |
| Others |
Supply Flow & Price Mechanics
Sixty-day aluminum extrusion lead times from European smelters compress margin pools for mid-tier rack manufacturers lacking long-term supply contracts, concentrating pricing power with vertically integrated producers who control polymer chemistry capabilities and REACH-compliant coating formulations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates carbon-fiber performance platforms from aluminum mid-market systems and steel entry-level hitch mounts. Price differentiation hinges on NHTSA FMVSS certification tier and volume scale, with fleet procurement aggregators commanding steepest discounts. Cost compression in the aluminum mid-tier is intensifying because primary metal volatility erodes contract margins. Retail consumers in Southern Europe exhibit highest price sensitivity, while commercial fleet operators in North America prioritize predictive maintenance telemetry over unit cost.
Supply Chain Analysis
China and Germany anchor aluminum extrusion and polymer component production for rack manufacturing, with Taiwan supplying precision-machined receiver-tube interfaces. Raw material dependencies center on 6061-T6 aluminum billet, glass-reinforced nylon resin, and epoxy matrix systems for carbon-fiber layup. Supply chain risk concentrates in single-source vulnerability for REACH-compliant polymer additives facing ECHA regulatory restriction. Distribution runs through outdoor recreation retail chains in North America and dedicated automotive accessory distributors in European urban centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as e-bike penetration in suburban households forces platform redesigns across all installation categories, creating replacement demand tailwinds for e-bike-compatible architectures.
For Market Incumbents: Fortify polymer chemistry capabilities to maintain dual-market access under REACH chemical compliance, while expanding permanent-installation capacity for commercial fleet operators demanding predictive maintenance telemetry. Defensive positioning requires backward integration into aluminum extrusion to offset smelter contract volatility, and accelerated KBA type-approval investment to block emerging entrants from European urban markets. For New Entrants and Emerging Players: Predictive maintenance telemetry integration represents the critical service-layer gap where incumbents under-serve commercial fleet operators. White-space concentration sits in rapid-swap removable systems for leased-vehicle markets in Germany and the Netherlands, plus corrosion-resistant platforms for Mediterranean coastal rental services. Go-to-market execution should anchor on direct fleet procurement channels rather than contested outdoor retail distribution. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because NHTSA FMVSS certification barriers and REACH compliance costs consolidate procurement toward established engineering suppliers with in-house polymer expertise. Acquisition targets should display carbon-fiber composite capabilities or established fleet service contracts. The signal to watch is harmonization progress on e-bike weight classifications, which would trigger platform redesign cycles and supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| E-bike Platform Redesign | Structural rating upgrades capture battery-assisted bicycle loads exceeding legacy hitch-mount capacities. |
| REACH Compliance Investment | In-house polymer chemistry capabilities maintain European market access as ECHA restricts additive formulations. |
| Fleet Telemetry Integration | Predictive maintenance systems differentiate procurement for bike-share operators in North American urban centers. |
| Carbon-Fiber Capacity Expansion | Helicopter-assisted mountain tourism in Switzerland commands premium pricing for weight-critical platforms. |
| Permanent Installation Systems | Welded receiver-tube architectures with integrated wiring serve dedicated commercial vehicle assignments. |
Methodological Framework
A standing panel of rack engineering directors, fleet procurement managers at bike-share operators, outdoor recreation retail category buyers, and polymer chemistry specialists provided ongoing calibration. Primary fieldwork combined structured interviews with these stakeholders and secondary validation through NHTSA FMVSS guidance documents, ECHA REACH substance databases, KBA type-approval registries, and customs trade data on aluminum extrusion flows. Bottom-up segment sizing triangulated against top-down production capacity estimates from European and North American manufacturing clusters.
Consistency checks validated volume and value outputs against external benchmarks including vehicle registration databases, cycling participation surveys, and fleet operator procurement disclosures across the projection horizon. Segmentation dimensions modeled encompass product type, material grade, end-user category, and installation permanence, with regional regulatory clusters treated as distinct demand drivers. CAGRs derived from fitted growth curves applied to e-bike penetration trajectories and replacement cycle assumptions, with aluminum pricing sensitivity and REACH compliance cost inflation as key variable inputs.
Underlying assumptions cover sustained e-bike weight classification divergence and aluminum smelter capacity utilization, with deviation risk concentrated in regulatory harmonization timelines and polymer additive substitution costs. Recalibration cycles align with material shifts in NHTSA rulemaking, ECHA substance restriction updates, and fleet operator procurement consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Electric Cargo Bikes Market
Bikes and Motorcycles
US Fuel Cell Bikes Market
Bikes and Motorcycles
Brazil E-Bike Market
Bikes and Motorcycles
Japan Motorcycle ADAS Market
Bikes and Motorcycles
Motorcycle Accessories Market
Bikes and Motorcycles
Motorcycle Rider Assistance System Market
Bikes and Motorcycles
Latin America Two-Wheeler Market
Bikes and Motorcycles
Carbon Fiber Bicycle Market
Bikes and Motorcycles
Motorcycle Fuel Hoses Market
Bikes and Motorcycles
Motorcycle Wheels Market
Bikes and Motorcycles
Motorcycle Headlight Market
Bikes and Motorcycles
GPS Bike Computers Market
Bikes and Motorcycles
300cc Motorcycle Market
Bikes and Motorcycles
Sweden E-Bike Market
Bikes and Motorcycles
Motorcycles, Scooters and Mopeds Market
Bikes and Motorcycles
United Arab Emirates E-Bike Market