
 E-Lock for Electric Vehicle Charging Market | 2026-2036
E-Lock for Electric Vehicle Charging Market Size, Share, and Industry Trends Forecast 2026-2036
E-Lock for Electric Vehicle Charging Market Insights
A shift from outsourced electromechanical assemblies toward in-house magnetic locking module production is realigning supply economics for tier-one charging hardware suppliers. Marquardt Gruppe leverages its automotive switchgear heritage to control proprietary solenoid designs for high-cycle locking mechanisms. TE Connectivity anchors its position through backward integration into precision stamping and contact metallurgy for charge-port latches. Kiekert competes by extending its door-latch expertise into sealed, vibration-resistant e-lock architectures for DC fast-charging stations.
An e-lock for electric vehicle charging is an electromechanical or solid-state locking device that secures the charging connector to the vehicle inlet, typically rated for IP54 or higher environmental sealing and engineered to withstand thousands of insertion-extraction cycles. Its primary purpose is preventing unauthorized disconnection, cable theft, and arcing hazards during power transfer. Smart lock systems dominate value pools due to firmware-upgradeable security protocols and remote diagnostics integration, while Bluetooth-enabled units represent the fastest-expanding technology segment as smartphone-native authentication displaces physical key fobs. Cloud-based lock deployments remain nascent outside fleet-managed charging hubs where centralized access control justifies recurring platform fees.
FCC certification governs wireless-communication-enabled locks in the United States, while the EU AI Act and GDPR impose data-handling constraints on biometric and cloud-connected variants sold in Europe. IEC 61851 and UL 2594 establish baseline electrical-safety and mechanical-durability thresholds that determine market-access eligibility across major jurisdictions. Stakeholders must weigh regional certification burdens against the margin premium of software-defined locking platforms before committing to geographic expansion.
Market Dynamics
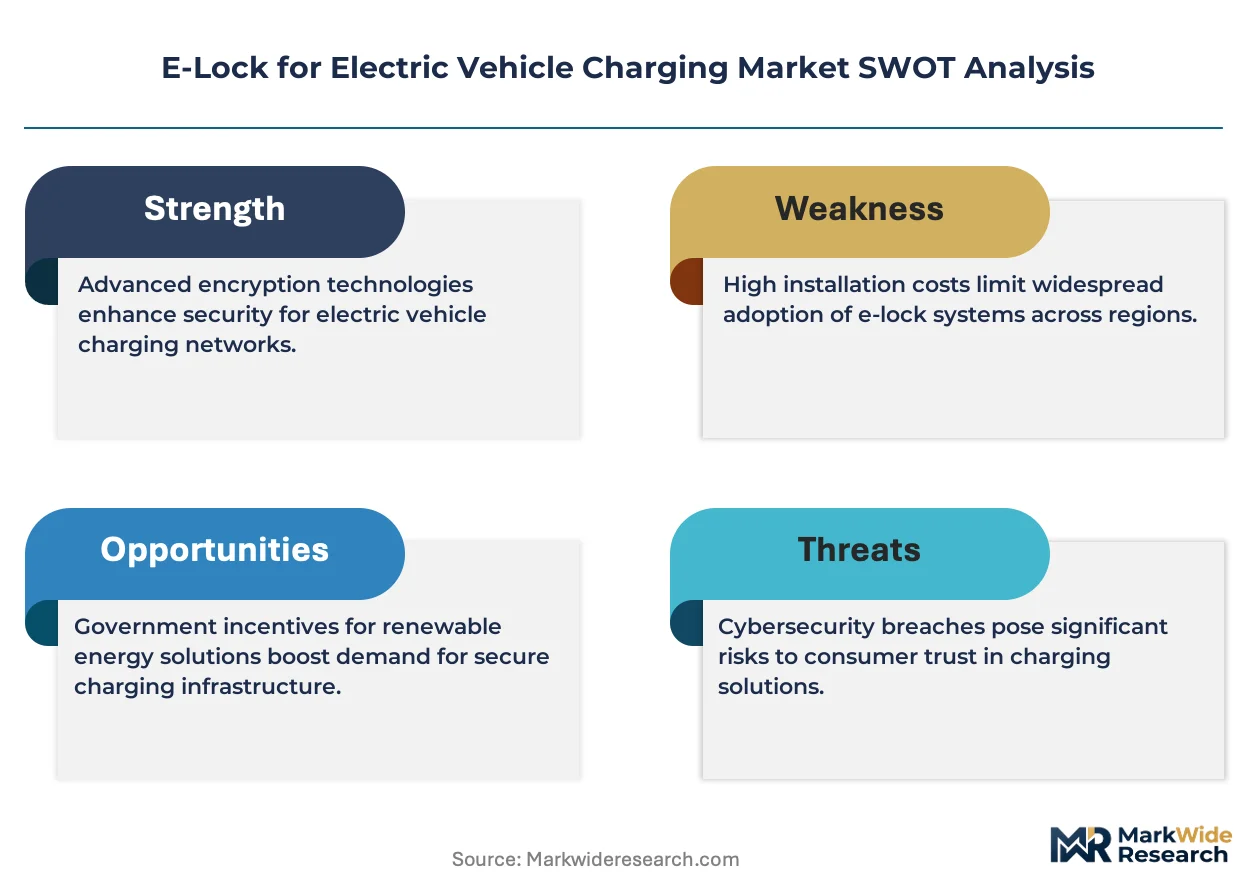
The transition from dumb mechanical latches to firmware-upgradeable smart locks is compressing hardware margins while expanding recurring revenue pools for platform-integrated suppliers.
Growth Catalysts
- IEC 61851 Mandates:Tightening connector-locking requirements across Germany, China, and the United States are forcing charging station upgrades and replacement cycles.
- Fleet Electrification:Logistics operators at depots and hubs demand centralized access control for overnight charging, creating volume pull for networked e-lock systems.
- Smartphone Authentication:Bluetooth-enabled units are displacing physical key fobs as native mobile credentialing becomes standard for EV drivers.
Market Restraints
- Rare Earth Magnet Volatility:Neodymium and dysprosium price swings squeeze solenoid actuator margins for magnetic locking module producers.
- Chinese Component Concentration:Precision stamping and contact metallurgy supply clusters in Shenzhen and Dongguan create single-source vulnerability for Western assemblers.
- Biometric Regulatory Friction:GDPR and the EU AI Act impose data-handling constraints that slow biometric e-lock deployment across European markets.
Strategic Opportunities
- Cloud-Connected Fleet Hubs:Centralized access control platforms justify recurring SaaS fees in depot-managed charging networks where authentication complexity is highest.
- V2G Bidirectional Integration:Vehicle-to-grid protocols require tamper-proof locking during power export, opening specification windows for high-reliability actuator designs.
- Indian Charging Infrastructure:BIS certification alignment and PLI scheme incentives for domestic manufacturing create first-mover positioning for localized e-lock production.
Industry Challenges
- Firmware Security Talent Scarcity:Over-the-air update architectures require embedded cybersecurity expertise that competes with automotive ECU and infotainment hiring pools.
- Multi-Jurisdiction Certification Timelines:Simultaneous FCC, CE marking, and UL 2594 approvals extend product launch cycles by eight to fourteen months.
- Legacy Charge Port Retrofit Complexity:Backward compatibility with first-generation vehicle inlets limits design freedom for next-generation latching mechanisms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Lock for Electric Vehicle Charging Market |
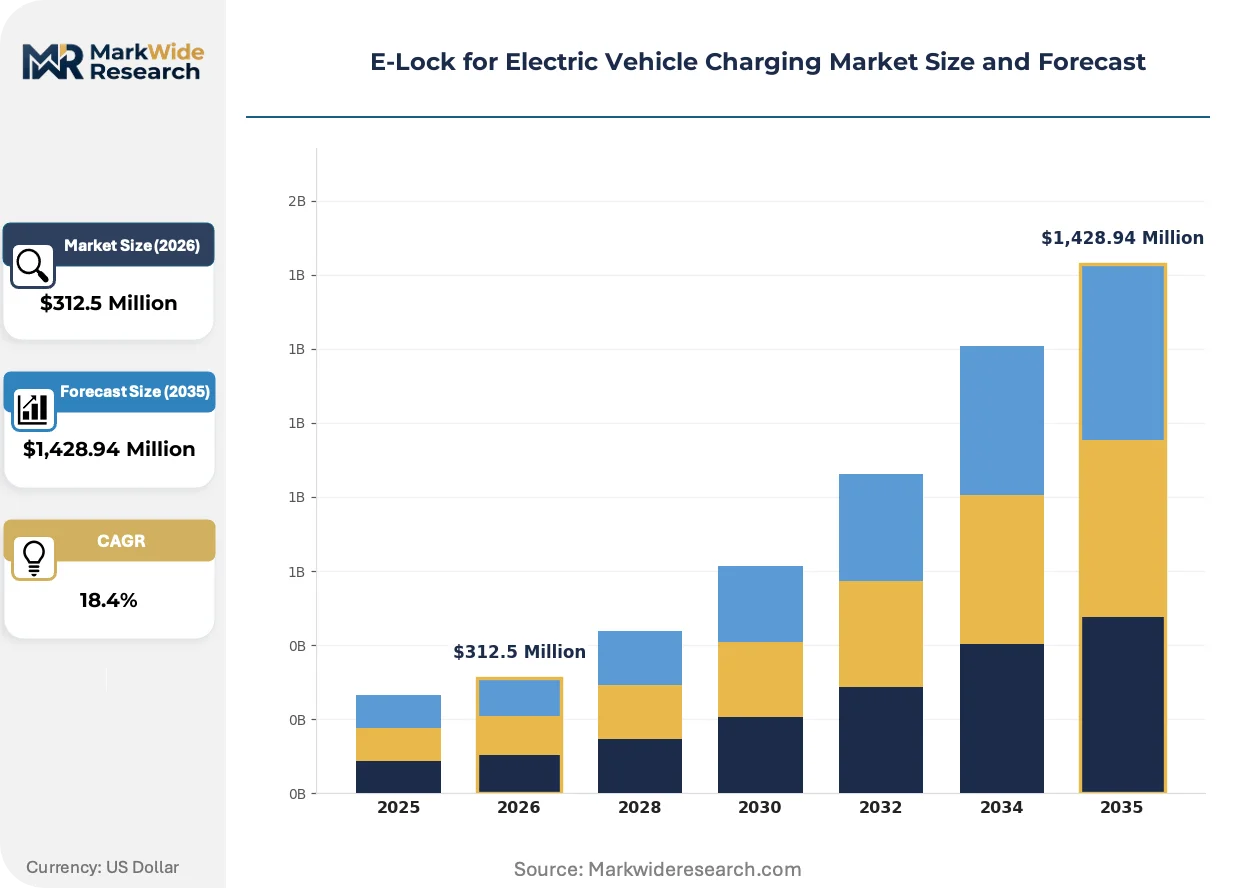
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $1,428.94 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Lock, Mechanical Lock, Cloud-Based Lock, Biometric Lock End User: Fleet Operators, Homeowners, Commercial Charging Station, Rental Services Technology: Bluetooth, Wi-Fi, RFID, Cellular Installation: On-Premise, Remote Location, Integrated Systems, Stand-Alone |
| Companies Covered | Marquardt Gruppe, TE Connectivity, HELLA, Kiekert, Zhaowei Machinery and Electronic, Volex, Röchling, Mida, JT Mobility, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Lock for Electric Vehicle Charging Market Trends and Innovations
Wireless credentialing and predictive maintenance algorithms are redefining how charging hardware suppliers capture value beyond the physical lock mechanism.
Solid-state piezoelectric actuators are overtaking traditional solenoid designs in high-cycle DC fast-charging applications. Tier-one charging hardware suppliers at public highway corridors and fleet depots are piloting these units for their silent operation and million-cycle durability. This shift is overtaking the historical dominance of electromechanical assemblies in premium charging infrastructure specifications.
The EU AI Act's risk-classification framework for biometric authentication systems is forcing European e-lock vendors to segregate data processing architectures. On-device template storage is displacing cloud-based matching to avoid high-risk system designation and audit burdens. German and French charging network operators are prioritizing edge-only biometric locks to preempt CNIL and national data authority enforcement actions.
Subscription-based access platforms are unbundling hardware procurement from authentication service fees. Fleet managers and commercial parking operators are rejecting capital-heavy purchase models in favor of per-charge or per-port recurring arrangements. This pattern is most visible in United States municipal and workplace charging deployments where budget cyclicality favors operational expenditure treatment.
E-Lock for Electric Vehicle Charging Market Segmentation
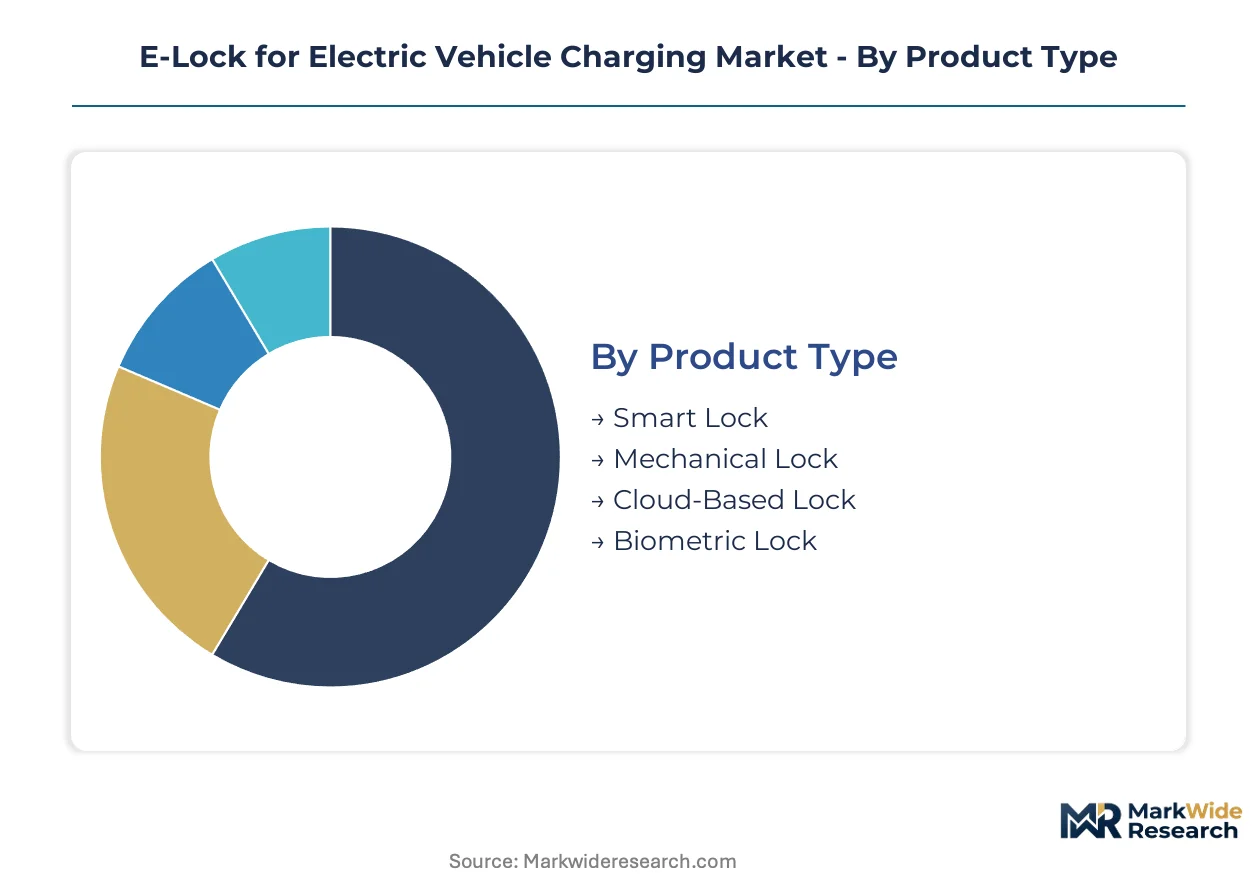
Segmentation in the E-Lock for Electric Vehicle Charging Market reveals how hardware specifications, connectivity protocols, and deployment contexts fragment purchasing criteria across fleet depots, residential garages, and highway corridor infrastructure.
Product Type:
Standalone electromechanical units dominate legacy installations while embedded smart systems penetrate new charging infrastructure builds.
- Smart Lock:Firmware-upgradeable units with over-the-air security patches and remote diagnostics integration. Fleet operators in Germany and the United States specify these for depot-managed networks where centralized access control reduces operational overhead.
- Mechanical Lock:Spring-loaded or cam-based latches without electronic actuation, specified for cost-sensitive residential Level 2 installations. Homeowners in price-conscious segments favor these where smartphone credentialing adds unnecessary complexity.
- Cloud-Based Lock:Authentication logic hosted on centralized servers with recurring platform fees. Demand concentrates in municipal and workplace charging deployments in the United States where operational expenditure treatment appeals to budget-constrained procurement officers.
- Biometric Lock:Fingerprint or facial recognition units with on-device template storage to satisfy GDPR and EU AI Act constraints. French and German network operators pilot these for premium charging locations where physical credential loss risks are unacceptable.
Mechanical locks lead volumes today; smart locks are gaining share fastest.
End User:
Volume concentration shifts from individual consumers toward institutional purchasers with complex authentication requirements and multi-port management needs.
- Fleet Operators:Logistics companies and delivery services managing overnight charging at depots and hubs. These buyers demand networked e-lock systems with API integration into fleet management platforms, driving specification pull for cellular-connected units.
- Homeowners:Individual EV owners installing Level 2 residential charging. Bluetooth-enabled locks displace physical key fobs as smartphone-native authentication becomes standard, though price sensitivity limits adoption of premium biometric or cloud-connected variants.
- Commercial Charging Station:Retail, hospitality, and workplace parking operators offering public or semi-public access. These deployments prioritize vandal resistance and payment system integration, favoring IP67-rated smart locks with contactless credential readers.
- Rental Services:Car-sharing and short-term vehicle lease operators requiring temporary credential issuance. Dynamic access codes and time-bound digital keys distinguish this segment, with demand emerging in urban China and European metropolitan markets.
Fleet operators command the largest revenue pool; rental services are climbing the fastest.
Technology:
Communication protocol selection determines cybersecurity surface area, power consumption, and interoperability with existing vehicle telematics and charging network software.
- Bluetooth:Low-energy wireless standard enabling smartphone-native authentication without cellular dependency. This protocol is expanding most quickly across residential and light commercial installations where infrastructure simplicity outweighs range limitations.
- Wi-Fi:Higher bandwidth connectivity supporting firmware updates and real-time diagnostic streaming. Public charging corridor operators in the United States specify these for remote troubleshooting capabilities.
- RFID:Contactless card-based credentialing with deterministic response times. Fleet depots favor this mature technology for reliability in high-interference electromagnetic environments near high-power charging equipment.
- Cellular:LTE or 5G modules enabling cloud-backed authentication without local network infrastructure. Highway corridor and remote location deployments depend on this for coverage in areas lacking Wi-Fi backhaul.
Bluetooth anchors current installations; cellular is expanding most quickly.
Installation:
Physical mounting context dictates environmental sealing requirements, cable management complexity, and integration with existing charge port architectures.
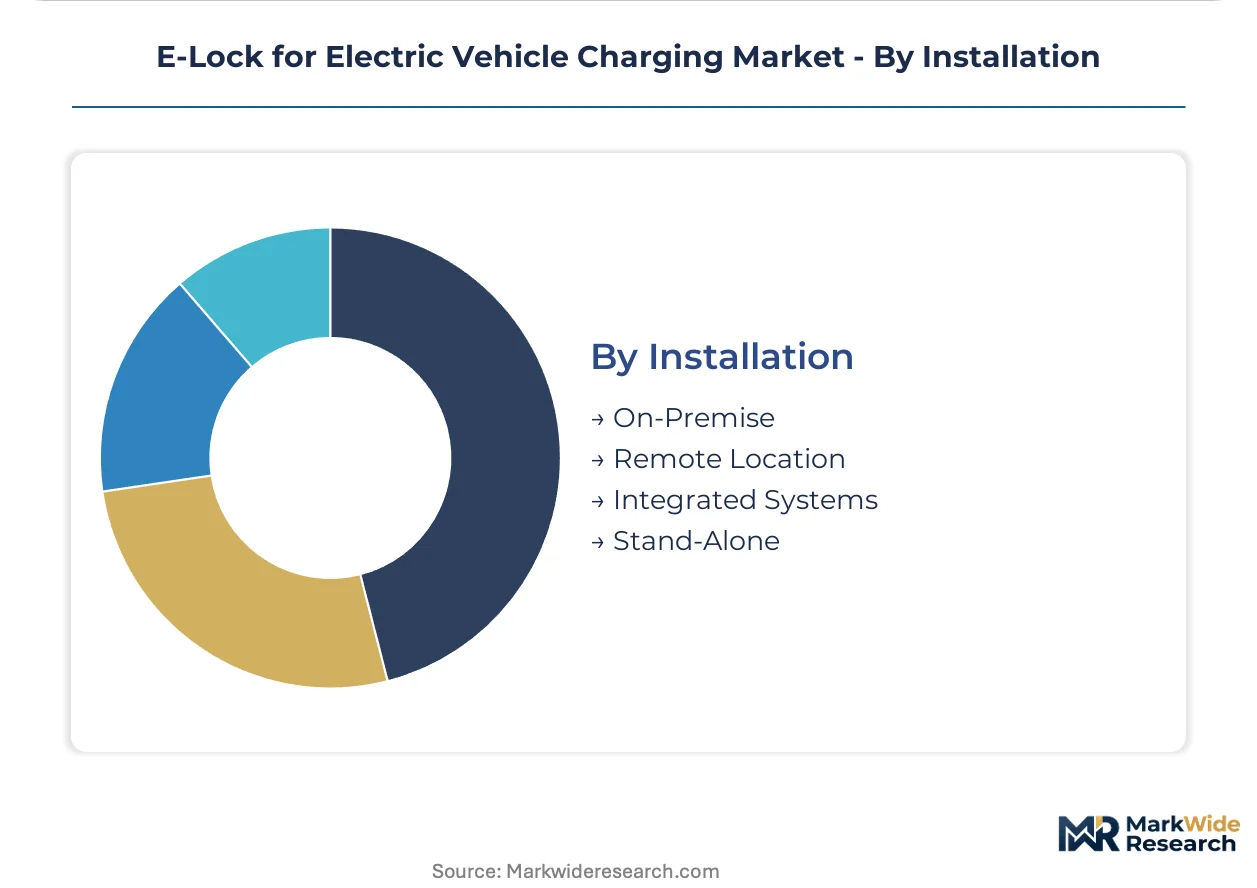
- On-Premise:Fixed installations at owned or long-leased facilities including residential driveways, corporate campuses, and fleet depots. These deployments prioritize durability and warranty terms over portability.
- Remote Location:Highway corridor, rural, or temporary event charging infrastructure lacking permanent electrical service. Cellular-connected locks with solar or battery backup power dominate this challenging deployment context.
- Integrated Systems:E-locks embedded within charging station enclosures by original equipment manufacturers. TE Connectivity and Kiekert supply these to tier-one charging hardware vendors seeking reduced assembly complexity.
- Stand-Alone:Retrofit units attaching to existing charge ports without enclosure replacement. This segment serves legacy infrastructure upgrades driven by IEC 61851 mandate compliance in Germany and China.
On-premise deployments retain volume leadership; integrated systems are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production economics are pushing magnetic locking module assembly toward jurisdictions with streamlined electromagnetic compatibility certification pathways, creating a cost-of-compliance arbitrage between European precision engineering and Asian component manufacturing clusters.
Germany
KBA enforcement of IEC 61851 connector-locking mandates drives depot and highway corridor upgrades across Bavaria and North Rhine-Westphalia. The EU AI Act's biometric risk classification shapes R&D priorities for Stuttgart-based automotive suppliers developing edge-only authentication systems. Industrial concentration in Baden-Württemberg hosts precision solenoid prototyping facilities serving tier-one charging hardware vendors.
China
Dual carbon goals accelerate fleet electrification at logistics hubs in Shenzhen and Dongguan, generating volume demand for high-cycle locking mechanisms. GB standards alignment with IEC 61851 streamlines export certification for domestic producers. The Yangtze River Delta precision stamping cluster supplies contact metallurgy components to Western assemblers facing single-source vulnerability.
United States
FCC certification requirements for wireless-communication-enabled locks create regulatory friction for European biometric entrants targeting municipal deployments in California and Texas. The Inflation Reduction Act's charging infrastructure incentives concentrate demand in fleet depots across the Midwest and Southeast. NHTSA safety consultations inform tamper-proof locking specifications for V2G bidirectional integration pilots.
India
BIS certification alignment and PLI scheme incentives for domestic manufacturing attract first-mover positioning for localized e-lock production in Maharashtra and Gujarat. CEA electrical safety mandates at public charging stations create replacement cycles for legacy mechanical latches. The Delhi-NCR logistics corridor generates fleet operator demand for networked access control systems.
France
CNIL enforcement actions under GDPR compel on-device biometric template storage for charging network operators in Île-de-France. ANSM consultation on electromagnetic medical device compatibility indirectly shapes testing protocols for high-power locking actuators. Auvergne-Rhône-Alpes hosts pilot deployments of edge-only facial recognition locks at premium charging locations.
E-Lock for Electric Vehicle Charging Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cloud-connected authentication platforms and solid-state actuator architectures. The supplier base concentrates around three strategic archetypes: automotive heritage manufacturers leveraging door-latch and switchgear expertise, connectivity specialists commanding precision metallurgy and stamping capabilities, and component-scale producers from Asian industrial clusters. Competitive positioning hardens through backward integration into captive solenoid design and strategic partnerships with tier-one charging hardware vendors.
Among German automotive-heritage suppliers, Marquardt Gruppe and Kiekert exemplify the electromechanical-to-smart-lock transition archetype, each representing decades of vehicle access-system expertise repurposed for charging infrastructure sealing and vibration resistance. TE Connectivity anchors the connectivity-specialist tier, its position reflecting precision stamping and contact metallurgy capabilities applied to charge-port latch architectures. Zhaowei Machinery and Electronic occupies the component-scale archetype within Shenzhen-Dongguan supply clusters, illustrating the geographic concentration that creates sourcing vulnerability for Western assemblers.
| Leading Market Players |
|---|
| Marquardt Gruppe |
| TE Connectivity |
| HELLA |
| Kiekert |
| Zhaowei Machinery and Electronic |
| Volex |
| Röchling |
| Mida |
| JT Mobility |
| Others |
Pricing and Supply Chain Analysis
Fleet operator procurement concentration across German depots and United States logistics hubs anchors subscription-based pricing models that unbundle hardware capital expenditure from recurring authentication service fees.
Pricing Analysis
Distributor margin compression runs through the channel as tier-one charging hardware vendors consolidate direct procurement relationships. Three-tier pricing structure across premium smart locks, standard Bluetooth-enabled units, and economy mechanical latches differentiates on IEC 61851 certification grade and firmware upgradeability. Pricing pressure stems from rare earth magnet volatility in solenoid actuators, squeezing magnetic locking module producers. Fleet operators exhibit lowest price sensitivity due to operational expenditure treatment preferences, while residential homeowners drive cost compression in mechanical lock tiers.
Supply Chain Analysis
Dual-sourcing requirements from Western assemblers mandate multi-supplier qualification for precision stamping and contact metallurgy components. Manufacturing concentrates in China, Germany, and the United States, with the Yangtze River Delta cluster feeding contact metallurgy and Baden-Württemberg hosting solenoid prototyping. Neodymium and dysprosium dependencies for magnetic actuators tether the supply chain to commodity price swings. Single-source vulnerability in Shenzhen-Dongguan stamping clusters poses structural risk. Distribution runs through tier-one charging hardware vendors and direct OEM integration channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where BIS certification alignment and PLI scheme incentives in India offer cost-of-compliance advantages against European GDPR and EU AI Act regulatory burdens.
For Market Incumbents: Lock in backward integration into captive solenoid design to defend against solid-state piezoelectric actuator substitution and rare earth price volatility. Prioritize FCC pre-certification for wireless-enabled locks to accelerate United States municipal deployment timelines. Deepen API integration partnerships with fleet management platforms to create switching costs against cloud-connected authentication entrants. For New Entrants and Emerging Players: Enter via Indian domestic manufacturing under PLI scheme incentives, targeting BIS-certified production for localized supply to Maharashtra and Gujarat charging infrastructure. The rental services segment offers lowest competitive density with dynamic access code requirements. Pursue white-label supply agreements with tier-one charging hardware vendors lacking in-house magnetic locking expertise. For Investors and Strategic Acquirers: Tier-one charging hardware vendors are the most active acquirer in this space, seeking to internalize magnetic locking module production and reduce assembly complexity. Long-term viability hinges on firmware security talent access and multi-jurisdiction certification capability. Watch solid-state actuator pilot adoption at highway corridor DC fast-charging stations as inflection signal for electromechanical displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Solenoid Design | Marquardt Gruppe and TE Connectivity control proprietary actuator architectures, reducing rare earth margin exposure. |
| Cloud-Connected Fleet Platform Launch | Recurring SaaS fees from depot-managed authentication justify centralized access control investment in United States Midwest deployments. |
| Indian PLI Scheme Manufacturing Localization | BIS certification alignment and domestic production incentives create first-mover positioning in Maharashtra and Gujarat infrastructure. |
| FCC Pre-Certification Investment | Wireless-communication-enabled locks require electromagnetic compliance before California and Texas municipal procurement cycles. |
| Solid-State Piezoelectric Actuator Development | Silent operation and million-cycle durability specifications displace electromechanical assemblies in premium highway corridor infrastructure. |
Research Methodology
Coverage spans Germany, China, the United States, India, and France, with primary inputs from each market cluster. The approach combines executive interviews with tier-one charging hardware procurement directors, fleet operator facility managers, and automotive supplier R&D leads with secondary validation through IEC 61851 regulatory filings, FCC equipment authorization databases, and BIS certification records. Bottom-up unit demand modeling and top-down infrastructure investment triangulation anchor volume estimates.
Granularity-level modeling disaggregates the analysis window by product type, end user, technology protocol, and installation context, with additional segmentation by regional regulatory cluster and certification tier. CAGRs derive from logistic diffusion curves fitted to fleet electrification timelines and public charging network buildout trajectories. Forecast inputs include rare earth magnet price indices, IEC 61851 mandate implementation schedules, and PLI scheme incentive disbursement patterns.
Inputs from regulatory filing databases and supplier financial disclosures were available through the study window; gaps in proprietary fleet operator deployment data introduce uncertainty bands around depot-managed charging volume assumptions. Forecasts reflect assumptions on IEC 61851 alignment timelines and rare earth price stabilization. Deviation in V2G bidirectional integration mandates or EU AI Act biometric enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
EV Thermal Management System Market
Electric Vehicles
EV Platform Market
Electric Vehicles
Railway Lithium Battery Market
Electric Vehicles
Battery-Swapping for Electric Two-Wheeler Market
Electric Vehicles
Lawn Mower Battery Market
Electric Vehicles
Global Electric Vehicle (EV) Management Solution Market
Electric Vehicles
Asia Pacific Electric Three-Wheelers Market
Electric Vehicles
Asia Pacific Automotive High Performance Electric Vehicles Market
Electric Vehicles
Global Smart Electric Drive Market
Electric Vehicles
Electric Vehicle Battery Cases Market
Electric Vehicles
United States Electric Pick-Up Trucks Market
Electric Vehicles
Electric Moped Market
Electric Vehicles
Water Proof E-Scooter Market
Electric Vehicles
Electric Vehicle Operations Management Solutions Market
Electric Vehicles
US Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
UK Electric Bus Battery Pack Market