
 Battery-Only Electric Bus Market | 2026-2036
Battery-Only Electric Bus Market Size, Share, and Industry Trends Forecast 2026-2036
Battery-Only Electric Bus Market Insights
Solid-state battery prototyping is tilting procurement criteria toward energy density thresholds above 300 Wh/kg. BYD Company Ltd. leverages captive cell production across its bus division. Yutong Co., Ltd. anchors its European push with modular platform architectures. CRRC Corporation Limited dominates rail-adjacent transit ecosystems with integrated charging infrastructure.
A battery-only electric bus relies entirely on electrochemical storage without auxiliary combustion, typically employing lithium iron phosphate or nickel manganese cobalt cell configurations with liquid thermal management and 350-800 V architectures to deliver 200-500 km daily range for fixed-route passenger service. Standard buses occupy the volume base across most procurement tenders, while articulated configurations capture premium margin pools in high-density corridors. Fast charging technology leads deployment in markets with intermittent depot access, whereas vehicle-to-grid integration remains nascent but structurally significant for grid-stabilization revenue models.
China's MIIT enforces GB/T standards for battery swap interoperability, while the EU Green Deal and F-Gas Regulation constrain coolant chemistries and manufacturing carbon intensity. The US EPA and NHTSA coordinate tailpipe and safety standards that effectively mandate electric powertrains in specific state-level fleet mandates. Stakeholders must weigh cell chemistry commitments against evolving thermal-runaway testing protocols and subsidy clawback provisions.
Market Dynamics
Solid-state battery prototyping is compressing procurement timelines as municipal buyers rewrite tender specifications around energy density thresholds above 300 Wh/kg, forcing incumbent liquid-electrolyte suppliers to accelerate qualification cycles or face disqualification from premium corridor contracts.
Growth Catalysts
- China's MIIT battery-swap standards:GB/T interoperability mandates eliminate depot infrastructure fragmentation, enabling fleet operators to standardize charging assets across multi-vendor procurements.
- Metropolitan corridor densification:São Paulo and Rio de Janeiro transit authorities are consolidating zero-emission fleet commitments into single-tender packages exceeding 500 units.
- Lithium iron phosphate chemistry maturation:Cell-to-pack architectures reduce thermal management complexity, cutting bus-level integration costs for fixed-route operators.
Market Restraints
- Cathode material concentration:Nickel and cobalt processing capacity clusters in the Democratic Republic of Congo and Indonesia, exposing cell manufacturers to supply disruption and price volatility.
- EU F-Gas Regulation constraints:Coolant chemistry restrictions limit thermal management system options, forcing redesign cycles that extend platform validation timelines.
- Depot charging infrastructure capex:Grid interconnection upgrades for 800 V fast-charging depots require distribution-level transformer investments that strain municipal capital budgets.
Strategic Opportunities
- Vehicle-to-grid integration:Bidirectional charging protocols enable transit authorities to monetize grid-stabilization services through FERC Order 2222 participation in US markets.
- Articulated bus premiumization:High-density corridor operators in Brazil are specifying 18-meter configurations with battery capacities exceeding 500 kWh, creating margin pools above standard 12-meter tenders.
- Battery leasing decoupling:Asset-light procurement models separate chassis ownership from energy storage, reducing upfront capital barriers for Latin American municipal operators.
Industry Challenges
- Cell qualification timeline compression:UN 38.3 thermal-runaway testing protocols require 18-24 month validation cycles that lag behind procurement award schedules.
- Electronics technician scarcity:High-voltage systems maintenance demands specialized certification programs that transit agencies struggle to staff at scale.
- Legacy depot retrofit friction:Existing maintenance facilities require structural reinforcement and ventilation upgrades to accommodate battery-electric fire suppression systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery-Only Electric Bus Market |
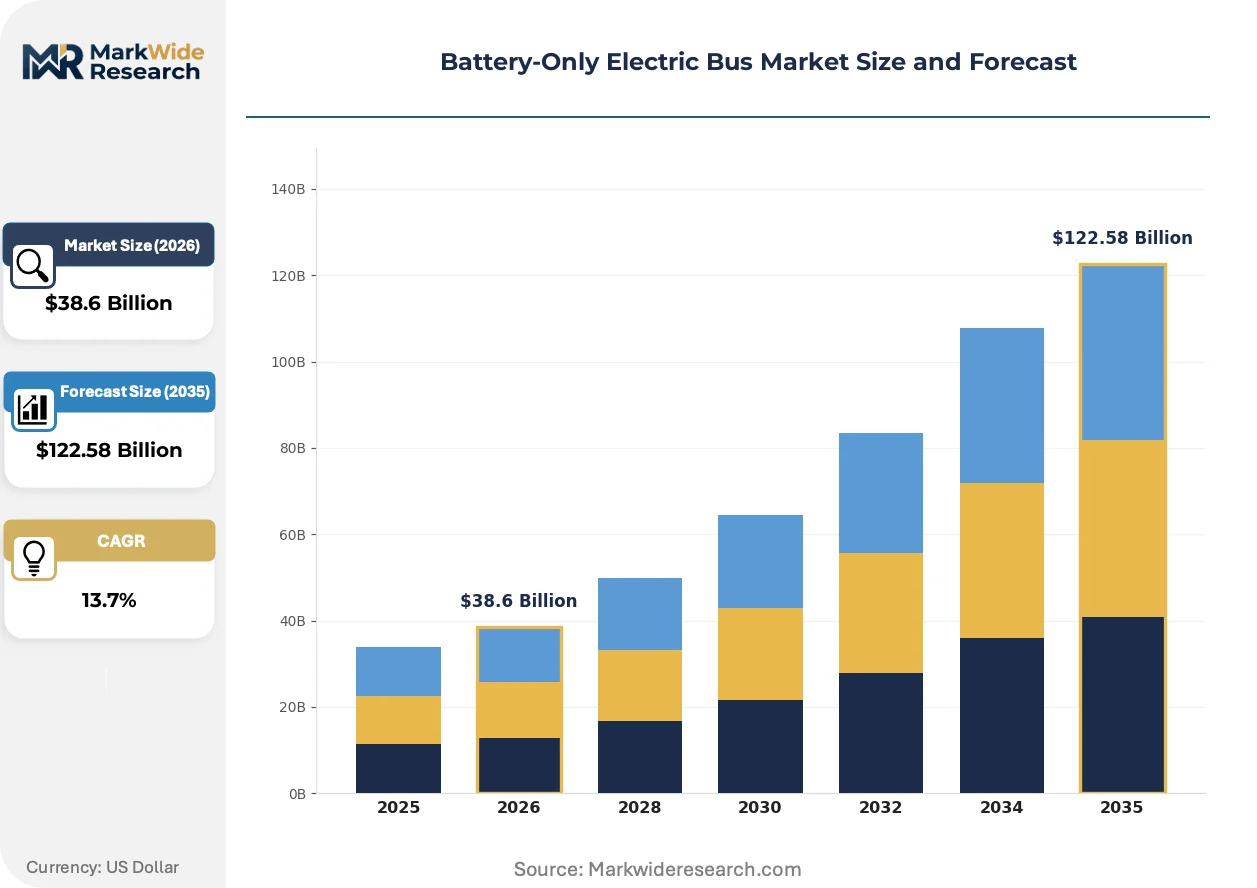
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $122.58 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Buses, Double-Decker Buses, Articulated Buses, Mini Buses Capacity: 10-20 Seats, 21-40 Seats, 41-60 Seats, 61+ Seats Technology: Battery Management Systems, Regenerative Braking, Fast Charging, Vehicle-to-Grid End User: Public Transportation, Schools, Tourist Services, Corporate Transport |
| Companies Covered | BYD Company Ltd., Yutong Co., Ltd., CRRC Corporation Limited, Daimler Buses, MAN Truck & Bus, Wrightbus, Iveco Bus, VDL Bus & Coach, Proterra, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery-Only Electric Bus Market Trends and Innovations
Silicon-anode cell chemistries are destabilizing incumbent lithium-ion supply relationships as energy density benchmarks rewrite competitive qualification criteria across procurement channels.
Solid-state electrolyte architectures are rendering obsolete liquid thermal management systems in premium corridor applications. São Paulo metropolitan operators now specify solid-state readiness clauses in 10-year fleet tenders. This chemistry transition compresses supplier qualification timelines from 36 months to 18 months.
The EU Green Deal's manufacturing carbon intensity disclosures constrain coolant selection and cell sourcing for European deployments. Bus OEMs must document Scope 3 emissions across nickel refining and cathode active material production. Articulated configurations face the strictest verification burdens due to larger battery masses.
Municipal tender unbundling is fragmenting traditional chassis-powertrain integration. Brazilian transit authorities now issue separate RFPs for rolling stock, charging infrastructure, and energy management software. This disaggregation favors modular platform specialists over vertically integrated incumbents in corridor electrification programs.
Battery-Only Electric Bus Market Segmentation
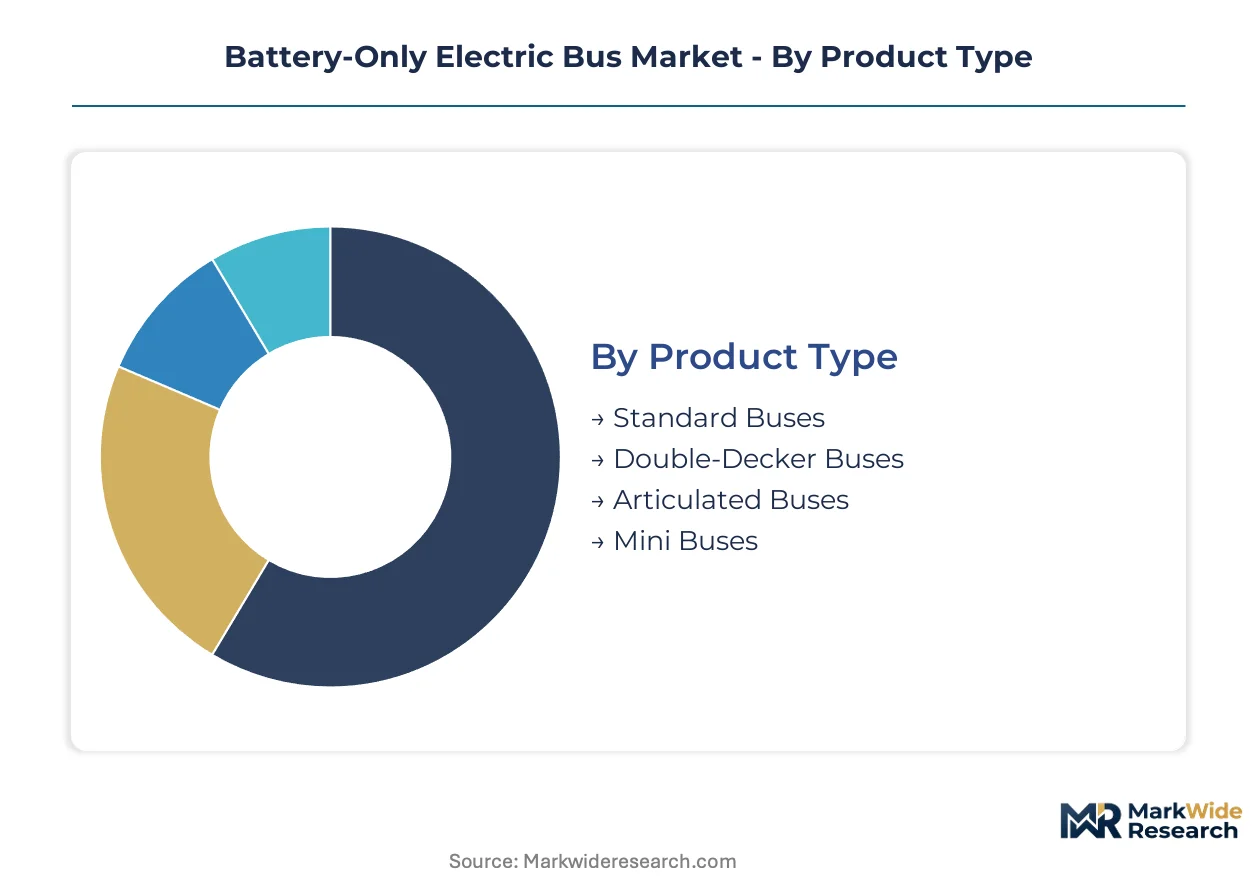
Segmentation in the battery-only electric bus market exposes divergent procurement cycles and margin structures across vehicle configurations and operational use cases. Fleet operators prioritize different technical specifications based on route density, passenger volume, and depot infrastructure maturity.
Product Type:
Cycle times vary dramatically across bus architectures, with standard configurations turning over in 7-10 years while articulated platforms extend to 12-15 years due to higher capital commitment and corridor-specific deployment.
- Standard Buses:These 12-meter single-deck configurations employ lithium iron phosphate cell packs with 200-350 kWh capacities and 350 V architectures. São Paulo metropolitan operators specify standard buses for feeder routes and medium-density corridors where depot charging infrastructure is already installed. Procurement volumes here concentrate in municipal tender packages exceeding 500 units.
- Articulated Buses:18-meter bendy-bus designs integrate battery capacities above 500 kWh with 800 V fast-charging compatibility and distributed thermal management across multiple cell modules. Rio de Janeiro's Bus Rapid Transit corridors specify these for high-frequency trunk routes where passenger loads exceed 150 persons per vehicle.
- Double-Decker Buses:Two-level passenger configurations with elevated battery placement and reinforced chassis structures serve tourist-heavy and premium commuter markets.
- Mini Buses:Compact 6-8 meter designs with sub-150 kWh packs target last-mile connectivity and low-frequency rural routes.
Standard buses dominate installed base. Articulated buses are where expansion concentrates.
Capacity:
Seat-count segmentation maps directly to route economics and subsidy eligibility thresholds across municipal procurement frameworks.
- 41-60 Seats:Mid-capacity configurations balance passenger throughput with battery weight trade-offs, serving as the workhorse for urban trunk routes. Brazil's consolidated tender packages specify this range for corridor electrification programs linking suburban terminals to city centers.
- 61+ Seats:High-capacity designs maximize passenger density per vehicle-kilometer, with articulated platforms in this bracket commanding premium margins. São Paulo's metro-bus integration projects specify these for dedicated lane operations where dwell time minimization is critical.
- 10-20 Seats:Low-capacity shuttles serve paratransit and on-demand mobility pilots.
- 21-40 Seats:Compact urban configurations bridge feeder and mainline service requirements.
41-60 seat configurations anchor current fleet composition. 61+ seat platforms are climbing the fastest.
Technology:
Technology adoption curves separate mature systems with proven field data from emerging capabilities still in validation cycles.
- Fast Charging:Pantograph and plug-in systems delivering 350-450 kW enable opportunity charging at route termini, extending daily range without depot expansion. Operators in Rio de Janeiro deploy these where grid interconnection upgrades would otherwise delay electrification timelines.
- Vehicle-to-Grid:Bidirectional power flow protocols allow battery assets to participate in grid stabilization services. FERC Order 2222 in US markets creates revenue streams that offset capital costs for early adopters with compatible charging infrastructure.
- Battery Management Systems:Cell-level monitoring and thermal regulation software ensures warranty compliance and safety certification.
- Regenerative Braking:Kinetic energy recovery systems extend range by 15-25% in stop-and-go urban duty cycles.
Battery Management Systems penetrate universally. Vehicle-to-Grid is gaining share fastest.
End User:
End-user categories reflect fundamentally different procurement authority structures and total cost of ownership calculations.
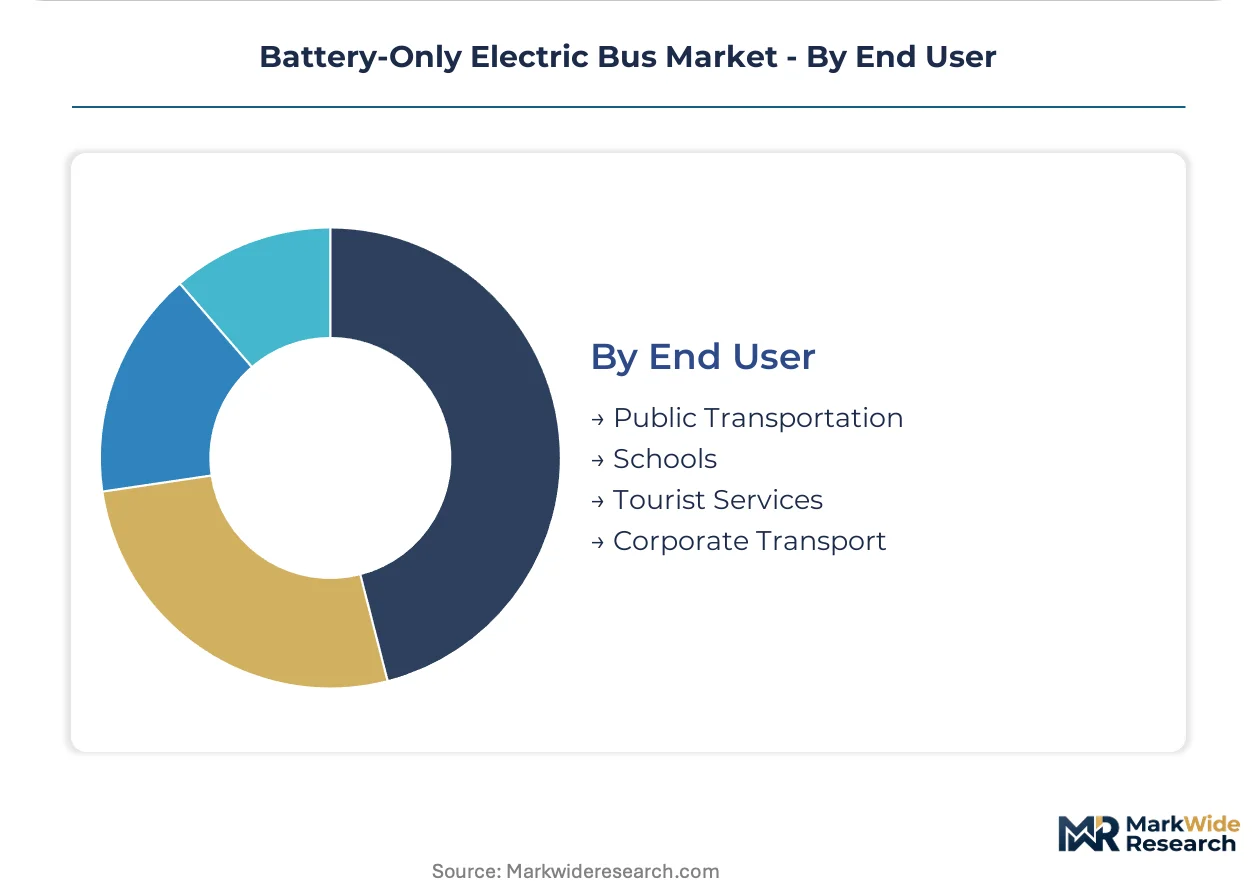
- Public Transportation:Municipal transit authorities with consolidated fleet mandates drive volume procurement through multi-year tender programs. Brazil's metropolitan operators in São Paulo and Rio de Janeiro anchor regional demand with zero-emission fleet commitments exceeding 2,000 vehicles across current planning horizons.
- Schools:Dedicated student transport services with predictable route patterns and depot-based overnight charging optimize for total cost of ownership over acquisition price alone.
- Tourist Services:Premium open-top and heritage-route operators specify custom bodywork with extended range for intermittent charging access.
- Corporate Transport:Private shuttle services for technology campuses and industrial parks prioritize brand alignment and employee experience metrics.
Public Transportation commands installed base volume. Schools represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers export battery-electric bus platforms across Latin American metropolitan corridors, with São Paulo and Rio de Janeiro transit authorities consolidating procurement into multi-hundred-unit tenders.
China
Domestic fleet electrification and GB/T battery-swap standardization drive manufacturing scale. MIIT interoperability mandates eliminate depot infrastructure fragmentation across provincial operators. Zhengzhou and Shenzhen anchor production clusters where cell-to-pack architectures reduce integration costs for municipal buyers.
Brazil
São Paulo and Rio de Janeiro metropolitan authorities package zero-emission commitments into single-tender programs exceeding 500 units. ANVISA vehicle safety certification aligns with EU-equivalent crash-test protocols. The Bus Rapid Transit corridor expansion in Rio concentrates articulated bus demand for high-frequency trunk routes.
Germany
EU Green Deal manufacturing carbon intensity disclosures constrain coolant selection and cell sourcing for European deployments. KBA type-approval processes validate thermal-runaway containment systems. Baden-Württemberg and Bavaria host OEM engineering centers developing modular platform architectures for municipal tender participation.
United States
FERC Order 2222 enables transit authorities to monetize grid-stabilization services through vehicle-to-grid bidirectional charging protocols. EPA tailpipe standards and state-level fleet mandates effectively mandate electric powertrains in California and New York. The EPA-NHTSA coordination on safety standards shapes high-voltage system certification timelines.
United Kingdom
Transport for London decarbonization targets drive double-decker electrification with extended-range specifications. The F-Gas Regulation restricts coolant chemistries, forcing thermal management redesign cycles. Wrightbus in Northern Ireland exemplifies regional manufacturing adaptation to premium corridor requirements.
Battery-Only Electric Bus Market Competitive Landscape
On the supply side, the industry is consolidating around captive cell production and modular platform specialization. Tiered competitive positioning separates vertically integrated battery manufacturers from chassis-assembly specialists and charging-infrastructure integrators. Dominant moves include strategic partnerships between cell suppliers and bus OEMs, plus geographic expansion through localized assembly joint ventures in target procurement markets.
Within the integrated-manufacturer tier, BYD Company Ltd. and Yutong Co., Ltd. represent archetypes of captive supply chain control, while CRRC Corporation Limited occupies a position bridging rail-adjacent transit ecosystems with bus electrification. These Chinese entities exemplify how GB/T standardization and domestic manufacturing scale translate into export competitiveness across Latin American tender markets.
| Leading Market Players |
|---|
| BYD Company Ltd. |
| Yutong Co., Ltd. |
| CRRC Corporation Limited |
| Daimler Buses |
| MAN Truck & Bus |
| Wrightbus |
| Iveco Bus |
| VDL Bus & Coach |
| Proterra |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in China's lithium iron phosphate cell production is compressing module prices and forcing tier-two suppliers to extend payment terms or exit the market entirely. This utilization imbalance grants procurement leverage to Brazilian municipal operators while squeezing margins for European thermal management specialists facing EU F-Gas Regulation compliance costs.
Pricing Analysis
The technology-generation pricing gap separates liquid-electrolyte platforms at standard rates from solid-state-ready configurations commanding 15-25% premiums. Three-tier pricing structure across premium articulated, standard single-deck, and economy mini-bus levels reflects battery capacity scale and charging architecture complexity. Cost compression in the standard bus tier is intensifying because Chinese cell-to-pack architectures eliminate redundant module housings. Latin American municipal buyers exhibit highest price sensitivity due to foreign exchange exposure and subsidy clawback provisions, while European operators prioritize total cost of ownership including carbon intensity disclosure compliance.
Supply Chain Analysis
Extended payment terms from 90 to 180 days have become standard for cathode active material procurement as suppliers absorb working capital strain from nickel price volatility. Cell manufacturing concentrates in China, South Korea, and Japan, with lithium carbonate processing anchored in Chile and Australia. Raw material dependencies span cobalt from the Democratic Republic of Congo, nickel from Indonesia, and refined lithium from South American salt flats. Single-source vulnerability in cathode precursor supply creates disruption exposure when Indonesian nickel processing facilities face environmental compliance inspections. Distribution runs through OEM-anchored assembly joint ventures in Brazil and localized bus body fabrication partnerships across European procurement markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards defensive moats built on regulatory entrenchment. GB/T standard certification and ANVISA type-approval create switching costs that lock out unqualified suppliers from multi-year tender cycles.
For Market Incumbents: Insulate core corridor positions by deepening backward integration into cell-to-pack architectures and securing captive lithium carbonate offtake from Chilean brine operations. Solid-state chemistry transitions threaten liquid-electrolyte incumbents with disqualification from premium São Paulo tenders specifying 300 Wh/kg thresholds. Priority investment in UN 38.3 thermal-runaway testing capacity compresses qualification timelines to match procurement award schedules.
For New Entrants and Emerging Players: School bus electrification in the United States represents the most penetrable segment due to predictable route patterns and depot-based overnight charging that minimizes fast-charging infrastructure requirements. Brazilian battery leasing decoupling models reduce upfront capital barriers for municipal operators previously excluded from chassis ownership. A software-defined energy management go-to-market angle differentiates against hardware-centric incumbents in fragmented Latin American procurement.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among charging infrastructure operators with vehicle-to-grid protocol compatibility and long-term service contracts. Five-to-ten year viability hinges on solid-state chemistry qualification timelines and thermal management system redesign cycles. Acquisition targets should display modular platform architectures enabling rapid reconfiguration across standard and articulated bus variants. The signal to monitor is FERC Order 2222 implementation velocity in US markets, which determines grid-stabilization revenue materialization for bidirectional charging assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Captive cell offtake from Chinese tier-one manufacturers secures pricing visibility for Brazilian tender participation. |
| Platform Standardization | Modular 12-meter and 18-meter architectures reduce engineering validation costs across GB/T and ANVISA certification pathways. |
| Charging Infrastructure Partnership | Pantograph fast-charging deployments with Rio de Janeiro BRT operators extend daily range without depot grid upgrades. |
| Backward Integration | In-house lithium iron phosphate cell production eliminates margin leakage to Korean and Japanese cathode suppliers. |
| Geographic Manufacturing Footprint | Localized assembly joint ventures in São Paulo state satisfy domestic content requirements for federal subsidy eligibility. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with transit authority procurement directors, OEM platform engineers, and cell manufacturer supply chain managers; and secondary validation against MIIT GB/T filings, ANVISA certification databases, and FERC grid interconnection records. Municipal tender documentation from São Paulo and Rio de Janeiro provided volume and specification benchmarks. Bottom-up unit economics triangulated against top-down fleet electrification commitment totals across the analysis window.
Forecast inputs incorporated bus configuration mix shifts, battery chemistry transition timelines, and charging infrastructure deployment velocity. Segmentation modeling spanned vehicle architecture, passenger capacity tier, charging technology adoption, and end-user procurement authority structure. CAGRs derived from corridor-level fleet replacement schedules and subsidy program renewal cycles. Solid-state readiness clauses in Brazilian metropolitan tenders and EU F-Gas Regulation thermal management redesign timelines shaped projection boundaries.
Macroeconomic conditions sit as an overlay; deviation in Brazilian real exchange rates, lithium carbonate spot prices, or Chinese export credit availability would shift the trajectory. Forecasts reflect documented assumptions around GB/T interoperability adoption and ANVISA-EU regulatory convergence. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Van Market
Electric Vehicles
Africa Electric Scooter Market
Electric Vehicles
Right Hand Drive Electric Vehicle Market
Electric Vehicles
Electric Unicycle Market
Electric Vehicles
Wireless Electric Vehicle Charging Market
Electric Vehicles
Electric Vehicle UBI Market
Electric Vehicles
Electric Delivery Vans Market
Electric Vehicles
Automotive EV HUB Market
Electric Vehicles
EV Lightweight Materials Market
Electric Vehicles
France Automotive High Performance Electric Vehicles Market
Electric Vehicles
New Zealand E-Bike Market
Electric Vehicles
Worldwide EV Range Extender Market
Electric Vehicles
Japan E-Bike Market
Electric Vehicles
Belgium Solar E-Bike Market
Electric Vehicles
Electric All-Terrain Vehicle (ATV) Market
Electric Vehicles
EV Coolants Market