
 Oman Electric Vehicle (EV) Market | 2026-2036
Oman Electric Vehicle (EV) Market Size, Share, and Industry Trends Forecast 2026-2036
Oman Electric Vehicle (EV) Market Insights
Fleet operator procurement is hardening as the dominant demand channel in Oman's EV landscape. Hyundai Motor Company leverages its regional assembly partnerships to sustain competitive positioning in the commercial van segment. BMW anchors its presence through premium SUV offerings targeting corporate leasing channels. BYD competes aggressively on battery cost structures, extending its reach into government tender processes.
Electric vehicles in Oman are battery-powered automobiles utilizing lithium-ion or solid-state electrochemical cells to convert stored electrical energy into mechanical propulsion, with typical energy densities ranging from 150 to 300 watt-hours per kilogram and regenerative braking systems that recover kinetic energy during deceleration. Their primary purpose is to displace internal combustion engines in passenger and light-commercial transport, reducing fossil fuel dependency and tailpipe emissions in urban corridors. The vehicle type dimension shows SUVs capturing the strongest household demand due to terrain compatibility and family size norms, while sedans retain fleet preference for operational efficiency. Battery technology stratification reveals lithium-ion as the incumbent production standard, though solid-state configurations are attracting R&D capital for future thermal safety advantages.
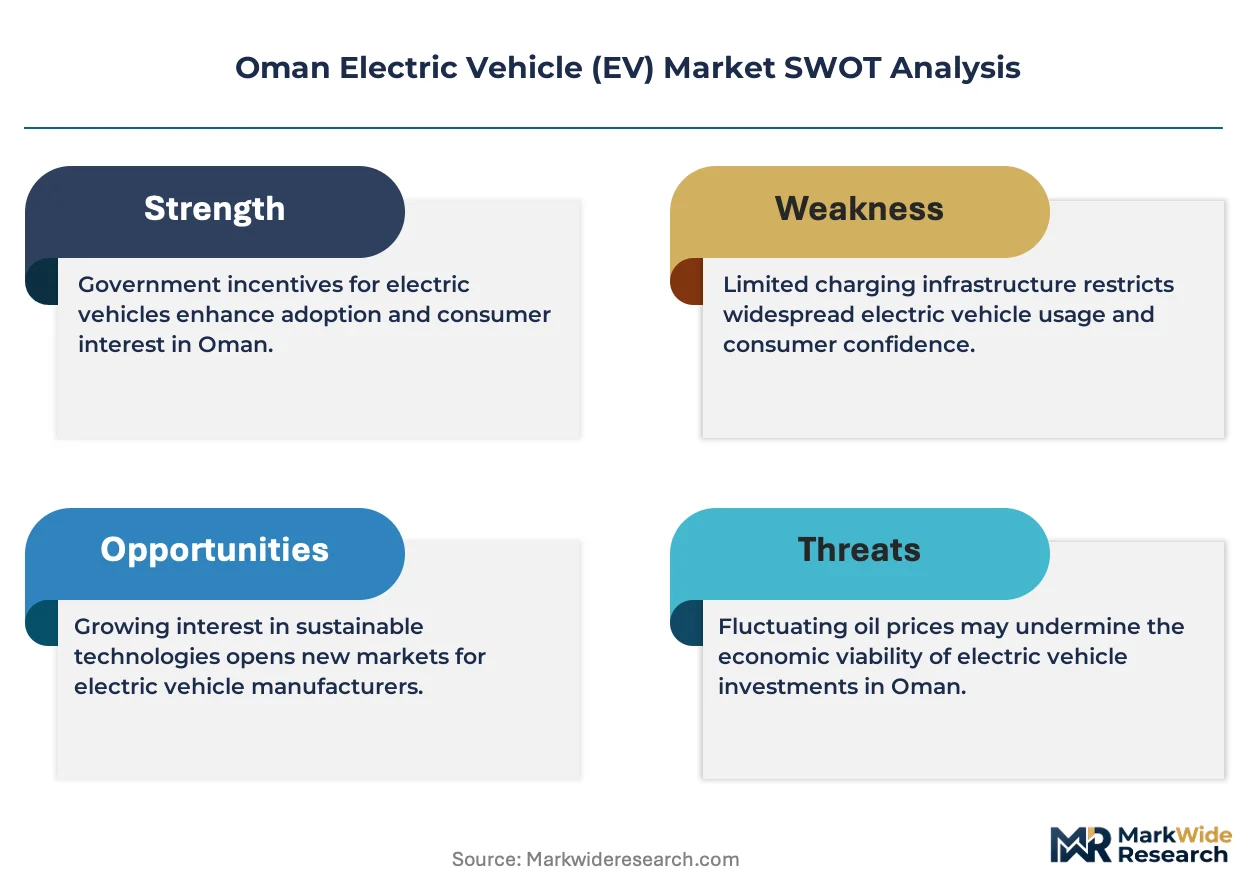
Oman's Ministry of Transport, Communications and Information Technology and the Authority for Electricity Regulation shape EV market access through charging infrastructure licensing and grid interconnection standards that determine deployment velocity. The country's national EV policy and building codes mandating charging readiness in new commercial developments directly influence property developer procurement decisions. Stakeholders must monitor grid capacity allocation timelines and utility tariff structures to align investment cycles with infrastructure availability.
Market Dynamics
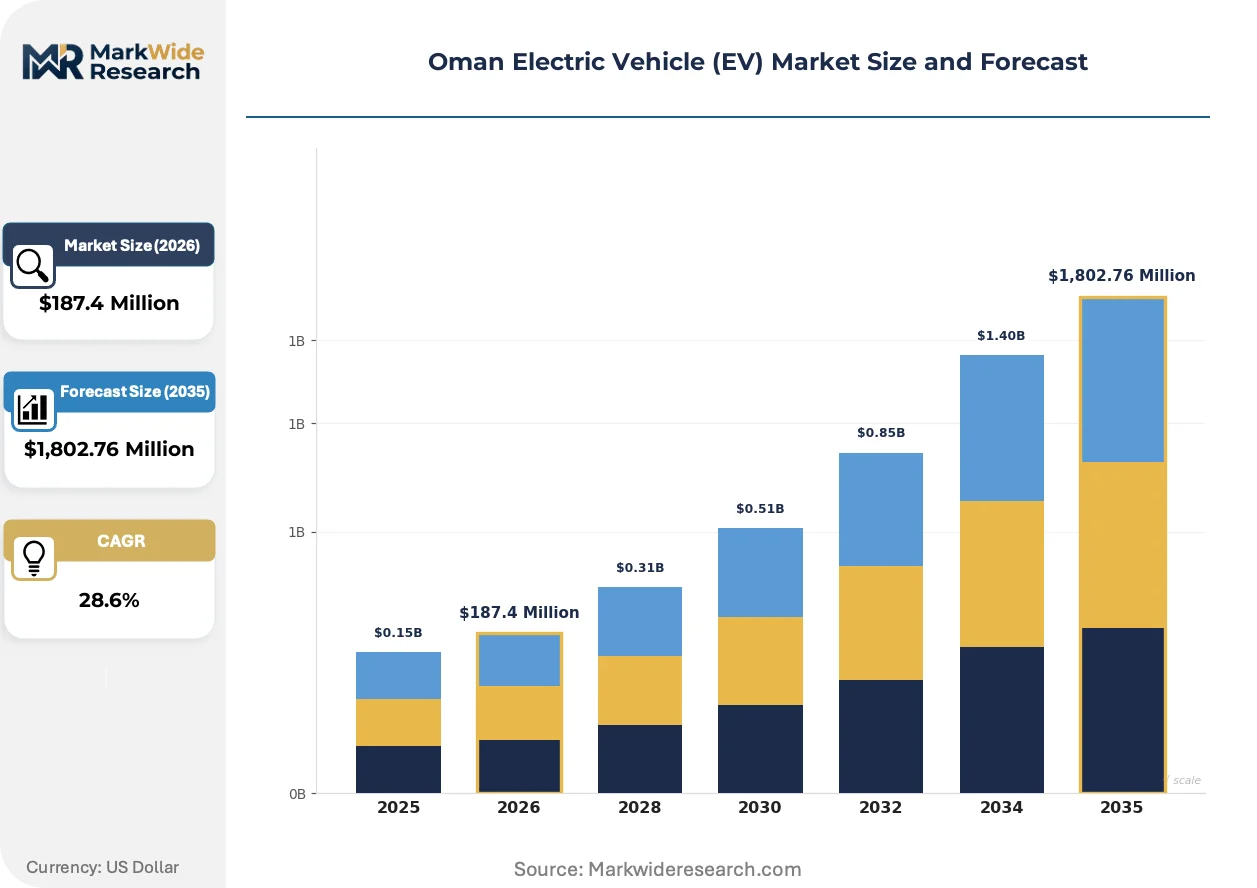
Fleet operator procurement is hardening as the dominant demand channel in Oman's EV landscape, with government mandates and utility-scale charging infrastructure investments compressing adoption timelines for commercial operators across Muscat and Salalah.
Growth Catalysts
- National EV Policy Framework:Oman's comprehensive electrification roadmap mandates government fleet conversion targets and establishes licensing pathways for charging infrastructure deployment, creating predictable demand visibility for commercial vehicle suppliers.
- Utility-Scale Charging Investments:The Authority for Electricity Regulation's grid interconnection standards and tariff structures are unlocking capital flows into fast-charging corridors along the Muscat-Salalah logistics axis.
- Last-Mile Logistics Electrification:E-commerce fulfillment networks and corporate transport services are replacing diesel vans with electric alternatives to reduce fuel cost volatility and meet sustainability procurement criteria.
Market Restraints
- Lithium-Ion Supply Concentration:Battery cell production concentrates in East Asian manufacturing hubs, exposing Omani fleet operators to shipping cost volatility and extended lead times for commercial vehicle orders.
- Grid Capacity Allocation Bottlenecks:Utility distribution network upgrades in secondary governorates lag behind vehicle deployment schedules, forcing charging infrastructure developers to absorb interconnection delay costs.
- Arid Climate Thermal Management:Extreme summer temperatures in interior Omani regions accelerate battery degradation rates, compressing warranty coverage terms and residual value projections for fleet assets.
Strategic Opportunities
- Dhofar Governorate Expansion:Salalah's port logistics zone and free trade infrastructure present underpenetrated demand for electric heavy-duty trucks serving transshipment corridors to Yemen and East Africa.
- Building Code Integration:New commercial development mandates requiring charging readiness in parking structures are creating captive installation markets for electrical contractors and property developers in Muscat's premium residential zones.
- Solid-State Battery Convergence:Emerging thermal safety advantages from solid-state electrochemical configurations are attracting R&D capital that could reposition Oman as a testbed for high-temperature climate validation protocols.
Industry Challenges
- Specialized Technician Scarcity:High-voltage battery diagnostics and power electronics repair functions lack certified training pipelines in Oman's technical education institutions, extending vehicle downtime for fleet operators.
- Interoperability Certification Complexity:Multiple charging connector standards and communication protocols across European, Chinese, and Japanese vehicle platforms are forcing infrastructure operators to deploy redundant hardware configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oman Electric Vehicle (EV) Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,802.76 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedans, SUVs, Hatchbacks, Vans Battery Technology: Lithium-ion, Nickel-metal Hydride, Solid-state, Lead-acid Charging Infrastructure: Fast Chargers, Home Chargers, Public Charging Stations, Wireless Charging Customer Segment: Individual Consumers, Fleet Operators, Government Agencies, Corporate Entities |
| Companies Covered | Tesla, BMW, Hyundai Motor Company, Nissan, Renault Group, BYD, Chevrolet, MG Motor, Mays, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oman Electric Vehicle (EV) Market Trends and Innovations
Electrification architecture is actively fragmenting across vehicle classes and use cases in Oman, with divergent technology choices emerging between premium passenger segments and utilitarian fleet applications.
Vehicle-to-grid (V2G) bidirectional charging hardware is decentralizing energy asset ownership in Oman's commercial property sector. Large-format battery packs in electric vans and SUVs now function as distributed storage nodes for building load management. Property developers in Muscat's Al Mouj and Madinat Sultan Qaboos districts are integrating V2G capability into corporate leasing packages, compressing payback periods for solar-plus-storage installations through peak shaving revenue streams.
Oman's Authority for Electricity Regulation has issued grid interconnection standards that mandate smart metering integration for all public charging stations above 50kW capacity. This policy compresses deployment timelines for ultra-fast charging corridors while forcing hardware suppliers to certify cybersecurity protocols against emerging data protection requirements. Fleet operators in the logistics sector are responding by consolidating charging procurement under single-network contracts to simplify compliance overhead.
Corporate mobility managers are unbundling vehicle ownership from energy procurement in Oman's government and banking sectors. Leasing structures now separate battery asset financing from chassis contracts, with third-party energy service companies assuming residual value risk for battery packs. This model is most visible in Muscat Governorate's diplomatic and oil services corporate fleets, where total cost of ownership calculations now prioritize energy cost predictability over capital expenditure minimization.
Oman Electric Vehicle (EV) Market Segmentation
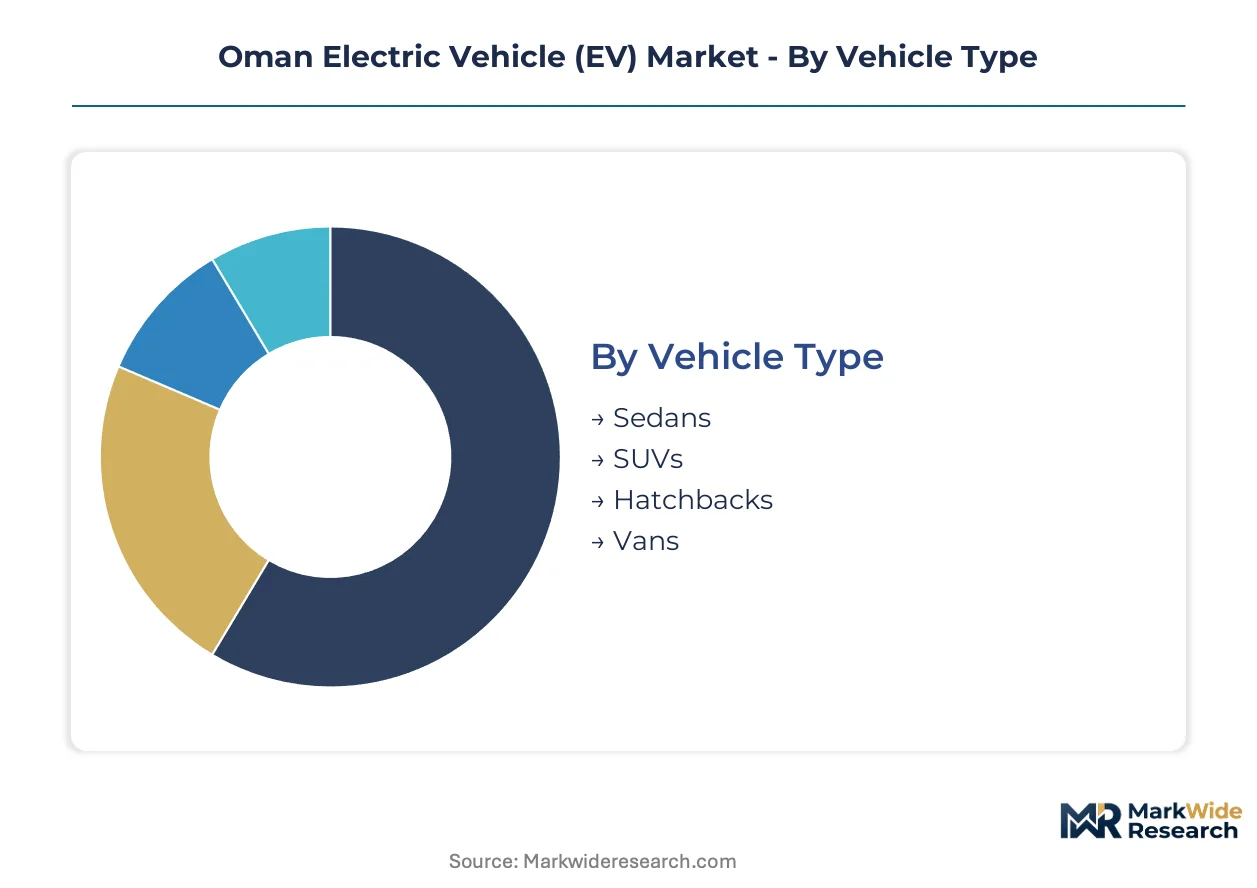
Segmentation in Oman's EV market reveals how procurement authority concentrates across distinct customer archetypes, each subject to divergent regulatory compliance burdens. Fleet operators and government agencies navigate Authority for Electricity Regulation licensing requirements that individual consumers bypass entirely.
Vehicle Type:
Sedans and SUVs carry mandatory type-approval certifications from the Ministry of Transport, Communications and Information Technology, while commercial vans face additional payload safety inspections before fleet registration.
- Sedans:Four-door passenger configurations with 400-600 km range ratings dominate corporate leasing channels. Procurement concentrates in Muscat Governorate banking and diplomatic sectors where chauffeur-driven service contracts prioritize rear-seat comfort and charging predictability.
- SUVs:Higher ground clearance and all-wheel-drive architectures suit family transport across Oman's varied terrain. Demand clusters in premium residential developments near Al Mouj and Madinat Sultan Qaboos where dual-vehicle households designate SUVs for weekend interior travel.
- Hatchbacks:Compact urban runabouts with sub-4-meter lengths suit single-professional households in Muscat's dense commercial districts.
- Vans:Panel and passenger van configurations serve last-mile logistics and corporate shuttle contracts subject to commercial vehicle operator licensing.
Leading the category by volume: SUVs. Expanding most quickly: Vans.
Battery Technology:
Cost tiers separate established chemistries from emerging alternatives, with thermal management requirements scaling directly with energy density and ambient temperature exposure.
- Lithium-ion:Nickel-manganese-cobalt and lithium-iron-phosphate cells constitute the incumbent production standard. Procurement dominates across all vehicle classes due to established supply chains and 150-250 Wh/kg energy densities proven in Omani summer conditions.
- Solid-state:Ceramic or polymer electrolyte configurations eliminate thermal runaway risks and enable 300+ Wh/kg densities. Development concentrates in validation protocols for 50°C+ operating environments that could reposition Oman as a high-temperature testbed.
- Nickel-metal Hydride:Mature chemistry retains niche presence in hybrid auxiliary power units and budget fleet conversions.
- Lead-acid:Flooded and AGM variants persist only in low-speed commercial vehicles and aftermarket starter battery replacements.
Highest deployment volume: Lithium-ion. Steepest R&D capital attraction: Solid-state.
Charging Infrastructure:
Application context determines hardware specifications, with grid interconnection standards from the Authority for Electricity Regulation creating tiered compliance obligations by power rating.
- Fast Chargers:DC rapid units at 50-350 kW outputs compress charging cycles to 20-40 minutes. Deployment concentrates along the Muscat-Salalah logistics corridor where fleet operators prioritize route efficiency over capital expenditure minimization.
- Home Chargers:Level 2 AC units at 7-22 kW leverage residential tariff structures. Installation concentrates in Muscat Governorate villa compounds where off-street parking availability exceeds apartment stock.
- Public Charging Stations:Destination and workplace AC installations serve dwell-time charging at retail and office locations.
- Wireless Charging:Inductive pad systems eliminate connector wear but face interoperability certification complexity across multiple vehicle platforms.
Dominant by installation count: Home Chargers. Gaining share fastest: Fast Chargers.
Customer Segment:
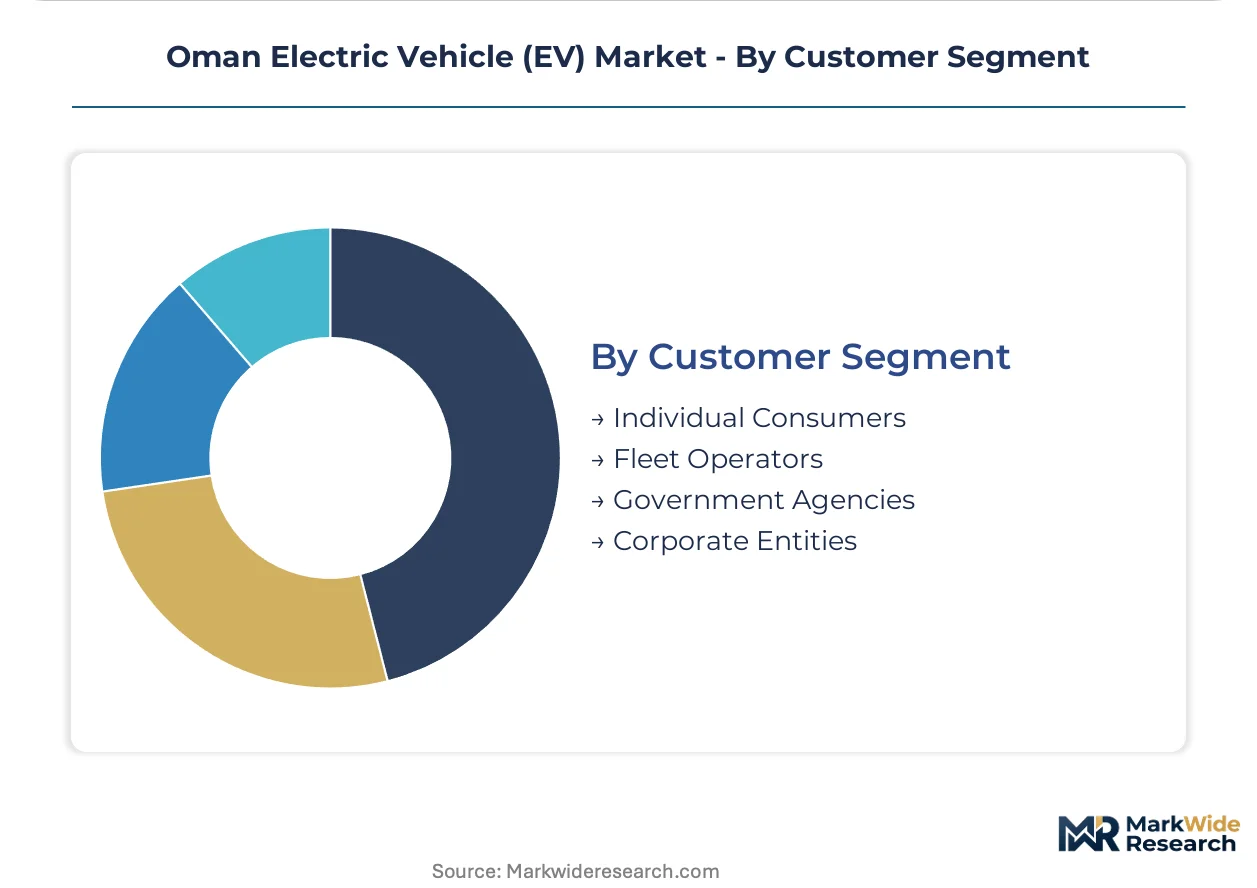
Procurement authority and volume scale inversely across this dimension, with concentrated fleet purchasing power negotiating terms unavailable to fragmented individual demand.
- Fleet Operators:Logistics, corporate transport, and rental companies aggregate vehicle orders into tender processes. Procurement concentrates in e-commerce fulfillment networks replacing diesel vans across Muscat and Salalah urban zones.
- Government Agencies:Ministry mandates enforce electrification timelines for official vehicle pools. Procurement channels through centralized tender processes that prioritize total cost of ownership over sticker price.
- Individual Consumers:Private households purchase through retail dealerships with financing packages. Demand clusters in dual-income professional segments with villa parking and solar rooftop installations.
- Corporate Entities:Non-transport businesses acquire EVs for executive mobility and facility maintenance fleets.
Highest volume concentration: Fleet Operators. Fastest policy-mandated expansion: Government Agencies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Duqm Special Economic Zone is concentrating industrial investment flows and logistics infrastructure that reshape EV deployment corridors across Oman's governorates.
Muscat Governorate
Corporate leasing channels and premium residential developments drive household SUV procurement. The Authority for Electricity Regulation mandates smart metering integration for public charging stations above 50kW. Al Mouj and Madinat Sultan Qaboos districts cluster vehicle-to-grid pilot installations.
Dhofar Governorate
Port logistics zones and transshipment corridors generate demand for electric heavy-duty trucks serving Yemen and East Africa trade routes. The Ministry of Transport enforces commercial vehicle operator licensing for fleet registrations. Salalah's free trade infrastructure anchors charging corridor investments along the Muscat-Salalah logistics axis.
Al Batinah Governorate
Industrial zone workforce transport contracts and coastal manufacturing facilities sustain mid-size sedan fleet orders. Building codes mandating charging readiness in new commercial developments influence property developer procurement. Sohar Port vicinity concentrates corporate shuttle electrification programs.
Ad Dakhiliyah Governorate
Interior region temperature exposure accelerates battery thermal management validation protocols for solid-state R&D. National EV policy framework establishes licensing pathways that determine infrastructure deployment velocity. Nizwa's educational institutions host technician training pipeline development for high-voltage diagnostics.
Oman Electric Vehicle (EV) Market Competitive Landscape
Top-tier vendors anchor premium SUV and sedan segments, while mid-tier specialists compete on battery cost structures and commercial van configurations. The competitive landscape stratifies across three tiers: legacy automakers with regional assembly partnerships, battery-integrated Chinese manufacturers, and emerging local distributors. Consolidation pressures concentrate procurement authority in fleet tender processes. Dominant competitive moves include strategic partnerships for charging infrastructure deployment and portfolio diversification across vehicle classes.
Within the premium-tier vector, BMW occupies a position exemplifying corporate leasing channel penetration. Among battery-cost-driven specialists, BYD represents the archetype of government tender competitiveness. Tesla sits within the direct-to-consumer segment, anchoring brand positioning in residential charging ecosystems. Hyundai Motor Company exemplifies regional assembly partnership strategies that sustain commercial van market access.
| Leading Market Players |
|---|
| Tesla |
| BMW |
| Hyundai Motor Company |
| Nissan |
| Renault Group |
| BYD |
| Chevrolet |
| MG Motor |
| Mays |
| Others |
Pricing and Supply Chain Analysis
Oman's national EV policy framework and Authority for Electricity Regulation charging infrastructure mandates gate both qualified supply access and premium-tier pricing eligibility for fleet operators and property developers across Muscat Governorate.
Pricing Analysis
Lead-time-driven pricing stratification separates fleet procurement channels in Oman's EV market, with commercial operators paying premiums for accelerated delivery schedules while spot inventory from regional distributors trades at compressed margins. Three-tier pricing structure across premium, standard, and economy levels reflects battery chemistry grade, thermal management certification tier, and after-sales service bundling. Cost compression in the commercial van segment is intensifying because BYD and Chinese manufacturers are undercutting legacy OEM battery cost structures. Fleet operators exhibit highest price sensitivity due to total cost of ownership procurement criteria, while diplomatic and oil services corporate leasing channels show lowest sensitivity to sticker price premiums.
Supply Chain Analysis
Authority for Electricity Regulation grid interconnection certification and Ministry of Transport type-approval protocols gate supplier market access, filtering hardware vendors and vehicle platforms eligible for government tender participation. Battery cell production concentrates in China, South Korea, and Japan, drawing from nickel-manganese-cobalt cathode materials, lithium carbonate feedstock, and ceramic electrolyte precursors. Single-source vulnerability in East Asian cell manufacturing exposes Omani fleet operators to shipping cost volatility and extended order lead times. Distribution runs through regional assembly partnerships in the Gulf and direct import channels from Chinese manufacturers, with local distributors handling warranty and service localization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oman's EV market sits in a technology-transition phase as solid-state battery architectures displace incumbent lithium-ion configurations for high-temperature climate applications.
For Market Incumbents: Deepen backward integration into battery thermal management systems and high-voltage diagnostics training pipelines to defend against Chinese manufacturers' cost advantages and technician scarcity bottlenecks. Anchor fleet tender participation through charging infrastructure deployment partnerships that lock in route corridor access along the Muscat-Salalah logistics axis. For New Entrants and Emerging Players: Capture underpenetrated demand in Dhofar Governorate's port logistics zones for electric heavy-duty trucks serving transshipment corridors to Yemen and East Africa. Target Salalah's free trade infrastructure with battery-swapping service models that bypass grid interconnection delays and compress fleet asset utilization rates. For Investors and Strategic Acquirers: Solid-state battery R&D capital flows into high-temperature validation protocols is the leading indicator that Oman could reposition as a climate-specific testbed hub. Long-term viability rests on charging infrastructure operator consolidation and energy service company battery-residual-value risk models. Monitor Authority for Electricity Regulation tariff structure revisions as the inflection signal for distributed storage asset monetization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Locks in lithium-ion cell allocation from East Asian manufacturers for fleet scale deployment. |
| Charging Infrastructure Partnership | Secures grid interconnection priority with Authority for Electricity Regulation for corridor development. |
| Technician Training Pipeline Investment | Addresses high-voltage diagnostics scarcity extending vehicle downtime for commercial operators. |
| Vehicle-to-Grid Platform Integration | Enables peak shaving revenue streams for property developers in Al Mouj and Madinat Sultan Qaboos. |
| Solid-State Battery Validation Program | Positions Oman as high-temperature testbed for ceramic electrolyte thermal safety protocols. |
Research Methodology
Ministry of Transport regulatory filings, Authority for Electricity Regulation grid interconnection standards, and Oman National Statistics Office trade data formed the secondary backbone, supplemented by primary interviews with fleet procurement managers, charging infrastructure developers, property developer technical directors, and automotive distributor operations heads. Bottom-up and top-down triangulation validated vehicle registration trends against utility-scale charging deployment pipelines and government tender award records.
Bottom-up modeling anchored volume projections in fleet operator replacement cycles, government mandate timelines, and residential solar-plus-storage adoption patterns across the analysis window. Segmentation dimensions included vehicle class, battery technology tier, charging infrastructure type, and customer procurement authority. CAGRs derived from logistic diffusion curves fitted to infrastructure availability constraints and policy implementation schedules. Forecast inputs incorporated grid capacity allocation timelines and solid-state battery R&D commercialization trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to lithium-ion supply chain disruptions and solid-state technology validation timelines. Model assumptions reflect Authority for Electricity Regulation tariff structures and Ministry of Transport fleet conversion mandates. A model refresh is warranted upon material change in national EV policy framework implementation velocity or grid interconnection standard revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Asia Pacific Automotive High Performance Electric Vehicles Market
Electric Vehicles
E-Bike Market
Electric Vehicles
North America Electric Vehicle Thermal Management System Market
Electric Vehicles
Electric Vehicle HVAC Market
Electric Vehicles
Mexico Automotive High Performance Electric Vehicle Market
Electric Vehicles
Global Smart Electric Drive Market
Electric Vehicles
Fuel-Cell Electric Vehicle Insulation Market
Electric Vehicles
EV Taxi Market
Electric Vehicles
China Electric Truck Market
Electric Vehicles
Asia-Pacific Electric Bus Market
Electric Vehicles
Automotive Electric Vehicle Power System Market
Electric Vehicles
Electric Shuttle Market
Electric Vehicles
Global Electric Vehicles Market
Electric Vehicles
Poland E-Bike Market
Electric Vehicles
US Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
India Electric Vehicle Financing Market