
 India Electric Rickshaw Market | 2026-2036
India Electric Rickshaw Market Size, Share, and Industry Trends Forecast 2026-2036
India Electric Rickshaw Market Outlook
Multi-source battery procurement is recalibrating cost structures across the India electric rickshaw supply chain. Mahindra Electric leverages its captive distribution network to secure fleet contracts in tier-2 cities. Kinetic Green anchors its position through dedicated R&D on lithium-ion retrofit kits for existing lead-acid fleets. YC Electric dominates the unorganized segment with ultra-low-cost assembly models priced for individual owner-operators.
An electric rickshaw is a three-wheeled battery-powered vehicle with a DC motor rated between 650W and 1,500W, designed for short-haul passenger or cargo transport at speeds below 25 km/h. The chassis typically uses mild steel tubular construction with a fiberglass or metal roof, while the drivetrain integrates a brushless DC motor with a controller unit and either lead-acid or lithium-ion battery packs. Passenger E-Rickshaws sustain the dominant revenue share due to established financing channels and high daily trip frequency in urban slum corridors. Cargo E-Rickshaws represent the fastest-expanding product category as e-commerce delivery services replace diesel vans and manual carts in congested city centers. Battery Type segmentation reveals a structural margin shift: lithium-ion variants command higher upfront pricing but deliver superior total cost of ownership through extended cycle life and reduced downtime.
BIS certification mandates for electric vehicle components, combined with FAME-II subsidy disbursement protocols administered by CEA and state nodal agencies, determine market access and effective pricing for manufacturers. The PLI scheme for advanced chemistry cell manufacturing is reshaping domestic battery sourcing economics, with implications for assembler procurement strategies. Stakeholders must monitor state-level EV policy revisions and swapping infrastructure tenders to anticipate demand inflection points before competitors lock in fleet partnerships.
Market Dynamics
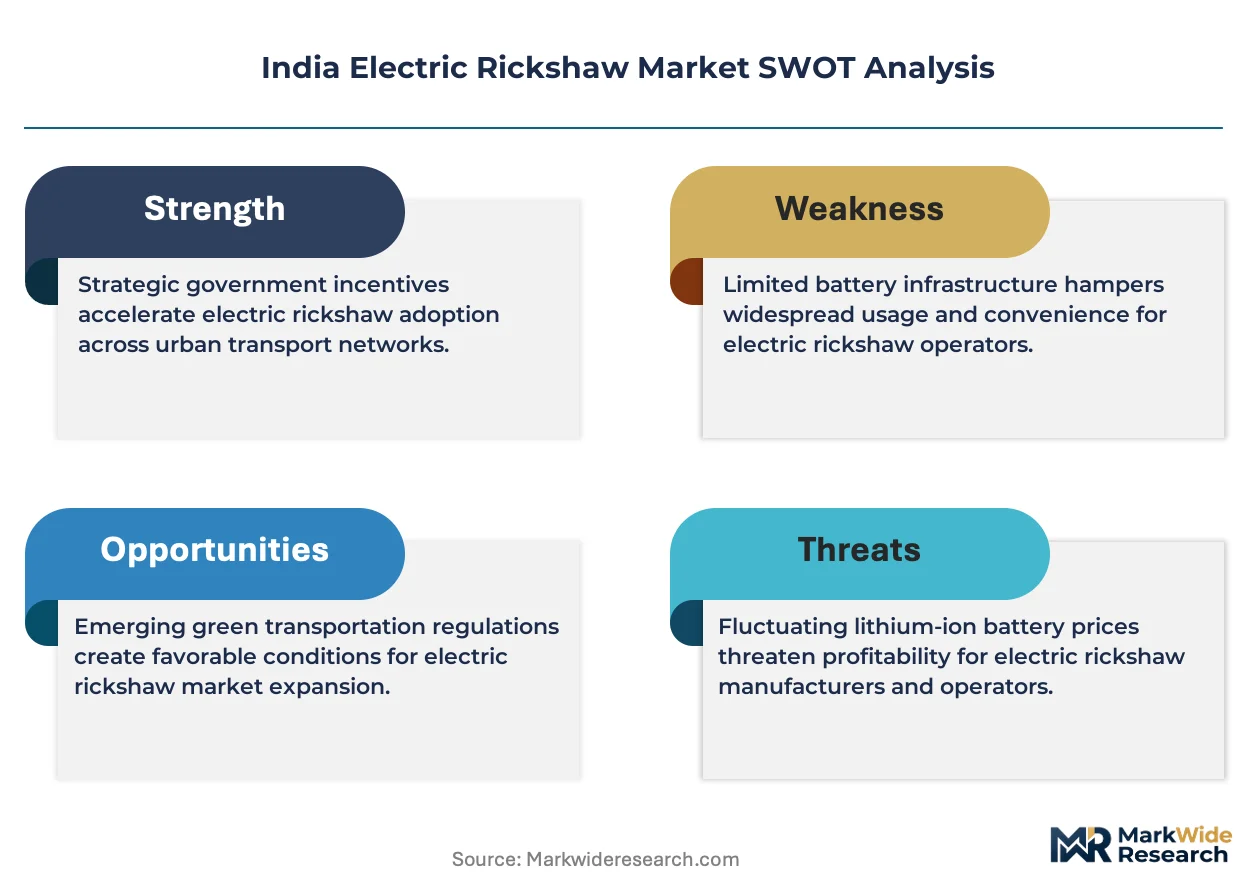
The India electric rickshaw market is being fundamentally restructured by the PLI scheme for advanced chemistry cell manufacturing, which is compressing battery procurement costs and forcing assembler business models toward captive lithium-ion integration.
Growth Catalysts
- FAME-II subsidy disbursement:The CEA-administered incentive regime reduces upfront vehicle acquisition costs for fleet operators in Uttar Pradesh and Bihar, accelerating replacement of lead-acid fleets.
- E-commerce last-mile density:Urban logistics platforms in Delhi-NCR and Mumbai are standardizing cargo e-rickshaw specifications for parcel consolidation, creating dedicated demand pull.
- Swappable battery infrastructure:State nodal agencies in West Bengal and Madhya Pradesh are tendering swapping station networks that eliminate range anxiety for owner-operators without home charging access.
Market Restraints
- Lithium cell import concentration:Domestic assemblers remain dependent on Chinese cylindrical cell suppliers, exposing margins to yuan-rupee volatility and DGFT licensing delays.
- BIS certification bottlenecks:Component-level testing mandates for controllers and battery management systems extend product launch timelines by four to six months.
- Lead-acid residual value collapse:The secondary market for used lead-acid battery packs is evaporating as scrap dealers face environmental compliance costs under state pollution control board directives.
Strategic Opportunities
- Tier-3 city electrification:Unpenetrated districts in Jharkhand and Chhattisgarh lack organized financing channels, creating first-mover advantage for asset-light leasing models.
- Refrigerated cargo retrofit kits:Integration of thermoelectric cooling units with standard cargo chassis addresses pharmaceutical and fresh produce logistics gaps in Hyderabad and Bangalore.
- State EV policy arbitrage:Gujarat and Tamil Nadu are extending registration fee waivers and road tax exemptions beyond FAME-II timelines, incentivizing fleet registration migration.
Industry Challenges
- Skilled technician scarcity:Brushless DC motor diagnostics and lithium-ion thermal management repair capabilities are concentrated in tier-1 service centers, leaving tier-2 operators dependent on manufacturer dispatch.
- Swap station interoperability:Proprietary battery form factors from competing OEMs prevent standardized swapping infrastructure, fragmenting capital deployment across incompatible networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Electric Rickshaw Market |
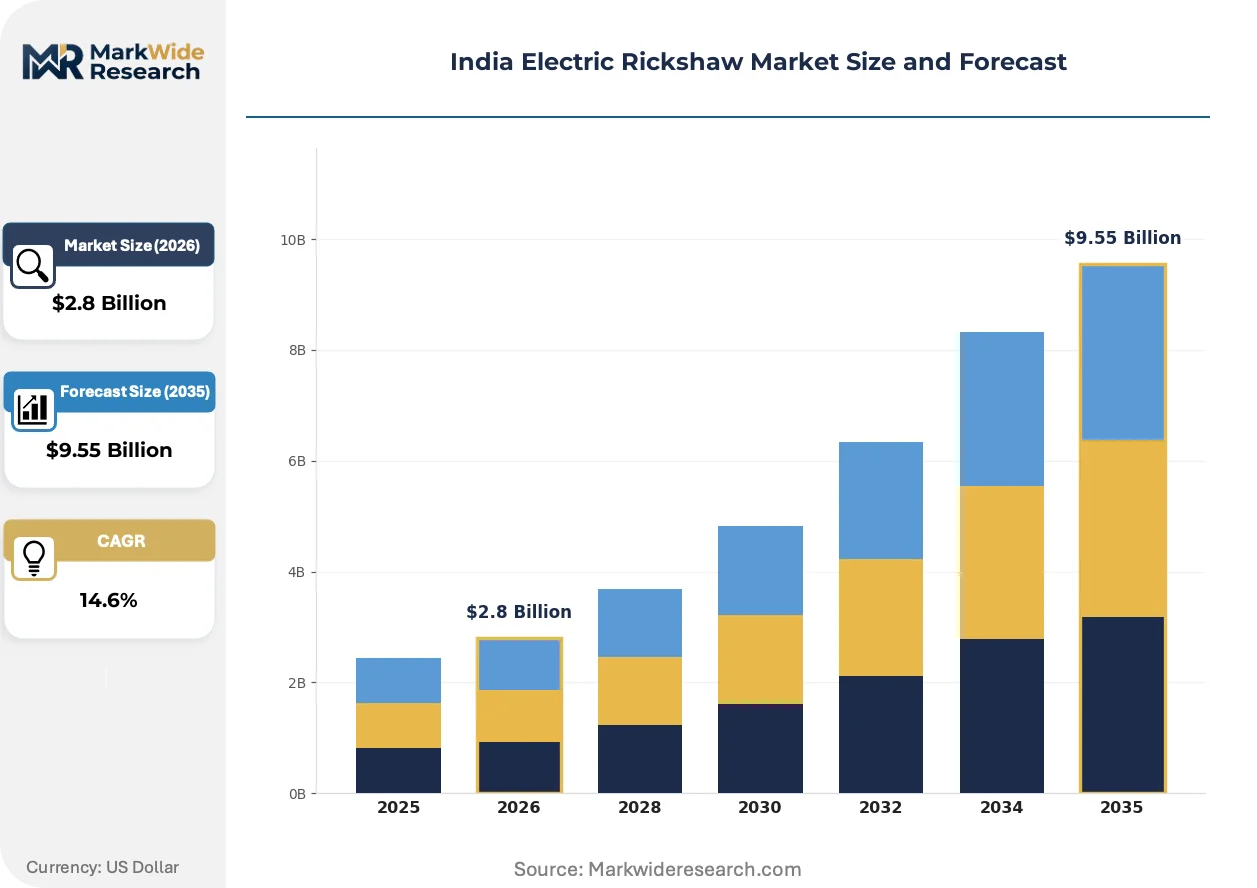
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passenger E-Rickshaws, Cargo E-Rickshaws, E-Autos, E-Loaders End User: Public Transportation, Private Owners, Delivery Services, Ride-Hailing Battery Type: Lithium-ion, Lead-acid, Nickel Metal Hydride, Others Charging Infrastructure: Fast Charging Stations, Battery Swapping, Home Charging, Commercial Charging |
| Companies Covered | Mahindra Electric, City Life, Zeniak Innovation, Atul Auto, Kinetic Green, YC Electric, Piaggio, Bajaj Auto, Hooghly Motors, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Electric Rickshaw Market Strategic Shifts
Battery chemistry migration and digital fleet management tools are compressing total cost of ownership calculations while restructuring how owner-operators access vehicle financing and after-sales support across Indian urban corridors.
Lithium iron phosphate cell chemistry is converging with modular battery architecture to enable hot-swappable configurations without specialized lifting equipment. Fleet operators in Kolkata and Lucknow are adopting these standardized packs to minimize vehicle downtime during shift changes. The technology is converging with telematics platforms that track state-of-health metrics, allowing residual value-based secondary market trading of battery assets.
BIS certification mandates for electric vehicle components are tightening testing protocols for motor controllers and battery management systems under CEA technical specifications. Manufacturers must now submit accelerated lifecycle test data before subsidy eligibility approval, compressing the competitive set to firms with captive testing facilities. The regulatory burden falls heaviest on unorganized assemblers in Delhi's Mayapuri industrial cluster, who lack capital for upgraded validation equipment.
Third-party fleet management platforms are unbundling vehicle ownership from operational control, allowing aggregator apps to match idle e-rickshaw capacity with demand spikes across multiple logistics clients. Owner-operators in Varanasi and Patna are leasing drive time to e-commerce and food delivery platforms rather than committing to single-contract cargo exclusivity. This behavioral pivot is most visible in dense old-city commercial districts where parking constraints and narrow lanes favor distributed small-format logistics over van-based delivery.
India Electric Rickshaw Market Segmentation
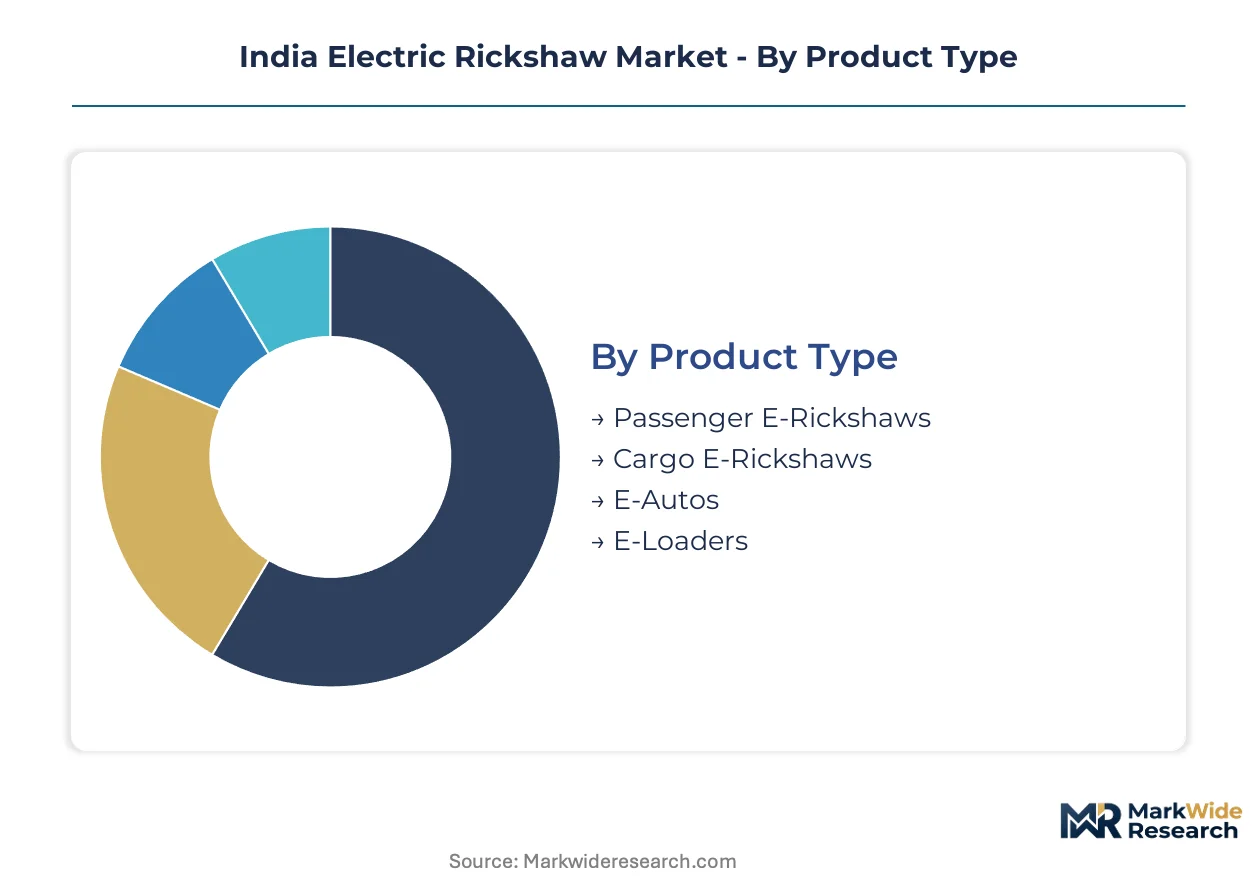
Segmentation in the India electric rickshaw market reveals how buyer priorities diverge across operational intensity, financing access, and infrastructure availability. Each category exposes distinct margin structures and regulatory touchpoints that determine assembler strategy and fleet procurement patterns.
Product Type:
Buyers in this category separate by trip frequency and payload requirements rather than upfront price sensitivity alone.
- Passenger E-Rickshaws:Three-wheeled configurations with 4-6 passenger capacity and 650W-1,200W brushless DC motors dominate urban last-mile mobility. Demand concentrates in Uttar Pradesh and Bihar slum corridors where established microfinance channels enable daily owner-operator income cycles.
- Cargo E-Rickshaws:Reinforced chassis designs with 500-800 kg payload ratings and extended wheelbases serve e-commerce parcel consolidation. Delhi-NCR logistics platforms are standardizing these specifications to replace diesel vans in congested old-city districts.
- E-Autos:Enclosed cabin variants with higher motor ratings and weather protection command premium positioning for inter-city short hauls. These units attract fleet investors in Gujarat and Tamil Nadu seeking registration fee waiver arbitrage beyond FAME-II timelines.
- E-Loaders:Heavy-duty flatbed configurations with 1,000W+ motors target industrial material movement and agricultural produce transport. Demand remains concentrated in peri-urban Madhya Pradesh and Chhattisgarh manufacturing belts.
Passenger E-Rickshaws lead volumes today; Cargo E-Rickshaws are climbing the fastest.
End User:
Financing access and utilization predictability distinguish buyers across this dimension.
- Public Transportation:State urban development authorities and municipal corporations procure through tender processes for metro feeder services and transit gap bridging. Bihar and West Bengal nodal agencies bundle vehicle purchases with charging infrastructure deployment.
- Private Owners:Individual entrepreneurs operating 1-3 vehicles constitute the unorganized segment backbone. These buyers prioritize ultra-low entry prices and localized after-sales networks in tier-3 districts of Jharkhand and Rajasthan.
- Delivery Services:E-commerce platforms and third-party logistics providers standardize fleet specifications for parcel density optimization. These operators in Mumbai and Bangalore drive cargo chassis adoption with telematics integration requirements.
- Ride-Hailing:Aggregator-app drivers leasing vehicle access by shift represent an emerging category. Kolkata and Lucknow operators are migrating toward this model to reduce single-client dependency and maximize asset utilization.
Private Owners anchor current fleet composition; Delivery Services are expanding most quickly.
Battery Type:
Total cost of ownership calculations and subsidy eligibility criteria drive buyer selection here.
- Lithium-ion:Lithium iron phosphate cell chemistry with 2,000+ cycle life and thermal stability enables swappable modular architectures. Fleet operators in West Bengal and Madhya Pradesh are adopting these packs to qualify for FAME-II incentive disbursement protocols administered by CEA.
- Lead-acid:Flooded and VRLA variants with 300-500 cycle life retain price advantage for individual owner-operators without formal financing. Uttar Pradesh and Bihar unorganized assemblers continue sourcing these packs despite collapsing secondary market residual values under state pollution control directives.
- Nickel Metal Hydride:Intermediate chemistry with moderate energy density finds niche application in temperature-sensitive hill station deployments. Limited presence in Himachal Pradesh and Uttarakhand tourist corridor fleets.
- Others:Emerging sodium-ion and solid-state prototypes remain pre-commercial, with pilot deployments restricted to OEM testing programs and academic research partnerships.
Lead-acid retains volume leadership; Lithium-ion is gaining share fastest.
Charging Infrastructure:
Real estate access and grid reliability determine buyer preference across this category.
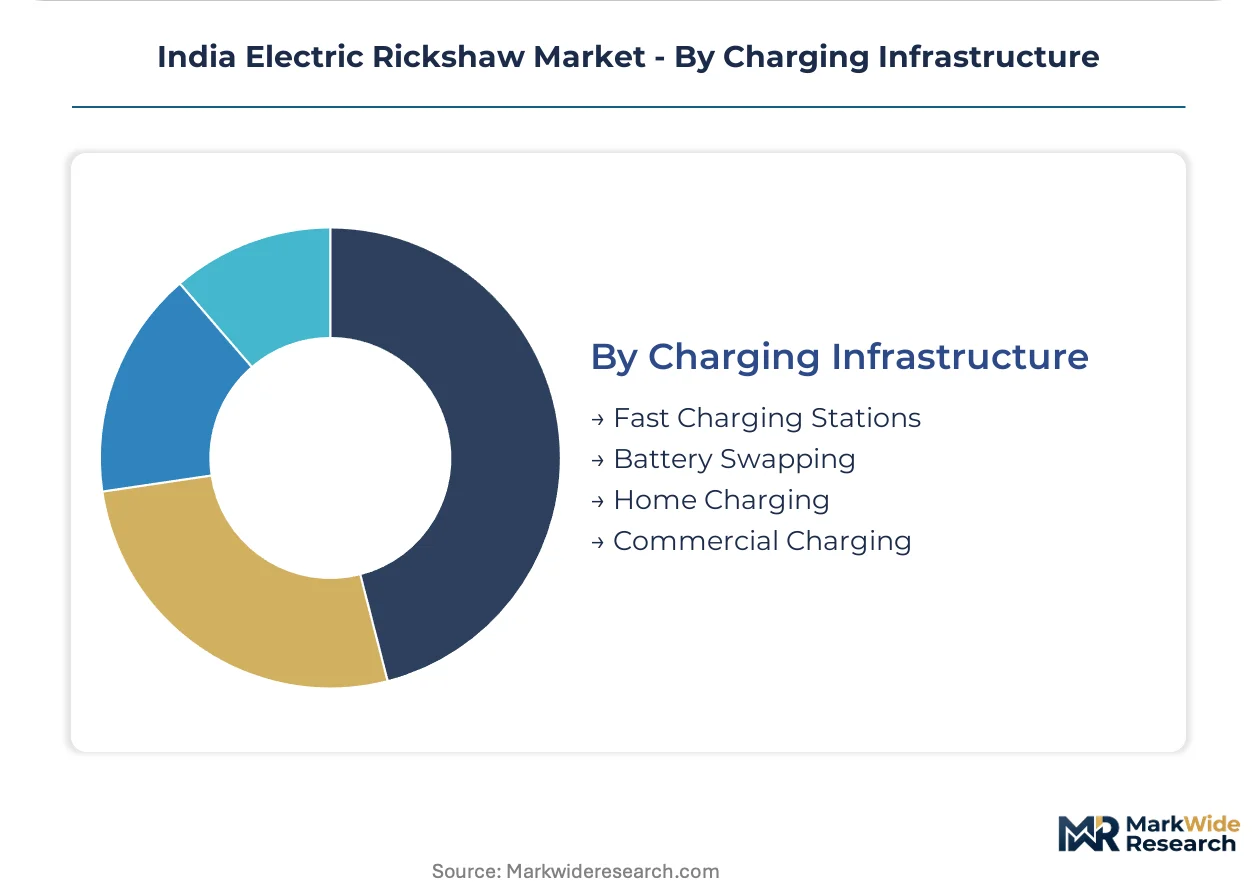
- Fast Charging Stations:15-30 kW DC infrastructure requiring dedicated electrical connections and commercial land titles. Deployment concentrates in Delhi-NCR and Mumbai logistics hubs serving high-rotation cargo fleets.
- Battery Swapping:Standardized pack exchange networks eliminate downtime for operators without overnight parking security. State nodal agencies in West Bengal and Madhya Pradesh are tendering interoperable swapping station rollouts.
- Home Charging:220V AC overnight charging through residential meter connections dominates individual owner-operator behavior. Prevalent in dense urban slum corridors across Varanasi, Patna, and Kanpur.
- Commercial Charging:Shared AC charging points at market complexes and transport terminals serve fragmented fleet operators. Hyderabad and Bangalore are piloting these configurations for pharmaceutical delivery corridor electrification.
Home Charging leads volumes today; Battery Swapping is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Delhi-NCR anchors production capacity for electric rickshaw assembly, with component sourcing networks extending into Haryana and Uttar Pradesh industrial belts. State-level EV policies and FAME-II subsidy disbursement protocols administered by CEA are redistributing fleet procurement across India's northern and eastern corridors.
Uttar Pradesh
Daily trip density in Kanpur and Varanasi slum corridors sustains passenger e-rickshaw utilization rates above 12 hours per vehicle. The state nodal agency bundles FAME-II incentive disbursement with localized microfinance channel activation. Unorganized assemblers in Ghaziabad and Meerut supply ultra-low-cost lead-acid variants to individual owner-operators.
Bihar
Patna and Muzaffarpur logistics platforms are standardizing cargo chassis specifications for e-commerce parcel consolidation. Bihar's urban development authority procures passenger units through tender processes for metro feeder services. Dense old-city commercial districts in these cities favor distributed small-format logistics over van-based delivery.
West Bengal
Kolkata fleet operators adopt lithium iron phosphate swappable packs to minimize downtime during shift changes. The state nodal agency tenders interoperable battery swapping station networks across the Kolkata Metropolitan Area. Hooghly district assemblers concentrate on fiberglass body fabrication for weather-protected cabin variants.
Gujarat
Registration fee waivers and road tax exemptions beyond FAME-II timelines attract fleet investors to Ahmedabad and Surat. Gujarat's EV policy extends subsidy eligibility to enclosed-cabin e-auto configurations for inter-city short hauls. Industrial material movement demand in Vadodara's manufacturing belt drives e-loader procurement.
Tamil Nadu
Chennai's logistics platforms specify telematics-integrated cargo e-rickshaws for pharmaceutical delivery corridor electrification. The state maintains registration fee waivers that incentivize fleet registration migration from neighboring states. Coimbatore's component fabrication clusters supply brushless DC motor assemblies to upstream assemblers.
India Electric Rickshaw Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue lithium-ion retrofit specialization and swappable battery integration. The vendor base stratifies across three tiers: organized OEMs with captive distribution networks, mid-scale assemblers with regional financing partnerships, and unorganized fabricators serving price-sensitive owner-operators. Strategic archetypes include backward-integrated battery specialists, asset-light leasing platform operators, and component-agnostic contract assemblers. Dominant competitive moves encompass state-level fleet partnership lock-ins and PLI scheme qualification for advanced chemistry cell procurement.
Within the organized OEM tier, Mahindra Electric and Kinetic Green occupy positions anchored by captive R&D infrastructure and distribution network scale. YC Electric exemplifies the unorganized segment archetype through ultra-low-cost assembly models priced for individual owner-operators. Bajaj Auto and Piaggio represent legacy two-wheeler and three-wheeler manufacturers extending portfolio diversification into electrified configurations. Atul Auto, City Life, and Hooghly Motors sit within the regional specialist category with concentrated presence in specific state markets. Zeniak Innovation occupies a position among emerging entrants targeting technology differentiation vectors.
| Leading Market Players |
|---|
| Mahindra Electric |
| City Life |
| Zeniak Innovation |
| Atul Auto |
| Kinetic Green |
| YC Electric |
| Piaggio |
| Bajaj Auto |
| Hooghly Motors |
| Others |
Value Chain & Pricing Dynamics
Lithium iron phosphate cell chemistry migration is compressing battery pack costs while concentrating procurement leverage among assemblers with PLI scheme qualification for advanced chemistry cell manufacturing. This dual shift simultaneously reshapes cost economics across passenger and cargo configurations and redistributes margin capture toward firms with captive lithium-ion integration capabilities in Uttar Pradesh and Bihar industrial corridors.
Pricing Analysis
Input-cost pass-through from Chinese cylindrical cell suppliers is intensifying price volatility for unorganized assemblers lacking multi-year offtake contracts. Three-tier pricing structure across premium, standard, and economy levels separates organized OEMs with BIS-certified lithium-ion configurations from lead-acid assemblers in Delhi's Mayapuri cluster. Price differentiation hinges on battery chemistry certification grade and after-sales service bundling. Cost compression in economy tiers is accelerating because scrap dealers face environmental compliance costs under state pollution control board directives. Individual owner-operators in tier-3 districts exhibit highest price sensitivity; fleet operators with FAME-II subsidy access show lowest.
Supply Chain Analysis
Dual-sourcing requirements from CEA subsidy protocols mandate assemblers qualify at least two battery suppliers before FAME-II disbursement eligibility. Geographic supply concentration centers on China for cylindrical lithium cells, South Korea for battery management systems, and domestic Gujarat and Tamil Nadu for brushless DC motor assemblies. Raw material dependencies span lithium carbonate, copper winding wire, and mild steel tubular chassis components. Supply chain risk rests on DGFT licensing delays for Chinese cell imports. Distribution runs through captive OEM networks in tier-2 cities, regional financing partnerships in Bihar and West Bengal, and unorganized fabricator clusters serving price-sensitive owner-operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's electric rickshaw market functions as a geographic-arbitrage play where Gujarat and Tamil Nadu registration fee waivers beyond FAME-II timelines attract fleet migration from subsidy-dependent northern states. This regulatory differential creates cost advantages for enclosed-cabin e-auto configurations in western and southern corridors.
For Market Incumbents: Cement fleet partnership lock-ins through swappable battery infrastructure deployment in Kolkata and Lucknow before state nodal agency tenders close. Deepen backward integration into lithium iron phosphate pack assembly to offset Chinese cell import volatility. Prioritize BIS certification investment for motor controllers to extend product launch timelines as competitive moat against unorganized assemblers lacking validation capital.
For New Entrants and Emerging Players: Launch via asset-light leasing models targeting unpenetrated tier-3 districts in Jharkhand and Chhattisgarh where organized financing channels remain absent. Penetrate refrigerated cargo retrofit kits for pharmaceutical logistics in Hyderabad and Bangalore corridors. Pursue interoperability partnerships with state swapping station networks to bypass proprietary battery form factor fragmentation.
For Investors and Strategic Acquirers: Valuations sit cheapest among unorganized assemblers with lead-acid legacy exposure facing residual value collapse under environmental compliance directives. Long-term viability over the next decade hinges on lithium-ion retrofit capability and PLI scheme qualification for advanced chemistry cell procurement. Watch state EV policy revision timing as inflection indicator for fleet registration migration patterns.
| Strategic Initiative | Industry Significance |
|---|---|
| Swappable Battery Infrastructure Deployment | State nodal agency tenders in West Bengal and Madhya Pradesh eliminate range anxiety for owner-operators without home charging access. |
| Backward Integration into Lithium-Ion Pack Assembly | PLI scheme qualification compresses procurement costs and insulates margins from yuan-rupee volatility. |
| Refrigerated Cargo Retrofit Development | Thermoelectric cooling integration addresses pharmaceutical and fresh produce logistics gaps in southern corridors. |
| Asset-Light Leasing Platform Launch | Unbundled vehicle ownership models penetrate tier-3 districts lacking organized microfinance channels. |
| BIS Certification Investment | Accelerated lifecycle test data submission compresses competitive set to firms with captive validation facilities. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with OEM procurement heads, state nodal agency officials, fleet operator associations, battery supplier technical directors, and tier-2 service center technicians alongside secondary validation. Secondary sources encompassed CEA FAME-II disbursement records, BIS certification registries, state pollution control board directives, customs import data for lithium cells, and PLI scheme applicant disclosures. Bottom-up vehicle deployment estimates triangulated against top-down subsidy allocation trajectories.
Comparable-period anchoring tied projection assumptions to historical FAME-II utilization rates and state EV policy implementation timelines across the analysis window. Segmentation dimensions modeled included product type, battery chemistry, end-user financing access, and charging infrastructure availability alongside regional regulatory cluster differentiation. CAGRs derived from logistic adoption curves fitted to fleet replacement cycles and e-commerce logistics penetration trajectories. Industry-specific inputs incorporated BIS certification timeline distributions and swapping station deployment schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under DGFT licensing disruption or lithium cell import restriction scenarios. Deviation in state EV policy waiver extensions beyond FAME-II timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Vehicle on Board Charger Market
Electric Vehicles
E-Bike Lithium-Ion Battery Market
Electric Vehicles
Electric Vehicle Thermal Management Market
Electric Vehicles
Global Electric Light Commercial Vehicles Market
Electric Vehicles
AC BEV On-Board Charger Market
Electric Vehicles
Two-Wheeled Electric Vehicle Battery Market
Electric Vehicles
Commercial Vehicle Traction Battery Systems Market
Electric Vehicles
Mexico Automotive High Performance Electric Vehicle Market
Electric Vehicles
Electric Sports Utility Vehicle (E-SUV) Market
Electric Vehicles
Global Electric Vehicle (EV) Management Solution Market
Electric Vehicles
China Electric Truck Market
Electric Vehicles
Silicone in Electric Vehicles Market
Electric Vehicles
Foldable Electric Car Market
Electric Vehicles
Solar Powered Electric Vehicle Market
Electric Vehicles
Electric Tuk-Tuks Market
Electric Vehicles
France Solar E-Bike Market