
 Japan E-Bike Market | 2026-2036
Japan E-Bike Market Size, Share, and Industry Trends Forecast 2026-2036
Japan E-Bike Market Outlook
Urban commuters over age fifty-five is reorganizing the Japan e-bike demand profile, displacing recreational cyclists as the dominant buyer archetype. Yamaha Motor Co Ltd leverages its domestic manufacturing footprint to sustain price competitiveness against import-heavy rivals. Panasonic anchors the premium segment through proprietary drive systems and battery integration. Shimano competes on component standardization, extending its bicycle drivetrain dominance into electric-assist architectures.
An e-bike integrates an electric motor with pedal-assist or throttle-based propulsion, typically employing a 250-watt motor and lithium-ion battery pack to supplement human power up to speeds of 24 kilometers per hour under Japanese road traffic law. The primary purpose centers on reducing physical exertion during urban commutes and enabling cargo transport across hilly terrain. City e-bikes occupy the volume core, reflecting dense metropolitan infrastructure and parking constraints, while folding e-bikes represent the fastest-expanding product type as rail-intermodal commuters seek portability. Lithium-ion batteries dominate the power segment, displacing lead acid alternatives as energy density improves and METI safety certification streamlines pack approvals.
METI administers purchase subsidy frameworks that directly shape consumer affordability thresholds, while Japan's Road Traffic Law governs motor wattage limits and mandatory helmet provisions for specific rider categories. JIS standards for electrical bicycle systems establish baseline safety and interoperability requirements that manufacturers must satisfy for domestic market access. Stakeholders must monitor whether METI expands subsidy eligibility to commercial delivery fleets, a decision that would redirect production capacity toward ruggedized, high-cycle battery configurations.
Market Dynamics
METI's subsidy expansion for electric mobility is compressing price thresholds and accelerating replacement cycles among aging urban commuters across Greater Tokyo. This policy-driven affordability shift is reorganizing production priorities toward rail-intermodal portability and commercial fleet ruggedization.
Growth Catalysts
- Rail-Bike Intermodal Integration:Dense metropolitan infrastructure in Greater Tokyo enables commuters to combine bicycle and train travel, multiplying daily usage frequency and shortening replacement intervals for folding e-bike configurations.
- METI Purchase Subsidies:Direct consumer rebates reduce upfront acquisition costs for lithium-ion powered models, expanding addressable demand beyond early adopters into mass-market commuter segments.
- Last-Mile Logistics Electrification:Delivery operators including Yamato Transport deploy e-bike fleets for parcel distribution, creating commercial volume anchors that stabilize component procurement at scale.
Market Restraints
- Lithium-Ion Supply Concentration:Battery cell production concentrates among a limited supplier base including GS Yuasa, exposing assemblers to input cost volatility and allocation constraints during demand surges.
- Speed and Motor Wattage Caps:Japan's Road Traffic Law restricts assisted propulsion to 24 kilometers per hour and 250-watt motors, capping performance differentiation and limiting export compatibility with higher-threshold markets.
- Parking Infrastructure Scarcity:Dense urban land costs constrain secure bicycle parking availability, suppressing ownership rates among apartment-dwelling commuters despite subsidy accessibility.
Strategic Opportunities
- Commercial Fleet Subsidy Expansion:METI may extend purchase incentives to logistics operators, redirecting manufacturing capacity toward high-cycle battery configurations and ruggedized frame architectures.
- Osaka-Kyoto Corridor Penetration:Underdeveloped rail-intermodal cycling infrastructure in Kansai metropolitan areas offers whitespace for folding e-bike adoption among business commuters.
- Energy Density Convergence:Advances in lithium-ion cell chemistry from domestic suppliers enable lighter pack designs without sacrificing range, opening cargo-bike applications for elderly caregivers and small retailers.
Industry Challenges
- JIS Certification Timeline Compression:Electrical bicycle system approvals require extensive safety testing under evolving standards, delaying product launches and freezing inventory capital during regulatory transitions.
- Service Technician Training Gap:Rapid motor and battery integration complexity outpaces vocational education curricula, constraining after-sales network expansion into rural prefectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan E-Bike Market |
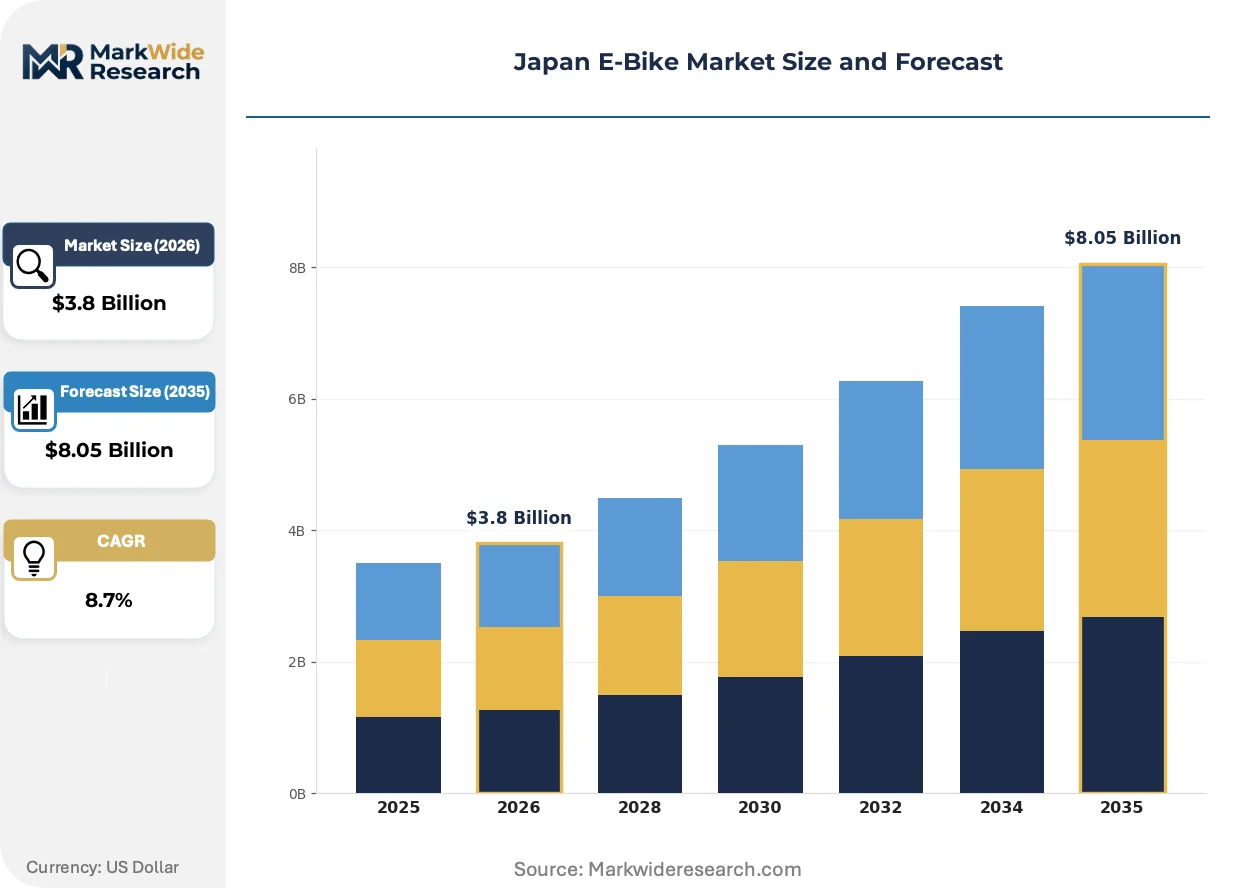
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: City E-Bikes, Mountain E-Bikes, Folding E-Bikes, Cruiser E-Bikes Battery Type: Lithium-ion, Lead Acid, Nickel-Metal Hydride, Others End User: Commuters, Recreational Users, Delivery Services, Retail Customers Distribution Channel: Online Retail, Specialty Stores, Department Stores, E-commerce Platforms |
| Companies Covered | Shimano, Giant Manufacturing Co Ltd, Yamaha Motor Co Ltd, Merida, Trek Bicycle, Panasonic, Shinsankai Co., Ltd. (ERWAY), Rad Power Bikes, Bridgestone, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan E-Bike Market Strategic Shifts
Japanese e-bike architecture is diverging along commuter and commercial lines as battery chemistry and frame design specialize for distinct usage intensities. This product stratification is compressing development cycles and forcing component suppliers to prioritize modularity.
Lithium-ion battery pack design is bifurcating between high-energy-density configurations for lightweight commuter portability and high-cycle-life architectures for commercial delivery endurance. Aging urban commuters prioritize weight reduction for rail-stair portability, while logistics operators demand cell chemistries rated for thousands of deep discharge cycles. This technical divergence is forcing assemblers to dual-source pack configurations and maintain separate inventory streams.
METI is expanding subsidy eligibility criteria to encompass commercial delivery fleets, revising framework conditions that previously restricted incentives to personal mobility. This regulatory extension incentivizes manufacturers to certify ruggedized models under JIS electrical bicycle standards, accelerating product-line diversification. Logistics operators are responding by consolidating procurement specifications to capture volume rebates.
After-sales service models are fragmentating as direct-to-consumer channels bypass traditional bicycle retailers. Online purchasers expect manufacturer-managed battery health monitoring and remote diagnostics, displacing neighborhood shop maintenance relationships. This channel shift concentrates in Greater Tokyo, where digital-native commuters prioritize convenience over established retail loyalty.
Japan E-Bike Market Segmentation
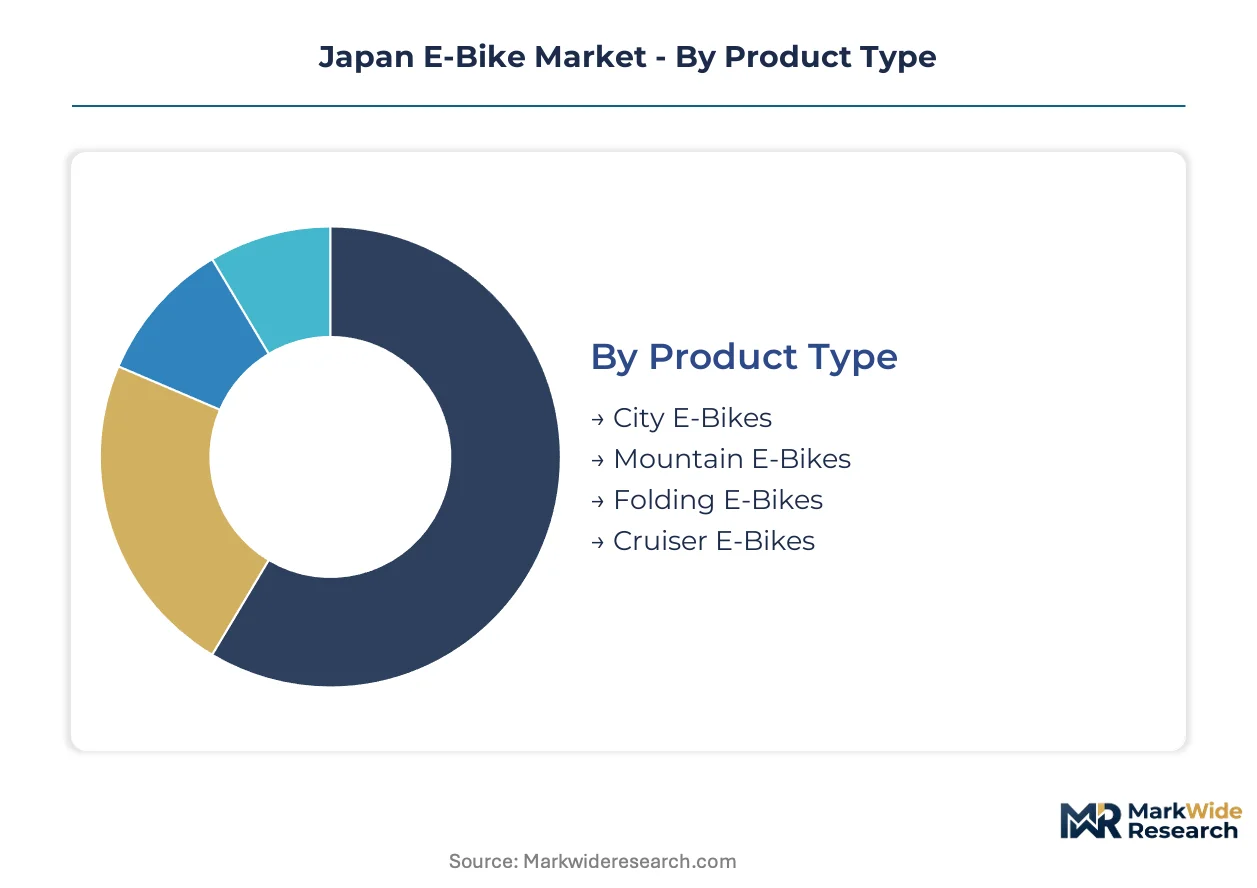
Segmentation in the Japan e-bike market reveals how subsidy eligibility, rail infrastructure density, and battery chemistry trade-offs allocate demand across distinct product configurations. Understanding these partitions clarifies where METI policy intersects with manufacturer R&D priorities.
Product Type:
Substitution pressure from compact motor scooters and shared mobility services weighs most heavily on full-frame configurations, forcing product type strategy toward portability and specialized terrain performance.
- City E-Bikes:These step-through frames integrate 250-watt mid-drive motors with enclosed battery packs optimized for stop-and-go urban traffic. Demand concentrates in Greater Tokyo's 23 wards, where METI subsidies compress payback periods against train passes for commuters over fifty-five. Parking scarcity in dense wards suppresses ownership rates despite affordability gains.
- Folding E-Bikes:Collapsible frame architectures with 16-20 inch wheels enable rail-bike intermodal travel through Tokyo Station and Shinjuku hub corridors. Yamato Transport pilots folding configurations for last-mile parcel delivery, creating commercial volume anchors that stabilize component procurement.
- Mountain E-Bikes:Suspension-equipped frames with torque-sensor pedal assist target recreational trail access in Yamanashi and Nagano prefectures. Niche positioning limits subsidy capture.
- Cruiser E-Bikes:Upright seating geometries with balloon tires emphasize comfort over efficiency for short-distance neighborhood errands. Aging suburban buyers in Saitama and Chiba prefectures drive replacement cycles.
City e-bikes retain volume leadership; folding e-bikes hold the steepest expansion curve.
Battery Type:
Cost tier stratification separates premium lithium-ion deployments from residual lead acid demand in price-sensitive commercial leasing arrangements.
- Lithium-ion:Energy density improvements from GS Yuasa and domestic cell suppliers enable 500+ charge cycle ratings within 3-kilogram pack weights. METI safety certification streamlines JIS compliance timelines, accelerating product launches for rail-intermodal commuters across Osaka-Kyoto corridors.
- Lead Acid:Heavy, low-cycle alternatives persist in third-party fleet leasing arrangements where upfront capital constraints override total cost of ownership calculations. Chubu region logistics operators maintain residual procurement.
- Nickel-Metal Hydride:Transitional chemistry occupies shrinking middle ground as lithium-ion cost curves compress price premiums. Limited new product integration.
- Others:Experimental solid-state and sodium-ion prototypes remain pre-commercial, with domestic manufacturers reserving R&D budgets for METI-funded mobility consortia.
Lithium-ion configurations command the dominant revenue share; solid-state alternatives are climbing the fastest toward commercial viability.
End User:
Customer type segmentation tracks how aging demographics and logistics electrification reshape production priorities across distinct usage intensities.
- Commuters:Daily rail-intermodal travelers in Greater Tokyo generate the highest per-unit utilization rates, shortening replacement intervals to 3-4 years. METI purchase subsidies directly target this cohort through income-adjusted rebate structures.
- Delivery Services:Yamato Transport and Sagawa Express deploy ruggedized fleet configurations rated for 50+ kilometer daily ranges and 2,000+ annual charge cycles. Commercial subsidy expansion would redirect manufacturing capacity toward high-durability battery architectures.
- Recreational Users:Weekend cyclists in rural Hokkaido and Kyushu prioritize range over portability, sustaining demand for larger frame geometries with extended-range battery options.
- Retail Customers:Small shop owners and elderly caregivers in regional cities adopt cargo-capable e-bikes for short-haul goods transport, bridging last-mile gaps where delivery fleet coverage remains thin.
Commuters retain volume leadership; delivery services hold the steepest expansion curve.
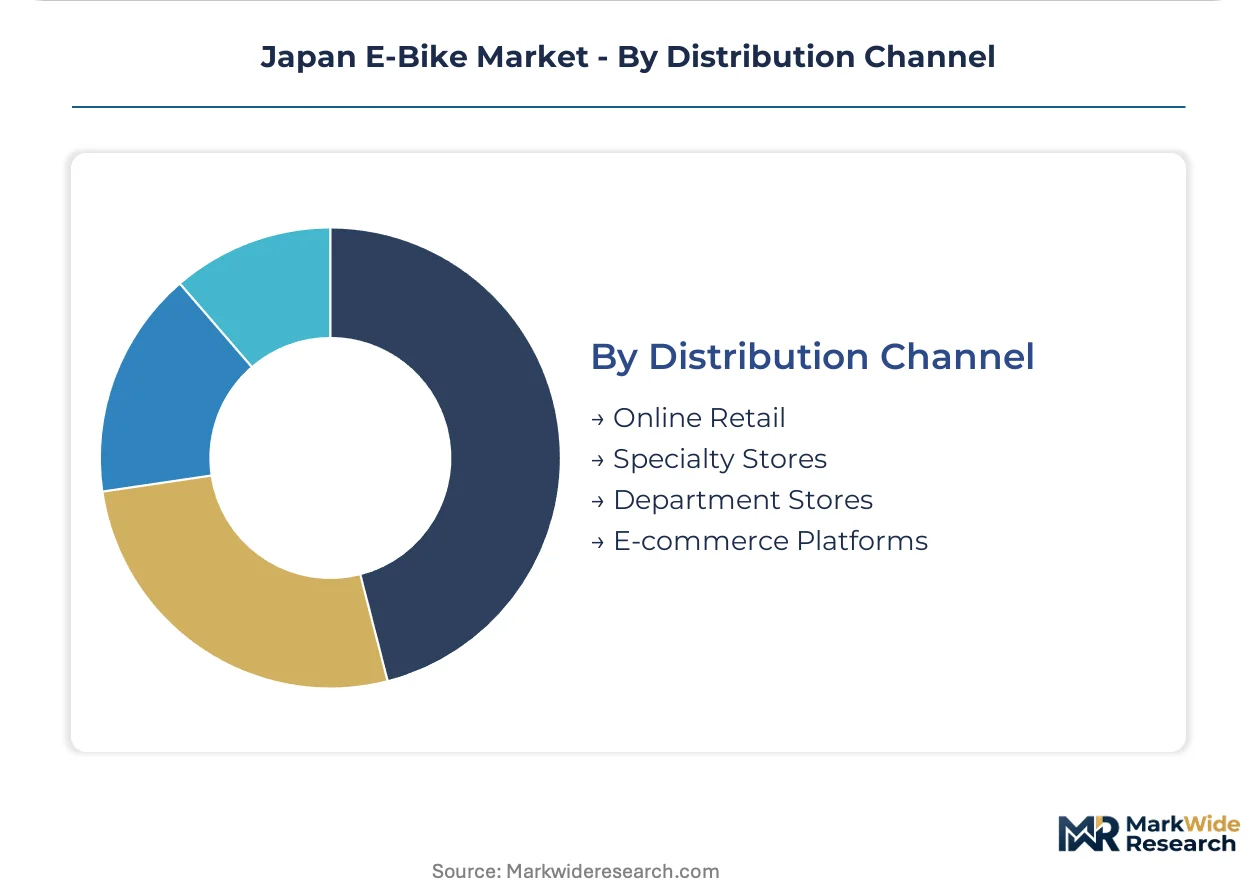
Distribution Channel:
Geography determines channel viability, with digital-native Greater Tokyo buyers bypassing traditional retail networks that still anchor rural prefecture sales.
- Specialty Stores:Neighborhood bicycle retailers in Tokyo's Setagaya and Minato wards provide test-ride infrastructure and after-sales battery health monitoring. Technician training gaps constrain expansion into Tohoku and Shikoku regions.
- Online Retail:Direct-to-consumer platforms capture digitally fluent commuters seeking manufacturer-managed remote diagnostics and subscription-based maintenance packages. Concentration in Greater Tokyo reflects urban digital adoption patterns.
- Department Stores:Isetan and Mitsukoshi flagship locations anchor premium segment visibility, showcasing Panasonic and Yamaha integrated drive systems to affluent suburban buyers.
- E-commerce Platforms:Rakuten and Amazon Japan marketplace listings aggregate price comparison traffic, compressing margins for standard commuter configurations through transparent specification benchmarking.
Specialty stores retain volume leadership; online retail holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese e-bike exports flow primarily toward Southeast Asian urban mobility markets, while domestic demand concentrates in metropolitan corridors where rail infrastructure enables intermodal commuting patterns.
Kanto/Tokyo
Rail-bike intermodal commuters and last-mile delivery fleets from Yamato Transport drive replacement cycles across Greater Tokyo's 23 wards. METI purchase subsidies compress payback periods for aging urban buyers over fifty-five. Setagaya and Minato wards anchor specialty retail density while Shinjuku Station corridors multiply folding e-bike utilization frequency.
Kansai/Osaka
Underdeveloped cycling infrastructure relative to Kanto creates whitespace for folding e-bike adoption among business commuters across the Osaka-Kyoto corridor. METI safety certification streamlines JIS compliance timelines for lithium-ion pack approvals. Osaka Station hub traffic and Umeda commercial density concentrate early adopter demand.
Chubu/Nagoya
Residual lead acid procurement persists among third-party fleet leasing operators facing upfront capital constraints. Central Japan's logistics operators maintain conservative battery chemistry preferences. Nagoya's automotive supplier ecosystem generates secondary demand from component manufacturer employees seeking plant-to-station connectivity.
Kyushu
Weekend recreational cyclists in rural prefectures prioritize range over portability for trail access across volcanic terrain. Limited METI subsidy penetration reflects lower rail-intermodal dependency. Fukuoka City represents the primary urban demand pocket where commercial delivery electrification trials expand.
Hokkaido
Extended-range battery configurations address sparse charging infrastructure across northern latitudes with severe winter performance requirements. Sapporo's compact urban core supports limited commuter adoption despite demographic aging. Agricultural cooperatives pilot cargo-capable e-bikes for short-haul produce transport bridging rural supply gaps.
Japan E-Bike Market Competitive Environment
Player mix skews toward diversified industrial conglomerates with captive bicycle divisions rather than pure-play specialists. Domestic manufacturing footprints dominate premium positioning while import-dependent assemblers compete on price elasticity. Two strategic archetypes prevail: integrated drive system developers and component standardization platforms. Capacity expansion into ruggedized commercial configurations and strategic partnerships for battery cell allocation represent dominant competitive moves.
Among Japan-based industrial groups, Panasonic, Yamaha Motor Co Ltd, and Bridgestone occupy positions reflecting distinct heritage advantages. Panasonic exemplifies the integrated system archetype through proprietary battery-drive integration. Yamaha Motor Co Ltd leverages motorcycle engineering lineage into pedal-assist architectures. Bridgestone represents rubber-to-road vertical heritage applied to urban mobility durability requirements. Shimano and Giant Manufacturing Co Ltd anchor component and scale archetypes respectively, with the former extending bicycle drivetrain dominance into electric-assist standards.
| Leading Market Players |
|---|
| Shimano |
| Giant Manufacturing Co Ltd |
| Yamaha Motor Co Ltd |
| Merida |
| Trek Bicycle |
| Panasonic |
| Shinsankai Co., Ltd. (ERWAY) |
| Rad Power Bikes |
| Bridgestone |
| Others |
Value Chain & Pricing Dynamics
Sixty-day battery pack lead times from GS Yuasa concentrate assembler negotiating power among a handful of domestic suppliers, compressing margin flexibility for import-dependent assemblers while METI subsidy timing dictates working capital cycles. This inventory-to-pricing coupling forces manufacturers to pre-position lithium-ion cells ahead of seasonal demand surges, amplifying balance sheet exposure to cell chemistry transitions.
Pricing Analysis
Lithium-ion generation pricing gaps separate current-density packs from residual lead acid configurations and emerging solid-state prototypes. Three-tier pricing structure across premium, standard, and economy levels reflects JIS certification tier and after-sales service bundling. Pricing pressure stems from METI subsidy unpredictability and e-commerce price transparency on Rakuten. Delivery services exhibit highest price sensitivity due to fleet-scale procurement, while department store channels sustain brand premiums.
Supply Chain Analysis
Japan and South Korea anchor lithium-ion cell production for domestic e-bike assembly, with China supplying magnet materials and Taiwan contributing motor controllers. Raw material dependencies center on lithium carbonate, rare earth magnets, and copper wiring. Single-source vulnerability concentrates in GS Yuasa cell allocation during demand surges. Distribution runs through specialty retailers in urban wards and direct-to-consumer platforms for rail-intermodal commuters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated logistics operators like Yamato Transport as fleet procurement volumes dwarf individual consumer purchases, fragmenting pricing leverage across asymmetric scale tiers.
For Market Incumbents: Shield premium positioning through captive battery-drive integration and JIS certification depth against price-aggressive import assemblers. Prioritize backward integration into cell chemistry R&D to reduce GS Yuasa allocation dependency. Defend channel control in Setagaya and Minato ward specialty networks where technician relationships anchor replacement battery attach rates. For New Entrants and Emerging Players: METI commercial fleet subsidy fast-track offers regulatory arbitrage against incumbent personal-mobility certification backlogs. Target Osaka-Kyoto corridor whitespace where rail-intermodal infrastructure remains underdeveloped. Pursue direct-to-consumer launch with manufacturer-managed remote diagnostics to bypass saturated Tokyo retail density. For Investors and Strategic Acquirers: Long-term, this sits as a demographic-utility play because aging urban commuters treat e-bikes as essential mobility infrastructure rather than discretionary recreation. Acquisition focus should center on component suppliers with JIS electrical bicycle system approval capabilities. Watch METI subsidy expansion to commercial fleets as volume inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| JIS Electrical Bicycle System Certification | Accelerates product launch timelines and unlocks METI subsidy eligibility for domestic assemblers. |
| High-Cycle Battery Architecture Development | Captures Yamato Transport fleet procurement specifications and stabilizes component volume commitments. |
| Rail-Intermodal Portability R&D | Addresses folding e-bike demand from Tokyo Station corridor commuters and reduces replacement intervals. |
| Direct-to-Consumer Platform Launch | Bypasses specialty retailer margin capture and enables subscription-based battery health monitoring services. |
| Osaka-Kyoto Corridor Distribution Expansion | Penetrates underdeveloped Kansai cycling infrastructure ahead of competitor retail saturation. |
Study Parameters
A standing panel of bicycle assemblers, METI policy officers, lithium-ion procurement managers, and rail-intermodal commuters provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from METI subsidy disbursement records, JIS standard revision documentation, and Rakuten marketplace transaction data. Bottom-up unit shipment estimates triangulated against top-down demographic mobility projections.
Consistency checks validated volume and value outputs against external benchmarks including vehicle registration databases and customs trade flows. Segmentation modeling incorporated product type, battery chemistry, end-user archetype, and distribution channel dimensions across the analysis window. CAGRs derived from age-cohort mobility transition rates and commercial fleet electrification trajectories, with METI policy scenario weighting applied.
Decision-makers should treat outputs as directional under sustained METI subsidy authorization and lithium-ion cost curve assumptions; material deviation in either would warrant model refresh. Recalibration cycles align with material shifts in subsidy eligibility criteria and battery chemistry commercialization timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Europe Hybrid Electric Vehicle Battery Market
Electric Vehicles
Global EV Relay Market
Electric Vehicles
Electric Vehicle Rental Market
Electric Vehicles
Hybrid Electric Vehicle Battery Market
Electric Vehicles
Electric Moped Market
Electric Vehicles
EV Lightweight Materials Market
Electric Vehicles
South America Electric Bus Battery Pack Market
Electric Vehicles
China NEV Taxi Market
Electric Vehicles
Battery Electric Vehicle (BEV) Market
Electric Vehicles
Automotive Battery Pack Pressure Equalization Membrane Market
Electric Vehicles
Train Battery Market
Electric Vehicles
Global Electric Vehicle (EV) Management Solution Market
Electric Vehicles
Electric Vehicle Operations Management Solutions Market
Electric Vehicles
Electric Vehicle Testing, Inspection, and Certification Market
Electric Vehicles
Bus Pantograph Charger Market
Electric Vehicles
Electric Sports Utility Vehicle (E-SUV) Market