
 One Wheel Electric Scooter Market | 2026-2036
One Wheel Electric Scooter Market Size, Share, and Industry Trends Forecast 2026-2036
One Wheel Electric Scooter Market Intelligence
Aftermarket service revenue is narrowing as manufacturers build direct-to-consumer repair networks. Future Motion Inc. leverages proprietary firmware ecosystems to lock in recurring maintenance spend. Dongguan Begode Intelligent Technology Co. Ltd. anchors production scale in Guangdong province, controlling component costs through captive supply of motor assemblies. King Song Intell Co. Ltd. differentiates via modular battery architectures that simplify field replacement.
A one wheel electric scooter is a single-wheeled, self-balancing personal electric vehicle powered by a brushless hub motor and gyroscopic stabilization sensors, typically achieving speeds of 20-50 km/h with lithium-ion battery packs ranging from 500Wh to 3,000Wh. The device serves last-mile transportation and recreational mobility where compact footprint outweighs multi-passenger capacity. Commuter-class product types now carry the widest margin pools as urban professionals prioritize reliability over extreme performance. Smart connectivity technology is displacing basic Bluetooth pairing with integrated telematics that enable fleet management for delivery services. Off-road variants remain enthusiast-niche, with high-performance segments constrained by thermal management costs.
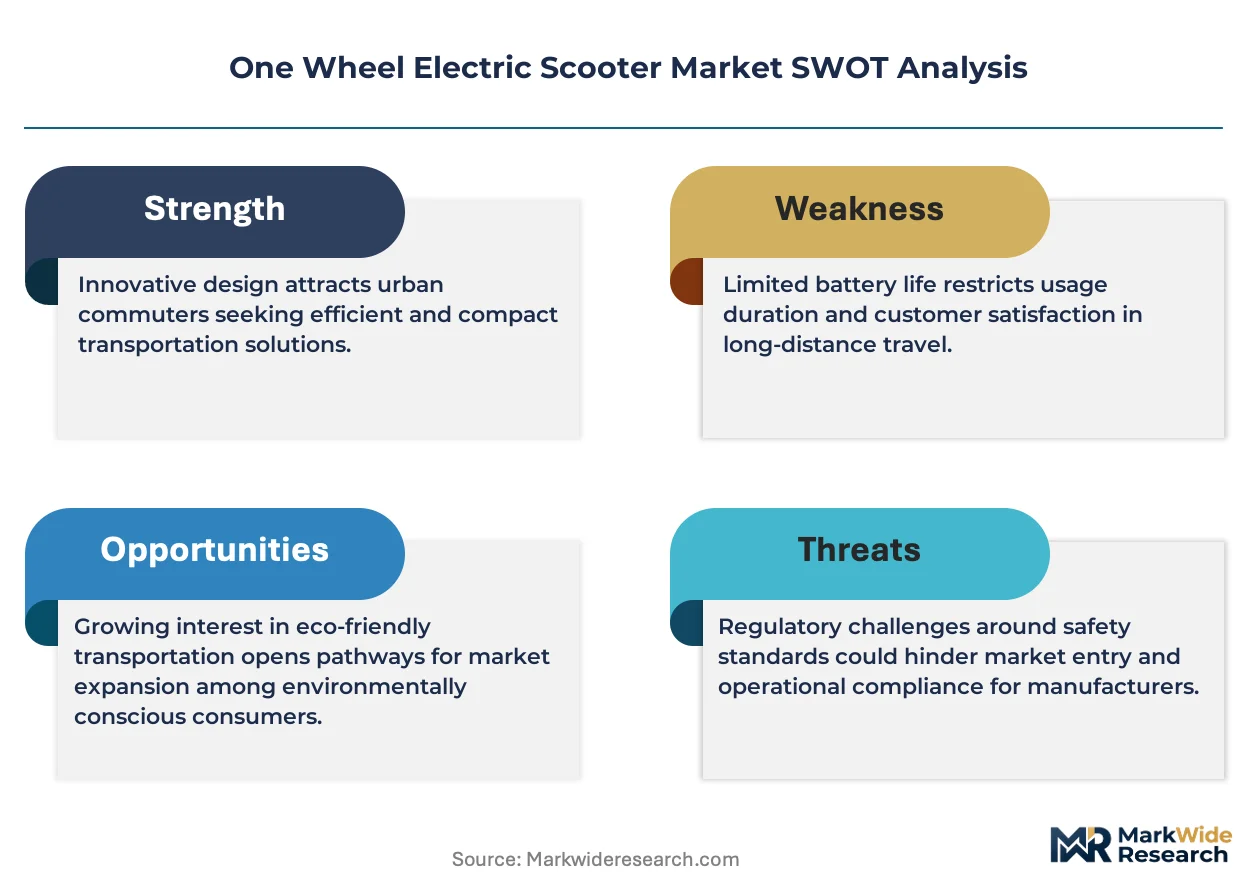
Underwriters Laboratories standards and the EU Machinery Directive shape product safety requirements, while the US Consumer Product Safety Commission monitors incident reporting for defect investigations. China's compulsory certification system filters low-quality entrants, tightening market access for unbranded imports. Stakeholders must monitor evolving municipal ordinances that classify these devices alongside bicycles or motorized vehicles, as this designation determines sidewalk access, helmet mandates, and insurance liabilities.
Market Dynamics
Urban micromobility infrastructure expansion is compressing last-mile transit times and elevating single-wheeled electric vehicles from enthusiast novelty to professional commuter tool, fundamentally restructuring demand composition toward reliability-focused product tiers.
Growth Catalysts
- EU Machinery Directive harmonization:Unified safety certification across member states accelerates cross-border retail distribution and reduces manufacturer compliance duplication costs.
- Lithium-ion energy density improvements:Higher-capacity cell chemistries extend single-charge range thresholds, eliminating range anxiety for 15-20 kilometer daily commuter circuits.
- German municipal ordinance liberalization:Berlin and Munich reclassification of personal electric vehicles alongside bicycles unlocks sidewalk access and reduces insurance liability burdens for riders.
Market Restraints
- Guangdong motor assembly concentration:Captive supply chains cluster 60-70% of brushless hub motor production in China's Pearl River Delta, exposing procurement to regional logistics disruptions.
- Thermal management cost floor:High-performance off-road variants face hard margin constraints from liquid cooling system requirements and heat dissipation materials.
- US Consumer Product Safety Commission defect investigation protocols:Incident reporting mandates trigger inventory holds and firmware revision cycles that compress working capital efficiency.
Strategic Opportunities
- India BIS certification pathway:Bureau of Indian Standards personal electric vehicle framework creates first-mover positioning in a 1.4 billion population market with nascent micromobility infrastructure.
- Integrated telematics-fleet management convergence:Smart connectivity platforms enable delivery service subscription models, shifting revenue from hardware sales to recurring software fees.
- Modular battery field-replacement architectures:Swappable cell designs reduce service downtime and open aftermarket revenue streams independent of manufacturer repair networks.
Industry Challenges
- Gyroscopic stabilization firmware talent scarcity:Control algorithm engineering expertise concentrates among semiconductor and drone industry incumbents, inflating compensation premiums for qualified hires.
- Underwriters Laboratories 2272 certification timeline:Electrical systems safety validation requires 8-14 month testing cycles, delaying product launches behind competitor announcements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | One Wheel Electric Scooter Market |
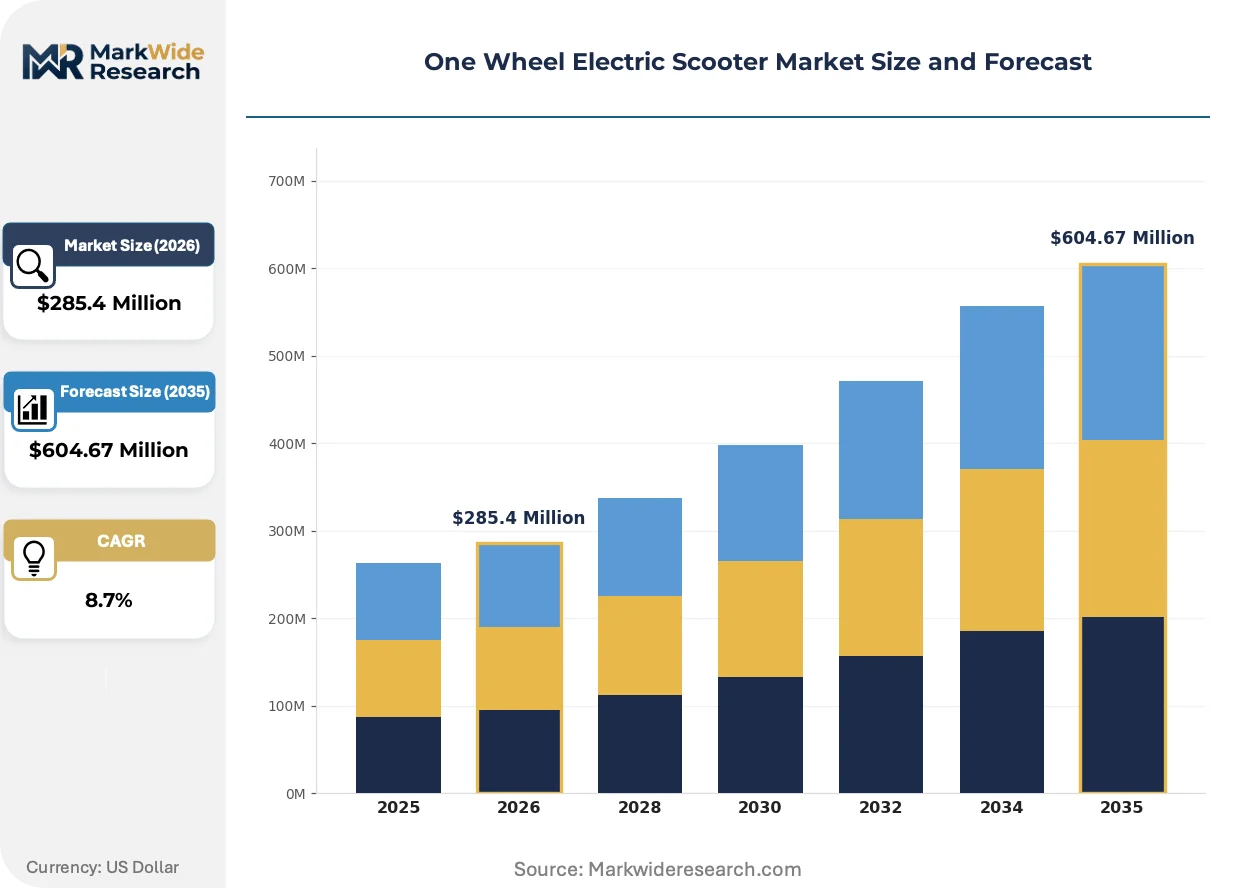
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $604.67 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Balancing, Off-Road, Commuter, High-Performance Application: Personal Use, Urban Commuting, Recreational, Delivery Services End User: Students, Professionals, Tourists, Enthusiasts Technology: Smart Connectivity, Battery Management, Regenerative Braking, GPS Integration |
| Companies Covered | Future Motion Inc., Inmotion Technologies Co., Ltd., Dongguan Begode Intelligent Technology Co. Ltd., King Song Intell Co. Ltd., Ninebot Limited, Airwheel Holding Limited, Swagtron, IPS Electric Unicycle, SuperRide, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
One Wheel Electric Scooter Market Strategic Shifts & Innovations
Smart connectivity systems are displacing basic Bluetooth pairing with integrated telematics platforms that enable real-time diagnostics, geofencing, and fleet management capabilities for commercial operators.
Solid-state battery prototyping is digitizing energy management architectures by replacing liquid electrolyte cells with ceramic conductive materials. Tier-one suppliers in Japan and South Korea are piloting these systems for premium commuter segments. This transition is digitizing battery state-of-health monitoring through embedded sensor arrays that transmit degradation data to manufacturer cloud platforms.
China's compulsory certification system is tightening market access filters for unbranded personal electric vehicle imports. The SAMR enforcement protocol now requires third-party testing at designated laboratories before marketplace listing approval. Low-quality entrants face 6-12 month exclusion periods, concentrating shelf presence among established firmware ecosystem holders.
Delivery service procurement is compressing hardware replacement cycles from 36 months to 18-24 months as commercial operators prioritize uptime guarantees over capital depreciation schedules. Fleet managers in the United States and Germany now specify modular component architectures in vendor selection criteria. This pattern is most visible in last-mile logistics verticals where vehicle downtime directly correlates with per-delivery cost erosion.
One Wheel Electric Scooter Market Segmentation
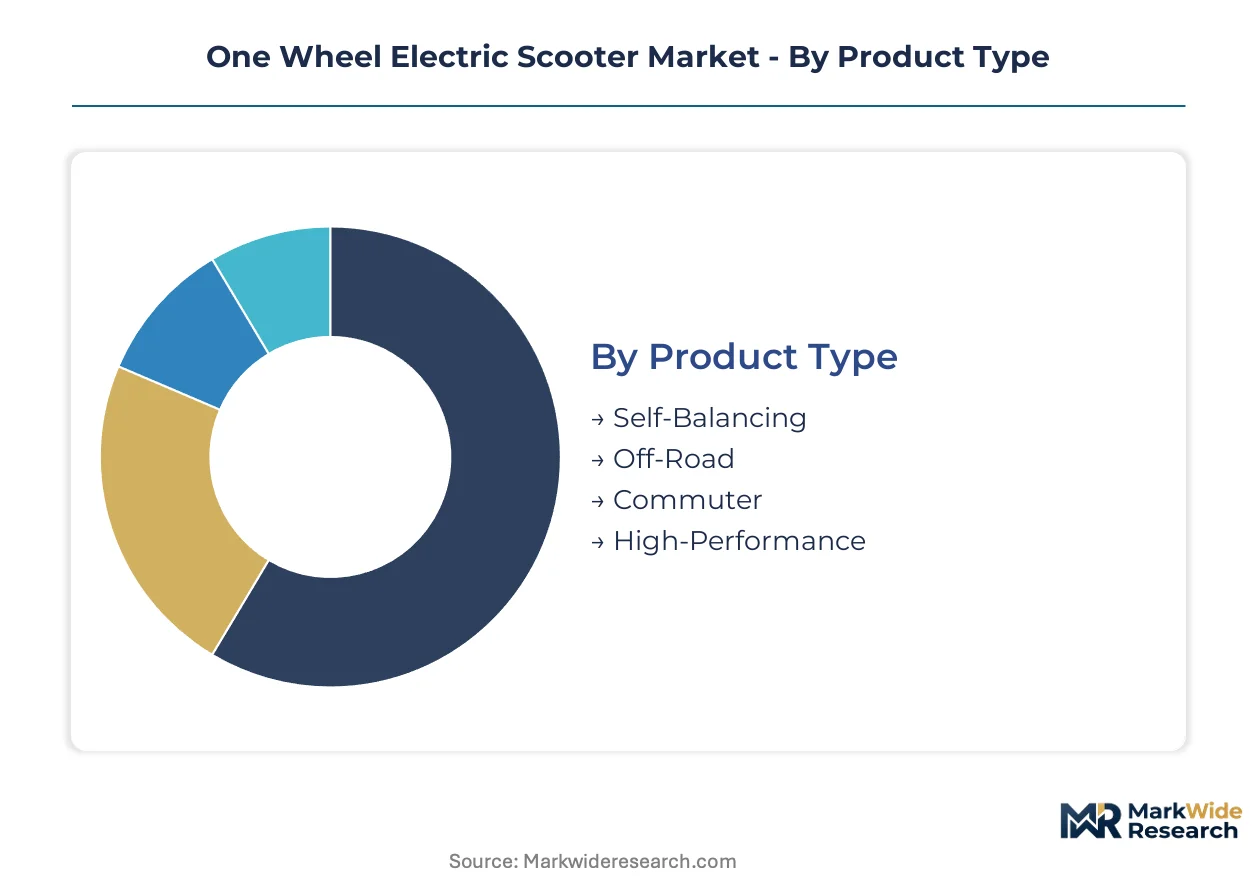
One wheel electric scooter segmentation reveals divergent margin profiles across use cases. Product architecture choices separate enthusiast hardware from fleet-grade reliability systems. Technology integration intensity varies sharply between personal ownership and commercial deployment models.
Product Type:
Cost tier differentiation separates entry-level commuter hardware from premium performance engineering.
- Self-Balancing:Entry-level segment employing single-axis gyroscopic stabilization with 500-800Wh battery packs. Demand concentrates among students in German university cities where sidewalk access permissions reduce licensing friction. Price sensitivity limits firmware update frequency and connected feature depth.
- Commuter:Mid-tier products optimized for 15-25 kilometer daily circuits with IP54 weather sealing and 1,000-1,500Wh cell configurations. Urban professionals in United States metropolitan areas prioritize UL 2272 certification and manufacturer repair network density over top speed specifications.
- Off-Road:Knobby-tire variants with reinforced chassis and suspension travel for unpaved terrain. Enthusiast buyers in China's Sichuan and Yunnan provinces drive volume despite thermal management cost premiums.
- High-Performance:Racing-grade hardware achieving 50+ km/h with liquid-cooled hub motors and 2,500-3,000Wh battery architectures. Niche segment constrained by insurance liability frameworks in most jurisdictions.
Commuter-class hardware commands the established base. The steepest expansion runs through delivery-optimized self-balancing variants.
Application:
Customer workflow integration determines device specification priorities and replacement cycle timing.
- Personal Use:Weekend recreational riding and occasional errand transport. Battery longevity concerns dominate purchase criteria over raw performance metrics.
- Urban Commuting:Daily multimodal transit integration with public transportation hubs. Riders in Berlin, Munich, and New York City demand rapid-fold mechanisms and transit-friendly weight classes under 15 kilograms.
- Recreational:Park and trail riding without destination utility. Tourism operators in Barcelona and Miami deploy rental fleets with geofenced operational zones.
- Delivery Services:Last-mile logistics procurement with 12-16 hour daily utilization targets. Fleet managers specify modular battery architectures and telematics integration for route optimization.
Urban commuting anchors current installed base. Delivery services are climbing the fastest as logistics operators compress hardware replacement cycles.
End User:
Volume concentration and margin capture diverge across demographic cohorts with distinct risk tolerances.
- Students:Price-elastic demand segment prioritizing campus mobility and minimal regulatory compliance. Purchase decisions hinge on peer recommendation and secondary market availability.
- Professionals:Reliability-focused buyers accepting 40-60% price premiums for manufacturer warranty terms and direct service channel access. Concentrated in United States and German metropolitan employment centers.
- Tourists:Rental-dependent segment with zero ownership intent. Demand flows through hospitality partnerships and airport concession operators.
- Enthusiasts:Performance-maximizing early adopters driving firmware ecosystem loyalty and aftermarket modification spending. Community influence shapes brand perception beyond formal marketing.
Professionals generate the highest per-unit margins. Students represent the volume foundation with steepest adoption trajectory.
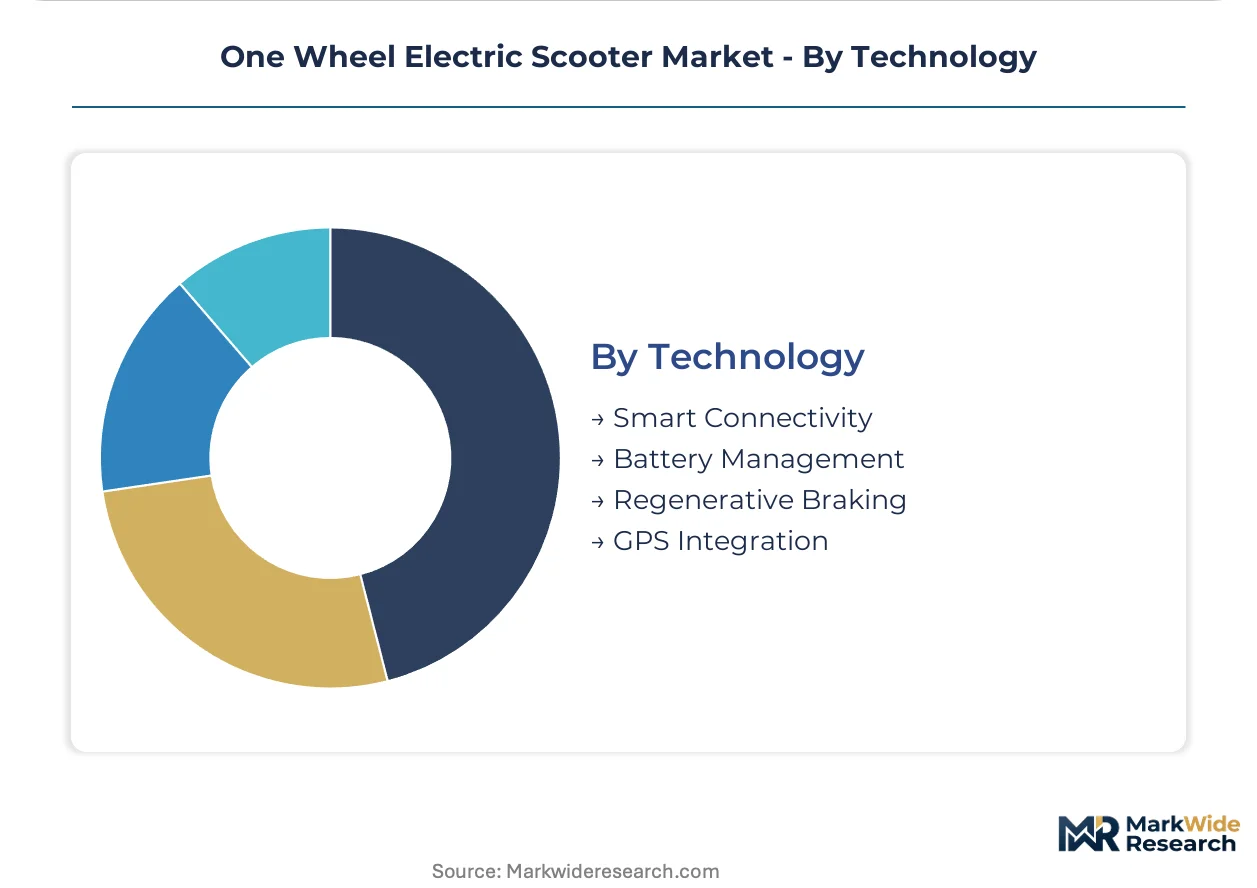
Technology:
Integration depth separates basic personal mobility from connected fleet infrastructure.
- Smart Connectivity:Bluetooth and cellular-enabled telematics platforms enabling real-time diagnostics and remote lock functionality. Delivery fleet procurement specifications now mandate API access for dispatch system integration.
- Battery Management:Cell-level monitoring systems with temperature balancing and charge rate optimization. Solid-state prototyping in Japan and South Korea targets premium commuter segments with ceramic electrolyte architectures.
- Regenerative Braking:Kinetic energy recovery systems extending effective range 8-12% in stop-start urban environments. Firmware calibration distinguishes commuter-tuned profiles from aggressive regen settings preferred by enthusiasts.
- GPS Integration:Location tracking with geofencing and theft recovery capabilities. Rental fleet operators in Barcelona and Miami require this layer for asset protection and usage-based billing.
Battery management systems anchor technical differentiation. Smart connectivity platforms are gaining share fastest as fleet procurement expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. Students in German university towns accept price premiums for sidewalk access permissions. Professionals in United States coastal metros prioritize manufacturer warranty density over acquisition cost.
United States
Urban professionals in New York and San Francisco drive commuter-class procurement. The US Consumer Product Safety Commission monitors incident reporting for defect investigations, triggering inventory holds that compress working capital. Los Angeles anchors West Coast fleet trials for delivery service operators.
Germany
Berlin and Munich reclassified personal electric vehicles alongside bicycles, unlocking sidewalk access and reducing insurance liability burdens. The KBA framework harmonizes type approval with EU Machinery Directive safety requirements. Baden-Württemberg hosts Stuttgart-area micromobility infrastructure pilots.
China
Guangdong province concentrates brushless hub motor production in the Pearl River Delta, exposing procurement to regional logistics disruptions. SAMR enforcement protocols now require third-party testing at designated laboratories before marketplace listing approval. Sichuan and Yunnan provinces sustain off-road enthusiast demand despite thermal management cost premiums.
India
Bureau of Indian Standards personal electric vehicle framework creates first-mover positioning in a population-dense market with nascent micromobility infrastructure. BIS certification pathways filter low-quality entrants through mandatory safety validation. Maharashtra and Karnataka states concentrate urban professional demand in Mumbai and Bangalore employment centers.
Japan
Premium commuter segments pilot solid-state battery prototyping with ceramic electrolyte architectures. METI standards guide energy density improvements and electrical systems safety. Kanto region around Tokyo anchors smart connectivity platform development for integrated telematics.
One Wheel Electric Scooter Market Key Industry Players
Capability concentration sits with firmware ecosystem holders; scale advantage sits with Guangdong-based production aggregators. The vendor base separates into three tiers: premium-tier specialists with proprietary stabilization algorithms, mid-tier assemblers leveraging captive motor supply, and entry-level importers facing SAMR exclusion periods. Strategic moves cluster around direct-to-consumer repair network buildout and modular battery architecture licensing.
Within the firmware-locked tier, Future Motion Inc. exemplifies ecosystem control through proprietary maintenance spend capture. Dongguan Begode Intelligent Technology Co. Ltd. and King Song Intell Co. Ltd. anchor the production-scale segment, with the former representing Guangdong supply chain integration and the latter occupying modular field-replacement positioning. Inmotion Technologies Co., Ltd. sits among the smart connectivity specialists.
| Leading Market Players |
|---|
| Future Motion Inc. |
| Inmotion Technologies Co., Ltd. |
| Dongguan Begode Intelligent Technology Co. Ltd. |
| King Song Intell Co. Ltd. |
| Ninebot Limited |
| Airwheel Holding Limited |
| Swagtron |
| IPS Electric Unicycle |
| SuperRide |
| Others |
Cost & Logistics Intelligence
Guangdong province's captive supply of brushless hub motor assemblies anchors production economics for mid-tier manufacturers, concentrating margin capture with firmware-locked incumbents who bundle proprietary maintenance contracts. This upstream concentration funnels pricing power toward direct-to-consumer repair network operators, compressing aftermarket service revenue for independent distributors.
Pricing Analysis
After-sales service contracts and firmware-locked maintenance subscriptions drive lifetime value capture for established ecosystem holders. Three-tier pricing structure across premium, standard, and economy levels separates UL 2272-certified commuter hardware from entry-level self-balancing units and thermal-management-heavy off-road variants. Pricing pressure stems from delivery service fleet procurement compressing hardware replacement cycles toward 18-24 month intervals. Students in German university towns exhibit highest price sensitivity, while professionals in United States coastal metros accept substantial premiums for manufacturer warranty density.
Supply Chain Analysis
Export control frameworks on advanced gyroscopic stabilization semiconductors constrain firmware algorithm sourcing from drone industry incumbents, inflating compensation premiums for qualified control engineering talent. Component manufacturing concentrates in China, South Korea, and Japan, with lithium-ion cell production and brushless motor assemblies drawing from regional specialist clusters. Critical dependencies span high-density battery cells, gyroscopic sensors, and thermal management materials. Single-source vulnerability runs through Guangdong motor assembly concentration exposed to regional logistics disruptions. Distribution runs through direct-to-consumer channels and fleet procurement contracts, bypassing traditional retail intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as delivery service demand splits procurement specifications between modular battery architectures and integrated telematics platforms. This demand-side divergence rewards specialists over generalists.
For Market Incumbents: Build firmware ecosystem moats through proprietary maintenance spend capture and direct-to-consumer repair network density. Incumbents should deepen backward integration into battery management system design to defend against modular field-replacement challengers. Certification investment in UL 2272 and EU Machinery Directive harmonization creates regulatory barriers for low-quality entrants facing SAMR exclusion periods. For New Entrants and Emerging Players: India's BIS certification pathway for personal electric vehicles represents the most penetrable entry point among population-dense markets with nascent micromobility infrastructure. Delivery-optimized self-balancing variants with API-accessible telematics platforms offer white-space positioning against enthusiast-focused incumbents. Go-to-market execution should prioritize fleet manager relationships over consumer retail channels. For Investors and Strategic Acquirers: Capital is best deployed toward smart connectivity specialists with integrated telematics platforms and modular battery architecture licensors. Long-term viability favors vendors positioned for subscription revenue models shifting hardware economics toward recurring software fees. Watch for municipal ordinance reclassifications that unlock sidewalk access as inflection indicators for commuter-class demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Repair Network Buildout | Future Motion Inc.'s proprietary firmware ecosystems capture recurring maintenance spend independent of distributor channels. |
| Modular Battery Architecture Licensing | King Song Intell Co. Ltd.'s field-replacement designs reduce service downtime and open aftermarket revenue streams. |
| Smart Connectivity Platform Integration | Inmotion Technologies Co., Ltd.'s API-accessible telematics enables delivery fleet dispatch system convergence. |
| Guangdong Production Scale Expansion | Dongguan Begode Intelligent Technology Co. Ltd.'s captive motor supply controls component costs through upstream manufacturing concentration. |
| India BIS Certification First-Mover Positioning | Early entrants in Maharashtra and Karnataka states capture urban professional demand ahead of infrastructure maturation. |
Research Approach
Desk research of customs trade data, SEC filings from micromobility-adjacent technology firms, and SAMR certification registries preceded structured interviews with fleet procurement managers at last-mile logistics operators, firmware engineering leads at stabilization algorithm developers, and aftermarket service heads at direct-to-consumer repair networks. Primary fieldwork with battery management system designers and gyroscopic sensor procurement specialists combined with secondary validation against UL certification databases and EU Machinery Directive harmonization protocols. Bottom-up unit economics modeling triangulated against top-down market sizing from regional vehicle registration patterns.
Assumption sets held battery energy density improvement trajectories and municipal ordinance liberalization timelines as fixed parameters while varying delivery service fleet penetration rates and commercial utilization intensity across the analysis window. Segmentation dimensions modeled include product type tier, application workflow integration, end-user demographic cohort, and technology integration depth. CAGRs derived from logistic curve fitting to adoption phase transitions, with industry-specific inputs spanning thermal management cost curves and firmware update frequency benchmarks.
Macroeconomic conditions sit as an overlay; deviation in lithium commodity pricing, semiconductor availability, or urban commercial real estate density would shift the trajectory. Forecasts reflect documented assumptions on regulatory harmonization pace and fleet procurement cycle compression. Material shifts in gyroscopic stabilization firmware talent scarcity or SAMR enforcement stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Global Automotive High-Performance Electric Vehicles Market
Electric Vehicles
China Electric Car Market
Electric Vehicles
Electric Scooters and Mopeds Market
Electric Vehicles
Africa Electric Scooter Market
Electric Vehicles
Belgium E-Bike Market
Electric Vehicles
Electric Bike Kit Market
Electric Vehicles
Folding E-Scooter Market
Electric Vehicles
Electric Shuttle Market
Electric Vehicles
Used EV Market
Electric Vehicles
Asia Pacific Electric Scooter Market
Electric Vehicles
Electric Vehicle Communication Controller Market
Electric Vehicles
Commercial Vehicle Electric Propulsion System Market
Electric Vehicles
Electric Passenger Cars Market
Electric Vehicles
United Kingdom Hybrid Electric Vehicle Battery Market
Electric Vehicles
Middle East and Africa Electric Vehicle Thermal Management System Market
Electric Vehicles
Electric All-Terrain Vehicle (ATV) Market