
 Vehicle Battery Market | 2026-2036
Vehicle Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle Battery Market Outlook
Direct OEM supply contracts is reconfiguring how vehicle battery makers secure volume commitments and margin stability. CATL leverages its integrated mining-to-cell operations to anchor cost positions in lithium iron phosphate production. LG Energy Solution competes through joint venture manufacturing in North America, while BYD sustains vertical control over both cell output and automotive demand through its captive EV platform.
A vehicle battery is an electrochemical storage device engineered to deliver sustained direct-current power for propulsion, lighting, and auxiliary systems, typically employing lithium-ion cells with nickel-cobalt-manganese or lithium iron phosphate cathodes arranged in modular packs with active thermal management. Its primary commercial purpose is to enable zero-emission or hybrid-electric drivetrains while meeting cycle-life thresholds exceeding one thousand full-depth discharges. Lithium-ion chemistry dominates installed capacity owing to its energy density advantage, though solid-state designs are attracting development capital for their projected safety and range improvements. Electric vehicle applications command the largest share of demand growth, while battery management systems technology concentrates margin pools through software-defined performance optimization and warranty risk reduction.
The US Inflation Reduction Act and the EU Battery Regulation are reshaping where cell and component production must locate to qualify for consumer subsidies and market access. China's MIIT sets domestic technical thresholds for energy density and recycling recovery rates that filter which producers achieve scale approval. Stakeholders must monitor how divergent carbon-accounting rules and local-content mandates fragment what had been a globally integrated supply base.
Market Dynamics
Direct OEM supply contracts are reconfiguring how vehicle battery makers secure volume commitments and margin stability, as CATL leverages integrated mining-to-cell operations to anchor cost positions in lithium iron phosphate production.
Growth Catalysts
- US Inflation Reduction Act:Local-content mandates for battery components redirect capital toward domestic cathode and cell manufacturing facilities to qualify consumer subsidies.
- Solid-state chemistry advances:Development capital flows into next-generation designs promising enhanced safety profiles and extended range capabilities for premium electric vehicle platforms.
- China's MIIT technical thresholds:Domestic energy density and recycling recovery standards filter producer approvals, concentrating scale among vertically integrated cell manufacturers.
Market Restraints
- Lithium carbonate price volatility:Raw material cost swings compress cell producer margins and destabilize long-term contract pricing mechanisms.
- Cathode precursor supply concentration:Processing capacity clusters in Southeast Asia, creating single-point vulnerability for nickel-cobalt-manganese supply chains.
- EU Battery Regulation carbon-accounting rules:Divergent lifecycle assessment methodologies fragment what had been globally integrated production networks.
Strategic Opportunities
- India's PLI scheme for advanced chemistry cells:Production-linked incentives attract greenfield manufacturing investments targeting two-wheeler and three-wheeler electrification.
- Battery management systems software:Performance optimization algorithms and predictive warranty analytics open recurring revenue streams beyond hardware sales.
- Second-life stationary storage applications:Retired electric vehicle packs find secondary deployment in grid stabilization and commercial backup power systems.
Industry Challenges
- Electrochemical engineering talent scarcity:Cell design and thermal management expertise concentrates among a limited pool of specialists with gigafactory-scale experience.
- Gigafactory capex intensity:Multi-billion dollar facility investments require decade-long offtake commitments before commissioning begins.
- UN 38.3 certification timelines:Lithium-ion transport safety testing creates bottlenecks for new cell form factors entering international logistics networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle Battery Market |
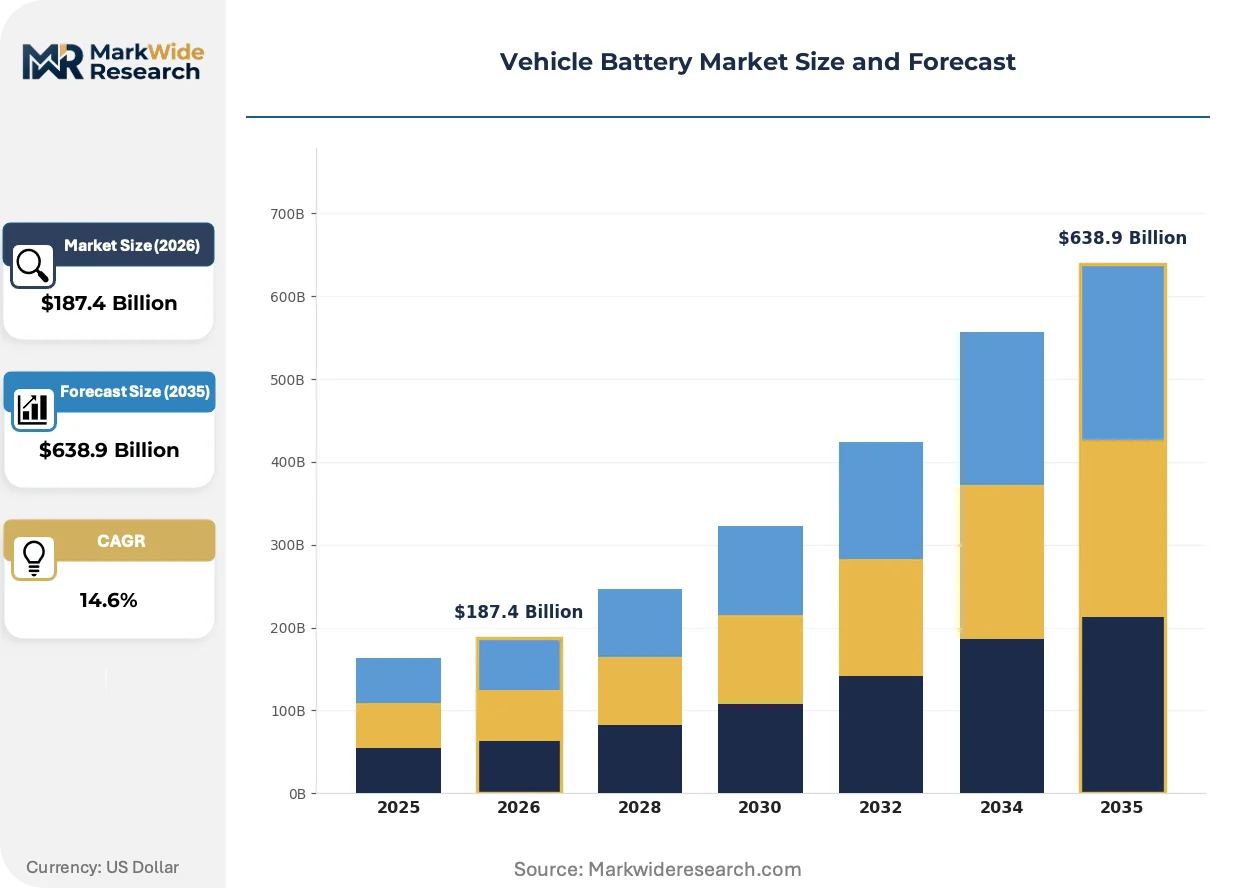
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $638.9 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Nickel-metal Hydride, Lead-acid, Solid-state Application: Hybrid Vehicles, Electric Vehicles, Start-stop Systems, Commercial Vehicles End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Fleet Operators Technology: Fast Charging, Wireless Charging, Battery Management Systems, Regenerative Braking |
| Companies Covered | CATL (Contemporary Amperex Technology Co. Limited), LG Energy Solution, BYD (Build Your Dreams), Panasonic Energy, Samsung SDI, SK Innovation, Northvolt, EVE Energy, CALB (China Aviation Lithium Battery), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle Battery Market Strategic Shifts
Silicon-anode formulations and dry electrode coating processes are compressing manufacturing energy intensity while extending energy density thresholds for next-generation cell architectures.
Dry electrode coating technology eliminates solvent-based slurry processing, reducing drying oven energy consumption by half. CATL and LG Energy Solution are retrofitting pilot lines to validate throughput at commercial scale. This process is digitizing quality control through in-line spectroscopic monitoring that replaces offline sampling protocols.
Europe's Battery Passport regulation mandates digital product passports tracking carbon footprint, material provenance, and recycling content across the value chain. Cell producers must deploy blockchain-anchored data infrastructure to comply with 2027 enforcement deadlines. Premium electric vehicle OEMs in Germany and Sweden are already requiring passport-ready cells for new platform launches.
Fleet operators and energy utilities are consolidating procurement through multi-year framework agreements that bundle cell supply with battery management systems and recycling services. Traditional spot-market purchasing for aftermarket replacement is contracting. This consolidation is most visible in California and Texas, where municipal transit electrification programs aggregate demand across hundreds of vehicles.
Vehicle Battery Market Segmentation
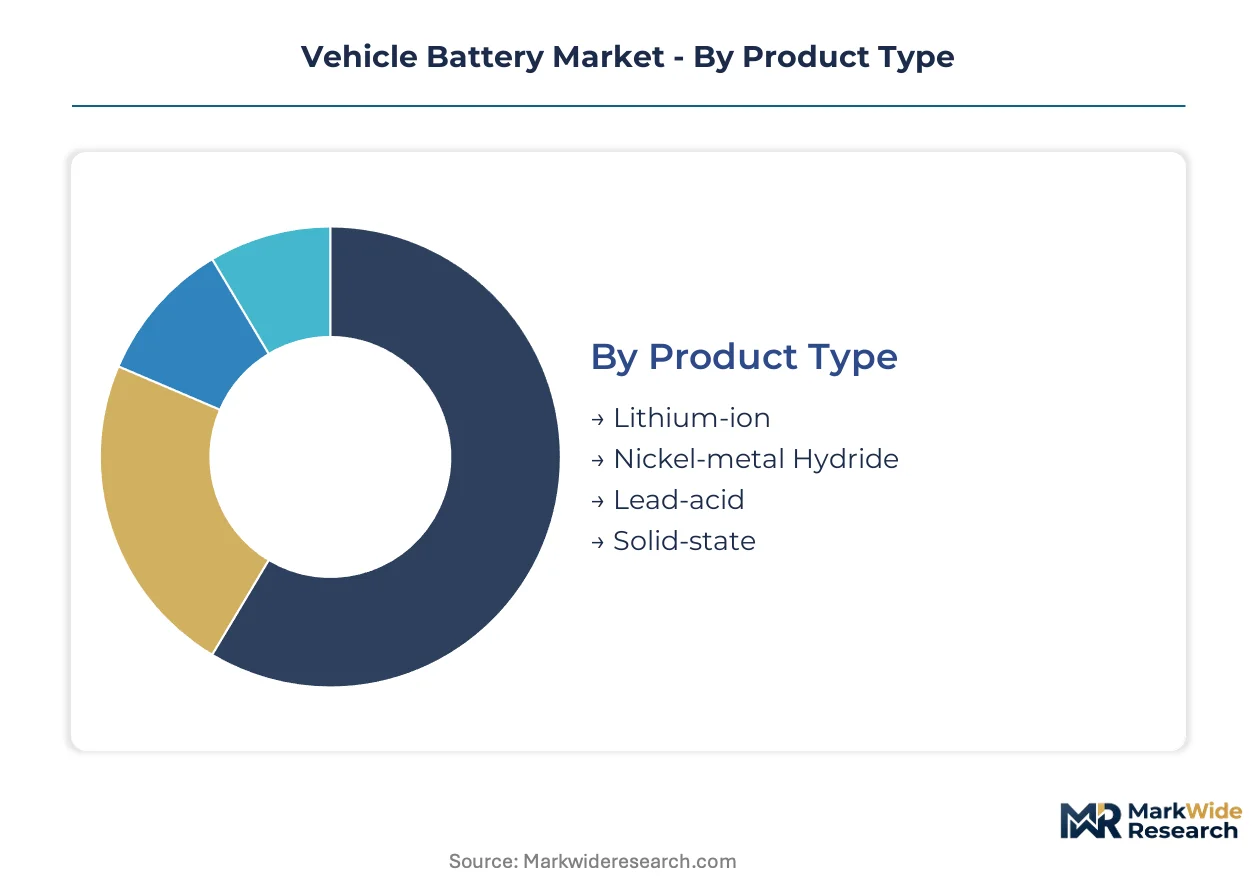
Segmentation in vehicle batteries reveals how chemistry choices, vehicle architectures, and procurement channels allocate margin pools differently. Each dimension exposes distinct competitive barriers and capital intensity profiles that determine which producers capture value.
Product Type:
Mature lithium-ion formats coexist with emerging solid-state architectures at opposite ends of the commercialization spectrum.
- Lithium-ion:Nickel-cobalt-manganese and lithium iron phosphate cathodes dominate current production, with energy densities reaching 300 Wh/kg in premium automotive configurations. Chinese cell producers anchor cost positions through integrated mining-to-cell operations serving domestic EV platforms.
- Solid-state:Sulfide and oxide electrolyte designs eliminate flammable liquid components while targeting 500 Wh/kg energy density thresholds. Japanese and Korean producers concentrate pilot manufacturing for luxury electric vehicle launches.
- Nickel-metal Hydride:Mature chemistry retains position in hybrid drivetrains where cost sensitivity and proven cycle life outweigh density requirements.
- Lead-acid:Conventional flooded and absorbed glass mat formats persist in internal combustion start-stop systems and auxiliary power roles.
Lithium-ion retains volume leadership; solid-state holds the steepest expansion curve.
Application:
Cost tier stratification separates mass-market electrification from premium performance platforms.
- Electric Vehicles:Battery electric platforms demand 60-100 kWh packs with 800V architectures enabling 350 kW fast charging. European and Chinese OEM procurement concentrates cell supply through decade-long offtake agreements.
- Commercial Vehicles:Heavy-duty trucking and bus applications require megawatt-hour scale packs with thermal management systems rated for continuous duty cycles. North American fleet electrification programs aggregate demand across municipal transit authorities.
- Hybrid Vehicles:Parallel and series hybrid architectures utilize smaller 1-2 kWh packs optimized for high-rate partial cycling.
- Start-stop Systems:Micro-hybrid applications employ ultracapacitor-battery combinations for engine restart events.
Electric vehicles command the dominant revenue share; commercial vehicles are climbing the fastest as freight electrification accelerates.
End User:
Customer type determines contract structure, with direct OEM relationships commanding priority capacity allocation.
- OEMs:Vehicle manufacturers negotiate exclusive supply agreements specifying cell form factor, thermal interface, and warranty terms. German and Swedish premium brands require battery passport compliance for platform launches.
- Fleet Operators:Municipal transit and logistics companies procure through multi-year framework agreements bundling cells, battery management systems, and recycling services. California and Texas electrification programs aggregate demand across hundreds of vehicles.
- Tier-1 Suppliers:System integrators source cells for pack assembly, adding thermal management and structural enclosures.
- Aftermarket Providers:Independent distributors serve replacement demand for legacy hybrid models and commercial vehicle refurbishment.
OEMs retain volume leadership; fleet operators hold the steepest expansion curve.
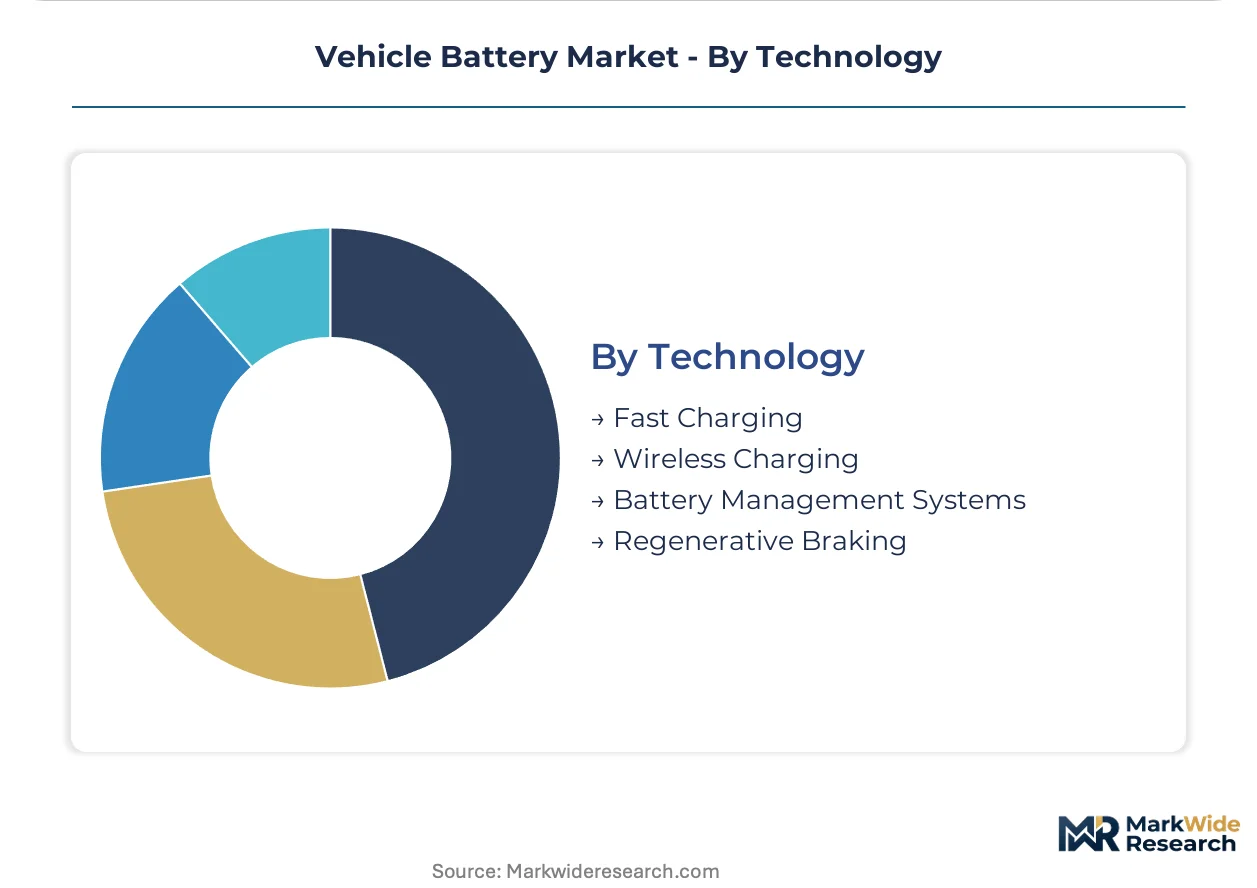
Technology:
Supply concentration in enabling technologies creates distinct margin architectures around software and power electronics.
- Battery Management Systems:State-of-charge algorithms and cell balancing electronics concentrate margin pools through predictive warranty analytics and over-the-air performance optimization. Korean and Japanese semiconductor houses dominate integrated circuit supply.
- Fast Charging:800V architectures and silicon carbide power electronics enable 10-80% charge events in under 20 minutes. European charging infrastructure deployment mandates accelerate adoption.
- Regenerative Braking:Kinetic recovery systems integrate power electronics with friction braking for energy recuperation.
- Wireless Charging:Inductive pad systems target fleet depot applications where automated connection eliminates operator handling.
Battery management systems retain volume leadership; fast charging holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands pricing leverage through integrated mining-to-cell operations while European producers absorb carbon-accounting compliance premiums. This asymmetry redirects capital toward jurisdictions with local-content subsidies.
China
Domestic EV platforms from BYD and Nio absorb 60% of global cell output. MIIT energy density thresholds filter producer approvals toward vertically integrated manufacturers. Ningde anchors cathode precursor capacity expansion serving both domestic OEMs and export markets.
United States
Ford and GM electrification programs aggregate demand exceeding 200 GWh annually. IRA local-content mandates redirect cathode investments toward domestic facilities in Kentucky and Tennessee. Michigan's gigafactory corridor concentrates joint-venture assembly operations.
Germany
Premium OEM procurement requires battery passport compliance for 2027 platform launches. ECHA carbon-accounting rules fragment legacy supply chains. Saxony-Anhalt hosts Northvolt's integrated cell and recycling complex.
South Korea
Hyundai-Kia and Samsung SDI coordinate 800V fast-charging architectures. METI-aligned technical standards accelerate solid-state pilot manufacturing. Gyeonggi Province concentrates cathode material R&D clusters.
India
Two-wheeler electrification drives 50 GWh demand projections by 2030. PLI scheme for advanced chemistry cells attracts greenfield investments from Korean and Chinese producers. Gujarat's Dholera special investment region hosts pilot gigafactory developments.
Vehicle Battery Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with narrower margin capture. The market structures around three tiers: mining-to-cell conglomerates, joint-venture assemblers, and pure-play technology licensors. Strategic moves concentrate on captive offtake agreements and backward integration into cathode precursors.
Within the integrated mining-to-cell tier, CATL and BYD exemplify cost-position dominance through captive lithium sourcing and in-house cathode production. LG Energy Solution occupies a joint-venture position anchoring North American capacity through domestic manufacturing partnerships. These three represent divergent archetypes: Chinese vertical integration, Korean alliance-based expansion, and platform-captive demand absorption.
| Leading Market Players |
|---|
| CATL (Contemporary Amperex Technology Co. Limited) |
| LG Energy Solution |
| BYD (Build Your Dreams) |
| Panasonic Energy |
| Samsung SDI |
| SK Innovation |
| Northvolt |
| EVE Energy |
| CALB (China Aviation Lithium Battery) |
| Others |
Value Chain & Pricing Dynamics
Gigafactory undercapacity in North America is tightening cell availability and emboldening suppliers to enforce indexed lithium contracts. This utilization squeeze rewards producers with captive cathode capacity while pressuring OEMs to accept longer offtake terms.
Pricing Analysis
Configured-to-order pricing for 800V packs commands 15-25% premiums over standard 400V configurations. Contract-based long-term offtake dominates, with pricing stratifying across premium, standard, and economy tiers based on energy density certification and volume scale. Cost compression in lithium iron phosphate cells is intensifying because Chinese integrated producers are expanding Ningde capacity. Fleet operators show highest price sensitivity, while German premium OEMs absorb passport-compliance premiums without volume pushback.
Supply Chain Analysis
CATL, LG Energy Solution, and Samsung SDI hold over 70% of contract manufacturing capacity for automotive-qualified cells. Supply concentrates in China, South Korea, and Japan, with cathode precursor processing anchored in Fujian and Gyeonggi. The chain draws from Chilean lithium, Indonesian nickel, and DRC cobalt, creating single-source vulnerability for Class 1 nickel sulfate. Distribution runs through direct OEM supply agreements rather than spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state chemistry maturation represents a high-growth disruption, with sulfide electrolyte pilots now validating 500 Wh/kg architectures for premium platforms.
For Market Incumbents: Pre-empt solid-state entrants by locking decade-long offtake with sulfide-electrolyte specialists. Anchor cost positions through backward integration into Indonesian nickel processing. Defend against Chinese LFP cost pressure by scaling 800V fast-charging differentiation.
For New Entrants and Emerging Players: Pursue India's two-wheeler electrification gap, where 50 GWh demand lacks qualified domestic suppliers. Target fleet operators in Texas and California with battery-management-systems-inclusive service bundles. Enter through second-life stationary storage partnerships with municipal utilities.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across dry-electrode coating equipment as solventless processes halve energy consumption. Five-to-ten-year viability favors producers with integrated mining-to-cell footprints. Watch cathode precursor margin capture as the inflection signal—processors with Indonesian nickel sulfate access will outearn cell assemblers.
| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture Manufacturing | Ford-SK Innovation partnerships in Kentucky satisfy IRA local-content mandates for consumer subsidies. |
| Backward Integration into Cathode | CATL's Fujian precursor plants lock in nickel sulfate supply ahead of Indonesian export restrictions. |
| Battery Passport Compliance | Northvolt's blockchain-anchored data infrastructure positions for ECHA carbon-accounting enforcement. |
| Dry Electrode Retrofit | LG Energy Solution pilot lines validate throughput gains that compress manufacturing energy intensity. |
| Second-Life Storage Partnerships | Retired Nissan Leaf packs in California utility programs open recurring revenue beyond automotive sales. |
Study Parameters
A spread of perspectives from OEM platform engineers, cathode R&D directors, fleet procurement managers, and IRA policy specialists converged on the working assumptions. Primary interviews with Tier 1 supplier executives and gigafactory operations heads combined with secondary validation against SEC filings, MIIT production license databases, and EU Battery Regulation draft impact assessments. Bottom-up cell production capacity tallies triangulated against top-down EV sales forecasts.
Demand-supply-balance modeling anchored projections across the analysis window, with vehicle class, propulsion architecture, and regional production cluster as core segmentation dimensions. CAGRs derived from installed capacity buildout schedules and OEM electrification program announcements. Forecast inputs incorporated lithium carbonate futures curves and IRA tax credit eligibility thresholds.
Sensitivities concentrate around MIIT energy density threshold revisions and ECHA carbon-accounting methodology changes. Forecasts reflect assumptions on solid-state commercialization timelines and Indonesian nickel export policy. Cross-checking against IEA Global EV Outlook capacity benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
United Kingdom Electric Vehicle (EV) Market
Electric Vehicles
Self Balancing Electric Scooter Market
Electric Vehicles
China NEV Taxi Market
Electric Vehicles
EV Thermal Management System Market
Electric Vehicles
High-Performance Electric Sports Cars Market
Electric Vehicles
North America E-Bike Market
Electric Vehicles
Global Industrial Electric Vehicle Market
Electric Vehicles
Preassembled Harness Modules for Skateboard EV Platforms Market
Electric Vehicles
Electric Vehicle Lithium-Ion Battery Market
Electric Vehicles
BEV On-Board Charger Market
Electric Vehicles
Premium Electric Motorcycle Market
Electric Vehicles
48V Mild Hybrid Electric Vehicle (MHEV) Market
Electric Vehicles
Electric Commercial Vehicle Market
Electric Vehicles
Special Purpose Electric Vehicle Market
Electric Vehicles
France Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
Electric Vehicle Skateboard Platform Market