
 E-Bike Battery Market | 2026-2036
E-Bike Battery Market Size, Share, and Industry Trends Forecast 2026-2036
E-Bike Battery Market Analysis
Chinese cylindrical cell producers is restructuring supply commitments across European e-bike OEMs as local content rules tighten. Panasonic Corporation leverages its Japanese manufacturing base to sustain premium positioning in high-voltage packs. Samsung SDI anchors its competitiveness through rigorous safety certification protocols. LG Energy Solution differentiates via nickel-cobalt-aluminum cathode formulations optimized for cycle longevity.
An e-bike battery is a rechargeable electrochemical energy storage system, typically lithium-ion based with nominal voltages of 36V or 48V and energy densities between 150-250 Wh/kg, engineered to deliver sustained discharge currents for pedal-assist and throttle-controlled electric bicycles. Lithium-ion chemistry dominates the battery type dimension due to superior energy density and declining cell costs, while nickel-cobalt variants retain niche positions where specific power output matters. The 600Wh and 800Wh capacity tiers are capturing disproportionate growth as range anxiety diminishes among delivery companies and tour operators operating extended routes.
The EU Battery Regulation, China's GB/T standards, and the US EPA energy efficiency guidelines collectively dictate cell chemistry disclosure, recyclability mandates, and safety testing protocols that determine market access across major consumption zones. Compliance with these frameworks now requires documented supply chain due diligence from raw material extraction through end-of-life collection. Stakeholders must monitor how solid-state prototyping timelines and sodium-ion alternatives reshape procurement strategies without assuming seamless technology transitions.
Market Dynamics
EU Battery Regulation carbon footprint thresholds are forcing cell chemistry roadmaps toward localized production and documented supply chain due diligence from extraction through end-of-life collection.
Growth Catalysts
- Last-mile delivery electrification:Urban logistics fleets in Germany and the Netherlands are scaling battery procurement as commercial operators replace combustion vans with cargo e-bikes for parcel distribution.
- REACH compliance infrastructure:Chemical disclosure mandates under Europe's REACH framework are creating competitive advantage for suppliers with pre-certified cell chemistries and documented material provenance.
- Solid-state prototyping pipelines:Advanced electrolyte research programs are compressing development timelines for next-generation cells with enhanced thermal stability and energy density targets.
Market Restraints
- Lithium carbonate volatility:Raw material input costs for cathode production fluctuate with South American brine extraction volumes and Chinese refining capacity constraints.
- Jiangsu-Zhejiang supply concentration:Over 60 percent of global cylindrical cell assembly capacity sits within a 300-kilometer corridor, creating single-point vulnerability for European OEMs.
- Recyclability mandate friction:EU Battery Regulation's end-of-life collection targets impose reverse logistics costs that smaller pack assemblers cannot absorb without scale.
Strategic Opportunities
- Polish and Hungarian manufacturing zones:Greenfield cell assembly investments near German OEM hubs qualify for EU Green Deal transition financing and reduce transport emissions for carbon footprint scoring.
- Tourism operator range tiers:Alpine bike tour companies in Switzerland and Austria are specifying 800Wh+ packs for multi-day routes, opening premium pricing segments beyond urban commuting.
- CE marking fast-track pathways:Pre-certified testing protocols under notified body agreements allow accelerated market entry for compliant pack designs.
Industry Challenges
- Battery management system firmware integration:Pack suppliers must harmonize proprietary BMS protocols with disparate e-bike motor controller architectures from Bosch, Shimano, and Brose.
- UN 38.3 certification timelines:Transport safety testing for lithium-ion cells creates 12-16 week delays that compress product launch windows and strain working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Bike Battery Market |
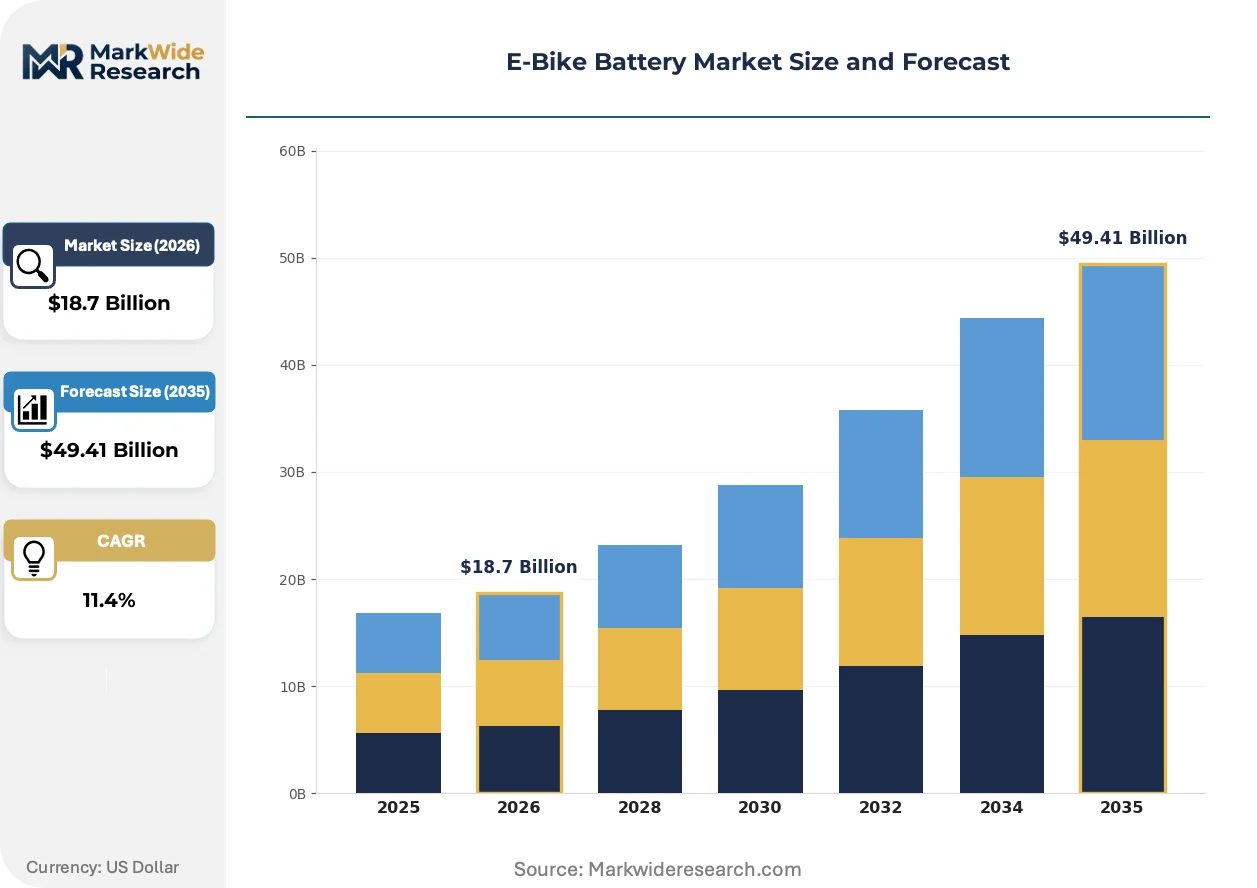
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-Ion, Nickel-Cobalt, Lead-Acid, Lithium Polymer Capacity: 200Wh, 400Wh, 600Wh, 800Wh Application: Urban Commuting, Delivery Services, Recreational Riding, Off-Roading End User: Individual Consumers, Delivery Companies, Rental Services, Tour Operators |
| Companies Covered | Panasonic Corporation, Samsung SDI, LG Energy Solution, CATL, BYD Company, BMZ Group, Bosch eBike Systems, Shimano Inc., Amperex Technology Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Bike Battery Market Emerging Trajectories
Cell chemistry standardization around nickel-manganese-cobalt formulations is compressing R&D fragmentation while regulatory pressure on carbon accounting accelerates supply chain transparency investments.
Lithium iron phosphate cathode formulations are consolidating in the commercial fleet segment due to superior cycle life and thermal stability. Delivery operators in Rotterdam and Copenhagen are specifying LFP packs for 2,000+ cycle durability. This chemistry is consolidating procurement volumes away from energy-dense NMC alternatives for high-utilization applications.
The EU Battery Regulation's carbon footprint declaration requirements are reshaping supplier qualification processes. Cell producers must document kg CO2 equivalent per kWh across mining, refining, and assembly stages. German OEMs are rejecting Chinese suppliers unable to provide granular scope 3 emissions data.
Fleet operators are unbundling battery ownership from vehicle acquisition through lease-to-own structures. Last-mile logistics providers in Barcelona and Milan prefer operational expenditure models that transfer degradation risk to financiers. This shift concentrates procurement decision-making among specialized mobility asset lessors rather than fragmented retail channels.
E-Bike Battery Market Segmentation
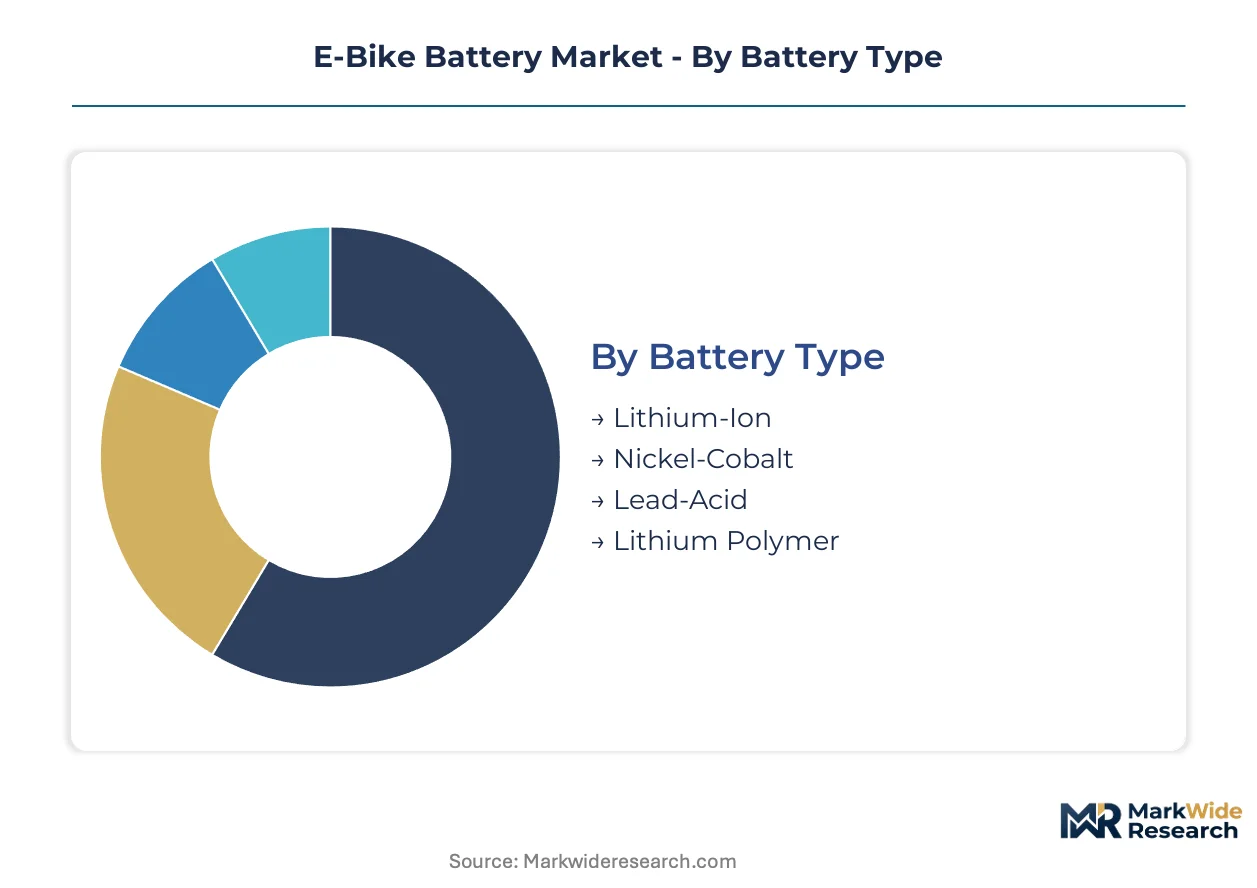
E-bike battery procurement decisions fragment across chemistry preferences, range requirements, and duty-cycle intensity. Fleet operators prioritize cycle longevity and total cost of ownership, while individual buyers balance upfront expenditure against replacement timelines.
Battery Type:
The customization-vs-standardization spectrum spans proprietary cell formulations against commoditized pack architectures.
- Lithium-Ion:Nickel-manganese-cobalt cathode formulations deliver 150-250 Wh/kg energy density with established recycling pathways. German OEMs specify NMC variants for premium commuter lines where range and weight reduction command price premiums.
- Nickel-Cobalt:Higher specific power output suits throttle-assist cargo applications requiring sustained discharge currents. Rotterdam delivery fleets specify these cells for hill-climb performance in loaded configurations.
- Lead-Acid:Lowest unit cost retains niche presence in price-sensitive Southeast Asian markets with limited charging infrastructure penetration.
- Lithium Polymer:Flexible form factors enable frame-integrated pack designs for step-through urban models popular in Dutch and Danish markets.
Leading the category by volume: Lithium-Ion. Growing fastest: Lithium Polymer.
Capacity:
Cost tier stratification separates entry-level urban mobility from premium long-distance applications.
- 600Wh:Balanced energy reserve eliminates range anxiety for daily commuters with occasional weekend touring. Swiss rental operators specify this tier for multi-day alpine route packages.
- 800Wh:Maximum range extension supports commercial delivery routes exceeding 80 kilometers per shift. Austrian tour operators demand these packs for unsupported multi-day itineraries.
- 200Wh:Ultra-lightweight configurations suit folding e-bikes for multimodal transit integration in dense Japanese and Korean urban cores.
- 400Wh:Mid-range specification dominates OEM bundled offerings where upgrade pricing captures margin expansion.
Dominant by installed base: 400Wh. Climbing the fastest: 800Wh.
Application:
Volume concentration tracks urban logistics electrification against leisure market seasonality.
- Delivery Services:High-utilization duty cycles demand thermal management and rapid-charge compatibility. Barcelona last-mile operators specify packs with 4C charge rates for overnight fleet turnaround.
- Urban Commuting:Moderate daily distances prioritize weight reduction and frame integration aesthetics. Copenhagen infrastructure investment sustains replacement demand across this segment.
- Recreational Riding:Weekend usage patterns tolerate lower cycle-life specifications in exchange for purchase price reduction.
- Off-Roading:Vibration resistance and IP67 ingress protection command engineering premiums for mountain bike applications.
Highest shipment volume: Urban Commuting. Steepest expansion trajectory: Delivery Services.
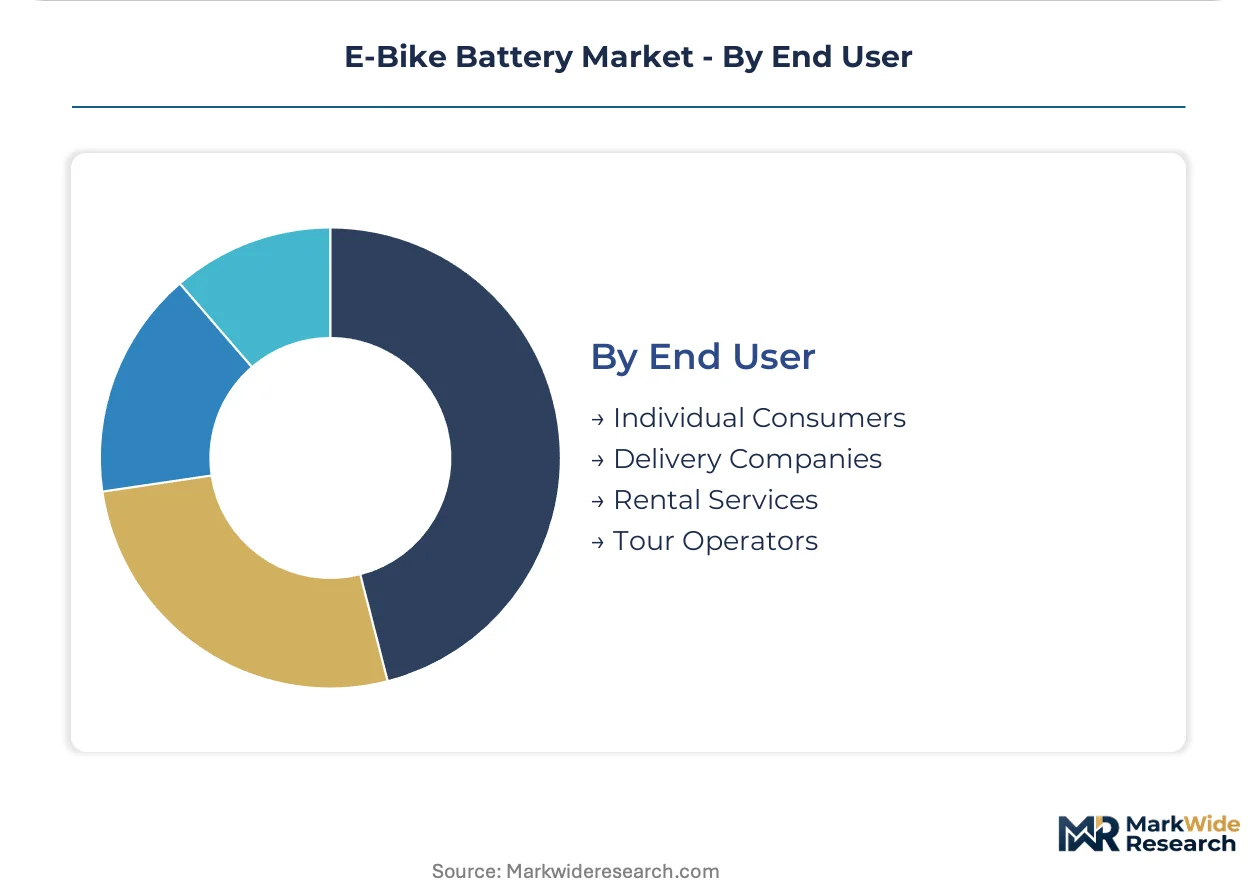
End User:
Customer type determines procurement channel structure and financing modality preferences.
- Delivery Companies:Centralized fleet procurement negotiates volume pricing and standardized BMS protocols. Milan-based logistics consolidators specify lease-to-own structures transferring degradation risk to financiers.
- Tour Operators:Seasonal demand concentration requires rapid deployment and retrieval logistics for temporary fleet scaling.
- Individual Consumers:Fragmented retail channel with dealer network dependency for installation and warranty service.
- Rental Services:Shared mobility operators prioritize swap-compatible form factors minimizing downtime across heterogeneous vehicle pools.
Largest aggregate demand: Individual Consumers. Gaining share fastest: Delivery Companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chilean lithium brine deposits anchor cathode supply chains for battery producers serving European and Asian assembly plants. German OEM procurement teams negotiate directly with Santiago-based traders to secure carbonate volumes for NMC formulations. Rotterdam port terminals now handle specialized lithium hydroxide shipments bound for Polish cell factories.
China
Jiangsu and Zhejiang manufacturing clusters assemble over sixty percent of global cylindrical cells for e-bike applications. GB/T standards mandate cell chemistry disclosure and recyclability protocols that determine domestic market access. Suzhou-based pack integrators are expanding automated production lines to meet European OEM qualification timelines.
Germany
Last-mile delivery fleets in Berlin and Hamburg are scaling 800Wh battery procurement as logistics operators replace diesel vans with cargo e-bikes. KBA type-approval requirements and EU Battery Regulation carbon footprint thresholds pressure suppliers toward documented supply chain due diligence. Bavarian industrial zones near Munich host pack assembly operations qualifying for EU Green Deal transition financing.
Netherlands
Urban logistics electrification in Amsterdam and Rotterdam drives concentrated demand for rapid-charge compatible LFP packs. REACH compliance infrastructure creates competitive advantage for suppliers with pre-certified cell chemistries. Eindhoven-region testing laboratories process UN 38.3 certification for cells destined for German OEM integration.
United States
EPA energy efficiency guidelines and emerging state-level zero-emission delivery mandates shape procurement specifications for fleet operators in California and New York. Bay Area mobility startups are piloting battery lease-to-own structures that transfer degradation risk to specialized financiers. Detroit-area automotive suppliers are repurposing lithium-ion expertise for e-bike pack assembly.
Switzerland
Alpine tour operators in Zurich and Geneva are specifying 800Wh+ packs for unsupported multi-day itineraries across mountain routes. Swissmedic-equivalent safety certification requirements align with EU Battery Regulation disclosure mandates. Basel-region logistics hubs coordinate seasonal battery deployment for temporary fleet scaling across Austrian and Italian border zones.
E-Bike Battery Market Vendor Landscape
Global majors compete with regional champions across cell chemistry roadmaps and certification protocol depth. The vendor base stratifies into three tiers: integrated cell-to-pack conglomerates with captive cathode supply, specialized pack assemblers serving OEM qualification programs, and regional fabricators focused on cost-optimized commodity volumes. Dominant competitive moves include greenfield manufacturing investments in Polish and Hungarian zones to satisfy EU Battery Regulation carbon scoring, and strategic partnerships between cell producers and e-bike motor controller architects to harmonize BMS firmware protocols.
Among Japanese and Korean cell conglomerates, Panasonic Corporation, Samsung SDI, and LG Energy Solution occupy positions exemplifying the premium-tier archetype through rigorous safety certification depth and high-voltage pack specialization. Chinese manufacturers including CATL and BYD Company represent scale-driven competitors with integrated upstream positions in lithium refining. European pack integrators such as BMZ Group and Bosch eBike Systems sit within the regional qualification-focused tier, leveraging proximity to German OEM hubs for accelerated CE marking pathways.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Samsung SDI |
| LG Energy Solution |
| CATL |
| BYD Company |
| BMZ Group |
| Bosch eBike Systems |
| Shimano Inc. |
| Amperex Technology Limited |
| Others |
Supply Flow & Price Mechanics
Fleet procurement consolidation around 800Wh LFP specifications is compressing margin structures for pack assemblers unable to achieve Jiangsu-scale manufacturing economics. German OEMs now mandate documented carbon accounting from extraction through end-of-life collection, forcing suppliers to absorb compliance costs or surrender pricing power to integrated cell producers.
Pricing Analysis
Warranty bundling and degradation risk transfer now separate premium pack suppliers from commodity assemblers in European procurement channels. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with UN 38.3 pre-certification and EU Battery Regulation carbon disclosure commanding 15-20 point spreads. Cost compression in the standard tier is intensifying because Rotterdam fleet operators are unbundling battery ownership through lease-to-own structures. Individual consumers in Southeast Asian markets exhibit highest price sensitivity, while Swiss tour operators tolerate premium positioning for alpine-rated thermal management.
Supply Chain Analysis
Dual-sourcing mandates from German OEMs now require qualified cell supply from both Chinese cylindrical producers and Korean conglomerates to mitigate Jiangsu-Zhejiang corridor concentration risk. Cathode active material draws from Chilean lithium brine deposits, Indonesian nickel laterite, and Chinese cobalt hydroxide refining. Single-source vulnerability persists in electrolyte salt production where Japanese chemical specialists dominate pharmaceutical-grade purity tiers. Distribution runs through Rotterdam port terminals for European assembly plants and Long Beach for North American pack integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The e-bike battery market is becoming a vertical-integration race where cathode precursor production and BMS firmware harmonization determine who captures margin from motor controller architects.
For Market Incumbents: Deepen backward integration into lithium hydroxide refining to secure scope 3 emissions documentation required by EU Battery Regulation carbon thresholds. Expand Polish and Hungarian cell assembly capacity to qualify for EU Green Deal transition financing before REACH compliance infrastructure hardens competitive moats. Sodium-ion prototyping pipelines from CATL and BYD threaten NMC volume in price-sensitive Southeast Asian markets. For New Entrants and Emerging Players: The 400Wh-to-600Wh price-point gap in European urban commuting represents the most penetrable white space, as incumbent pack assemblers prioritize 800Wh fleet volumes. Target Spanish and Italian rental services with swap-compatible form factors that minimize downtime across heterogeneous vehicle pools. Accelerated CE marking through Eindhoven-region testing laboratories offers faster market entry than German KBA type-approval pathways. For Investors and Strategic Acquirers: The window for entry favors specialized mobility asset lessors with lease-to-own infrastructure and degradation risk modeling capabilities. Long-term viability hinges on solid-state electrolyte patent positions and motor controller BMS protocol harmonization. Watch for EU Battery Regulation enforcement actions against Chinese suppliers lacking granular emissions data as the inflection indicator for supplier qualification shakeouts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Precursor Production | Secures scope 3 emissions documentation for EU Battery Regulation compliance and carbon footprint scoring. |
| Polish and Hungarian Manufacturing Footprint Expansion | Qualifies pack assembly operations for EU Green Deal transition financing and reduces transport emissions. |
| BMS Firmware Harmonization with Motor Controller Architects | Eliminates integration friction with Bosch, Shimano, and Brose protocols that currently compress margins. |
| Pre-Certification Investment for UN 38.3 and CE Marking | Compresses 12-16 week certification timelines that strain working capital and delay product launches. |
| Solid-State Electrolyte Prototyping Pipeline | Positions for next-generation thermal stability and energy density targets before sodium-ion alternatives mature. |
Methodological Framework
Multi-period observation of cell chemistry roadmaps, fleet procurement volumes, and certification timeline compression anchored the trend analysis, supplemented by interviews with pack assembly plant managers, OEM procurement leads at Bosch and Shimano, Eindhoven testing laboratory directors, and Rotterdam logistics fleet operators. Secondary validation drew from EU Battery Regulation disclosure filings, UN 38.3 certification databases, Chilean lithium export customs records, and SEC filings of listed cell producers. Bottom-up cell production capacity estimates triangulated against top-down e-bike registration data from German KBA and Dutch RDW.
Segment-weighting across battery type, capacity tier, application intensity, and end-user financing modality structured the analytical framework. CAGRs were derived from installed base replacement cycles and fleet electrification penetration curves across the projection horizon. Forecast inputs incorporated LFP chemistry adoption rates in commercial delivery, solid-state prototyping timelines, and sodium-ion cost parity assumptions against NMC formulations.
Inputs from OEM procurement leads and testing laboratory directors were available through the study window; gaps in Chinese supplier scope 3 emissions data introduce uncertainty bands around carbon footprint scoring compliance forecasts. Deviation in EU Battery Regulation enforcement intensity or South American lithium brine extraction volumes would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Global Electric Vehicle (EV) Management Solution Market
Electric Vehicles
Germany Automotive High Performance Electric Vehicles Market
Electric Vehicles
Vietnam Solar E-Bike Market
Electric Vehicles
Electric Vehicle Relay Market
Electric Vehicles
Premium Electric Motorcycle Market
Electric Vehicles
Water Proof E-Scooter Market
Electric Vehicles
Electric Vehicle Transmission Market
Electric Vehicles
AC BEV On-Board Charger Market
Electric Vehicles
Europe Solar E-Bike Market
Electric Vehicles
High Voltage PTC Heaters for Electric Vehicles Market
Electric Vehicles
Japan E-Bike Market
Electric Vehicles
Germany Electric Bus Battery Pack Market
Electric Vehicles
Oman Electric Vehicle (EV) Market
Electric Vehicles
Electric Shuttle Market
Electric Vehicles
Hybrid EV Conversion Kit Market
Electric Vehicles
China NEV Taxi Market