
 APAC E-Bikes Market | 2026-2036
APAC E-Bikes Market Size, Share, and Industry Trends Forecast 2026-2036
APAC E-Bikes Market Intelligence
Mid-drive motor performance tier is redrawing competitive boundaries across the APAC E-Bikes landscape. Yadea Group Holdings Ltd leverages its integrated battery-motor manufacturing base in Wuxi to control cost structures at scale. Giant Manufacturing Co. Ltd anchors premium positioning through its proprietary drive systems and cycling heritage. Yamaha Motor Company differentiates via torque-sensor engineering refined through decades of powertrain development.
An e-bike combines a pedal-driven bicycle frame with an electric assist system comprising a rechargeable battery pack, motor unit, and controller module delivering supplemental power up to regulated speed thresholds, primarily serving urban mobility and commercial logistics applications. Lithium-ion battery configurations now dominate procurement decisions as energy density improvements reduce weight penalties for delivery services operating extended routes. Hub motor designs retain volume leadership across city bike and folding bike categories where simplicity and serviceability outweigh terrain-handling demands. Mid-drive architectures capture margin concentration in mountain bike and cargo bike segments where torque distribution and center-of-gravity optimization command price premiums from recreational users and fleet operators.
China's SAMR enforces GB 17761 standards governing maximum speeds, vehicle mass, and motor power ratings that determine street-legality and insurance classification across the largest national market. India's BIS certification requirements for lithium-ion cells and chargers are elevating safety barriers for imported and domestic products alike. Japan's METI maintains stringent type-approval protocols under road transport vehicle law that filter non-compliant entrants from its high-specification commuter segment. Stakeholders must monitor divergent national certification timelines and subsidy phase-out schedules to align capacity investments with regulatory windows.
Market Dynamics
China's GB 17761 safety certification tightening is forcing manufacturing consolidation across the APAC E-Bikes landscape, as smaller assemblers lose access to battery suppliers unwilling to absorb compliance testing costs.
Growth Catalysts
- India's PLI scheme for advanced chemistry cell manufacturing:Domestic lithium-ion cell production incentives are reducing import dependency for battery packs serving metro commuter corridors in Mumbai and Bangalore.
- Last-mile delivery electrification mandates:Urban logistics operators across Jakarta, Bangkok, and Ho Chi Minh City are replacing gasoline two-wheelers with electric alternatives under municipal clean air commitments.
- Mid-drive motor torque-sensor engineering:Precision powertrain calibration is opening cargo bike segments where load-hauling efficiency determines fleet operator procurement decisions.
Market Restraints
- Lithium carbonate price volatility:Raw material cost swings for cathode active materials compress margin structures for battery pack assemblers operating on fixed-price fleet contracts.
- Single-source dependency on Yangtze River Delta motor controllers:Concentrated PCB and power electronics manufacturing in Jiangsu and Zhejiang provinces creates supply vulnerability for ASEAN market entrants.
- Japan METI type-approval timeline friction:Extended road transport vehicle law certification cycles filter non-compliant products from the high-specification commuter segment.
Strategic Opportunities
- Vietnam's underpenetrated provincial cities:Secondary urban centers outside Hanoi and Ho Chi Minh City present white space for distributor network expansion before subsidy windows mature.
- Battery-swapping infrastructure convergence:Interoperable swap station networks combining IoT telemetry with standardized pack form factors are emerging as an alternative to overnight charging for delivery fleets.
- Indonesia's nickel-to-battery verticalization push:State-backed refining and cell manufacturing investments are creating captive supply advantages for domestic e-bike assembly operations.
Industry Challenges
- BIS lithium-ion cell certification backlog:India's testing infrastructure capacity constraints delay product launches for importers and domestic manufacturers targeting festive season procurement cycles.
- Legacy fleet operator maintenance skill gaps:Transitioning motorcycle mechanics to electric powertrain diagnostics requires retraining programs that compress deployment timelines for commercial buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC E-Bikes Market |
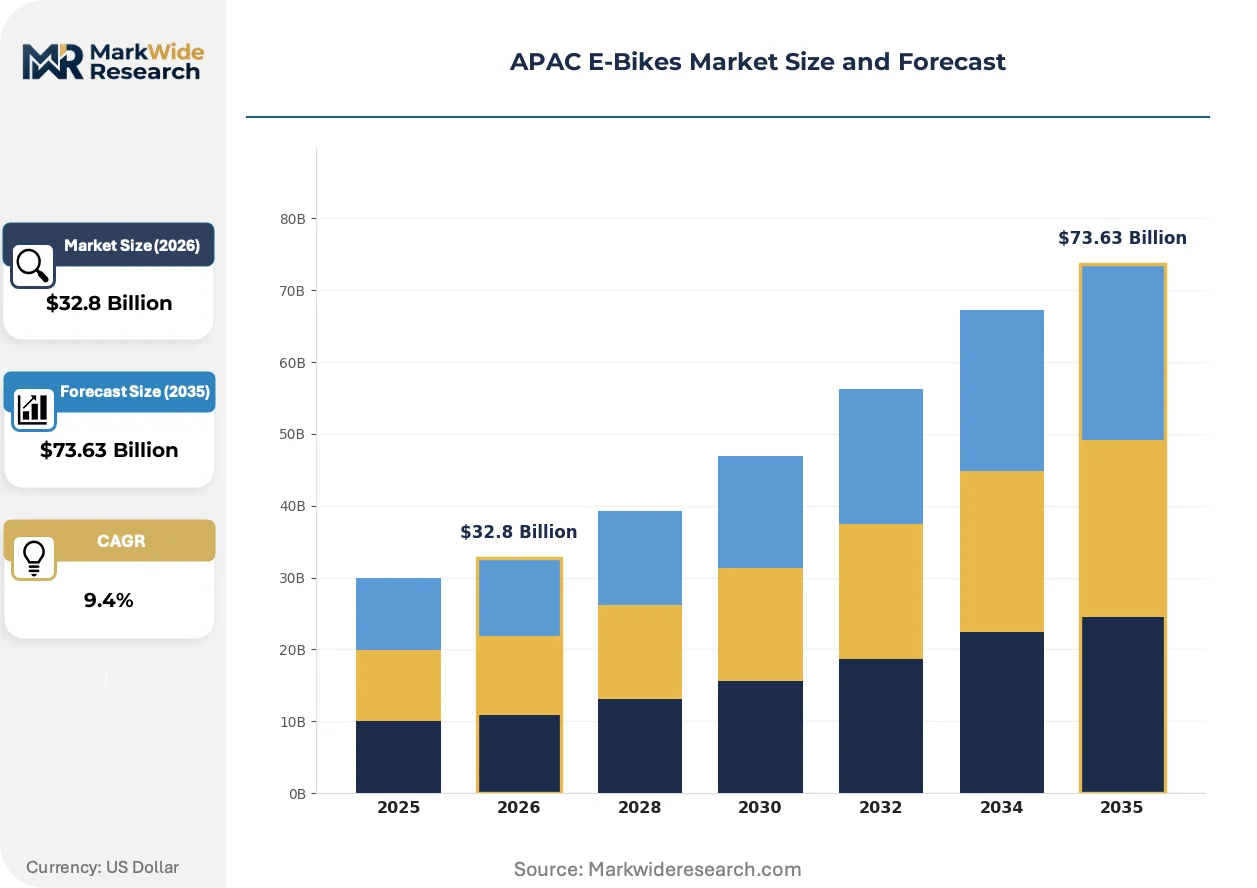
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $73.63 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: City Bikes, Mountain Bikes, Folding Bikes, Cargo Bikes Battery Type: Lithium-Ion, Lead-Acid, Nickel-Metal Hydride, Others Motor Type: Mid-Drive, Hub Motor, Integrated, Geared End User: Commuters, Recreational Users, Delivery Services, Leisure Riders |
| Companies Covered | Yadea Group Holdings Ltd, Aima Technology Group Co. Ltd, Jiangsu Xinri E-Vehicle Co. Ltd, Giant Manufacturing Co. Ltd, Merida Industry Co. Ltd, Yamaha Motor Company, Shenzhen TAILG Technology Group Co. Ltd, NIU Technologies, Luyuan Electric Vehicle, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC E-Bikes Market Strategic Shifts & Innovations
Solid-state battery prototyping and torque-vectoring motor controls are redrawing technical boundaries in the APAC E-Bikes market, compressing development cycles for premium product tiers.
Sodium-ion chemistry is supplanting lithium-iron-phosphate configurations in entry-level urban commuter bikes where energy density trade-offs are acceptable for cost-sensitive buyers. Chinese cell manufacturers are scaling pilot production lines for sodium-ion packs targeting the Yangtze River Delta replacement market. This chemistry shift is enabling price positioning below lithium-based equivalents without triggering GB 17761 mass threshold violations.
China's SAMR enforcement of GB 42295 battery safety standards is mandating thermal runaway propagation testing for all new lithium-ion pack designs. The regulation forces redesign cycles for battery management systems and enclosure engineering. Domestic manufacturers with captive testing facilities are accelerating certification timelines while import-dependent brands face extended approval queues.
Fleet procurement committees are consolidating vendor relationships around full-service lease models bundling hardware, maintenance, and battery refresh obligations. Traditional distributor networks serving individual consumers are losing share to direct manufacturer contracts with logistics operators in Singapore and Kuala Lumpur. This channel compression is most visible in Indonesia's two-wheel delivery sector where Gojek and Grab have established preferred supplier frameworks.
APAC E-Bikes Market Segmentation
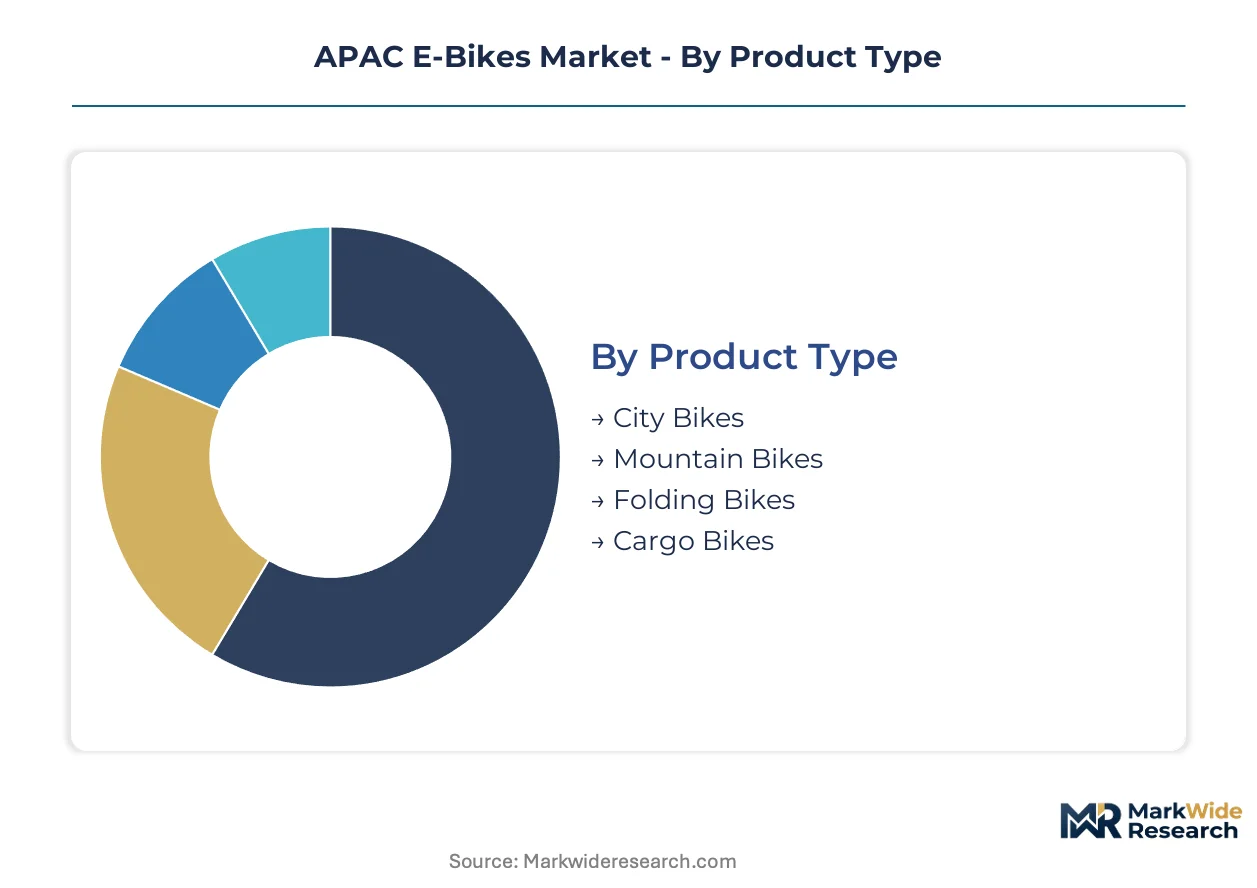
Segmentation clarity determines procurement strategy for fleet operators navigating divergent national certification regimes. Product architecture choices cascade through battery chemistry decisions and motor placement specifications that trigger distinct compliance pathways across China's GB standards, India's BIS requirements, and Japan's METI protocols.
Product Type:
GB 17761 mass thresholds and speed classifications in China filter which frame geometries qualify for street-legal operation without licensing burdens, while India's urban density patterns favor compact configurations for metro corridor parking constraints.
- City Bikes:Step-through frames with integrated battery housings dominate procurement volumes across China's Yangtze River Delta manufacturing cluster. Municipal fleet operators in Jakarta and Bangkok specify these configurations for their serviceability and theft-resistant battery placement.
- Mountain Bikes:Full-suspension frames with reinforced bottom brackets accommodate mid-drive motor torque loads. Demand concentrates in Japan's high-specification recreational segment where METI type-approval standards filter entry-level competitors from premium positioning.
- Folding Bikes:Hinge mechanisms with quick-release battery packs serve multi-modal commuters across Singapore's MRT-integrated corridors and Hong Kong's ferry-terminal connections.
- Cargo Bikes:Extended wheelbases with reinforced head tubes support front-loading delivery configurations. India's last-mile logistics operators in Mumbai and Bangalore are scaling procurement of these variants under municipal clean air mandates.
Established volume favors City Bikes; emerging adoption favors Cargo Bikes.
Battery Type:
Cost tier stratification separates chemistry choices, with sodium-ion pilot lines disrupting entry-level positioning and lithium-ion retaining margin concentration in performance segments.
- Lithium-Ion:NMC and LFP cathode configurations deliver energy density above 200 Wh/kg for extended-range delivery routes. China's SAMR enforcement of GB 42295 thermal runaway standards is forcing redesign cycles for pack enclosures and battery management systems.
- Lead-Acid:Flooded and AGM variants persist in India's price-sensitive provincial markets where BIS certification backlogs delay lithium-ion product launches. Weight penalties restrict these configurations to short-radius urban applications.
- Nickel-Metal Hydride:Memory-effect limitations and lower energy density have relegated this chemistry to legacy fleet maintenance contracts in Japan's established commuter corridors.
- Others:Sodium-ion prototypes from Chinese cell manufacturers are targeting the Yangtze River Delta replacement market with cost positioning below lithium equivalents without triggering GB 17761 mass threshold violations.
Procurement committees are consolidating around Lithium-Ion for new fleet deployments; Lead-Acid retains residual share in cost-constrained replacement cycles.
Motor Type:
Application requirements determine torque distribution needs, with load-hauling efficiency driving mid-drive specification and simplicity favoring hub integration for flat-terrain urban circuits.
- Mid-Drive:Bottom-bracket placement leverages bicycle drivetrain gear ratios for torque multiplication. Fleet operators in Ho Chi Minh City and Kuala Lumpur specify these for cargo applications where hill-climbing efficiency determines total cost of ownership.
- Hub Motor:Direct-drive and geared variants integrated into front or rear wheels dominate China's export volumes for city bike and folding bike categories. Jiangsu and Zhejiang province PCB manufacturing concentration creates supply vulnerability for ASEAN market entrants.
- Integrated:Frame-embedded motor housings with proprietary controller interfaces command price premiums from premium positioning strategies.
- Geared:Planetary reduction systems within hub enclosures optimize torque output for stop-start urban traffic patterns across India's metro commuter corridors.
Hub Motor architectures retain volume leadership; Mid-Drive configurations are expanding most quickly in commercial logistics specifications.
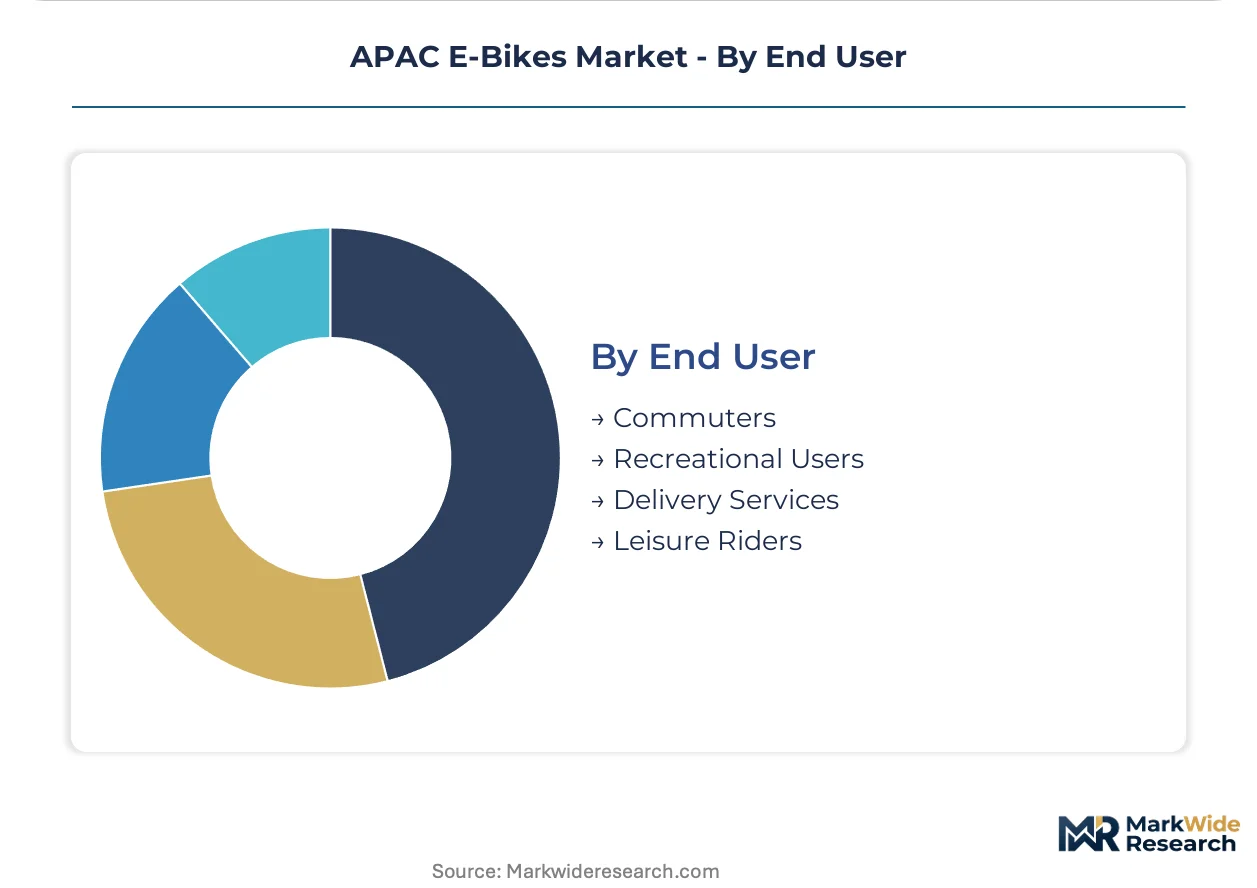
End User:
Customer type fragmentation separates individual purchase decisions from fleet procurement frameworks, with channel compression favoring direct manufacturer contracts over traditional distribution.
- Commuters:Daily work-trip riders across China's tier-one cities and India's expanding metro networks prioritize reliability and charging infrastructure access. GB 17761 speed limitations align with urban traffic flow constraints.
- Recreational Users:Weekend trail riders in Japan's mountain prefectures and Australia's coastal regions specify torque-sensor calibration and suspension travel. METI type-approval timelines filter non-compliant products from this quality-sensitive segment.
- Delivery Services:Platform logistics operators including Gojek and Grab in Indonesia have established preferred supplier frameworks bundling hardware, maintenance, and battery refresh obligations.
- Leisure Riders:Occasional urban explorers and tourist rental fleets in Vietnam's secondary cities represent white space for distributor network expansion before subsidy windows mature.
Delivery Services are driving the steepest expansion trajectory; Commuters retain the largest installed base across the region.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from China's Yangtze River Delta manufacturing cluster dominate regional supply, while import dependency shapes procurement strategies across Southeast Asian markets lacking domestic cell production.
China
Domestic replacement demand and fleet electrification orders from Indonesia and Vietnam drive volume. SAMR enforces GB 42295 thermal runaway standards that force battery pack redesign cycles. Wuxi and Changzhou anchor motor-controller manufacturing concentration serving ASEAN market entrants.
India
Metro commuter corridors in Mumbai and Bangalore absorb cargo bike deployments for last-mile logistics. BIS certification backlogs for lithium-ion cells delay product launches ahead of festive procurement cycles. Tamil Nadu and Maharashtra host emerging assembly operations targeting price-sensitive provincial markets.
Japan
High-specification recreational demand concentrates in mountain prefectures requiring torque-sensor calibration. METI type-approval timelines under road transport vehicle law filter non-compliant entrants. Kansai and Chubu regions maintain premium commuter segment positioning through quality-sensitive distribution.
Indonesia
Gojek and Grab platform logistics operators consolidate vendor relationships around full-service lease models. State-backed nickel refining investments create captive supply advantages for domestic assembly. Java-based operations scale preferred supplier frameworks bundling hardware and battery refresh obligations.
Vietnam
Secondary urban centers outside Hanoi and Ho Chi Minh City present distributor network expansion opportunities. Municipal clean air commitments in Ho Chi Minh City accelerate gasoline two-wheeler replacement programs. Northern manufacturing zones absorb Chinese component imports for local assembly.
APAC E-Bikes Market Key Industry Players
Concentration sits with integrated battery-motor manufacturers and heritage cycling brands occupying distinct tier positions. China's Jiangsu and Zhejiang province clusters host volume leaders controlling cost structures through captive PCB and power electronics production. Three archetypes define competitive positioning: scale-driven integrated manufacturers, premium heritage brands with proprietary drive systems, and platform logistics enablers bundling hardware with service obligations. Dominant moves include backward integration into cell manufacturing and direct fleet contracts bypassing traditional distribution layers.
Among Chinese volume manufacturers, Yadea Group Holdings Ltd and Jiangsu Xinri E-Vehicle Co. Ltd occupy positions exemplifying scale-driven integration archetypes, while Giant Manufacturing Co. Ltd represents heritage brand positioning through cycling pedigree and proprietary system development.
| Leading Market Players |
|---|
| Yadea Group Holdings Ltd |
| Aima Technology Group Co. Ltd |
| Jiangsu Xinri E-Vehicle Co. Ltd |
| Giant Manufacturing Co. Ltd |
| Merida Industry Co. Ltd |
| Yamaha Motor Company |
| Shenzhen TAILG Technology Group Co. Ltd |
| NIU Technologies |
| Luyuan Electric Vehicle |
| Others |
Cost & Logistics Intelligence
Fixed-price fleet contracts spanning 24-36 month terms lock in both battery pack supply access and margin visibility for logistics operators across Jakarta and Bangkok, insulating procurement committees from lithium carbonate spot volatility while committing assemblers to cost structures that compress when raw material swings exceed contract escalation clauses.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in the APAC E-Bikes landscape. Premium tiers command positioning through METI type-approval certification and torque-sensor calibration, while economy positioning relies on sodium-ion chemistry and hub motor simplicity for cost-sensitive provincial markets. Cost compression in entry-level segments is intensifying because Chinese cell manufacturers are scaling sodium-ion pilot production. Fleet operators exhibit lowest price sensitivity due to total cost of ownership framing, whereas individual commuters in India's tier-two cities show highest elasticity.
Supply Chain Analysis
Yangtze River Delta port congestion and PCB manufacturing concentration in Jiangsu and Zhejiang provinces create chokepoint vulnerability for ASEAN market entrants dependent on Chinese motor controller imports. Battery cell supply draws from China, South Korea, and Japan, with cathode active materials and power electronics representing critical input dependencies. Single-source vulnerability in concentrated PCB manufacturing threatens supply continuity for Indonesian and Vietnamese assemblers. Distribution runs through direct manufacturer contracts with platform logistics operators, bypassing traditional distributor layers in Singapore and Kuala Lumpur.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery-as-a-service subscription layers and full-service lease bundling are expanding faster than hardware sales across Indonesian and Vietnamese fleet deployments, converting capital expenditure into recurring revenue streams that improve customer lifetime value metrics.
For Market Incumbents: Compound defensive positioning through backward integration into cell manufacturing and captive certification testing facilities that accelerate GB 42295 thermal runaway approval timelines. Sodium-ion chemistry disruption from Chinese pilot lines threatens lithium-ion margin structures. Control over Yangtze River Delta motor-controller supply secures volume allocation priority during capacity constraints. For New Entrants and Emerging Players: Differentiate on battery-swapping interoperability and IoT-enabled telemetry platforms that reduce fleet operator total cost of ownership. Vietnam's secondary urban centers outside Hanoi and Ho Chi Minh City represent the most penetrable white space. Target direct procurement relationships with municipal clean air program administrators rather than competing through distributor networks. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fleet-focused hardware-as-a-service providers bundling maintenance and battery refresh obligations. Long-term viability favors integrated battery-motor manufacturers with captive Yangtze River Delta production and direct logistics platform contracts. Watch sodium-ion chemistry cost parity achievement as the inflection signal for lithium-ion margin compression acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cell Manufacturing | Captive lithium-ion or sodium-ion cell production insulates margin structures from cathode material price volatility and BIS certification backlogs. |
| Battery-Swapping Infrastructure Deployment | Interoperable swap station networks with standardized pack form factors reduce fleet operator downtime and enable pay-per-use pricing models. |
| Direct Fleet Contract Consolidation | Preferred supplier frameworks with Gojek and Grab bypass distributor margins and lock in multi-year hardware-service bundles. |
| GB 42295 Certification Acceleration | Domestic testing facility investments compress SAMR approval timelines versus import-dependent competitors facing extended queues. |
| Torque-Sensor Engineering Investment | Precision powertrain calibration opens cargo bike segments where load-hauling efficiency determines procurement decisions in Ho Chi Minh City. |
Research Approach
Initial hypotheses were tested against primary input from fleet procurement managers at platform logistics operators, battery pack engineering directors, municipal clean air program administrators, and aftermarket service network heads, then refined through secondary validation against SAMR regulatory filings, BIS certification databases, Indonesia's Ministry of Industry investment disclosures, and Yangtze River Delta customs export records, with bottom-up unit economics triangulated against top-down market sizing.
Variance decomposition across the projection horizon isolates volume drivers by product architecture, battery chemistry tier, motor placement specification, end-user category, and national regulatory cluster, with CAGRs derived from segment-level growth rate reconciliation and cross-referenced against lithium carbonate price trajectory assumptions and fleet electrification mandate implementation schedules.
Material uncertainties — subsidy phase-out timing, lithium-sodium chemistry cost crossover points, and METI type-approval timeline extensions — sit outside the modeled envelope, with forecasts reflecting documented assumptions about regulatory enforcement intensity and raw material supply continuity. Practitioners should keep alternative scenarios live as GB standards enforcement consistency and nickel-to-battery verticalization progress evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Belgium E-Bike Market
Electric Vehicles
Electric Vehicle Communication Controller Market
Electric Vehicles
Hybrid Electric Vehicle Battery Market
Electric Vehicles
Europe Electric Light Commercial Vehicles Market
Electric Vehicles
Latin America Electric Bus Market
Electric Vehicles
Electric Motorcycles and Scooters Market
Electric Vehicles
Electric Scooters and Mopeds Market
Electric Vehicles
Electric Vehicle Electric Heating Film Market
Electric Vehicles
Global Electric Vehicles Market
Electric Vehicles
EV Lightweight Materials Market
Electric Vehicles
Bus Pantograph Charger Market
Electric Vehicles
Nordic E-Bike Market
Electric Vehicles
Spain Solar E-Bike Market
Electric Vehicles
Oman EV Market
Electric Vehicles
Automotive Coolant Distribution Manifold for EV Battery Market
Electric Vehicles
US Automotive High Performance Electric Vehicle Market