
 Electric Bike Kit Market | 2026-2036
Electric Bike Kit Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Bike Kit Market Analysis
Chinese brushless motor production is rebalancing as export certification costs rise for EU-bound kit manufacturers. Bafang leverages in-house controller design to sustain pricing power across European distributor networks. Pendix anchors its position through German-engineered mid-drive systems that compete on torque precision rather than wattage ratings. Yose Power differentiates via direct-to-consumer battery-motor bundles that occupy the value tier in North American online channels.
An electric bike kit converts standard bicycles into pedal-assisted electric vehicles through the addition of a motor, battery, controller, and sensors, with hub motors typically delivering 250W to 1000W of nominal power through direct-rim or spoke-mounted configurations. The primary commercial purpose is enabling low-cost electrification of existing bicycle fleets without full vehicle replacement, reducing capital outlay for delivery operators and commuter programs. Mid-drive systems command margin pools in OEM supply chains where torque-sensing integration and frame compatibility justify premium positioning, while DIY installation routes are accelerating fastest among retail consumers seeking weekend conversion projects without workshop dependency. Hub motor kits retain volume leadership in Asian export markets where simplicity and minimal frame modification dominate procurement criteria.
The EU F-Gas Regulation and CE marking requirements under the Machinery Directive shape product standards for battery thermal management and motor enclosure ratings, with ECHA REACH compliance adding material disclosure burdens on imported controllers. The US Consumer Product Safety Commission and FCC regulate battery safety and wireless connectivity modules respectively, creating dual-certification costs for brands selling transatlantic. Stakeholders must monitor how pending EU Battery Passport rules reshape supply chain documentation requirements for cells sourced outside the trading bloc.
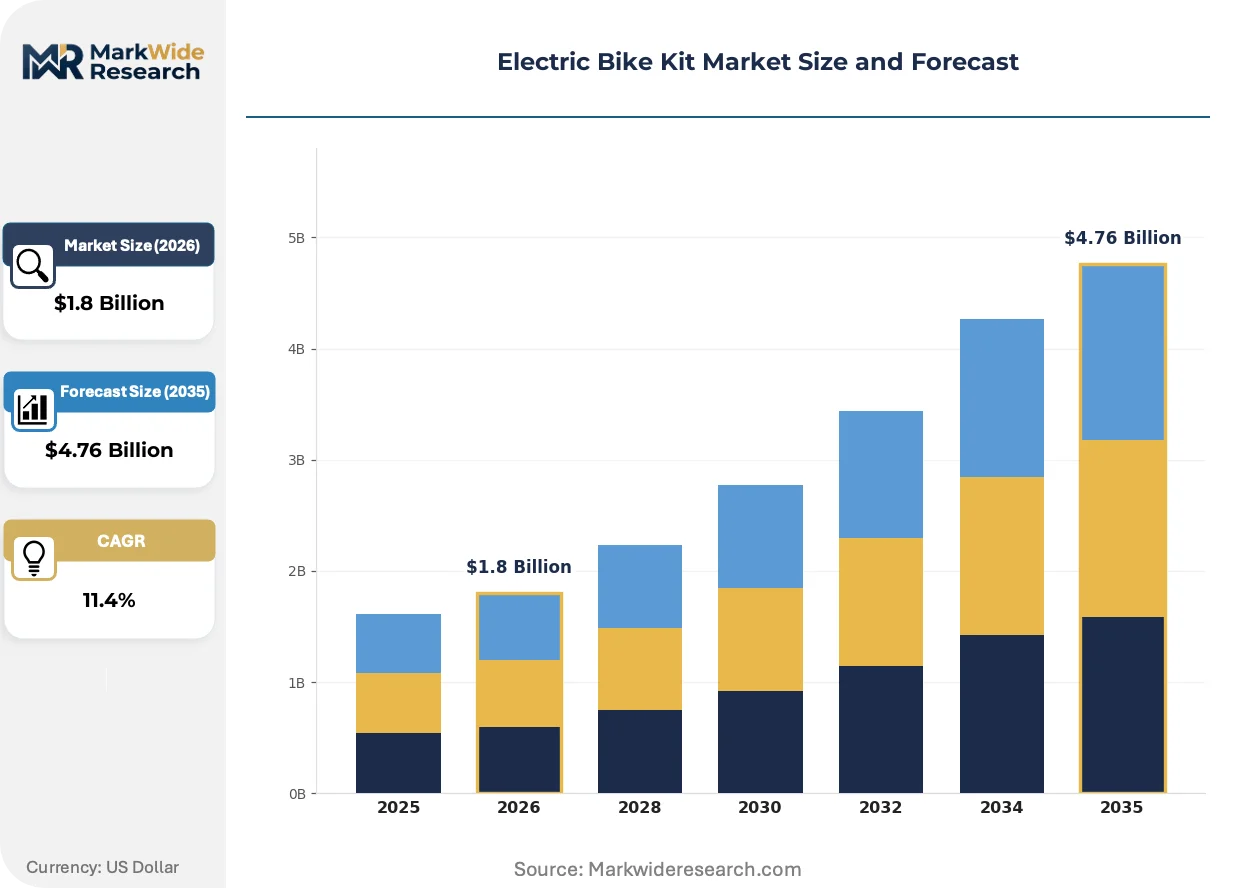
Market Dynamics
EU urban mobility directives are forcing fleet operators to electrify existing bicycle assets rather than replace entire vehicle pools, compressing procurement timelines and reshaping supplier relationships around retrofit compatibility.
Growth Catalysts
- Lithium-ion energy density gains:Cell chemistry advances enable 40% range extension without frame redesign, reducing total conversion cost for delivery fleet operators.
- Germany's bicycle commuter subsidies:Federal tax incentives for employer-provided e-bikes accelerate mid-drive kit adoption among corporate procurement departments.
- F-Gas Regulation compliance:EU mandates on thermal management systems push OEMs toward integrated battery-motor solutions with certified enclosure ratings.
Market Restraints
- Controller semiconductor concentration:Taiwanese foundry capacity constraints create 12-16 week lead times for brushless motor control boards.
- REACH material disclosure:ECHA compliance adds documentation burden on imported battery housings and wiring harnesses from Asian suppliers.
- Hub motor torque limitations:Direct-drive systems lack hill-climbing performance for cargo applications above 150 kg payload.
Strategic Opportunities
- Amsterdam-Copenhagen fleet retrofit corridors:Municipal delivery contracts favor hub motor suppliers with same-day installation capability.
- Battery Passport alignment:EU supply chain documentation rules create first-mover advantage for cell traceability systems.
- Direct-to-consumer bundling:Online battery-motor pairings bypass distributor markups in North American retail channels.
Industry Challenges
- Dual-certification complexity:FCC wireless modules and CPSC battery safety standards create parallel testing tracks for transatlantic brands.
- Torque-sensing calibration:Mid-drive integration requires frame-specific sensor mapping that strains technical support capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Bike Kit Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hub Motor, Mid-Drive System, Conversion Kit, Battery Pack End User: Retail Consumers, E-Bike Manufacturers, Delivery Services, Ride-Sharing Companies Power Rating: 250W, 500W, 750W, 1000W Installation Type: DIY Kits, Pre-Installed, Professional Installation, Modular Components |
| Companies Covered | Sailimotor, EBikeKit, Bafang, Pendix, Yose Power, Swytch, eBikeling, Rubbee, Tongsheng, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Bike Kit Market Emerging Trajectories
Retrofit electrification is compressing the traditional bicycle replacement cycle while forcing component suppliers to modularize around legacy frame geometries rather than clean-sheet designs.
Regenerative braking hardware is converging with standard hub motor architectures to capture descent energy in hilly urban terrains. European courier fleets in Lisbon and San Francisco are piloting these systems to extend daily range without battery swaps. The technology is converging with fleet telematics platforms that monitor energy recovery rates across route profiles.
The EU Battery Passport rules are mandating cell-level traceability documentation that reshapes procurement contracts for non-EU battery suppliers. Manufacturers must now embed digital product passports covering carbon footprint and material origin. German mid-drive specialists are responding by qualifying domestic cell assembly partners to shorten compliance timelines.
Installation service unbundling is fragmenting the traditional distributor-installer relationship as YouTube-educated consumers attempt weekend conversions. Amazon and specialist forums now host diagnostic communities that reduce dependency on authorized service networks. This pattern is most visible in US and Australian markets where labor costs exceed kit hardware prices.
Electric Bike Kit Market Segmentation
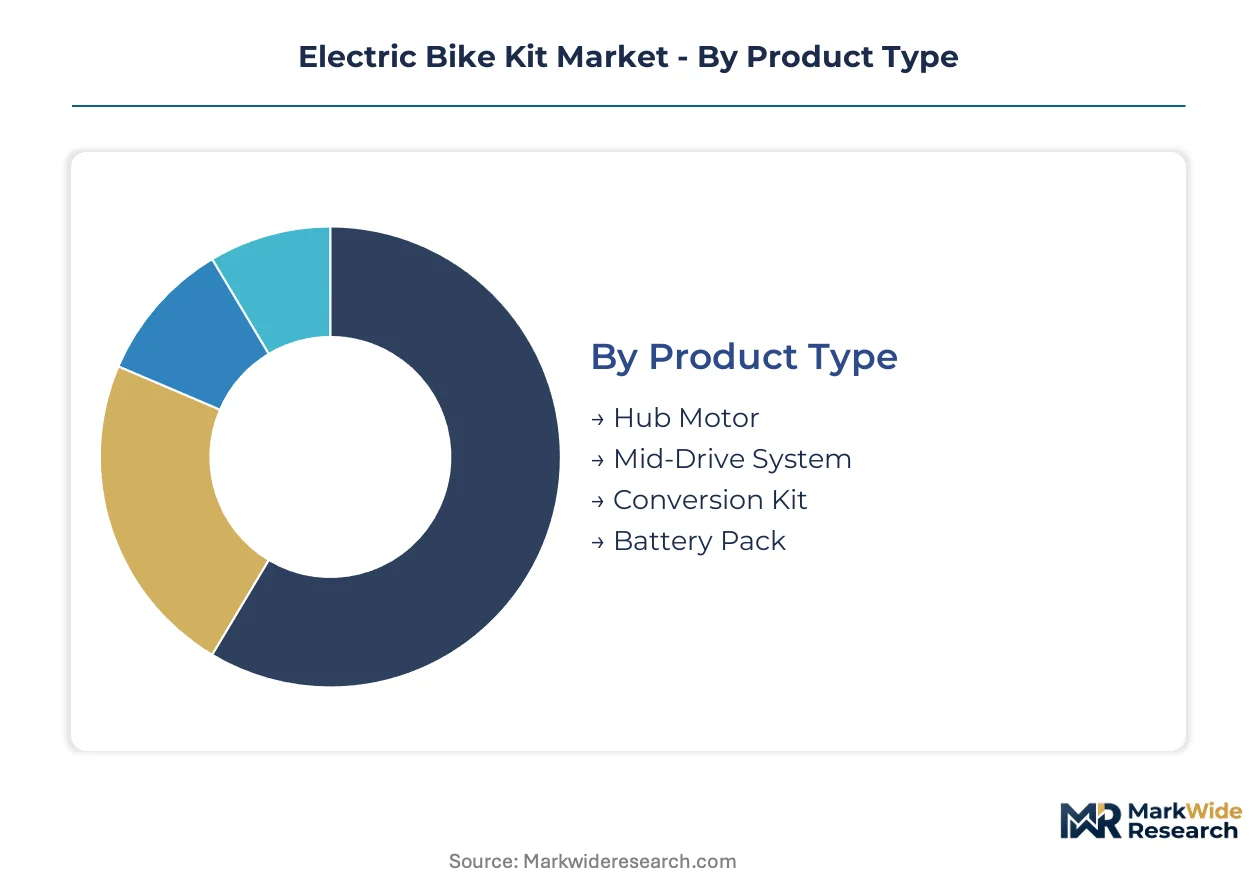
Segmentation in the electric bike kit market reveals divergent procurement logics between fleet operators optimizing for total cost of ownership and retail consumers prioritizing installation simplicity. The four-dimensional structure—product architecture, end-user application, power output, and installation modality—determines supplier competitive positioning and margin capture.
Product Type:
Hub motor configurations dominate unit volume through mechanical simplicity, while mid-drive systems anchor premium pricing through torque-sensing precision and frame integration requirements.
- Hub Motor:Direct-drive or geared units mount within the wheel hub, delivering power through rim torque without frame stress. Amsterdam and Copenhagen municipal fleets specify these for same-day retrofit capability on existing cargo bicycles, driven by EU urban mobility directive compliance deadlines.
- Mid-Drive System:Crank-mounted motors leverage bicycle gearing for torque multiplication, requiring frame-specific bottom bracket compatibility. German corporate procurement departments favor these for commuter subsidy programs where pedal-assist smoothness justifies higher conversion cost.
- Conversion Kit:Bundled motor-controller-sensor packages enable standard bicycle electrification without OEM frame purchase. Demand concentrates in North American online channels where labor costs exceed hardware prices.
- Battery Pack:Modular lithium-ion enclosures with BMS integration range from frame-tube to rack-mounted configurations. EU Battery Passport rules are reshaping procurement contracts toward cell-traceable suppliers.
Mature deployment sits with Hub Motor. Newer deployment is concentrated in Mid-Drive System.
End User:
Application context dictates performance specifications, with commercial operators prioritizing durability metrics and payload capacity over consumer-oriented weight minimization.
- Retail Consumers:Weekend conversion projects drive DIY installation demand, with YouTube tutorials reducing dependency on authorized service networks. Australian and US markets show strongest activity where individual labor substitution economics favor self-installation.
- E-Bike Manufacturers:OEM procurement of mid-drive systems for factory integration requires torque-sensor calibration protocols and frame compatibility documentation. German specialists capture this tier through engineering partnership models.
- Delivery Services:Fleet operators in Lisbon and San Francisco pilot regenerative braking hub motors to extend daily range without battery swap infrastructure. Route telematics integration shapes supplier selection criteria.
- Ride-Sharing Companies:High-utilization dockless fleets demand rapid field-replaceable components, favoring modular hub architectures over integrated mid-drive systems.
Volume concentrates with Delivery Services. Margin expansion is steepest with E-Bike Manufacturers.
Power Rating:
Regulatory thresholds segment the market, with EU type-approval limits at 250W creating distinct procurement pools from North American performance-oriented specifications.
- 250W:EU-compliant nominal output for pedal-assist systems without throttle capability. German bicycle commuter subsidy programs mandate this ceiling for employer-provided fleet eligibility.
- 500W:Mid-tier output balancing hill-climbing torque with battery range conservation. Cargo applications above 100 kg payload in hilly terrain specify this threshold.
- 750W:US Class 3 speed-pedelec specification enabling 28 mph assisted velocity. FCC wireless module certification adds parallel testing requirements for controller connectivity.
- 1000W:Direct-drive hub motor peak output for commercial cargo hauling. Thermal management under sustained load requires enhanced enclosure ratings per F-Gas Regulation.
Regulatory alignment clusters at 250W. Performance differentiation drives expansion at 750W.
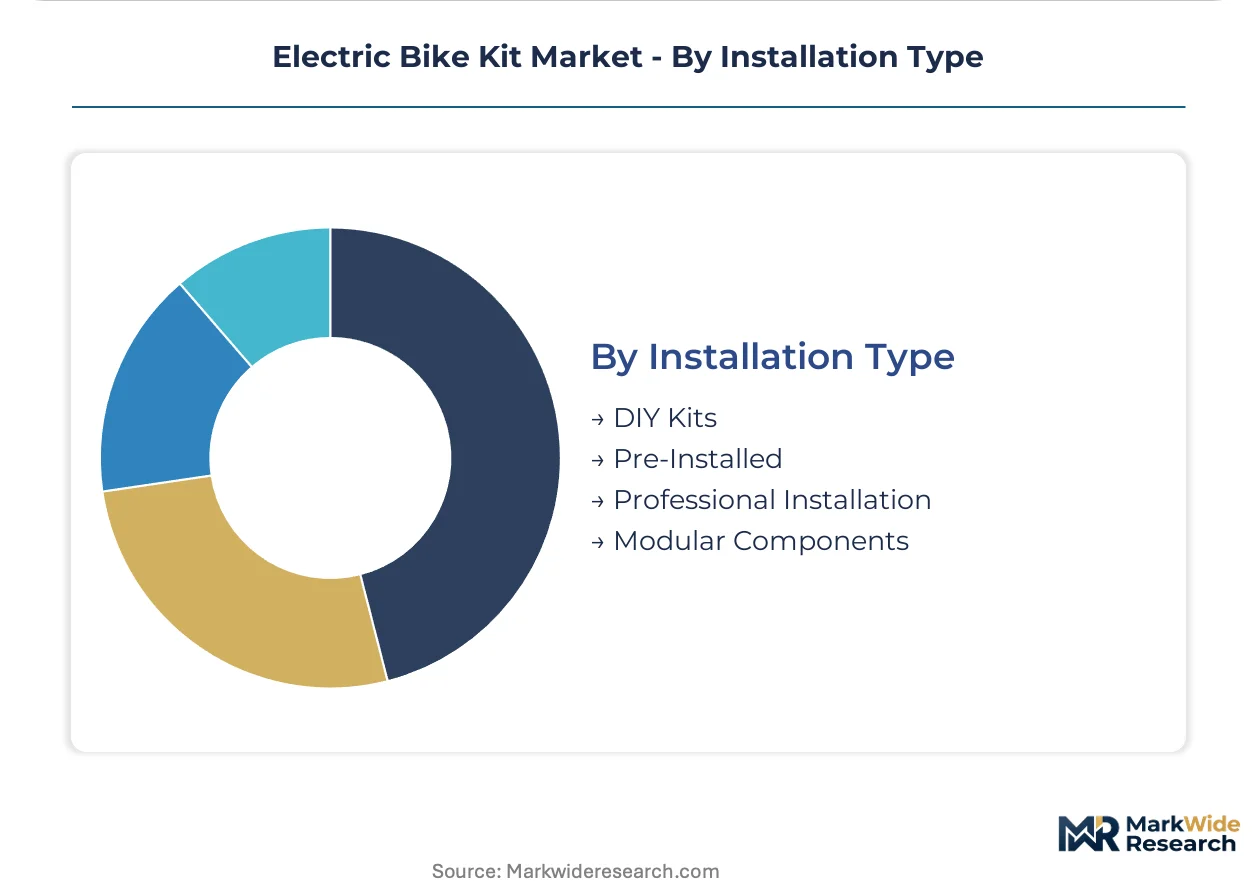
Installation Type:
Service unbundling is fragmenting traditional distributor-installer relationships as diagnostic communities reduce technical support dependency.
- DIY Kits:Consumer-assembled packages with plug-and-play wiring harnesses and online troubleshooting forums. Amazon marketplace bundling of battery-motor pairs bypasses distributor markups.
- Pre-Installed:Factory-integrated systems on complete e-bikes, not technically kits but competing for the same consumer expenditure. OEM mid-drive calibration eliminates field variability.
- Professional Installation:Authorized service network dependency for mid-drive torque-sensor mapping and frame stress verification. KBA certification requirements in Germany elevate labor credential standards.
- Modular Components:Separately sourced motors, batteries, and controllers enabling custom specification. REACH material disclosure burdens concentrate on imported controller housings and wiring assemblies.
Channel control rests with Professional Installation. Volume acceleration is fastest through DIY Kits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium-ion cell manufacturing clusters in China and South Korea anchor upstream supply for kit battery packs, while European assembly plants concentrate around German engineering centers and Dutch logistics hubs.
Germany
Federal bicycle commuter subsidies and KBA certification requirements drive mid-drive kit procurement by corporate fleet departments. The F-Gas Regulation mandates thermal management compliance for battery enclosures. Stuttgart and Munich host engineering partnerships between kit specialists and automotive tier-one suppliers.
Netherlands
Amsterdam municipal delivery contracts prioritize same-day retrofit capability on existing cargo bicycle fleets. EU urban mobility directives compress procurement timelines for electrification compliance. Eindhoven's manufacturing corridor supplies hub motor controllers to fleet operators across the Randstad.
United States
FCC wireless module certification and CPSC battery safety standards create dual-testing requirements for transatlantic brands. Class 3 speed-pedelec regulations at 750W differentiate state-level procurement. San Francisco courier fleets pilot regenerative braking systems integrated with route telematics platforms.
China
Brushless motor production rebalances as export certification costs rise for EU-bound manufacturers. GB standards and MIIT oversight shape domestic product specifications. Zhejiang and Guangdong provinces concentrate hub motor assembly for Asian export markets where mechanical simplicity dominates.
Denmark
Copenhagen's municipal delivery operators retrofit conventional bicycles to meet stricter urban mobility directives. CE marking under the Machinery Directive shapes controller enclosure specifications. The Øresund corridor links Danish fleet operators with Swedish battery assembly partners for Nordic distribution.
Electric Bike Kit Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue direct-to-consumer bundling and fleet telematics integration. The vendor base distributes across three tiers: engineering-intensive mid-drive specialists, volume-oriented hub motor fabricators, and online-native battery-motor bundlers. Strategic moves concentrate on distributor network consolidation and EU Battery Passport alignment for cell traceability.
Among Chinese brushless motor specialists, Bafang and Tongsheng occupy positions within the volume-tier export segment. German-engineered mid-drive systems are represented by Pendix, which exemplifies torque-precision positioning against wattage-rated competition. These three anchors illustrate the geographic and technical bifurcation between Asian manufacturing scale and European engineering integration.
| Leading Market Players |
|---|
| Sailimotor |
| EBikeKit |
| Bafang |
| Pendix |
| Yose Power |
| Swytch |
| eBikeling |
| Rubbee |
| Tongsheng |
| Others |
Supply Flow & Price Mechanics
Germany's bicycle commuter subsidies mandating 250W pedal-assist specifications are compressing procurement budgets for corporate fleet departments, forcing suppliers to unbundle installation services and absorb controller semiconductor cost volatility into hardware margins.
Pricing Analysis
Warranty and technical support bundling separates authorized distributor channels from direct-to-consumer marketplaces, with professional installation networks commanding premium positioning through KBA-certified labor credentials. Price differentiation hinges on CE marking tier and torque-sensor calibration complexity, with mid-drive systems carrying higher service attachments than hub motor alternatives. Cost compression in the DIY tier intensifies as Amazon marketplace bundling bypasses traditional distributor markups. Fleet operators show lowest price sensitivity due to total cost of ownership framing, while weekend conversion consumers exhibit highest elasticity to battery-motor bundle discounts.
Supply Chain Analysis
Reverse-logistics flows for battery pack refurbishment and controller remanufacturing are emerging as margin recovery channels for warranty returns and trade-in programs. Manufacturing concentration centers on China for brushless motor assembly, South Korea for lithium-ion cell production, and Germany for mid-drive system integration. The supply chain draws from rare earth magnet suppliers, Taiwanese semiconductor foundries, and domestic cell assembly partners. Single-source vulnerability in controller chip sourcing creates procurement risk. Distribution runs through European distributor networks for fleet contracts and Amazon marketplace for North American retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electric bike kit market is becoming a vertical-integration race where captive battery cell supply and in-house controller design determine margin sustainability against import certification cost inflation.
For Market Incumbents: Anticipate REACH documentation burdens and EU Battery Passport rules by qualifying domestic cell assembly partnerships before compliance deadlines compress sourcing flexibility. Defend distributor relationships through same-day installation capability in Amsterdam-Copenhagen corridor contracts. Prioritize backward integration into controller semiconductor sourcing to offset Taiwanese foundry capacity constraints. For New Entrants and Emerging Players: EU F-Gas Regulation in Germany opens a window for thermal management specialists to capture mid-drive premium positioning through certified enclosure ratings. Target US direct-to-consumer channels where labor costs exceed hardware prices and YouTube-educated consumers reduce service network dependency. Lead with battery-motor bundle simplicity rather than torque-sensing complexity. For Investors and Strategic Acquirers: The window for entry favors engineering-intensive mid-drive specialists with established German OEM partnerships over volume hub motor fabricators. Long-term viability rests on cell traceability systems aligned with EU supply chain documentation rules. Monitor EU Battery Passport implementation timelines as inflection indicator for procurement contract restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Cell Assembly | Domestic cell partnerships shorten EU Battery Passport compliance timelines for German mid-drive suppliers. |
| Controller Semiconductor Sourcing Diversification | Multi-foundry procurement reduces 12-16 week lead time exposure from Taiwanese capacity constraints. |
| Fleet Telematics Platform Integration | Regenerative braking data capture extends daily range for Lisbon and San Francisco courier operators. |
| Direct-to-Consumer Channel Expansion | Amazon marketplace bundling bypasses distributor markups in North American price-sensitive segments. |
| KBA Certification Investment | German labor credential standards elevate authorized service network barriers against DIY competitors. |
Methodological Framework
Independent corroboration across kit manufacturer executives, European fleet procurement managers, and North American online retail channel operators underwrites the qualitative findings. Primary interviews with mid-drive engineering specialists, battery pack integrators, and distributor network heads combined with secondary validation from EU regulatory filings, ECHA REACH documentation databases, and FCC equipment authorization records. Bottom-up unit shipment estimates triangulate against top-down market value reconstruction across hub motor, mid-drive, and conversion kit product architectures.
Rate-of-change decomposition separates volume growth from average selling price evolution across the projection horizon. Segmentation dimensions modeled include product architecture, end-user application, power rating tier, and installation modality. CAGRs derive from regression analysis against lithium-ion energy density improvement curves and EU urban mobility directive implementation schedules. Industry-specific forecast inputs incorporate brushless motor export certification cost trajectories and bicycle commuter subsidy program enrollment data.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery chemistry would alter the outlook through thermal management system redesign requirements. Forecasts reflect documented assumptions about EU Battery Passport implementation timing and Taiwanese semiconductor foundry capacity expansion. Practitioners should monitor ECHA material disclosure enforcement intensity and FCC wireless module certification backlogs for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
North America E-Bike Market
Electric Vehicles
India Electric Rickshaw Market
Electric Vehicles
Pedelec Market
Electric Vehicles
Global Smart Electric Drive Market
Electric Vehicles
Vietnam E-Bike Market
Electric Vehicles
Norway Electric Vehicle Market
Electric Vehicles
Busbar for EV Market
Electric Vehicles
Europe Automotive Battery Thermal Management System Market
Electric Vehicles
Asia-Pacific Electric Vehicle Market
Electric Vehicles
Asia-Pacific Solar E-Bike Market
Electric Vehicles
India Electric Vehicle Market
Electric Vehicles
Two-Wheeled Electric Vehicle Battery Market
Electric Vehicles
Compact E-Scooter Market
Electric Vehicles
Europe Electric Bus Market
Electric Vehicles
UK Electric Bus Battery Pack Market
Electric Vehicles
Global Electric Vehicles Market