
 Europe Electric Vehicle Power Inverter Market | 2026-2036
Europe Electric Vehicle Power Inverter Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Electric Vehicle Power Inverter Market Analytics
CE marking under the EU's Machinery Directive is collapsing the supplier base for third-party inverter manufacturers seeking direct OEM integration. Continental AG leverages its vertically integrated power electronics division to sustain long-term supply agreements with German premium automakers. Robert Bosch GmbH anchors its position through captive semiconductor packaging capabilities in Reutlingen. Valeo SA competes aggressively on thermal management integration, bundling inverters with heat pump systems for French OEM platforms.
Europe Electric Vehicle Power Inverter converts direct current from traction batteries into alternating current for electric motors, typically handling voltage ranges from 400V to 800V with switching frequencies above 10 kHz to minimize torque ripple and copper losses. Silicon Carbide technology leads on efficiency metrics but Insulated Gate Bipolar Transistor architectures still dominate mid-volume passenger vehicle lines due to established foundry capacity and lower wafer costs. Bidirectional Inverters represent the fastest-growing product category as vehicle-to-grid protocols gain regulatory traction across Nordic utilities and German transmission operators. Automotive OEMs capture the deepest margin pools through captive inverter design, while Aftermarket Providers struggle with firmware-locking practices that restrict component-level replacement.
EMA's extended scope under the EU AI Act and REACH substance restrictions are forcing material substitutions in solder alloys and encapsulant chemistries, extending qualification timelines by multiple development cycles. The F-Gas Regulation directly impacts thermal interface materials used in inverter cooling systems, restricting fluorinated gas content in manufacturing processes. Battery Manufacturers must monitor how ECHA's candidate list expansions affect epoxy potting compounds and ceramic substrate binders. Stakeholders should track whether the EU Green Deal's embedded carbon border adjustments will penalize imported silicon carbide substrates against European-sourced alternatives.
Market Dynamics
Silicon carbide substrate qualification timelines are compressing competitive windows across European inverter supply chains as OEMs race to meet 800V platform mandates before model-year 2028 redesign cycles lock.
Growth Catalysts
- EU Green Deal embedded carbon rules:German and French OEMs accelerate domestic sourcing of silicon carbide wafers to avoid border adjustment penalties on imported substrates.
- Fleet electrification corridors:Urban logistics operators in the Netherlands and Denmark concentrate bidirectional inverter procurement for vehicle-to-grid integration with Nordic transmission utilities.
- Traction battery voltage escalation:800V architectures spread from premium segments into mid-volume passenger lines, expanding addressable market for high-frequency switching designs.
Market Restraints
- Silicon carbide wafer cost volatility:European foundry capacity for 150mm SiC substrates remains concentrated among a single German materials supplier, amplifying input price exposure.
- F-Gas Regulation thermal interface constraints:Fluorinated gas restrictions complicate manufacturing of high-performance cooling compounds for inverter heat dissipation systems.
- CE marking Machinery Directive friction:Third-party inverter manufacturers face collapsing paths to direct OEM integration as certification scope expands under EU harmonized standards.
Strategic Opportunities
- Polish and Czech manufacturing zones:Central European automotive clusters attract inverter assembly investment to serve Volkswagen Group and Stellantis platform production.
- Heat pump-inverter bundling:French OEM platforms create integrated thermal-electronic procurement packages that favor suppliers with captive climate system expertise.
- CSRD supply chain disclosure mandates:Sustainability reporting requirements favor inverter vendors with traceable rare earth sourcing and renewable-powered foundry operations.
Industry Challenges
- Power electronics packaging talent scarcity:German semiconductor clusters compete for finite pools of SiC module design engineers against battery and charging infrastructure sectors.
- REACH substance substitution cycles:ECHA candidate list expansions for epoxy potting compounds force reformulation of encapsulant chemistries, extending qualification timelines across multiple development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Electric Vehicle Power Inverter Market |
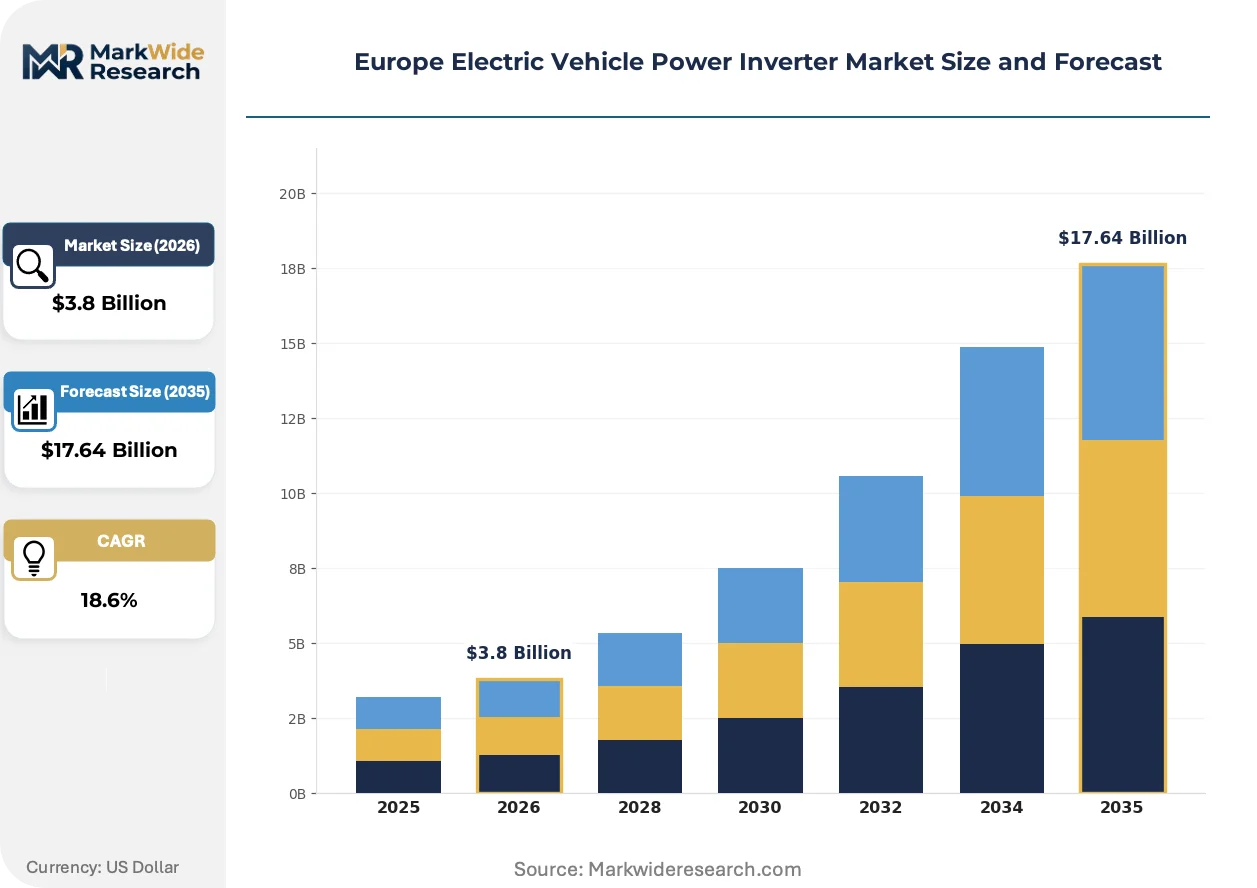
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Onboard Inverters, Bidirectional Inverters, DC-DC Converters, AC-DC Converters Application: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Vehicles, Two-Wheelers Technology: Silicon Carbide, Insulated Gate Bipolar Transistor, Metal-Oxide-Semiconductor Field-Effect Transistor, Analog ICs End User: Automotive OEMs, Aftermarket Providers, Fleet Operators, Battery Manufacturers |
| Companies Covered | Continental AG, Robert Bosch GmbH, Valeo SA, Denso Corporation, Mitsubishi Electric Corporation, Aptiv PLC, Vitesco Technologies, Siemens AG, Marelli, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Electric Vehicle Power Inverter Market Evolving Landscape
Power semiconductor architecture decisions are locking in competitive position five years ahead of vehicle launch as platform voltage standards harden across European OEM roadmaps.
Silicon carbide MOSFETs convert DC battery current to AC motor drive with switching losses below 30% of equivalent IGBT designs. German premium automakers embed SiC inverters as standard across 800V platforms launching 2026-2028. This technology is displacing IGBT architectures in passenger vehicle lines above 400V, compressing margin pools for suppliers without captive SiC packaging capability.
F-Gas Regulation amendments tighten fluorinated greenhouse gas restrictions in manufacturing processes and product content. Thermal interface material suppliers reformulate phase-change compounds and gap fillers to eliminate perfluorinated substances. Inverter cooling system designers in France and Sweden accelerate testing of graphite-based alternatives ahead of 2027 enforcement thresholds.
Fleet operators in Denmark and the Netherlands consolidate procurement authority for vehicle-to-grid capable inverters through energy service company intermediaries. Traditional tiered sales through automotive OEM channels fragment as transmission utilities and municipal fleet managers negotiate direct volume agreements with inverter vendors. This channel rotation concentrates in Nordic markets where regulatory frameworks for grid-stabilizing vehicle exports mature fastest.
Europe Electric Vehicle Power Inverter Market Segmentation
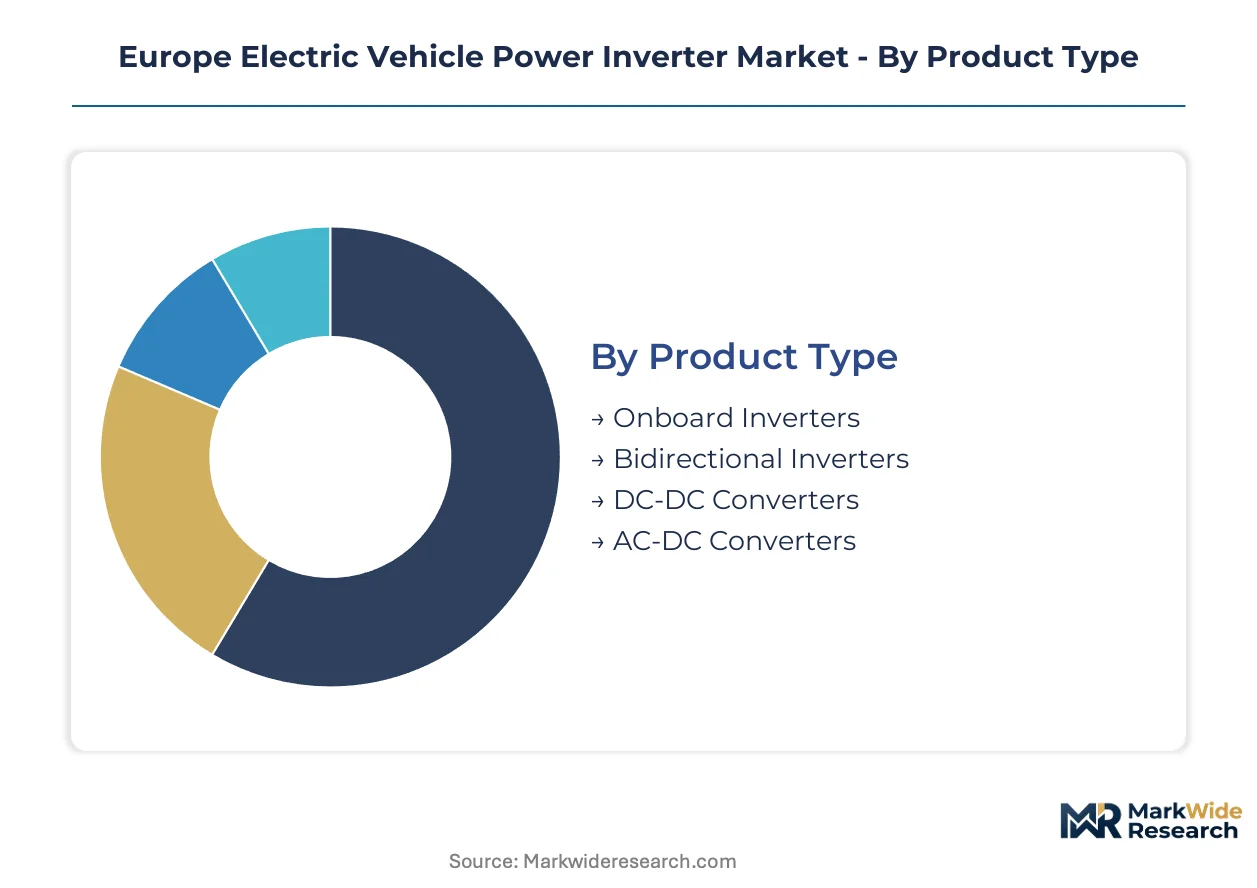
Power inverter segmentation in Europe reflects divergent technology maturities and regulatory pressure points across electrification value chains. Voltage platform decisions and bidirectional charging mandates are fragmenting procurement patterns faster than supplier portfolios can adapt.
Product Type:
Substitution pressure from integrated power electronics modules is squeezing standalone DC-DC and AC-DC converter margins as OEMs consolidate toward multi-functional architectures.
- Onboard Inverters:These units convert DC battery output to variable-frequency AC for traction motors, handling continuous loads above 150 kW in premium passenger configurations. German and French OEMs concentrate procurement for 800V platform launches, prioritizing suppliers with captive silicon carbide packaging capability to meet EU Green Deal embedded carbon thresholds.
- Bidirectional Inverters:Enabling vehicle-to-grid and vehicle-to-load power flow, these designs incorporate dual-active bridge topologies with isolation transformers rated for utility synchronization. Nordic fleet operators in Denmark and the Netherlands are consolidating procurement through energy service intermediaries as transmission utilities mature grid-stabilizing export frameworks.
- DC-DC Converters:Step-down units supply 12V and 48V auxiliary systems from high-voltage traction batteries.
- AC-DC Converters:Onboard charging modules integrate with inverter thermal management systems in consolidated power electronics enclosures.
Onboard Inverters retain volume leadership; Bidirectional Inverters hold the steepest expansion curve.
Application:
Cost tier stratification separates premium 800V architectures from 400V mass-market platforms across passenger and commercial vehicle lines.
- Passenger Vehicles:European OEMs split procurement between 400V IGBT-based designs for mid-volume lines and 800V silicon carbide architectures for premium segments. German automakers lock supplier selections ahead of model-year redesign cycles, compressing qualification windows for third-party inverter manufacturers.
- Commercial Vehicles:Urban logistics operators prioritize bidirectional capability for depot-based vehicle-to-grid integration with municipal energy managers. Dutch and Danish fleet electrification corridors concentrate demand among transmission utility partners seeking distributed grid stabilization assets.
- Heavy-Duty Vehicles:Long-haul trucking electrification in Germany and France drives demand for liquid-cooled inverters above 300 kW continuous rating.
- Two-Wheelers:Cost-sensitive designs favor IGBT and MOSFET architectures with passive air cooling for urban mobility platforms.
Passenger Vehicles dominate revenue contribution; Commercial Vehicles are climbing the fastest as fleet electrification corridors mature.
Technology:
Supply concentration in European silicon carbide foundry capacity is amplifying input cost volatility and extending qualification timelines for switching device architectures.
- Silicon Carbide:Wide-bandgap MOSFETs achieve switching losses below 30% of equivalent IGBT designs at frequencies above 50 kHz, enabling compact thermal packaging for 800V platforms. A single German materials supplier controls European 150mm substrate output, exposing OEMs to border adjustment penalties under EU Green Deal carbon rules.
- Insulated Gate Bipolar Transistor:Mature trench-field-stop designs leverage established 300mm silicon foundry capacity across European semiconductor clusters. Mid-volume passenger vehicle lines below 400V system voltage retain IGBT architectures due to lower wafer costs and qualified second-source supply chains.
- Metal-Oxide-Semiconductor Field-Effect Transistor:Super-junction silicon designs serve auxiliary power conversion and low-voltage traction applications.
- Analog ICs:Gate drivers and protection circuits integrate with digital control cores in modular power stage designs.
IGBT retains volume leadership; Silicon Carbide commands the steepest expansion trajectory as 800V platforms proliferate.
End User:
Customer type determines margin capture depth, with captive OEM design locking aftermarket providers out of firmware-accessible replacement markets.
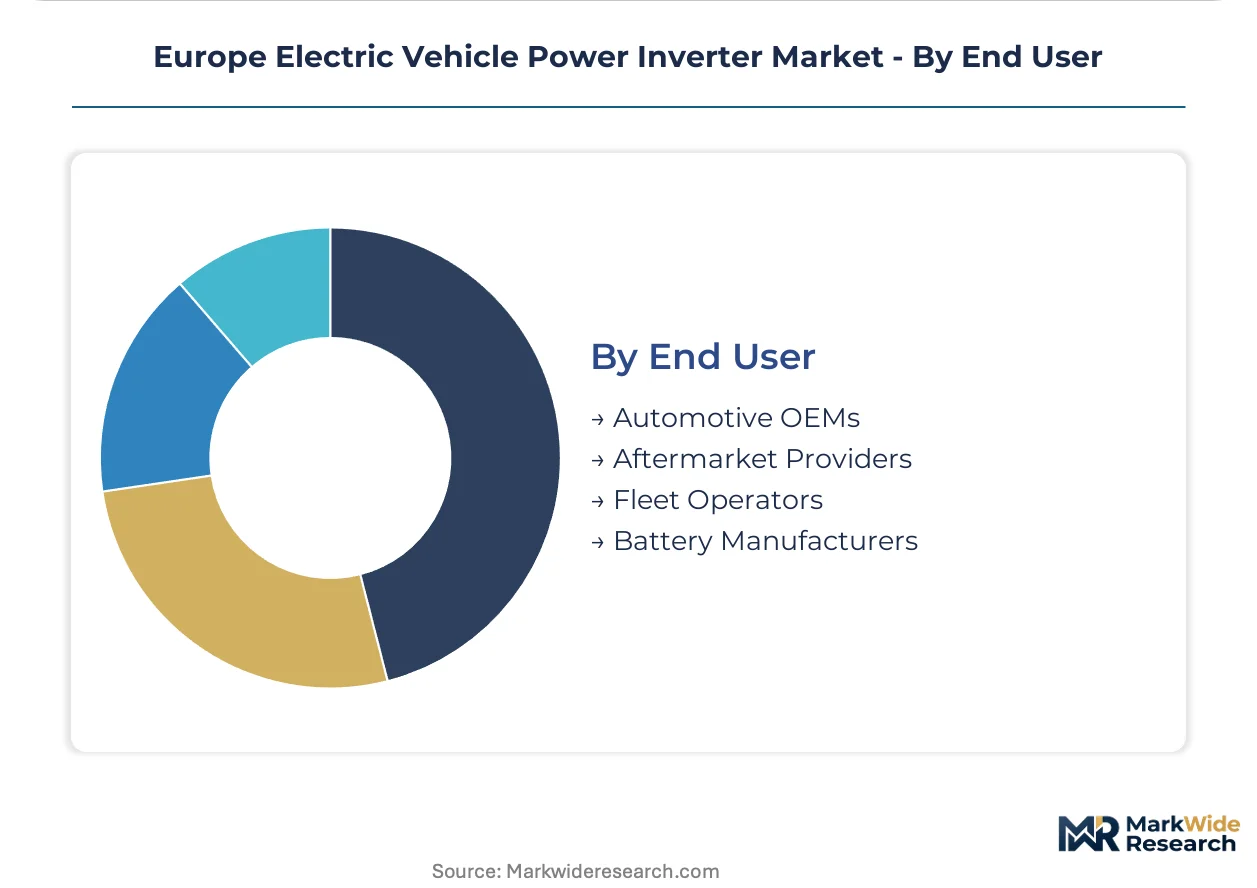
- Automotive OEMs:German premium automakers and French mass-market producers internalize inverter design for platform differentiation, outsourcing only power module packaging and thermal assembly. CE marking under the EU Machinery Directive is collapsing direct integration paths for third-party manufacturers lacking harmonized certification scope.
- Fleet Operators:Energy-integrated procurement through Danish and Dutch transmission utility partnerships is bypassing traditional tiered automotive sales channels. Municipal logistics managers negotiate direct volume agreements for vehicle-to-grid capable inverters, fragmenting established supplier-OEM relationships.
- Aftermarket Providers:Firmware-locking practices restrict component-level replacement, limiting addressable scope to thermal interface materials and connector assemblies.
- Battery Manufacturers:Cell producers monitor ECHA candidate list expansions for epoxy potting compounds affecting module-level integration.
Automotive OEMs retain volume leadership; Fleet Operators hold the steepest expansion curve as energy service intermediaries consolidate procurement authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal and national fleet electrification targets are concentrating inverter demand across automotive manufacturing clusters, with each major economy developing distinct procurement patterns tied to local OEM platforms and utility partnerships.
Germany
Premium automakers in Bavaria and Baden-Württemberg are locking supplier selections for 800V platform launches ahead of model-year 2028 redesign cycles. The KBA enforces type-approval standards that compress qualification windows for third-party inverter manufacturers. Stuttgart and Ingolstadt host captive power electronics divisions serving Volkswagen Group and BMW platform production.
France
Mass-market OEMs in Île-de-France prioritize thermal management integration, bundling inverters with heat pump systems for platform differentiation. The F-Gas Regulation drives reformulation of phase-change compounds in thermal interface materials. Auvergne-Rhône-Alpes clusters concentrate testing of graphite-based cooling alternatives ahead of enforcement thresholds.
Netherlands
Urban logistics operators in the Randstad corridor consolidate bidirectional inverter procurement through energy service intermediaries. Transmission utilities mature grid-stabilizing vehicle export frameworks faster than neighboring markets. Eindhoven Region attracts assembly investment to serve Stellantis platform production with proximity to North Sea port infrastructure.
Denmark
Municipal fleet managers negotiate direct volume agreements for vehicle-to-grid capable inverters, bypassing traditional tiered automotive sales channels. Nordic transmission operators prioritize distributed grid stabilization assets in Copenhagen and Aarhus electrification corridors. The country's integrated energy-automotive procurement model fragments established supplier-OEM relationships.
Poland
Central European automotive clusters near Warsaw and Kraków attract inverter assembly investment to serve Volkswagen Group production with lower embedded carbon profiles than Asian imports. CSRD supply chain disclosure mandates favor vendors with traceable rare earth sourcing. Silesian manufacturing zones develop packaging capabilities for silicon carbide modules.
Europe Electric Vehicle Power Inverter Market Competitive Landscape
Listed leaders compete with private specialists across certification scope and captive semiconductor packaging capability. The supplier base concentrates around vertically integrated power electronics divisions and tier-one automotive component groups with harmonized CE marking under the EU Machinery Directive. Three archetypes dominate: German premium-tier captive designers, French thermal-integration bundlers, and Japanese scale-driven module suppliers. Competitive moves center on backward integration into silicon carbide substrate supply and strategic partnerships with Nordic energy service intermediaries.
Within the German captive-design tier, Continental AG and Robert Bosch GmbH exemplify archetypes of vertically integrated power electronics divisions sustaining long-term supply agreements through in-house semiconductor packaging. Valeo SA occupies a position among French thermal-integration specialists competing on bundled climate-electronic procurement packages. These three anchors illustrate how regional industrial specialization—German premium automotive, French mass-market OEM platforms, and cross-border thermal management expertise—shapes competitive positioning under tightening EU efficiency mandates.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| Valeo SA |
| Denso Corporation |
| Mitsubishi Electric Corporation |
| Aptiv PLC |
| Vitesco Technologies |
| Siemens AG |
| Marelli |
| Others |
Value Network & Pricing Analysis
Twenty-six-week lead times for 150mm silicon carbide substrates from the single German materials supplier concentrate pricing power among captive OEM designers while compressing margin pools for third-party manufacturers lacking backward integration into wafer supply.
Pricing Analysis
CE marking tier under the EU Machinery Directive creates the primary spread between integrated OEM supply agreements and aftermarket component sales. Three-tier pricing structure across premium 800V silicon carbide architectures, mid-volume 400V IGBT designs, and economy auxiliary converters reflects certification investment and captive packaging capability. Pricing pressure stems from wafer cost volatility as European foundry capacity fails to match demand escalation from platform voltage mandates. Fleet operators negotiating through Nordic energy service intermediaries exhibit highest price sensitivity; German premium automakers with captive design teams show lowest sensitivity due to platform differentiation requirements.
Supply Chain Analysis
Inventory compression to sub-four-week safety stocks across German and French OEM production lines amplifies exposure to substrate supply interruptions. Manufacturing concentrates in Germany, France, and emerging Polish assembly zones serving Volkswagen Group and Stellantis platforms. Raw material dependencies center on silicon carbide wafers, rare earth magnetic materials for isolation transformers, and reformulated thermal interface compounds eliminating fluorinated substances. Single-source vulnerability in European 150mm SiC substrate output represents the dominant structural risk. Distribution runs through long-term supply agreements with automotive OEMs, bypassing traditional tiered component channels as energy-integrated procurement fragments established relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's electric vehicle power inverter market sits in early-cycle expansion as 800V platform mandates accelerate replacement of IGBT architectures with silicon carbide designs across German and French OEM roadmaps.
For Market Incumbents: Secure captive silicon carbide packaging capability through acquisition of German substrate suppliers or exclusive offtake agreements before model-year platform locks freeze supplier selections. Invest in CE marking scope expansion under harmonized EU Machinery Directive standards to collapse integration paths for emerging competitors. Address power electronics packaging talent scarcity through targeted recruitment from battery and charging infrastructure sectors in Stuttgart and Dresden semiconductor clusters. For New Entrants and Emerging Players: Lead with bidirectional inverter designs targeting Nordic fleet electrification corridors in Denmark and the Netherlands, where energy service intermediaries consolidate procurement authority outside traditional OEM channels. Exploit thermal management integration opportunities in French mass-market platforms bundling heat pump and inverter procurement. Pursue direct utility partnerships as the primary go-to-market angle, bypassing CE-marked automotive certification requirements through grid-stabilizing equipment pathways. For Investors and Strategic Acquirers: Long-term, this sits as a materials-capture play because silicon carbide substrate supply concentration determines competitive position across the projection horizon. Target acquisition candidates with traceable rare earth sourcing and renewable-powered foundry operations positioned for CSRD supply chain disclosure mandates. Watch for inflection in Polish and Czech manufacturing zone development as indicators of assembly capacity migration toward lower embedded carbon profiles.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Substrate Backward Integration | German OEMs secure wafer supply against EU Green Deal carbon border penalties on imported substrates. |
| Bidirectional Charging Certification Investment | Nordic utilities prioritize grid-synchronization capabilities in vehicle-to-grid procurement specifications. |
| Thermal Management Bundling Partnership | French OEM platforms integrate heat pump and inverter sourcing for climate-electronic differentiation. |
| Central European Manufacturing Footprint | Polish and Czech zones serve Stellantis and Volkswagen production with reduced carbon intensity. |
| REACH-Compliant Material Reformulation | ECHA candidate list expansions force encapsulant chemistry substitutions extending qualification cycles. |
Research Methodology
A standing panel of OEM platform engineers, Tier 1 supplier procurement directors, Nordic transmission utility planning officers, and power semiconductor packaging specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from KBA type-approval filings, EU Green Deal regulatory impact assessments, ECHA substance restriction updates, and IHS Markit vehicle production databases. Bottom-up segment sizing triangulated against top-down OEM platform rollout schedules across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across voltage platform tiers, switching device architectures, and end-user procurement channels. The analytical framework modeled vehicle class, propulsion voltage, technology generation, and regional production cluster dimensions throughout the forecast period. CAGRs derived from platform-specific adoption curves weighted by OEM production commitments and utility partnership maturation timelines incorporated silicon carbide cost-down trajectories and F-Gas Regulation compliance costs as industry-specific inputs.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement, stable silicon carbide substrate supply expansion, or accelerated Nordic vehicle-to-grid regulatory frameworks would require recalibration. Forecasts reflect documented assumptions regarding OEM platform voltage decisions and REACH substance substitution timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Africa Electric Vehicle Market
Electric Vehicles
Electric Car Rental Market
Electric Vehicles
Mexico Automotive Electric Bus Market
Electric Vehicles
Singapore Electric Vehicle Market
Electric Vehicles
Middle East Wireless EV Charging Market
Electric Vehicles
Fuel Cell Electric Vehicle (FCEV) Market
Electric Vehicles
Electric Vehicle Control Unit Market
Electric Vehicles
France Electric Bus Battery Pack Market
Electric Vehicles
India Electric Vehicle Financing Market
Electric Vehicles
Hybrid E-Scooter Market
Electric Vehicles
Asia Pacific Electric Scooter Market
Electric Vehicles
Automotive Battery Pack Pressure Equalization Membrane Market
Electric Vehicles
North America Electric Bus Market
Electric Vehicles
Worldwide EV Range Extender Market
Electric Vehicles
Global Automotive Lithium Ion Battery Controller Market
Electric Vehicles
Central and Eastern Europe E-Bike Market