
 Bike Wheels Market | 2026-2036
Bike Wheels Market Size, Share, and Industry Trends Forecast 2026-2036
Bike Wheels Market Insights
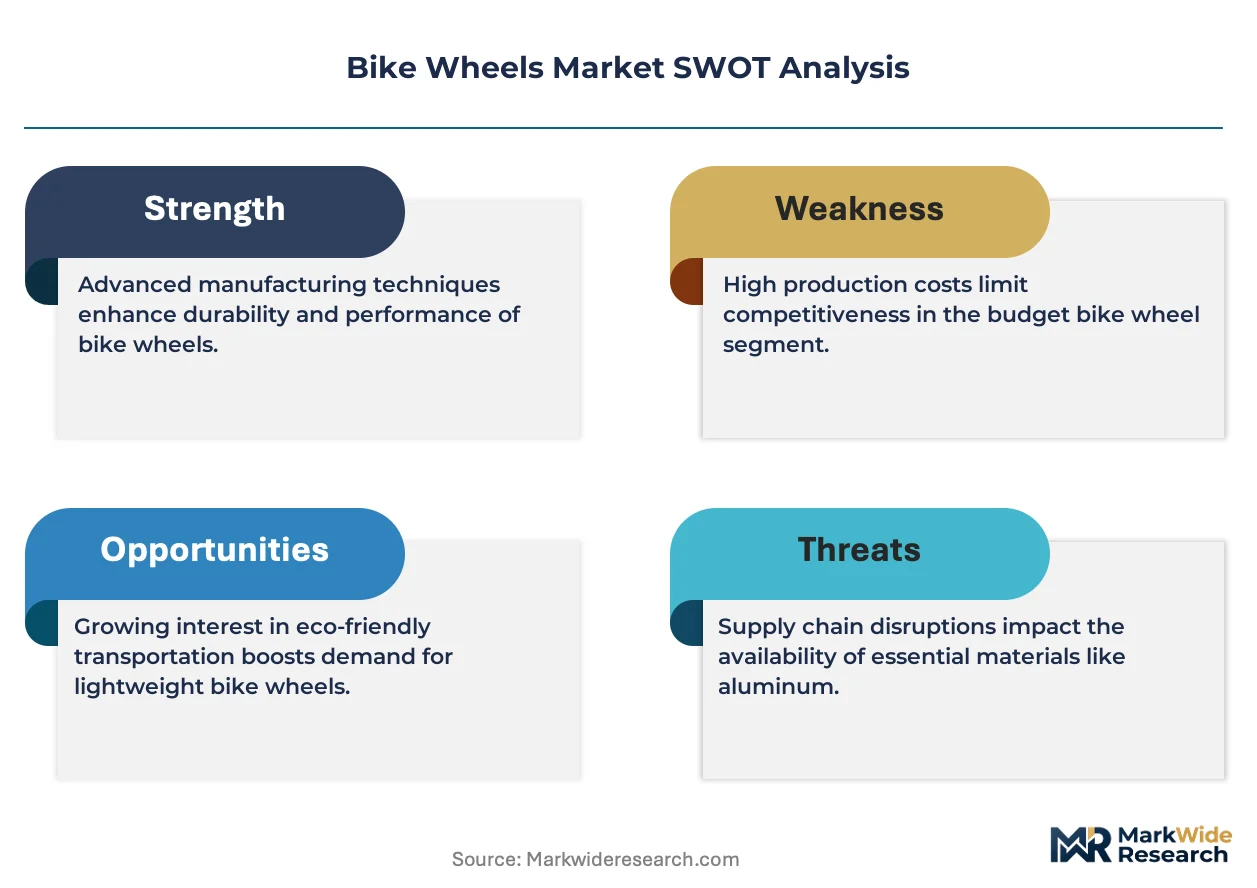
ISO 4210 safety certification is bifurcating the competitive landscape into qualified suppliers and marginal producers. DT Swiss leverages its Swiss engineering heritage to dominate premium carbon fiber road wheelsets. Shimano anchors the mass-market tier through backward integration into hub and rim manufacturing. Hunt Bike Wheels competes aggressively on direct-to-consumer pricing while sustaining rapid product refresh cycles.
Bike wheels are rotating structures comprising rims, hubs, spokes, and nipples, typically ranging from 20 to 29 inches in diameter, designed to support rider weight while minimizing rotational inertia for efficient power transfer. Carbon fiber layup processes now enable rim weights below 400 grams while maintaining impact resistance thresholds specified by UCI racing regulations. Spoked wheels retain the largest volume share across road cycling and mountain biking applications, though tubeless wheels are capturing margin pools as sealant-based puncture resistance becomes standard in performance segments. Carbon fiber material commands premium positioning in professional cyclist and bicycle manufacturer channels, while aluminum alloy sustains volume leadership in commuting and leisure rider segments where cost sensitivity dominates.
REACH restricts hazardous substances in European wheel coatings and adhesives, compelling reformulation of rim bed compounds and spoke nipple finishes. The EU Green Deal extends producer responsibility to end-of-life carbon fiber recovery, reshaping material economics for ENVE and Reynolds Cycling. ISO standards govern fatigue testing protocols that gate market access across multiple jurisdictions. Stakeholders must monitor evolving circular economy mandates that will determine which material technologies and recovery infrastructure investments yield sustainable cost positions.
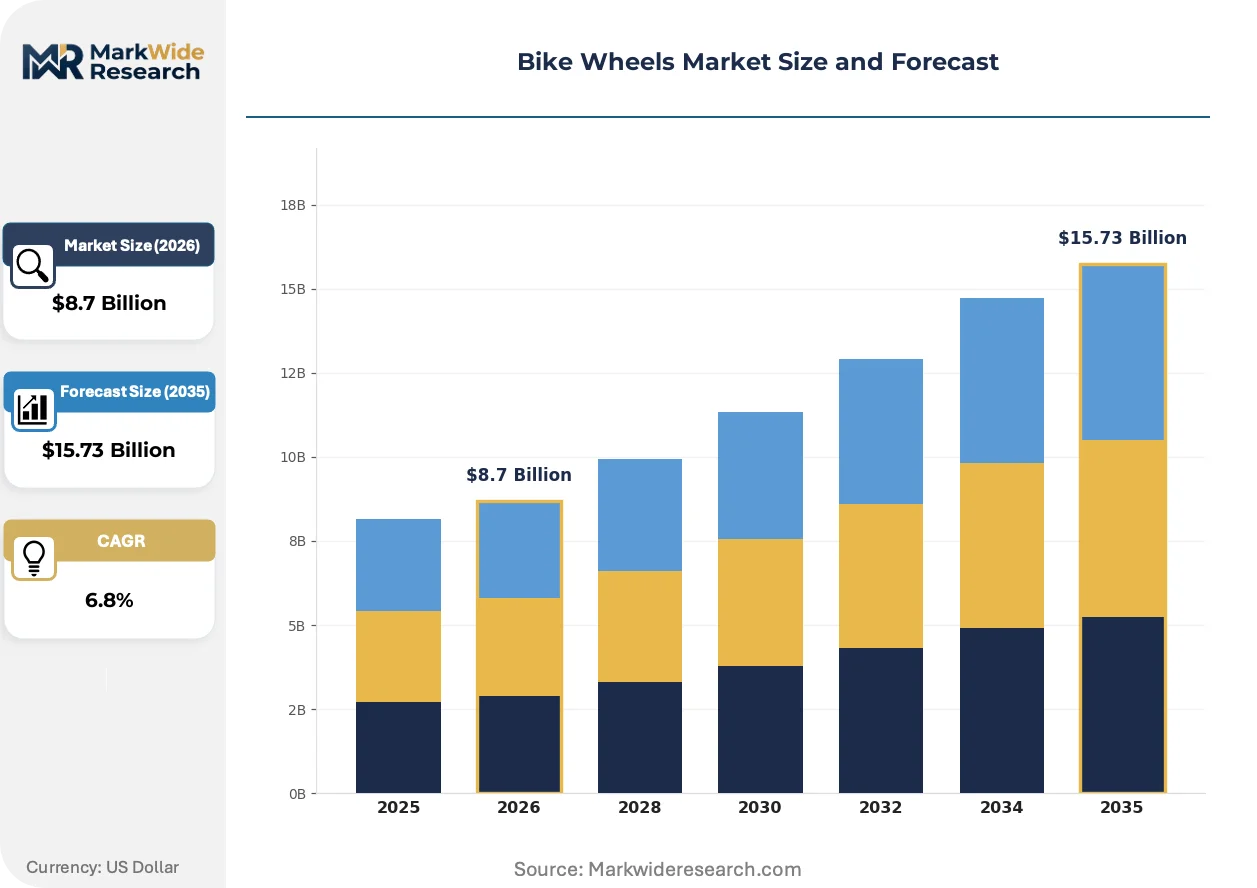
Market Dynamics
Tubeless wheel technology is compressing replacement cycles while carbon fiber layup advances are fragmenting price tiers across professional and amateur cyclist segments.
Growth Catalysts
- REACH compliance mandates:European ECHA regulations on hazardous substance restrictions are accelerating reformulation of rim bed compounds and spoke nipple finishes, pushing manufacturers toward certified supply chains.
- Carbon fiber rim layup:Automated tape placement and resin transfer molding are reducing unit costs for sub-400-gram rims, expanding addressable demand in performance road cycling.
- China production scaling:Domestic OEM suppliers in Zhejiang and Guangdong provinces are capturing export volume through backward integration into hub and rim manufacturing.
Market Restraints
- Carbon fiber feedstock concentration:Toray Industries and Mitsubishi Chemical dominate aerospace-grade precursor supply, creating input cost volatility for wheel manufacturers.
- EU Green Deal end-of-life liability:Extended producer responsibility mandates for carbon fiber recovery are imposing capital requirements without established recycling infrastructure.
- Aluminum alloy substitution:Commuter and leisure segments retain cost-sensitive demand that carbon fiber cannot satisfy at current price points.
Strategic Opportunities
- India cycling infrastructure:Smart Cities Mission investments in urban mobility are creating fleet procurement channels for delivery services and bike-share operators.
- Direct-to-consumer channel expansion:Digital-native brands are bypassing traditional distributor margins through owned e-commerce and subscription-based wheel refresh programs.
- ISO 4210 certification arbitrage:Safety testing standardization is creating tiered supplier qualification systems that favor early compliance investments.
Industry Challenges
- Composite technician scarcity:Carbon fiber layup and NDT inspection skills are concentrated in aerospace and automotive sectors, constraining wheel manufacturing scale-up.
- Hub motor integration complexity:E-bike drivetrain electrification is forcing spoke tension and flange geometry redesigns that conflict with legacy rim architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bike Wheels Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spoked Wheels, Solid Wheels, Tubeless Wheels, Clinker Wheels Material: Aluminum Alloy, Carbon Fiber, Steel, Magnesium Alloy Application: Road Cycling, Mountain Biking, Touring, Commuting, BMX Riding End User: Professional Cyclists, Leisure Riders, Delivery Services, Bicycle Manufacturers |
| Companies Covered | Shimano, DT Swiss, Mavic, Zipp, ENVE, Fulcrum Wheels, Campagnolo, Reynolds Cycling, Hunt Bike Wheels, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bike Wheels Market Trends and Innovations
Wheel system architectures are converging around aerodynamic optimization algorithms and real-world validation protocols that bypass traditional wind tunnel dependencies.
Hookless bead rim profiles are miniaturizing tire-rim interface tolerances while maintaining burst pressure safety margins. Professional cycling teams and gran fondo participants are specifying these configurations for tubeless setups above 100 PSI. The technology is miniaturizing the performance gap between mid-tier and premium wheelsets, compressing brand premium extraction.
EU Green Deal circular economy mandates are forcing carbon fiber recovery infrastructure investments ahead of commercial viability. Manufacturers must now account for end-of-life material flows in product cost structures. ENVE and Reynolds Cycling are most exposed given their European assembly operations and premium positioning.
Delivery fleet operators are consolidating procurement through long-term service contracts that bundle wheel replacement, maintenance, and uptime guarantees. Traditional component distributors are losing volume to integrated mobility service providers. This pattern is most visible in China where Meituan and Ele.me specify wheel durability standards directly with OEM suppliers.
Bike Wheels Market Segmentation
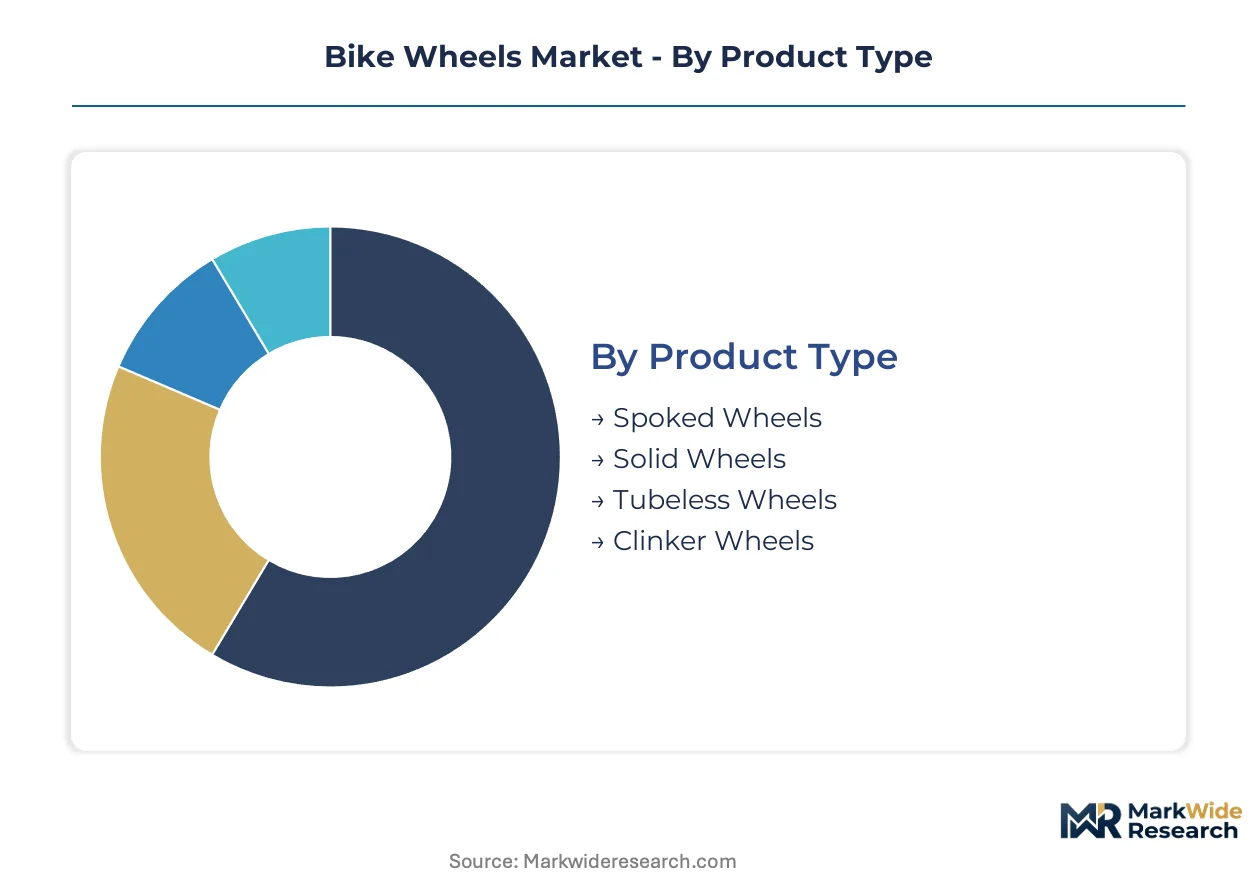
Bike wheel segmentation reveals how margin pools concentrate around material technology and application performance tiers. Manufacturers calibrate product architectures to capture value across professional racing, fleet logistics, and mass leisure channels.
Product Type:
Tubeless and carbon-integrated configurations command the widest margin spreads as sealant-based reliability becomes non-negotiable in performance segments.
- Spoked Wheels:Traditional tensioned-spoke architectures with 16 to 36 spoke counts dominate volume across road cycling and mountain biking. Demand concentrates in China and Southeast Asia where OEM suppliers scale aluminum rim production for export markets constrained by ISO 4210 fatigue testing protocols.
- Tubeless Wheels:Hookless bead profiles with sub-millimeter tire-rim tolerances eliminate inner tubes while maintaining burst pressure margins above 100 PSI. Professional cyclists and gran fondo participants in Europe specify these configurations, compressing replacement cycles as sealant refresh becomes routine maintenance.
- Solid Wheels:Molded disc constructions without spoke penetrations serve BMX and urban bike-share applications where vandalism resistance outweighs weight penalties.
- Clinker Wheels:Vintage-style wired-on rim profiles retain niche demand in European restoration and collector markets.
The dominant share belongs to Spoked Wheels, while Tubeless Wheels is closing the gap fastest.
Material:
Cost tier stratification separates aerospace-grade carbon fiber from commodity aluminum alloy, with intermediate metals capturing mid-market positioning.
- Carbon Fiber:Automated tape placement and resin transfer molding enable rim weights below 400 grams while satisfying UCI impact resistance thresholds. Professional cyclists and bicycle manufacturers in Switzerland and Italy absorb premium pricing for layup precision and aerodynamic optimization.
- Aluminum Alloy:Extruded and welded 6061-T6 rims sustain volume leadership in commuting and leisure segments across India and Brazil where cost sensitivity dominates procurement decisions.
- Steel:Chromoly and stainless variants persist in cargo bikes and heavy-duty touring applications requiring spoke tension durability over weight minimization.
- Magnesium Alloy:Thixomolded rims offer density advantages for children's bicycles and entry-level mountain bikes in East Asian retail channels.
Aluminum Alloy retains the largest volume position, though Carbon Fiber is expanding most quickly among performance-tier suppliers.
Application:
Volume concentrates in utility cycling while margin extraction follows racing and technical terrain specialization.
- Road Cycling:Aerodynamic rim profiles with 40 to 65 millimeter depths target wattage savings at 40-plus kilometer-per-hour speeds. European gran fondo culture and Asian racing leagues drive specification of integrated tubeless systems with ceramic bearing hubs.
- Mountain Biking:Wide internal rim widths from 30 to 40 millimeters accommodate plus-size tires for traction across rock gardens and root networks. North American trail networks and Alpine bike parks demand impact-resistant carbon layups with lifetime warranty protection.
- Touring:36-spoke tandem-rated wheels with mechanical disc compatibility serve long-distance loaded touring across European EuroVelo routes.
- Commuting:Dynamo hub integration and puncture-resistant tire compatibility dominate urban mobility specifications in Dutch and Danish municipal procurement.
- BMX Riding:20-inch reinforced rims with 48-spoke lacing patterns withstand freestyle impact loading in North American and Australian action sports retail.
Road Cycling holds the premium revenue concentration, yet Mountain Biking is gaining share fastest as trail infrastructure investment accelerates across multiple continents.
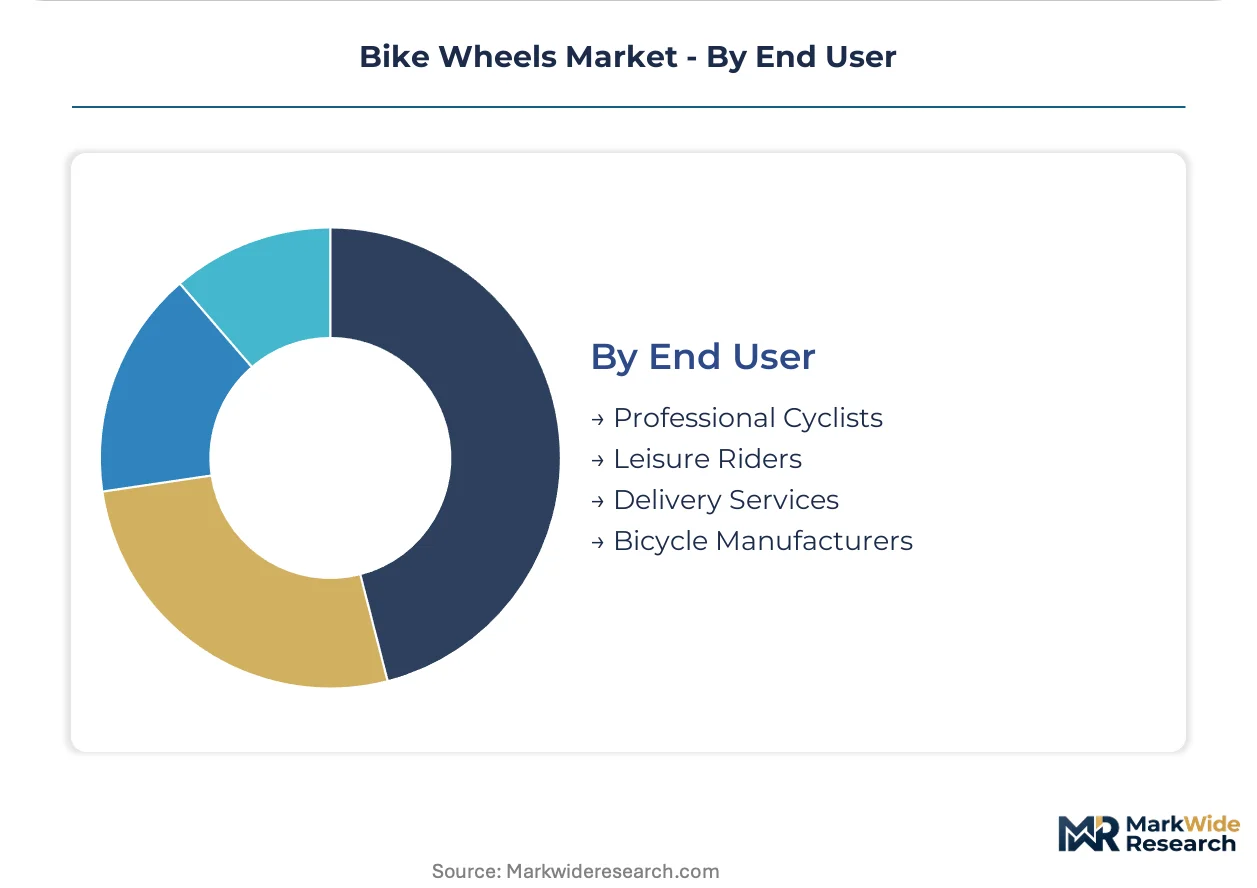
End User:
Procurement authority bifurcates between individual enthusiast decision-making and fleet operator consolidated purchasing.
- Professional Cyclists:UCI-registered teams and continental squads specify wheelsets through direct manufacturer relationships with season-long supply guarantees. Sponsorship contracts with DT Swiss and ENVE lock in equipment standardization across WorldTour and ProTeam rosters.
- Delivery Services:Meituan, Ele.me, and European last-mile logistics operators consolidate wheel procurement through integrated service contracts bundling replacement, maintenance, and uptime guarantees. Durability specifications now bypass traditional distributor channels for direct OEM engagement.
- Leisure Riders:Weekend enthusiasts and fitness cyclists purchase through direct-to-consumer digital channels with subscription-based refresh programs disrupting retail markup structures.
- Bicycle Manufacturers:OEM specification at frame assembly stage locks in hub and rim sourcing through backward-integrated supply relationships with Zhejiang and Guangdong producers.
Bicycle Manufacturers control the largest volume throughput, while Delivery Services is climbing the fastest as fleet electrification multiplies wheel replacement frequency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European REACH mandates and the EU Green Deal are accelerating carbon fiber recovery infrastructure investments, while Chinese OEM scaling and Indian urban mobility programs reshape procurement patterns across distinct national markets.
China
Domestic OEM suppliers in Zhejiang and Guangdong provinces are scaling hub and rim manufacturing for both domestic consumption and export markets. MIIT industrial policy supports dual carbon goals through energy-efficient production quotas. Hangzhou and Shenzhen clusters now host backward-integrated suppliers serving Meituan and Ele.me fleet specifications directly.
Germany
Gran fondo culture and UCI-registered team procurement anchor premium carbon fiber demand across road cycling segments. KBA vehicle safety standards influence e-bike wheel integration requirements for hub motor compatibility. Baden-Württemberg engineering clusters concentrate precision layup and ceramic bearing assembly operations.
United States
North American trail network expansion drives impact-resistant carbon layup specifications for mountain biking applications. EPA environmental compliance shapes coating and adhesive formulations for domestic assembly operations. Colorado and California technical terrain clusters host validation protocols for enduro and downhill wheel architectures.
India
Smart Cities Mission investments in urban mobility infrastructure are creating fleet procurement channels for delivery services and bike-share operators. BIS certification requirements for bicycle components are tightening quality gates for imported and domestic wheelsets. Maharashtra and Karnataka industrial corridors are attracting aluminum rim extrusion capacity for commuter segment supply.
Switzerland
Swiss engineering heritage commands premium positioning in professional cyclist channels through precision manufacturing reputations. Swissmedic medical device adjacent quality systems influence NDT inspection protocols for carbon fiber layup validation. Jura and Ticino manufacturing clusters maintain specialized technician pools for aerospace-grade composite transfer.
Bike Wheels Market Competitive Landscape
Player mix skews toward European heritage premium specialists and Asian OEM scale operators. Market structure bifurcates between certification-qualified suppliers and marginal producers unable to satisfy ISO 4210 fatigue testing protocols. Three archetypes dominate: Swiss-Italian engineering heritage brands, Chinese backward-integrated OEMs, and direct-to-consumer digital natives. Competitive moves concentrate on M&A for carbon fiber recovery capabilities and strategic partnerships with delivery fleet operators.
Within the heritage engineering tier, DT Swiss and Campagnolo exemplify precision manufacturing positioning anchored in European cycling tradition. Zipp occupies a position representing aerodynamic optimization specialization. Among Asian OEM fabricators, Shimano exemplifies mass-market tier dominance through captive hub and rim production. These three anchors illustrate how geographic origin and organizational structure map to distinct competitive archetypes without overlapping segment claims.
| Leading Market Players |
|---|
| Shimano |
| DT Swiss |
| Mavic |
| Zipp |
| ENVE |
| Fulcrum Wheels |
| Campagnolo |
| Reynolds Cycling |
| Hunt Bike Wheels |
| Others |
Pricing and Supply Chain Analysis
Carbon fiber substitution for aluminum alloy in performance road cycling simultaneously shifts production gravity toward Zhejiang and Guangdong provinces and compresses margin extraction at mid-tier price points as automated layup costs decline.
Pricing Analysis
Cost-plus contracts with Toray Industries precursor indexation dominate carbon fiber wheelset procurement between OEM suppliers and bicycle manufacturers. Pricing stratifies across UCI-certified premium tiers, ISO 4210-qualified standard tiers, and uncertified economy tiers based on fatigue testing compliance and layup precision. Cost compression in mid-tier carbon fiber runs through backward-integrated Chinese hub and rim manufacturers expanding automated tape placement capacity. Delivery services exhibit highest price sensitivity through consolidated fleet procurement, while professional cyclist sponsorship contracts absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Inbound logistics costs through Ningbo-Zhoushan port congestion and trans-Pacific container availability constraints shape inventory positioning for North American and European distributors. Manufacturing concentrates in China, Taiwan, and Switzerland, with aerospace-grade carbon fiber feedstock drawing from Toray Industries and Mitsubishi Chemical precursor supply. Single-source vulnerability sits with Japanese chemical conglomerates controlling PAN precursor quality grades. Distribution runs through direct-to-consumer digital channels, traditional bicycle distributors, and integrated mobility service providers bundling fleet maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through delivery fleet procurement consolidation in China and Europe, fragmenting traditional distributor influence as Meituan and Ele.me specify durability standards directly with OEM suppliers.
For Market Incumbents: Shield premium positioning by accelerating ISO 4210 certification investments ahead of regulatory enforcement waves, while deepening captive supply of carbon fiber layup capacity in Baden-Württemberg and Ticino clusters to offset aerospace technician scarcity threatening scale-up timelines.
For New Entrants and Emerging Players: Fleet uptime guarantee services represent the most penetrable white-space as incumbents under-serve delivery operators with transactional replacement models rather than integrated lifecycle contracts. Target Indian Smart Cities Mission procurement channels through aluminum rim extrusion partnerships in Maharashtra industrial corridors, leveraging BIS certification gaps among established suppliers.
For Investors and Strategic Acquirers: EU Green Deal extended producer responsibility mandates reshape the acquisition landscape toward carbon fiber recovery infrastructure capabilities ahead of commercial viability. Five-to-ten-year viability favors targets with established end-of-life material flow partnerships. Monitor ECHA enforcement patterns on REACH rim bed compound reformulation as the inflection signal for compliance-cost winner determination.
| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Fiber Recovery Infrastructure Investment | EU Green Deal liability mandates force end-of-life cost accounting for ENVE and Reynolds Cycling assembly operations. |
| Backward Integration into Hub Manufacturing | Zhejiang province OEM suppliers capture margin pools previously extracted by Japanese bearing specialists through captive precision machining. |
| Direct-to-Consumer Channel Expansion | Hunt Bike Wheels and digital-native competitors bypass traditional distributor markups through owned e-commerce subscription programs. |
| ISO 4210 Certification Acceleration | Safety testing standardization creates tiered supplier qualification systems marginalizing uncertified producers across European procurement. |
| Delivery Fleet Service Contract Bundling | Integrated mobility providers consolidate wheel replacement, maintenance, and uptime guarantees displacing component distributors in China. |
Research Methodology
Operator-level perspectives from procurement directors at delivery fleet operators, composite engineering leads at wheel manufacturers, ceramic bearing specialists, and ISO certification auditors anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through UCI equipment registration databases, ECHA REACH substance restriction filings, MIIT industrial policy directives, and customs trade data from Zhejiang and Guangdong export corridors. Bottom-up demand modeling from end-use segments triangulated against top-down supply capacity assessments across carbon fiber precursor, rim extrusion, and hub assembly tiers.
Sensitivity analysis tested forecast robustness across carbon fiber feedstock price volatility scenarios, REACH enforcement intensity variations, and delivery fleet electrification penetration rates. Segmentation dimensions modeled include material technology tier, product architecture type, application performance requirement, end-user procurement authority, and regional regulatory cluster. CAGRs derived from segment-level volume and value buildups incorporating bicycle manufacturer OEM specification cycles, gran fondo participation trends, and Smart Cities Mission infrastructure deployment timelines.
Material uncertainties — ECHA substance restriction expansion scope, EU Green Deal carbon fiber recovery infrastructure commercialization timing, and Toray Industries precursor capacity allocation decisions — sit outside the modeled envelope. Forecasts reflect documented assumptions on technician pool scalability and fleet electrification spoke tension redesign adoption curves. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Run Flat Tire Inserts Market
Tires and Wheels
Wheel Cover Market
Tires and Wheels
Bias Tire Market
Tires and Wheels
Automotive Tire Analytics Market
Tires and Wheels
Bus Radial Tire Market
Tires and Wheels
Global Electric Vehicle Tire Market
Tires and Wheels
Wheel and Tire Service Equipment Market
Tires and Wheels
Global Advanced Tires Market
Tires and Wheels
Tire Changers Market
Tires and Wheels
Two Wheeler Tire Market
Tires and Wheels
Global Pneumatic Tires Market
Tires and Wheels
North America 2-Wheeler Replacement Tire Market
Tires and Wheels
Tire & Wheel Cleaners Market
Tires and Wheels
Off-The-Road (OTR) Tire Market
Tires and Wheels
Passenger Tire Market
Tires and Wheels
Wheel Market