
 Automotive Intelligent Battery Sensor Market | 2026-2036
Automotive Intelligent Battery Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Intelligent Battery Sensor Market Intelligence
Germany is tilting toward expanded semiconductor packaging capacity for automotive sensor modules. Infineon Technologies AG leverages captive wafer fabrication to sustain margin control across intelligent battery sensor chipsets. Robert Bosch GmbH anchors its competitive stance through deep integration of sensor hardware with vehicle energy management firmware. Texas Instruments Incorporated specializes in precision analog front-end circuits that differentiate its offerings in high-voltage battery monitoring architectures.
An automotive intelligent battery sensor measures current, voltage, and temperature at the battery terminal with micro-ampere resolution and sub-millisecond response times to enable state-of-charge and state-of-health estimation for vehicle energy systems. Wired sensors dominate unit shipments due to established automotive qualification protocols and electromagnetic immunity requirements, while wireless sensors represent the fastest-expanding category as OEMs reduce harness complexity in electric vehicle platforms. Fleet operators constitute a concentrated demand pool where uptime-critical commercial vehicles require predictive battery analytics to minimize roadside failures.
NHTSA mandates drive functional safety requirements through ISO 26262 compliance for battery management electronics, while EPA emissions regulations indirectly tighten idle-stop system performance standards where intelligent sensors govern restart reliability. The EU Green Deal and associated battery passport frameworks compel traceable state-of-health data across cell lifecycle stages. Stakeholders must weigh technology roadmaps against evolving cybersecurity standards for connected vehicle battery interfaces.
Market Dynamics
The automotive intelligent battery sensor market pivots on the electrification of vehicle architectures, where 48V mild-hybrid systems and full battery-electric platforms multiply sensor node density per vehicle while tightening accuracy tolerances for state-of-health algorithms.
Growth Catalysts
- ISO 26262 functional safety mandates:NHTSA-aligned crashworthiness requirements force ASIL-D certification for battery management electronics, expanding addressable sensor content per vehicle platform.
- Fleet telematics integration:Commercial vehicle operators deploy predictive battery analytics to eliminate unscheduled downtime, concentrating procurement volume among uptime-critical logistics providers.
- Silicon carbide power electronics:Higher switching frequencies in inverter designs demand sub-millisecond current sensing resolution, pulling precision analog front-end architectures into mainstream battery sensor specifications.
Market Restraints
- Automotive-grade silicon wafer supply:Captive foundry capacity at Infineon and Bosch limits second-source availability for precision mixed-signal chipsets serving intelligent battery sensors.
- Copper and nickel price volatility:Terminal connector materials expose sensor bill-of-materials to commodity swings that compress margin structures for tier-two module suppliers.
- Wireless electromagnetic immunity thresholds:UN ECE R10 compliance for 2.4 GHz sensor transmissions creates certification bottlenecks that delay OEM platform integration timelines.
Strategic Opportunities
- India automotive electronics manufacturing:PLI scheme incentives for advanced automotive component production attract sensor packaging investments targeting domestic OEMs and export markets.
- Battery passport data infrastructure:EU Green Deal traceability requirements create recurring revenue streams for cloud-connected sensors delivering state-of-health documentation across cell lifecycle stages.
- Software-defined vehicle architectures:Over-the-air calibration capabilities enable sensor firmware updates that extend hardware service life and reduce warranty exposure for module suppliers.
Industry Challenges
- Functional safety engineering talent:ASIL-D verification expertise scarcity extends product development cycles and inflates compensation costs for sensor firmware teams.
- Legacy 12V system integration:Dual-voltage architectures in transition-phase vehicles complicate sensor communication protocol standardization across platform generations.
- Cybersecurity certification timelines:UN R155 compliance for connected battery interfaces adds 8-14 month validation phases that delay new sensor product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Intelligent Battery Sensor Market |
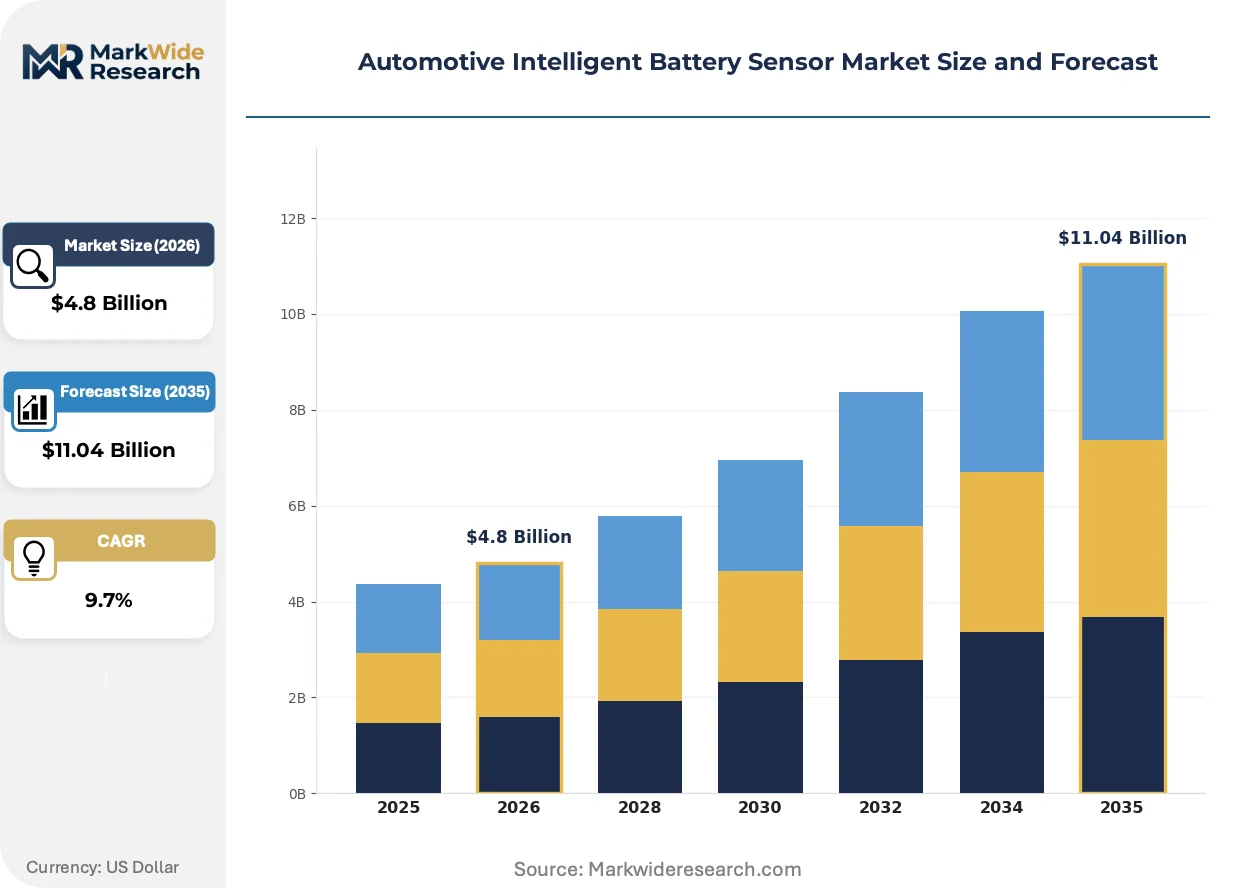
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired Sensors, Wireless Sensors, Smart Connectors, Monitoring Systems End User: OEMs, Aftermarket Providers, Fleet Operators, Vehicle Assemblers Technology: IoT, Bluetooth, NFC, RFID Application: Electric Vehicles, Hybrid Vehicles, Start-Stop Systems, Energy Storage |
| Companies Covered | Infineon Technologies AG, NXP Semiconductors N.V., Robert Bosch GmbH, TE Connectivity, HELLA GmbH & Co. KGaA, Continental AG, Texas Instruments Incorporated, Renesas Electronics Corporation, DENSO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Intelligent Battery Sensor Market Strategic Shifts & Innovations
Automotive battery sensing is pivoting from discrete measurement modules toward integrated edge-computing nodes that preprocess raw signals before transmission, compressing latency and wiring mass simultaneously.
Shunt-based current sensing with integrated sigma-delta converters is rendering obsolete traditional hall-effect architectures in high-voltage battery management systems. Tier-one suppliers in Germany and Japan have qualified micro-ohm shunt designs for 800V platforms, eliminating magnetic drift errors that plagued prior generations. The shift compresses sensor footprint by 40% while extending calibration stability across temperature extremes.
EU battery passport frameworks under the Green Deal mandate granular state-of-health data capture from cell formation through end-of-life recycling. Automotive OEMs in Germany and France now specify blockchain-anchored sensor telemetry to satisfy traceability audits. This regulatory pull is accelerating cloud-native sensor firmware development among European module suppliers.
Fleet procurement patterns favor outcome-based sensor service contracts that bundle hardware, predictive analytics, and replacement logistics into per-mile pricing. Commercial vehicle operators in the United States and South Korea are disintermediating traditional tier-one distributors to negotiate direct sensor data subscriptions with semiconductor manufacturers. The model transfers technical risk to suppliers while locking in multi-year telemetry revenue streams.
Automotive Intelligent Battery Sensor Market Segmentation
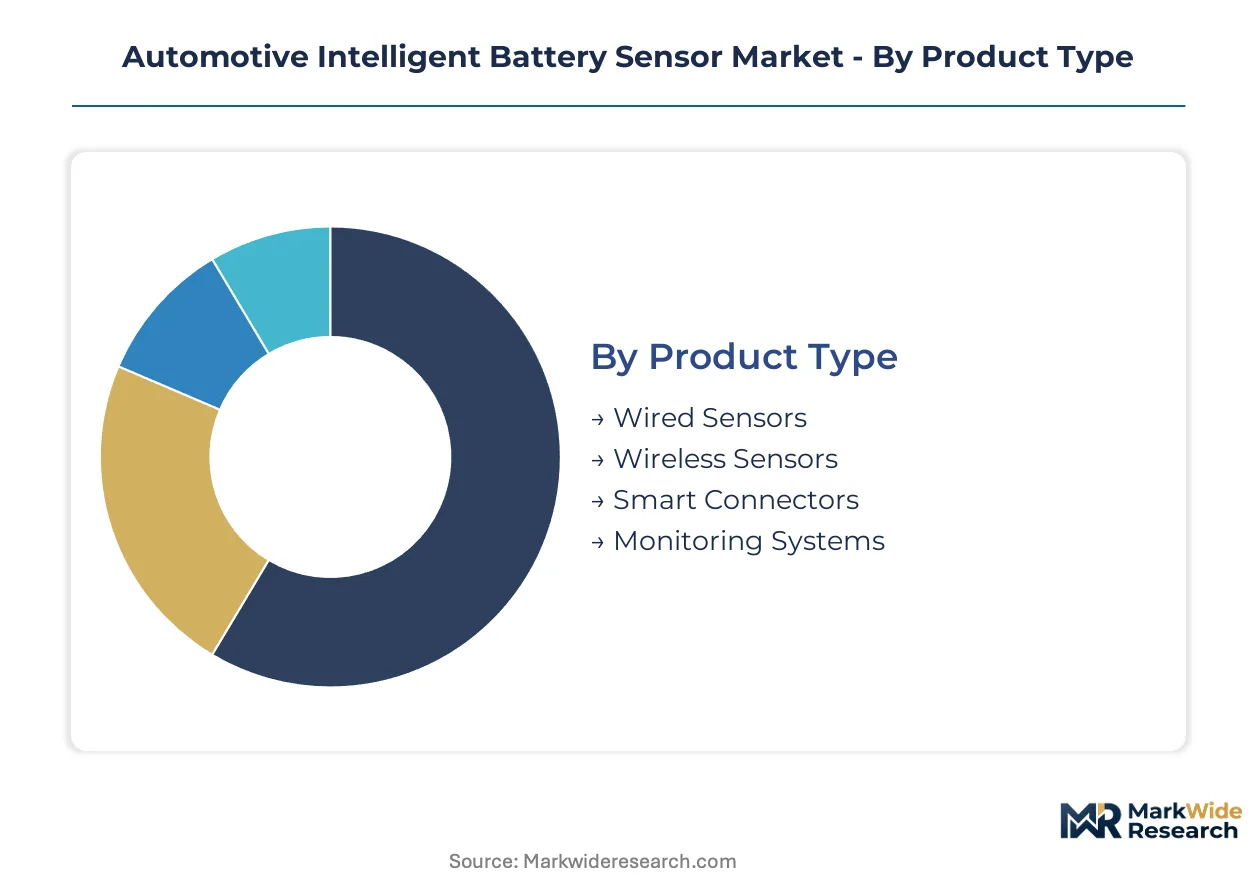
Automotive intelligent battery sensor segmentation reveals how electrification intensity and connectivity requirements reshape procurement patterns across vehicle architectures. Product type and application splits track the migration from 12V auxiliary monitoring toward high-voltage battery management systems in electrified platforms.
Product Type:
Cost tier differentiation separates legacy-qualified hardware from emerging wireless architectures that reduce harness mass.
- Wired Sensors:Copper-shielded harness connections with ISO 11452 electromagnetic immunity qualification dominate current production volumes. Established automotive qualification protocols at Robert Bosch GmbH and Infineon Technologies AG sustain procurement concentration in Germany and Japan for 12V and 48V systems.
- Wireless Sensors:2.4 GHz transceiver modules with integrated antennas eliminate physical harness connections to battery terminals. UN ECE R10 certification bottlenecks in South Korea and the United States delay OEM platform integration despite harness complexity reduction potential.
- Smart Connectors:Terminal-integrated measurement nodes combine shunt resistors with sigma-delta converters in compact form factors.
- Monitoring Systems:Multi-channel aggregation units that consolidate sensor telemetry for centralized battery management controllers.
Wired sensors command the established base. The steepest expansion runs through wireless architectures.
End User:
Customer type determines volume concentration, with fleet procurement patterns diverging sharply from discrete vehicle sales channels.
- OEMs:Volkswagen Group and Hyundai Motor Group specify ASIL-D certified sensors for platform-scale battery management integration. Direct semiconductor supplier relationships bypass traditional tier-one distributors for 800V electric vehicle programs.
- Fleet Operators:Logistics providers in the United States negotiate per-mile sensor service contracts bundling hardware, predictive analytics, and replacement logistics. Uptime-critical commercial vehicle operations concentrate procurement volume among long-haul trucking and last-mile delivery segments.
- Aftermarket Providers:Independent service channels serving aging vehicle populations with replacement battery monitoring modules.
- Vehicle Assemblers:Contract manufacturing operations integrating sensor modules into complete battery pack assemblies.
OEMs anchor production-scale demand. Fleet operators are climbing the fastest as outcome-based procurement models expand.
Technology:
Connectivity protocol selection governs electromagnetic compatibility investment and cybersecurity certification burden.
- IoT:Cellular and Wi-Fi enabled sensors transmitting state-of-health telemetry to cloud analytics platforms. EU battery passport requirements under the Green Deal pull blockchain-anchored IoT architectures into German and French OEM specifications.
- Bluetooth:Low-energy 2.4 GHz protocols for short-range diagnostic and maintenance access without physical connector engagement.
- NFC:Near-field communication for secure pairing and localized data retrieval in service bay environments.
- RFID:Passive identification tags for battery passport traceability across cell lifecycle stages.
IoT connectivity commands the established base. Bluetooth modules are gaining share fastest for diagnostic applications.
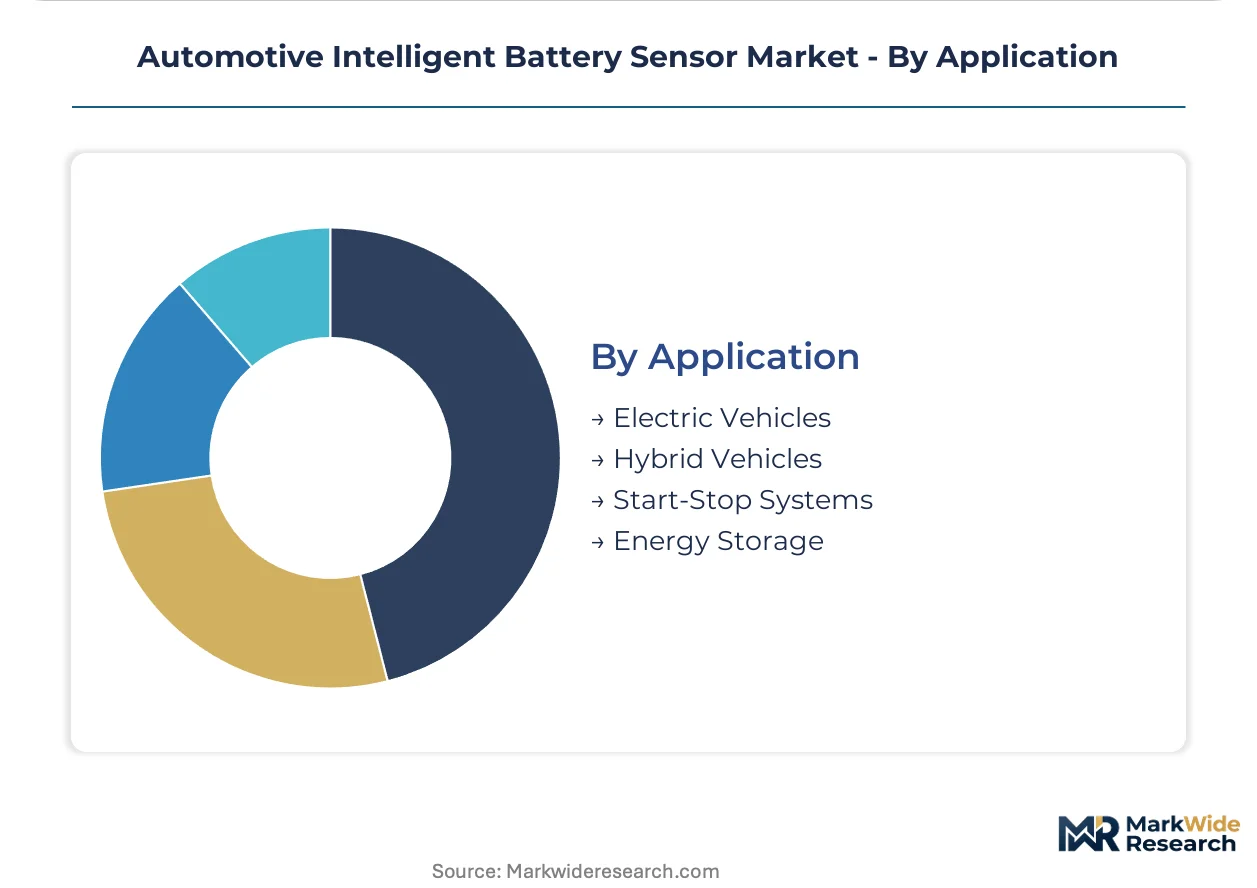
Application:
Electrification intensity across vehicle architectures determines sensor accuracy requirements and voltage isolation specifications.
- Electric Vehicles:400V and 800V battery management systems demand micro-ohm shunt-based current sensing with sub-millisecond response times. Silicon carbide inverter adoption at Tesla and BYD pulls precision analog front-end architectures into high-volume production.
- Hybrid Vehicles:48V mild-hybrid systems multiply sensor node density per vehicle while maintaining cost constraints from 12V legacy architectures.
- Start-Stop Systems:Idle-stop reliability monitoring governed by EPA emissions regulations in the United States.
- Energy Storage:Stationary battery systems requiring state-of-health estimation for grid-scale deployment.
Electric vehicles command the established base. Hybrid applications are expanding most quickly as 48V architectures proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Germany integrates sensors into 800V architectures for premium electric vehicles. India deploys identical hardware for cost-optimized 48V mild-hybrid systems. South Korea pursues wireless certification to eliminate harness mass entirely.
Germany
Volkswagen Group and BMW specify ASIL-D certified sensors for platform-scale battery management. KBA type-approval requirements enforce electromagnetic immunity testing for all battery monitoring electronics. Stuttgart and Munich host captive wafer fabrication at Infineon Technologies AG and Robert Bosch GmbH.
United States
Fleet operators in Texas and California negotiate per-mile sensor service contracts for long-haul trucking electrification. NHTSA crashworthiness mandates drive functional safety requirements through ISO 26262 compliance. Detroit anchors tier-one supplier engineering centers for domestic OEM integration programs.
China
BYD and Tesla Shanghai deploy micro-ohm shunt-based current sensing for 400V and 800V platforms at manufacturing scale. MIIT new energy vehicle subsidy rules mandate state-of-health data reporting for battery passport traceability. Shenzhen and Shanghai concentrate module packaging capacity for export and domestic OEM supply.
South Korea
Hyundai Motor Group accelerates wireless sensor qualification to reduce harness complexity in dedicated electric vehicle architectures. UN ECE R10 certification bottlenecks delay 2.4 GHz platform integration despite technical readiness. Seoul and Ulsan host DENSO Corporation and Renesas Electronics Corporation packaging operations.
Japan
Toyota and Honda specify precision analog front-end circuits for hybrid vehicle battery management across 48V and high-voltage systems. METI carbon neutrality roadmaps tighten idle-stop reliability standards where intelligent sensors govern restart performance. Nagoya and Tokyo anchor Renesas Electronics Corporation and DENSO Corporation semiconductor operations.
Automotive Intelligent Battery Sensor Market Key Industry Players
Capability concentration sits with captive wafer fabricators; scale advantage sits with tier-one module integrators. German and Japanese semiconductor manufacturers control precision mixed-signal chipset supply while automotive suppliers manage vehicle-level qualification and firmware integration. Two strategic archetypes dominate: captive foundry operators with backward integration into silicon, and module specialists with deep vehicle energy management firmware expertise. Competitive moves center on ASIL-D certification acceleration and direct OEM relationships that bypass traditional distribution.
Within the captive foundry tier, Infineon Technologies AG and Robert Bosch GmbH exemplify manufacturers controlling wafer fabrication for margin protection. Texas Instruments Incorporated occupies a position among precision analog specialists serving high-voltage battery monitoring architectures. These three entities represent the dominant competitive anchors across the sensor value chain.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| NXP Semiconductors N.V. |
| Robert Bosch GmbH |
| TE Connectivity |
| HELLA GmbH & Co. KGaA |
| Continental AG |
| Texas Instruments Incorporated |
| Renesas Electronics Corporation |
| DENSO Corporation |
| Others |
Cost & Logistics Intelligence
Single-source dependency on automotive-grade silicon wafer supply from Infineon Technologies AG and Robert Bosch GmbH captive foundries determines both three-tier pricing structure across premium, standard, and economy levels and the geographic concentration of module packaging operations in Germany and Japan. This structural chokepoint compresses margin structures for tier-two suppliers while amplifying pricing power for integrated semiconductor manufacturers serving OEM direct procurement channels.
Pricing Analysis
German and Japanese sensor modules command 15-25% premiums over South Korean equivalents due to ASIL-D certification density and captive wafer fabrication. Price differentiation rests on functional safety grade and volume scale, with fleet operators negotiating per-mile service contracts that bundle hardware, analytics, and logistics. Cost compression in standard-tier wired sensors is intensifying because copper and nickel terminal connector volatility exposes bill-of-materials to commodity swings. Aftermarket providers exhibit highest price sensitivity; OEM direct channels show lowest due to platform-scale procurement and multi-year telemetry revenue lock-in.
Supply Chain Analysis
Silicon feedstock draws from Taiwan, South Korea, and Germany for precision mixed-signal chipsets serving intelligent battery sensors. Raw material dependencies center on copper shunt resistors, nickel-plated terminal connectors, and automotive-grade epoxy molding compounds. Single-source vulnerability at captive foundry operators limits second-source availability during capacity constraints. Distribution runs through tier-one module integrators with direct OEM relationships bypassing traditional distributors for 800V electric vehicle programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as software-defined vehicle architectures disaggregate hardware from firmware, creating specialist niches for predictive analytics providers and cybersecurity-certified module suppliers.
For Market Incumbents: Insulate margin structures through backward integration into sigma-delta converter design and ASIL-D certification acceleration at Stuttgart engineering centers. Threat substitution from wireless sensor architectures demands electromagnetic immunity investment ahead of UN ECE R10 resolution. Channel control lever sits with direct OEM relationships that bypass tier-one distributors for platform-scale battery management integration. For New Entrants and Emerging Players: Establish a beachhead in India automotive electronics manufacturing where PLI scheme incentives attract sensor packaging investments targeting domestic OEMs and export markets. Most penetrable segment: wireless sensor modules for 48V mild-hybrid systems where certification bottlenecks delay incumbent platform integration. Go-to-market angle: outcome-based service contracts bundling hardware and predictive analytics for uptime-critical commercial vehicle fleets in Texas and California. For Investors and Strategic Acquirers: EU battery passport mandates under the Green Deal reshape the acquisition landscape toward cloud-native sensor firmware developers with blockchain-anchored telemetry capabilities. Long-term viability frames around 5-10 year service revenue streams from state-of-health documentation across cell lifecycle stages. Target archetype: mid-cap module suppliers with direct fleet operator relationships and ISO 26262 functional safety engineering depth. Signal to watch: acceleration in UN R155 cybersecurity certification timelines as inflection indicator for connected battery interface readiness.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Certification Acceleration | Infineon Technologies AG and Robert Bosch GmbH leverage captive wafer fabrication to compress validation timelines for battery management electronics. |
| Wireless Sensor Platform Integration | Hyundai Motor Group and DENSO Corporation target UN ECE R10 compliance to eliminate harness complexity in dedicated electric vehicle architectures. |
| Battery Passport Data Infrastructure | EU Green Deal traceability requirements pull blockchain-anchored IoT architectures into German and French OEM specifications for state-of-health documentation. |
| Direct OEM Relationship Development | Volkswagen Group and Texas Instruments Incorporated bypass tier-one distributors for 800V platform sensor procurement, locking in multi-year telemetry revenue. |
| India Manufacturing Footprint Expansion | PLI scheme incentives attract sensor packaging investments targeting domestic OEMs and export markets for cost-optimized 48V mild-hybrid systems. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with Tier 1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and fleet operations managers at uptime-critical logistics providers. Secondary validation drew from vehicle production databases, IHS Markit registration data, NHTSA crashworthiness filings, and EU battery passport regulatory documentation. Bottom-up sensor unit economics triangulated against top-down vehicle electrification forecasts to anchor volume and value estimates.
Calibration against historical adoption curves for 48V mild-hybrid and 800V battery-electric platforms refined penetration assumptions across the projection horizon. Segmentation dimensions modeled span product type, connectivity protocol, vehicle propulsion architecture, and regional production cluster. CAGRs derived from slope analysis of electrification intensity curves and silicon carbide inverter adoption rates at named OEMs. Industry-specific inputs included ASIL-D certification timelines and UN ECE R10 electromagnetic immunity test schedules.
Stress conditions across copper and nickel commodity volatility, captive foundry capacity constraints, and wireless certification bottlenecks were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding fleet telematics integration velocity and battery passport regulatory enforcement timing. Cross-checking against IEA electric vehicle deployment benchmarks and MIIT new energy vehicle subsidy disbursement patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Construction Electric Vehicle Market
Electric Vehicles
Africa Electric Scooter Market
Electric Vehicles
Vehicle Electrification Market
Electric Vehicles
Europe Solar E-Bike Market
Electric Vehicles
Electric Two Wheelers MRO Market
Electric Vehicles
Automotive Battery Thermal Management System Market
Electric Vehicles
Driveline Electric Vehicle Market
Electric Vehicles
South America Automotive High Performance Electric Vehicles Market
Electric Vehicles
North America Electric Vehicle (EV) Fluids Market
Electric Vehicles
Europe Electric Truck Market
Electric Vehicles
India Solar E-Bike Market
Electric Vehicles
Electromagnetic and Radio Frequency Interference Coating for Electric Vehicles Market
Electric Vehicles
Electric Vehicle Insulation Market
Electric Vehicles
France Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
Automotive Energy Harvesting and Regeneration Market
Electric Vehicles
NGO Steel in Electric Vehicle Market