
 Germany Electric Commercial Vehicle Battery Pack Market | 2026-2036
Germany Electric Commercial Vehicle Battery Pack Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Electric Commercial Vehicle Battery Pack Market Insights
Premium energy density specifications and commodity cost-per-kWh benchmarks is decoupling in Germany's electric commercial vehicle battery pack landscape. CATL leverages its vertical integration into cathode materials to sustain aggressive cost positioning for logistics fleet tenders. Akasol AG anchors its competitiveness through specialized thermal management systems engineered for German commercial vehicle duty cycles. BMZ Group differentiates via modular pack architectures that accommodate varying chassis configurations across municipal bus and delivery van segments.
A Germany electric commercial vehicle battery pack constitutes an integrated electrochemical energy storage system comprising lithium-ion cells arranged in modules, managed by battery management systems, and housed within structural enclosures rated for commercial vehicle vibration and thermal loads. These systems typically operate at 400-800V architectures with capacities spanning 100 kWh to 400 kWh to deliver sustained power for urban freight and passenger transport applications. Lithium-ion chemistry dominates current procurement volumes given its established manufacturing scale and performance validation, while solid-state configurations attract development investment for their projected gains in energy density and operational safety margins. Application patterns reveal logistics and delivery services as the most active procurement segments, reflecting e-commerce fulfillment timelines and municipal low-emission zone enforcement that compel fleet turnover.
KBA vehicle type approval requirements, EU Battery Regulation sustainability mandates, and Germany's BImSchV federal emission control ordinances collectively establish compliance thresholds that filter market access for imported pack suppliers. The EU Green Deal's interim CO2 reduction targets for heavy-duty vehicles translate directly into binding procurement quotas for fleet operators, accelerating replacement demand. Stakeholders must monitor how forthcoming battery passport traceability rules and recycled content minimums reshape supplier qualification criteria and pack cost structures.
Market Dynamics
The EU Battery Regulation's recycled content mandates and forthcoming battery passport traceability rules are compressing supplier qualification timelines and reshaping procurement criteria for fleet operators across German commercial transport corridors.
Growth Catalysts
- Federal Emission Control Ordinances:Germany's BImSchV mandates accelerate fleet turnover timelines for municipal logistics operators serving low-emission zones in Berlin, Hamburg, and Munich metropolitan areas.
- Last-Mile Delivery Density:E-commerce fulfillment volume concentration in the Rhine-Ruhr corridor creates favorable duty-cycle economics for battery-electric vans and medium-duty trucks.
- Charging Infrastructure Rollout:Federal funding programs for depot and highway charging stations reduce range anxiety barriers for long-haul electrification pilots.
Market Restraints
- Cathode Material Cost Volatility:Lithium and nickel price swings transmit directly into pack cost structures, compressing margin visibility for fleet tender negotiations.
- Cell Supply Concentration:Asian cell manufacturers control dominant shares of high-nickel chemistry output, creating procurement dependency risks for German pack integrators.
- Energy Density Limitations:Current lithium-ion gravimetric performance caps payload-range tradeoffs for heavy-duty regional freight applications.
Strategic Opportunities
- Solid-State Chemistry Convergence:Polymer-ceramic electrolyte interfaces promise thermal runaway elimination and 40% volume reduction for future pack architectures.
- Bavarian Manufacturing Corridor:Underdeveloped pack assembly capacity in southern Germany offers greenfield site advantages for automated production lines.
- EU Green Deal HDV Targets:Interim CO2 reduction thresholds for heavy-duty vehicles translate into binding zero-emission procurement quotas for 2025-2030 fleet planning cycles.
Industry Challenges
- Battery Passport Compliance Timeline:Full supply chain traceability documentation requirements strain IT infrastructure and supplier audit capabilities ahead of 2027 enforcement deadlines.
- Thermal Management Engineering Gap:Scarce specialist talent for commercial vehicle duty-cycle simulation and pack cooling system design extends development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Electric Commercial Vehicle Battery Pack Market |
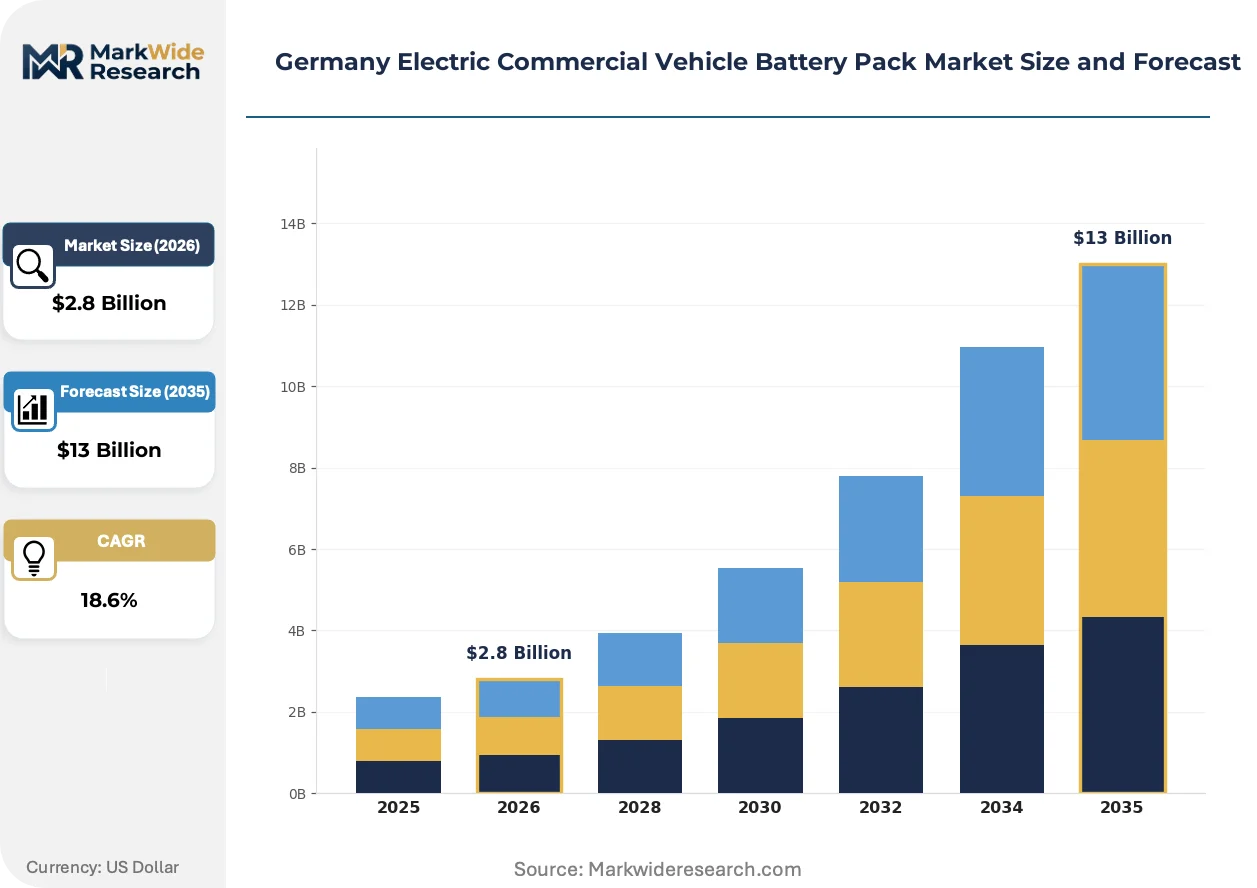
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Lead Acid, Solid State, Nickel-metal Hydride Application: Logistics, Public Transport, Construction, Delivery Services Capacity: 100 kWh, 200 kWh, 300 kWh, 400 kWh End User: Fleet Operators, Government Agencies, Private Companies, Logistics Providers |
| Companies Covered | Akasol AG, CATL, BYD Company, Northvolt AB, SAIC Volkswagen Power Battery, LG Energy Solution, Samsung SDI, BMZ Group, Automotive Cells Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Electric Commercial Vehicle Battery Pack Market Trends and Innovations
Cell-to-pack architectures and silicon-anode chemistries are compressing pack mass and cost structures while regulatory traceability mandates force supply chain reconfiguration across German commercial vehicle procurement.
Lithium iron phosphate chemistry is absorbing procurement share in urban delivery applications where energy density requirements moderate and cycle life priorities dominate. Municipal fleet operators in Cologne and Stuttgart are specifying LFP-dominant configurations for depot-charged distribution routes. This chemistry shift is absorbing margin pressure from nickel supply volatility while extending pack warranty terms to 8-year coverage.
The EU Battery Regulation's recycled content minimums and carbon footprint disclosure rules are tightening supplier documentation requirements for pack integrators serving German OEMs. Industrial consequence includes accelerated qualification of European-based cathode material refiners to shorten transport emissions calculations. Heavy-duty truck segments face the steepest compliance burden given larger pack sizes and higher material throughput.
Fleet operators are consolidating procurement decisions at the holding-company level rather than delegating to individual depot managers. This centralization concentrates volume leverage for tender negotiations and standardizes charging infrastructure specifications across multi-city operations. The pattern is most visible among parcel carriers operating integrated networks across North Rhine-Westphalia and Baden-Württemberg.
Germany Electric Commercial Vehicle Battery Pack Market Segmentation
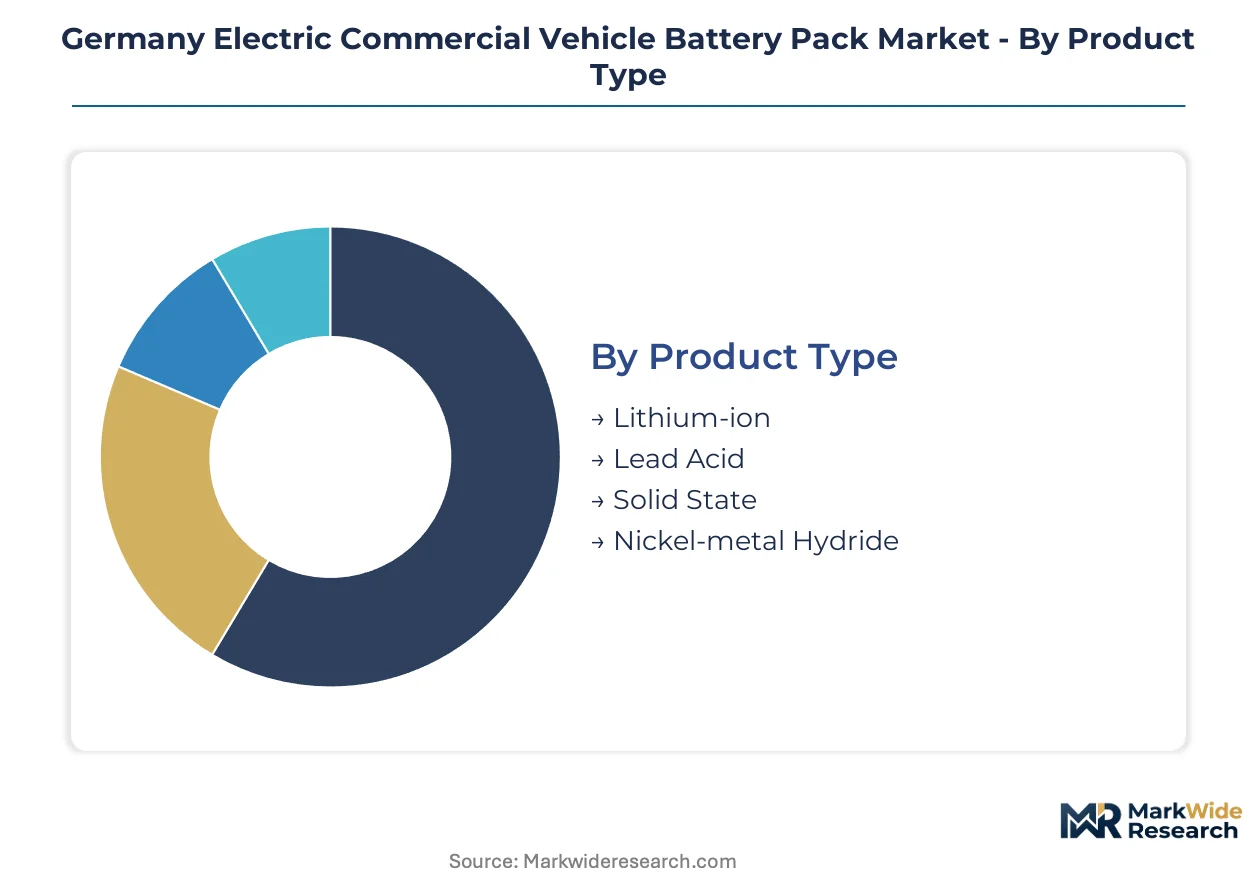
Battery pack procurement in Germany's commercial vehicle sector fragments across chemistry types, duty cycles, and fleet ownership structures. Each segmentation axis carries distinct certification burdens from KBA type approval and EU Battery Regulation traceability mandates that reshape supplier qualification requirements.
Product Type:
KBA homologation pathways diverge sharply across electrochemical systems, with solid-state configurations facing extended validation timelines versus established lithium-ion architectures.
- Lithium-ion:NMC and LFP cell configurations dominate current procurement volumes, with nickel-rich variants preferred for long-range heavy-duty routes and iron-phosphate chemistries absorbing share in urban depot-charged operations. Rhine-Ruhr logistics fleets specify these packs for 400-800V architectures given validated thermal runaway containment and established recycling infrastructure.
- Solid State:Polymer-ceramic electrolyte interfaces promise 40% volume reduction and thermal runaway elimination, though KBA approval timelines lag commercial deployment by several years. BMW and Daimler Truck pilot programs concentrate in Bavarian manufacturing corridors.
- Lead Acid:Absorbed glass mat configurations persist in auxiliary power and low-voltage starter applications for retrofit hybrid conversions.
- Nickel-metal Hydride:Toyota-derived hybrid architectures retain niche presence in municipal bus series-hybrid drivetrains.
Lithium-ion sits at the top of the volume ranking, with solid-state climbing the fastest.
Application:
Duty-cycle intensity and charging predictability determine pack specification priorities across commercial transport segments.
- Logistics:Regional freight corridors between Hamburg, Berlin, and Munich demand 300-400 kWh configurations with rapid-charge capability. Fleet operators negotiate warranty terms around 8-year cycle life guarantees.
- Public Transport:Depot-charged municipal bus fleets in Cologne and Stuttgart favor LFP-dominant packs with standardized 200 kWh capacities for predictable route electrification.
- Construction:Off-road duty cycles with vibration exposure and intermittent charging access require reinforced enclosures and conservative depth-of-discharge protocols.
- Delivery Services:Last-mile van operators in North Rhine-Westphalia consolidate procurement at holding-company level, standardizing 100-150 kWh packs across multi-city depot networks.
Logistics commands the largest procurement volumes, while delivery services expands most quickly on e-commerce fulfillment density.
Capacity:
Energy storage sizing directly correlates with vehicle class homologation and axle load regulations under German StVZO technical inspection standards.
- 100 kWh:Compact delivery van segment standard, enabling 150-200 km urban range without payload compromise. Deutsche Post DHL specifications dominate tender volumes.
- 200 kWh:Medium-duty truck and municipal bus sweet spot, balancing curb weight against depot charging infrastructure constraints.
- 300 kWh:Regional distribution truck configuration emerging in Baden-Württemberg automotive supplier corridors.
- 400 kWh:Heavy-duty tractor-trailer pilot programs on Autobahn corridor charging routes, constrained by current cell energy density limits.
200 kWh maintains installed base leadership, with 300 kWh gaining share fastest on regional freight electrification.
End User:
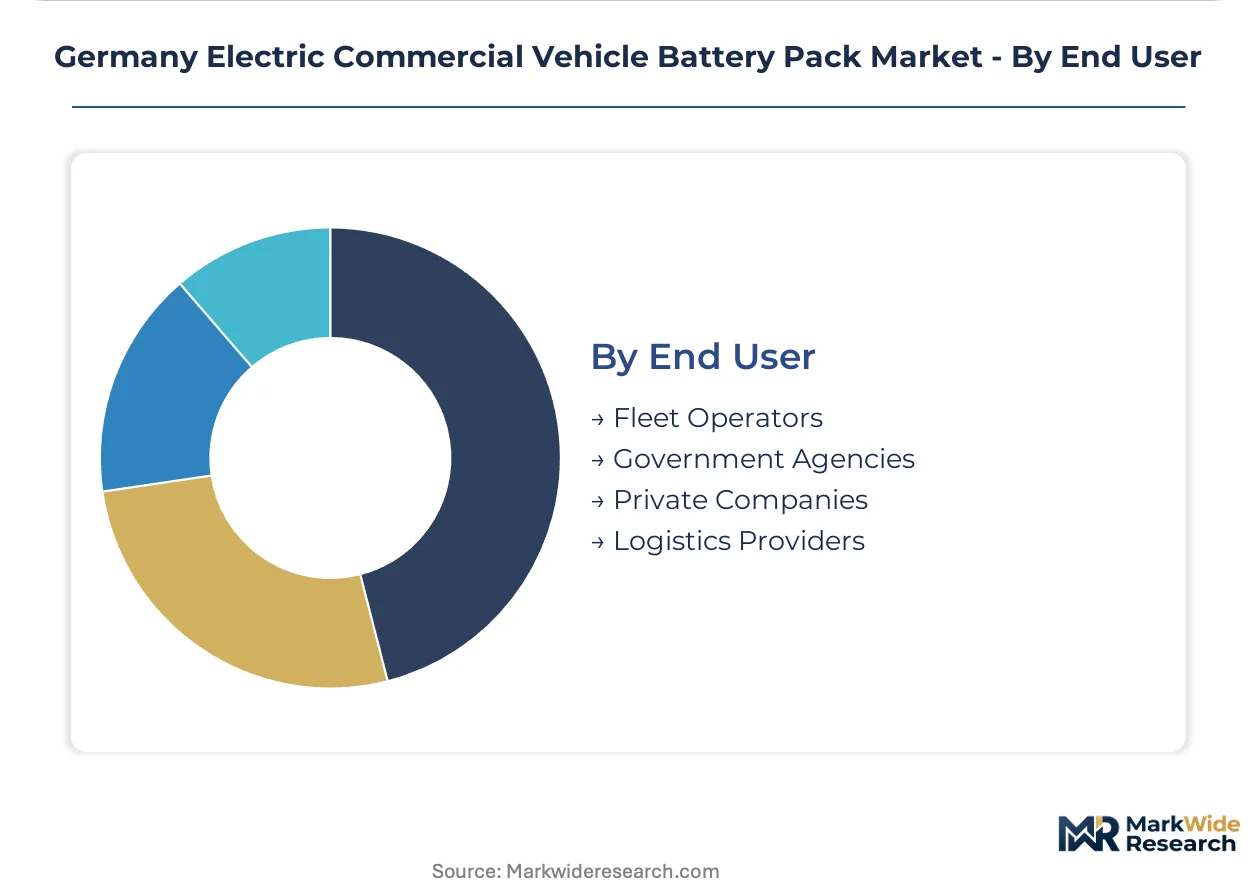
Procurement centralization and compliance documentation capabilities segment buyer sophistication across German commercial transport.
- Fleet Operators:Integrated parcel and grocery networks leverage volume consolidation for tender leverage and standardized charging specifications across North Rhine-Westphalia operations.
- Government Agencies:Municipal transit authorities face binding zero-emission procurement quotas under EU Green Deal interim targets, with battery passport documentation requirements accelerating supplier qualification.
- Private Companies:Mid-size commercial fleets exhibit fragmented procurement with depot-specific charging infrastructure decisions.
- Logistics Providers:Third-party freight operators prioritize pack swap compatibility and multi-OEM chassis integration to preserve fleet flexibility.
Fleet operators occupy the top volume position, with government agencies climbing fastest on mandated electrification timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany outpaces neighboring France in commercial vehicle battery pack deployment density, while Poland and the Netherlands accelerate procurement through EU cohesion funding and port electrification mandates respectively.
North Rhine-Westphalia
The Rhine-Ruhr metropolitan corridor concentrates Germany's last-mile delivery electrification, with DHL and Amazon fulfillment networks driving 100-150 kWh pack procurement. KBA type approval requirements filter supplier access for logistics fleet tenders. Cologne and Düsseldorf depot clusters standardize LFP-dominant configurations for predictable urban duty cycles.
Baden-Württemberg
Automotive supplier corridors between Stuttgart and Karlsruhe pilot 300 kWh regional distribution truck configurations. BImSchV federal emission control ordinances accelerate municipal fleet turnover timelines. The Stuttgart metropolitan area hosts concentrated charging infrastructure rollout for medium-duty electrification programs.
Bavaria
Munich's municipal transit authority faces binding zero-emission procurement quotas under EU Green Deal interim targets for heavy-duty vehicles. Battery passport traceability requirements strain supplier qualification capabilities ahead of enforcement deadlines. BMW and Daimler Truck solid-state pilot programs concentrate manufacturing development in southern Bavarian corridors.
Lower Saxony
Volkswagen commercial vehicle headquarters in Wolfsburg anchors procurement standardization for integrated fleet networks. Federal funding programs for depot charging stations reduce range anxiety barriers for regional freight operators. The Hanover-Brunswick logistics corridor exhibits consolidated holding-company procurement decisions across multi-city operations.
Berlin-Brandenburg
Capital region low-emission zone enforcement compels accelerated van fleet turnover among parcel carriers and grocery distributors. EU Battery Regulation recycled content mandates reshape supplier documentation requirements for pack integrators. Berlin's municipal bus electrification program specifies standardized 200 kWh LFP configurations for depot-charged route networks.
Germany Electric Commercial Vehicle Battery Pack Market Competitive Landscape
Top-tier vendors anchor high-volume supply agreements with German OEMs, while mid-tier specialists compete on thermal management engineering and modular pack architectures. The vendor structure exhibits concentration around Asian cell manufacturers and European pack integrators with established KBA homologation pathways. Two strategic archetypes dominate: vertically integrated cathode material producers and modular system architects serving multi-OEM chassis platforms. Competitive moves center on backward integration into raw material refining and automated pack assembly capacity expansion in underdeveloped southern German corridors.
Within the European pack integration tier, Akasol AG and BMZ Group exemplify specialized thermal management and modular architecture approaches respectively. CATL represents the vertically integrated Asian cell manufacturer archetype with captive cathode material production. These three anchors illustrate the competitive tension between cost-positioned volume suppliers and engineering-differentiated regional specialists serving German commercial vehicle duty cycles.
| Leading Market Players |
|---|
| Akasol AG |
| CATL |
| BYD Company |
| Northvolt AB |
| SAIC Volkswagen Power Battery |
| LG Energy Solution |
| Samsung SDI |
| BMZ Group |
| Automotive Cells Company |
| Others |
Pricing and Supply Chain Analysis
Thermal management engineering talent scarcity in southern Germany widens labor-cost spreads between premium engineering-differentiated packs and commoditized volume offerings. CATL's captive cathode production and Akasol AG's specialized cooling architectures anchor opposite ends of this pricing spectrum, with fleet procurement consolidating around standardized specifications that compress mid-tier margins.
Pricing Analysis
Bundled battery management system integration and unbundled cell-only supply splits procurement patterns across German commercial vehicle tenders. Three-tier pricing structure across premium, standard, and economy levels reflects KBA certification grade and volume scale commitments, with iron-phosphate chemistry absorbing margin pressure from nickel volatility. Pricing pressure stems from Asian cell manufacturers' aggressive logistics fleet positioning, while municipal transit authorities exhibit least price sensitivity due to EU Green Deal mandate compliance timelines.
Supply Chain Analysis
Germany's BImSchV federal emission control ordinances and EU Battery Regulation recycled content minimums are reshaping cathode material sourcing toward European-based refiners. High-nickel chemistry output concentrates in China, South Korea, and Japan, with lithium carbonate and cobalt sulfate dependencies creating single-source vulnerability risks for German pack integrators. Distribution runs through OEM-anchored direct procurement channels and Tier 1 supplier networks serving multi-depot fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's electric commercial vehicle battery pack market represents a late-cycle quality story as fleet procurement shifts toward solid-state pilot programs and battery passport-compliant traceability specifications.
For Market Incumbents: Deepen backward integration into cathode material refining to defend margin position against nickel price volatility and Asian cell manufacturer cost aggression. Expand automated pack assembly capacity in Bavarian manufacturing corridors to capture heavy-duty truck electrification demand under EU Green Deal interim targets. For New Entrants and Emerging Players: Mid-size construction equipment fleets represent an underserved buyer archetype with fragmented procurement and limited thermal management engineering coverage. Target off-road duty cycle applications with reinforced enclosure designs and conservative depth-of-discharge protocols, leveraging distributor partnerships with regional equipment rental networks. For Investors and Strategic Acquirers: Automotive OEMs are the most active acquirer in this space, consolidating pack integration capabilities to secure supply chain control. Five-to-ten year viability hinges on solid-state chemistry convergence timelines and battery passport compliance infrastructure buildout. Watch for KBA approval acceleration for polymer-ceramic electrolyte configurations as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Refining | European material refiners shorten transport emissions calculations for EU Battery Regulation compliance. |
| Solid-State Pilot Program Expansion | BMW and Daimler Truck development concentrates in Bavarian manufacturing corridors ahead of KBA validation. |
| Automated Pack Assembly Capacity Buildout | Underdeveloped southern German corridors offer greenfield site advantages for production scaling. |
| Battery Passport IT Infrastructure Investment | Full supply chain traceability documentation requirements strain supplier audit capabilities ahead of enforcement. |
| Thermal Management Engineering Talent Acquisition | Scarce specialist capability for commercial vehicle duty-cycle simulation extends development cycles. |
Research Methodology
Coverage spans German federal states and neighboring EU commercial vehicle corridors, with primary inputs from each region combined with secondary validation. Fleet procurement directors, KBA homologation engineers, cathode material refining executives, and municipal transit authority technical officers contributed interview data. Secondary sources include EU Battery Regulation implementation guidance, KBA type approval databases, federal transport ministry funding disclosures, and customs trade records for cell and module imports. Bottom-up fleet deployment estimates triangulate against top-down OEM production forecasts.
Rate-of-change decomposition separates volume growth from average pack capacity expansion and chemistry mix shifts across the analysis window. Segmentation dimensions include electrochemical system, vehicle application, energy capacity tier, and fleet ownership structure. CAGRs derive from logistic curve fitting to fleet electrification mandate timelines and charging infrastructure rollout schedules. Heavy-duty CO2 reduction targets and battery passport enforcement deadlines anchor industry-specific forecast inputs.
Underlying measurement precision varies by segment; solid-state pilot volumes and emerging 400 kWh heavy-duty configurations carry wider uncertainty bands than established LFP urban delivery deployments. Forecasts reflect documented assumptions regarding cathode material price trajectories and KBA approval timeline acceleration. Supply concentration risks, EU recycled content mandate implementation delays, and thermal runaway incident frequency warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Spain Solar E-Bike Market
Electric Vehicles
Germany Solar E-Bike Market
Electric Vehicles
Electric Commercial Vehicle Market
Electric Vehicles
Electric Vehicle Skateboard Platform Market
Electric Vehicles
Middle East Wireless EV Charging Market
Electric Vehicles
Self Balancing Electric Scooter Market
Electric Vehicles
BEV On-Board Charger Market
Electric Vehicles
Europe Electric Scooter Market
Electric Vehicles
Middle-East E-Bike Market
Electric Vehicles
North America Electric Truck Market
Electric Vehicles
48V Mild Hybrid Electric Vehicle (MHEV) Market
Electric Vehicles
Electric Vehicle Liquid Cold Plates Market
Electric Vehicles
Busbar for EV Market
Electric Vehicles
Canada Solar E-Bike Market
Electric Vehicles
Electric Vehicle Battery Enclosure Market
Electric Vehicles
Europe Automotive Battery Thermal Management System Market