
 E-Axle Market | 2026-2036
E-Axle Market Size, Share, and Industry Trends Forecast 2026-2036
E-Axle Market Intelligence
Silicon carbide is shifting power electronics economics across e-axle architectures, cutting inverter losses and enabling higher thermal operating thresholds. Robert Bosch GmbH leverages in-house semiconductor sourcing to sustain margin control across integrated drive modules. BorgWarner Inc. anchors North American supply through its dedicated e-mobility manufacturing footprint. Nidec Corporation specializes in compact, high-RPM motor designs that occupy the lightweight vehicle segment.
An e-axle combines an electric motor, power electronics inverter, and reduction gearbox into a single integrated drive unit, typically delivering torque outputs from 1500 Nm to 5000 Nm depending on vehicle class and thermal management architecture. Its primary purpose is to convert DC battery current into mechanical wheel torque while minimizing packaging volume and mass relative to discrete component layouts. Integrated E-Axle configurations lead volume deployment because OEMs prioritize assembly-line simplicity and NVH containment, though Hub E-Axle designs attract engineering investment for their elimination of driveline losses and suspension packaging freedom. Passenger Vehicles dominate current procurement flows, while Commercial Vehicles represent the fastest-expanding application as last-mile delivery electrification tightens total-cost-of-ownership calculations.
FDA oversight extends to automotive-grade semiconductor packaging materials used in e-axle inverters, while EPA tailpipe regulations indirectly accelerate electric drivetrain substitution timelines. China's MIIT enforces GB standards for motor efficiency and electromagnetic compatibility that gate market access for foreign suppliers. Stakeholders must monitor how NHTSA evolving crashworthiness standards for battery-integrated chassis structures reshape e-axle mounting and isolation requirements.
Market Dynamics
Silicon carbide power semiconductors are compressing inverter thermal budgets while China's MIIT efficiency mandates force synchronous motor redesigns across supplier portfolios.
Growth Catalysts
- China NEV mandate:The dual credit policy compels domestic OEMs to electrify mainstream model lineups, sustaining e-axle procurement volumes across passenger vehicle segments.
- Silicon carbide adoption:Wide-bandgap semiconductors cut switching losses by half versus silicon IGBTs, enabling higher power density in integrated drive modules.
- Last-mile delivery electrification:Commercial fleet operators in urban logistics corridors are substituting diesel vans with battery-electric alternatives, expanding torque demand into the 3000-5000 Nm range.
Market Restraints
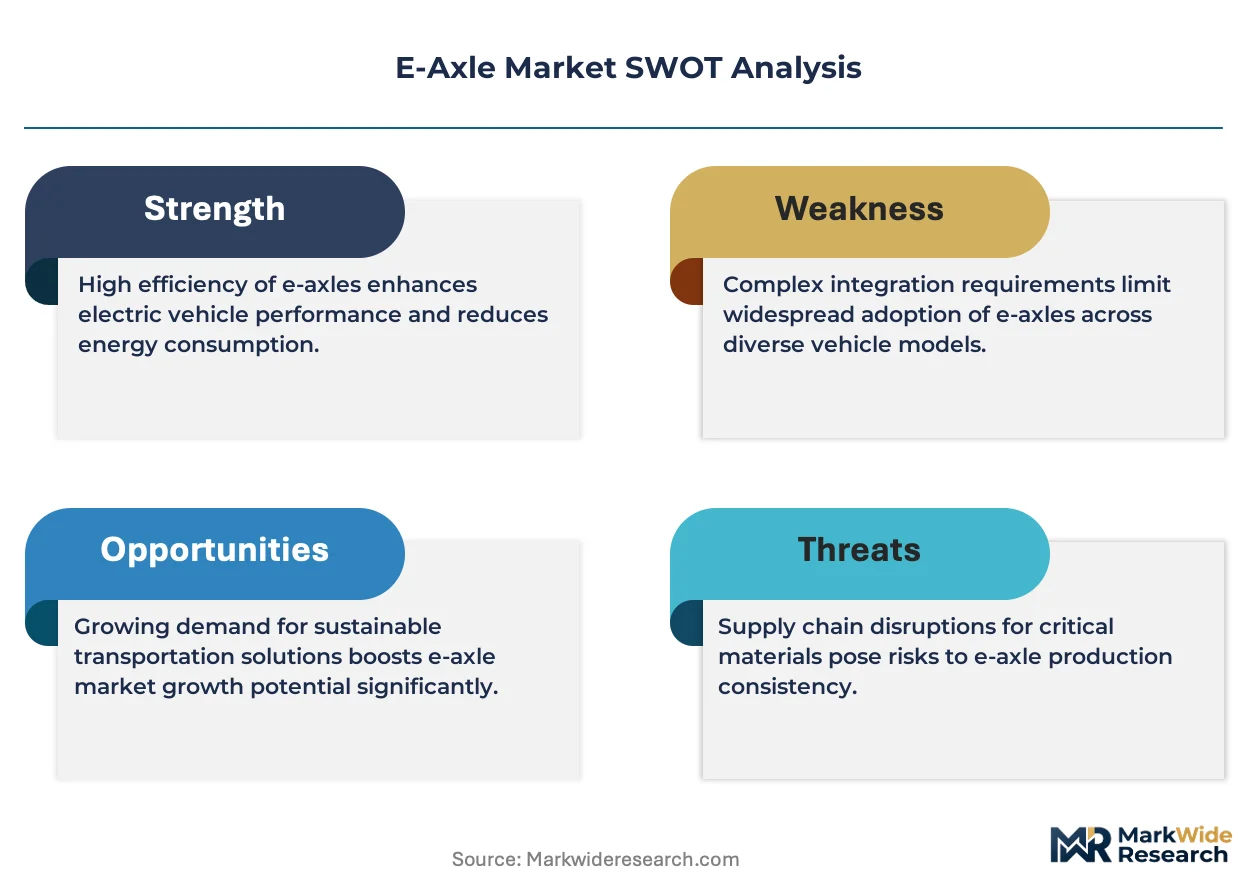
- Rare earth magnet supply concentration:Neodymium and dysprosium processing capacity clusters in China's Inner Mongolia and Jiangxi provinces, exposing motor manufacturers to export quota volatility.
- Thermal management capex intensity:Liquid-cooled inverter housings require precision die-casting investments that strain mid-tier supplier balance sheets.
- Legacy driveline substitution inertia:Internal combustion powertrain engineering teams within established OEMs resist platform redevelopment timelines that compress e-axle integration windows.
Strategic Opportunities
- Hub motor architectures:Elimination of half-shafts and differential housings frees suspension packaging volume for battery cell stacking in skateboard chassis designs.
- EU Green Deal manufacturing incentives:Battery and e-mobility component production subsidies in Germany, Hungary, and Poland are attracting inverter assembly investments.
- 800-volt platform migration:Premium passenger vehicle segments are demanding higher voltage architectures that reduce copper mass in motor windings and power cabling.
Industry Challenges
- Electromagnetic compatibility certification:GB standards enforcement by China's MIIT requires extensive anechoic chamber testing that extends product qualification timelines by 8-12 months.
- Systems integration talent scarcity:The convergence of mechanical gearbox design, power electronics, and motor control software demands cross-functional engineering teams that remain concentrated at Tier-1 suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Axle Market |
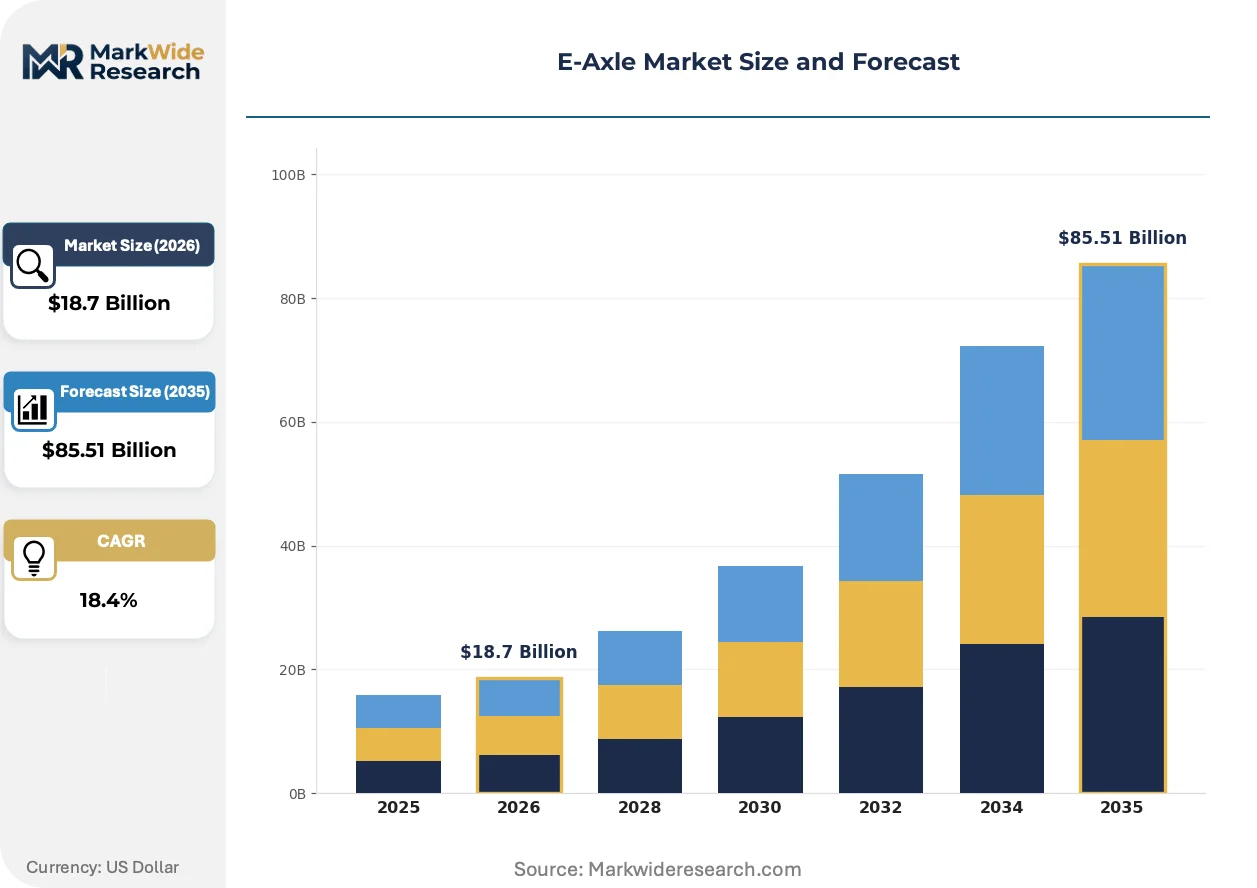
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $85.51 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Parallel E-Axle, Integrated E-Axle, Hub E-Axle, Modular E-Axle Power Rating: 100 kW, 150 kW, 200 kW, 250 kW Vehicle Type: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Trucks, Motorcycles Deployment: OEMs, Aftermarket, Fleet Operators, Research Institutions |
| Companies Covered | Continental AG, BorgWarner Inc., Robert Bosch GmbH, Dana Incorporated, Schaeffler AG, ZF Friedrichshafen AG, Magna International Inc., Cummins Inc., Nidec Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Axle Market Strategic Shifts & Innovations
Power semiconductor material transitions and modular platform architectures are compressing development cycles while regulatory efficiency mandates force synchronous motor redesigns.
Silicon carbide MOSFETs are expanding into 800-volt inverter designs by enabling faster switching frequencies that reduce filter component volume. Premium passenger vehicle OEMs in Germany and South Korea are qualifying these devices for 2025 platform launches. The technology is expanding into mainstream vehicle segments as foundry capacity ramps and die costs approach silicon parity at 150 kW power levels.
REACH substance restrictions on PFAS-based cooling fluids are forcing thermal management suppliers to reformulate dielectric coolants for direct motor winding contact. The industrial consequence is accelerated validation programs for synthetic ester and hydrocarbon alternatives. Commercial vehicle e-axle suppliers serving European markets are most affected, with several delaying 2024 product launches to complete material compatibility testing.
Fleet procurement teams are consolidating e-axle sourcing decisions at the platform-architecture level rather than delegating to individual vehicle program managers. This behavior concentrates purchasing power among three to four global Tier-1 suppliers capable of delivering integrated motor-inverter-gearbox modules. The pattern is most visible in North American last-mile delivery electrification, where Amazon, FedEx, and UPS standardization committees are qualifying single e-axle designs across multiple van body configurations.
E-Axle Market Segmentation
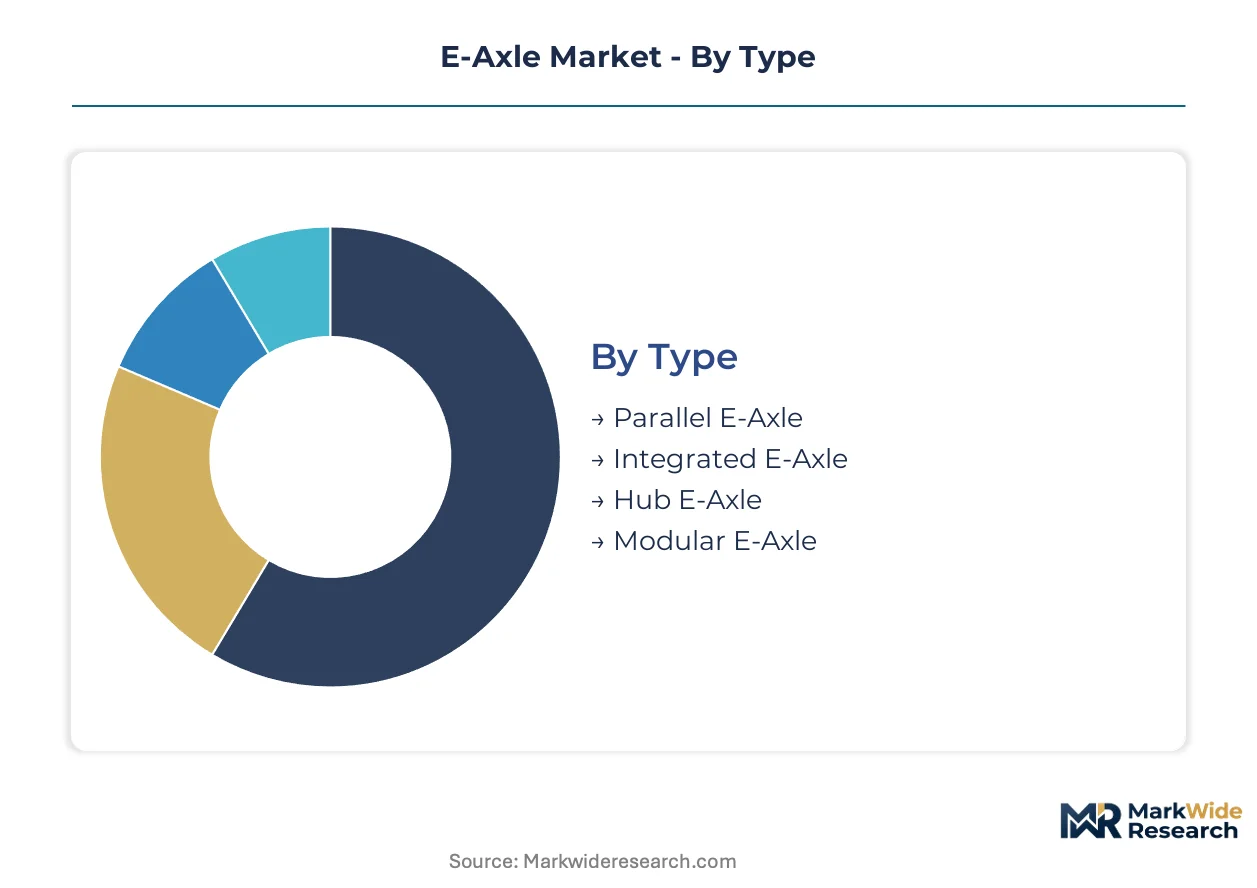
E-axle procurement patterns diverge sharply across integration architectures and vehicle applications. OEM platform strategies and thermal management requirements create distinct demand clusters that suppliers must navigate simultaneously.
Type:
Integration density separates buyers by assembly complexity tolerance and NVH containment priorities.
- Integrated E-Axle:Combines motor, inverter, and reduction gearbox into a single sealed housing with shared thermal management circuits. China's NEV mandate sustains procurement volumes as domestic OEMs electrify mainstream sedans and crossovers under MIIT efficiency requirements.
- Hub E-Axle:Eliminates half-shafts and differential housings by mounting motors directly inside wheel hubs, freeing suspension packaging volume for battery stacking. German premium OEMs in Stuttgart's manufacturing corridor are qualifying these for skateboard chassis designs targeting urban delivery segments.
- Parallel E-Axle:Retains discrete component mounting with separate motor and gearbox housings for service accessibility.
- Modular E-Axle:Enables platform-scale component sharing across multiple vehicle programs through standardized motor-inverter interfaces.
Integrated E-Axle leads volumes today; Hub E-Axle is gaining share fastest.
Power Rating:
Torque requirements stratify by vehicle mass and duty cycle intensity across passenger and commercial applications.
- 150 kW:Dominates compact and mid-size passenger vehicle segments where packaging constraints favor compact motor designs. South Korean OEMs are concentrating procurement for B-segment crossovers targeting European CO2 compliance thresholds.
- 200 kW:Serves premium passenger vehicles and light commercial vans requiring sustained highway cruising capability. Fleet operators in North American last-mile corridors are specifying this rating for electric van platforms serving Amazon and UPS route networks.
- 100 kW:Occupies urban micro-mobility and entry-level A-segment vehicles with limited thermal budgets.
- 250 kW:Addresses heavy-duty pickup and commercial van segments demanding peak torque for trailer towing.
150 kW commands the largest installed base; 200 kW is expanding most quickly.
Vehicle Type:
Application-specific duty cycles determine thermal architecture and torque ripple tolerance requirements.
- Passenger Vehicles:Battery-electric sedans, crossovers, and SUVs account for the dominant procurement flow as OEMs convert ICE model lineups. Germany's premium manufacturing corridor around Munich anchors qualification programs for 800-volt platform architectures.
- Commercial Vehicles:Last-mile delivery vans and urban logistics trucks are driving torque demand into higher power bands. Fleet standardization committees at major logistics operators are consolidating sourcing decisions at the platform level rather than individual vehicle programs.
- Heavy-Duty Trucks:Regional haul and drayage applications are emerging as early adoption segments for 350+ kW e-axle configurations.
- Motorcycles:Electric two-wheelers in Asian urban corridors are driving compact, high-RPM motor specialization.
Passenger Vehicles retains volume leadership; Commercial Vehicles shows the steepest expansion trajectory.
Deployment:
Procurement authority concentration varies by fleet scale and platform standardization maturity.
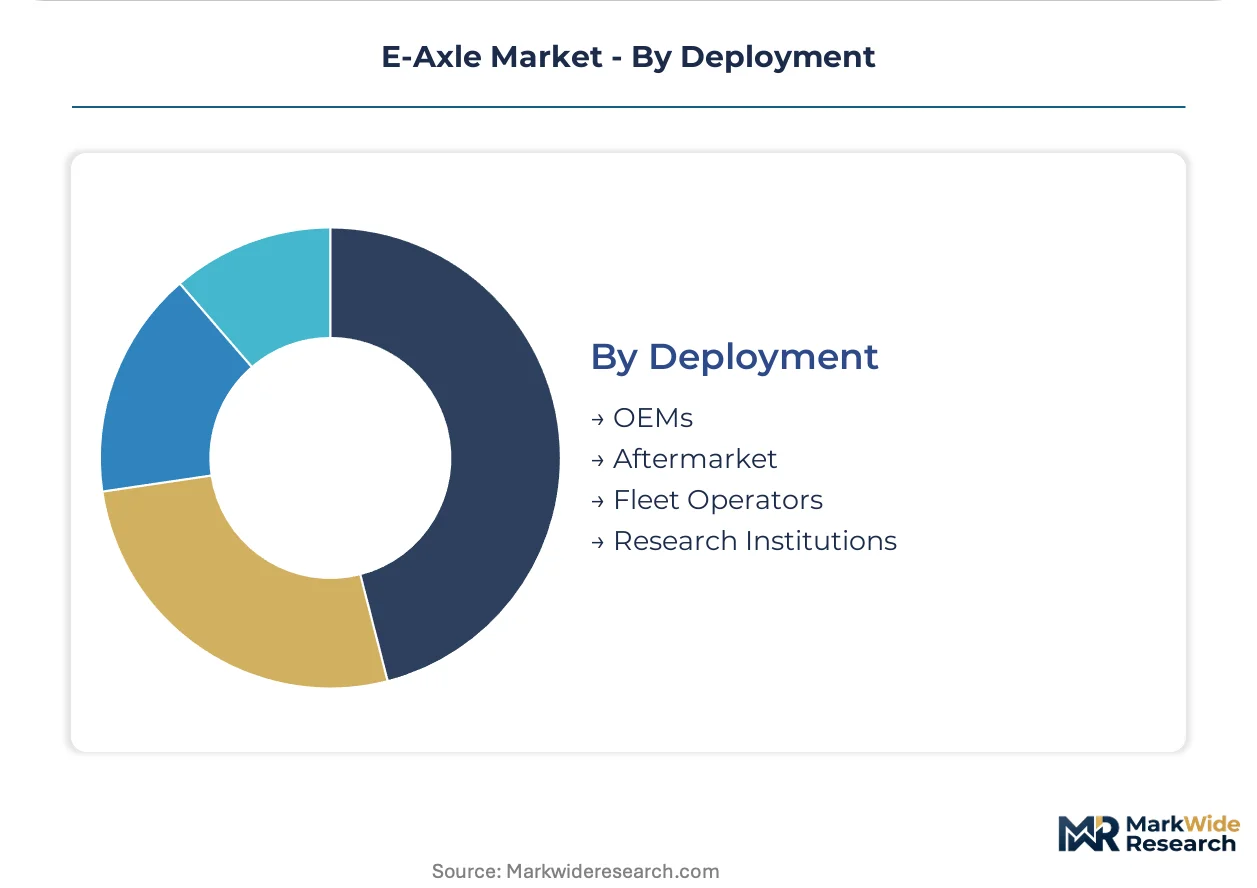
- OEMs:Control integrated drive module specifications for new vehicle platforms with 5-7 year development horizons. Tier-1 suppliers with captive semiconductor sourcing are capturing platform-architecture decisions early in design cycles.
- Fleet Operators:Amazon, FedEx, and UPS standardization committees are qualifying single e-axle designs across multiple van body configurations, concentrating purchasing power among three to four global suppliers.
- Aftermarket:Retrofit applications for existing chassis platforms remain limited by battery integration complexity and crashworthiness recertification requirements.
- Research Institutions:Universities and national laboratories are procuring modular configurations for powertrain benchmarking and thermal management validation studies.
OEMs dominate current procurement; Fleet Operators are consolidating sourcing authority fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart's premium automotive manufacturing corridor anchors global e-axle qualification activity as OEMs converge on integrated drive module architectures. Procurement authority concentrates in three national markets where regulatory mandates and industrial clustering reinforce supplier investment decisions. Each geography presents distinct qualification requirements shaped by local efficiency standards and fleet electrification timelines.
China
Domestic OEM procurement volumes surge under MIIT's NEV mandate and dual credit policy enforcement. GB standards for motor efficiency and electromagnetic compatibility gate foreign supplier market access through extended certification timelines. Yangtze River Delta manufacturing clusters around Shanghai host the densest concentration of integrated e-axle assembly capacity serving BYD and Geely platform programs.
Germany
Premium passenger vehicle OEMs specify 800-volt architectures for 2025 platform launches, compressing inverter thermal budgets. EU Green Deal manufacturing incentives attract power electronics assembly investments to Bavaria and Baden-Württemberg. Munich-Stuttgart corridor engineering centers qualify silicon carbide inverter designs for Mercedes-Benz and BMW skateboard chassis programs.
United States
Last-mile delivery fleet operators consolidate sourcing authority through Amazon, FedEx, and UPS standardization committees. NHTSA crashworthiness standards for battery-integrated chassis reshape e-axle mounting and isolation requirements. Michigan's automotive engineering corridor anchors Tier-1 supplier technical centers serving Detroit Three electrification programs.
South Korea
Hyundai-Kia platform architectures drive 150 kW compact motor procurement for B-segment crossover exports. MFDS automotive semiconductor packaging oversight extends to e-axle inverter materials certification. Seoul-Incheon manufacturing belt concentrates motor winding and precision gearbox machining capacity.
Japan
Compact high-RPM motor specialization serves urban micro-mobility and kei-car electrification segments. METI efficiency targets force synchronous motor redesigns across supplier portfolios. Nagoya-Toyota City industrial corridor hosts captive e-axle development for Toyota's dedicated battery-electric platform rollout.
E-Axle Market Key Industry Players
Strategic partnerships dominate the current landscape as Tier-1 suppliers secure semiconductor supply agreements and foundry capacity allocations. The vendor structure concentrates among integrated system specialists with captive power electronics capabilities, while mid-tier gearbox manufacturers face margin compression from thermal management capex requirements. Three archetypes define positioning: diversified automotive conglomerates with in-house semiconductor sourcing, dedicated e-mobility spin-offs with pure-play electrification portfolios, and industrial motor specialists leveraging high-RPM design expertise. Capacity expansion and backward integration into silicon carbide wafer supply represent the dominant competitive vectors.
Among German diversified conglomerates, Robert Bosch GmbH and ZF Friedrichshafen AG exemplify the integrated system archetype through their Stuttgart-based engineering centers. Continental AG occupies a position within the same tier, representing the legacy automotive supplier pivot toward electrification-dedicated business units. BorgWarner Inc. anchors the North American supplier vector, while Nidec Corporation exemplifies the industrial motor specialist archetype originating from Japanese precision manufacturing heritage.
| Leading Market Players |
|---|
| Continental AG |
| BorgWarner Inc. |
| Robert Bosch GmbH |
| Dana Incorporated |
| Schaeffler AG |
| ZF Friedrichshafen AG |
| Magna International Inc. |
| Cummins Inc. |
| Nidec Corporation |
| Others |
Cost & Logistics Intelligence
Silicon carbide MOSFET transitions simultaneously compress inverter manufacturing costs and redraw supplier power maps by rewarding foundry-scale players with captive wafer supply. China's MIIT efficiency mandates force synchronous motor redesigns that feed component standardization, while 800-volt platform migrations in Germany's premium corridor concentrate procurement authority among three to four integrated system specialists.
Pricing Analysis
Input-cost pass-through from rare earth magnet supply concentration in China's Inner Mongolia and Jiangxi provinces shapes motor pricing trajectories across supplier tiers. Three-tier pricing structure across premium, standard, and economy levels separates silicon carbide-enabled 800-volt inverters from silicon IGBT-based 400-volt modules from remanufactured service-exchange units. Cost compression in mid-tier integrated drive modules is intensifying because thermal management capex requirements strain balance sheets. Fleet operators at Amazon, FedEx, and UPS standardization committees exhibit highest price sensitivity through consolidated platform-level sourcing, while German premium OEMs in Stuttgart's manufacturing corridor demonstrate lowest sensitivity for silicon carbide-qualified designs.
Supply Chain Analysis
Dual-sourcing requirements from OEM platform engineers mandate multi-supplier qualification for silicon carbide wafers across Taiwan, South Korea, and Japan to mitigate single-source vulnerability. The e-axle supply chain draws from neodymium and dysprosium processing in China, precision die-casting capacity in Germany's Bavaria region, and motor winding automation in South Korea's Seoul-Incheon belt. Tariff exposure on Chinese-processed rare earth concentrates threatens margin stability for motor manufacturers without captive magnet recycling streams. Distribution runs through Tier-1 supplier technical centers in Michigan's automotive corridor, Stuttgart's engineering cluster, and Shanghai's Yangtze River Delta manufacturing belt serving domestic OEM platform programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The E-Axle Market reads as a late-cycle quality story where 800-volt silicon carbide architectures displace silicon IGBT-based designs across premium passenger vehicle procurement. Fleet standardization committees at major logistics operators now consolidate sourcing decisions at the platform level rather than delegating to individual vehicle program managers.
For Market Incumbents: Anchor platform-architecture decisions early in OEM design cycles by securing captive silicon carbide wafer supply agreements with foundry partners in Taiwan and South Korea. Deepen backward integration into precision die-casting capacity for liquid-cooled inverter housings to defend margin position against thermal management capex intensity. The priority lever centers on electromagnetic compatibility pre-certification investments that compress MIIT GB standards timelines by 4-6 months versus competitors relying on third-party testing houses. For New Entrants and Emerging Players: Silicon carbide inverter design specialization offers entry into the 200 kW commercial vehicle segment where fleet procurement teams seek alternatives to incumbent integrated system specialists. Target North American last-mile delivery electrification corridors where Amazon, FedEx, and UPS standardization committees qualify single e-axle designs across multiple van body configurations. Pursue direct motor winding contact thermal management partnerships with synthetic ester coolant formulators to bypass PFAS-based fluid restrictions delaying European product launches. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier gearbox manufacturers with precision machining heritage because thermal management capex requirements force consolidation among suppliers lacking balance sheet capacity for liquid-cooled housing investments. The acquisition target archetype combines captive motor winding automation with established OEM platform engineering relationships. Watch silicon carbide die cost convergence with silicon IGBTs at 150 kW power levels as the inflection indicator for mainstream vehicle segment penetration timing.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Foundry Partnership | Secures wafer supply allocation from Taiwan and South Korea for 800-volt inverter ramp. |
| Platform-Architecture Early Engagement | Captures OEM design decisions 5-7 years ahead of production through integrated drive module specifications. |
| Thermal Management Backward Integration | Controls precision die-casting investments for liquid-cooled inverter housings to sustain margin. |
| Electromagnetic Compatibility Pre-Certification | Compresses MIIT GB standards timelines through captive anechoic chamber testing capacity. |
| Fleet Standardization Committee Qualification | Concentrates purchasing power through single e-axle designs across Amazon, FedEx, and UPS van configurations. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with OEM platform engineers, Tier-1 supplier procurement leads, fleet standardization committee technical directors, and thermal management R&D specialists with secondary validation. Vehicle production databases, IHS Markit registration data, SEC 10-K filings from automotive suppliers, and MIIT GB standards documentation anchored the data foundation. Bottom-up e-axle unit shipment estimates triangulated against top-down OEM electrification platform announcements across the analysis window.
Comparable-period anchoring tied projection models to historical qualification timelines for integrated drive module architectures, spanning power rating segments from 100 kW through 250 kW across passenger vehicle, commercial vehicle, and heavy-duty truck applications. Segmentation dimensions modeled included integration architecture type, vehicle class, thermal management approach, and regional regulatory cluster. CAGRs derived from slope-consistent growth pattern matching against analogous electrification component markets. Forecast inputs incorporated silicon carbide adoption curves, rare earth magnet supply quota volatility, and fleet electrification total-cost-of-ownership calculations.
The model holds under sustained NEV mandate enforcement and dual credit policy continuity; deviation in China's rare earth export quota administration or REACH substance restriction acceleration on cooling fluids would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Off-Highway Electric Machine Battery Pack Systems Market
Electric Vehicles
US Automotive High Performance Electric Vehicle Market
Electric Vehicles
Electric Commercial Vehicle Market
Electric Vehicles
Middle-East and Africa E-Bike Market
Electric Vehicles
Global Solar Powered Car Market
Electric Vehicles
China Electric Vehicle Market
Electric Vehicles
Global Electric Vehicle (EV) Management Solution Market
Electric Vehicles
Netherlands Solar E-Bike Market
Electric Vehicles
Global Electric Classic Car Market
Electric Vehicles
Electric Pickup Truck Market
Electric Vehicles
Electric Vehicle (EV) Ball Bearings Market
Electric Vehicles
Asia-Pacific Electric Bus Market
Electric Vehicles
Electric Vehicle Panoramic Sunroof Market
Electric Vehicles
Electric All-Terrain Vehicle (ATV) Market
Electric Vehicles
Speed Pedelec E-Bike Market
Electric Vehicles
China Electric Car Market