
 E-SUV Market | 2026-2036
E-SUV Market Size, Share, and Industry Trends Forecast 2026-2036
E-SUV Market Foresight
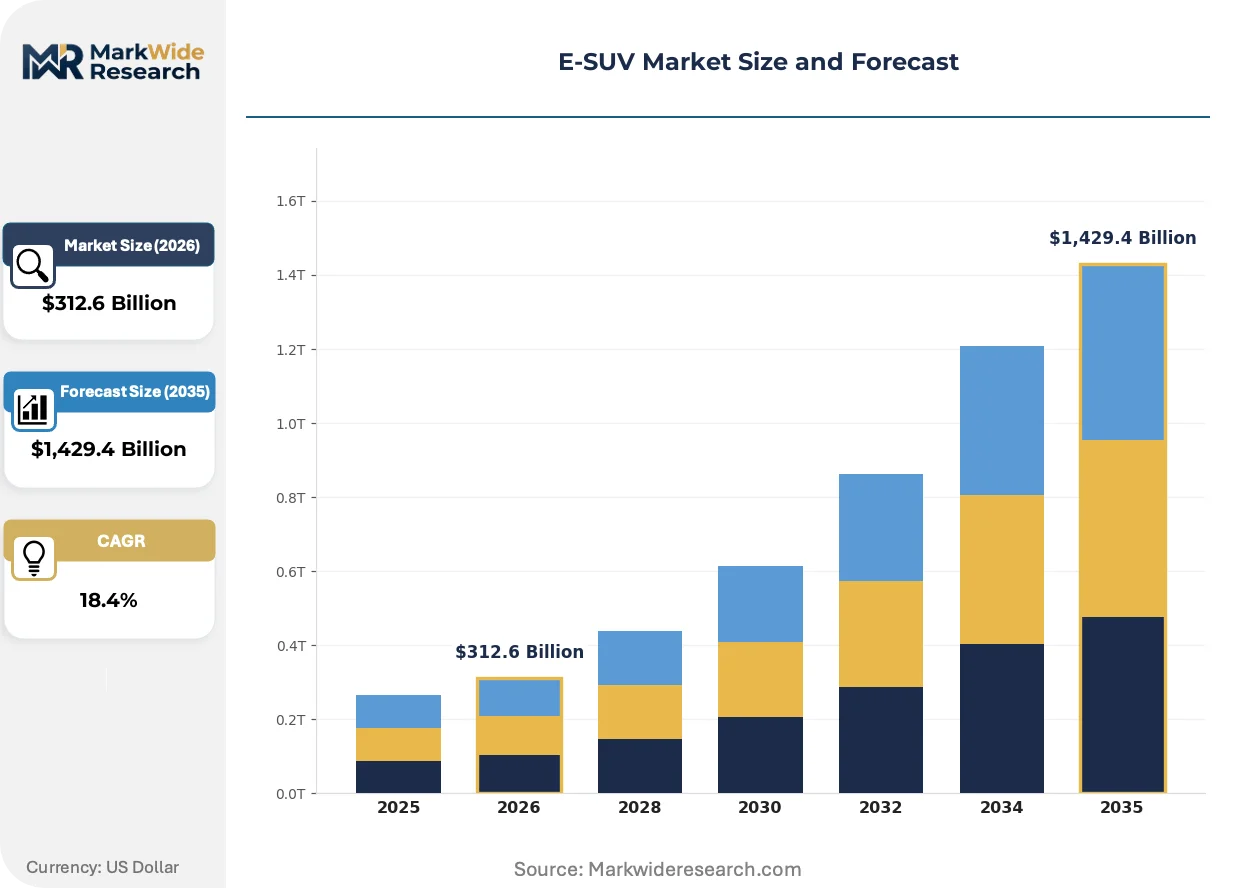
The EU F-Gas Regulation is expanding compliance burdens for thermal management suppliers while simultaneously accelerating R&D into CO2-based heat pumps and low-GWP refrigerant architectures. Tesla Inc. leverages its in-house cell production and supercharger network to sustain pricing power across premium E-SUV tiers. BYD Company Ltd. anchors its position through vertical integration into blade battery manufacturing and semiconductor fabrication. Volkswagen AG competes by extending its MEB platform across multiple E-SUV nameplates to amortize development costs.
An E-SUV is a sport utility vehicle propelled by one or more electric motors drawing energy from rechargeable battery packs or hydrogen fuel cells, typically offering ground clearance above 180 millimeters and curb weights exceeding two metric tons due to battery mass. These vehicles serve dual commercial purposes: private transportation with towing and all-weather capability, plus fleet deployment where total cost of ownership advantages materialize over high-utilization duty cycles. Battery Electric Vehicle powertrains dominate volume shipments while Plug-in Hybrid Electric Vehicle configurations retain share in markets with sparse fast charging availability. Full-size and Luxury vehicle types command disproportionate margin pools despite Compact and Midsize segments representing higher unit velocity.
The EPA tailpipe standards and California Air Resources Board mandates in the United States, alongside China's MIIT new energy vehicle credit system and the EU Green Deal's 2035 combustion phase-out, collectively reshape product planning cycles and factory retooling schedules. NHTSA crashworthiness protocols and UN ECE battery safety regulations add parallel certification layers that favor manufacturers with established regulatory affairs infrastructure. Stakeholders must monitor how charging interoperability standards and raw material sourcing disclosure requirements evolve to determine capital allocation between cell chemistry bets and platform flexibility investments.
Market Dynamics
Battery cell chemistry transitions and thermal management regulatory pressure are compressing development cycles faster than chassis platform renewal rates can accommodate.
Growth Catalysts
- EU F-Gas Regulation:The 2024 phase-down schedule for high-GWP refrigerants is accelerating supplier investment in CO2-based heat pump architectures for cabin and battery thermal control.
- Fleet electrification mandates:Corporate sustainability commitments across Germany, China, and the United States are pulling forward procurement timelines for zero-emission sport utility vehicles in high-utilization commercial applications.
- Solid-state cell architectures:Laboratory breakthroughs in sulfide and oxide electrolyte designs are enabling energy density gains that reduce pack mass and extend range without increasing footprint.
Market Restraints
- Lithium carbonate volatility:Concentrated South American brine and Australian hard-rock supply chains expose cell manufacturers to input cost swings that resist hedging through long-term contracts.
- Fast charging infrastructure gaps:Sparse high-power station density in rural and secondary highway corridors limits battery-electric powertrain viability for towing and long-haul use cases.
- UN ECE battery safety certification:Extended thermal runaway propagation testing timelines add six to nine months to homologation schedules for new pack designs.
Strategic Opportunities
- India's PLI scheme for advanced chemistry cells:Domestic manufacturing incentives are attracting pack assembly investments that could serve Southeast Asian export demand with lower logistics exposure.
- V2G integration with grid services:Bidirectional charging hardware convergence with utility demand-response programs is opening revenue streams for fleet operators during idle periods.
- Subscription-based ownership models:Battery-as-a-service contracts are decoupling vehicle purchase from energy storage capital, lowering entry barriers in price-sensitive compact segments.
Industry Challenges
- Thermal engineering talent scarcity:Competition for specialists in two-phase cooling and refrigerant system design is inflating compensation costs and extending hiring cycles.
- Platform retooling capex intensity:Dedicated E-SUV architectures require clean-sheet body shop investments that strain balance sheets during simultaneous battery plant construction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-SUV Market |
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $1,429.4 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Compact, Midsize, Full-size, Luxury Powertrain: Battery Electric Vehicle, Plug-in Hybrid Electric Vehicle, Hydrogen Fuel Cell, Others Charging Technology: Fast Charging, Wireless Charging, Level 2 Charging, Ultra-Fast Charging Market Segment: Private Users, Commercial Fleets, Car-Sharing Services, Ride-Hailing |
| Companies Covered | Tesla Inc., BYD Company Ltd., Hyundai Motor Company, Toyota Motor Corporation, Volkswagen AG, AB Volvo, Kia Corporation, Ford Motor Company, Honda Motor Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-SUV Market Shifts & Advancements
Cell-to-pack structural integration and software-defined thermal management are collapsing legacy subsystem boundaries while regulatory disclosure requirements reshape supplier qualification protocols.
Cell-to-pack architectures are eliminating module housings and integrating the battery enclosure as a structural chassis member. Automakers in China and Germany are adopting this design at scale for new dedicated platforms. The approach is decentralizing thermal management responsibility from discrete HVAC units to distributed cooling plates embedded within the pack structure.
The EU F-Gas Regulation's refrigerant phase-down timeline is forcing heat pump suppliers to validate CO2 transcritical cycles for sub-zero operation. Industrial consequence includes parallel engineering tracks for R-744 systems alongside low-GWP HFO blends. Full-size E-SUV segments targeting Nordic markets are prioritizing CO2 architectures despite higher compressor cost.
Fleet procurement teams are consolidating supplier relationships around vertically integrated cell-to-vehicle providers. Direct sourcing contracts are displacing tiered distributor networks for high-volume operators. This concentration is most visible in California and Germany where total cost of ownership modeling drives specification decisions.
E-SUV Market Segmentation
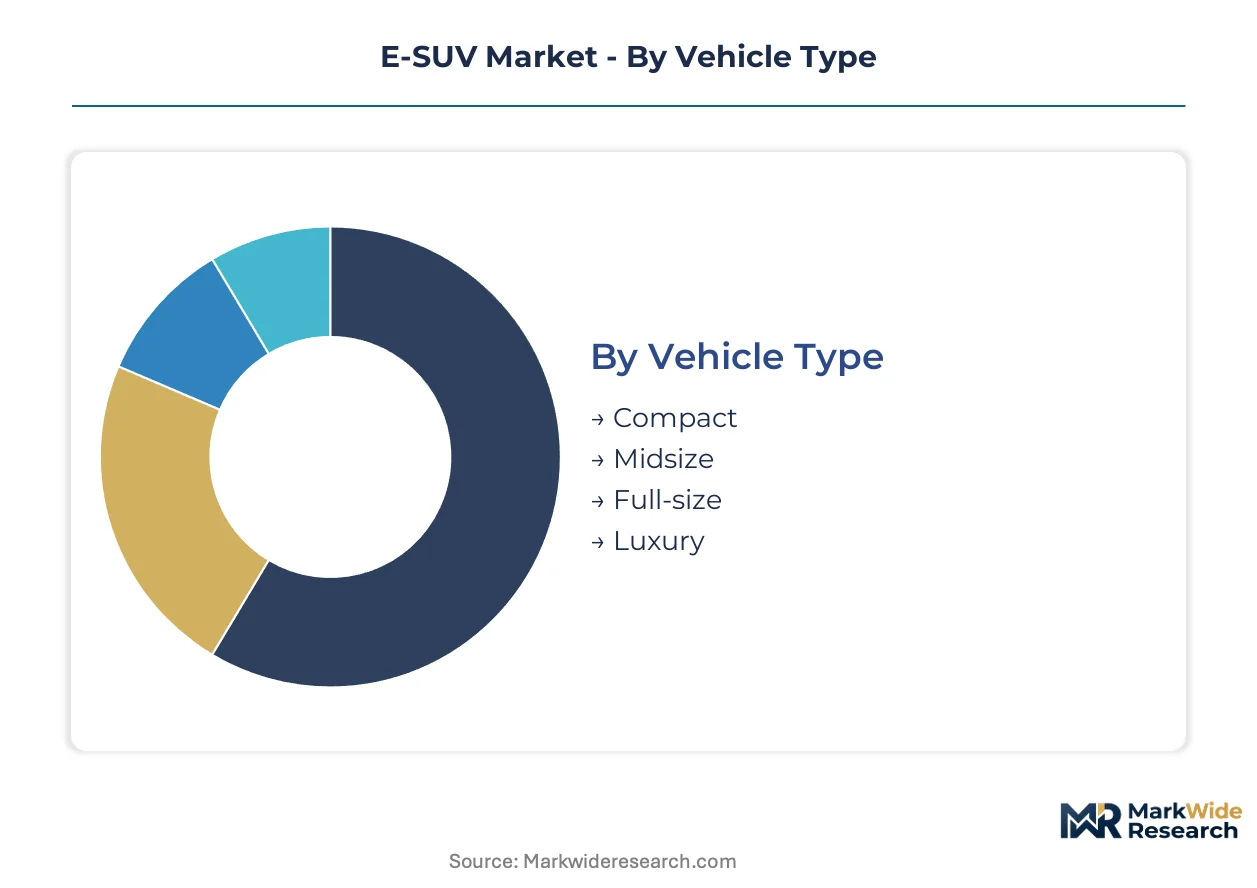
E-SUV segmentation reflects divergent upgrade cycles across vehicle classes and powertrain technologies. Fleet procurement teams prioritize total cost of ownership metrics while private buyers respond to charging infrastructure density and cabin technology refresh rates.
Vehicle Type:
Replacement cycles vary dramatically by footprint and price positioning, with compact segments turning over faster than full-size luxury nameplates.
- Compact:Urban-focused dimensions below 4.5 meters enable maneuverability in constrained Chinese and European city centers. German and Netherlands fleet operators favor this segment for last-mile logistics where parking scarcity dominates specification decisions.
- Midsize:The 4.7-4.9 meter footprint balances second-row accommodation with garage compatibility across US suburban and Chinese tier-two city households. This segment captures the highest absolute volume as it straddles single-vehicle family needs and dual-car household secondary slots.
- Full-size:Three-row seating configurations serve North American towing requirements and Chinese extended-family transport. Battery mass penalties exceed 600 kilograms versus comparable internal combustion architectures, compressing effective payload ratings.
- Luxury:Price points above 80,000 euros concentrate demand in California, Shanghai, and Munich where discretionary income and charging infrastructure density align. Materials specification and autonomous feature sets drive repurchase timing rather than functional obsolescence.
Midsize sits at the top of the volume ranking, with Compact climbing the fastest as urban congestion charges expand across European metropolitan areas.
Powertrain:
Technology cost curves and regulatory phase-out timelines are fragmenting procurement strategies across fleet and private channels.
- Battery Electric Vehicle:Lithium-ion cell packs dominate new platform engineering with energy densities approaching 300 watt-hours per kilogram in premium cell-to-pack architectures. China's MIIT credit system and California's ACC II mandates are pulling forward BEV share in those markets faster than infrastructure deployment elsewhere.
- Plug-in Hybrid Electric Vehicle:Dual-powertrain complexity adds 15-20% manufacturing cost but resolves range anxiety in German and US rural corridors where 150-kilowatt station density remains sparse. Fleet operators in secondary highway markets retain PHEV specifications for route flexibility.
- Hydrogen Fuel Cell:Proton exchange membrane stacks serve commercial full-size applications in Japan and South Korea where government-backed station buildouts support heavy-duty use cases. Passenger E-SUV volumes remain constrained by 70-megapascal infrastructure gaps.
- Others:Range-extender configurations and experimental sodium-ion architectures occupy niche positions in price-sensitive emerging markets.
Battery Electric Vehicle commands the volume lead, with Plug-in Hybrid Electric Vehicle expanding most quickly in markets bridging infrastructure buildout phases.
Charging Technology:
Power delivery specifications are becoming primary segmentation variables as fleet operators model downtime costs against hardware premiums.
- Fast Charging:Direct current systems at 50-150 kilowatts enable 30-minute replenishment cycles for intercity commercial routes. German autobahn corridor deployments and China's State Grid expansion are concentrating demand in those geographies.
- Ultra-Fast Charging:350-kilowatt liquid-cooled cable systems support 10-80% state-of-charge events in under 20 minutes for premium full-size E-SUVs. California's Electrify America network and IONITY's European corridor buildout are driving specification inclusion.
- Wireless Charging:Inductive pad systems at 11-22 kilowatts eliminate connector wear in taxi and ride-hail applications. Pilot deployments in Oslo and Shenzhen are validating operational economics for high-utilization fleets.
- Level 2 Charging:Alternating current residential and workplace systems at 7-19 kilowatts remain the dominant overnight solution for private garages across US single-family housing stock.
Fast Charging holds the volume position, with Ultra-Fast Charging gaining share fastest as 800-volt electrical architectures proliferate through premium vehicle tiers.
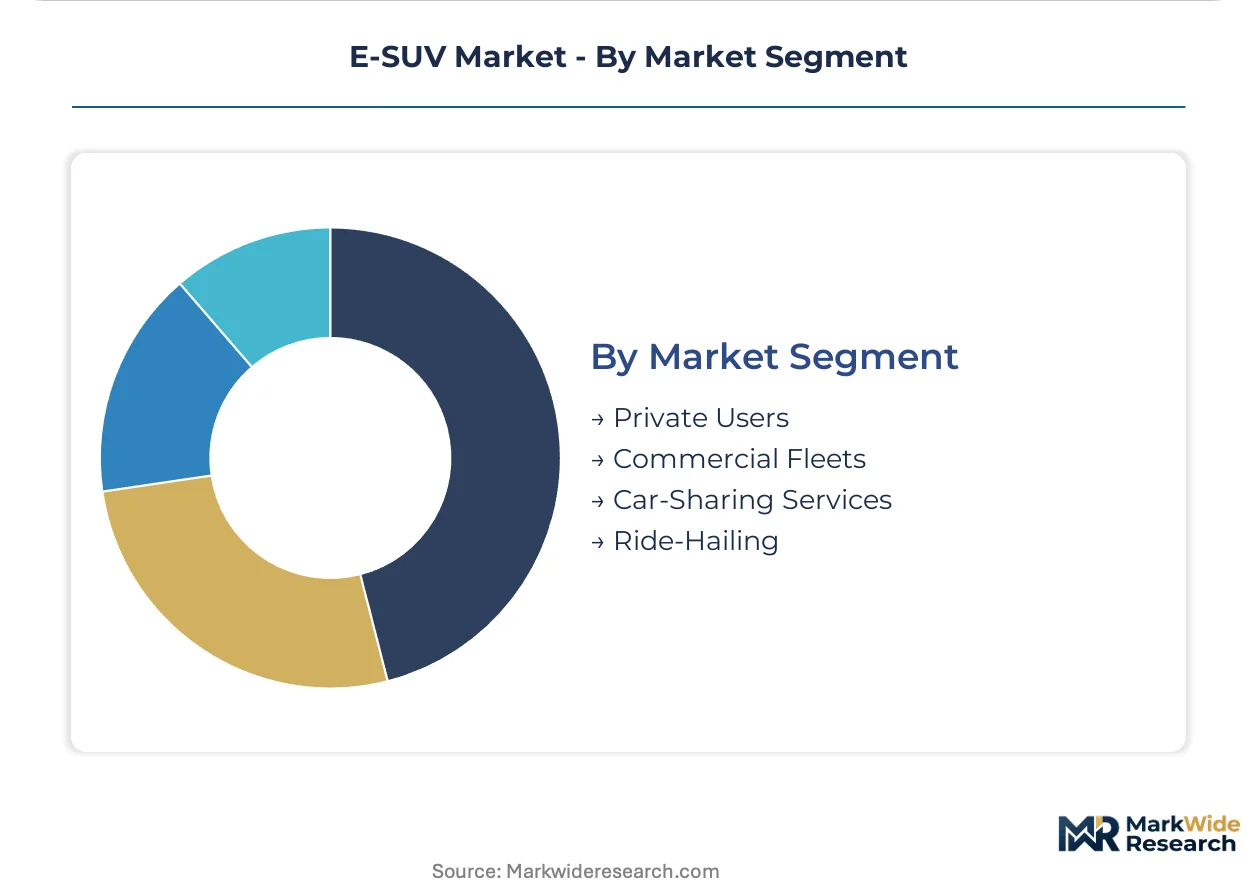
Market Segment:
Customer type determines specification emphasis, with commercial buyers prioritizing utilization rates and residual value modeling over private buyer technology preferences.
- Commercial Fleets:High-mileage operators in Germany and California calculate total cost of ownership over 150,000-kilometer duty cycles. Battery degradation warranties and service network density outweigh upfront capital differentials in procurement scoring.
- Private Users:Individual purchasers in China's tier-one cities and US coastal metros respond to purchase incentives and registration privilege programs. Home charging access and single-vehicle household constraints shape powertrain selection.
- Car-Sharing Services:Station-based and free-floating operators in Paris, Berlin, and Beijing require rapid interior cleaning protocols and damage-resistant trim specifications. Utilization targets above 40% per day mandate fast-charging compatibility.
- Ride-Hailing:Driver-owned and fleet-managed vehicles in London and New York face congestion charge exemptions and zero-emission zone compliance deadlines. Rear-seat comfort and ingress-ergonomics drive vehicle selection over driver-centric dynamics.
Commercial Fleets lead absolute volume, with Car-Sharing Services climbing the fastest as municipal permits increasingly mandate zero-emission fleet percentages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thermal engineering talent concentrates in Stuttgart, Shanghai, and Detroit, anchoring development centers for battery thermal management and electric drivetrain calibration. These clusters attract specialists from legacy powertrain programs undergoing forced transition.
China
MIIT's new energy vehicle credit system mandates annual BEV production quotas that OEMs must meet or purchase from competitors. The Yangtze River Delta hosts cell-to-pack manufacturing scale-ups where BYD and CATL suppliers co-locate near Shanghai port logistics. Local governments in Shenzhen and Hefei subsidize charging infrastructure density targets that exceed national minimums.
Germany
EU F-Gas Regulation refrigerant phase-down deadlines are compressing supplier validation timelines for CO2 heat pump architectures. Bavaria's automotive corridor from Munich to Ingolstadt houses Volkswagen Group's E-SUV platform engineering and BMW's battery competence center. KBA homologation protocols for battery thermal runaway testing add certification layers that favor established regulatory affairs teams.
United States
EPA tailpipe standards and California's ACC II mandates are pulling forward zero-emission fleet procurement timelines for commercial operators. Michigan's Detroit-to-Lansing corridor retains powertrain calibration expertise while Texas hosts Tesla's cell manufacturing and Nevada anchors Panasonic joint venture capacity. NHTSA crashworthiness protocols for heavy battery architectures favor manufacturers with existing safety engineering infrastructure.
South Korea
METI-aligned hydrogen station buildouts in Japan create export demand for Korean fuel cell stack suppliers targeting commercial full-size applications. Seoul Capital Area engineering centers for Hyundai and Kia are pivoting from combustion platform development to 800-volt electrical architectures. Busan-Ulsan manufacturing complexes are retooling for E-SUV export production targeting European and North American markets.
India
PLI scheme incentives for advanced chemistry cell manufacturing are attracting pack assembly investments from Korean and Chinese suppliers. Tamil Nadu's Sriperumbudur industrial belt hosts Hyundai and Kia final assembly with growing local component sourcing mandates. DGFT import duty structures on completely built units are accelerating domestic E-SUV platform development for cost-sensitive compact segments.
E-SUV Market Competitive Landscape
The competitive structure tilts toward vertically integrated battery producers with captive semiconductor supply. Three tiers have emerged: scale-driven platform amortizers, chemistry-specialist cell manufacturers, and software-defined thermal management integrators. Capacity expansion and strategic partnerships dominate competitive moves, with M&A activity concentrating on thermal engineering boutiques and charging network assets.
Within the integrated manufacturing tier, Tesla Inc. and BYD Company Ltd. exemplify archetypes of supercharger-networked premium positioning and blade battery vertical control respectively. Volkswagen AG occupies a platform-leveraging position across multiple nameplates. These three anchors represent divergent capital allocation strategies between in-house cell production, multi-brand architecture sharing, and charging infrastructure ownership.
| Leading Market Players |
|---|
| Tesla Inc. |
| BYD Company Ltd. |
| Hyundai Motor Company |
| Toyota Motor Corporation |
| Volkswagen AG |
| AB Volvo |
| Kia Corporation |
| Ford Motor Company |
| Honda Motor Co., Ltd. |
| Others |
Supply & Pricing Matrix
Fleet procurement consolidation around total cost of ownership modeling in Germany and California is forcing cell manufacturers to absorb lithium carbonate volatility through long-term contract structures rather than spot market exposure. This demand-side discipline compresses margin pools for pack assemblers lacking backward integration into cathode active material production.
Pricing Analysis
Battery-as-a-service unbundling from vehicle purchase is splitting pricing architectures between capital-light subscription tiers and traditional asset-ownership models. Three-tier pricing structure across premium, standard, and economy levels reflects cell chemistry grade, with NCM811 packs commanding 15-20% premiums over LFP alternatives for equivalent range ratings. Pricing pressure stems from fleet operator consolidation in North America and Europe, where procurement teams leverage volume commitments to extract service bundling concessions. Commercial fleet buyers exhibit highest price sensitivity due to residual value depreciation modeling, while luxury private buyers prioritize charging network access over upfront capital differentials.
Supply Chain Analysis
India's PLI scheme and China's MIIT localization mandates are reshaping sourcing footprints, requiring pack assembly investments within 500 kilometers of vehicle final assembly to qualify for incentive credits. Cathode active material production concentrates in China, South Korea, and Indonesia, with nickel sulfate processing drawing from Philippine laterite and Indonesian matte feedstocks. Cell manufacturers face single-source vulnerability for separator films and electrolyte salts, where Japanese and South Korean suppliers control 70% of qualified automotive-grade capacity. Distribution runs through OEM captive logistics networks for high-volume contracts, while spot procurement serves aftermarket replacement demand through regional battery distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities concentrate in battery manufacturing cost differentials between China's Yangtze River Delta and India's Tamil Nadu corridor, where labor and land costs diverge by 40-60% for equivalent automation levels.
For Market Incumbents: Acquire thermal engineering boutiques specializing in CO2 transcritical heat pump architectures before EU F-Gas Regulation phase-down deadlines eliminate refrigerant optionality. Defend position by extending cell-to-pack structural integration deeper into chassis platforms, raising capital barriers for competitors lacking clean-sheet architecture investments. Certification leverage at KBA and NHTSA creates switching costs for fleet operators dependent on rapid homologation cycles. For New Entrants and Emerging Players: Solid-state cell prototyping capabilities offer entry wedge into premium full-size segments where energy density premiums justify manufacturing cost penalties. Target India's compact E-SUV segment, where domestic content rules and DGFT duty structures protect local assemblers from Chinese import competition. Go-to-market through battery-as-a-service partnerships with ride-hail operators eliminates upfront capital barriers for driver-owned vehicles. For Investors and Strategic Acquirers: Asymmetric upside sits with semiconductor-integrated pack controllers, where analog chip shortages have concentrated supply among three qualified automotive suppliers. Five-to-ten-year viability hinges on 800-volt electrical architecture adoption rates across mid-tier OEMs, with charging infrastructure buildout serving as demand elasticity indicator. Monitor IONITY and Electrify America expansion capex as signal of premium segment demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Cell-to-Pack Structural Integration | Eliminates module housings and reduces pack mass by 15% in BYD and CATL architectures. |
| CO2 Heat Pump Validation | Meets EU F-Gas Regulation phase-down while extending sub-zero range retention for Nordic markets. |
| Battery Supply Agreement | Locks cathode active material capacity for Volkswagen MEB platform amortization across multiple nameplates. |
| Charging Infrastructure Partnership | Tesla's supercharger network opening to NACS adopters creates fleet operator lock-in through route planning integration. |
| Software-Defined Thermal Management | Enables over-the-air calibration updates that extend battery warranty periods without hardware replacement. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with OEM platform engineers, Tier 1 thermal management suppliers, fleet procurement directors, and charging network operators with secondary validation against vehicle production databases, MIIT credit system filings, SEC 10-K disclosures, and IHS Markit registration data. Bottom-up cell shipment modeling triangulated against top-down OEM production schedules.
Historical reference periods anchored the projection horizon to three complete vehicle platform cycles, capturing regulatory phase-in effects from EPA tailpipe standards and EU Green Deal implementation. Segmentation dimensions included vehicle class, propulsion architecture, charging technology tier, and regional production cluster. CAGRs derived from weighted average of technology adoption curves and infrastructure deployment rates, with solid-state cell commercialization timelines and lithium carbonate contract pricing serving as primary forecast sensitivity inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to charging infrastructure buildout pace and thermal runaway certification protocol changes at UN ECE. Projections reflect documented assumptions regarding cell chemistry cost curves and fleet electrification mandate enforcement. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
E-Rickshaw Market
Electric Vehicles
Africa Electric Scooter Market
Electric Vehicles
Global Electric Vehicles Engineering Plastics Market
Electric Vehicles
France Electric Bus Battery Pack Market
Electric Vehicles
Electric Vehicle Sound Generators Market
Electric Vehicles
Asia-Pacific Train Battery Market
Electric Vehicles
US Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
Fuel Cell Electric Vehicle (FCEV) Market
Electric Vehicles
48V Mild Hybrid Electric Vehicle (MHEV) Market
Electric Vehicles
Asia-Pacific Electric Vehicle (EV) Fluids Market
Electric Vehicles
Norway Electric Cars Market
Electric Vehicles
Asia-Pacific Lithium-Ion Battery for Electric Vehicle Market
Electric Vehicles
Electric Vehicle Battery Trays Market
Electric Vehicles
48V Mild Hybrid Battery Pack Systems Market
Electric Vehicles
Electric Vehicle High-Voltage DC-DC Converter Market
Electric Vehicles
Electric Commercial Vehicle Market