
 Dystrophic Epidermolysis Bullosa Market | 2026-2036
Dystrophic Epidermolysis Bullosa Market Size, Share, and Industry Trends Forecast 2026-2036
Dystrophic Epidermolysis Bullosa Market Intelligence
Subscription-based access to gene therapy manufacturing capacity is rebalancing how biopharma firms commercialize dystrophic epidermolysis bullosa treatments. Krystal Biotech leverages its viral vector platform to anchor production in North American markets. Castle Creek Biosciences sustains a differentiated position through autologous cell therapy specialization. Abeona Therapeutics competes on rare disease regulatory expertise and orphan drug positioning.
Dystrophic epidermolysis bullosa constitutes a group of inherited connective tissue disorders caused by mutations in the COL7A1 gene, resulting in defective type VII collagen and severe skin fragility with chronic wound formation. The condition demands sustained intervention across wound closure, infection prevention, pain modulation, and functional restoration. Gene therapies command the highest margin pools within product type segmentation due to curative intent and premium pricing dynamics. Hospitals dominate end user channels where centralized administration of advanced modalities occurs. Regenerative medicine within therapy area segmentation is attracting disproportionate R&D allocation as cell and gene platforms mature.
FDA breakthrough therapy designation accelerates review timelines for novel dystrophic epidermolysis bullosa modalities, while EMA PRIME eligibility streamlines European market access for priority medicines. ISO 14155 governs clinical investigation standards for these biologic interventions, ensuring data integrity across multinational trials. Stakeholders must monitor payer negotiation outcomes for gene therapies as these will determine commercial viability thresholds and patient access breadth.
Market Dynamics
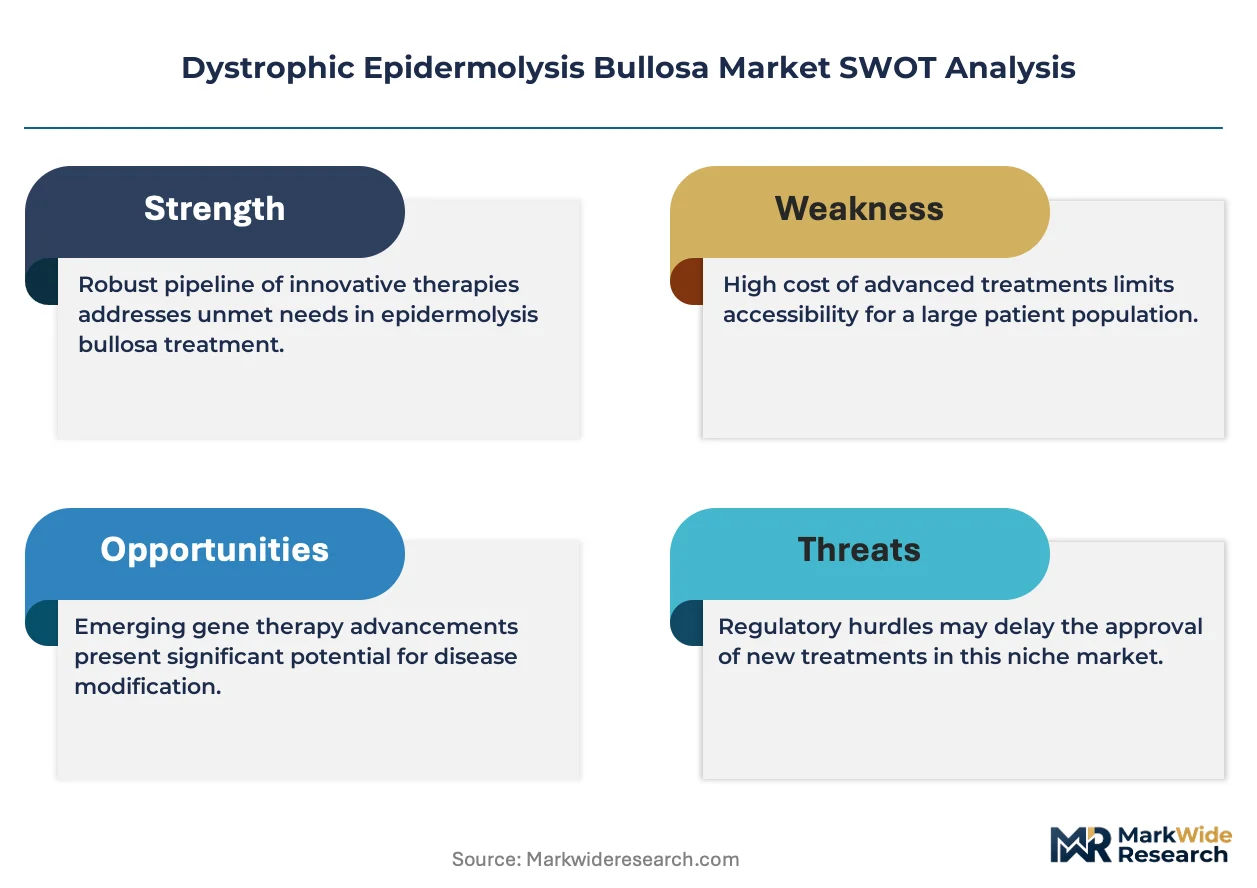
Gene therapy manufacturing capacity scarcity is concentrating competitive advantage among firms with captive viral vector production, while regulatory acceleration mechanisms compress development timelines for curative modalities.
Growth Catalysts
- FDA Breakthrough Therapy Designation:Expedited review pathways compress clinical development timelines for novel dystrophic epidermolysis bullosa gene therapies. Hospital-based dermatology units prioritize enrollment in designated trials.
- Type VII Collagen Restoration Platforms:Viral vector delivery systems enable functional correction of COL7A1 mutations at the dermal-epidermal junction. Academic medical centers anchor early adoption of these platforms.
- Specialized Wound Care Infrastructure:Concentrated demand in the United States, Germany, and Japan supports commercial viability of premium-priced curative interventions.
Market Restraints
- Viral Vector Supply Concentration:Contract development and manufacturing organizations in North America control critical AAV production capacity, creating bottleneck risk for late-stage programs.
- Reimbursement Uncertainty:Payer negotiation outcomes for single-administration gene therapies remain unresolved, threatening patient access breadth and manufacturer revenue recognition.
- Autologous Cell Therapy Complexity:Patient-specific manufacturing requirements extend production timelines and elevate cost structures compared to allogeneic alternatives.
Strategic Opportunities
- Pediatric Population Expansion:Early intervention protocols in neonatal dermatology units create demand for preemptive gene therapy administration before irreversible scarring manifests.
- EMA PRIME Eligibility:Accelerated assessment pathways for priority medicines streamline European market access and reduce regulatory capital requirements.
- Subscription-Based Manufacturing Access:Biopharma firms secure dedicated viral vector capacity through long-term offtake agreements, de-risking commercial scale-up.
Industry Challenges
- Gene Therapy Manufacturing Talent Scarcity:Viral vector process development and analytical characterization expertise concentrates at limited contract manufacturers and platform-integrated developers.
- ISO 14155 Compliance Complexity:Multinational clinical investigation standards demand harmonized data integrity protocols across disparate regulatory jurisdictions, extending study startup timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dystrophic Epidermolysis Bullosa Market |
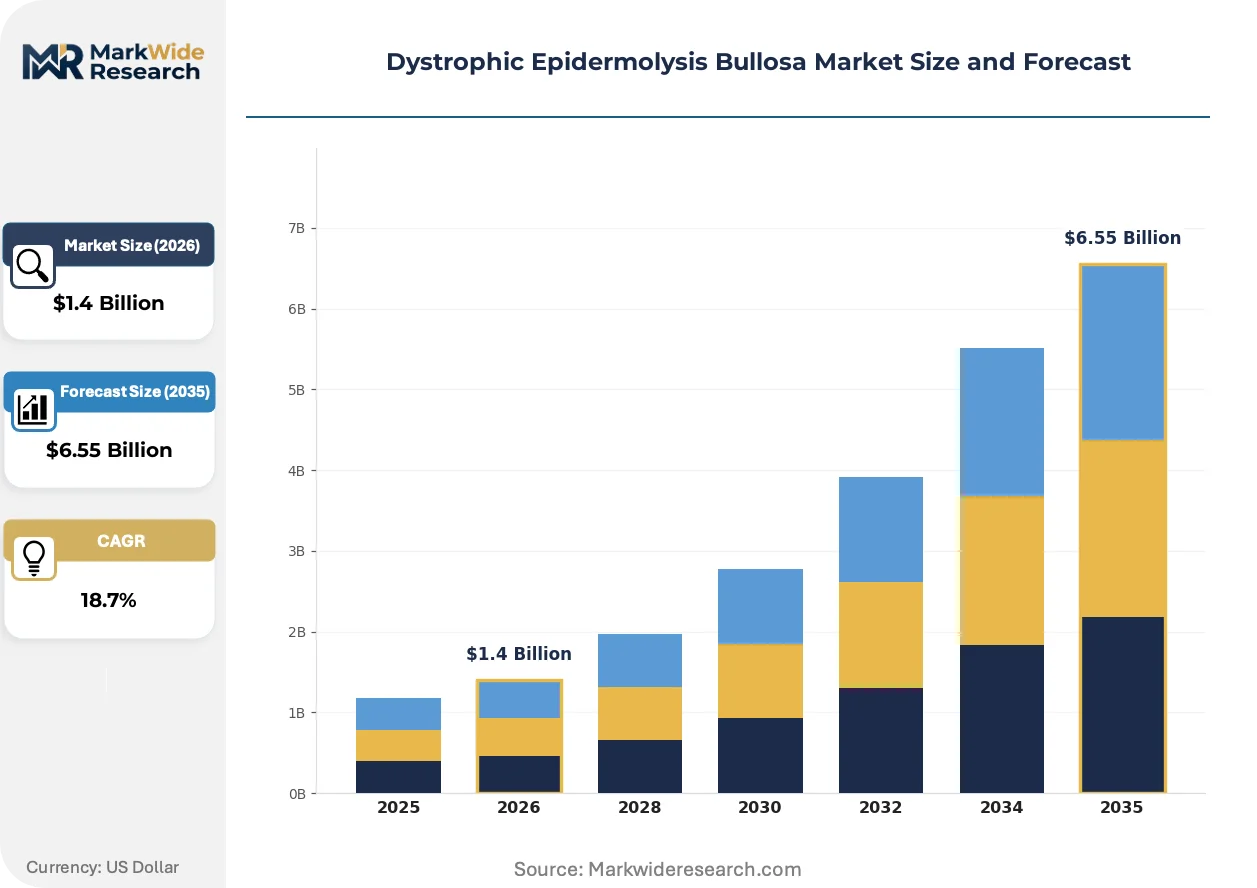
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $6.55 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Treatments, Gene Therapies, Wound Care Products, Systemic Therapies End User: Hospitals, Clinics, Research Institutions, Homecare Therapy Area: Dermatology, Genetics, Pain Management, Regenerative Medicine Delivery Mode: Transdermal, Injectable, Oral, Topical |
| Companies Covered | Krystal Biotech, Castle Creek Biosciences, Abeona Therapeutics, Amryt Pharma, Wings Therapeutics, Phoenix Tissue Repair, InMed Pharmaceuticals, RegeneRx, Holostem Terapie Avanzate, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dystrophic Epidermolysis Bullosa Market Strategic Shifts & Innovations
Curative intent is displacing chronic management as the dominant therapeutic paradigm, compressing investment allocation toward gene and cell platforms while wound care modalities face margin pressure.
Redosable non-viral gene delivery systems are integrating into early-stage development pipelines, offering repeat administration potential absent from first-generation AAV approaches. Academic dermatology centers in the United States and Germany are piloting these platforms for patients with pre-existing neutralizing antibodies. The structural consequence is a bifurcation in clinical development strategies, with viral vector specialists defending position through manufacturing scale while non-viral developers pursue regulatory differentiation.
EMA's PRIME eligibility scheme is compressing European market access timelines for rare disease gene therapies, creating competitive pressure on FDA breakthrough designation holders to pursue parallel submissions. The industrial consequence is a doubling of regulatory capital allocation toward European dossier preparation. Cell and gene therapy developers with orphan drug positioning are most affected, responding by embedding European regulatory expertise into core leadership structures.
Hospital procurement committees are unbundling gene therapy administration from traditional pharmaceutical purchasing frameworks, establishing distinct evaluation criteria for curative modalities. Academic medical centers with specialized wound care infrastructure are displacing community dermatology practices as the primary channel for advanced therapy access. This shift is most visible in the United States, where children's hospitals with established epidermolysis bullosa programs consolidate regional patient referral networks.
Dystrophic Epidermolysis Bullosa Market Segmentation
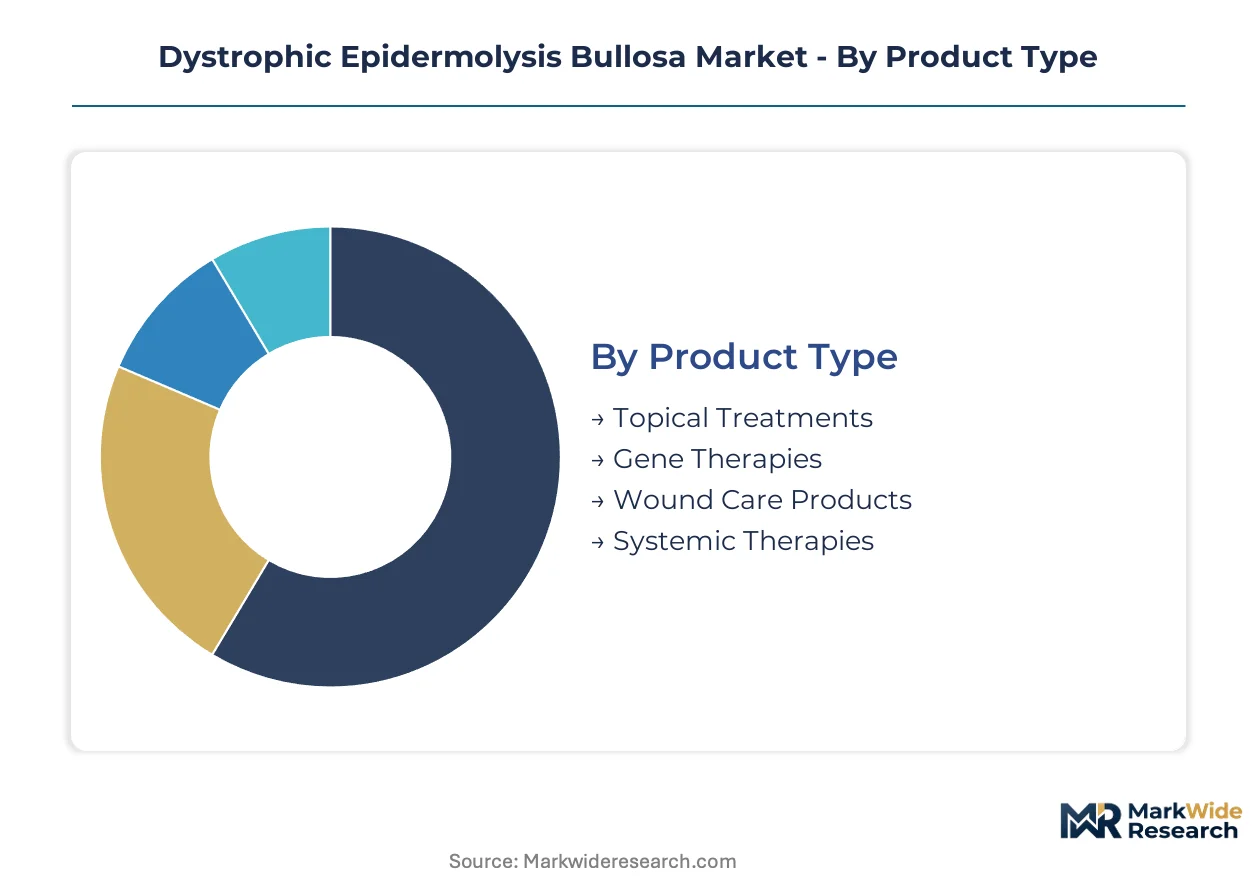
Segmentation in the dystrophic epidermolysis bullosa market reflects divergent commercial models across palliative versus curative intent. Product type stratification separates chronic wound management from one-time gene correction, while end user channels concentrate advanced modalities where specialized infrastructure exists.
Product Type:
Customization intensity varies sharply across this category, with patient-specific gene therapies demanding bespoke manufacturing versus standardized wound care formulations.
- Gene Therapies:Viral vector delivery of functional COL7A1 transgenes enables permanent correction of type VII collagen deficiency. Demand concentrates in academic medical centers across the United States, Germany, and Japan where FDA breakthrough-designated trials anchor early adoption. Premium pricing dynamics and curative intent position this segment at the apex of commercial margin pools.
- Wound Care Products:Advanced dressings, antimicrobial barriers, and biologic skin substitutes manage chronic lesion burden. Hospital procurement committees in specialized dermatology units drive volume, with reimbursement pathways more established than for gene modalities. Manufacturing scales through centralized production rather than patient-specific workflows.
- Topical Treatments:Emollients, corticosteroids, and antibiotic preparations address symptom management and infection prevention.
- Systemic Therapies:Oral and intravenous agents target pain modulation, pruritus control, and secondary complications.
Leading the category by volume: Wound Care Products. Expanding most quickly: Gene Therapies.
End User:
Channel concentration tracks therapy complexity, with invasive administration requiring infrastructure that fragments across institutional versus ambulatory settings.
- Hospitals:Centralized administration of gene therapies and advanced wound procedures occurs in academic medical centers with dedicated epidermolysis bullosa programs. Children's hospitals in the United States consolidate regional referral networks, while German university hospitals anchor European access. FDA and EMA regulatory designations prioritize enrollment at these sites.
- Clinics:Community dermatology practices manage stable patients with topical and oral regimens. Volume concentrates where payer reimbursement for specialty consultation remains favorable.
- Research Institutions:Early-phase clinical trials and natural history studies generate evidence for regulatory submissions.
- Homecare:Daily dressing changes and palliative support extend institutional protocols into residential settings.
Dominant by patient volume: Hospitals. Fastest channel expansion: Homecare.
Therapy Area:
R&D allocation intensity stratifies this category, with regenerative platforms attracting disproportionate capital versus established symptomatic management.
- Regenerative Medicine:Cell and gene platforms target functional restoration of dermal-epidermal junction integrity. Autologous fibroblast therapies and viral vector gene delivery command premium development investment. Academic medical centers in Japan and the United States pilot redosable non-viral alternatives for patients with pre-existing neutralizing antibodies.
- Dermatology:Conventional wound management, infection control, and scar mitigation constitute the clinical backbone. Established reimbursement and standardized protocols sustain volume despite margin compression.
- Genetics:Diagnostic confirmation, carrier screening, and prenatal testing support family planning decisions.
- Pain Management:Opioid-sparing protocols and neuropathic pain agents address chronic suffering.
Largest current allocation: Dermatology. Steepest investment trajectory: Regenerative Medicine.
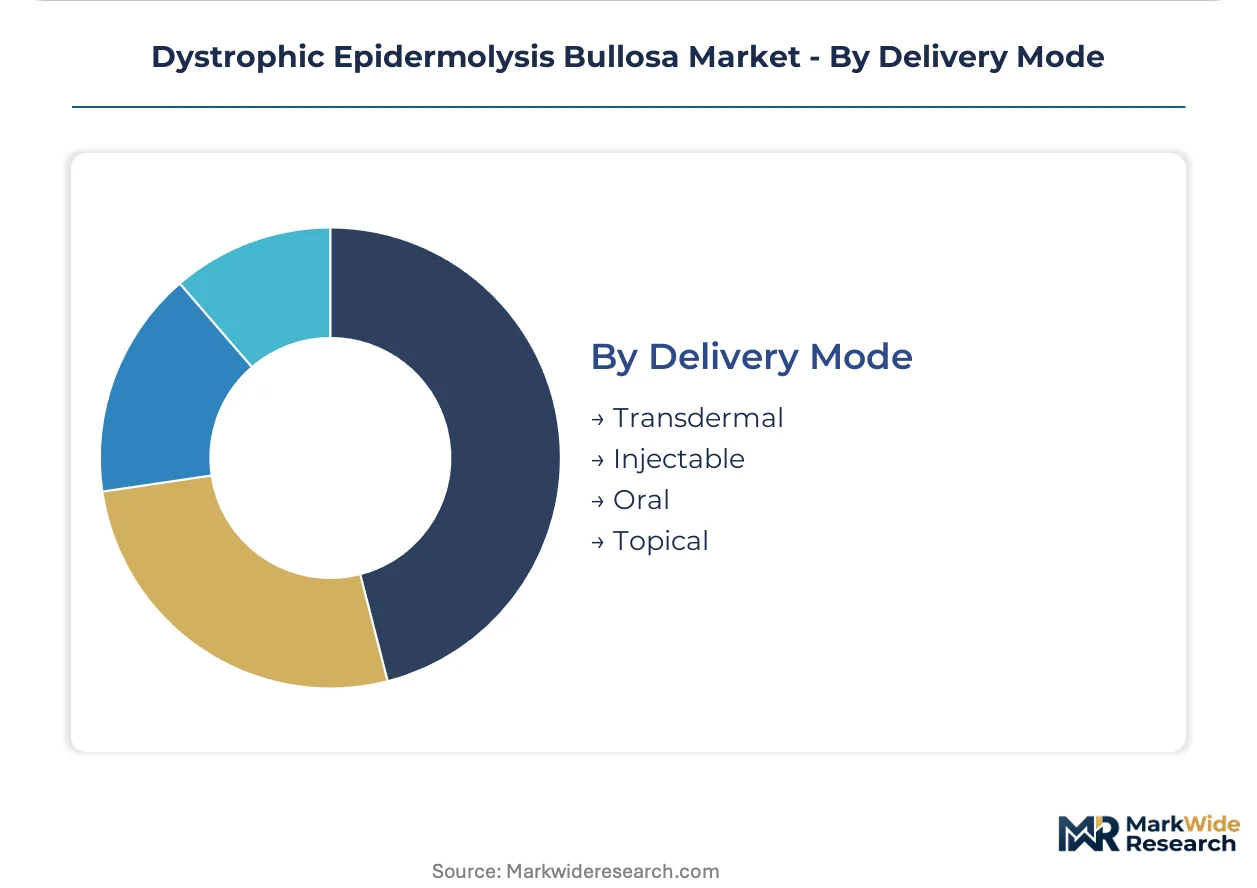
Delivery Mode:
Administration route determines manufacturing complexity and regulatory pathway, with injectable gene therapies facing distinct compliance burdens versus percutaneous alternatives.
- Injectable:Intradermal and intravenous gene therapy administration requires sterile compounding and specialized handling. Viral vector stability constraints concentrate production at captive North American facilities. FDA current good manufacturing practice oversight applies throughout cold chain distribution.
- Topical:Direct application to eroded skin surfaces dominates chronic management. Formulation stability and antimicrobial preservation drive manufacturing specifications.
- Transdermal:Patches and sustained-release systems offer controlled delivery for pain and pruritus.
- Oral:Systemic absorption targets pain, inflammation, and metabolic complications.
Highest volume: Topical. Gaining share fastest: Injectable.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of viral vectors and gene therapy manufacturing capacity concentrates in the United States, while patient demand distributes across developed markets with specialized wound care infrastructure. Consumption patterns diverge sharply between countries with FDA breakthrough-designated trial access and those awaiting EMA PRIME eligibility outcomes.
United States
Children's hospitals with dedicated epidermolysis bullosa programs anchor national patient referral networks, concentrating advanced therapy administration in academic medical centers. FDA breakthrough therapy designation accelerates clinical trial enrollment and compresses regulatory review timelines for novel gene modalities. Boston and Philadelphia clusters host captive viral vector production facilities serving North American supply requirements.
Germany
University hospitals in Munich and Heidelberg pilot redosable non-viral gene delivery platforms for patients with pre-existing neutralizing antibodies. EMA PRIME eligibility streamlines European market access pathways and reduces regulatory capital burdens for priority medicines. The country's centralized wound care infrastructure supports commercial viability of premium-priced curative interventions.
Japan
PMDA regulatory frameworks accommodate accelerated approval pathways for regenerative medicine products targeting rare genetic disorders. Academic dermatology centers in Tokyo and Osaka anchor early adoption of autologous cell therapy platforms. METI industrial policy supports domestic biomanufacturing capacity expansion for patient-specific therapeutic workflows.
United Kingdom
London and Cambridge clusters concentrate gene therapy process development expertise and analytical characterization capabilities. MHRA post-Brexit regulatory autonomy enables tailored assessment pathways for novel biologic interventions. NHS specialized commissioning frameworks determine patient access breadth for single-administration curative modalities.
Switzerland
Swissmedic regulatory standards align with EMA frameworks while maintaining independent assessment timelines for orphan drug designations. Basel and Zurich host contract development organizations serving European viral vector manufacturing requirements. The country's pharmaceutical industrial base supports translational research bridging academic discovery to clinical application.
Dystrophic Epidermolysis Bullosa Market Key Industry Players
Top-tier vendors anchor platform-integrated gene therapy development, while mid-cap specialists concentrate on autologous cell therapy manufacturing and rare disease regulatory navigation. The competitive structure stratifies across viral vector production scale, regulatory expertise depth, and captive manufacturing access. Three archetypes dominate: platform-integrated developers with in-house viral vector supply, cell therapy specialists with patient-specific manufacturing workflows, and orphan drug navigators with accelerated pathway experience. Capacity expansion through subscription-based manufacturing offtake agreements and strategic partnerships for European regulatory dossier preparation constitute the dominant competitive moves.
Within the platform-integrated tier, Krystal Biotech and Castle Creek Biosciences exemplify divergent manufacturing strategies—one leveraging viral vector production scale, the other sustaining autologous cell therapy specialization. Abeona Therapeutics occupies a position within the orphan drug navigator archetype, anchoring rare disease regulatory expertise. These three entities collectively represent the competitive spectrum spanning production infrastructure, therapeutic modality, and market access capability.
| Leading Market Players |
|---|
| Krystal Biotech |
| Castle Creek Biosciences |
| Abeona Therapeutics |
| Amryt Pharma |
| Wings Therapeutics |
| Phoenix Tissue Repair |
| InMed Pharmaceuticals |
| RegeneRx |
| Holostem Terapie Avanzate |
| Others |
Cost & Logistics Intelligence
Venture-backed gene therapy developers with captive viral vector production anchor supply-side discipline, translating manufacturing scarcity into premium pricing power for curative modalities while contract manufacturers extract tolling margins from capacity-constrained late-stage programs.
Pricing Analysis
Cost-down pressure on gene therapy administration accelerates as hospital procurement committees unbundle curative modalities from traditional pharmaceutical purchasing frameworks. Three-tier pricing structure across premium gene correction, advanced wound care, and palliative management reflects reimbursement pathway maturity and clinical outcome differentiation. Pricing pressure stems from unresolved payer negotiations for single-administration interventions, with children's hospitals least price-sensitive due to dedicated epidermolysis bullosa program funding and community dermatology practices most exposed to margin compression.
Supply Chain Analysis
Regional distribution centers in Boston and Philadelphia anchor North American viral vector cold chain logistics, feeding academic medical centers with specialized wound care infrastructure. Manufacturing concentration in the United States, Germany, and Japan draws from plasmid DNA substrates, HEK293 cell banks, and chromatography resins as critical inputs. Single-source vulnerability at contract development organizations creates bottleneck risk for AAV production campaigns. Distribution runs through hospital-based pharmacy compounding units rather than traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gene therapy manufacturing capacity scarcity is consolidating competitive advantage among platform-integrated developers, forcing autologous cell therapy specialists toward strategic partnership or exit as captive viral vector supply becomes table stakes for commercial viability.
For Market Incumbents: Deploy subscription-based manufacturing offtake agreements to lock in viral vector capacity before competitor enrollment accelerates. Deepen backward integration into plasmid DNA supply to reduce dependency on contract manufacturers with concentrated order books. Neutralize emerging non-viral gene delivery threats by piloting redosable platforms for patients with pre-existing neutralizing antibodies at German university hospitals. For New Entrants and Emerging Players: Redosable non-viral gene delivery technology offers the most penetrable wedge for patients excluded from first-generation AAV trials due to immunogenicity. Target pediatric dermatology units in Japan where PMDA accelerated approval pathways reduce regulatory capital requirements. Pursue licensing arrangements with academic medical centers holding natural history study data to compress clinical development timelines. For Investors and Strategic Acquirers: Distressed-cycle entries favor autologous cell therapy specialists with patient-specific manufacturing workflows in European markets awaiting EMA PRIME eligibility outcomes. Long-term viability hinges on regulatory dossier preparation capabilities and orphan drug designation maintenance. Watch FDA breakthrough therapy designation revocation decisions as the critical inflection signal for portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | FDA breakthrough designation compresses review timelines for novel COL7A1 gene therapies. |
| Manufacturing Scale-Up | Captive viral vector production de-risks commercial supply for hospital-based administration. |
| Regulatory Approval Pathway | EMA PRIME eligibility streamlines European market access for priority rare disease medicines. |
| Strategic Partnership | Long-term offtake agreements secure dedicated capacity at North American contract manufacturers. |
| Pipeline Diversification | Redosable non-viral platforms address patients with pre-existing AAV neutralizing antibodies. |
Research Approach
Document review covered FDA breakthrough therapy designations, EMA PRIME eligibility assessments, ClinicalTrials.gov registry entries, and hospital procurement database extracts, complemented by interviews with gene therapy development executives, regulatory affairs leads specializing in orphan drug pathways, hospital formulary directors at children's hospitals, and payer access specialists at national health technology assessment bodies. Bottom-up patient population estimates triangulated against top-down pharmaceutical revenue attribution across the analysis window.
Value outputs derive from segmented demand modeling across gene therapy, wound care, topical treatment, and systemic therapy product types, with patient volume projections calibrated to epidemiological prevalence data and treatment penetration assumptions. CAGRs were derived from logistic growth curve fitting anchored to historical adoption patterns in comparable rare disease gene therapy markets. Forecast inputs include regulatory designation timelines, manufacturing capacity expansion announcements, and reimbursement negotiation outcomes.
Several conditions sit outside the modeled scope, including preclinical-stage pipeline attrition, manufacturing facility regulatory inspection failures, and national health system budget reallocation shocks. Forecasts reflect documented assumptions regarding payer acceptance of single-administration curative pricing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Sanfilippo Syndrome Market
Rare Diseases
Erdheim-Chester Disease Market
Rare Diseases
Byler Disease Market
Rare Diseases
Orphan Diseases Market
Rare Diseases
Dravet Syndrome Market
Rare Diseases
Global Tyrosine Hydroxylase Deficiency Market
Rare Diseases
Achondrogenesis Market
Rare Diseases
Fragile X Syndrome Market
Rare Diseases
Niemann Pick Disease Market
Rare Diseases
Rare Inflammatory Disease Treatment Market
Rare Diseases
Yellow Nail Syndrome Treatment Market
Rare Diseases
Aarskog Scott Syndrome Treatment Market
Rare Diseases
Skeletal Dysplasia Market
Rare Diseases
Asia-Pacific Down Syndrome Market
Rare Diseases
Phelan-Mcdermid Syndrome Market
Rare Diseases
Rare Neurodegenerative Disease Treatment Market