
 Byler Disease Market | 2026-2036
Byler Disease Market Size, Share, and Industry Trends Forecast 2026-2036
Byler Disease Market Outlook
Gene-silencing oligonucleotides are displacing conventional bile acid sequestrants and is realigning therapeutic economics in progressive familial intrahepatic cholestasis. Gilead Sciences, Inc. leverages its nucleic acid delivery infrastructure to sustain pipeline momentum. Intercept Pharmaceuticals, Inc. anchors its position through farnesoid X receptor modulation expertise. Mirum Pharmaceuticals, Inc. differentiates via ileal bile acid transporter inhibition programs.
Byler disease denotes a rare autosomal recessive disorder caused by ATP8B1 mutations that impair bile acid secretion, leading to progressive cholestasis, pruritus, and hepatic fibrosis; diagnostic confirmation requires genetic sequencing alongside serum bile acid quantification and liver histopathology. Therapeutics command the largest revenue pool due to chronic administration requirements, while genetic testing represents the fastest-expanding application segment as newborn screening protocols broaden. Monitoring devices retain stable demand in hospital settings where transplant evaluation protocols necessitate serial assessment.
FDA orphan drug designation and EMA priority medicines status shape clinical trial investment and reimbursement pathways across North America and Europe. The country's national pharmaceutical regulator in Japan enforces stringent pediatric pharmacokinetic data requirements that filter market entrants. Stakeholders must weigh regulatory exclusivity timelines against gene therapy platform maturation when allocating R&D capital.
Market Dynamics
Gene-silencing oligonucleotides are compressing development timelines and displacing conventional bile acid sequestrants as the therapeutic backbone for progressive familial intrahepatic cholestasis, forcing incumbents to recalibrate platform investments.
Growth Catalysts
- FDA orphan drug exclusivity:Seven-year market exclusivity provisions incentivize rare disease pipeline investment, lowering effective cost of capital for ATP8B1-targeted programs.
- Newborn screening expansion:State-level mandates in Texas and California now include cholestasis panels, compressing diagnostic latency and expanding addressable patient pools.
- Specialist hepatology networks:Concentration of pediatric transplant centers in Boston, Heidelberg, and Tokyo creates referral density that accelerates therapeutic adoption curves.
Market Restraints
- Biologic manufacturing complexity:Oligonucleotide synthesis requires single-use reactor systems with limited global supplier base, constraining batch scale-up.
- Japan pediatric pharmacokinetic requirements:PMDA mandates dedicated juvenile toxicity studies that extend development timelines by 18-24 months for entrants lacking Japanese partnership infrastructure.
- Gene therapy substitution threat:AAV-based ATP8B1 correction programs in preclinical stages threaten to obsolete chronic administration models before oligonucleotide platforms achieve peak penetration.
Strategic Opportunities
- Companion diagnostic integration:FDA-cleared next-generation sequencing panels for ATP8B1 variants enable point-of-care genetic confirmation, unlocking newborn screening channel access.
- Real-world evidence frameworks:EMA adaptive pathways allow post-authorization efficacy confirmation, reducing pivotal trial size requirements for ultra-rare subsets.
- Academic medical center alliances:Partnerships with King's College Hospital and Cincinnati Children's Hospital Medical Center secure natural history data and accelerate regulatory dossier assembly.
Industry Challenges
- Genetic counseling workforce scarcity:Certified biochemical genetics counselors concentrate in fewer than forty US institutions, creating bottlenecks in patient identification and trial recruitment.
- Liver biopsy standardization:Inter-institutional variability in fibrosis staging protocols complicates endpoint harmonization across multinational trials, requiring centralized pathology review infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Byler Disease Market |
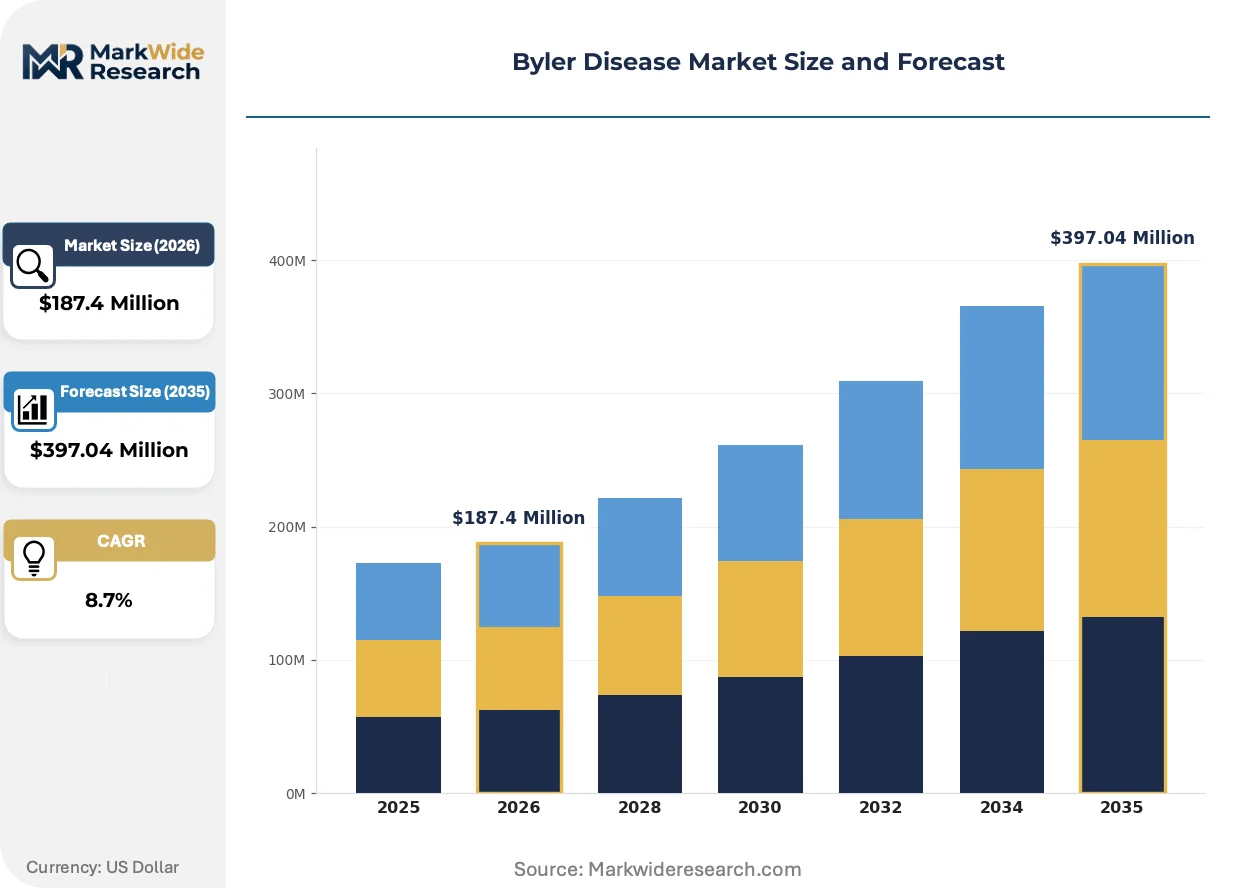
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostics, Therapeutics, Monitoring Devices, Research Tools End User: Hospitals, Clinics, Research Institutions, Home Care Settings Delivery Mode: Injection, Oral, Topical, Intravenous Application: Clinical Research, Patient Management, Symptom Relief, Genetic Testing |
| Companies Covered | Genfit SA, Gilead Sciences, Inc., Intercept Pharmaceuticals, Inc., Johnson & Johnson Services, Inc., Novartis International AG, Mirum Pharmaceuticals, Inc., Dicerna Pharmaceuticals, Inc., Shire plc, Albireo Pharma, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Byler Disease Market Strategic Shifts
Antisense oligonucleotide chemistry advances are compressing the therapeutic development cycle for monogenic cholestatic disorders, while regulatory science evolution and care model restructuring reshape how value is captured across the patient journey.
GalNAc-conjugated siRNA constructs targeting ATP8B1 mRNA are automating the previously manual process of bile acid flux modulation, enabling hepatocyte-specific knockdown without systemic exposure. Pediatric hepatology units at Toronto's Hospital for Sick Children and Paris's Bicêtre Hospital are adopting these platforms ahead of formal guidelines, compressing the gap between regulatory approval and clinical protocol integration. This automation of pharmacologic intervention is displacing the iterative dose-titration protocols that previously dominated pruritus management.
EMA's priority medicines scheme now mandates pediatric investigation plans for all novel cholestatic therapies, forcing developers to embed juvenile formulation development into phase I design rather than retrofitting post-approval. The industrial consequence is a 30-40% increase in early-phase program costs, offset by accelerated assessment timelines and conditional reimbursement pathways. Hepatology-focused biotechs with existing pediatric toxicology databases, particularly those with prior PIP approvals for other rare liver indications, are capturing disproportionate regulatory capital allocation.
Academic medical centers are consolidating cholestasis care into vertically integrated diagnostic-therapeutic hubs that bypass traditional referral networks. Cincinnati Children's Hospital Medical Center and King's College Hospital now offer same-week genetic sequencing, hepatology consultation, and trial enrollment, compressing the diagnostic odyssey from months to days. This hub concentration is most visible in Germany and the United Kingdom, where national rare disease strategies explicitly fund center-of-excellence designation for PFIC subtypes.
Byler Disease Market Segmentation
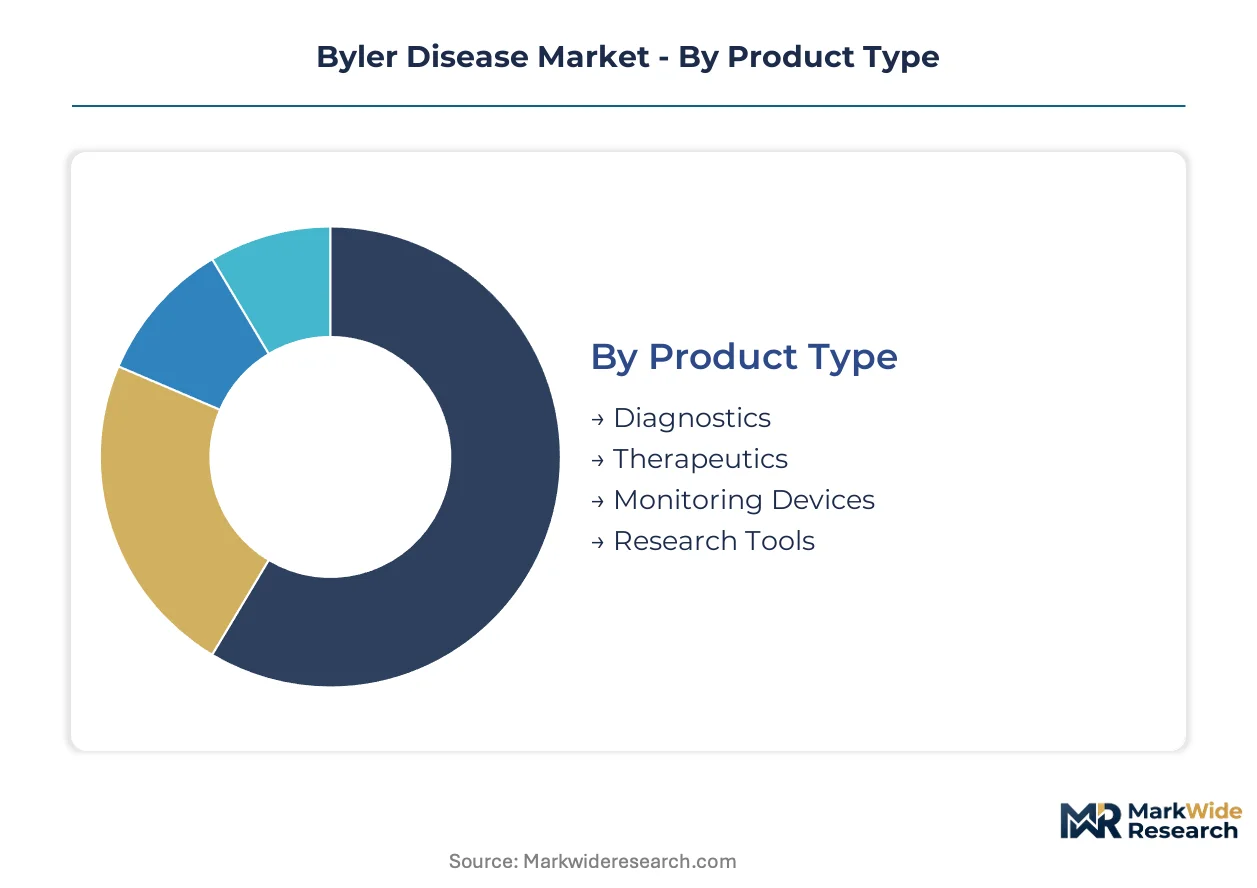
Segmentation in the Byler disease market reflects divergent regulatory pathways and reimbursement thresholds. Each category demands distinct certification strategies, from FDA-cleared companion diagnostics to EMA-adapted pediatric formulations.
Product Type:
FDA orphan drug designation applies to therapeutics, while diagnostics require CLIA laboratory certification and EMA in vitro diagnostic regulation compliance. Research tools face lighter oversight but limited reimbursement.
- Therapeutics:Chronic administration of bile acid modulators and gene-silencing oligonucleotides generates the largest revenue pool. Hospital-based adoption concentrates in pediatric transplant centers at Boston Children's Hospital and Cincinnati Children's Hospital Medical Center, where specialist hepatology networks accelerate protocol integration.
- Diagnostics:Next-generation sequencing panels for ATP8B1 variants require FDA premarket notification or EMA CE marking for clinical use. Demand clusters in Germany and Japan where newborn screening mandates for cholestasis panels have expanded, compressing diagnostic latency from months to days.
- Monitoring Devices:Liver function assessment tools for transplant evaluation protocols.
- Research Tools:Biomarker assay platforms and preclinical model systems for academic laboratories.
Leading the category by volume: Therapeutics. Growing fastest: Diagnostics.
End User:
Procurement authority and reimbursement rates vary sharply across settings, with academic medical centers commanding preferential pricing through trial enrollment leverage.
- Hospitals:Pediatric hepatology units at King's College Hospital and Toronto's Hospital for Sick Children integrate same-week genetic sequencing with therapeutic initiation. These vertically integrated hubs bypass traditional referral networks, capturing concentrated patient flows and accelerating adoption curves for novel modalities.
- Research Institutions:Natural history study sites and pivotal trial locations. Partnerships with academic medical centers secure regulatory dossier assembly advantages through existing pediatric toxicology databases.
- Clinics:Regional referral points for initial cholestasis workup and patient stabilization.
- Home Care Settings:Emerging channel for subcutaneous oligonucleotide administration and pruritus monitoring.
Hospitals dominate procurement value. Research institutions show the steepest expansion trajectory as EMA adaptive pathways reduce trial size requirements.
Delivery Mode:
Manufacturing complexity and cold chain requirements segment production economics, with oligonucleotide synthesis constraining batch scale-up.
- Injection:Subcutaneous GalNAc-conjugated siRNA constructs enable hepatocyte-specific ATP8B1 knockdown. Single-use reactor systems with limited global supplier base create manufacturing bottlenecks that favor incumbents with captive synthesis capacity.
- Intravenous:Hospital-administered formulations for acute decompensation episodes. Concentration in tertiary centers reflects nursing protocol requirements and transplant evaluation integration.
- Oral:Farnesoid X receptor modulators and bile acid sequestrants for maintenance therapy.
- Topical:Pruritus relief formulations with limited systemic absorption profiles.
Injection leads by revenue concentration. Intravenous protocols are gaining share fastest through hub-and-spoke care models.
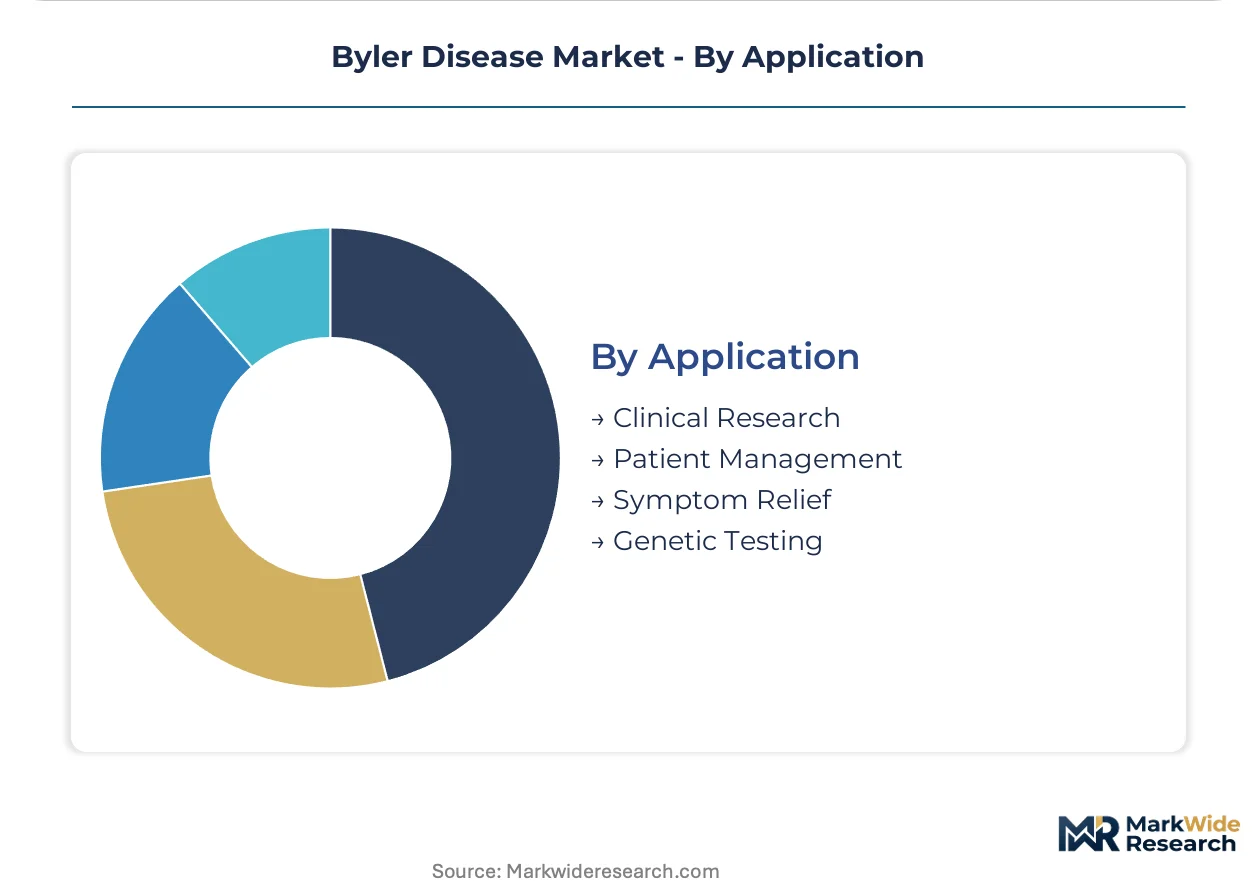
Application:
Reimbursement coding and evidence requirements differentiate commercial viability across use cases, with genetic testing commanding premium pricing through diagnostic confirmation necessity.
- Genetic Testing:ATP8B1 variant confirmation via next-generation sequencing represents the fastest-expanding application segment. State-level mandates in Texas and California now include cholestasis panels, directly expanding addressable testing volume.
- Patient Management:Longitudinal care coordination across transplant evaluation protocols. EMA priority medicines status and FDA orphan drug exclusivity reshape trial economics for chronic administration models.
- Clinical Research:Natural history studies and pivotal trials at designated centers of excellence.
- Symptom Relief:Pruritus management and nutritional support interventions.
Patient management generates the largest revenue base. Genetic testing climbs the fastest as newborn screening protocols broaden across multiple jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialist hepatology networks in the United States, Germany, and Japan concentrate diagnostic capacity and therapeutic adoption. FDA orphan drug incentives and EMA pediatric investigation plans reshape trial economics across these jurisdictions. Hospital-based care models in each country compress diagnostic latency and accelerate protocol integration.
United States
Pediatric transplant centers at Boston Children's Hospital and Cincinnati Children's Hospital Medical Center anchor therapeutic demand. FDA orphan drug designation provides seven-year market exclusivity for ATP8B1-targeted programs. State-level newborn screening mandates in Texas and California now include cholestasis panels, expanding addressable patient pools.
Germany
Heidelberg University Hospital and Hamburg's pediatric hepatology units drive referral density for progressive familial intrahepatic cholestasis. EMA priority medicines status mandates pediatric investigation plans, accelerating assessment timelines for novel modalities. The country's national rare disease strategy funds center-of-excellence designation for PFIC subtypes.
Japan
PMDA enforces stringent pediatric pharmacokinetic data requirements that filter market entrants without Japanese partnership infrastructure. METI coordinates national newborn screening expansion for cholestatic disorders. Tokyo's specialist hepatology networks concentrate transplant evaluation protocols and trial enrollment capacity.
United Kingdom
King's College Hospital offers same-week genetic sequencing and therapeutic initiation, bypassing traditional referral networks. EMA adaptive pathways enable post-authorization efficacy confirmation for ultra-rare subsets. The NHS rare disease strategy consolidates cholestasis care into vertically integrated diagnostic-therapeutic hubs.
Switzerland
Swissmedic maintains alignment with EMA regulatory frameworks while offering expedited review for pediatric rare disease therapies. Basel and Zurich host concentrated biopharma R&D infrastructure supporting oligonucleotide platform development. Academic medical center alliances secure natural history data for regulatory dossier assembly.
Byler Disease Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with nucleic acid delivery platforms commanding premium positioning against conventional bile acid modulators. The market structure tilts toward consolidated therapeutic development, where gene-silencing oligonucleotides displace earlier-generation sequestrants. Three archetypes dominate: hepatology-focused biotechs with pediatric toxicology databases, large-cap pharmas leveraging nucleic acid infrastructure, and rare disease specialists with regulatory exclusivity track records. Competitive moves concentrate on academic medical center alliances and companion diagnostic integration.
Within the large-cap pharma tier, Gilead Sciences, Inc. and Novartis International AG occupy positions anchored by nucleic acid delivery infrastructure and rare disease commercialization experience. Among hepatology-focused specialists, Intercept Pharmaceuticals, Inc. and Mirum Pharmaceuticals, Inc. exemplify farnesoid X receptor modulation and ileal bile acid transporter inhibition expertise respectively. Genfit SA represents the European contingent with metabolic disease positioning. These companies collectively illustrate the competitive tension between platform breadth and indication-specific depth.
| Leading Market Players |
|---|
| Genfit SA |
| Gilead Sciences, Inc. |
| Intercept Pharmaceuticals, Inc. |
| Johnson & Johnson Services, Inc. |
| Novartis International AG |
| Mirum Pharmaceuticals, Inc. |
| Dicerna Pharmaceuticals, Inc. |
| Shire plc |
| Albireo Pharma, Inc. |
| Others |
Value Chain & Pricing Dynamics
Pediatric transplant centers in Boston, Heidelberg, and Tokyo are consolidating procurement authority through vertically integrated care hubs, forcing suppliers to qualify across multiple hospital systems simultaneously and compressing price negotiation leverage for single-site manufacturers. This buyer concentration is reshaping how oligonucleotide producers structure volume discounts and service bundling.
Pricing Analysis
Volume concentration in hospital-based procurement splits margin capture between high-volume academic medical centers and lower-volume regional clinics. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and after-sales clinical support intensity. Cost compression in the standard tier is intensifying because of manufacturing scale constraints in single-use reactor systems. Regional clinics exhibit the highest price sensitivity due to limited formulary budgets, while transplant centers prioritize clinical outcomes over unit cost.
Supply Chain Analysis
Dual-sourcing requirements mandated by hospital procurement committees in the United States, Germany, and Japan force oligonucleotide developers to qualify backup synthesis partners, extending supplier onboarding timelines. Manufacturing draws from specialized single-use reactor systems, phosphoramidite reagents, and GalNAc conjugation chemistries anchored in Switzerland, the United States, and Singapore. Single-source vulnerability in phosphoramidite supply creates exposure to batch failure cascades. Distribution runs through cold-chain logistics partners serving tertiary pediatric centers directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Byler disease market is becoming a vertical-integration race as developers pursue captive control over GalNAc conjugation chemistry to secure manufacturing slots and protect margin structure against biologic CDMO scarcity.
For Market Incumbents: Deploy pediatric toxicology database leverage to accelerate regulatory dossiers ahead of gene therapy substitution threats. Secure exclusive synthesis partnerships with single-use reactor operators in Switzerland and Singapore to bottleneck competitor scale-up. Deepen academic medical center alliances at Cincinnati Children's Hospital Medical Center and King's College Hospital to lock referral channel access. For New Entrants and Emerging Players: The premium-to-economy price-point gap in genetic testing services offers entry through CLIA-certified laboratory partnerships targeting state newborn screening expansion in Texas and California. White-space concentration sits in home care settings for subcutaneous oligonucleotide administration, where nursing protocol standardization remains underdeveloped. Pursue companion diagnostic co-development with sequencing platform vendors to bypass hospital procurement gatekeeping. For Investors and Strategic Acquirers: The window for entry favors hepatology-focused biotechs with existing PIP approvals and captive nucleic acid delivery infrastructure. Long-term viability hinges on positioning ahead of AAV-based ATP8B1 correction programs reaching clinical stages. Watch for PMDA partnership infrastructure announcements as the inflection signal for Japanese market access capability.| Strategic Initiative | Industry Significance |
|---|---|
| GalNAc Conjugation Capacity Expansion | Captive synthesis control insulates against CDMO bottlenecks for siRNA constructs. |
| Pediatric Investigation Plan Submission | EMA priority medicines status unlocks accelerated assessment timelines for novel modalities. |
| Companion Diagnostic Co-Development | FDA-cleared ATP8B1 sequencing panels secure newborn screening channel access. |
| Academic Medical Center Alliance | Partnerships with Cincinnati Children's Hospital compress diagnostic-to-treatment latency. |
| Japanese Partnership Infrastructure | PMDA juvenile toxicity study capabilities filter market entrants without local presence. |
Study Parameters
FDA orphan drug filings, EMA pediatric investigation plan submissions, and ClinicalTrials.gov registry data formed the secondary backbone for therapeutic pipeline mapping. Primary interviews with pediatric hepatologists, regulatory affairs leads at rare disease biotechs, hospital procurement managers at designated transplant centers, and payer access specialists were combined with secondary validation. Bottom-up patient flow modeling and top-down revenue triangulation anchored market size estimation.
Historical trendline analysis of gene-silencing oligonucleotide approvals and bile acid modulator pricing trajectories informed the projection framework. Segmentation dimensions modeled include product type, delivery mode, end-user setting, and regional regulatory cluster across the analysis window. CAGR derivation incorporated newborn screening mandate expansion rates, pediatric formulation development timelines, and transplant center concentration patterns.
Inputs from FDA and EMA regulatory databases were available through the study window; gaps in real-world pricing transparency for hospital-administered biologics introduce uncertainty bands around revenue forecasts. Deviation in gene therapy clinical trial readouts would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Gaucher Disease Drugs Market
Rare Diseases
Europe Rett Syndrome Market
Rare Diseases
Lennox-Gastaut Syndrome Market
Rare Diseases
North America Rett Syndrome Market
Rare Diseases
Global Gaucher Disease Market
Rare Diseases
Metachromatic Leukodystrophy Market
Rare Diseases
Churg Strauss Syndrome Market
Rare Diseases
Rare Diseases Treatment Market
Rare Diseases
Erdheim-Chester Disease Market
Rare Diseases
Krabbe Disease Treatment Market
Rare Diseases
Fabry Disease Market
Rare Diseases
Congenital Adrenal Hyperplasia Market
Rare Diseases
Zellweger Spectrum Disorders Market
Rare Diseases
Menkes Syndrome Market
Rare Diseases
Gastrointestinal Rare Diseases Treatment Market
Rare Diseases
Rare Neurological Disease Treatment Market