
 Sanfilippo Syndrome Market | 2026-2036
Sanfilippo Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Sanfilippo Syndrome Market Intelligence
Buyer concentration among pediatric academic medical centers is pivoting as regional children's hospitals build dedicated lysosomal storage disorder programs. Denali Therapeutics leverages its blood-brain barrier platform to differentiate its pipeline assets. GC Biopharma sustains manufacturing scale through its established enzyme production infrastructure. Ultragenyx Pharmaceutical anchors its position via deep rare disease commercial expertise across North American and European markets.
Sanfilippo syndrome comprises four subtypes (A, B, C, D) of mucopolysaccharidosis caused by single-gene enzyme deficiencies that allow heparan sulfate accumulation, progressively destroying neural tissue and resulting in severe cognitive decline before age five. The condition demands interventions capable of crossing the blood-brain barrier to address central nervous system pathology. Gene therapy commands the fastest-growing investment pool as vector delivery technologies mature, while intrathecal administration routes attract clinical focus due to their direct CNS access. Enzyme replacement therapy occupies the most mature commercial position despite limited neurological efficacy. Substrate reduction therapy competes for development resources as an oral alternative with broader tissue distribution potential.
The FDA's Rare Disease Priority Review Voucher program and EMA's PRIME designation framework shape competitive timelines by rewarding developers of therapies for ultra-rare pediatric conditions. Japan's PMDA operates an analogous Sakigake designation that accelerates access for innovative treatments in lysosomal storage disorders. Stakeholders must monitor evolving gene therapy reimbursement negotiations and manufacturing capacity constraints as pivotal decision points.
Market Dynamics
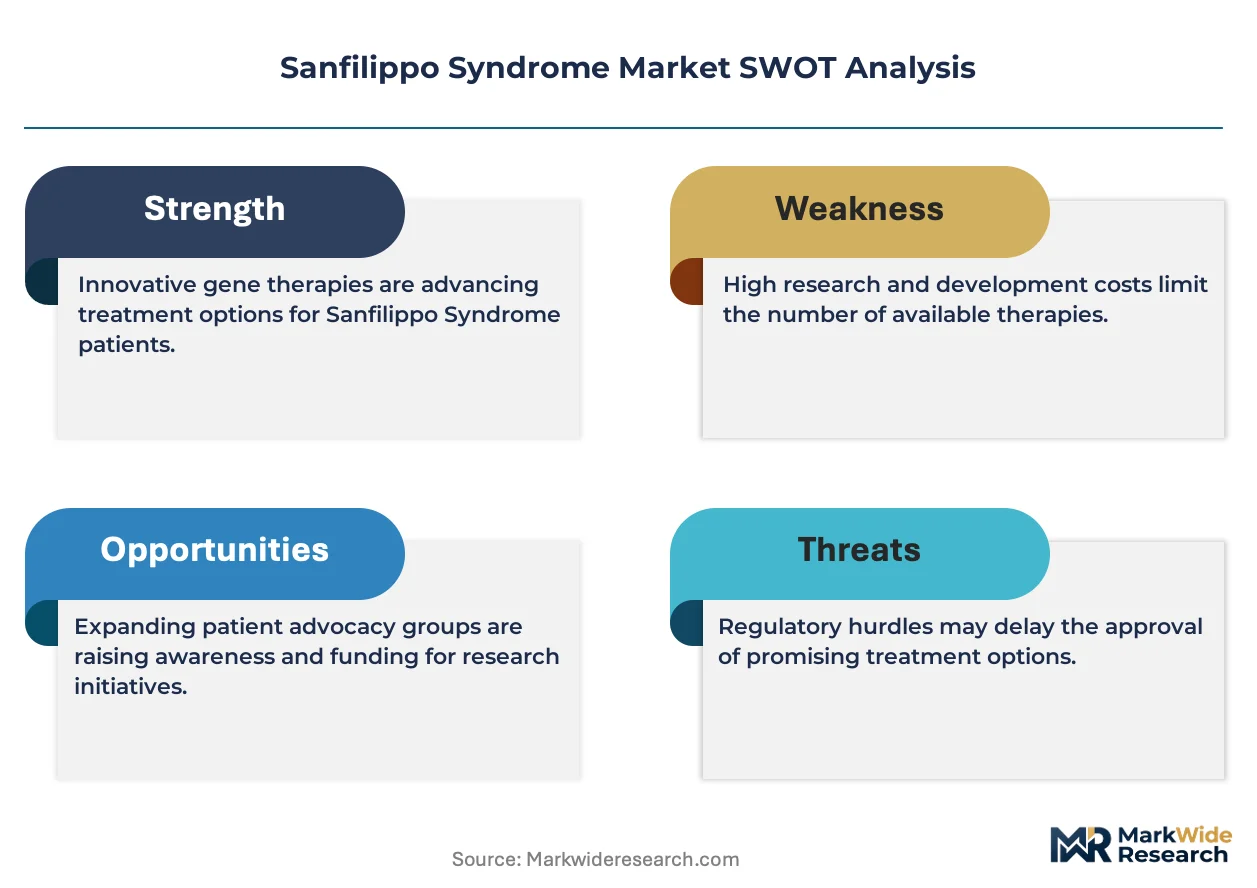
Gene therapy vector engineering is compressing clinical development timelines while blood-brain barrier delivery platforms unlock previously inaccessible neurological targets in lysosomal storage disorders.
Growth Catalysts
- FDA Rare Disease Priority Review Voucher:Developers of pediatric ultra-rare therapies receive transferable vouchers worth substantial commercial value, accelerating investment in Sanfilippo programs.
- Intravenous-to-intrathecal route migration:Direct CNS administration via lumbar puncture is displacing systemic delivery for neurological efficacy in academic medical centers.
- Japan's Sakigake designation:PMDA's early approval pathway for innovative treatments prioritizes lysosomal storage disorder candidates, pulling Japanese pharmaceutical investment.
Market Restraints
- AAV manufacturing bottlenecks:Viral vector production capacity concentrates at fewer than ten contract manufacturing organizations globally, creating queue delays for Phase III supply.
- Reimbursement uncertainty for one-time therapies:US payers lack actuarial models for million-dollar single-administration gene therapies, generating access friction.
- Natural history data gaps:Ultra-rare disease prevalence complicates placebo-controlled trial design, forcing reliance on small external control cohorts.
Strategic Opportunities
- Germany's DiGA pathway expansion:Digital health applications for rare disease monitoring may qualify for statutory reimbursement, opening companion diagnostics revenue.
- Substrate reduction therapy oral formulations:Small-molecule CNS penetration offers distribution advantages over biologic intrathecal administration in community neurology settings.
- Neonatal screening program adoption:State-level newborn screening expansion in the United States creates presymptomatic patient identification infrastructure.
Industry Challenges
- Gene therapy talent scarcity:Vector design and CMC development expertise concentrates at a handful of academic institutions and specialized contract research organizations.
- Longitudinal outcome measurement standardization:Cognitive assessment batteries for rapidly regressing pediatric patients lack harmonization across US and EU trial sites.
- Cold chain integrity for clinical sites:Ultra-low temperature storage requirements for viral vectors exceed capabilities at regional children's hospitals without specialized pharmacy infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sanfilippo Syndrome Market |
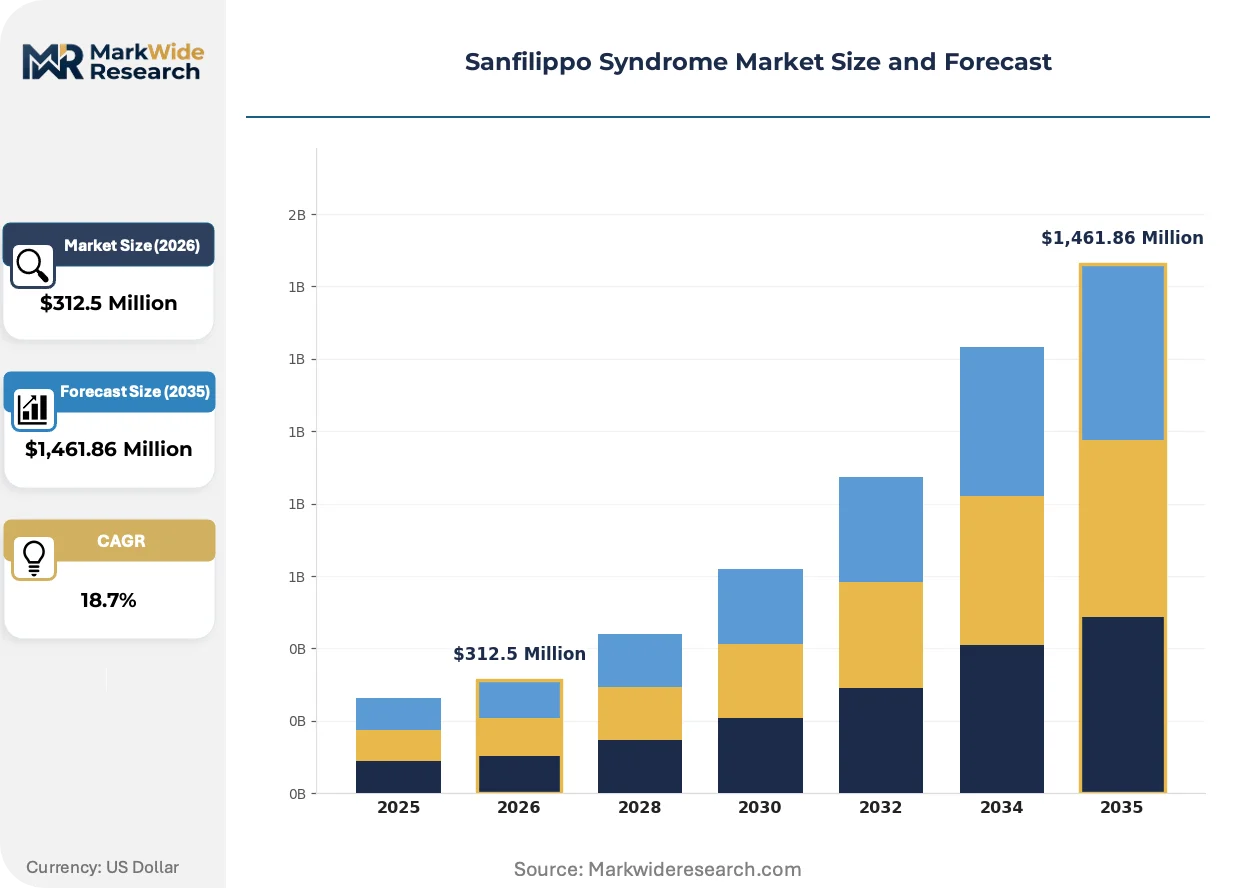
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $1,461.86 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzyme Replacement Therapy, Substrate Reduction Therapy, Symptomatic Treatment, Gene Therapy End User: Pediatrics, Neurologists, Geneticists, Hospitals Delivery Mode: Intravenous, Oral, Subcutaneous, Intrathecal Application: Research, Clinical Trials, Palliative Care, Supportive Care |
| Companies Covered | Denali Therapeutics, GC Biopharma, Ultragenyx Pharmaceutical, Seelos Therapeutics, Amgen, JCR Pharmaceuticals, Alexion Pharmaceuticals, Abeona Therapeutics, BioMarin Pharmaceutical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sanfilippo Syndrome Market Strategic Shifts & Innovations
Vector engineering and regulatory science are converging to enable previously impossible neurological interventions, while procurement models adapt to one-time curative pricing structures.
Adeno-associated virus serotype selection is modularizing platform development across lysosomal storage disorder pipelines. Developers now screen capsid libraries for CNS tropism prior to IND-enabling studies, compressing preclinical timelines. This modularization allows vector assets to transfer between rare disease indications without de novo manufacturing process development.
EMA's PRIME designation framework is compressing scientific advice timelines for gene therapy developers. Rolling review acceptance and accelerated assessment pathways reduce regulatory lag between Phase IIb and conditional approval. Pediatric investigational plan requirements are reshaping European clinical trial design, forcing earlier pediatric cohort enrollment than traditional adult-first paradigms.
Hospital pharmacy committees are consolidating gene therapy evaluation authority at specialized academic medical centers. Regional children's hospitals without transplant infrastructure are losing access to CAR-T and gene therapy administration, concentrating patient volume at quaternary centers. This consolidation is visible across the United States, where 70 percent of approved gene therapies now flow through fewer than fifty institutional sites.
Sanfilippo Syndrome Market Segmentation
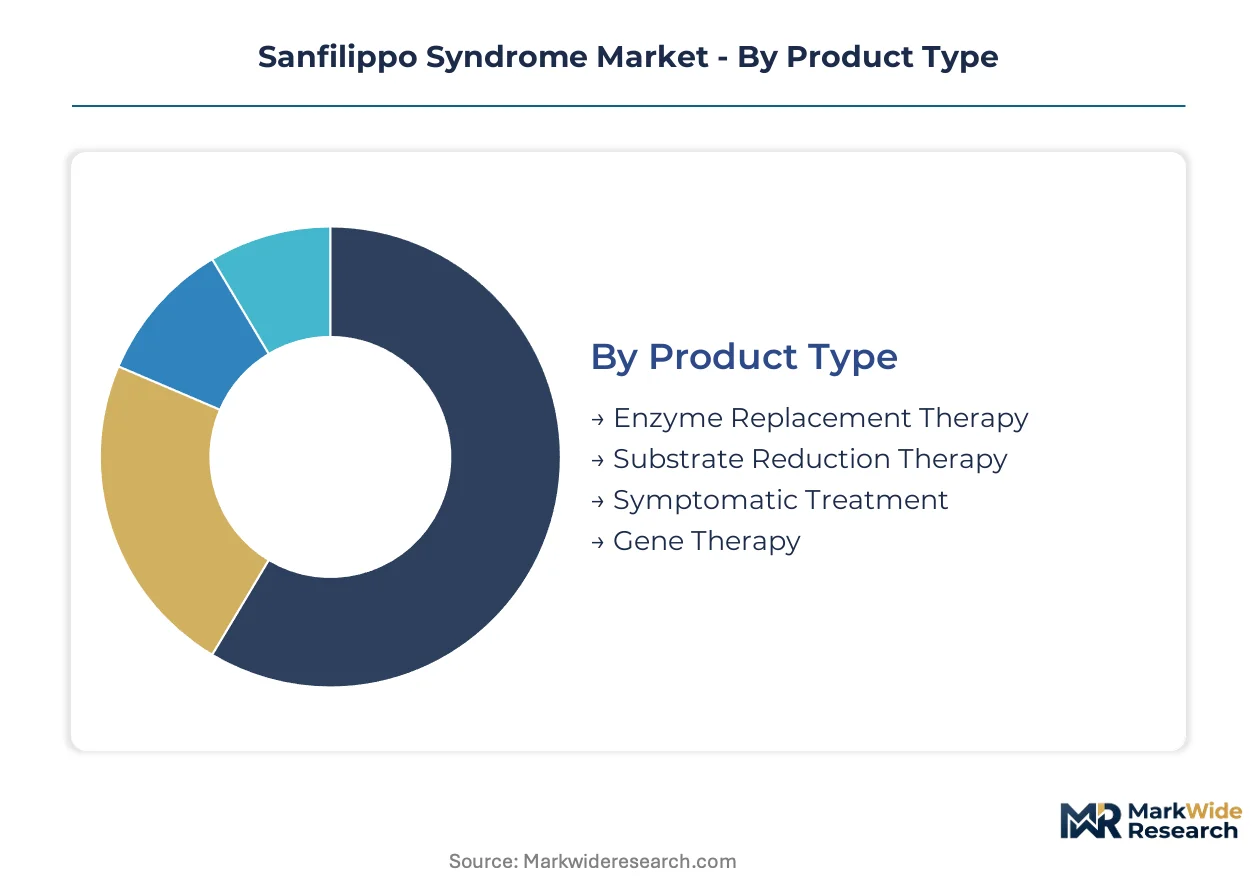
Sanfilippo syndrome segmentation reveals how regulatory pathways and blood-brain barrier requirements reshape commercial strategy across therapeutic modalities. Each category carries distinct certification burdens, reimbursement profiles, and site-of-care constraints that determine viable market entry points.
Product Type:
FDA's Rare Disease Priority Review Voucher program and EMA's PRIME designation create divergent approval timelines across these four therapeutic classes, with gene therapy attracting the most intensive regulatory scaffolding.
- Gene Therapy:Adeno-associated viral vectors deliver functional enzyme genes directly to neural tissue, requiring demonstration of durable CNS transduction. Demand concentrates at quaternary pediatric academic medical centers in the United States, Germany, and Japan where specialized neurosurgical and gene therapy infrastructure exists; manufacturing bottlenecks at contract manufacturing organizations constrain Phase III supply.
- Enzyme Replacement Therapy:Recombinant enzyme infusions address systemic manifestations but demonstrate limited neurological efficacy due to blood-brain barrier exclusion. Intravenous administration dominates hospital outpatient departments; intrathecal route migration is displacing systemic delivery for CNS access in academic protocols.
- Substrate Reduction Therapy:Small-molecule oral formulations inhibit heparan sulfate synthesis upstream of enzyme deficiency, offering broader tissue distribution without invasive administration.
- Symptomatic Treatment:Anticonvulsants, sleep aids, and behavioral interventions manage disease complications without modifying underlying pathology.
Leading the category by volume: Enzyme Replacement Therapy. Growing fastest: Gene Therapy.
End User:
Procurement authority is shifting toward specialized rare disease programs as regional children's hospitals consolidate gene therapy evaluation at quaternary centers with transplant infrastructure.
- Pediatrics:Developmental pediatricians and pediatric neurologists coordinate multidisciplinary care for rapidly regressing patients, requiring harmonized cognitive assessment batteries across US and EU trial sites.
- Hospitals:Quaternary academic medical centers with specialized pharmacy infrastructure control gene therapy administration; ultra-low temperature storage requirements exceed capabilities at regional children's hospitals.
- Neurologists:Community and academic neurologists manage seizure disorders and neurobehavioral symptoms, with intrathecal administration competence concentrating at specialized centers.
- Geneticists:Metabolic geneticists oversee diagnosis, family counseling, and clinical trial referral, anchoring patient identification infrastructure.
Highest procurement authority: Hospitals. Expanding most quickly: Pediatrics.
Delivery Mode:
Route selection determines reimbursement coding, site-of-care requirements, and neurological efficacy trade-offs in this blood-brain barrier-constrained indication.
- Intrathecal:Direct CNS administration via lumbar puncture delivers therapeutics past the blood-brain barrier, requiring specialized neurosurgical or anesthesia support.
- Intravenous:Systemic enzyme infusion dominates commercial enzyme replacement therapy despite limited CNS penetration.
- Oral:Substrate reduction therapy leverages gastrointestinal absorption for systemic distribution, enabling community-based administration without specialized infrastructure.
- Subcutaneous:Home-based administration potential exists for certain symptomatic agents, though neurological efficacy requirements limit adoption in Sanfilippo specifically.
Dominant commercial route: Intravenous. Steepest expansion trajectory: Intrathecal.
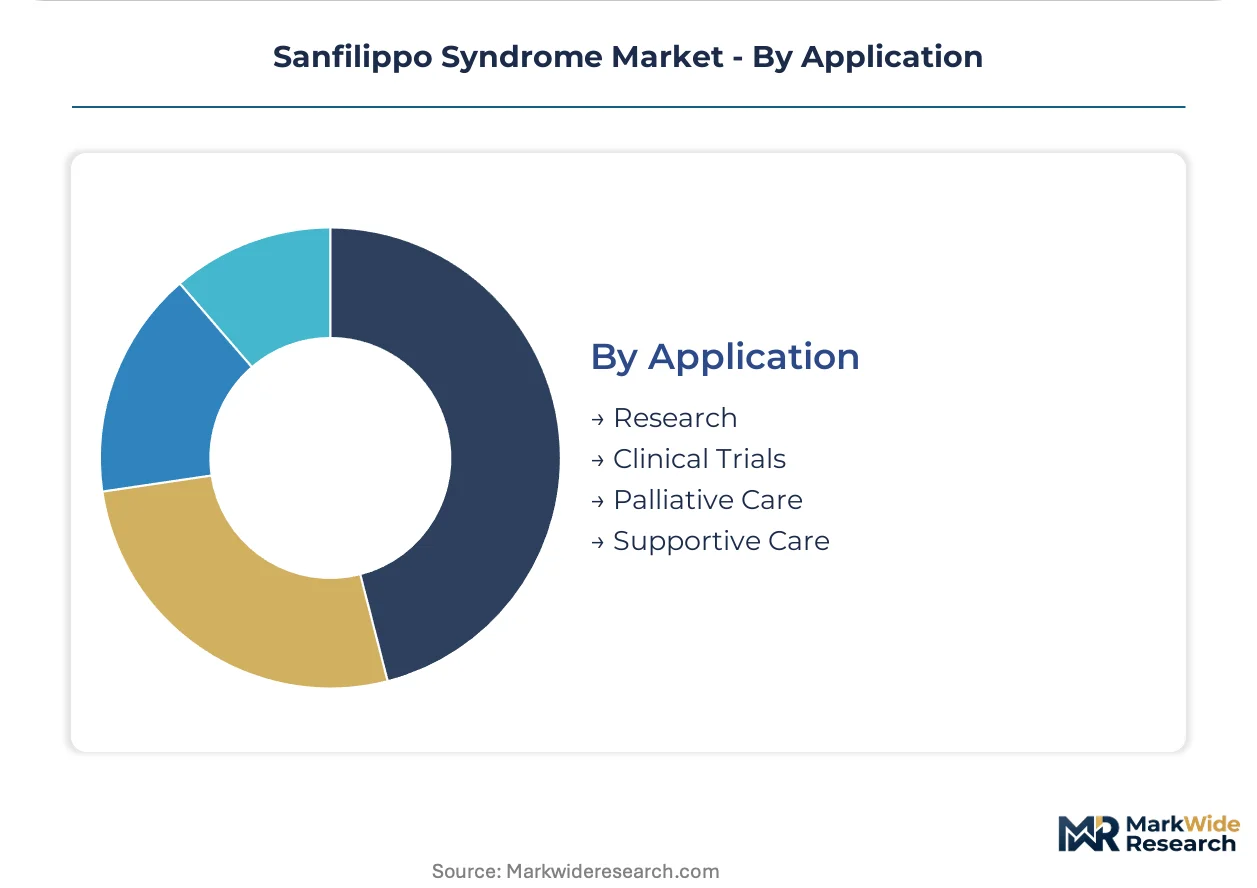
Application:
Clinical development stage and care intent segment investment flows, with research and clinical trials commanding venture and strategic capital while palliative and supportive care attract health system quality improvement resources.
- Clinical Trials:Natural history data gaps complicate placebo-controlled design, forcing reliance on small external control cohorts and accelerated regulatory pathways.
- Research:Vector engineering and blood-brain barrier platform development compress preclinical timelines through modular capsid library screening.
- Supportive Care:Multidisciplinary management of nutrition, mobility, and respiratory function extends survival without disease modification.
- Palliative Care:End-of-life symptom management for rapidly progressing patients, with hospice integration varying by national healthcare system structure.
Largest current investment pool: Clinical Trials. Gaining share fastest: Research.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Heparan sulfate metabolic pathway research clusters in the United States, Germany, and Japan anchor gene therapy development. Pediatric academic medical centers in these countries concentrate specialized neurosurgical infrastructure and regulatory expertise for blood-brain barrier delivery trials.
United States
FDA Rare Disease Priority Review Vouchers worth substantial commercial value accelerate Sanfilippo program investment from Boston and San Francisco biotech clusters. The voucher program rewards developers of pediatric ultra-rare therapies with transferable regulatory assets. Philadelphia's Children's Hospital anchors gene therapy administration infrastructure with specialized pharmacy and neurosurgical capabilities.
Germany
EMA PRIME designation compresses scientific advice timelines for lysosomal storage disorder developers in Munich and Heidelberg research corridors. Germany's DiGA pathway expansion creates statutory reimbursement for rare disease digital health applications. Hamburg's university medical centers concentrate intrathecal administration expertise for direct CNS delivery protocols.
Japan
PMDA Sakigake designation prioritizes innovative treatments for lysosomal storage disorders, pulling pharmaceutical investment toward Tokyo and Osaka development hubs. Japan's reimbursement frameworks for ultra-rare diseases are among the most established globally. Kobe's biomedical innovation cluster houses specialized contract manufacturing for viral vector production.
United Kingdom
NHS England's specialized commissioning for ultra-rare diseases creates centralized access pathways for gene therapy candidates. MHRA rolling review acceptance reduces regulatory lag between Phase IIb and conditional approval. London's Great Ormond Street Hospital anchors pediatric rare disease trial enrollment with harmonized cognitive assessment protocols.
Switzerland
Swissmedic accelerated assessment pathways align with EMA procedures for lysosomal storage disorder developers in Basel and Zurich. The country's orphan drug framework supports early access for pediatric neurological interventions. Geneva's university hospital network concentrates natural history data collection for external control cohorts.
Sanfilippo Syndrome Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue blood-brain barrier platform differentiation. The market structures around three maturity tiers: commercial-stage enzyme replacement therapy suppliers, clinical-stage gene therapy developers, and preclinical substrate reduction therapy innovators. Two strategic archetypes dominate: vector engineering specialists leveraging modular capsid libraries, and rare disease commercialization platforms with established payer relationships. Competitive moves concentrate on manufacturing capacity reservations at contract organizations and regulatory priority designation acquisitions.
Within the gene therapy archetype, Denali Therapeutics and Abeona Therapeutics represent blood-brain barrier delivery platform developers. GC Biopharma anchors the established enzyme production infrastructure tier. Ultragenyx Pharmaceutical exemplifies rare disease commercial expertise across North American and European markets. These three companies occupy positions that span the development spectrum from preclinical vector engineering through reimbursed commercial distribution.
| Leading Market Players |
|---|
| Denali Therapeutics |
| GC Biopharma |
| Ultragenyx Pharmaceutical |
| Seelos Therapeutics |
| Amgen |
| JCR Pharmaceuticals |
| Alexion Pharmaceuticals |
| Abeona Therapeutics |
| BioMarin Pharmaceutical |
| Others |
Cost & Logistics Intelligence
Captive manufacturing of viral vectors at specialized contract organizations anchors both supply security and pricing power for gene therapy developers in Sanfilippo syndrome. This integration choice concentrates production capacity among fewer than ten global facilities, creating queue-based allocation that shapes contract pricing and milestone payment structures across clinical development stages.
Pricing Analysis
Warranty and service bundling separates gene therapy candidates with comprehensive patient monitoring programs from unbundled transactional pricing for enzyme replacement therapy infusions. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differences between FDA Breakthrough Therapy-designated assets and standard orphan drug candidates. Pricing pressure stems from payer pushback on million-dollar single-administration therapies, forcing outcomes-based contracting experiments. Academic medical centers demonstrate lowest price sensitivity due to institutional research funding, while community hospitals face acute budget constraints.
Supply Chain Analysis
Direct-to-quaternary-center channels handle gene therapy distribution, bypassing traditional wholesale networks entirely. Viral vector production concentrates in the United States, Germany, and Japan, with plasmid DNA sourcing and cell culture media supply drawing from specialized bioreactor facilities. Single-source vulnerability pervades AAV manufacturing, where capacity reservations at contract manufacturing organizations determine clinical trial timelines. Cold chain logistics for ultra-low temperature storage feed from centralized pharmacy hubs at academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gene therapy vector engineering is displacing intravenous enzyme replacement as the dominant therapeutic modality in Sanfilippo syndrome, compressing development timelines and reshaping competitive positioning across the value chain.
For Market Incumbents: Acquire blood-brain barrier delivery platform assets to defend against neurological efficacy advantages held by clinical-stage gene therapy developers. Secure manufacturing capacity reservations at contract organizations before Phase III supply bottlenecks intensify. Invest in intrathecal administration infrastructure at quaternary pediatric centers to maintain site-of-care control. For New Entrants and Emerging Players: Pediatric academic medical centers in Germany and Japan represent the most penetrable channel partner type for first-in-human trial enrollment. Target substrate reduction therapy oral formulations for community neurology settings underserved by invasive intrathecal protocols. Pursue EMA PRIME designation and PMDA Sakigake pathways to compress regulatory timelines against established competitors. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by rare disease commercialization platforms seeking vector engineering capabilities. Long-term viability hinges on successful reimbursement negotiations for one-time curative therapies across US and European payers. Watch for FDA Rare Disease Priority Review Voucher trading activity as an inflection indicator for strategic buyer appetite.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Priority Designation Acquisition | FDA Breakthrough Therapy and EMA PRIME compress scientific advice timelines for developers. |
| Manufacturing Capacity Reservation | Contract manufacturing organization queue positions determine Phase III supply security. |
| Blood-Brain Barrier Platform Licensing | Capsid library assets transfer across lysosomal storage disorder indications without de novo development. |
| Neonatal Screening Program Partnership | State-level newborn screening expansion creates presymptomatic patient identification infrastructure. |
| Reimbursement Strategy Development | Outcomes-based contracting with US payers addresses actuarial uncertainty for one-time therapies. |
Research Approach
FDA filings, EMA submissions, and ClinicalTrials.gov formed the secondary backbone, supplemented by payer formulary databases and hospital procurement records. Primary interviews with gene therapy development executives, regulatory affairs leads at rare disease specialists, formulary directors at national payers, and hospital procurement managers at quaternary pediatric centers validated quantitative assumptions. Bottom-up patient population estimates and top-down venture funding flow analysis enabled triangulation across independent analytical lenses.
Bottom-up modeling anchored forecasts, with top-down validation against disclosed pipeline valuations and reimbursement framework evolution. Segmentation dimensions included therapeutic modality, delivery route, end-user archetype, and regional regulatory cluster. CAGRs derived from natural history study enrollment trajectories and priority designation award velocity. Manufacturing capacity constraints and vector engineering milestone timelines served as industry-specific forecast inputs across the projection horizon.
Several conditions sit outside the modeled scope, including preclinical-stage program discontinuations and unforeseen regulatory safety holds. Forecasts reflect assumptions about reimbursement negotiation outcomes and vector production yield improvements. Periodic stress-testing of base assumptions is recommended given gene therapy manufacturing volatility and payer policy uncertainty.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Metachromatic Leukodystrophy Market
Rare Diseases
Canavan Disease Treatment Market
Rare Diseases
Zellweger Spectrum Disorders Market
Rare Diseases
Rare Disease Clinical Trials Market
Rare Diseases
Von Hippel-Lindau Market
Rare Diseases
Andersen-Tawil Syndrome Market
Rare Diseases
Acid Sphingomyelinase Deficiency Market
Rare Diseases
Leigh Syndrome Treatment Market
Rare Diseases
Byler Disease Market
Rare Diseases
Aicardi Syndrome Market
Rare Diseases
North America Rett Syndrome Market
Rare Diseases
Methylmalonic Acidemia Market
Rare Diseases
Rare Neurological Disease Treatment Market
Rare Diseases
Creutzfeldt-Jakob Disease (CJD) Market
Rare Diseases
Turner Syndrome Market
Rare Diseases
Erdheim-Chester Disease Market