
 Aarskog Scott Syndrome Treatment Market | 2026-2036
Aarskog Scott Syndrome Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Aarskog Scott Syndrome Treatment Market Outlook
Orphan drug designation criteria under the FDA is hardening the commercial pathway for rare genetic disorder therapeutics. Novo Nordisk leverages its endocrine expertise to sustain leadership in growth hormone modalities for pediatric rare diseases. Sanofi anchors its position through broad rare disease portfolios spanning multiple genetic syndromes. Pfizer competes via established injectable delivery platforms that clinicians recognize in pediatric settings.
Aarskog Scott syndrome treatment encompasses therapeutic interventions targeting the X-linked genetic disorder characterized by short stature, facial dysmorphism, and skeletal abnormalities, primarily involving recombinant growth hormone administration and corrective surgical procedures. The condition arises from FGD1 gene mutations affecting intracellular signaling pathways, with treatment protocols requiring coordinated endocrinological, orthopedic, and genetic specialist oversight. Growth hormone therapy occupies the largest therapeutic segment due to established reimbursement pathways and measurable height velocity outcomes in pediatric populations. Genetic therapy represents the fastest-expanding category as CRISPR-based platforms advance toward clinical translation for monogenic disorders. Surgical intervention maintains steady utilization for craniofacial and hand deformity corrections with predictable procedural volumes.
FDA orphan drug incentives, EMA rare disease frameworks, and national newborn screening expansions collectively shape product development priorities and market access conditions for Aarskog Scott syndrome interventions. Regulatory alignment across FDA, EMA, and Health Canada accelerates multinational trial designs but demands differentiated pediatric study protocols. Stakeholders must monitor gene therapy regulatory guidance evolution and reimbursement policy shifts for curative versus chronic management paradigms.
Market Dynamics
FDA orphan drug incentives are hardening the commercial pathway for rare genetic disorder therapeutics, forcing developers to demonstrate pediatric-specific efficacy earlier in clinical programs. This structural pressure concentrates investment in endocrinology infrastructure where reimbursement pathways for growth hormone modalities remain most established.
Growth Catalysts
- Orphan Drug Incentives:FDA tax credits and market exclusivity provisions accelerate therapeutic pipelines targeting FGD1 gene mutations, reducing financial risk for pediatric rare disease programs.
- Newborn Screening Expansion:State-level mandates in the United States identify affected infants earlier, compressing time-to-treatment initiation and expanding addressable patient pools.
- CRISPR Platform Maturation:Gene editing technologies advance toward clinical translation for monogenic disorders, attracting venture funding into curative rather than chronic management paradigms.
Market Restraints
- Reimbursement Fragmentation:Medicaid state-by-state variation creates access barriers for growth hormone therapy in rural pediatric populations without specialized endocrinology centers.
- Clinical Trial Complexity:Small patient cohorts necessitate multinational study designs requiring alignment across FDA, EMA, and Health Canada pediatric protocols, extending development timelines.
- Specialist Workforce Scarcity:Pediatric endocrinologist concentration in academic medical centers limits treatment capacity outside major metropolitan clusters.
Strategic Opportunities
- Gene Therapy Regulatory Tailwinds:FDA's emerging guidance on long-term follow-up for gene editing products creates clarity for CRISPR-based FGD1 correction strategies.
- Telemedicine Integration:Remote endocrinology consultations expand reach into underserved states, reducing geographic barriers to specialist oversight.
- Surgical Robotics Adoption:Craniofacial and hand deformity correction procedures benefit from precision platforms that reduce operative time and improve outcomes in pediatric populations.
Industry Challenges
- Genetic Counselor Shortage:Interpretation of FGD1 variant significance requires specialized expertise that outstrips current training program output.
- Long-Term Safety Surveillance:Growth hormone therapy in rare disease populations demands decades of post-marketing data collection that strains registry infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aarskog Scott Syndrome Treatment Market |
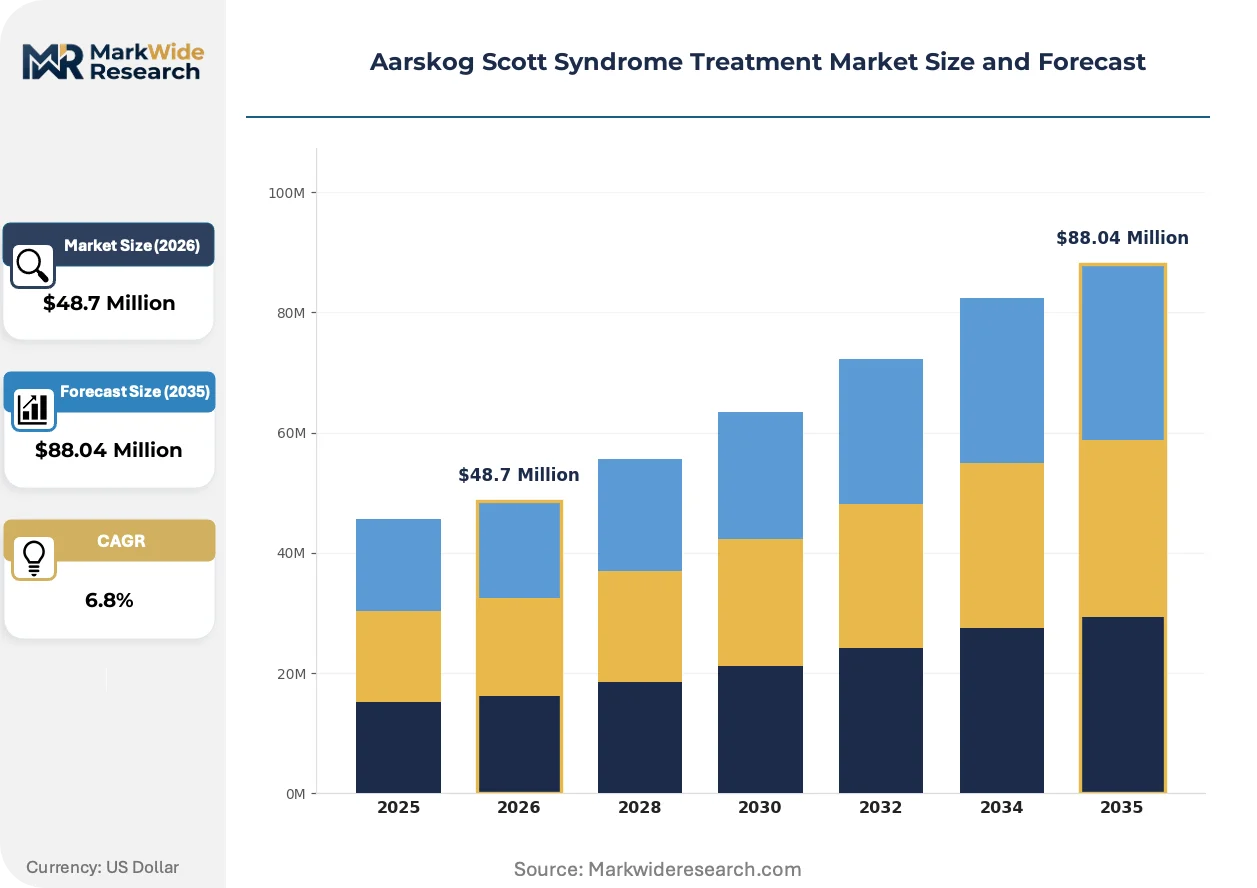
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $88.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Growth Hormone, Genetic Therapy, Surgical Intervention, Symptomatic Treatment Delivery Mode: Intravenous, Subcutaneous, Oral, Injectable End User: Pediatric Clinics, Hospitals, Research Laboratories, Homecare Settings Treatment Approach: Comprehensive Care, Personalized Therapy, Supportive Care, Preventive Measures |
| Companies Covered | Sanofi, Johnson & Johnson Private Limited, Novo Nordisk, Takeda Pharmaceutical Company, Medtronic, Eli Lilly and Company, GeneScience Pharmaceuticals Co., Ltd, Novartis AG, Pfizer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aarskog Scott Syndrome Treatment Market Strategic Shifts
Curative modalities are displacing chronic management frameworks across pediatric rare disease portfolios, compressing investment timelines and restructuring competitive positioning around one-time intervention economics rather than recurring revenue models.
CRISPR-based gene editing platforms for monogenic disorders are unifying previously separate therapeutic development tracks, enabling single-intervention correction of FGD1 mutations. Academic medical centers with established pediatric gene therapy programs are accelerating patient access protocols. This convergence is compressing the traditional boundaries between genetic diagnosis and therapeutic intervention, collapsing the diagnostic-therapeutic interval.
EMA's rare disease framework and FDA's harmonized pediatric investigation plans are synchronizing multinational trial requirements, reducing redundant study designs. Pharmaceutical developers now submit coordinated protocols across regulatory jurisdictions simultaneously. Pediatric endocrinology networks in Germany, France, and the United Kingdom are consolidating referral pathways to capture eligible patients for these harmonized studies.
Academic medical centers are consolidating rare disease care into vertically integrated centers of excellence, displacing fragmented specialist referrals. Parents of children with Aarskog Scott syndrome now seek coordinated endocrinology, orthopedic, and genetic services within single institutions. This concentration is most visible in the United States, where Boston, Philadelphia, and Houston anchor national referral networks that draw patients across state boundaries.
Aarskog Scott Syndrome Treatment Market Segmentation
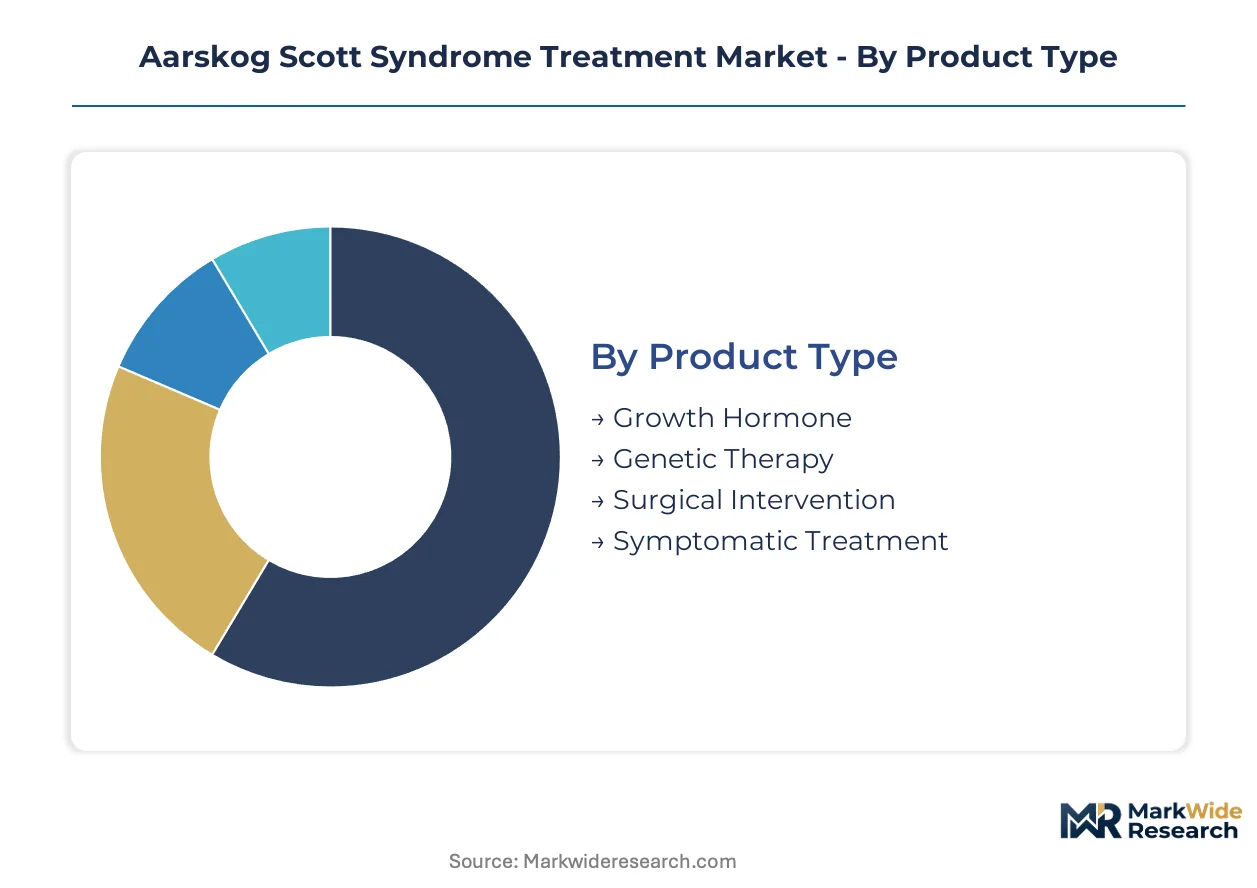
Treatment modality selection in Aarskog Scott syndrome hinges on disease severity, FGD1 mutation profile, and reimbursement tier. Segmentation reveals how pediatric endocrinologists allocate resources across chronic management versus curative intervention pathways.
Product Type:
Reimbursement tier and outcome measurability drive product selection, with established chronic therapies competing against emerging one-time interventions for capital allocation.
- Growth Hormone:Recombinant human growth hormone administered via daily subcutaneous injection remains the backbone of stature management. Pediatric endocrinology practices in the United States concentrate demand here due to well-defined prior authorization pathways and documented height velocity outcomes.
- Genetic Therapy:CRISPR-based FGD1 correction strategies and viral vector delivery systems target the underlying monogenic defect. Academic medical centers with gene therapy infrastructure in Boston, Houston, and Philadelphia are accelerating patient access protocols for these investigational modalities.
- Surgical Intervention:Craniofacial reconstruction and hand deformity correction address structural complications.
- Symptomatic Treatment:Orthodontic management, ophthalmologic care, and behavioral supports address secondary manifestations.
Growth hormone leads on scale; genetic therapy leads on momentum.
Delivery Mode:
Patient compliance requirements and pharmacokinetic profiles determine route selection, with pediatric populations imposing unique adherence constraints.
- Subcutaneous:Daily self-administration of growth hormone via pen devices dominates chronic therapy. Homecare penetration in suburban United States markets depends on caregiver training infrastructure and insurance-covered nursing support.
- Intravenous:Gene therapy vectors and perioperative medications require controlled infusion settings. Hospital-based administration in major metropolitan clusters maintains strict monitoring protocols for immunogenicity events.
- Injectable:Depot formulations and surgical adjuncts occupy this intermediate category.
- Oral:Limited current applicability due to peptide degradation and poor bioavailability.
Subcutaneous administration dominates volume; intravenous delivery commands premium positioning.
End User:
Care coordination complexity and specialist availability shape where treatment episodes originate and conclude.
- Pediatric Clinics:Dedicated endocrinology practices manage longitudinal growth hormone therapy and multidisciplinary coordination. State-level Medicaid expansion in the United States determines access breadth outside academic medical center catchments.
- Hospitals:Surgical interventions, gene therapy infusions, and acute complication management concentrate here. Tertiary centers in Philadelphia, Boston, and Houston anchor regional referral networks spanning multiple states.
- Research Laboratories:Natural history studies and biomarker development support regulatory submissions.
- Homecare Settings:Growth hormone administration shifts here as caregiver competence matures.
Pediatric clinics lead on patient volume; hospitals lead on revenue per episode.
Treatment Approach:
Institutional philosophy and payer incentives determine whether care prioritizes symptom suppression or underlying defect correction.
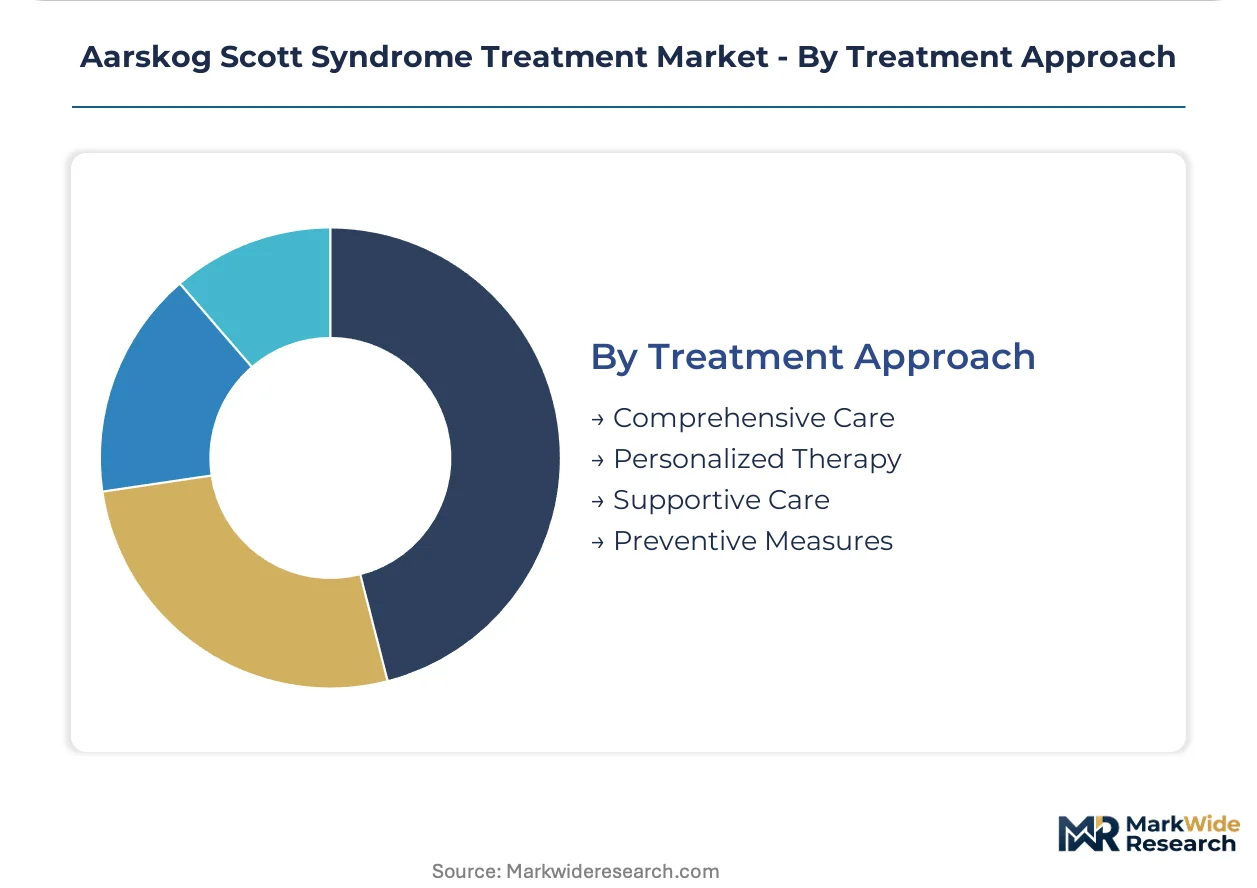
- Comprehensive Care:Vertically integrated centers combine endocrinology, orthopedics, genetics, and psychology within single institutions. Academic medical centers in the United States compete for patient volume through this coordinated model.
- Personalized Therapy:Genotype-phenotype correlation guides mutation-specific intervention selection. FGD1 variant interpretation services at specialized laboratories in Boston and Houston inform treatment matching.
- Supportive Care:Educational accommodations and behavioral interventions address cognitive-behavioral phenotypes.
- Preventive Measures:Early orthopedic screening and cardiac monitoring anticipate complications.
Comprehensive care leads on institutional investment; personalized therapy leads on clinical differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aarskog Scott syndrome treatment infrastructure traces its clinical foundations to mid-20th century European pediatric endocrinology, with subsequent scaling concentrated in North American academic medical centers that established the multidisciplinary care models now replicated worldwide.
United States
Pediatric endocrinology networks in Boston, Philadelphia, and Houston anchor national referral systems drawing patients across state boundaries. FDA orphan drug tax credits and market exclusivity provisions accelerate therapeutic pipelines targeting FGD1 mutations. Texas Medical Center in Houston maintains one of the highest procedural volumes for craniofacial surgical interventions in rare genetic syndromes.
Germany
Academic medical centers in Munich and Heidelberg consolidate rare disease care through vertically integrated centers of excellence. EMA rare disease frameworks synchronize pediatric investigation plans across European jurisdictions. The German Society for Pediatric Endocrinology and Diabetology coordinates multicenter natural history studies that inform regulatory submissions.
Japan
PMDA's Sakigake designation system fast-tracks innovative therapies for pediatric rare diseases with high unmet need. The National Center for Child Health and Development in Tokyo serves as the primary referral hub for genetic syndrome management. Japanese pharmaceutical developers leverage domestic growth hormone manufacturing expertise to supply regional markets.
United Kingdom
NHS England's specialized commissioning framework concentrates rare disease treatment in designated supraregional centers. The Manchester Centre for Genomic Medicine and Great Ormond Street Hospital in London anchor national referral pathways. UK regulatory alignment with EMA pediatric investigation plans reduces redundant study requirements for multinational trials.
Canada
Health Canada's orphan drug regulatory pathway mirrors FDA incentives while requiring distinct pediatric study protocols. The Hospital for Sick Children in Toronto maintains the country's largest pediatric endocrinology practice for rare genetic disorders. Provincial health technology assessment processes create variable access conditions for growth hormone therapy across Ontario, Quebec, and British Columbia.
Aarskog Scott Syndrome Treatment Market Competitive Environment
Premium-margin players sit above commodity-margin players across therapeutic modality specialization, with gene therapy platforms commanding valuation multiples that dwarf established growth hormone franchises. The vendor base organizes around three tiers: multinational endocrine specialists with established pediatric rare disease portfolios, diversified pharmaceutical conglomerates leveraging injectable delivery platforms, and emerging gene therapy developers attracting venture funding for curative modalities. Dominant competitive moves include strategic partnerships between academic gene therapy programs and commercial developers, plus geographic expansion of pediatric endocrinology networks into underserved state Medicaid markets.
Within the established endocrine therapy tier, Novo Nordisk and Sanofi exemplify divergent strategic positioning. Novo Nordisk anchors its presence through specialized growth hormone formulations and deep pediatric endocrinology relationships. Sanofi occupies a diversified position spanning multiple rare genetic syndromes rather than concentration in single-disease modalities. Pfizer sits within the injectable delivery platform segment, leveraging clinician familiarity with its device systems in pediatric settings. These three entities represent distinct archetypes: the hormone specialist, the rare disease generalist, and the delivery-technology incumbent.
| Leading Market Players |
|---|
| Sanofi |
| Johnson & Johnson Private Limited |
| Novo Nordisk |
| Takeda Pharmaceutical Company |
| Medtronic |
| Eli Lilly and Company |
| GeneScience Pharmaceuticals Co., Ltd |
| Novartis AG |
| Pfizer |
| Others |
Value Chain & Pricing Dynamics
Pediatric endocrinology practices in the United States concentrate purchasing decisions for growth hormone therapies, creating a contract-based pricing structure where academic medical centers leverage volume commitments against manufacturers. This buyer concentration shapes reimbursement negotiations and formulary positioning across state Medicaid programs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels reflects FDA approval status and delivery device sophistication. Price differentiation hinges on orphan drug exclusivity periods and pediatric indication breadth, with gene therapy candidates commanding premium positioning against chronic management alternatives. Pricing pressure stems from state-level Medicaid formulary restrictions that compress margins on established growth hormone products. Rural pediatric clinics exhibit highest price sensitivity due to limited prior authorization support infrastructure.
Supply Chain Analysis
FDA current Good Manufacturing Practice certification gates entry for recombinant protein production facilities, concentrating active pharmaceutical ingredient supply in the United States, Denmark, and Switzerland. Manufacturing draws from specialized bioreactor infrastructure and cold-chain distribution networks. Single-source vulnerability persists for viral vector production used in gene therapy candidates. Distribution runs through specialty pharmacy channels with direct-to-patient home delivery for chronic therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where FDA orphan drug tax credits and pediatric investigation plan harmonization continuously expand addressable patient pools through earlier diagnosis mandates.
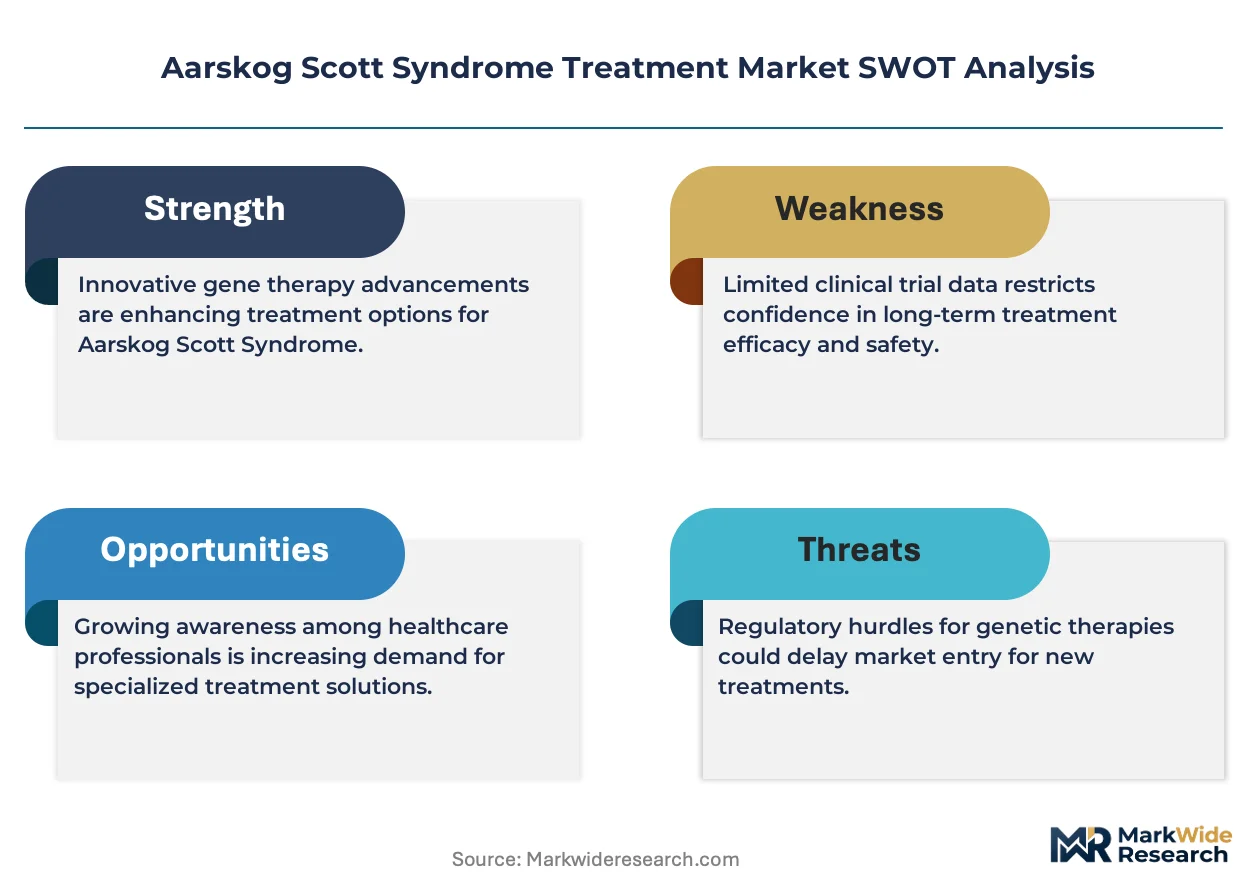
For Market Incumbents: Anchor market position through backward integration into viral vector manufacturing capacity and exclusive partnerships with academic gene therapy programs in Boston and Houston. CRISPR-based curative modalities threaten chronic therapy revenue streams. Defensive consolidation should prioritize captive supply of plasmid DNA and lentiviral packaging cell lines to secure gene therapy pipeline access. For New Entrants and Emerging Players: Rural Medicaid expansion states without established pediatric endocrinology infrastructure represent the most penetrable buyer archetype. Telemedicine-enabled remote consultation platforms offer white-space entry with lower capital requirements than brick-and-clinic expansion. Go-to-market positioning should emphasize caregiver training programs and insurance navigation support to differentiate against incumbent specialty pharmacy networks. For Investors and Strategic Acquirers: Large-cap rare disease specialists with existing FDA breakthrough therapy designations are the most active acquirer in this space, seeking gene therapy platform capabilities. Long-term viability favors vertically integrated developers controlling both genetic correction technology and pediatric clinical trial infrastructure. The signal to watch is FDA guidance publication on long-term follow-up protocols for germline-editing interventions, which will clarify reimbursement frameworks for curative modalities.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pursuit | FDA tax credits reduce clinical program burn rate for pediatric rare disease developers. |
| Pediatric Investigation Plan Harmonization | EMA-FDA alignment cuts redundant study costs across Atlantic trial sites. |
| Academic Medical Center Partnership | Boston Children's and Texas Children's anchor patient access for gene therapy protocols. |
| Specialty Pharmacy Network Expansion | Cold-chain home delivery capabilities capture growth hormone therapy volume outside hospital settings. |
| Gene Therapy Manufacturing Scale-Up | Viral vector production bottlenecks constrain CRISPR-based FGD1 correction supply. |
Study Parameters
Coverage spans North America, Western Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with pediatric endocrinologists, regulatory affairs specialists at orphan drug developers, hospital pharmacy directors, and state Medicaid formulary managers. Secondary validation drew from FDA orphan drug designations, EMA pediatric investigation plans, ClinicalTrials.gov entries, and CMS state drug utilization review data. Bottom-up patient prevalence modeling and top-down therapeutic revenue estimates were triangulated against manufacturer reported sales.
Granularity-level modeling tracked treatment modality, delivery route, end-user setting, and regional regulatory cluster across the analysis window. CAGRs were derived from epidemiological projections, treatment penetration curves, and pricing trajectory assumptions. Forecast inputs incorporated newborn screening expansion timelines, gene therapy regulatory pathway clarity, and Medicaid reimbursement policy shifts.
Underlying measurement precision varies by segment; growth hormone therapy carries tighter precision than gene therapy due to established utilization patterns. Forecasts reflect assumptions about regulatory approval timelines and payer acceptance of curative versus chronic management economics. A model refresh is warranted upon material change in FDA gene therapy guidance or state-level Medicaid formulary restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Rare Disease Clinical Trials Market
Rare Diseases
Pompe Disease Market
Rare Diseases
Middle East and Africa Down Syndrome Market
Rare Diseases
Erdheim-Chester Disease Market
Rare Diseases
Hutchinson-Gilford Progeria Syndrome Market
Rare Diseases
Edward’s Syndrome Treatment Market
Rare Diseases
Rare Neurological Disease Treatment Market
Rare Diseases
Leigh Syndrome Treatment Market
Rare Diseases
Gastrointestinal Rare Diseases Treatment Market
Rare Diseases
Hemophagocytic Lymphohistiocytosis Market
Rare Diseases
Global Rare Hemophilia Factors Market
Rare Diseases
Sarcoidosis Therapeutics Market
Rare Diseases
Andersen-Tawil Syndrome Market
Rare Diseases
Behcets Disease Market
Rare Diseases
Spina Bifida Market
Rare Diseases
North America Rett Syndrome Market