
 Asia-Pacific Down Syndrome Market | 2026-2036
Asia-Pacific Down Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Down Syndrome Market Outlook
Aftermarket service revenue around diagnostic test interpretation and longitudinal counseling is reshaping how value accrues across the Asia-Pacific Down Syndrome landscape. F. Hoffmann-La Roche Ltd leverages its deep assay portfolio to anchor high-margin recurring testing relationships in major hospital networks. Thermo Fisher Scientific sustains technology leadership through advanced genetic analysis platforms that dominate reference laboratory workflows. Natera competes on proprietary non-invasive screening methodologies that extend its reach into outpatient prenatal channels.
The Asia-Pacific Down Syndrome ecosystem encompasses genetic screening technologies, therapeutic interventions, nutritional formulations, and psychosocial support services designed to improve developmental outcomes and quality of life for individuals with trisomy 21. Chromosomal analysis via karyotyping, fluorescence in situ hybridization, and quantitative polymerase chain reaction constitutes the technical backbone of diagnostic confirmation, while applied behavioral analysis and speech-language pathology address core cognitive and communicative deficits. Diagnostic Tests command the largest revenue pool due to mandatory newborn screening expansions across multiple national health programs, though Telemedicine delivery modes represent the fastest structural expansion as rural patient populations gain specialist access through virtual platforms. Educational Support applications concentrate margin potential where government procurement of individualized education plans is formalizing.
Japan's PMDA and Australia's TGA enforce stringent premarket validation requirements for genetic diagnostic kits that shape product registration timelines and clinical evidence standards across the region. India's CDSCO and China's NMPA maintain parallel but divergent pathways for in vitro diagnostic approval that fragment market access strategies for multinational manufacturers. Stakeholders must monitor harmonization negotiations between ASEAN regulatory coalitions and national agencies to anticipate where centralized conformity assessment might consolidate entry costs.
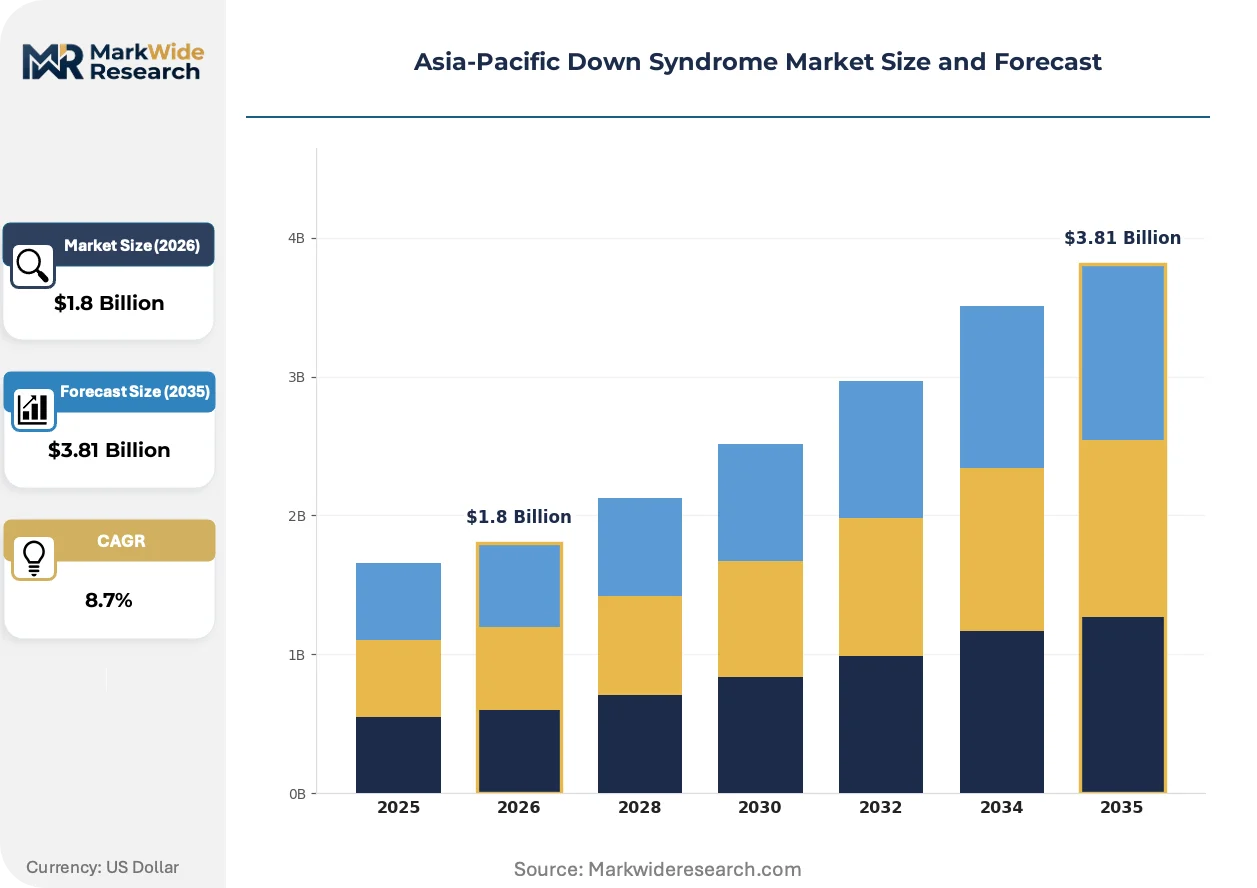
Market Dynamics
Mandatory newborn screening expansions across Asia-Pacific health systems are restructuring demand flows toward hospital-network procurement of chromosomal diagnostic platforms, while India's PLI scheme for medical devices accelerates domestic kit manufacturing.
Growth Catalysts
- Japan's PMDA streamlined approval pathways:Accelerated genetic diagnostic kit registrations reduce time-to-market for non-invasive prenatal testing platforms, expanding hospital laboratory adoption.
- Telemedicine infrastructure:Virtual specialist consultation models penetrate rural Australia and Southeast Asian archipelagos, extending developmental counseling access beyond urban tertiary centers.
- Quantitative polymerase chain reaction:Cost reductions in qPCR instrumentation enable tier-two Chinese hospitals to establish in-house karyotyping confirmation capacity, displacing centralized reference laboratory dependency.
Market Restraints
- Fluorescent probe supply concentration:Specialized FISH probe manufacturing clusters in Germany and the United States create import vulnerability for Asia-Pacific diagnostic laboratories.
- CDSCO fragmented state-level licensing:India's decentralized in vitro diagnostic approval system generates inconsistent compliance timelines across Maharashtra, Karnataka, and Tamil Nadu manufacturing zones.
- Applied behavioral analysis therapist scarcity:Certified ABA practitioner training programs fail to match pediatric diagnostic volume growth in China's tier-one cities.
Strategic Opportunities
- Vietnam's northern economic corridor:Underpenetrated newborn screening coverage in Hanoi and Hai Phong industrial zones offers first-mover positioning for chromosomal analysis platform vendors.
- NMPA digital therapeutics framework:China's emerging regulatory pathway for software-based cognitive intervention tools creates reimbursement precedent for gamified developmental therapy applications.
- Pharmacy-based prenatal screening:Community pharmacy chains in South Korea and Taiwan pilot non-invasive test sample collection, bypassing traditional hospital-based patient routing.
Industry Challenges
- Genetic counselor certification heterogeneity:Australia's TGA recognition standards diverge from Japan's clinical geneticist licensing requirements, complicating cross-border telemedicine service deployment.
- Legacy hospital information system integration:Chromosomal analysis platforms face interoperability friction with entrenched electronic medical record architectures in Southeast Asian public hospital networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Down Syndrome Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Tests, Therapeutic Devices, Medical Nutrition, Counseling Services Delivery Mode: In-Home Care, Telemedicine, Outpatient Care, Hospital Services End User: Pediatrics, Healthcare Providers, Caregivers, Educational Institutions Application: Behavioral Therapy, Health Monitoring, Educational Support, Community Integration |
| Companies Covered | F. Hoffmann-La Roche Ltd, Thermo Fisher Scientific, Natera, Myriad Genetics, AC Immune SA, Alzheon, Annovis Bio, Aelis Farma, NeuroNascent, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Down Syndrome Market Strategic Shifts
Artificial intelligence-assisted karyotype interpretation and cloud-based longitudinal developmental tracking are compressing diagnostic turnaround times while expanding specialist reach into remote patient populations across the region.
Next-generation sequencing platforms are virtualizing the technical workflow of chromosomal abnormality detection. Regional reference laboratories in Singapore and Sydney deploy cloud-connected sequencers that transmit raw data to centralized bioinformatics pipelines, eliminating on-site cytogeneticist staffing requirements. Hospital networks in Thailand and Malaysia are adopting this architecture fastest, collapsing the capital barrier to diagnostic service launch.
China's NMPA revised in vitro diagnostic classification rules now mandate clinical validation datasets sourced from domestic patient cohorts for prenatal screening kit registration. Multinational manufacturers must establish local clinical trial partnerships or license indigenous biobank access, extending product launch timelines. Domestic Chinese assay developers leverage this structural preference to capture share in non-invasive prenatal testing segments.
Rural patient families increasingly demand unbundled diagnostic interpretation services separate from bundled hospital-based care packages. Independent genetic counseling platforms in India and Indonesia now sell standalone post-test consultation blocks through direct-to-patient digital channels, disrupting traditional obstetrician-mediated referral flows. This pattern concentrates in South Indian states and Java's peri-urban districts where smartphone penetration exceeds specialist density.
Asia-Pacific Down Syndrome Market Segmentation
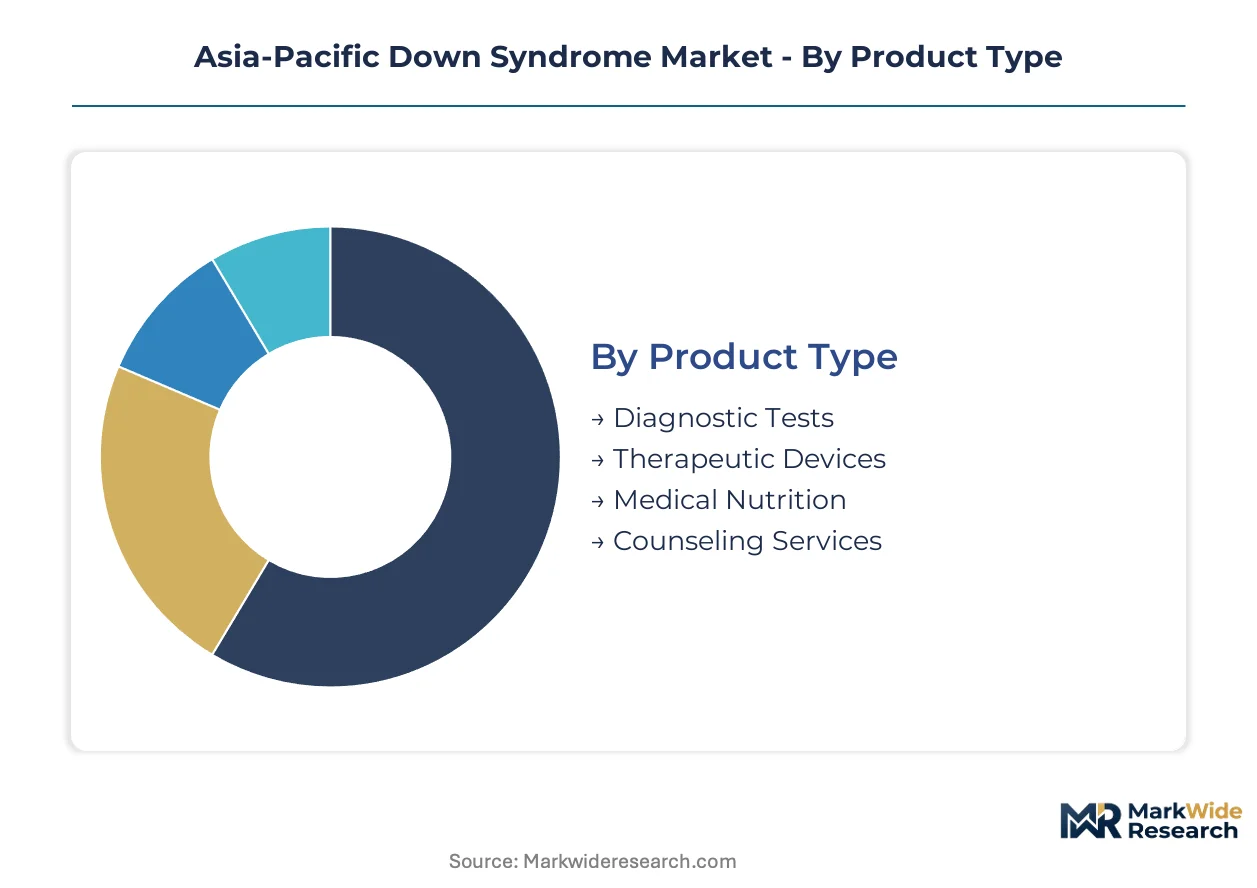
Segmentation in the Asia-Pacific Down Syndrome landscape reveals how clinical workflows, reimbursement pathways, and patient access models diverge across product categories and service delivery channels. Understanding these divisions exposes where procurement decisions concentrate and how regulatory frameworks shape vendor positioning.
Product Type:
The use-case spectrum spans acute diagnostic confirmation through lifelong developmental support, with each product category commanding distinct purchasing authorities and margin structures.
- Diagnostic Tests:Chromosomal analysis platforms including karyotyping, FISH, and qPCR assays form the technical foundation of newborn screening programs. Hospital laboratory procurement in China's tier-one cities and India's metropolitan medical colleges drives volume concentration, though NMPA and CDSCO registration requirements fragment vendor access timelines.
- Medical Nutrition:Specialized metabolic formulations address nutritional deficiencies common in trisomy 21 populations, requiring pediatric endocrinologist prescription and long-term compliance monitoring. Demand clusters in Japan's universal health coverage system and Australia's NDIS-funded disability support frameworks, where reimbursement certainty stabilizes patient adherence.
- Therapeutic Devices:Assistive communication tools and sensory integration equipment support cognitive development milestones.
- Counseling Services:Genetic counseling and psychosocial support navigate family decision-making around screening results and care planning.
The dominant share belongs to Diagnostic Tests, while Medical Nutrition is closing the gap fastest.
Delivery Mode:
Cost tier differentiation separates capital-intensive institutional infrastructure from leaner direct-to-patient channels that bypass traditional facility economics.
- Telemedicine:Virtual specialist consultation platforms collapse geographic barriers to developmental pediatric and genetic counseling expertise. Rural Australia and Indonesia's outer island provinces show steepest adoption curves as smartphone penetration outpaces specialist density, with TGA and Indonesia's Ministry of Health issuing parallel telehealth practice guidelines.
- Hospital Services:Tertiary medical centers anchor complex diagnostic confirmation and acute intervention capacity. China's tier-two hospital expansion and Vietnam's northern economic corridor infrastructure investments concentrate procurement demand, though legacy HIS integration friction slows platform deployment.
- In-Home Care:Family-delivered developmental therapy and health monitoring reduce institutional dependency.
- Outpatient Care:Community-based clinics manage routine surveillance and therapy scheduling.
Hospital Services retain the largest revenue pool, though Telemedicine is expanding most quickly.
End User:
Customer type fragmentation creates multiple decision-making nodes, from institutional procurement committees to individual family budgets.
- Pediatrics:Developmental pediatricians and neonatologists drive initial diagnostic workup and longitudinal care coordination. Japan's pediatric society screening guidelines and India's Rashtriya Bal Swasthya Karyakram program shape demand concentration, with specialist availability constraints in Southeast Asian markets creating access bottlenecks.
- Healthcare Providers:Hospital networks and reference laboratories aggregate capital equipment purchasing power. Singapore's centralized health system procurement and Australia's public hospital network tender processes favor vendors with established service infrastructure.
- Caregivers:Family members execute daily therapy protocols and monitor developmental progress.
- Educational Institutions:Schools and early intervention centers implement individualized education plans.
Pediatrics commands the deepest specialist relationships, while Healthcare Providers are consolidating purchasing influence fastest.
Application:
Application maturity varies sharply between evidence-based clinical interventions and emerging social integration models still seeking reimbursement codification.
- Behavioral Therapy:Applied behavioral analysis and structured developmental interventions address core cognitive and adaptive skill deficits. Certified practitioner scarcity in China's tier-one cities and India's metropolitan areas constrains service expansion, while Australia's NDIS and Japan's disability support systems provide stable funding foundations.
- Educational Support:Individualized education plans and inclusive classroom accommodations formalize learning pathway adaptations. Government procurement standardization in South Korea and Taiwan creates vendor qualification barriers, though margin potential concentrates where public funding mechanisms mature.
- Health Monitoring:Routine surveillance for cardiac, thyroid, and hematologic comorbidities.
- Community Integration:Vocational training and independent living preparation programs.
Behavioral Therapy captures the most established reimbursement, while Educational Support is gaining policy attention fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic kit buyers in Vietnam and Indonesia exhibit acute price sensitivity, while Japanese hospital networks prioritize assay accuracy over procurement cost, creating a demand-elasticity gradient that shapes vendor pricing architectures across the region.
China
Newborn screening coverage expansion in tier-two cities drives chromosomal analysis platform procurement, with NMPA domestic clinical validation requirements extending registration timelines for multinational kit manufacturers. Beijing-Tianjin-Hebei and Yangtze River Delta hospital clusters anchor reference laboratory consolidation.
Japan
PMDA accelerated approval pathways compress time-to-market for non-invasive prenatal testing platforms, expanding hospital laboratory adoption of genetic diagnostic kits. Kanto region tertiary medical centers concentrate high-margin recurring testing relationships with assay portfolio vendors.
India
CDSCO fragmented state-level licensing generates inconsistent compliance timelines across Maharashtra, Karnataka, and Tamil Nadu manufacturing zones, complicating nationwide kit distribution. PLI scheme incentives accelerate domestic diagnostic kit production in Hyderabad-Bengaluru corridor.
Australia
TGA stringent premarket validation requirements shape clinical evidence standards for genetic diagnostic kit registration, while NDIS disability support frameworks stabilize funding for developmental intervention services. Sydney and Melbourne reference laboratories dominate cloud-connected sequencing infrastructure deployment.
South Korea
Community pharmacy chains pilot non-invasive prenatal test sample collection, bypassing traditional hospital-based patient routing and reshaping demand flows toward retail-accessible screening. Seoul Capital Area concentration of genetic counseling platforms extends specialist reach through telemedicine channels.
Asia-Pacific Down Syndrome Market Competitive Environment
Capability concentration sits with specialized genetic assay developers; scale advantage sits with diversified life sciences conglomerates. The market structures around three tiers: multinational diagnostic platform vendors with deep hospital network relationships, emerging domestic kit manufacturers leveraging regulatory localization requirements, and niche telemedicine service providers penetrating rural access gaps. Dominant competitive moves include strategic partnerships with regional reference laboratories and portfolio diversification into longitudinal counseling services.
Within the multinational diagnostic tier, F. Hoffmann-La Roche Ltd and Thermo Fisher Scientific occupy positions anchored by comprehensive assay portfolios and advanced genetic analysis platforms respectively. Natera exemplifies the specialized screening methodology archetype, with its proprietary non-invasive prenatal testing approach representing the outpatient channel penetration strategy that competitors increasingly emulate.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Thermo Fisher Scientific |
| Natera |
| Myriad Genetics |
| AC Immune SA |
| Alzheon |
| Annovis Bio |
| Aelis Farma |
| NeuroNascent |
| Others |
Value Chain & Pricing Dynamics
Hyderabad-Bengaluru corridor manufacturing clusters anchor diagnostic kit production capacity under India's PLI scheme, translating concentrated domestic supply into pricing leverage against imported assay portfolios in tier-two hospital procurement.
Pricing Analysis
Aftermarket service revenue around longitudinal counseling and test interpretation drives lifetime value capture. Three-tier pricing structure across premium, standard, and economy levels separates NMPA-registered multinational assays from CDSCO-approved domestic kits and unbranded institutional contracts. Pricing pressure stems from government tender compression in India's national health programs. Diagnostic laboratories in Vietnam and Indonesia exhibit acute price sensitivity, while Japanese tertiary centers prioritize assay accuracy over procurement cost.
Supply Chain Analysis
Supplier-financing facilities extended by German and US fluorescent probe manufacturers cushion working capital constraints for Asia-Pacific reference laboratories. Manufacturing concentrates in China, India, and South Korea for qPCR instrumentation, chromosomal analysis platforms, and non-invasive prenatal testing consumables. Supply chains draw from specialized FISH probe production, semiconductor-grade optical components, and clinical-grade reagent formulations. Single-source vulnerability in fluorescent probe manufacturing creates import dependency risk. Distribution runs through hospital network procurement committees and centralized reference laboratory consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as mandatory newborn screening programs penetrate Vietnam's northern economic corridor and Indonesia's outer island provinces, with telemedicine infrastructure collapsing specialist access barriers faster than physical capacity deployment.
For Market Incumbents: Build regulatory moats through accelerated NMPA domestic clinical validation partnerships that extend multinational kit registration timelines. Deepen vertical integration into cloud-connected sequencing bioinformatics pipelines to capture recurring service revenue. Defend against emerging domestic Chinese assay developers leveraging structural preference for indigenous patient cohort data. For New Entrants and Emerging Players: Establish a beachhead in Vietnam's underpenetrated Hanoi-Hai Phong industrial corridor where newborn screening coverage gaps outpace installed diagnostic capacity. Target pharmacy-based prenatal screening pilot programs in South Korea and Taiwan as alternative patient routing channels. Lead with direct-to-patient genetic counseling platforms that unbundle interpretation services from hospital-based care packages. For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because cloud-connected sequencing infrastructure and telemedicine service networks exhibit winner-take-most dynamics in rural access expansion. Target acquisition archetypes include niche telemedicine providers with established TGA or PMDA compliance frameworks and domestic kit manufacturers with CDSCO multi-state licensing infrastructure. Monitor NMPA digital therapeutics framework reimbursement precedent as inflection signal for gamified cognitive intervention tool commercialization.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Domestic Clinical Validation Partnership | Accelerates kit registration timelines by leveraging indigenous biobank access in Beijing-Tianjin-Hebei clusters. |
| Cloud-Connected Sequencing Infrastructure Deployment | Eliminates on-site cytogeneticist staffing requirements for Thailand and Malaysia hospital networks. |
| Telemedicine Platform Integration | Extends developmental pediatric specialist reach into rural Australia and Indonesia's outer island provinces. |
| Pharmacy-Based Screening Channel Expansion | Bypasses traditional hospital-based patient routing through South Korean and Taiwanese retail chain partnerships. |
| Longitudinal Counseling Service Bundling | Captures high-margin recurring revenue from post-test interpretation and developmental tracking subscriptions. |
Study Parameters
The analysis maps genetic screening technologies, therapeutic interventions, nutritional formulations, and psychosocial support services, each validated through hospital laboratory directors, genetic counseling platform operators, pediatric endocrinologists, and GPO contracts managers. Primary interviews with these stakeholders combined secondary sources including NMPA registration filings, CDSCO state-level licensing records, PMDA accelerated approval pathway documentation, and TGA premarket validation standards. Bottom-up segment sizing and top-down macroeconomic triangulation anchored volume and value estimates.
Assumptions around NMPA domestic clinical validation requirements, PLI scheme incentive continuity, and telemedicine reimbursement codification were held fixed across the projection horizon, while qPCR instrumentation cost trajectories and certified ABA practitioner training program expansion were varied. Segmentation dimensions modeled include product type, delivery mode, end user, and application, with CAGRs derived from trend extrapolation against historical newborn screening program penetration curves and hospital infrastructure investment cycles.
Stress conditions across regulatory harmonization negotiations, fluorescent probe supply disruptions, and genetic counselor certification heterogeneity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions. Macroeconomic contraction, abrupt regulatory pathway revisions, or breakthrough non-invasive diagnostic technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Chronic Granulomatous Disease (CGD) Management Market
Rare Diseases
Alzheimer Disease Market
Rare Diseases
Acid Sphingomyelinase Deficiency Market
Rare Diseases
Middle East and Africa Down Syndrome Market
Rare Diseases
Middle East and Africa Rett Syndrome Market
Rare Diseases
Lennox-Gastaut Syndrome Market
Rare Diseases
Malignant Infantile Osteopetrosis Market
Rare Diseases
Hemophagocytic Lymphohistiocytosis Market
Rare Diseases
Atypical Hemolytic Uremic Syndrome (Ahus) Treatment Market
Rare Diseases
Arthrogryposis Management Market
Rare Diseases
Rare Inflammatory Disease Treatment Market
Rare Diseases
Achondrogenesis Market
Rare Diseases
Global Tyrosine Hydroxylase Deficiency Market
Rare Diseases
Global Rare Hemophilia Factors Market
Rare Diseases
Dystrophic Epidermolysis Bullosa Market
Rare Diseases
Global Guillain-Barre Syndrome Market