
 Global Chromatography Syringes Market | 2026-2036
Global Chromatography Syringes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chromatography Syringes Market Foresight
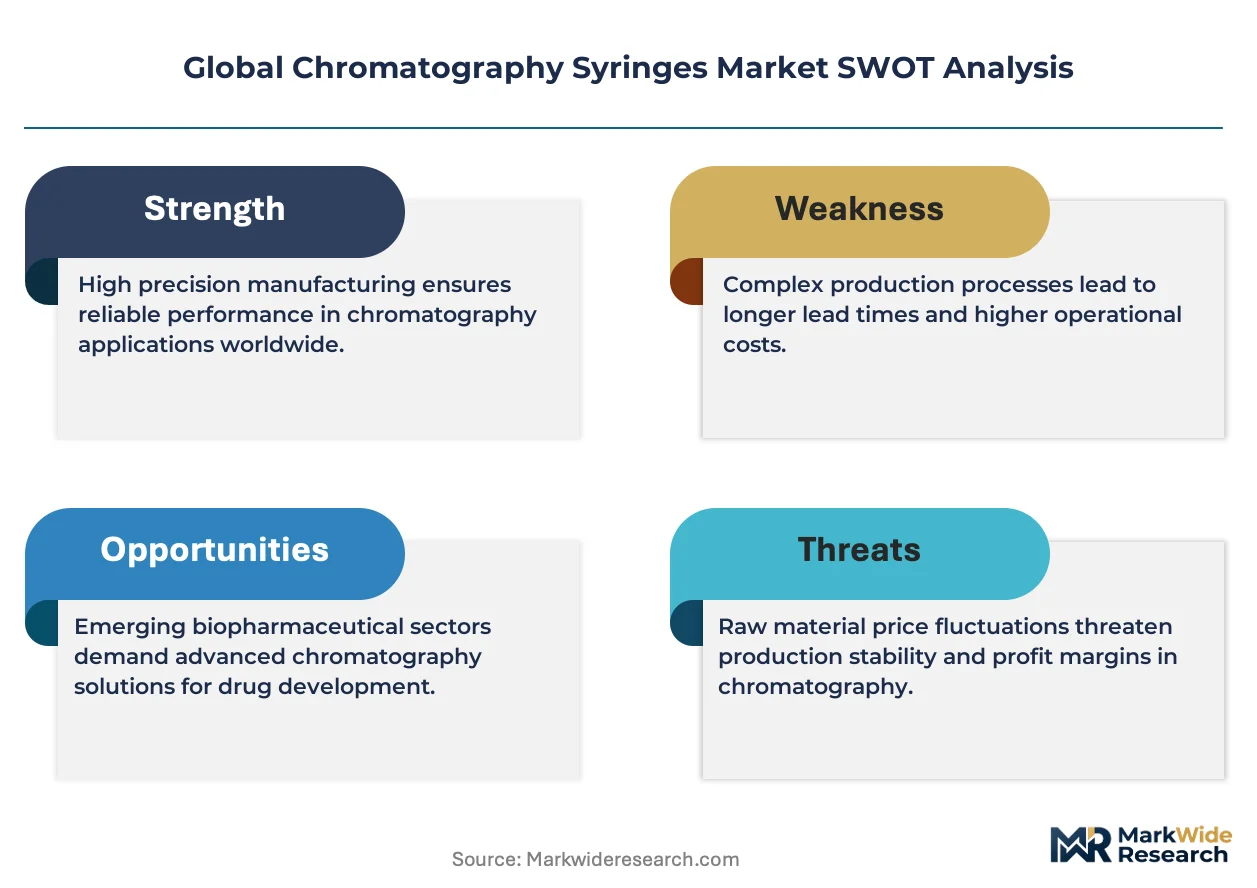
A shortage of precision glassblowers and metrology technicians is unwinding manufacturing capacity across the chromatography syringe supply base. Hamilton Company leverages its captive needle-point fabrication facilities in Nevada and Switzerland to sustain delivery reliability for high-volume pharmaceutical clients. Agilent Technologies anchors its syringe portfolio through deep integration with its LC and GC instrument ecosystems, while Thermo Fisher Scientific competes by extending aftermarket service contracts that bundle consumable replacement schedules.
Chromatography syringes are precision fluid-handling devices engineered with borosilicate glass barrels, stainless steel plungers, and PTFE-tipped seals to deliver microliter-to-milliliter sample volumes into analytical separation systems. These instruments must maintain tight dead-volume tolerances and chemical inertness to prevent sample degradation during injection into gas chromatographs, liquid chromatographs, or headspace analyzers. Liquid chromatography syringes dominate unit shipments due to their ubiquity in pharmaceutical quality control workflows, whereas gas chromatography syringes command stronger pricing power because of their specialized needle geometries and higher thermal tolerance requirements. Auto-sampler syringes represent the fastest-expanding product category as laboratories automate high-throughput screening protocols to reduce operator-induced injection variability.
The FDA enforces stringent biocompatibility and sterility standards for syringes used in pharmaceutical analytical methods, while the EPA mandates specific sampling precision thresholds for environmental contaminant testing protocols. EMA's MDR framework and REACH substance restrictions are reshaping material choices, pushing manufacturers toward silicone-free plunger tip formulations and heavy-metal-free glass compositions. Stakeholders must monitor how dual carbon goals in China and evolving ISO 17025 accreditation requirements in analytical laboratories will redirect procurement specifications toward lower-embodied-carbon syringe designs and extended-use durability benchmarks.
Market Dynamics
Laboratories in Germany, the United States, and China are consolidating instrument procurement around integrated consumable ecosystems, compressing standalone syringe vendor access and favoring suppliers with captive needle fabrication and metrology capabilities.
Growth Catalysts
- EMA MDR Framework:Stricter biocompatibility documentation for analytical devices is driving replacement cycles in European pharmaceutical quality control labs, expanding demand for certified consumables.
- Auto-sampler automation:High-throughput screening protocols in contract research organizations are accelerating adoption of precision-engineered syringes with programmable injection volumes.
- China:Dual carbon goals and expanding analytical instrumentation clusters in Shanghai and Beijing are redirecting procurement toward durable, extended-use syringe designs with lower embodied carbon.
Market Restraints
- Specialized glassblower scarcity:Precision borosilicate barrel production depends on artisanal craft skills concentrated in Switzerland and Germany, creating supply bottlenecks during demand surges.
- Platinum-iridium alloy costs:Needle-point fabrication requires precious metals subject to commodity price volatility, squeezing margin stability for mid-tier manufacturers.
- REACH substance restrictions:Silicone and heavy-metal limitations are forcing reformulation of plunger tip chemistries, extending R&D timelines and certification costs.
Strategic Opportunities
- India:CDSCO regulatory harmonization and expanding pharmaceutical manufacturing under PLI schemes are opening procurement channels for ISO 17025-certified consumable suppliers.
- Headspace analysis:Environmental contaminant testing protocols under EPA mandates are creating demand for specialized gas chromatography syringes with thermal tolerance above 300°C.
- Service contract bundling:Predictive replacement scheduling integrated with instrument maintenance agreements is capturing multi-year consumable commitments from large laboratory networks.
Industry Challenges
- Metrology technician shortage:Dead-volume tolerance verification requires specialized calibration expertise that training programs in Nevada and Switzerland struggle to replenish.
- ISO 17025 accreditation timelines:Laboratory certification delays in analytical facilities are compressing vendor qualification windows and extending sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chromatography Syringes Market |
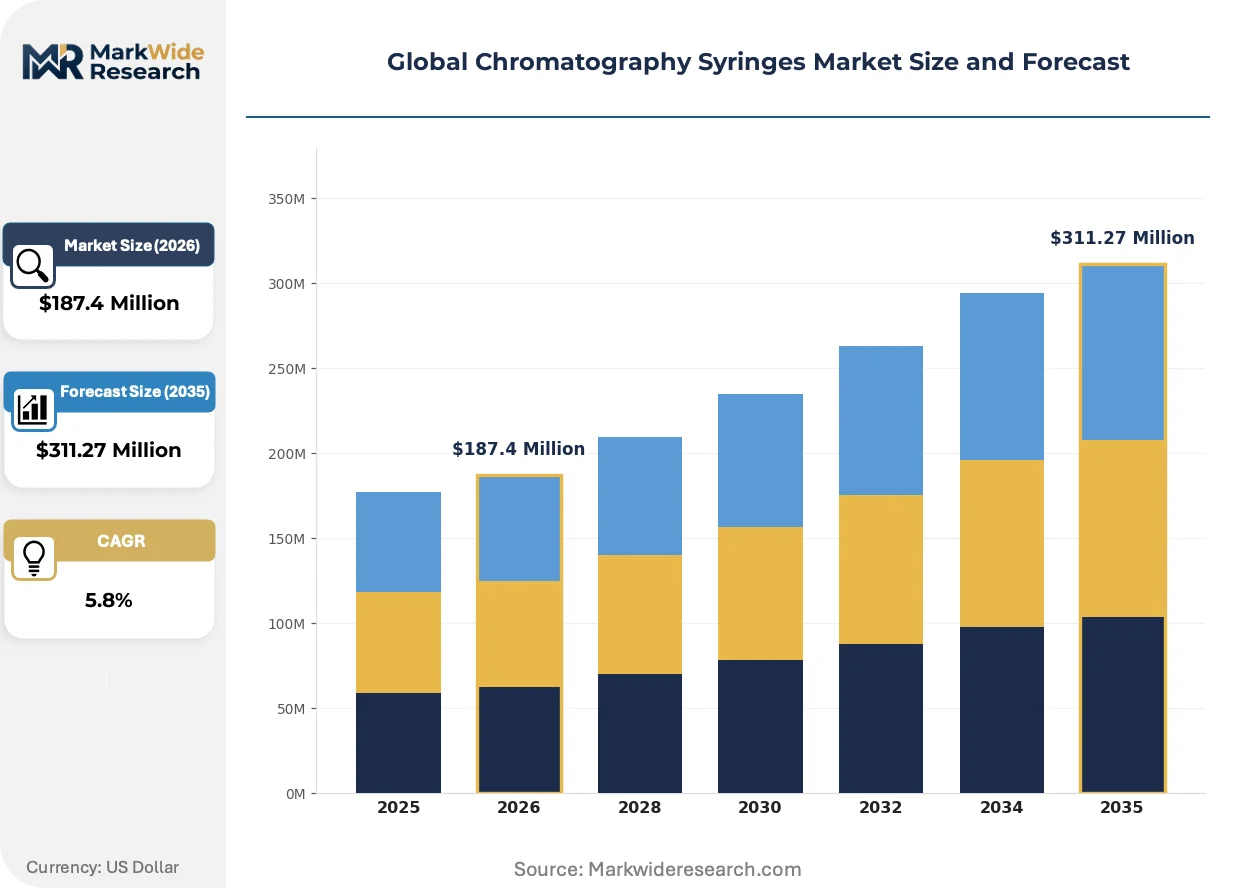
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Chromatography Syringes, Liquid Chromatography Syringes, Headspace Syringes, Auto-sampler Syringes, Micro Syringes Material: Stainless Steel, Borosilicate Glass, PTFE, High-Density Polyethylene, Silicone Application: Pharmaceutical Analysis, Environmental Testing, Food & Beverage Quality Control, Petrochemical Screening, Forensic Inspection End User: Analytical Laboratories, Research Institutions, Quality Assurance Facilities, Contract Testing Labs, Academic Centers |
| Companies Covered | Hamilton Company, Agilent Technologies, Inc., Thermo Fisher Scientific Inc., Shimadzu Corporation, Restek Corporation, SGE Analytical Science, Trajan Scientific and Medical, VICI AG International, PerkinElmer, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chromatography Syringes Market Shifts & Advancements
Material science advances and regulatory material restrictions are converging to reshape syringe construction, while procurement centralization is restructuring how laboratories source precision consumables.
Silicone-free plunger tip formulations incorporating perfluoroelastomer composites are supplanting traditional PTFE-tipped seals in pharmaceutical analytical workflows. EMA and FDA biocompatibility reviewers are prioritizing heavy-metal-free documentation, accelerating formulation switches among quality control laboratories in Germany and Switzerland. This transition is compressing market share for legacy seal suppliers unable to certify alternative chemistries under REACH substance restrictions.
EPA testing protocol revisions for environmental contaminant sampling are mandating tighter precision thresholds for gas chromatography injection systems. Contract laboratories in the United States must recalibrate or replace syringe fleets to maintain accreditation, redirecting capital toward certified consumable suppliers. The affected segment—environmental testing services—is consolidating vendor relationships around suppliers with documented traceability systems.
Centralized procurement through group purchasing organizations is displacing direct laboratory purchasing autonomy in large pharmaceutical and contract research networks. Instrument manufacturers with captive consumable portfolios are capturing preference through integrated sourcing portals, squeezing standalone syringe vendors from preferred supplier lists. This pattern concentrates most visibly in the United States, where laboratory network consolidation has advanced furthest.
Global Chromatography Syringes Market Segmentation
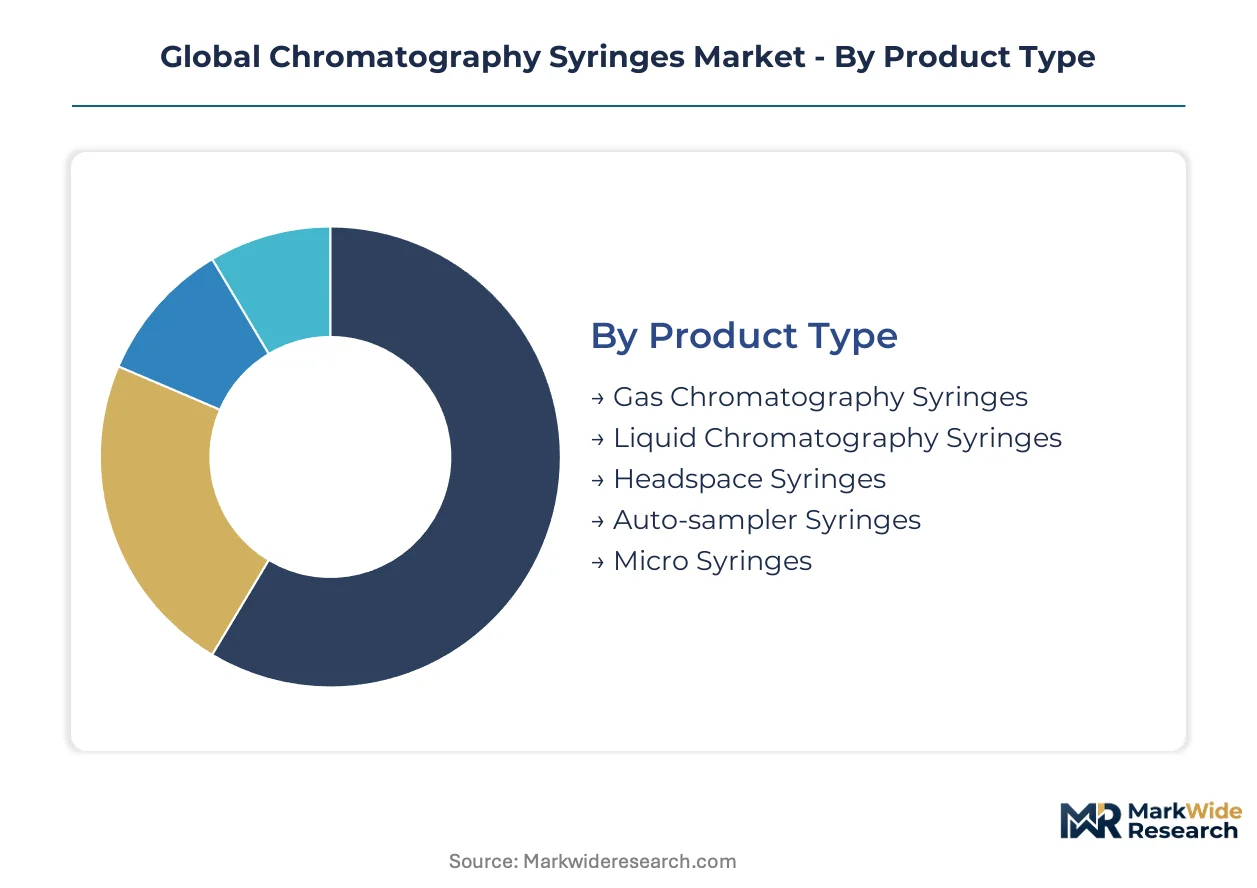
Chromatography syringe procurement flows through distinct channel architectures shaped by regulatory certification requirements and instrument integration needs. Each segmentation dimension reveals how supply routes bifurcate between integrated instrument ecosystems and standalone consumable vendors.
Product Type:
Channel distribution varies sharply across product categories, with auto-sampler syringes flowing predominantly through instrument OEM portals while manual syringes sustain distributor networks serving smaller laboratories.
- Liquid Chromatography Syringes:Borosilicate glass barrels with stainless steel plungers dominate pharmaceutical quality control workflows in Germany and the United States. Demand concentrates in contract research organizations automating high-throughput screening protocols under FDA biocompatibility mandates.
- Auto-sampler Syringes:Precision-engineered with programmable injection volumes and PTFE-tipped seals, these devices integrate directly with LC and GC instrument platforms. Procurement centralizes through Agilent and Thermo Fisher captive consumable portals serving large laboratory networks in China and the United States.
- Gas Chromatography Syringes:Specialized needle geometries with platinum-iridium alloy points command premium positioning through environmental testing channels under EPA protocol requirements.
- Headspace Syringes:Thermal tolerance above 300°C serves volatile organic compound analysis in contract laboratories.
- Micro Syringes:Microliter precision targets forensic inspection and specialized research applications.
Liquid chromatography syringes dominate installed base. Auto-sampler syringes are where expansion concentrates most steeply.
Material:
Cost tier stratification separates premium-certified materials from economy alternatives, with REACH-compliant formulations commanding 40-60% price premiums over legacy chemistries.
- Borosilicate Glass:Artisanal production in Switzerland and Germany supplies precision barrels with tight dead-volume tolerances for pharmaceutical analytical methods. Scarcity of qualified glassblowers constrains capacity expansion during demand surges in the United States and China.
- PTFE:Traditional plunger tip material faces displacement from silicone-free alternatives under EMA MDR biocompatibility documentation requirements. Reformulation investments extend R&D timelines for mid-tier manufacturers serving European quality control laboratories.
- Stainless Steel:Plunger construction standard across premium product tiers, with 316-grade variants specified for corrosive solvent compatibility.
- High-Density Polyethylene:Cost-effective barrel alternative for non-critical environmental screening applications.
- Silicone:Restricted under REACH substance limitations, forcing rapid phase-out in pharmaceutical workflows.
Borosilicate glass anchors premium tier positioning. PTFE reformulation represents the steepest technology transition.
Application:
Customer type segmentation separates regulated pharmaceutical testing from price-sensitive environmental screening, with accreditation requirements determining vendor qualification thresholds.
- Pharmaceutical Analysis:FDA and EMA biocompatibility standards enforce certified consumable procurement through ISO 17025-accredited suppliers. German and Swiss quality control laboratories drive replacement cycles under tightened MDR documentation requirements.
- Environmental Testing:EPA precision threshold mandates for contaminant sampling recalibrate syringe fleet specifications across United States contract laboratories. Consolidation favors suppliers with documented traceability systems.
- Food & Beverage Quality Control:FSSAI and national regulator harmonization in India opens procurement channels under CDSCO-aligned standards.
- Petrochemical Screening:Thermal and solvent resistance specifications favor stainless steel and glass configurations.
- Forensic Inspection:Micro-volume precision requirements sustain specialty distributor channels.
Pharmaceutical analysis commands premium pricing tiers. Environmental testing is where vendor consolidation accelerates.
End User:
Volume concentration among large laboratory networks enables group purchasing organization leverage, compressing standalone vendor access.
- Analytical Laboratories:Integrated instrument-consumable ecosystems dominate procurement in the United States and China, with Hamilton and Agilent capturing preference through captive needle fabrication capabilities.
- Contract Testing Labs:High-throughput automation drives auto-sampler syringe adoption with predictive replacement scheduling bundled into multi-year service agreements.
- Research Institutions:Grant-funded procurement sustains distributor channels for specialized micro-syringe configurations.
- Quality Assurance Facilities:Regulatory audit requirements enforce certified supplier lists with documented traceability.
- Academic Centers:Price sensitivity sustains economy-tier material options through educational pricing programs.
Analytical laboratories concentrate procurement volume. Contract testing labs are where service contract bundling advances fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States pharmaceutical laboratories favor auto-sampler integration, while German quality control facilities prioritize manual precision syringes for compendial testing. Chinese analytical clusters are leapfrogging toward automated platforms, diverging from the instrument-agnostic procurement patterns still common in Indian contract research operations.
United States
Environmental testing laboratories under EPA contaminant protocols drive specialized gas chromatography syringe procurement with thermal tolerance specifications above 300°C. FDA biocompatibility enforcement for pharmaceutical analytical methods sustains replacement cycles in quality control facilities. The Boston-Cambridge analytical instrumentation cluster concentrates contract research organization demand for high-throughput auto-sampler systems.
Germany
REACH substance restrictions and EMA MDR documentation requirements are accelerating silicone-free plunger tip reformulation in pharmaceutical quality control workflows. Artisanal borosilicate glass barrel production concentrates in southern German manufacturing zones. The Rhine-Main analytical services corridor hosts ISO 17025-accredited laboratories consolidating vendor relationships around integrated consumable ecosystems.
China
Dual carbon goals and NMPA regulatory harmonization are redirecting procurement toward extended-use syringe designs with lower embodied carbon in Shanghai and Beijing instrumentation clusters. SAMR quality certification requirements tighten material traceability standards for domestic consumable manufacturers. The Yangtze River Delta analytical services hub is automating high-throughput screening protocols at scale.
India
CDSCO regulatory alignment with international pharmaceutical standards is opening procurement channels for ISO 17025-certified consumable suppliers under PLI scheme incentives. FSSAI food safety testing expansion drives environmental and quality control syringe demand. The Hyderabad-Bengaluru pharmaceutical manufacturing corridor concentrates contract research organization instrument procurement.
Switzerland
Swissmedic pharmaceutical device oversight and REACH-compliant material documentation sustain premium-tier syringe positioning for precision analytical applications. Captive needle-point fabrication capabilities concentrate in western Swiss manufacturing zones. The Basel pharmaceutical quality control cluster maintains stringent biocompatibility certification requirements for consumable procurement.
Global Chromatography Syringes Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the chromatography syringe supply base. Instrument manufacturers with captive consumable portfolios leverage ecosystem lock-in through integrated sourcing portals, while standalone precision fabricators compete on metrology capabilities and material certification depth. Three archetypes define competitive positioning: integrated instrument-consumable ecosystems, captive needle fabrication specialists, and precision glassblowers with artisanal barrel production. Dominant competitive moves include backward integration into needle-point manufacturing and multi-year service contract bundling with predictive replacement scheduling.
Among integrated instrument ecosystem providers, Agilent Technologies, Inc. and Thermo Fisher Scientific Inc. exemplify the captive consumable portal model that is compressing standalone vendor access in large laboratory networks. Hamilton Company anchors the precision fabrication specialist tier with geographic concentration in Nevada and Switzerland. These three entities represent distinct strategic positions: ecosystem integration, scale-driven service bundling, and artisanal precision manufacturing with vertical control over critical components.
| Leading Market Players |
|---|
| Hamilton Company |
| Agilent Technologies, Inc. |
| Thermo Fisher Scientific Inc. |
| Shimadzu Corporation |
| Restek Corporation |
| SGE Analytical Science |
| Trajan Scientific and Medical |
| VICI AG International |
| PerkinElmer, Inc. |
| Others |
Supply & Pricing Matrix
Captive needle-point fabrication at scale in Nevada and Switzerland creates defensive moats that compress margin competition among standalone syringe vendors. Scale economies in metrology calibration and platinum-iridium alloy procurement anchor price floors for precision-tier products, while REACH-compliant material reformulation extends R&D recovery timelines across European supply bases.
Pricing Analysis
Long-term service contracts with predictive replacement scheduling dominate procurement in large pharmaceutical and contract research networks, displacing spot purchasing for auto-sampler syringes. Three-tier pricing structure across premium certified, standard ISO-compliant, and economy non-critical tiers separates pharmaceutical quality control laboratories from environmental screening facilities. Cost compression in mid-tier manual syringes is intensifying because platinum-iridium alloy volatility squeezes manufacturers without captive metal fabrication. Academic centers and smaller environmental testing labs exhibit highest price sensitivity, whereas FDA-audited pharmaceutical facilities prioritize certification depth over unit cost.
Supply Chain Analysis
Switzerland and Germany anchor artisanal borosilicate glass barrel production, with Nevada and China expanding precision machining capacity for plunger and needle components. Raw material dependencies center on platinum-iridium alloys for needle points, perfluoroelastomer composites for silicone-free seals, and heavy-metal-free glass formulations for REACH compliance. Single-source vulnerability concentrates in Swiss glassblower guilds, where apprenticeship pipelines fail to replenish retiring artisanal talent. Distribution runs through instrument OEM captive portals for auto-sampler syringes, while manual configurations sustain authorized distributor networks serving smaller laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across regulatory certification tiers creates niche opportunities as EMA MDR documentation requirements and EPA precision mandates splinter procurement specifications beyond one-size-fits-all supply.
For Market Incumbents: Fortify captive needle fabrication capabilities in Nevada and Switzerland to defend against mid-tier manufacturers sourcing from third-party metalworkers. Deepen ISO 17025 accreditation depth across plunger tip reformulation lines to capture replacement cycles triggered by REACH silicone restrictions. Instrument ecosystem lock-in through integrated consumable portals remains the critical defensive lever against standalone syringe vendors. For New Entrants and Emerging Players: CDSCO-aligned ISO 17025 fast-track certification opens procurement channels under India's PLI scheme incentives for pharmaceutical manufacturing expansion. Target environmental testing laboratories in the United States requiring thermal-tolerant gas chromatography syringes above 300°C, where EPA protocol recalibration creates fleet replacement demand. Service contract bundling with predictive analytics for replacement scheduling offers the most penetrable go-to-market angle against entrenched instrument OEMs. For Investors and Strategic Acquirers: Precision glassblowing specialists with artisanal barrel production capabilities represent acquisition targets with irreplaceable craft knowledge concentrated in Switzerland and southern Germany. Long-term viability over the coming decade rests on whether captive needle fabrication and metrology calibration depth can sustain margin structures against automated platform consolidation. The signal to watch is auto-sampler penetration rates in Chinese analytical instrumentation clusters, where dual carbon goals and NMPA harmonization redirect capital toward extended-use designs.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Needle Fabrication Expansion | Backward integration into platinum-iridium point production defends margin stability against commodity volatility. |
| Silicone-Free Seal Reformulation | Perfluoroelastomer composite development captures EMA MDR-driven replacement cycles in German quality control labs. |
| Auto-Sampler Platform Integration | Programmable injection volume engineering locks consumable procurement into Agilent and Thermo Fisher ecosystems. |
| ISO 17025 Accreditation Investment | Certification depth qualifies vendors for FDA-audited pharmaceutical analytical methods in United States facilities. |
| Service Contract Bundling | Predictive replacement scheduling integrated with instrument maintenance captures multi-year consumable commitments. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 483 inspection observations, EMA MDR technical documentation, and EPA environmental testing protocol revisions. Interviews with quality control laboratory directors, chromatography instrument procurement managers, precision glassblowing shop owners, and metrology calibration technicians informed supply-side constraint assessment. Secondary validation drew from REACH substance restriction databases, ISO 17025 accreditation registries, and customs trade data for borosilicate glass and platinum-group metal flows. Bottom-up segment sizing triangulated against top-down instrument installed base estimates.
Segmentation dimensions modeled include product type, material composition, application workflow, and end-user procurement channel across the projection horizon. CAGRs derive from instrument replacement cycles, regulatory recalibration timelines, and automation adoption curves in contract research organizations. Forecast inputs incorporate platinum-iridium price volatility bands, glassblower apprenticeship completion rates, and auto-sampler penetration trajectories in Chinese analytical clusters.
Underlying assumptions cover sustained EMA MDR enforcement stringency and EPA protocol precision threshold maintenance, with deviation risk concentrated in REACH substance restriction expansion beyond silicone and heavy metals. Recalibration cycles align with material shifts in dual carbon procurement mandates and NMPA-SAMR regulatory harmonization announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Lumbar Puncture Trays and Needles Market
Medical Supplies
Global Hospital Supplies Market
Medical Supplies
US Disposable Face Mask Market
Medical Supplies
Serological Pipettes Market
Medical Supplies
Pressure Monitoring Extension Tubing Sets Market
Medical Supplies
Compression Stockings Market
Medical Supplies
North America Surgical Glue Market
Medical Supplies
Cryogenic Vials and Tubes Market
Medical Supplies
Anti-Adhesion Barrier Gels Market
Medical Supplies
Measured Volume Burette Set Market
Medical Supplies
Blood Collection Tubes for Liquid Biopsy Market
Medical Supplies
Surgical Collagen Powders Market
Medical Supplies
Global Contact Lens Solution Market
Medical Supplies
Cryogenic Vials Market
Medical Supplies
Micro Vials Market
Medical Supplies
Europe Custom Procedure Kits Market