
 Global Pharmaceutical Gelatin Market | 2026-2036
Global Pharmaceutical Gelatin Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pharmaceutical Gelatin Market Foresight
Bovine-derived gelatin production in Argentina and Brazil is expanding to serve pharmaceutical-grade supply chains. Gelita AG leverages backward integration into collagen sourcing to secure raw material traceability. Rousselot anchors its competitive position through specialized hydrolyzed gelatin lines for controlled-release applications. PB Leiner differentiates via halal-certified production systems that unlock access across Middle Eastern and Southeast Asian pharmaceutical markets.
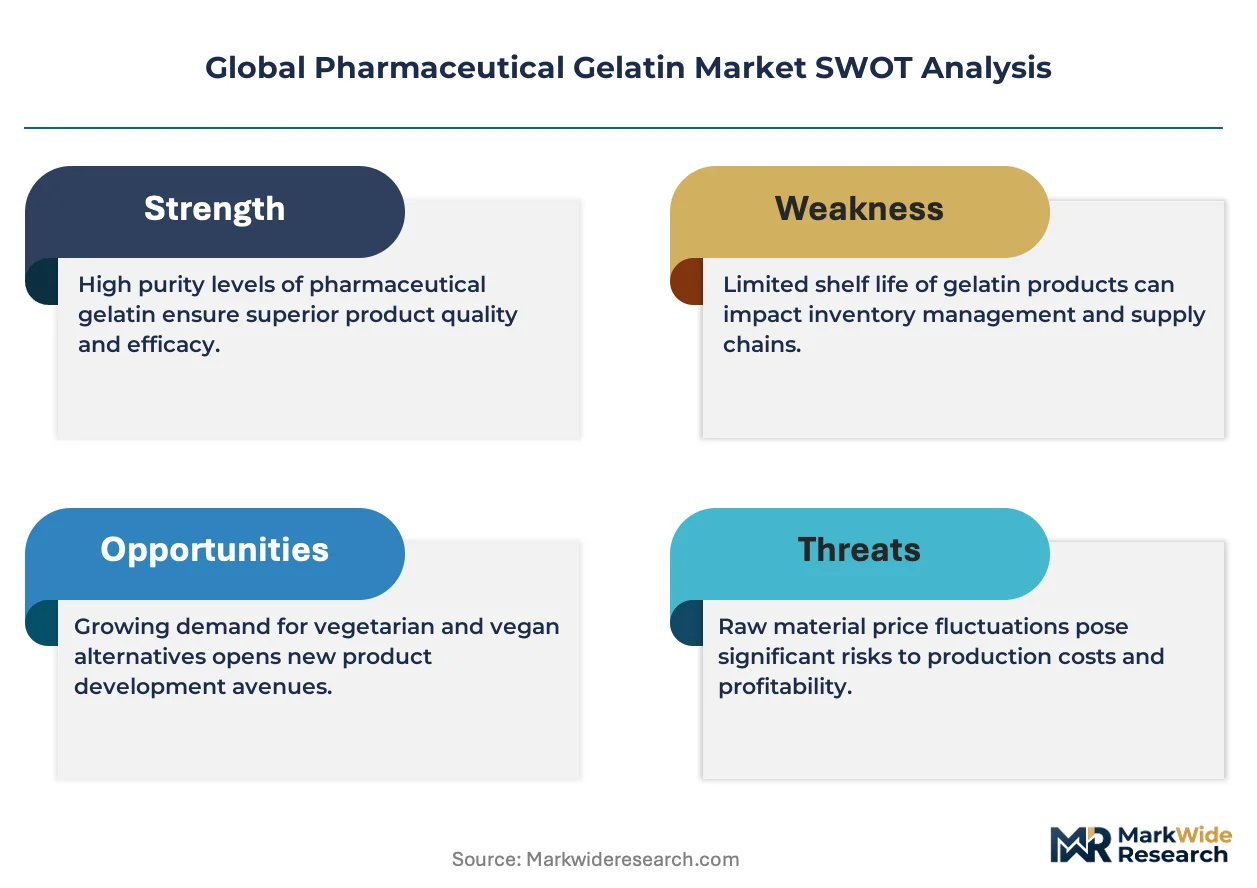
Pharmaceutical gelatin denotes purified collagen hydrolysate with specified bloom strength between 150 and 250 grams, extracted through acid or alkaline processing of mammalian or piscine connective tissues, and functionalized for film-forming, encapsulation, and binding in dosage form manufacturing. Type B gelatin, derived from lime-processed bovine hides, dominates capsule shell applications due to superior mechanical stability and dissolution predictability. Fish gelatin occupies the fastest-expanding niche as religious dietary restrictions and bovine spongiform encephalopathy concerns redirect formulation sourcing toward marine-origin alternatives. Porcine gelatin retains entrenched positions in tablet binding where cost efficiency outweighs substitution pressure.
EMA enforces traceability mandates through its veterinary medicinal product framework, while USP-NF monographs define dissolution and identification thresholds that determine batch acceptance. India's CDSCO aligns import and domestic manufacturing standards with ICH Q7 guidelines, elevating compliance costs for uncertified suppliers. Stakeholders must monitor regulatory divergence between pharmacopeial systems as dual-registration requirements fragment procurement strategies and reshape supplier qualification timelines.
Market Dynamics
Pharmaceutical gelatin supply chains are tightening around bovine-derived sourcing as EMA traceability mandates and USP dissolution standards force material qualification timelines upward. Hard capsule manufacturers face compressed batch acceptance windows while navigating religious dietary restrictions that fragment raw material procurement across mammalian and marine origins.
Growth Catalysts
- EMA Veterinary Traceability Framework:Batch-level documentation requirements for bovine-derived materials are elevating supplier qualification barriers, concentrating procurement among certified producers with backward-integrated collagen sourcing.
- India CDSCO ICH Q7 Alignment:Domestic pharmaceutical manufacturing expansion is accelerating demand for pharmaceutical-grade gelatin as export-oriented API production intensifies compliance requirements.
- Fish Gelatin Processing Advances:Marine-origin extraction technologies are unlocking supply alternatives where religious restrictions and BSE concerns previously blocked mammalian material adoption.
Market Restraints
- Bovine Hide Input Volatility:Argentina and Brazil hide supply fluctuations transmit directly to Type B gelatin cost structures, compressing margin predictability for capsule shell manufacturers.
- Pharmacopeial Divergence:EMA stability requirements, USP-NF dissolution thresholds, and India CDSCO import standards create dual-registration friction that fragments procurement strategies and extends supplier qualification timelines.
- Halal Certification Concentration:Limited halal-certified production capacity restricts access to Middle Eastern and Southeast Asian pharmaceutical markets, capping addressable demand for uncertified suppliers.
Strategic Opportunities
- Controlled-Release Formulation Expansion:Specialized hydrolyzed gelatin lines for modified-release tablets represent underpenetrated demand as pharmaceutical manufacturers reformulate immediate-release portfolios.
- India Domestic Production Surge:API manufacturing cluster growth in Hyderabad and Ahmedabad is generating localized demand for pharmaceutical-grade gelatin with reduced import dependency.
- ISO 22000 Convergence:Unified food safety management certification is streamlining cross-border supplier qualification, reducing redundant audit burdens for multi-jurisdictional pharmaceutical manufacturers.
Industry Challenges
- Bloom Strength Calibration Expertise:Scarce technical personnel capable of maintaining 150-250 gram specification ranges across acid and alkaline processing lines are extending production ramp-up timelines for new facilities.
- Dual Carbon Compliance Capex:Lime-processing effluent treatment and energy-intensive drying operations require substantial capital deployment as environmental enforcement tightens in major production geographies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pharmaceutical Gelatin Market |
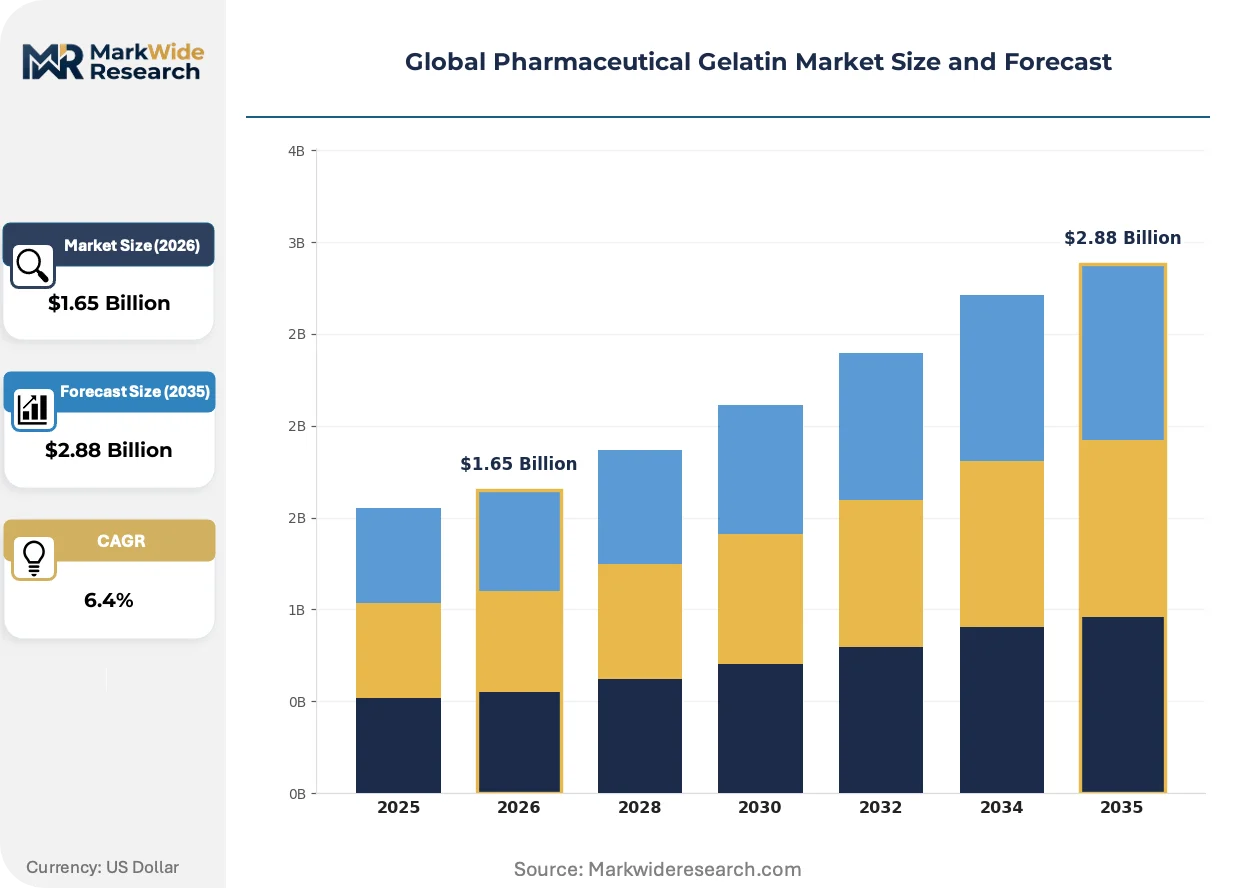
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $2.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Type A Gelatin, Type B Gelatin, Fish Gelatin, Bovine Gelatin, Porcine Gelatin Application: Capsule Shells, Tablet Binding, Plasma Expanders, Wound Care, Protein Supplements End User: Pharmaceutical Manufacturers, Contract Research Organizations, Nutraceutical Companies, Medical Device Producers, Biotechnology Firms Packaging Type: Bulk Bags, Drums, Vacuum Packs, Sachets, Intermediate Bulk Containers |
| Companies Covered | Gelita AG, Rousselot (Darling Ingredients), PB Leiner, Nitta Gelatin Inc., Weishardt, Tessenderlo Group, Funingpu Biotechnology, India Gelatine & Chemicals Ltd, Lapi Gelatine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pharmaceutical Gelatin Market Shifts & Advancements
Automation of quality control and batch release processes is compressing pharmaceutical gelatin manufacturing timelines while raising the technical floor for supplier participation. Regulatory digitization and alternative sourcing technologies are simultaneously reshaping competitive requirements.
Near-infrared spectroscopy coupled with machine learning algorithms is automating real-time bloom strength verification during gelatin extraction. Hard capsule manufacturers in Germany and Switzerland are deploying these systems to eliminate offline laboratory delays. This automation is compressing batch release cycles from days to hours, enabling just-in-time inventory models that reduce working capital requirements.
REACH Annex XVII restrictions on collagen-derived substances are tightening substance registration obligations for EU-based gelatin processors. The regulation is forcing reformulation documentation for legacy capsule shell products and accelerating migration toward pre-registered marine-origin alternatives. Pharmaceutical manufacturers with pan-European distribution are prioritizing suppliers with completed SVHC dossiers to avoid supply interruption.
Consolidated procurement through pharmaceutical contract manufacturing organizations is displacing direct raw material purchasing by mid-sized generic drug producers. CDMOs in India and Eastern Europe are capturing gelatin sourcing decisions through integrated formulation services that bundle excipient supply. This channel concentration is most visible in the Indian pharmaceutical export sector, where API-to-capsule integrated manufacturing is reducing standalone gelatin spot purchases.
Global Pharmaceutical Gelatin Market Segmentation
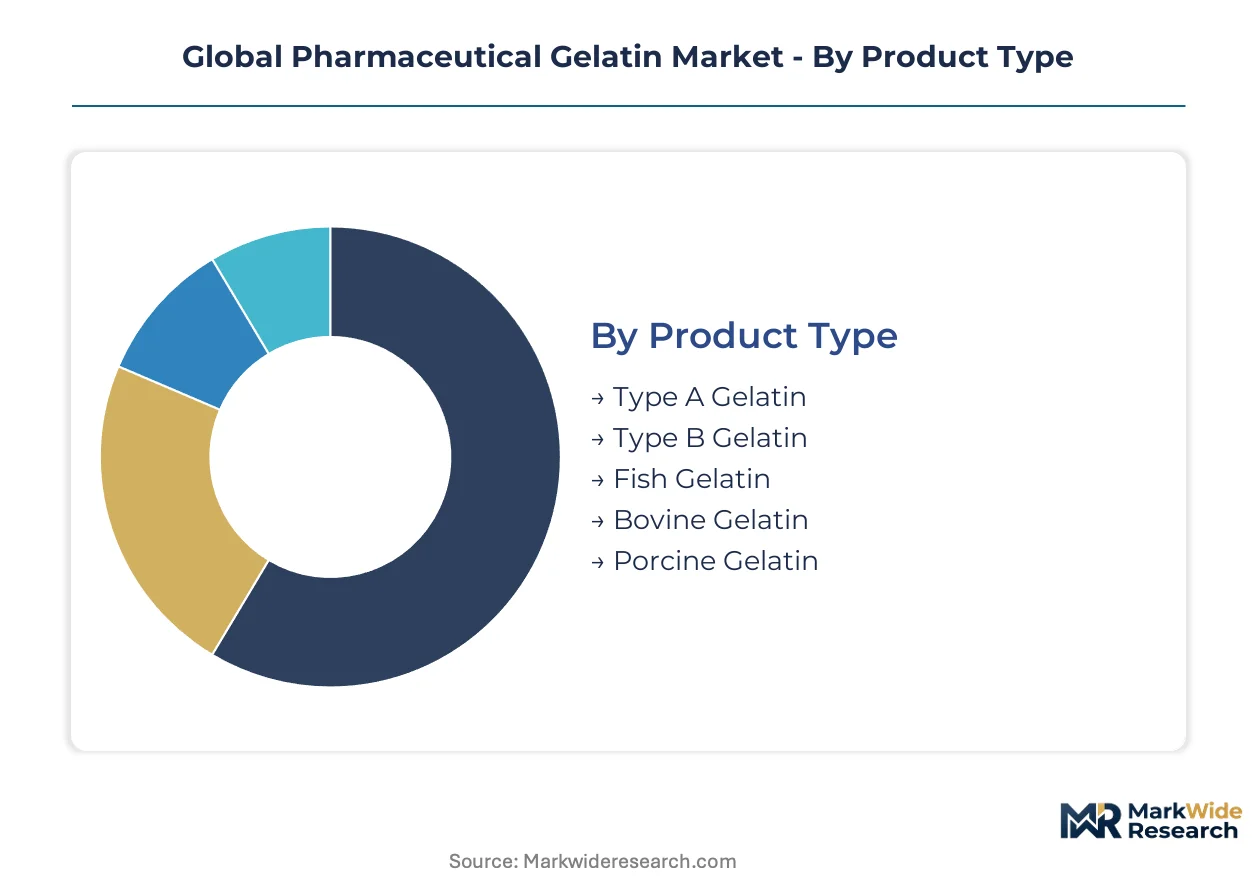
Pharmaceutical gelatin procurement strategies diverge sharply across product chemistry, dosage form application, and end-user scale. Segment-level specifications determine supplier qualification pathways, with EMA traceability mandates and USP-NF dissolution thresholds fragmenting procurement across mammalian and marine sourcing alternatives.
Product Type:
Reformulation cycles in capsule manufacturing are accelerating replacement demand for gelatin grades that balance dissolution predictability with religious dietary compliance.
- Type B Gelatin:Lime-processed bovine hide extract delivers bloom strength between 150-250 grams with superior mechanical stability for hard capsule shells. Demand concentrates in Germany and Switzerland as automated capsule filling lines require batch-to-batch consistency that acid-processed alternatives cannot match.
- Fish Gelatin:Marine-origin collagen hydrolysate extracted through mild acid processing avoids bovine spongiform encephalopathy concerns and satisfies halal/kosher requirements. Formulation teams in Saudi Arabia and Indonesia are redirecting sourcing toward marine alternatives where religious restrictions previously blocked mammalian adoption.
- Type A Gelatin:Acid-processed porcine or bovine material offers lower viscosity profiles suited to soft capsule applications and tablet binding where rapid dissolution is prioritized over shell hardness.
- Bovine Gelatin:Encompasses both Type A and Type B processing routes from cattle-derived collagen, with EMA veterinary traceability mandates elevating documentation requirements for each batch.
- Porcine Gelatin:Acid-extracted pigskin collagen retains cost advantages in tablet binding applications where mechanical stress on the dosage form remains minimal.
Volume placements concentrate in Type B Gelatin; the faster expansion belongs to Fish Gelatin.
Application:
Cost tier differentiation separates high-specification encapsulation grades from commodity binding applications, with regulatory burden escalating proportionally to patient contact intensity.
- Capsule Shells:Film-forming gelatin for hard and soft capsules demands precise bloom strength calibration and dissolution predictability under USP-NF monograph conditions. Hard capsule manufacturers in India and Italy are scaling output to serve generic drug export markets, intensifying demand for certified pharmaceutical grades.
- Tablet Binding:Lower-viscosity gelatin fractions serve as binders and disintegrants in immediate-release tablets where cost efficiency outweighs the mechanical performance requirements of encapsulation.
- Plasma Expanders:Highly purified gelatin polypeptides function as colloid volume replacement in emergency medicine, with pyrogen-free specifications elevating purification costs.
- Wound Care:Sponge and film formulations for hemostasis and tissue regeneration leverage gelatin's biocompatibility, with absorbable grades requiring endotoxin control.
- Protein Supplements:Nutraceutical applications tolerate broader specification ranges, with hydrolyzed gelatin peptides serving functional food and sports nutrition markets.
Revenue concentration sits with Capsule Shells; the steepest expansion trajectory belongs to Protein Supplements.
End User:
Customer scale determines procurement modality, with integrated pharmaceutical manufacturers capturing sourcing decisions that contract organizations previously fragmented.
- Pharmaceutical Manufacturers:Integrated dosage form producers in Hyderabad and Ahmedabad are consolidating gelatin procurement through backward integration into capsule shell manufacturing, reducing spot market dependency.
- Contract Research Organizations:Early-phase formulation development services generate small-batch demand for multiple gelatin grades, with qualification timelines compressed by sponsor timelines.
- Nutraceutical Companies:Dietary supplement producers in the United States and Japan drive demand for hydrolyzed collagen peptides with broader specification tolerances than pharmaceutical grades.
- Medical Device Producers:Hemostatic sponge and wound dressing manufacturers require absorbable gelatin with controlled porosity and degradation rates.
- Biotechnology Firms:Cell culture and bioprocessing applications utilize gelatin as a coating and nutrient substrate, with recombinant protein production demanding low-endotoxin grades.
Procurement volume aggregates with Pharmaceutical Manufacturers; the fastest share gains belong to Biotechnology Firms.
Packaging Type:
Supply chain configuration determines packaging selection, with just-in-time manufacturing favoring formats that minimize handling and contamination risk.
- Bulk Bags:Multi-ton flexible containers serve high-volume capsule shell manufacturers with dedicated unloading systems and climate-controlled storage.
- Drums:Steel or fiber containers remain standard for mid-scale pharmaceutical manufacturers with batch-specific material requirements.
- Vacuum Packs:Oxygen-barrier packaging extends shelf stability for hydrolyzed grades susceptible to oxidative degradation.
- Sachets:Pre-weighed single-use portions serve CRO formulation laboratories and pilot-scale manufacturing where cross-contamination control is paramount.
- Intermediate Bulk Containers:Reusable totes with liner systems reduce packaging waste for manufacturers with established return logistics.
Shipment volume concentrates in Bulk Bags; the format climbing fastest belongs to Vacuum Packs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Argentina and Brazil supply bovine hides that anchor Type B gelatin production chains. Germany, Switzerland, and India transform these raw materials into pharmaceutical-grade formulations serving capsule manufacturers worldwide.
Germany
Automated capsule filling lines in Baden-Württemberg and Bavaria demand batch-to-batch bloom strength consistency between 150-250 grams. EMA veterinary traceability frameworks enforce batch-level documentation for bovine-derived imports. The Eberbach and Ludwigshafen industrial corridors host specialized gelatin processing facilities serving domestic hard capsule manufacturers.
India
API manufacturing clusters in Hyderabad and Ahmedabad are scaling pharmaceutical-grade gelatin consumption as export-oriented production intensifies. CDSCO aligns import and domestic manufacturing standards with ICH Q7 guidelines, elevating compliance costs for uncertified suppliers. The Telangana and Gujarat pharmaceutical corridors are consolidating procurement through backward-integrated capsule shell manufacturing.
United States
USP-NF dissolution thresholds determine batch acceptance for hard capsule applications serving generic drug export markets. FDA enforcement of pharmacopeial standards tightens material specifications across immediate-release and controlled-release formulations. New Jersey and Pennsylvania host formulation development services generating multi-grade gelatin demand from contract research organizations.
Switzerland
Swissmedic oversight of veterinary medicinal products reinforces traceability requirements for bovine-derived collagen hydrolysates. Near-infrared spectroscopy deployment for real-time bloom strength verification is compressing batch release cycles from days to hours. Basel and Zurich pharmaceutical manufacturing zones are adopting just-in-time inventory models that reduce working capital requirements.
Indonesia
Halal certification requirements are redirecting formulation sourcing toward marine-origin gelatin alternatives. Religious dietary restrictions previously blocking mammalian adoption are accelerating fish gelatin processing technology investment. The Jakarta and Surabaya pharmaceutical packaging sectors represent emerging demand centers for certified pharmaceutical-grade materials.
Global Pharmaceutical Gelatin Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized hydrolyzed lines for controlled-release applications. The vendor base stratifies across integrated collagen processors, regional halal-certified specialists, and marine-origin technology developers. Three archetypes dominate: backward-integrated hide processors with captive bovine supply, halal-certification holders unlocking Middle Eastern and Southeast Asian access, and marine-extraction innovators circumventing BSE concerns. Capacity expansion and certification acquisition represent the dominant competitive moves as qualification timelines extend under tightening pharmacopeial standards.
Among European integrated processors, Gelita AG exemplifies the backward-integrated archetype through upstream control over collagen sourcing. Rousselot occupies a position within the specialized hydrolyzed tier, while PB Leiner anchors the halal-certified production segment. These three entities collectively represent the competitive spectrum spanning traceability assurance, modified-release technology, and religious dietary compliance.
| Leading Market Players |
|---|
| Gelita AG |
| Rousselot (Darling Ingredients) |
| PB Leiner |
| Nitta Gelatin Inc. |
| Weishardt |
| Tessenderlo Group |
| Funingpu Biotechnology |
| India Gelatine & Chemicals Ltd |
| Lapi Gelatine |
| Others |
Supply & Pricing Matrix
Bloom strength calibration specialists in Germany and Switzerland command wage premiums that compress margin spreads between pharmaceutical-grade and technical gelatin tiers. Labor-cost differentials between these European processing hubs and emerging extraction facilities in Argentina widen the pricing gap for certified Type B gelatin versus uncertified bovine alternatives.
Pricing Analysis
Service bundling separates certified pharmaceutical grades from commodity technical gelatin, with EMA traceability documentation and USP-NF compliance verification included in premium tier contracts while standard grades carry unbundled certification costs. Three-tier pricing structure across premium, standard, and economy levels reflects quality grade differentiation and halal certification status, with volume scale discounts concentrated among integrated capsule manufacturers. Cost compression in standard-tier bovine gelatin is intensifying because Argentina hide supply volatility transmits directly to input costs. Contract research organizations exhibit highest price sensitivity due to small-batch procurement volumes, while integrated pharmaceutical manufacturers in India demonstrate lowest sensitivity through backward-integrated sourcing.
Supply Chain Analysis
Direct-to-capsule-manufacturer channels handle high-volume demand from integrated pharmaceutical producers in Germany, Switzerland, and India, while specialty distributors serve mid-scale generic drug manufacturers with multi-grade requirements. Raw material supply draws from bovine hide processors in Argentina and Brazil, lime and acid chemical suppliers in Germany, and marine collagen extraction operations in Indonesia. Single-source vulnerability concentrates in EMA-certified bovine hide supply chains, where limited qualified producers in South America create bottleneck risk. Distribution runs through pharmaceutical contract manufacturing organizations in India and Eastern Europe that bundle excipient supply with formulation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical gelatin supply chains are consolidating around backward-integrated producers with captive collagen sourcing, as EMA traceability mandates and extended supplier qualification timelines force sub-scale competitors toward exit. Regulatory compliance cost escalation favors integrated players with dedicated quality infrastructure.
For Market Incumbents: Anchor competitive position through halal certification acquisition that unlocks Middle Eastern and Southeast Asian pharmaceutical markets currently inaccessible to uncertified suppliers. Deepen upstream control over bovine hide supply through direct sourcing agreements with Argentine and Brazilian processors, reducing spot market exposure to input volatility. Prioritize specialized hydrolyzed gelatin capacity for controlled-release tablet applications where formulation complexity creates stickier customer relationships. For New Entrants and Emerging Players: Capture white-space opportunity in fish gelatin processing for Indonesian and Saudi Arabian pharmaceutical markets where religious dietary restrictions block mammalian material adoption. Target biotechnology firm demand for low-endotoxin gelatin grades used in cell culture and bioprocessing applications, a segment showing fastest procurement volume gains. Pursue joint development agreements with CDMOs in Hyderabad and Ahmedabad that bundle gelatin supply into integrated formulation service contracts. For Investors and Strategic Acquirers: Re-rating potential sits with halal-certified marine-origin specialists given Indonesia's accelerating pharmaceutical packaging sector growth and regulatory redirection toward marine alternatives. Long-term viability favors producers with dual carbon compliance infrastructure already deployed, as environmental enforcement tightens lime-processing effluent standards. Acquisition target archetype: mid-scale Brazilian or Argentine bovine hide processors with pathway to EMA veterinary traceability certification. Monitor fish gelatin processing technology cost curves as inflection indicator for marine-origin substitution economics.| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Acquisition | Unlocks access to Saudi SFDA and Indonesian MOH pharmaceutical markets previously blocked by religious restrictions. |
| Backward Integration into Collagen Sourcing | Secures Argentine and Brazilian bovine hide supply chains against EMA traceability mandate compliance failures. |
| Specialized Hydrolyzed Line Investment | Captures controlled-release tablet reformulation demand from German and Swiss pharmaceutical manufacturers. |
| Fish Gelatin Processing Scale-Up | Addresses Indonesia and Saudi Arabia pharmaceutical market requirements while circumventing BSE concerns. |
| CDMO Partnership Development | Integrates gelatin supply into bundled formulation services capturing Indian pharmaceutical export sector procurement decisions. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving pharmaceutical manufacturing executives, capsule shell procurement managers, gelatin processing plant operators, and CDMO supply chain directors. CDSCO import records, EMA veterinary medicinal product registrations, USP-NF monograph revisions, and Argentine hide export statistics provided demand-side validation. Bottom-up volume modeling across dosage form applications reconciled with top-down pharmaceutical excipient market sizing.
Data-stream reconciliation between producer-reported capacity utilization and end-user procurement surveys calibrated segment-level growth assumptions across the projection horizon. Segmentation dimensions modeled include gelatin chemistry type, dosage form application, end-user scale, and regional regulatory cluster. CAGRs derived from historical volume trajectories adjusted for regulatory event impacts and substitution elasticity between mammalian and marine-origin alternatives. Near-infrared spectroscopy adoption curves and halal certification penetration rates informed technology-driven segment reallocation.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EMA-USP pharmacopeial divergence, Argentina hide supply disruptions, and fish gelatin processing cost breakthroughs. Forecasts reflect assumptions regarding regulatory harmonization progress and marine-origin substitution rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Wilson Disease Drugs Market
Pharmaceuticals
Global Oxytocic Pharmaceuticals Market
Pharmaceuticals
Europe Oral Anti-Diabetic Drug Market
Pharmaceuticals
Stye Drug Market
Pharmaceuticals
Global Psoriasis Drugs Market
Pharmaceuticals
Varicella Attenuated Live Vaccination Market
Pharmaceuticals
HPV Vaccines Market
Pharmaceuticals
Prostaglandin Analogs Market
Pharmaceuticals
Global Anticoagulant Reversal Drugs Market
Pharmaceuticals
Pharmaceutical Elixir Market
Pharmaceuticals
Submucosal Lifting Agent Market
Pharmaceuticals
Hepatocellular Carcinoma Drugs Market
Pharmaceuticals
Global Respiratory Drug Market
Pharmaceuticals
Asia-Pacific GLP 1 Agonist Market
Pharmaceuticals
Quinolones Market
Pharmaceuticals
Europe Laxative Market