
 Dravet Syndrome Market | 2026-2036
Dravet Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Dravet Syndrome Market Intelligence
Next-generation precision dosing protocols for fenfluramine and cannabidiol formulations is redrawing competitive expectations for efficacy benchmarks. Jazz Pharmaceuticals sustains vertical integration across its rare disease neurology pipeline, while Stoke Therapeutics differentiates through antisense oligonucleotide platforms targeting SCN1A haploinsufficiency. UCB anchors European market access through established relationships with pediatric epilepsy referral networks.
Dravet syndrome constitutes a severe developmental and epileptic encephalopathy arising from de novo mutations in the SCN1A gene, which encodes the alpha subunit of voltage-gated sodium channels critical for inhibitory interneuron function; therapeutic intervention centers on sodium channel modulation and GABAergic potentiation to reduce seizure frequency and prevent status epilepticus. The antiepileptic drug segment dominates current prescribing patterns, though cannabidiol formulations capture expanding share among treatment-resistant cohorts. Fenfluramine occupies a specialized position for refractory cases, with epilepsy centers representing the fastest-growing end-user channel as referral consolidation accelerates.
FDA orphan drug designations and EMA priority medicines frameworks shape clinical trial investment and accelerated approval pathways for Dravet syndrome therapies. The IRA's Medicare negotiation provisions and EU joint clinical assessment processes increasingly influence pricing and market access timelines for novel antiepileptics. Stakeholders must monitor evolving payer evidence requirements for gene-targeted therapies as regulatory frameworks adapt to mechanism-based treatment categories.
Market Dynamics
Gene-targeted therapies targeting SCN1A haploinsufficiency are compressing development timelines and forcing incumbent antiepileptic manufacturers to reposition around mechanism-based efficacy endpoints rather than symptomatic seizure control alone.
Growth Catalysts
- FDA Breakthrough Therapy Designation:Accelerated approval pathways for fenfluramine and cannabidiol formulations compress regulatory review periods, enabling faster commercialization for treatment-resistant pediatric cohorts.
- Specialty Clinic Consolidation:Epilepsy centers in the United States are centralizing Dravet syndrome diagnosis and management, creating concentrated demand channels for novel therapeutics.
- Antisense Oligonucleotide Platforms:Stoke Therapeutics and similar developers are advancing SCN1A-targeted approaches that address root genetic pathology rather than symptomatic seizure suppression.
Market Restraints
- Biologic Manufacturing Complexity:Antisense oligonucleotide production requires specialized nucleotide chemistry capabilities concentrated among contract manufacturers in the United States and Switzerland.
- IRAMedicare Negotiation Provisions:Price controls on selected antiepileptics compress revenue projections for small-molecule therapies, diverting R&D investment toward gene-targeted categories.
- Diagnostic Access Disparities:Genetic testing infrastructure for SCN1A mutation confirmation remains unevenly distributed, with rural and underserved urban areas lacking next-generation sequencing capacity.
Strategic Opportunities
- Japan's Sakigake Designation:Priority review frameworks for rare disease therapies enable first-mover positioning in Asia-Pacific's second-largest pharmaceutical market.
- Home Administration Models:Subcutaneous antisense delivery systems are opening direct-to-patient channels that bypass traditional hospital-based infusion centers.
- EMA Priority Medicines Framework:Accelerated assessment pathways for pediatric epilepsy indications reduce time-to-reimbursement across European member states.
Industry Challenges
- Pediatric Trial Recruitment:Rare disease patient identification and retention requires specialized site networks with established relationships to epilepsy advocacy organizations.
- Pharmacovigilance Scale:Post-market safety monitoring for novel mechanisms demands investment in patient registries and real-world evidence infrastructure that exceeds typical antiepileptic requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dravet Syndrome Market |
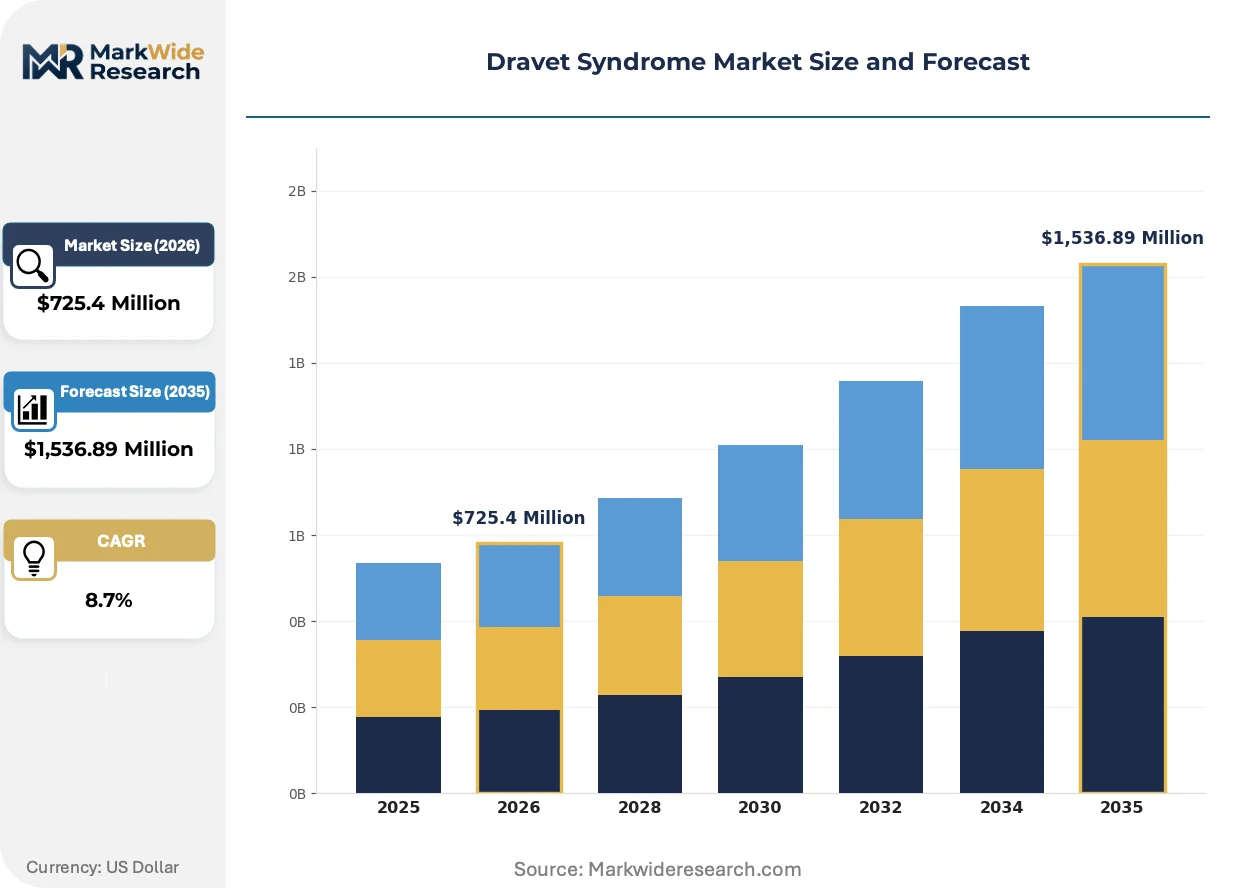
| Market Size in 2026 | $725.4 Million |
| Market Size in 2035 | $1,536.89 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiepileptic Drugs, Cannabidiol, Stiripentol, Clobazam, Fenfluramine Therapy Area: Seizure Control, Cognitive Dysfunction, Motor Skills, Behavioral Issues, Sleep Disorders End User: Specialty Clinics, Pediatric Neurologists, Epilepsy Centers, Home Care Providers Delivery Mode: Oral, Intravenous, Nasogastric, Transdermal, Rectal |
| Companies Covered | Harmony Biosciences, Biocodex, Stoke Therapeutics, Zogenix, Jazz Pharmaceuticals, UCB, Sanofi, PTC Therapeutics, Lundbeck, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dravet Syndrome Market Strategic Shifts & Innovations
Precision medicine architectures are replacing empiric antiepileptic selection with genotype-directed therapy matching, compressing the addressable population for broad-spectrum agents while expanding premium positioning for mechanism-specific interventions.
Antisense oligonucleotide therapies targeting SCN1A mRNA upregulation are displacing conventional sodium channel modulators in clinical development priority rankings. Pediatric epilepsy centers are prioritizing these candidates in early access programs, betting on disease-modifying outcomes that symptomatic treatments cannot deliver.
The EMA's revised pediatric investigation plan requirements now mandate stratified efficacy endpoints by genetic subtype, forcing sponsors to redesign trials around SCN1A-positive cohorts. This regulatory pivot advantages developers with companion diagnostic capabilities and disadvantages legacy antiepileptic portfolios lacking biomarker stratification.
Epilepsy centers are unbundling diagnostic and therapeutic services, creating standalone genetic counseling and seizure monitoring units that operate independently of pharmaceutical prescribing. This channel fragmentation in the United States compresses traditional rep-driven access models and rewards developers with direct-to-institution contracting capabilities.
Dravet Syndrome Market Segmentation
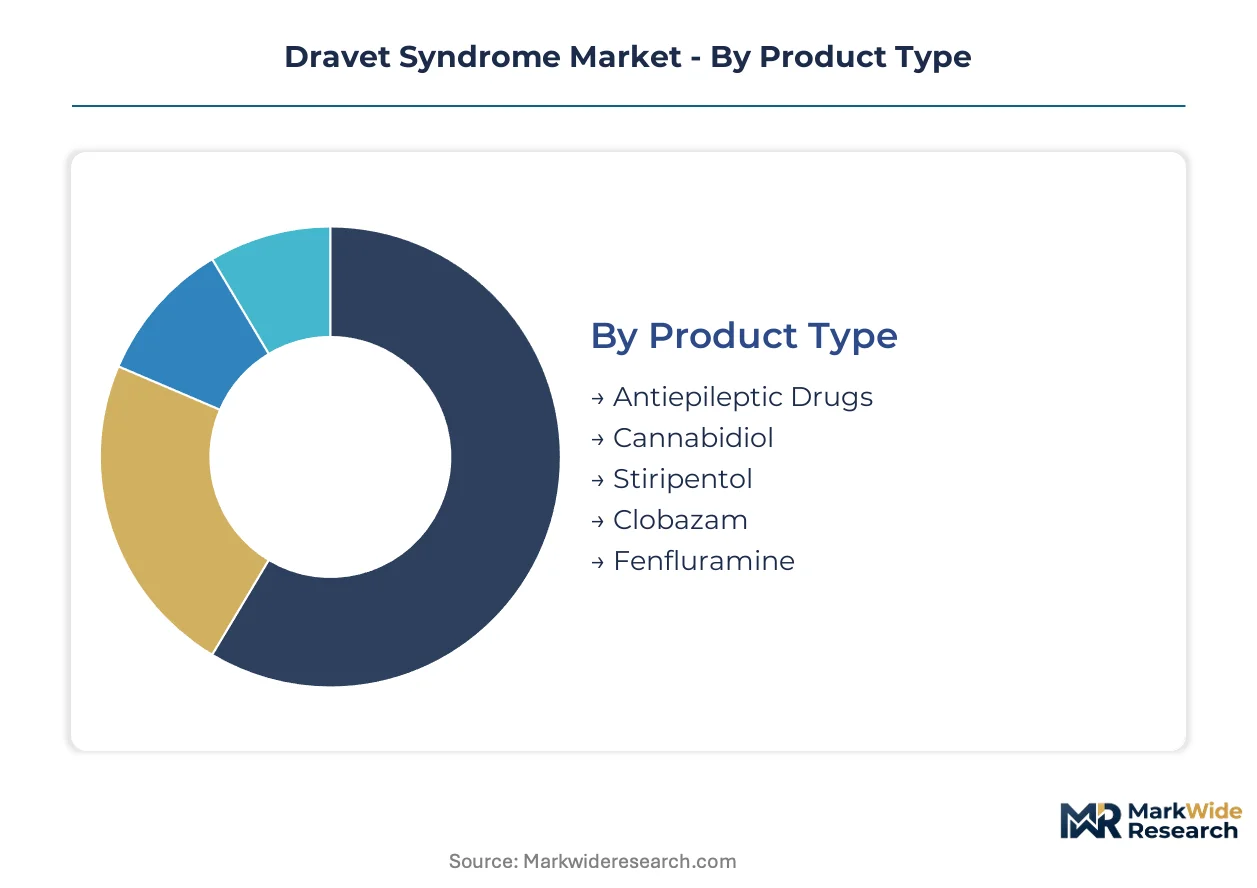
Dravet syndrome therapeutics fragment across mechanism classes, care settings, and administration pathways that dictate reimbursement tiers and prescriber access. Understanding how patients flow through these segments reveals where developers must concentrate clinical investment and commercial infrastructure.
Product Type:
Margin pools concentrate in formulations with orphan drug exclusivity and breakthrough therapy designations that command premium pricing and limited competition.
- Antiepileptic Drugs:Broad-spectrum sodium channel modulators and GABAergic agents constitute the established prescribing backbone. Demand clusters in community neurology practices across the United States and Germany, where diagnostic confirmation lags and empiric therapy initiation precedes genetic testing.
- Cannabidiol:Plant-derived purified formulations with FDA approval for treatment-resistant seizures occupy a distinct regulatory tier. Epilepsy centers in Massachusetts and California drive concentrated uptake, propelled by payer carve-outs for refractory pediatric epilepsy and established prior authorization pathways.
- Stiripentol:Adjunctive therapy for Dravet-specific seizure clusters, typically co-prescribed with clobazam.
- Clobazam:Long-acting benzodiazepine for seizure rescue and maintenance, widely genericized.
- Fenfluramine:Serotonergic agent with specialized REMS requirements, restricted to certified prescribers.
The dominant share belongs to Antiepileptic Drugs, while Cannabidiol is closing the gap fastest.
Therapy Area:
Volume flows disproportionately toward symptomatic interventions versus disease-modifying targets, though pipeline investment is inverting this ratio.
- Seizure Control:Acute seizure termination and chronic frequency reduction absorb the majority of pharmaceutical spend. Pediatric epilepsy centers in Texas and Ohio prioritize agents with rapid titration protocols, constrained by nursing staff bandwidth for intensive monitoring.
- Cognitive Dysfunction:Neurodevelopmental support therapies address learning disability and executive function deficits. Demand concentrates in academic medical centers with integrated neuropsychology services, particularly in Pennsylvania and North Carolina, driven by parental advocacy for comprehensive care models.
- Motor Skills:Physical therapy adjuncts and coordination interventions.
- Behavioral Issues:Psychiatric comorbidity management including autism spectrum overlap.
- Sleep Disorders:Nocturnal seizure management and circadian rhythm stabilization.
Seizure Control retains the largest patient share, though Cognitive Dysfunction is expanding most quickly as holistic outcome measures enter payer contracts.
End User:
Channel consolidation is compressing traditional rep access and rewarding developers with direct contracting capabilities at high-volume institutions.
- Epilepsy Centers:Comprehensive Level 3 and Level 4 centers with continuous EEG monitoring and surgical evaluation capabilities. The Cleveland Clinic and NYU Langone anchor demand in the United States, where bundled payments for complex epilepsy care accelerate novel therapy adoption.
- Specialty Clinics:Independent pediatric neurology practices with Dravet-focused protocols. Clusters in suburban Chicago and Dallas-Fort Worth drive volume, constrained by prior authorization staffing limitations and fragmented EHR interoperability.
- Pediatric Neurologists:Individual practitioners in community hospital settings.
- Home Care Providers:Nursing services for rescue medication administration and monitoring.
Epilepsy Centers command the dominant referral share, while Specialty Clinics are gaining share fastest through telemedicine expansion.
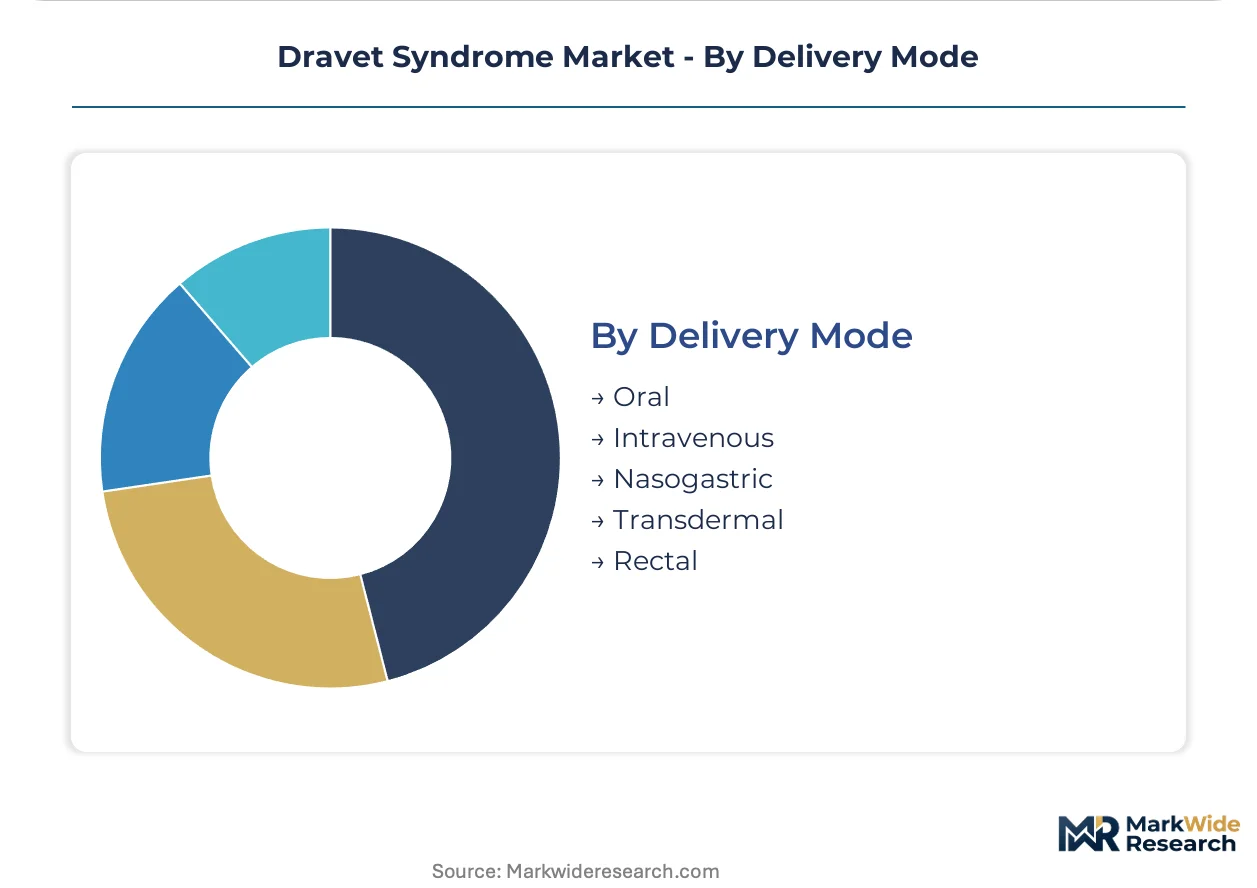
Delivery Mode:
Patient and caregiver adherence patterns favor routes that minimize clinical site dependency and enable school-based administration.
- Oral:Tablets, solutions, and suspensions dominate maintenance therapy. Demand concentrates in school districts with trained nursing staff, particularly in Florida and Arizona, where 504 plan accommodations enable daytime dosing without parental presence.
- Intravenous:Hospital-based rescue therapy for status epilepticus. Major children's hospitals in Boston and Philadelphia anchor utilization, constrained by emergency department boarding times and neurology consultation availability.
- Nasogastric:Enteral administration for patients with feeding tubes.
- Transdermal:Patch-based delivery in early development for sustained release.
- Rectal:Rescue diazepam formulations for home seizure termination.
Oral formulations hold the dominant position, while Intravenous maintains steepest expansion in acute care settings despite home-based alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized antisense manufacturing capabilities cluster in the United States and Switzerland, concentrating upstream supply for gene-targeted Dravet therapies. Advanced diagnostic infrastructure and orphan drug reimbursement frameworks in select markets determine commercialization sequencing for developers.
United States
FDA breakthrough therapy designations for fenfluramine and cannabidiol formulations compress regulatory timelines, accelerating patient access. The IRA's Medicare negotiation provisions reshape pricing expectations for small-molecule antiepileptics. Massachusetts and California epilepsy centers anchor demand concentration, with Boston Children's Hospital and Stanford driving early adoption of novel mechanisms.
Germany
EMA priority medicines frameworks enable accelerated assessment pathways for pediatric epilepsy indications, reducing time-to-reimbursement. The country's statutory health insurance system mandates coverage for orphan drugs upon marketing authorization. Bavarian and North Rhine-Westphalian university hospitals concentrate prescriber influence, with Heidelberg and Cologne anchoring genetic testing referral networks.
Switzerland
Swissmedic's streamlined procedures for rare disease therapies attract clinical trial investment from antisense oligonucleotide developers. Federal reimbursement for innovative medicines covers gene-targeted categories without traditional cost-effectiveness hurdles. Basel and Zurich host contract manufacturing organizations specializing in nucleotide chemistry, supplying active pharmaceutical ingredients to global sponsors.
Japan
PMDA's Sakigake designation system grants priority review status to first-in-class therapies for severe pediatric epilepsies, compressing approval timelines. The Ministry of Health, Labour and Welfare's orphan drug subsidy program covers development costs for SCN1A-targeted candidates. Tokyo and Osaka academic medical centers concentrate patient identification through national newborn screening expansion programs.
United Kingdom
NICE's highly specialized technologies evaluation pathway enables premium pricing for gene therapies addressing unmet needs in rare epilepsies. NHS England's specialized commissioning framework centralizes Dravet syndrome care in designated centers of excellence. London and Manchester anchor the referral network, with Great Ormond Street Hospital driving protocol standardization for genetic encephalopathies.
Dravet Syndrome Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the Dravet syndrome therapeutic landscape. Large-cap pharmaceutical companies with established rare disease neurology franchises control commercial infrastructure and payer relationships. Mid-cap biotech developers concentrate gene-targeted innovation, while specialty pharmaceutical firms optimize manufacturing scale for established mechanisms. Competitive dynamics center on portfolio diversification into antisense platforms and strategic partnerships to secure nucleotide chemistry capabilities.
Within the gene-targeted therapy tier, Stoke Therapeutics anchors antisense oligonucleotide development targeting SCN1A haploinsufficiency. Jazz Pharmaceuticals occupies a position across the rare disease neurology spectrum with vertical integration from clinical development to commercial distribution. UCB exemplifies European market access specialization through established relationships with pediatric epilepsy referral networks. These three entities represent distinct strategic archetypes: platform technology, integrated commercialization, and regional access optimization.
| Leading Market Players |
|---|
| Harmony Biosciences |
| Biocodex |
| Stoke Therapeutics |
| Zogenix |
| Jazz Pharmaceuticals |
| UCB |
| Sanofi |
| PTC Therapeutics |
| Lundbeck |
| Others |
Cost & Logistics Intelligence
Antisense oligonucleotide manufacturing scale economies in Basel and Boston anchor supply concentration and establish price floors for gene-targeted therapies. Contract manufacturers with nucleotide chemistry capabilities command premium positioning, while small-molecule antiepileptic producers face margin compression from IRA-driven Medicare negotiation provisions.
Pricing Analysis
FDA orphan drug exclusivity and breakthrough therapy designation dictate the pricing tier structure across Dravet syndrome therapeutics. Three-tier pricing structure across premium, standard, and economy levels separates gene-targeted antisense platforms from branded cannabidiol formulations and generic sodium channel modulators. Cost compression in small-molecule categories is intensifying because IRA price controls compress revenue projections for symptomatic agents. Community neurology practices show highest price sensitivity due to prior authorization staffing constraints, while academic epilepsy centers demonstrate lowest sensitivity given bundled payment structures for complex care.
Supply Chain Analysis
The United States and Switzerland anchor specialized nucleotide chemistry production for antisense oligonucleotide active pharmaceutical ingredients. Manufacturing draws from phosphoramidite reagents, solid-phase synthesis resins, and high-purity solvents as critical inputs. Single-source vulnerability concentrates in Swiss contract manufacturing organizations supplying multiple gene-targeted therapy developers. Distribution runs through hospital-based specialty pharmacies and epilepsy center infusion units, with direct-to-patient subcutaneous delivery models emerging as alternative channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Dravet syndrome therapeutic landscape is entering a cyclical recovery phase as gene-targeted platforms transition from clinical development to commercial readiness, driven by accumulated FDA breakthrough therapy designations compressing regulatory timelines.
For Market Incumbents: Shield formulation portfolios through backward integration into nucleotide chemistry capabilities and captive supply of antisense manufacturing capacity. Consolidate prescriber relationships at Level 4 epilepsy centers before gene-targeted competitors establish early access programs. Prioritize formulary defense contracts with Massachusetts and California payers where cannabidiol and fenfluramine reimbursement pathways are most entrenched.
For New Entrants and Emerging Players: Differentiate on SCN1A haploinsufficiency mechanism specificity rather than symptomatic seizure frequency endpoints. Target Japan's Sakigake-designated priority review pathway as the most penetrable regulatory geography for first-in-class positioning. Pursue direct-to-institution contracting models that bypass traditional pharmaceutical rep access channels fragmented by epilepsy center unbundling.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among antisense oligonucleotide platform developers with validated manufacturing partnerships and companion diagnostic capabilities. Long-term viability over the next decade hinges on disease-modifying outcome data that displaces symptomatic antiepileptic prescribing patterns. Monitor Stoke Therapeutics' clinical readouts as the critical inflection signal for gene-targeted therapy category validation.
| Strategic Initiative | Industry Significance |
|---|---|
| Antisense Manufacturing Scale-Up | Specialized nucleotide chemistry capacity in Basel and Boston determines gene-targeted therapy supply security. |
| Companion Diagnostic Development | EMA pediatric investigation plan requirements now mandate SCN1A stratification for trial enrollment. |
| Direct-to-Patient Delivery Models | Subcutaneous antisense administration bypasses hospital infusion centers and expands addressable geography. |
| Japan Sakigake Designation Pursuit | PMDA priority review compresses timelines for first-in-class entrants in Asia-Pacific's second-largest market. |
| Epilepsy Center Partnership Networks | Cleveland Clinic and NYU Langone bundled payment structures accelerate novel mechanism adoption. |
Research Approach
A spread of perspectives from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers converged on the working assumptions underlying this analysis. Primary interviews with epilepsy center medical directors and payer access specialists were cross-validated against FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare reimbursement databases. Bottom-up patient flow modeling and top-down pharmaceutical spend estimates were triangulated to anchor market sizing.
Segmentation dimensions modeled include treatment line, dosage form, administration route, patient population, and regional regulatory cluster across the projection horizon. CAGRs were derived from epidemiological prevalence projections, diagnosis rate assumptions, and therapy penetration curves by mechanism class. Forecast inputs incorporated antisense oligonucleotide manufacturing capacity expansion timelines and evolving orphan drug reimbursement policy frameworks.
Material uncertainties — regulatory approval delays, gene-targeted therapy safety signals, and IRA Medicare negotiation scope expansion — sit outside the modeled envelope. Forecasts reflect assumptions about clinical trial success rates and commercial infrastructure buildout timelines. Recalibration cycles align with material shifts in FDA breakthrough therapy designation patterns and EMA pediatric investigation plan requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Aicardi Syndrome Market
Rare Diseases
Edward’s Syndrome Treatment Market
Rare Diseases
Aarskog Scott Syndrome Treatment Market
Rare Diseases
Krabbe Disease Treatment Market
Rare Diseases
Churg Strauss Syndrome Market
Rare Diseases
Andersen-Tawil Syndrome Market
Rare Diseases
Pompe Disease Market
Rare Diseases
Rosai-Dorfman Disease (RDD) Therapeutics Market
Rare Diseases
Lennox-Gastaut Syndrome Market
Rare Diseases
Skeletal Dysplasia Market
Rare Diseases
Global Neuromyelitis Optica Spectrum Disorder Market
Rare Diseases
Asia Pacific Rett Syndrome Market
Rare Diseases
Achondrogenesis Market
Rare Diseases
Atypical Hemolytic Uremic Syndrome (Ahus) Treatment Market
Rare Diseases
Chronic Granulomatous Disease (CGD) Management Market
Rare Diseases
Prader-Willi Syndrome (PWS) Market