
 Global Dermatology Lasers Market | 2026-2036
Global Dermatology Lasers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dermatology Lasers Market Foresight
Picosecond pulse durations are repositioning nanosecond platforms across tattoo removal and pigmentation protocols. Lumenis leverages its installed base in hair removal to sustain recurring consumable revenue streams. Alma Lasers anchors its competitive stance through direct distribution across Middle Eastern and Asian markets. Sciton differentiates via physician training ecosystems that lock in platform loyalty.
Dermatology lasers are coherent light sources operating at specific wavelengths between 532 nm and 10,600 nm, designed to deliver selective photothermolysis for tissue modification without collateral thermal damage. Fractional CO2 and erbium systems dominate skin resurfacing revenue pools due to premium pricing and repeat treatment requirements. Hair removal applications lead procedure volume globally, while tattoo removal represents the fastest-growing application segment as picosecond technology expands treatable ink color palettes. Q-switched and long-pulse Nd:YAG platforms command significant share in vascular lesion protocols across Asian skin phototypes.
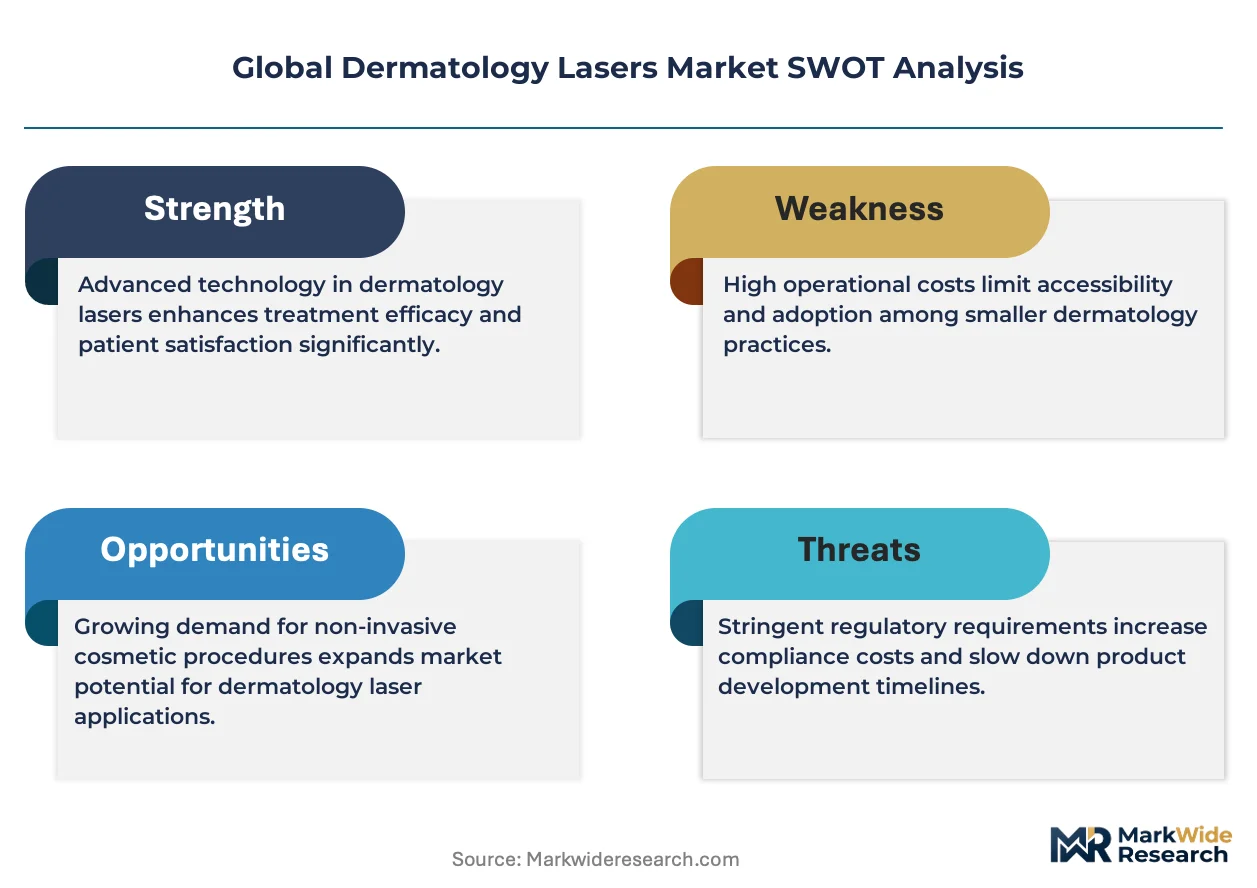
The FDA regulates dermatology lasers as Class II medical devices under 510(k) premarket notification, while the EU MDR imposes stricter clinical evidence requirements for CE marking of aesthetic energy devices. China's NMPA has tightened registration pathways for imported laser systems, extending commercialization timelines for foreign manufacturers. Japan's PMDA maintains distinct reimbursement classifications that influence hospital procurement of dermatological laser platforms. Stakeholders must monitor evolving cybersecurity requirements for networked laser systems and software-upgradable wavelength modules.
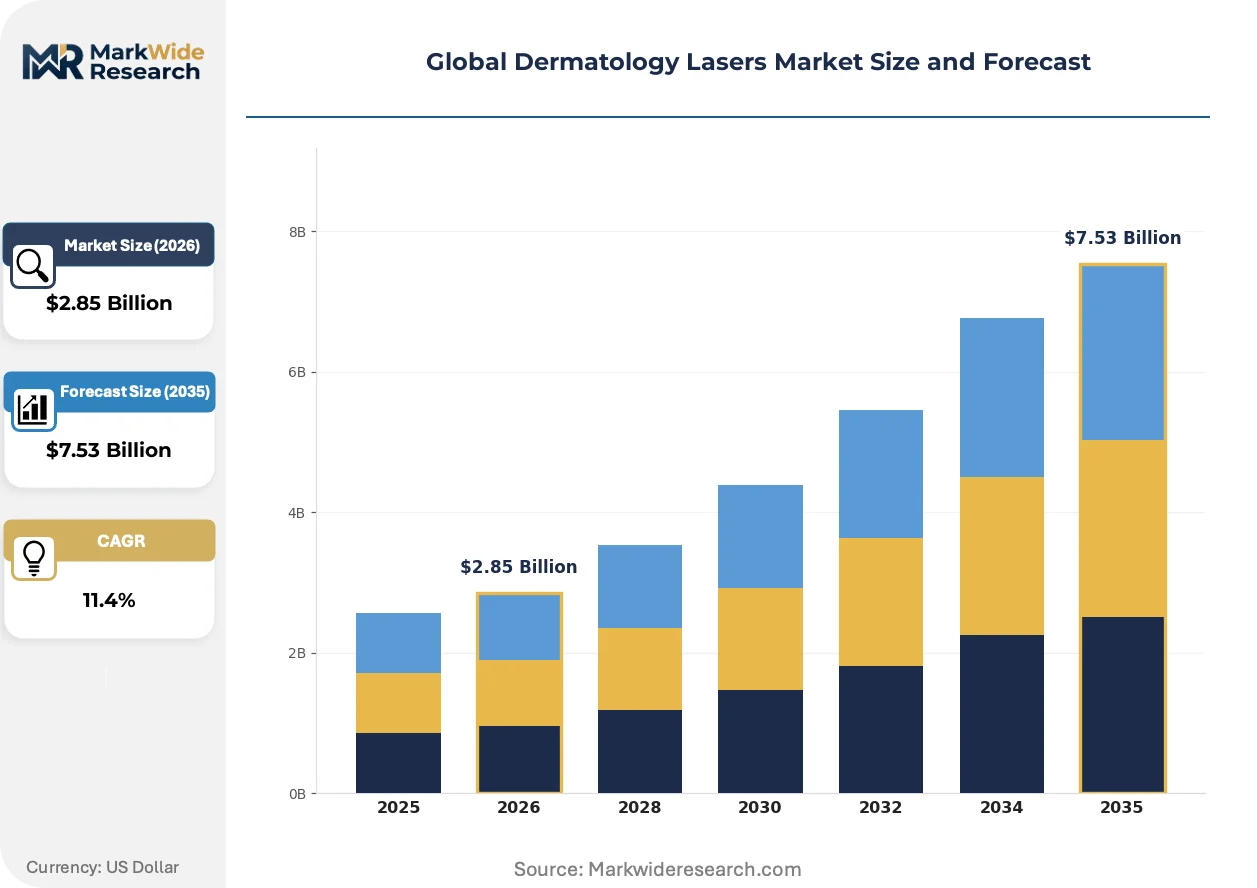
Market Dynamics
Picosecond pulse architecture is compressing treatment protocols and expanding addressable indications, forcing platform refresh cycles across installed bases while redirecting R&D budgets toward shorter-wavelength solid-state sources.
Growth Catalysts
- EU MDR clinical evidence mandates:Stricter CE marking requirements for aesthetic energy devices are filtering out marginal competitors and consolidating purchasing authority within hospital procurement committees across Germany and France.
- Medical spa network expansion:Aesthetic chains in the United States are standardizing laser service menus, creating predictable equipment refresh schedules and bundled consumable contracts.
- Q-switched Nd:YAG vascular protocols:Asian dermatology clinics are adopting long-pulse platforms for darker skin phototypes, opening procedure volume previously excluded from laser-based treatments.
Market Restraints
- CO2 laser tube supply concentration:German and American glass-ceramic manufacturers control critical resonator component production, exposing OEMs to input cost volatility and extended lead times.
- China NMPA registration timelines:Extended technical documentation reviews for imported laser systems delay commercialization by 18-24 months versus domestic competitors.
- Intense pulsed light substitution:Lower-capital IPL platforms capture price-sensitive hair removal volume in emerging markets, compressing entry-level laser ASPs.
Strategic Opportunities
- India dermatology clinic scaling:Metro hospital chains in Mumbai and Delhi are deploying fractional resurfacing platforms, creating first-mover advantage for direct-distribution models.
- Software-upgradable wavelength modules:Networked laser systems with cybersecurity-hardened firmware updates enable indication expansion without hardware replacement.
- Japan PMDA reimbursement reclassification:Revised hospital procurement categories for dermatological platforms favor multi-wavelength systems with documented clinical outcomes.
Industry Challenges
- Picosecond technician certification:Short-pulse platforms require specialized training in fluence calibration and skin cooling protocols, constraining clinic staffing flexibility.
- Legacy 510(k) cybersecurity gaps:Older FDA-cleared devices lack networked security architectures, complicating hospital IT integration and exposing liability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dermatology Lasers Market |
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $7.53 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Laser Type: CO2, Erbium, Nd:YAG, Pulsed Dye, Diode, Alexandrite Application: Hair Removal, Tattoo Removal, Skin Resurfacing, Vascular Lesions, Pigmentation Treatment, Wrinkle Reduction End User: Dermatology Clinics, Cosmetic Surgery Centers, Medical Spas, Beauty Salons, Clinics, Aesthetic Providers Technology: Fractional, Non-fractional, Pulsed, Continuous Wave, Q-switched, Long Pulse |
| Companies Covered | Cutera, Cynosure, Lumenis, Alma Lasers, Fotona, Candela Corporation, Quanta System, Sciton, Aerolase Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dermatology Lasers Market Shifts & Advancements
Hardware-software convergence is redefining platform value from wattage specifications to treatment protocol libraries and remote diagnostics capabilities.
Picosecond titanium-sapphire sources are electrifying tattoo removal and benign pigmentation protocols. Dermatology chains in California and Texas are replacing nanosecond platforms at 24-month cycles versus historical 60-month replacement schedules. This compression is accelerating consumable revenue recognition and narrowing payback periods for capital equipment.
China's NMPA has tightened registration pathways for imported laser systems, extending technical documentation requirements and mandating local clinical trials for certain wavelength categories. Foreign manufacturers are responding by establishing Shanghai-based regulatory affairs teams and partnering with domestic distributors holding existing NMPA licenses. High-power ablative platforms face the longest review queues.
After-sales service contracts are unbundling from equipment purchases across European hospital procurement. German and Swiss dermatology departments now separately negotiate preventive maintenance, spare parts, and software update agreements. This shift favors OEMs with captive service networks over third-party maintenance providers.
Global Dermatology Lasers Market Segmentation
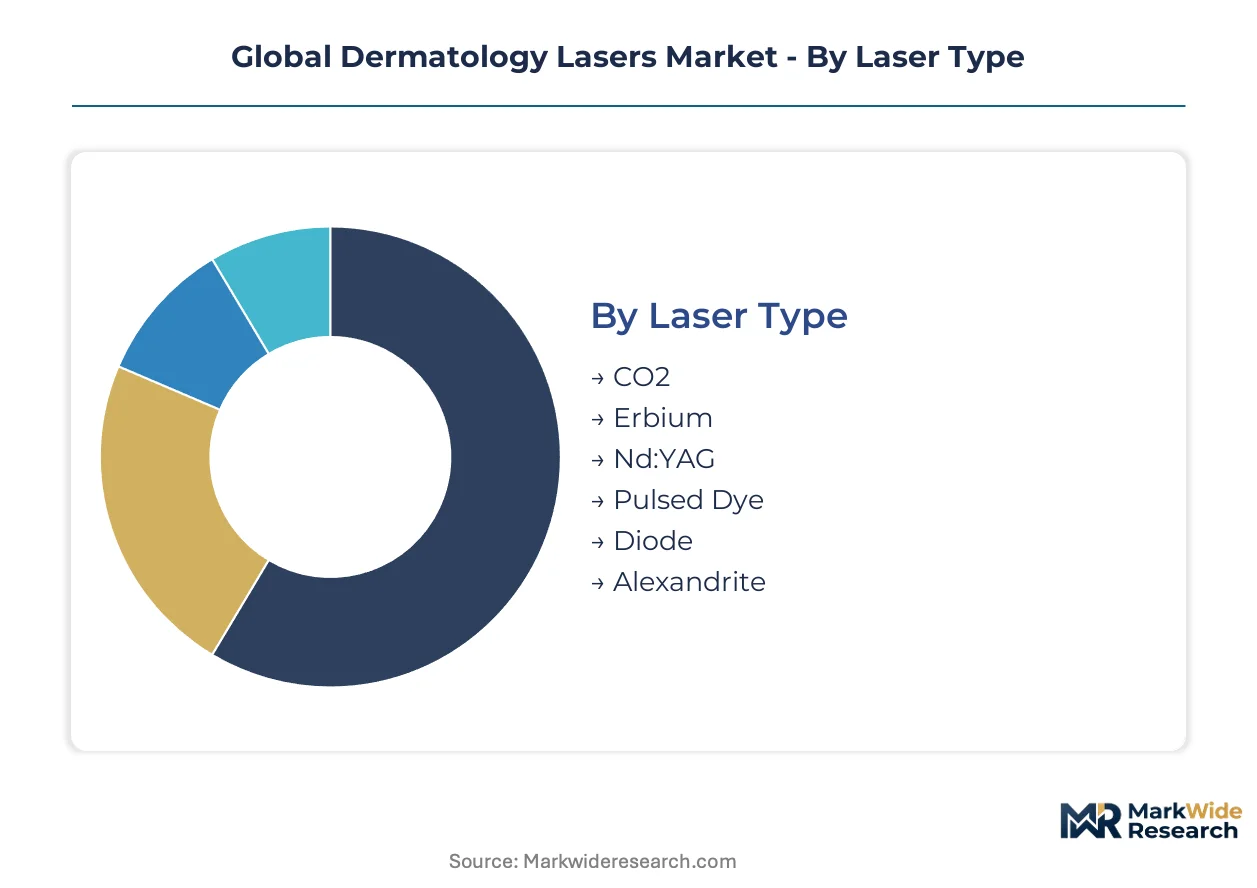
Segmentation in dermatology lasers reveals how technology architecture, clinical application, and delivery setting interact to determine equipment specifications and commercial strategy. Understanding these divisions exposes where capital concentrates, where consumable revenue recurs, and where regulatory pathways diverge.
Laser Type:
CO2 and erbium platforms function as standalone capital investments requiring dedicated facility infrastructure, while diode and Nd:YAG systems increasingly embed into multi-modality workstations.
- CO2:Gas laser architecture emitting at 10,600 nm delivers ablative tissue vaporization with controlled thermal coagulation zones. German and American glass-ceramic manufacturers control resonator tube supply, exposing OEMs to input cost volatility and extended lead times.
- Erbium:Solid-state crystal medium at 2,940 nm provides more superficial ablation with reduced erythema duration versus CO2. Fractional erbium platforms dominate premium skin resurfacing revenue pools in United States medical spa chains due to premium pricing and repeat treatment requirements.
- Nd:YAG:Neodymium-doped yttrium aluminum garnet crystal enables 1,064 nm penetration for deeper dermal targets. Q-switched and long-pulse configurations command significant share in vascular lesion protocols across Asian skin phototypes.
- Pulsed Dye:Organic dye medium tunable around 585-595 nm targets oxyhemoglobin with minimal melanin absorption. Compact footprint suits dermatology clinic deployment for pediatric vascular indications.
- Diode:Semiconductor junction architecture at 800-810 nm delivers efficient hair removal with air-cooled operation. Lower capital requirements drive adoption in India metro hospital chains expanding aesthetic service menus.
- Alexandrite:Chromium-doped chrysoberyl crystal at 755 nm balances melanin absorption and penetration depth. High peak power supports rapid large-area hair removal protocols in high-volume United States cosmetic surgery centers.
Hair removal applications lead procedure volume today; picosecond platforms for tattoo removal are gaining share fastest.
Application:
Procedure economics vary sharply between single-session outcomes requiring capital-intensive platforms and repeat-visit protocols generating recurring revenue through consumable attachment sales.
- Hair Removal:Diode and alexandrite wavelengths target melanin in hair follicles during anagen growth phase. Medical spa network standardization across Texas and California creates predictable equipment refresh schedules and bundled consumable contracts.
- Tattoo Removal:Picosecond pulse durations fragment ink particles below the thermal relaxation threshold of surrounding tissue. Dermatology chains are replacing nanosecond platforms at compressed 24-month cycles versus historical 60-month replacement schedules.
- Skin Resurfacing:Fractional CO2 and erbium systems create microscopic treatment zones leaving surrounding tissue intact for rapid re-epithelialization. Premium pricing and mandatory repeat sessions sustain revenue concentration in this category.
- Vascular Lesions:Pulsed dye and long-pulse Nd:YAG platforms target hemoglobin absorption peaks. Asian dermatology clinics adopt long-pulse configurations for darker skin phototypes, opening procedure volume previously excluded from laser-based treatments.
- Pigmentation Treatment:Q-switched lasers and picosecond sources address solar lentigines and melasma through selective photothermolysis. Shorter pulse durations expand treatable pigment color palettes beyond traditional nanosecond limitations.
- Wrinkle Reduction:Non-ablative fractional and infrared modalities stimulate dermal collagen remodeling without epidermal disruption. Lower downtime requirements attract patient populations unwilling to accept ablative recovery periods.
Skin resurfacing commands premium equipment ASPs; tattoo removal shows the steepest expansion trajectory as picosecond technology penetrates installed bases.
End User:
Facility type determines regulatory compliance burden, reimbursement pathway access, and technician certification requirements that shape equipment specification priorities.
- Dermatology Clinics:Physician-supervised settings with full diagnostic capability and malpractice coverage. India's metro hospital chains in Mumbai and Delhi deploy fractional resurfacing platforms, creating first-mover advantage for direct-distribution models.
- Cosmetic Surgery Centers:Operating room infrastructure supports combination procedures under anesthesia. Multi-wavelength systems with documented clinical outcomes align with Japan PMDA reimbursement reclassification favoring hospital procurement.
- Medical Spas:Non-physician operator settings driving standardization of laser service menus. Aesthetic chains in the United States negotiate bundled consumable contracts with predictable refresh schedules.
- Beauty Salons:Light-based aesthetic services without medical supervision in jurisdictions permitting such scope. Lower regulatory compliance costs attract entry-level diode and IPL platform deployment.
- Clinics:General practice and multi-specialty settings adding dermatological services. Equipment selection prioritizes versatility across indication range over peak performance in single applications.
- Aesthetic Providers:Mobile and pop-up service models requiring portable platform architectures. Compact footprint and air-cooled operation override raw power specifications in procurement decisions.
Dermatology clinics concentrate capital equipment investment today; medical spas are climbing the fastest as aesthetic chain consolidation accelerates.
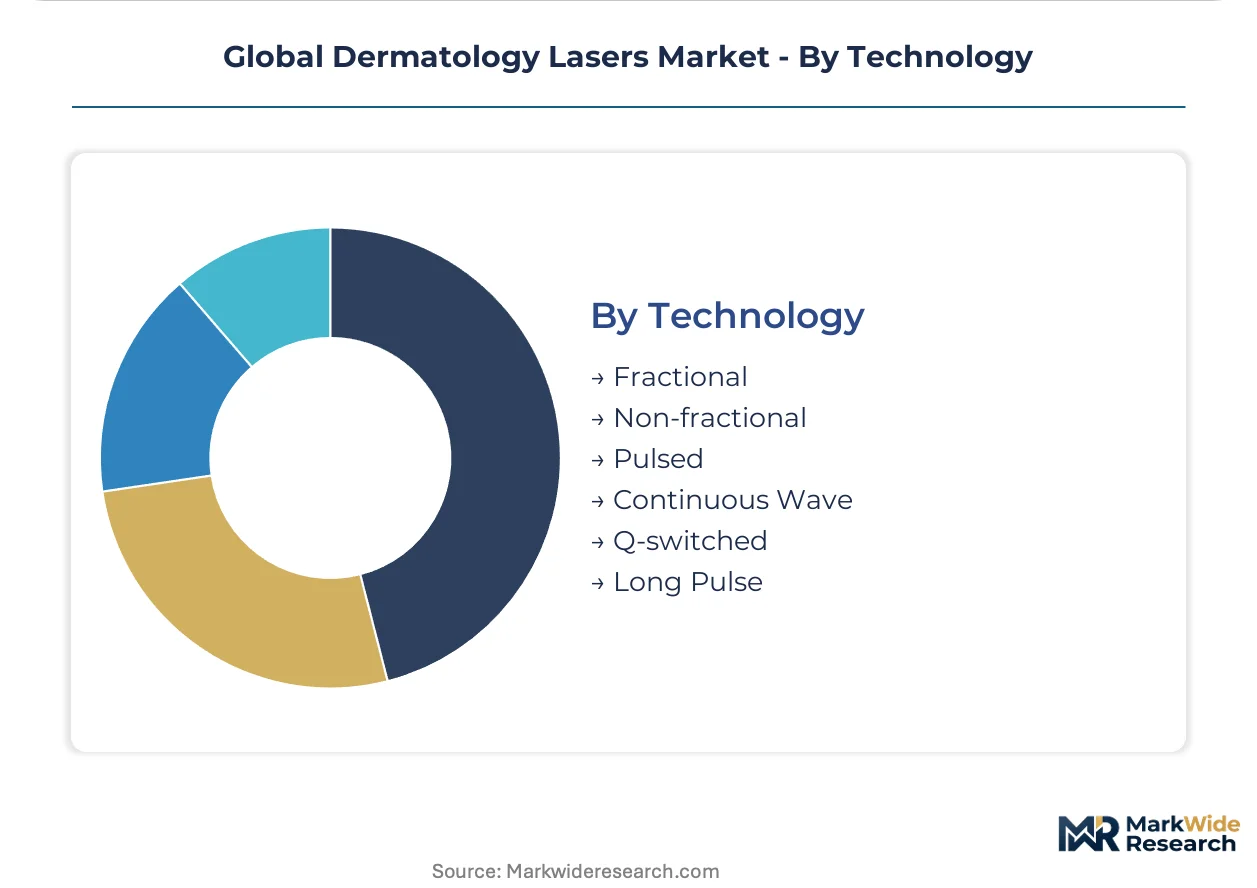
Technology:
Modulation architecture determines thermal injury pattern, recovery timeline, and treatable patient skin phototype range that constrains addressable market size.
- Fractional:Microscopic treatment column arrays preserve intervening intact tissue for rapid healing. CO2 and erbium fractional platforms dominate skin resurfacing revenue pools due to premium pricing and repeat treatment requirements.
- Non-fractional:Uniform beam profile delivers consistent energy across treatment area. Continuous wave and long-pulse configurations suit vascular and hair removal protocols requiring homogeneous thermal distribution.
- Pulsed:Discrete energy delivery with controlled pulse duration enables selective photothermolysis. Q-switched nanosecond and picosecond architectures define tattoo removal and pigmentation treatment categories.
- Continuous Wave:Uninterrupted emission sustains tissue interaction for cutting and coagulation applications. CO2 surgical lasers in dermatology deploy this mode for excisional procedures.
- Q-switched:Cavity dumping generates nanosecond pulse durations for photoacoustic ink fragmentation. Legacy installed bases face replacement pressure from picosecond technology expansion.
- Long Pulse:Millisecond-duration emission enables gradual heating of larger vascular targets. Safer operation across darker skin phototypes drives adoption in Asian and Middle Eastern markets.
Fractional technology anchors premium system pricing today; picosecond pulse architecture is expanding most quickly as platform refresh cycles compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's aesthetic clinic corridor concentrates the highest density of picosecond laser installations worldwide. Medical spa chains across Los Angeles and San Diego drive equipment refresh cycles that outpace national averages. The state's physician-owned practice networks influence technology adoption patterns across the western United States.
United States
Texas and Florida medical spa chains standardize laser service menus, creating predictable equipment procurement schedules and bundled consumable contracts. The FDA's 510(k) clearance pathway shapes commercialization timelines for aesthetic laser devices. Dallas and Houston dermatology networks deploy fractional resurfacing platforms at rates exceeding national benchmarks.
Germany
German glass-ceramic manufacturers control critical CO2 laser resonator tube production, exposing OEMs to input cost volatility and extended lead times. The EU MDR imposes stricter clinical evidence requirements for CE marking of aesthetic energy devices. Frankfurt and Munich hospital procurement committees consolidate purchasing authority for multi-wavelength dermatology platforms.
China
Shanghai-based regulatory affairs teams respond to NMPA registration pathway tightening for imported laser systems. The NMPA mandates local clinical trials for certain wavelength categories, extending commercialization timelines by 18-24 months versus domestic competitors. Beijing and Guangzhou dermatology clinic networks scale rapidly, creating concentrated demand growth corridors for hair removal and vascular lesion protocols.
India
Mumbai and Delhi metro hospital chains deploy fractional resurfacing platforms, creating first-mover advantage for direct-distribution models. The CDSCO regulates medical device imports with classification pathways that influence capital equipment procurement decisions. Bangalore's aesthetic medicine specialists drive adoption of long-pulse Nd:YAG systems for darker skin phototypes.
Japan
Tokyo and Osaka cosmetic surgery centers procure multi-wavelength systems aligned with PMDA reimbursement reclassifications. The PMDA maintains distinct hospital procurement categories that favor documented clinical outcomes. Kansai region dermatology departments negotiate separately for preventive maintenance and software update agreements.
Global Dermatology Lasers Market Competitive Landscape
Global majors compete with regional champions across distribution architecture and service network density. The vendor base stratifies between full-platform OEMs with captive consumable revenue and specialized manufacturers focused on single-modality excellence. Three archetypes dominate: installed-base incumbents leveraging recurring consumable streams, direct-distribution specialists capturing emerging market growth, and training-ecosystem players locking physician loyalty. Consolidation pressure intensifies through strategic partnerships and technology licensing arrangements.
Within the installed-base incumbent tier, Lumenis and Alma Lasers occupy positions that exemplify contrasting geographic strategies. Lumenis leverages its historical presence in hair removal to sustain recurring revenue architectures. Alma Lasers anchors its stance through direct distribution across Middle Eastern and Asian markets. Sciton represents the training-ecosystem archetype, differentiating via physician education programs that reinforce platform loyalty. These three illustrate how competitive positioning in dermatology lasers depends on post-sale relationship depth rather than hardware specifications alone.
| Leading Market Players |
|---|
| Cutera |
| Cynosure |
| Lumenis |
| Alma Lasers |
| Fotona |
| Candela Corporation |
| Quanta System |
| Sciton |
| Aerolase Corporation |
| Others |
Supply & Pricing Matrix
Precision optics engineers concentrated in German and Swiss manufacturing clusters command wage premiums that compress margins on mid-tier laser platforms while widening spreads between premium systems and economy alternatives. Labor-cost differentials between these specialized European workforces and Asian assembly operations feed directly into three-tier pricing stratification across dermatology laser portfolios.
Pricing Analysis
Input-cost pass-through from CO2 laser tube supply constraints drives pricing pressure on ablative resurfacing platforms, with German glass-ceramic manufacturers capturing value upstream. Certification grade—FDA 510(k) versus CE MDR versus NMPA—creates price differentiation between regulatory tiers, while volume scale through medical spa chain contracts compresses per-unit economics. Pricing pressure stems from IPL substitution in emerging markets, eroding entry-level laser ASPs. Medical spas exhibit highest price sensitivity due to capital constraints, whereas cosmetic surgery centers prioritize clinical outcome documentation over acquisition cost.
Supply Chain Analysis
Single-source vulnerability sits with German and American glass-ceramic manufacturers controlling CO2 laser resonator tube production. Geographic supply concentration centers on Germany, the United States, and China for critical components including neodymium-doped yttrium aluminum garnet crystals, titanium-sapphire gain media, and precision optical coatings. Raw material dependencies include rare-earth elements for solid-state lasers, specialty gases for CO2 architectures, and high-purity sapphire substrates. Tariff exposure on imported optical components threatens margin stability for OEMs with China-centric assembly. Distribution runs through direct sales forces for hospital procurement committees and authorized distributors for medical spa networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dermatology lasers market functions as a stable compounder anchored by recurring consumable revenue streams and predictable equipment refresh cycles driven by picosecond technology displacement.
For Market Incumbents: Anchor installed-base loyalty through software-upgradable wavelength modules that extend platform lifecycle and deepen consumable attachment. Defend against IPL substitution by bundling preventive maintenance contracts with capital equipment sales. Prioritize backward integration into resonator tube supply to mitigate German manufacturer pricing power. Investment in technician certification ecosystems locks clinic staffing decisions to proprietary platforms. For New Entrants and Emerging Players: Regional distributors with NMPA licenses in China offer the most viable entry pathway around extended registration timelines for imported systems. White-space targets include long-pulse Nd:YAG platforms for Indian metro hospital chains expanding vascular lesion protocols, and compact air-cooled diode systems for mobile aesthetic providers. Direct-distribution models in Mumbai and Delhi bypass established OEM service networks. Focus initial commercialization on software-defined platforms with cybersecurity-hardened firmware update capabilities. For Investors and Strategic Acquirers: Private equity firms with healthcare device portfolios are the most active acquirer in this space, targeting training-ecosystem players with captive physician networks. Long-term viability rests on consumable revenue recurrence rather than hardware shipment cyclicality. Acquisition target archetype: regional champions with direct distribution in Middle Eastern or Asian markets lacking captive service infrastructure. Monitor FDA cybersecurity guidance evolution as inflection indicator for legacy device liability exposure and replacement demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Wavelength Expansion | Networked firmware updates enable indication expansion without hardware replacement, deepening platform lock-in. |
| CE MDR Clinical Evidence Investment | Stricter EU documentation requirements filter marginal competitors and consolidate hospital procurement authority. |
| NMPA Regulatory Affairs Localization | Shanghai-based teams and domestic distributor partnerships compress 18-24 month registration delays for imported systems. |
| Technician Certification Ecosystem Development | Physician training programs in picosecond fluence calibration create switching costs and sustain platform loyalty. |
| Consumable Revenue Contract Unbundling | Separate preventive maintenance and spare parts agreements align with European hospital procurement committee preferences. |
Research Methodology
Coverage spans North America, Western Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Primary interviews engaged dermatology clinic medical directors, hospital biomedical engineers, medical spa chain procurement officers, and aesthetic device regulatory affairs specialists. Secondary sources included FDA 510(k) premarket notification databases, EU MDR technical documentation filings, NMPA registration records, and hospital GPO contract repositories. Bottom-up equipment shipment modeling and top-down procedure volume estimates were triangulated against manufacturer revenue disclosures.
Granularity-level modeling deployed wavelength-specific demand curves by skin phototype indication, with technology architecture and end-user facility type as cross-cutting segmentation dimensions. Value outputs across the projection horizon reflect procedure economics including consumable attachment rates and equipment replacement cycle compression. CAGRs were derived from installed base growth net of technology displacement effects, incorporating NMPA registration timeline assumptions and medical spa network expansion trajectories. Forecast inputs included picosecond platform penetration rates and IPL substitution elasticity by price tier.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NMPA regulatory pathway evolution and cybersecurity mandate implementation. Forecasts reflect assumptions regarding technician certification pipeline capacity and consumable pricing power preservation. Specific risks that could revise trajectories include resonator tube supply disruption, reimbursement reclassification in Japan, and accelerated IPL technology improvement. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Acne Scar Treatment Market
Dermatology
Saudi Arabia Hair Transplant Market
Dermatology
Seborrheic Keratosis Treatment Market
Dermatology
Acne Vulgaris Market
Dermatology
Seborrheic Keratosis Market
Dermatology
Atopic Dermatitis Treatment Market
Dermatology
Scar Treatment Oils Market
Dermatology
Global Ozone Therapy in Dermatology Market
Dermatology
Dermatophytic Onychomycosis Treatment Market
Dermatology
Alopecia Treatment (Hair Loss) Market
Dermatology
Keloid Treatment Market
Dermatology
Psoriasis Treatment Market
Dermatology
Global Dermatological OTC Drugs Market
Dermatology
Derma Rollers Market
Dermatology
Global Rosacea Market
Dermatology
Common Warts Market