
 Achondrogenesis Market | 2026-2036
Achondrogenesis Market Size, Share, and Industry Trends Forecast 2026-2036
Achondrogenesis Market Analysis
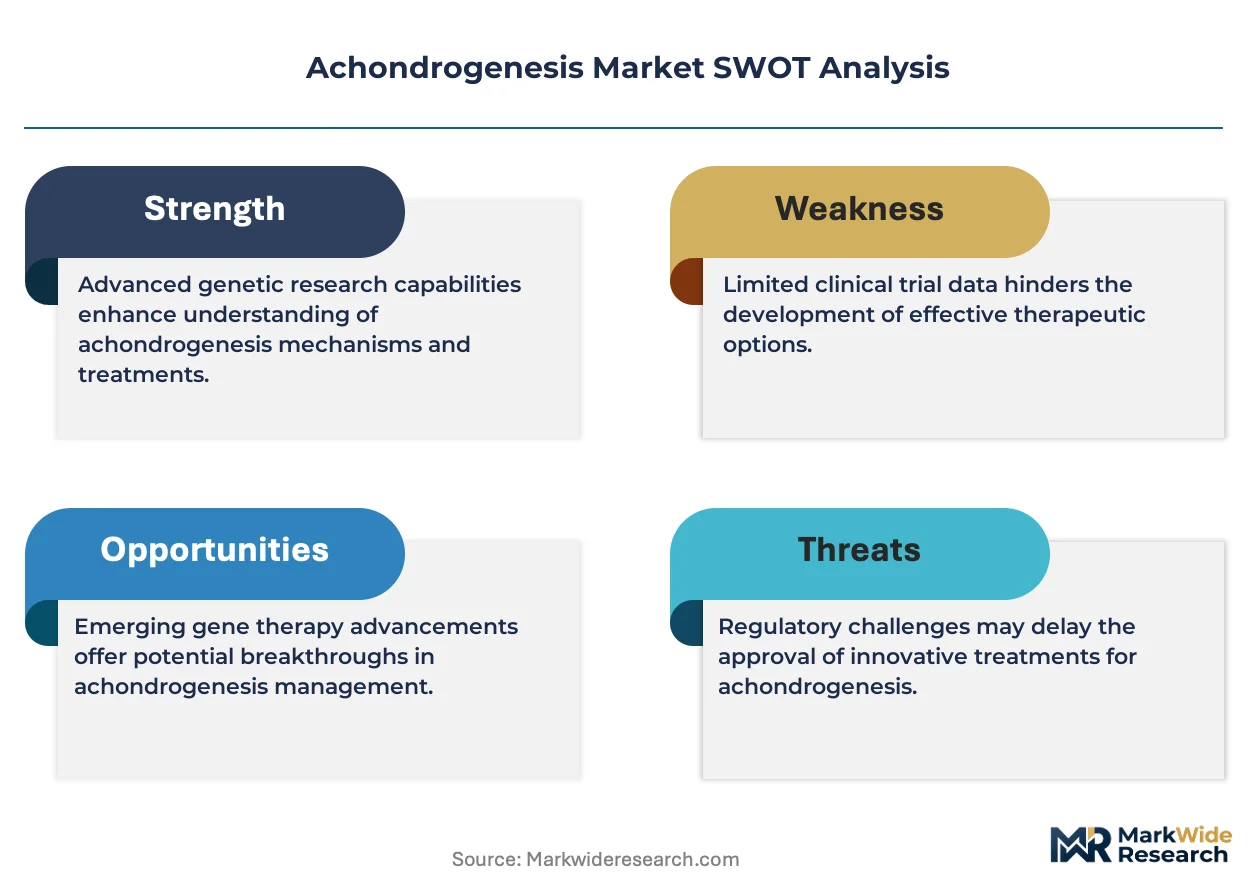
The FDA's Orphan Drug Designation program is recalibrating investment timelines for ultra-rare skeletal disorders. Thermo Fisher Scientific sustains its molecular diagnostics franchise through deep R&D allocation across prenatal sequencing workflows. Illumina dominates the next-generation sequencing infrastructure that underpins carrier screening and fetal exome analysis for recessive chondrodysplasias. Koninklijke Philips N.V. leverages its ultrasound imaging portfolio to anchor prenatal detection protocols in tertiary perinatal centers.
Achondrogenesis denotes a lethal autosomal recessive chondrodysplasia characterized by severe micromelia, deficient ossification of the vertebral bodies, and pulmonary hypoplasia resulting from mutations in TRIP11, SLC26A2, or COL2A1 genes. Diagnostic tools command the largest revenue pool within product type segmentation, driven by mandatory prenatal imaging and molecular confirmation workflows. Gene therapy represents the fastest-expanding category, though clinical-stage programs remain concentrated in academic-industry partnerships. Hospitals absorb the dominant share of end-user spending, reflecting the concentration of high-risk obstetrics and neonatal intensive care in quaternary referral networks.
The FDA maintains stringent oversight of gene therapy investigational new drug applications for in utero interventions, while the EMA's Committee for Advanced Therapies evaluates parallel pathways in Europe. ISO 15189 accreditation requirements shape quality benchmarks for diagnostic laboratories processing prenatal samples. Stakeholders must monitor regulatory precedent for germline-modifying therapies, as first-mover advantage in approved protocols will consolidate specialist referral networks and reimbursement contracts.
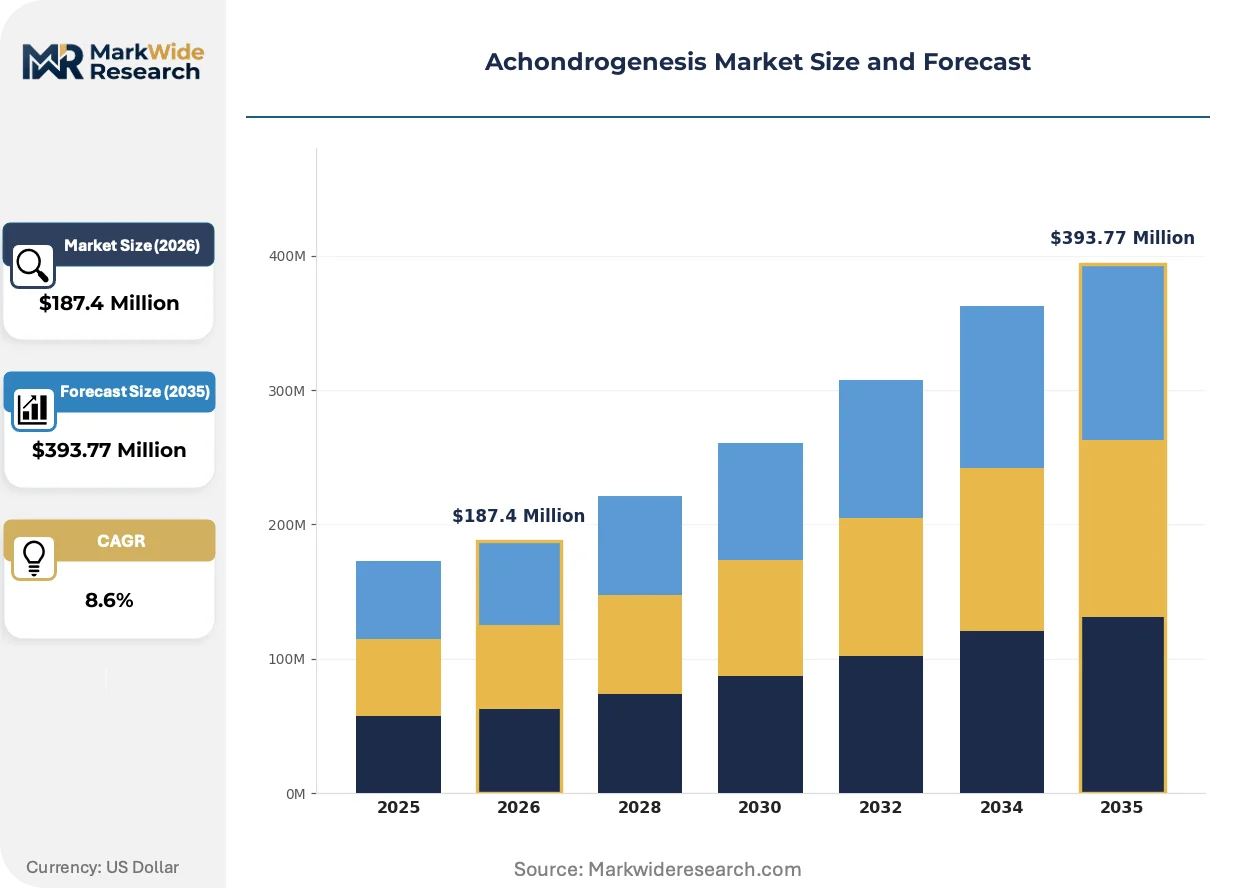
Market Dynamics
The FDA's expanding orphan drug incentives are compressing investment timelines for ultra-rare skeletal dysplasias, while prenatal diagnostic workflows concentrate around academic medical hubs with deep sequencing infrastructure.
Growth Catalysts
- Orphan Drug Act incentives:The FDA's tax credits and market exclusivity provisions accelerate sponsor recruitment for achondrogenesis gene therapy trials. Sponsors now front-load clinical design to capture these benefits.
- Non-invasive prenatal testing (NIPT) expansion:Cell-free DNA screening protocols are extending into recessive chondrodysplasia panels. Maternal-fetal medicine specialists in tertiary centers are adopting expanded carrier screening as standard workflow.
- Tertiary perinatal center clustering:High-risk obstetrics concentration in academic hubs creates captive demand for specialized diagnostics. These centers generate referral gravity that pulls molecular confirmation testing into centralized laboratory networks.
Market Restraints
- Gene therapy manufacturing input costs:Viral vector production and GMP plasmid supply constraints inflate COGS for in utero intervention candidates. Sponsors face margin pressure before clinical proof-of-concept.
- Specialized sonographer supply concentration:Advanced fetal skeletal imaging expertise clusters in fewer than forty US academic centers. This geographic concentration limits diagnostic access outside major metropolitan corridors.
- Reimbursement friction for exome sequencing:Payers apply prior authorization barriers to fetal exome analysis for lethal skeletal dysplasias. Diagnostic laboratories absorb bad debt from denied claims.
Strategic Opportunities
- In utero gene therapy regulatory pathway:The FDA's INTERACT meetings and emerging guidance on germline-modifying interventions create first-mover consolidation potential. Early protocol approvals will lock in specialist referral networks.
- Expanded carrier screening mandates:State-level newborn screening program expansions into recessive skeletal dysplasias are creating downstream demand for prenatal confirmation testing. Laboratories can capture this cascade.
- AI-assisted fetal skeletal biometry:Machine learning classification of micromelia and vertebral ossification defects on standard ultrasound is converging with cloud-based telemedicine platforms. Community hospitals can access tertiary-level diagnostic support.
Industry Challenges
- Fetal intervention surgical skill scarcity:In utero gene delivery requires maternal-fetal surgery expertise that resides in fewer than fifteen US centers. Training pipelines cannot scale to match trial demand.
- ISO 15189 accreditation timelines:Prenatal diagnostic laboratories face eighteen-to-twenty-four-month quality system implementation cycles. This delays market entry for new molecular testing entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Achondrogenesis Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Gene Therapy, Enzyme Replacement, Diagnostic Tools End User: Hospitals, Research Institutes, Clinics, Diagnostic Laboratories Delivery Mode: Intravenous, Subcutaneous, Oral, Intraosseous Indication: Bone Development Disorders, Genetic Conditions, Congenital Deficiencies, Others |
| Companies Covered | Siemens, Koninklijke Philips N.V., Thermo Fisher Scientific Inc., Invivoscribe, Inc., Stryker, CooperSurgical, Inc., Bio-Rad Laboratories, Inc., Abbott, Illumina, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Achondrogenesis Market Emerging Trajectories
Sequencing cost compression and regulatory pathway clarity are converging to reshape how lethal skeletal dysplasias are detected and potentially treated before birth.
Non-invasive prenatal diagnosis (NIPD) using cell-free fetal DNA is decentralizing access to achondrogenesis carrier detection. Community obstetrics practices in the United States are adopting outsourced NIPT panels that include TRIP11, SLC26A2, and COL2A1 gene targets. This technology is decentralizing what previously required amniocentesis at tertiary centers, compressing the diagnostic timeline from second-trimester intervention to first-trimester screening.
REACH authorization requirements for viral vector manufacturing in Europe are tightening supply chain documentation for gene therapy sponsors. The EMA's Committee for Advanced Therapies is demanding extended pharmacovigilance for in utero interventions. Sponsors targeting achondrogenesis are responding by front-loading CMC development to secure European trial site activation alongside US FDA IND submissions.
Patient advocacy networks are consolidating procurement influence over research funding and trial design. Foundation-led natural history study sponsorship in the United States is displacing traditional academic grant mechanisms as the primary data source for regulatory submissions. This shift is most visible in how FDA breakthrough therapy designations for skeletal dysplasias now require documented patient engagement in protocol development.
Achondrogenesis Market Segmentation
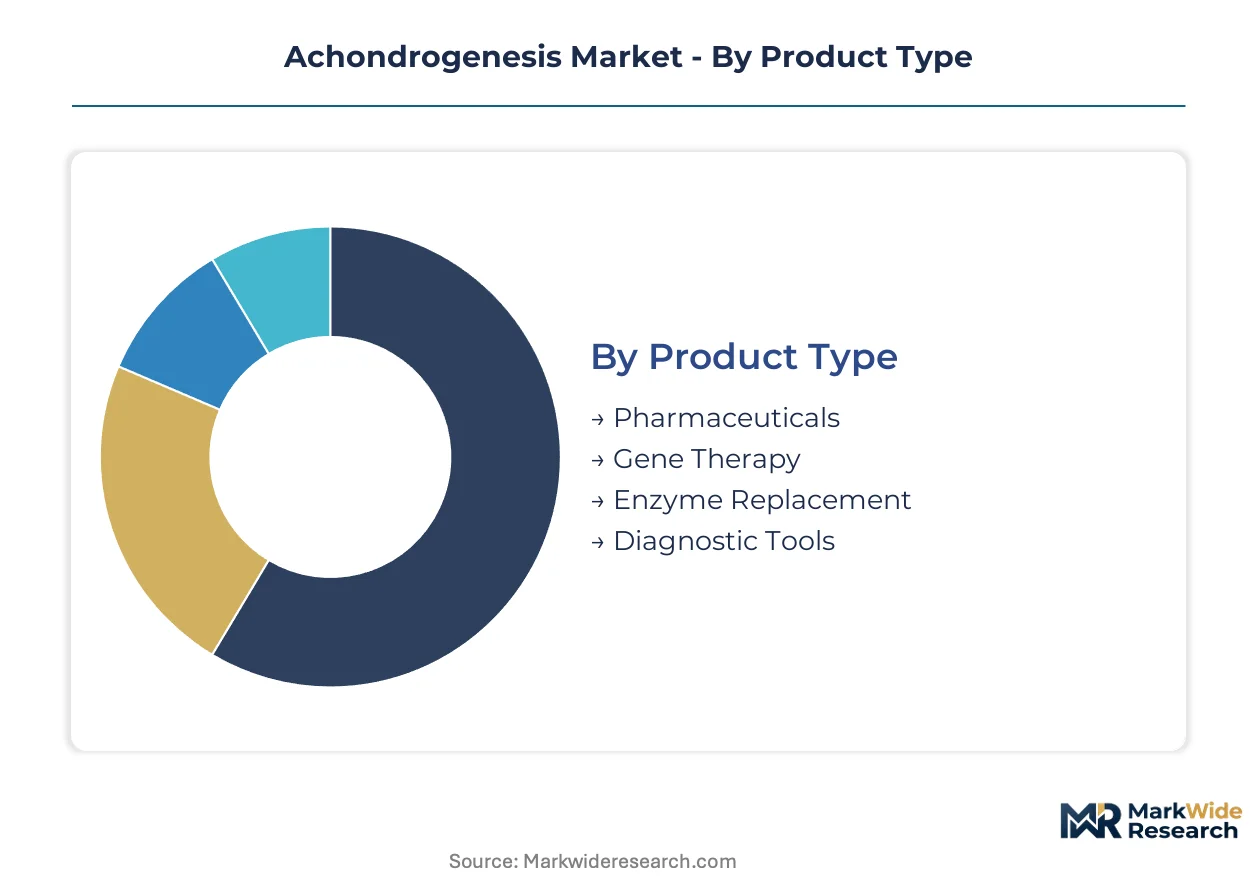
Achondrogenesis market segmentation reveals how supply-side capabilities concentrate around specialized infrastructure. Product type and end-user categories map directly to regulatory clearance pathways and reimbursement contracts.
Product Type:
Diagnostic tools and gene therapy manufacturing anchor supply concentration in FDA-cleared facilities and GMP viral vector sites.
- Diagnostic Tools:Prenatal ultrasound protocols and molecular sequencing workflows for TRIP11, SLC26A2, and COL2A1 mutation detection. Demand clusters at tertiary perinatal centers in Boston, San Francisco, and London where maternal-fetal medicine specialists command referral networks.
- Gene Therapy:In utero viral vector delivery systems targeting chondrocyte lineage correction. Sponsors front-load CMC development to capture FDA orphan drug incentives, though GMP plasmid supply constraints limit manufacturing scale.
- Pharmaceuticals:Supportive care agents for respiratory and orthopedic complications.
- Enzyme Replacement:Experimental SLC26A2 pathway modulation in preclinical development.
Today's leader: Diagnostic Tools. Tomorrow's challenger: Gene Therapy.
End User:
Hospital concentration in academic medical hubs shapes procurement patterns and technology adoption curves.
- Hospitals:Quaternary referral networks with integrated maternal-fetal surgery and neonatal intensive care units. These centers generate captive demand for specialized diagnostics and capture the dominant share of spending through bundled obstetric care contracts.
- Diagnostic Laboratories:ISO 15189-accredited molecular testing facilities processing amniocentesis and chorionic villus samples. Geographic concentration limits access outside major metropolitan corridors.
- Research Institutes:Academic-industry partnerships conducting natural history studies and IND-enabling work.
- Clinics:Community obstetrics practices outsourcing complex screening to centralized laboratory networks.
Procurement authority rests with Hospitals. Research Institutes are gaining influence through foundation-sponsored natural history data.
Delivery Mode:
Route selection follows intervention timing and anatomical target constraints.
- Intravenous:Systemic vector distribution for hepatocyte-targeted gene correction protocols.
- Intraosseous:Direct skeletal targeting for chondrocyte precursor delivery in utero. Demand concentrates at the fifteen US centers with maternal-fetal surgery expertise.
- Subcutaneous:Enzyme replacement administration in postnatal supportive care.
- Oral:Palliative agents for respiratory symptom management.
Intraosseous commands premium positioning. Intravenous offers the broadest addressable base.
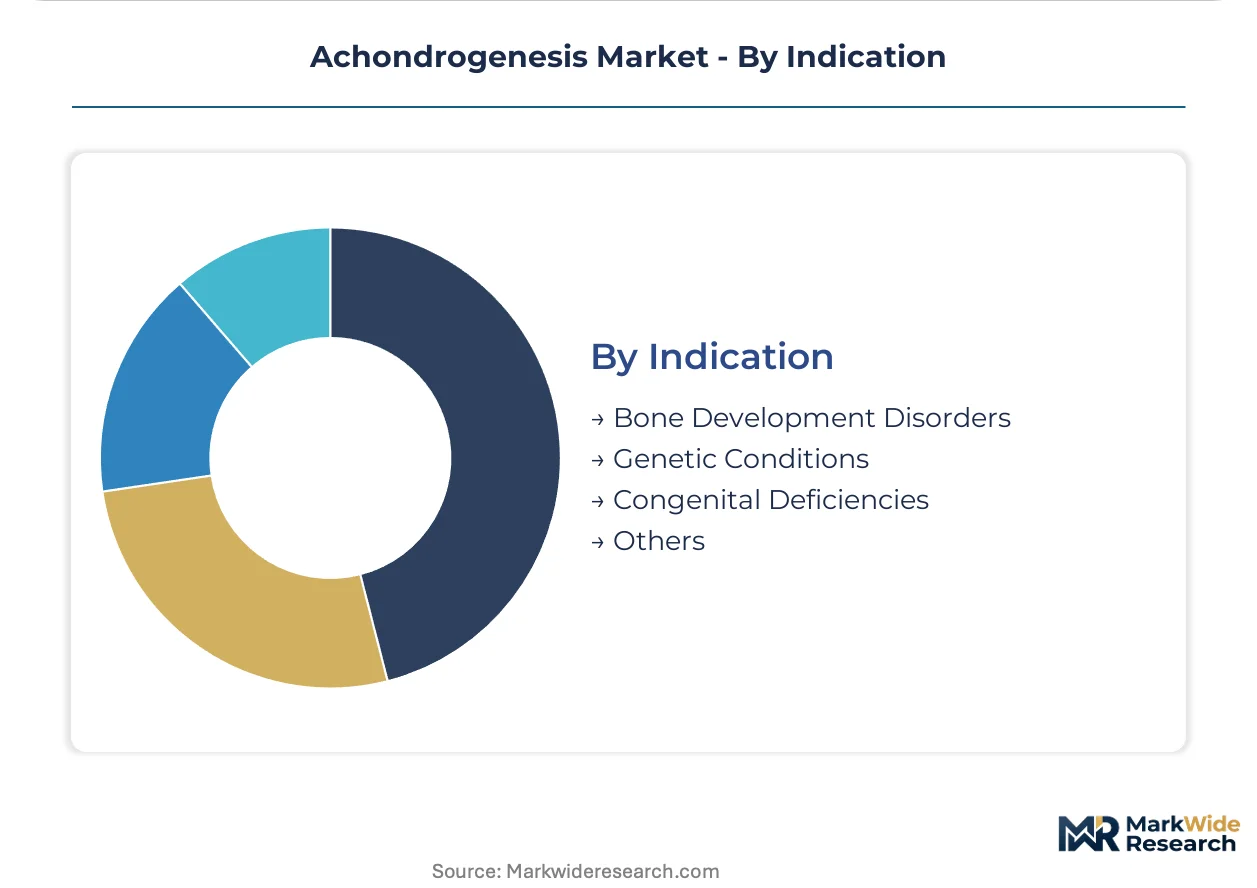
Indication:
Clinical indication segmentation tracks how diagnostic coding affects reimbursement pathways.
- Genetic Conditions:Confirmed TRIP11, SLC26A2, or COL2A1 mutations with molecular diagnostic backing. Payers apply prior authorization barriers, concentrating confirmed cases at centers with dedicated genetic counseling infrastructure.
- Bone Development Disorders:Phenotypic skeletal dysplasia classification based on fetal ultrasound biometry. Community hospitals refer ambiguous cases to tertiary centers with advanced imaging interpretation.
- Congenital Deficiencies:Associated pulmonary and orthopedic complications requiring multidisciplinary management.
- Others:Atypical presentations and variant classifications pending molecular confirmation.
Genetic Conditions anchor specialist referral networks. Bone Development Disorders drive community-to-tertiary care migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The achondrogenesis market traces its diagnostic foundations to postwar advances in prenatal radiology at London teaching hospitals, where fetal skeletal imaging protocols first standardized. Subsequent molecular characterization of TRIP11 and SLC26A2 mutations emerged from Dutch and German genetic research centers during the 1990s. Today's commercial activity clusters where tertiary perinatal infrastructure, sequencing capacity, and regulatory pathway clarity converge.
United States
FDA orphan drug incentives and bundled obstetric care contracts concentrate investment in Boston, San Francisco, and Philadelphia academic medical centers. The agency's INTERACT meeting framework accelerates IND timelines for in utero gene therapy sponsors. Maternal-fetal surgery expertise resides in fewer than fifteen US centers, creating geographic access constraints and referral network consolidation.
Germany
EMA Committee for Advanced Therapies oversight and REACH authorization requirements for viral vector manufacturing shape sponsor strategy. Heidelberg and Berlin host Europe's densest clusters of prenatal diagnostic laboratories with ISO 15189 accreditation. German university hospitals generate natural history data that anchors regulatory submissions for skeletal dysplasia programs.
United Kingdom
NHS specialized commissioning frameworks concentrate achondrogenesis diagnosis at London, Manchester, and Glasgow fetal medicine units. The MHRA's alignment with FDA gene therapy guidance reduces regulatory friction for transatlantic trial designs. Oxford and Cambridge academic-industry partnerships dominate European prenatal exome sequencing referral volumes.
Japan
PMDA consultation procedures for regenerative medicine products create structured entry pathways for in utero interventions. Tokyo and Osaka maternal-fetal medicine centers deploy advanced ultrasound biometry for lethal skeletal dysplasia screening. Japanese sequencing infrastructure supports expanded carrier screening panels that include recessive chondrodysplasia targets.
Switzerland
Swissmedic's streamlined orphan drug designation process attracts sponsor headquarters and clinical trial operations. Basel and Zurich pharmaceutical clusters provide viral vector manufacturing and GMP plasmid supply chain proximity. Swiss university hospitals participate in multinational natural history studies that satisfy FDA and EMA evidentiary requirements.
Achondrogenesis Market Vendor Landscape
Capital-heavy diagnostic equipment producers compete with asset-light molecular testing service providers across distinct value chain segments. Market structure bifurcates between consolidated imaging and sequencing platform vendors and fragmented laboratory service specialists. Three archetypes dominate: integrated diagnostic platform manufacturers, specialized prenatal testing laboratories, and gene therapy development sponsors. Competitive dynamics center on strategic partnerships between platform vendors and academic medical centers, plus regulatory pathway exclusivity capture through early FDA engagement.
Among integrated diagnostic platform manufacturers, Siemens, Koninklijke Philips N.V., and Thermo Fisher Scientific Inc. exemplify divergent strategic positions. Siemens occupies a position within advanced imaging hardware for fetal skeletal assessment. Koninklijke Philips N.V. represents ultrasound platform consolidation in tertiary perinatal centers. Thermo Fisher Scientific Inc. anchors molecular diagnostics infrastructure for prenatal sequencing workflows. These three entities collectively illustrate how equipment scale, regulatory clearance breadth, and academic medical center penetration define competitive positioning in rare disease diagnostic markets.
| Leading Market Players |
|---|
| Siemens |
| Koninklijke Philips N.V. |
| Thermo Fisher Scientific Inc. |
| Invivoscribe, Inc. |
| Stryker |
| CooperSurgical, Inc. |
| Bio-Rad Laboratories, Inc. |
| Abbott |
| Illumina, Inc. |
| Others |
Supply Flow & Price Mechanics
Quaternary referral hospital procurement committees anchor pricing power in the achondrogenesis market through bundled obstetric care contracts that consolidate diagnostic and therapeutic purchasing decisions. This buyer concentration enables premium-tier pricing for ISO 15189-accredited molecular testing while squeezing margins on commodity ultrasound hardware.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and geographic delivery cost. Premium tiers attach to tertiary perinatal centers with maternal-fetal surgery capabilities in Boston, San Francisco, and Philadelphia. Price differentiation stems from GMP plasmid supply scarcity and specialized sonographer labor premiums. Cost compression in standard-tier prenatal screening panels is intensifying because community hospitals outsource to centralized laboratory networks. Community obstetrics practices exhibit highest price sensitivity; quaternary academic centers demonstrate lowest sensitivity due to bundled reimbursement contracts.
Supply Chain Analysis
Viral vector manufacturing rests on GMP plasmid suppliers concentrated in the United States, Germany, and Switzerland. Raw material dependencies include recombinant AAV serotypes, synthetic DNA templates, and fetal bovine serum for cell culture propagation. Single-source vulnerability permeates the AAV capsid supply base following REACH authorization tightening in Europe. Distribution runs through specialized cold-chain logistics providers serving the fifteen US centers with maternal-fetal surgery expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in the achondrogenesis market hinges on sequencing cost compression enabling broader carrier screening panels, while gene therapy sponsors capture orphan drug exclusivity premiums. The shift from second-trimester invasive procedures to first-trimester cell-free DNA screening compresses diagnostic timelines and concentrates volume at accredited laboratory networks.
For Market Incumbents: Extend platform stickiness by embedding AI-assisted fetal skeletal biometry into existing ultrasound installations at tertiary perinatal centers. Deepen captive supply of GMP plasmid through backward integration into viral vector manufacturing to offset emerging entrant price pressure on gene therapy candidates. Lock in specialist referral networks through early FDA INTERACT engagement for in utero intervention protocols. For New Entrants and Emerging Players: Telemedicine-enabled remote interpretation platforms offer the most penetrable route into community hospital prenatal screening workflows. Target white-space in AI-assisted ultrasound classification for micromelia detection outside the forty US academic centers with advanced fetal imaging expertise. Deploy cloud-based diagnostic support as a wedge against incumbent hardware bundling. For Investors and Strategic Acquirers: Gene therapy development sponsors are the most active acquirer in this space, consolidating IND-enabling assets and natural history study data. Long-term viability frames around regulatory pathway exclusivity capture and specialist referral network lock-in rather than near-term revenue. Watch FDA breakthrough therapy designation velocity for skeletal dysplasias as the inflection signal for first-mover consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Orphan Drug Designation Capture | Front-loaded clinical design secures tax credits and market exclusivity for achondrogenesis gene therapy sponsors. |
| ISO 15189 Laboratory Accreditation | Eighteen-month quality system implementation creates defensive moats for incumbent molecular testing providers. |
| AI-Assisted Fetal Biometry Integration | Machine learning classification of vertebral ossification defects extends diagnostic reach to community hospitals. |
| GMP Viral Vector Manufacturing Scale-Up | REACH authorization compliance in Europe secures transatlantic trial site activation for in utero interventions. |
| Expanded Carrier Screening Mandate Lobbying | State-level newborn screening program expansion generates downstream demand for prenatal confirmation testing. |
Methodological Framework
Direct dialogue with maternal-fetal medicine specialists, genetic counselors, diagnostic laboratory directors, and gene therapy development executives grounded the qualitative foundation. Secondary validation drew from FDA orphan drug designations, EMA Committee for Advanced Therapies opinions, ClinicalTrials.gov entries for skeletal dysplasia interventions, and ISO 15189 accreditation registries. Bottom-up patient flow modeling and top-down orphan drug incentive impact assessment were triangulated to anchor volume and value estimates.
Bottom-up segmentation by product type, end user, delivery mode, and indication converged with top-down regulatory pathway analysis across the projection horizon. CAGRs were derived from patent expiry timelines, orphan drug exclusivity windows, and sequencing cost compression curves. Modeled dimensions included diagnostic tool versus gene therapy revenue splits, hospital versus laboratory procurement authority, and intraosseous versus intravenous delivery penetration.
The model assumes a particular technology adoption path; alternative pathways for in utero gene editing would alter the outlook if germline-modifying therapy guidance shifts. Forecasts reflect assumptions about FDA IND approval velocity, GMP plasmid supply scaling, and tertiary perinatal center referral network consolidation. A small set of triggers—EMA pharmacovigilance tightening, state-level carrier screening mandate expansion, and AI-assisted diagnostic FDA clearance—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Rett Syndrome Market
Rare Diseases
Alzheimer Disease Market
Rare Diseases
Rare Inflammatory Disease Treatment Market
Rare Diseases
Behcets Disease Market
Rare Diseases
Von Hippel-Lindau Market
Rare Diseases
Fragile X Syndrome Market
Rare Diseases
Chronic Granulomatous Disease Market
Rare Diseases
Hutchinson Gilford Progeria Syndrome (HGPS) Therapeutics Market
Rare Diseases
Arthrogryposis Management Market
Rare Diseases
Niemann Pick Disease Market
Rare Diseases
Phelan-Mcdermid Syndrome Market
Rare Diseases
Atypical Hemolytic Uremic Syndrome (Ahus) Treatment Market
Rare Diseases
Congenital Adrenal Hyperplasia Market
Rare Diseases
Asia-Pacific Down Syndrome Market
Rare Diseases
Parry-Romberg Syndrome Market
Rare Diseases
Dystrophic Epidermolysis Bullosa Treatment Market