
 Yellow Nail Syndrome Treatment Market | 2026-2036
Yellow Nail Syndrome Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Yellow Nail Syndrome Treatment Market Insights
Specialty-grade antifungal formulations is reorganizing competitive dynamics in Yellow Nail Syndrome treatment. Novartis leverages its respiratory and immunology infrastructure to address lymphatic complications tied to the syndrome. Pfizer sustains development of targeted systemic therapies through its established infectious disease pipeline. Sanofi competes via integrated dermatology networks that streamline patient access to combination regimens.
Yellow Nail Syndrome treatment encompasses therapeutic interventions addressing the triad of yellow dystrophic nails, lymphedema, and pleural effusions, with systemic antifungals such as itraconazole and nutritional supplementation with vitamin E serving as primary pharmacological modalities. The condition's management demands coordinated pulmonology, dermatology, and lymphatic care to resolve both cosmetic and functional impairment. Systemic medications capture the dominant margin pool given prolonged treatment durations and specialist oversight requirements, while topical treatments address localized nail pathology with narrower reimbursement profiles. Oral delivery mode retains the largest patient volume share, though intravenous options serve refractory cases in hospital settings.
FDA orphan drug designations and EMA rare disease frameworks incentivize manufacturers to pursue indications for conditions with limited therapeutic alternatives, directly shaping R&D allocation across the competitive set. WHO inclusion of lymphatic disorders within chronic disease programs elevates diagnostic awareness in lower-resource settings, expanding addressable patient populations. Stakeholders must monitor regulatory harmonization between FDA accelerated approval pathways and EMA conditional marketing authorization to optimize launch sequencing and portfolio prioritization.
Market Dynamics
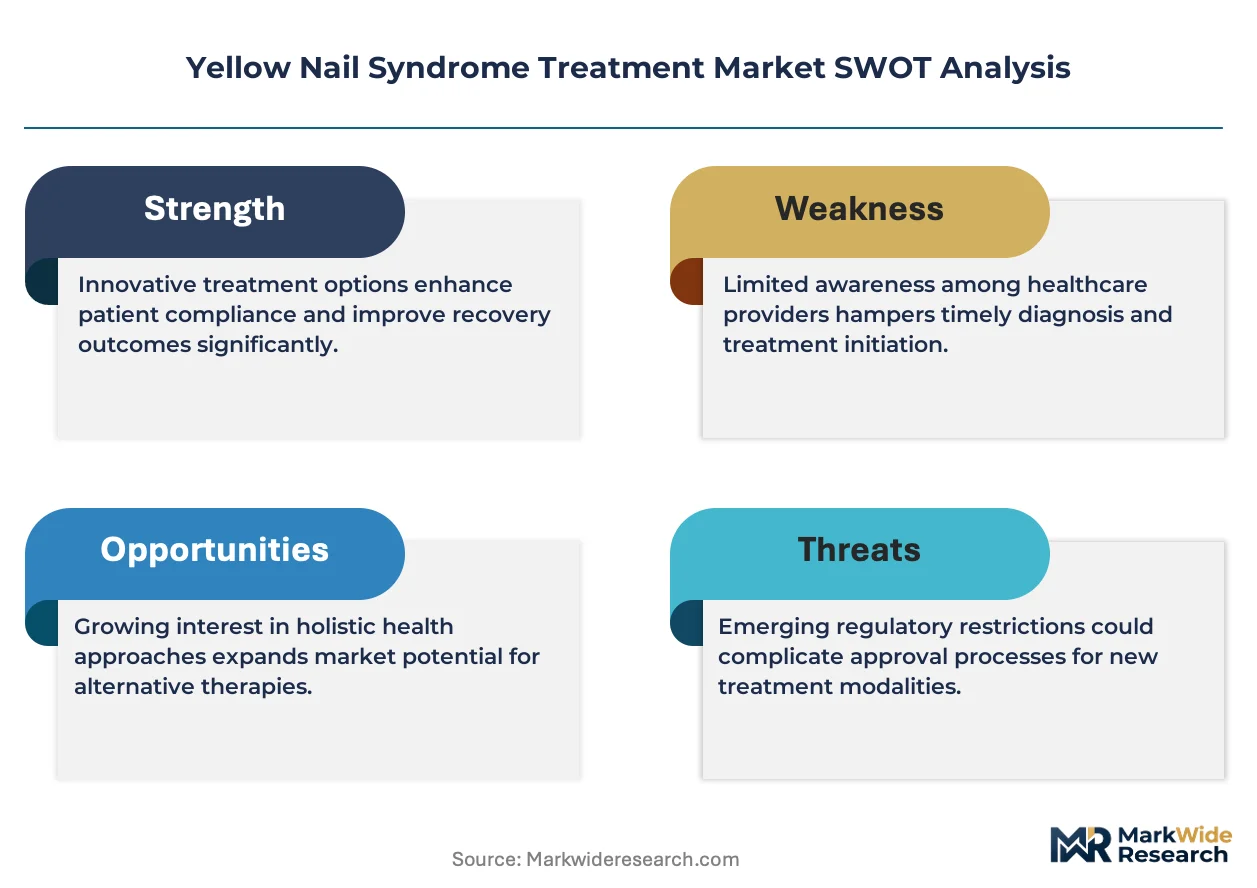
Orphan drug designation pathways at FDA and EMA are concentrating R&D investment toward rare disease indications, redirecting capital from blockbusters toward conditions like Yellow Nail Syndrome where unmet need justifies premium pricing and extended exclusivity periods.
Growth Catalysts
- FDA Orphan Drug Incentives:Tax credits for clinical trials and seven-year market exclusivity accelerate sponsor commitment to rare lymphatic disorders with limited therapeutic alternatives.
- Dermatology Clinic Expansion:Specialist outpatient networks in the United States and Germany are streamlining diagnostic pathways for nail dystrophy patients, shortening time-to-treatment initiation.
- WHO Chronic Disease Integration:Inclusion of lymphatic conditions within global noncommunicable disease programs elevates physician awareness in lower-resource settings and expands addressable screening populations.
Market Restraints
- Itraconazole Supply Concentration:Active pharmaceutical ingredient production for systemic antifungals clusters in specific Asian manufacturing zones, exposing formulation sponsors to single-source disruption risk.
- Reimbursement Fragmentation:Payers in Germany and the United States apply divergent prior authorization criteria for off-label systemic therapies, complicating commercial scale-up.
- Diagnostic Delay:Primary care physicians frequently misattribute nail dystrophy to onychomycosis alone, delaying appropriate lymphatic workup and treatment initiation by months.
Strategic Opportunities
- EMA Conditional Marketing Authorization:Early approval pathways for rare diseases allow sponsors to generate revenue while completing confirmatory trials, compressing time-to-market for novel modalities.
- Combination Regimen Positioning:Integrating vitamin E supplementation with systemic antifungals creates differentiation in markets where monotherapy saturation limits pricing power.
- Telemedicine Triage:Remote dermatology platforms in the United States are capturing nail dystrophy cases earlier in the diagnostic journey, creating direct-to-specialist channels that bypass primary care bottlenecks.
Industry Challenges
- Lymphatic Specialist Shortage:Fellowship-trained lymphedema physicians remain concentrated in academic medical centers, constraining patient access outside major metropolitan clusters.
- Cross-Disciplinary Care Coordination:Effective management requires pulmonology, dermatology, and lymphatic surgery alignment, yet electronic health record interoperability gaps fragment treatment continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yellow Nail Syndrome Treatment Market |
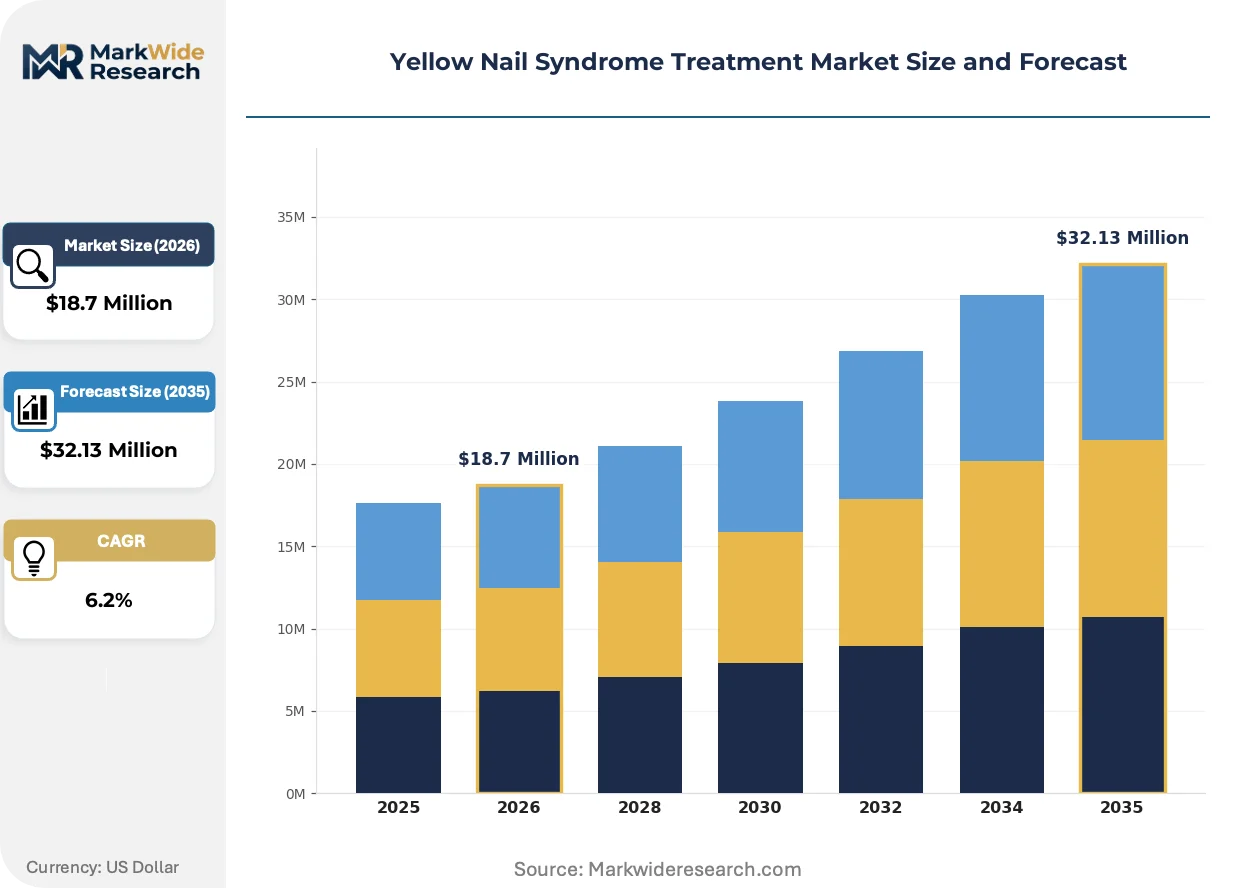
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $32.13 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Treatments, Systemic Medications, Nutritional Supplements, Antifungal Agents Delivery Mode: Oral, Topical, Injectable, Intravenous Patient Type: Adults, Pediatric, Geriatric, Immunocompromised Healthcare Setting: Outpatient Clinics, Hospitals, Home Healthcare, Specialty Centers |
| Companies Covered | Novartis, Sanofi, Pfizer, Sumitomo Corporation, Johnson & Johnson, AstraZeneca, Cipla, Abbott, GlaxoSmithKline, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yellow Nail Syndrome Treatment Market Trends and Innovations
Therapeutic development in Yellow Nail Syndrome is pivoting toward mechanism-based interventions that address underlying lymphatic pathology rather than symptomatic nail management alone, reshaping clinical trial endpoints and regulatory filing strategies.
Targeted lymphatic vessel growth factors are displacing empirical antifungal monotherapy in investigator-sponsored trials, with academic medical centers in Germany adopting these candidates for refractory lymphedema cases. Early adopters include university-affiliated dermatology departments seeking alternatives to prolonged itraconazole exposure. This modality is displacing cosmetic-focused protocols by demonstrating functional limb volume reduction alongside nail plate improvement.
EMA's rare disease framework now mandates pediatric investigation plans for conditions with childhood presentation, compelling sponsors to develop age-appropriate formulations earlier in development cycles. This requirement is extending clinical program timelines but expanding addressable populations. Juvenile-onset lymphatic disorders in European markets face heightened scrutiny for long-term safety surveillance.
Integrated care contracts between dermatology clinics and lymphedema therapy centers are restructuring referral economics in the United States, bundling diagnostic workup with ongoing compression therapy management. These arrangements displace fee-for-service billing for isolated nail procedures. The model is most visible in Medicare Advantage networks where capitated payments reward outcome efficiency over procedural volume.
Yellow Nail Syndrome Treatment Market Segmentation
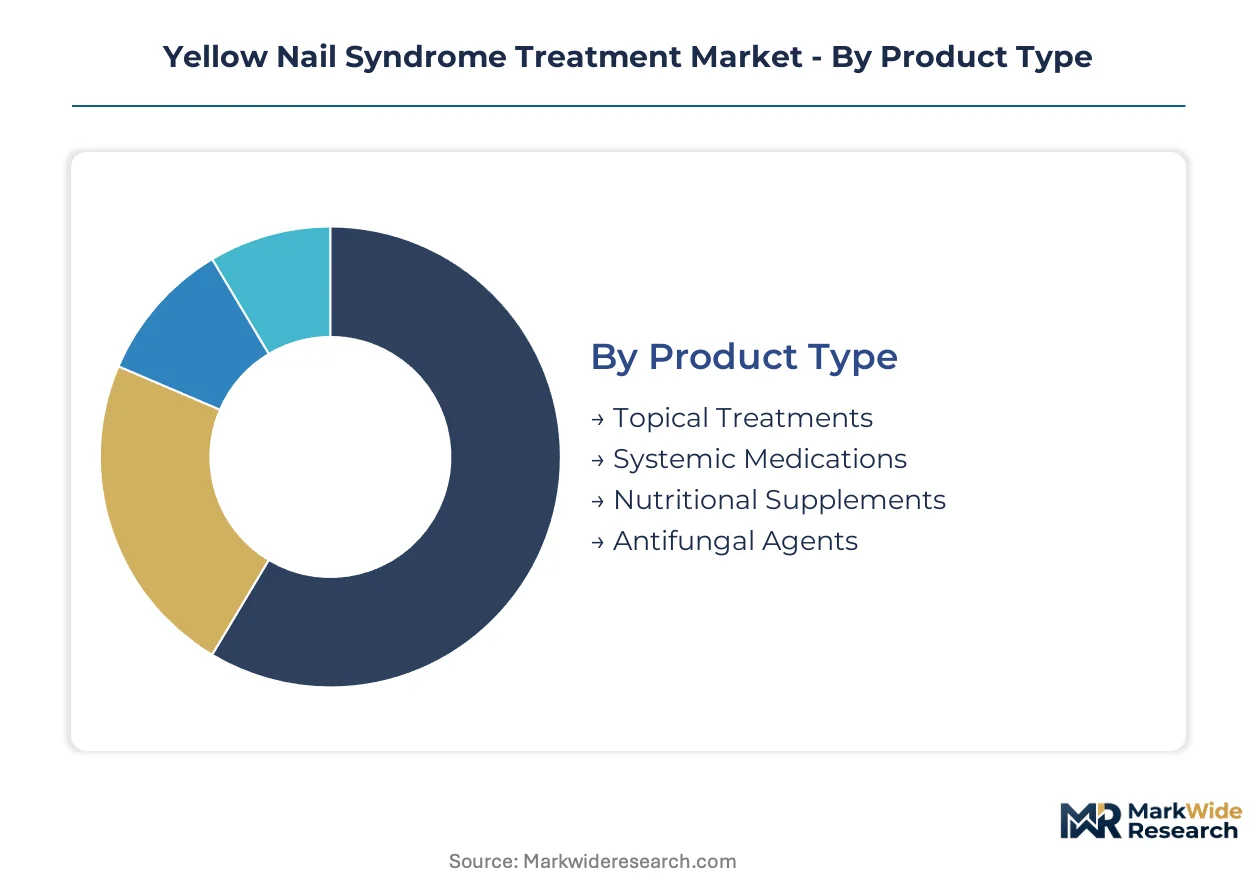
Yellow Nail Syndrome treatment segments reflect divergent reimbursement economics and care coordination requirements across dermatology, pulmonology, and lymphatic specialties. Manufacturers must align portfolio investments with the delivery infrastructure and patient access patterns dominating each segment.
Product Type:
Geographic concentration varies sharply across product categories, with systemic medications and antifungal agents anchored in United States and German reimbursement frameworks while nutritional supplements distribute through broader retail pharmacy networks.
- Systemic Medications:Oral formulations including itraconazole and targeted immunomodulators require specialist oversight and extended monitoring protocols. Demand clusters in academic medical centers across the United States and Germany where lymphedema specialists coordinate with dermatology departments.
- Antifungal Agents:Empirical therapy with azole-class compounds addresses both nail dystrophy and suspected underlying fungal colonization. United States outpatient clinics drive volume given direct-to-specialist referral patterns that bypass primary care delays.
- Topical Treatments:Lacquer-based and solution formulations target cosmetic nail improvement with limited functional impact.
- Nutritional Supplements:Vitamin E and antioxidant protocols distribute through retail channels with minimal regulatory oversight.
Systemic medications hold the largest share; momentum sits with antifungal agents as diagnostic protocols improve.
Delivery Mode:
Cost tier differentiation separates hospital-administered intravenous options from self-administered oral regimens, with reimbursement bandwidth determining patient access across Medicare Advantage and statutory health insurance systems.
- Oral:Capsule and tablet formulations dominate patient volumes due to home administration convenience and established bioavailability profiles. German dermatology networks prefer oral itraconazole for its lymphatic penetration characteristics.
- Intravenous:Hospital-based infusion protocols serve refractory cases with severe pleural effusions or extensive lymphedema. United States academic centers utilize intravenous options when oral bioavailability is compromised.
- Topical:Lacquer applications require prolonged adherence with limited systemic absorption.
- Injectable:Subcutaneous lymphatic growth factor candidates remain investigational with restricted availability.
Oral delivery holds the largest share; momentum sits with intravenous options as hospital-based lymphedema programs expand.
Patient Type:
Volume concentration tilts toward adult populations while regulatory mandates in European markets compel pediatric investigation plans that extend development timelines.
- Adults:Middle-aged patients with established triad presentations—yellow nails, lymphedema, pleural effusions—constitute the core addressable population. United States specialty centers report diagnostic delays averaging months as primary care misattributes nail changes to onychomycosis.
- Geriatric:Age-related lymphatic insufficiency compounds syndrome severity with comorbid cardiovascular conditions. German statutory insurance covers extended compression therapy for this cohort.
- Pediatric:Juvenile-onset cases trigger EMA pediatric investigation requirements.
- Immunocompromised:Transplant recipients and oncology patients experience accelerated disease progression.
Adults hold the largest share; momentum sits with geriatric segments as population aging intensifies across Western markets.
Healthcare Setting:
Supply concentration favors outpatient dermatology clinics in the United States while German statutory frameworks reinforce integrated care contracts between specialty centers and lymphedema therapy providers.
- Outpatient Clinics:Dermatology-focused facilities in the United States capture initial presentations through telemedicine triage and direct-to-specialist channels. Medicare Advantage capitation models reward these settings for coordinated diagnostic workup.
- Specialty Centers:Integrated lymphedema and pulmonology units in German university hospitals manage complex triad cases requiring multidisciplinary coordination.
- Hospitals:Acute care facilities handle pleural effusion drainage and refractory infections.
- Home Healthcare:Compression therapy and oral medication administration shift to residential settings post-stabilization.
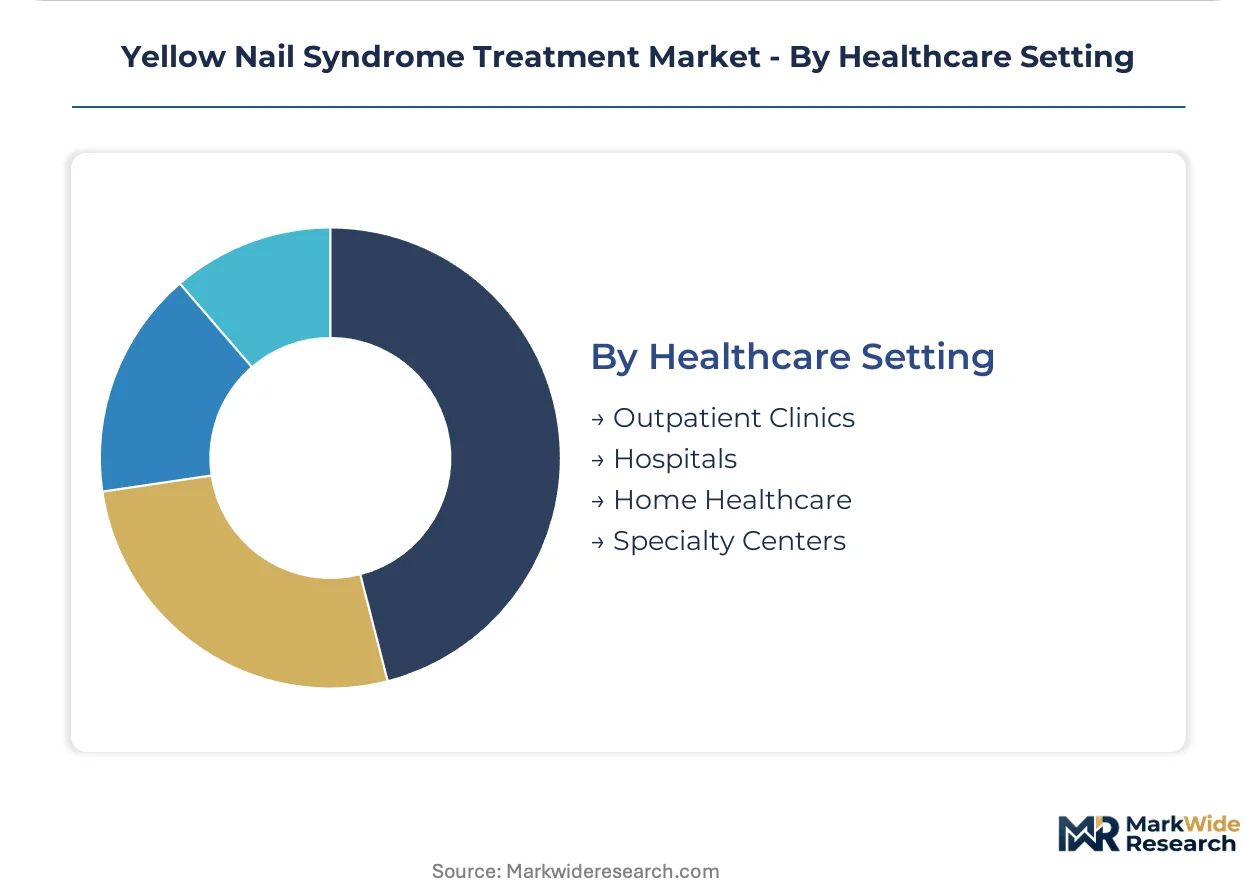
Outpatient clinics hold the largest share; momentum sits with specialty centers as integrated care models gain reimbursement traction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for active pharmaceutical ingredients concentrates supply risk in Asian manufacturing zones while finished formulation demand clusters in Western specialty care networks. The United States and Germany anchor consumption volumes through dermatology clinic expansion and integrated lymphedema programs. Reimbursement fragmentation across statutory and private payer systems creates divergent market access timelines.
United States
Telemedicine triage platforms and Medicare Advantage capitation models accelerate diagnostic capture for nail dystrophy patients. FDA orphan drug incentives including tax credits and seven-year exclusivity attract sponsor investment toward rare lymphatic indications. Academic medical centers in Boston and New York manage complex triad cases through coordinated pulmonology-dermatology units.
Germany
Statutory health insurance coverage for extended compression therapy and specialist lymphedema management drives treatment persistence. EMA conditional marketing authorization pathways allow revenue generation during confirmatory trial completion. University hospitals in Munich and Hamburg anchor integrated care contracts between dermatology clinics and lymphatic therapy centers.
United Kingdom
NHS England rare disease frameworks elevate diagnostic awareness for lymphatic disorders presenting with nail changes. MHRA alignment with EMA accelerated approval pathways streamlines sponsor market entry sequencing. London teaching hospitals concentrate fellowship-trained lymphedema specialists managing refractory pleural effusion cases.
Japan
PMDA Sakigake designation system fast-tracks innovative therapies for conditions with substantial unmet medical need. Aging demographics intensify demand for geriatric lymphatic insufficiency management. Tokyo and Osaka metropolitan areas host the majority of certified lymphedema therapists and specialized dermatology referral networks.
India
CDSCO regulatory harmonization with ICH guidelines facilitates multinational clinical trial participation for rare disease indications. Domestic manufacturing of generic itraconazole formulations reduces import dependence for systemic antifungal supply. Mumbai and Hyderabad clusters concentrate active pharmaceutical ingredient production and dermatology specialty hospital networks.
Yellow Nail Syndrome Treatment Market Competitive Landscape
Listed leaders compete with private specialists across orphan disease portfolios, with publicly traded pharmaceutical conglomerates leveraging respiratory and immunology infrastructure against focused biotechnology developers. Market structure tilts toward consolidated sponsor concentration given high regulatory barriers and extended development timelines for rare indications. Three archetypes dominate: diversified conglomerates with lymphatic therapy adjacencies, infectious disease specialists with azole-class expertise, and emerging biotechnology developers targeting vascular growth factors. Competitive dynamics center on portfolio diversification into rare disease designations and strategic partnerships with academic medical centers for investigator-sponsored trials.
Within the diversified pharmaceutical tier, Novartis and Pfizer exemplify archetypes leveraging existing therapeutic infrastructure. Novartis occupies a position at the intersection of immunology and lymphatic disease management, while Pfizer anchors systemic therapy development through established infectious disease capabilities. Sanofi sits within the integrated care delivery archetype, with dermatology network investments streamlining patient access pathways. These three listed entities represent contrasting strategic postures toward rare disease market development.
| Leading Market Players |
|---|
| Novartis |
| Sanofi |
| Pfizer |
| Sumitomo Corporation |
| Johnson & Johnson |
| AstraZeneca |
| Cipla |
| Abbott |
| GlaxoSmithKline |
| Others |
Pricing and Supply Chain Analysis
Specialty-grade itraconazole displacing empirical azole monotherapy in refractory cases simultaneously concentrates API sourcing in Indian and Chinese manufacturing zones and compresses margins for formulation sponsors facing orphan drug cost recovery requirements. This substitution dynamic tightens the link between supply geography and pricing power across systemic antifungal portfolios.
Pricing Analysis
Academic medical center procurement teams anchor contract-based long-term offtake for systemic antifungals, with price differentiation resting on FDA orphan designation tier and bundled lymphedema therapy service levels. Cost compression in standard oral formulations is intensifying because Indian generic manufacturers are expanding itraconazole API capacity. Medicare Advantage plans demonstrate highest price sensitivity due to capitated reimbursement structures, while German statutory insurance funds show lowest sensitivity given mandated rare disease coverage.
Supply Chain Analysis
Single-source API concentration in Hyderabad and Shanghai manufacturing corridors exposes formulation sponsors to regulatory inspection disruption risk. Active pharmaceutical ingredient production draws from Chinese chemical intermediate feedstocks, Indian fermentation capacity, and German quality certification protocols. Distribution runs through specialty pharmacy networks in the United States and hospital central procurement in Germany, with cold-chain requirements for intravenous formulations adding logistics complexity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Yellow Nail Syndrome treatment demand is recovering from pandemic-era diagnostic deferrals as dermatology clinic volumes normalize and telemedicine triage captures delayed presentations. This cyclical rebound creates windows for portfolio repositioning across stakeholder archetypes.
For Market Incumbents: Fortify lymphatic specialist network coverage through exclusive compression therapy partnerships that lock referral economics before biosimilar antifungal entry. Deepen backward integration into vitamin E sourcing to secure margin on combination regimens as monotherapy pricing softens. Prioritize FDA breakthrough therapy designation for vascular growth factor candidates to extend exclusivity runway.
For New Entrants and Emerging Players: Pediatric formulation gaps where incumbents under-serve present the most penetrable entry point given EMA pediatric investigation mandates extending development timelines for established sponsors. Target German university hospital integrated care contracts where statutory reimbursement guarantees revenue visibility. Lead with telemedicine-enabled diagnostic partnerships that bypass primary care bottlenecks and capture patients earlier in disease progression.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed dermatology platform rollups seeking orphan disease indications to diversify beyond cosmetic procedures. Long-term viability hinges on regulatory exclusivity durability rather than volume expansion given addressable patient constraints. Monitor FDA orphan drug designation grant rates as the inflection signal for R&D capital allocation sentiment.
| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pursuit | FDA seven-year exclusivity and tax credits de-risk development economics for rare lymphatic indications. |
| Pediatric Investigation Plan Submission | EMA mandates for juvenile-onset cases expand addressable populations while extending program timelines. |
| Integrated Care Contracting | Medicare Advantage capitation models reward bundled diagnostic and compression therapy management. |
| Telemedicine Triage Platform Deployment | Remote dermatology channels capture nail dystrophy cases before primary care misdiagnosis delays treatment. |
| API Manufacturing Partnership | Indian and Chinese fermentation capacity agreements secure itraconazole supply continuity for oral formulations. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with dermatology clinic directors, lymphedema therapy center administrators, hospital formulary committees, orphan drug regulatory affairs leads, and specialty pharmacy procurement managers. Secondary validation drew from FDA orphan drug designation databases, EMA rare disease framework documentation, ClinicalTrials.gov investigator-sponsored trial records, and German statutory health insurance reimbursement catalogs. Bottom-up patient volume estimates and top-down pharmaceutical revenue triangulation anchored segmentation-specific forecasts.
Across the analysis window, projections integrated treatment line positioning, delivery mode preference shifts, patient age cohort dynamics, and regional regulatory cluster differentiation. CAGRs were derived from log-linear trend fitting to historical adoption curves with adjustment for orphan drug launch pattern anomalies. Forecast inputs included dermatology clinic expansion rates, lymphedema specialist fellowship graduation volumes, and telemedicine platform penetration in nail dystrophy triage.
Forecasts assume regulatory continuity in FDA orphan incentive structures and EMA conditional marketing authorization pathways; material policy shifts would require re-modeling. Specific risks include itraconazole API supply disruption, reimbursement clawback provisions in Medicare Advantage, and diagnostic criteria revisions affecting addressable prevalence. Practitioners should keep alternative scenarios live as lymphatic growth factor clinical readouts and biosimilar entry timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Rosai-Dorfman Disease (RDD) Therapeutics Market
Rare Diseases
Asia Pacific Rett Syndrome Market
Rare Diseases
Batten Disease Market
Rare Diseases
Hairy Cell Leukemia Market
Rare Diseases
Hemophagocytic Lymphohistiocytosis Market
Rare Diseases
Cowden Syndrome Market
Rare Diseases
Atypical Hemolytic Uremic Syndrome (Ahus) Treatment Market
Rare Diseases
Andersen-Tawil Syndrome Market
Rare Diseases
Niemann Pick Disease Market
Rare Diseases
Skeletal Dysplasia Market
Rare Diseases
Global Guillain-Barre Syndrome Market
Rare Diseases
Kounis Syndrome Market
Rare Diseases
Rett Syndrome Market
Rare Diseases
Phelan-Mcdermid Syndrome Market
Rare Diseases
Orphan Diseases Market
Rare Diseases
Global Hemoglobinopathies Market