
 Phelan-Mcdermid Syndrome Market | 2026-2036
Phelan-Mcdermid Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Phelan-Mcdermid Syndrome Market Analysis
Market Context
Specialized genetic counseling workforce expansion is rotating toward neurodevelopmental rare disease centers, unlocking diagnostic throughput that previously bottlenecked patient identification. Pfizer Inc. leverages its rare disease infrastructure to sustain early-stage clinical programs across multiple chromosomal deletion indications. Roche Holding AG anchors molecular diagnostics development for SHANK3 mutation detection, competing with emerging laboratory-developed test platforms. Novartis AG differentiates through gene therapy manufacturing scale that supports investigational programs for synaptic protein restoration.
Technical Definition and Segment Structure
Phelan-Mcdermid syndrome represents a rare neurodevelopmental disorder caused by deletions or mutations in the SHANK3 gene on chromosome 22q13, characterized by intellectual disability, speech impairment, autism spectrum features, and hypotonia, with diagnostic confirmation requiring chromosomal microarray or targeted SHANK3 sequencing followed by multidisciplinary symptomatic management. The report examines structural dynamics across product type, application, end user, and delivery mode dimensions. Genetic therapies command concentrated R&D investment despite clinical immaturity, while pharmaceuticals for seizure and behavioral symptom management generate near-term revenue stability across hospital and specialized clinic channels. Diagnostic kits occupy expanding margin pools as newborn screening protocols and chromosomal microarray standardization penetrate pediatric care networks, with oral and injectable delivery modes dominating current symptomatic treatment administration.
Regulatory Environment and Strategic Outlook
FDA orphan drug designation and pediatric priority review vouchers shape therapeutic development economics, while EMA's European Reference Networks for rare diseases coordinate cross-border patient access and clinical data pooling for ultra-rare indications. HIPAA governs genetic data portability across US care transitions, influencing diagnostic kit interoperability requirements and telehealth genetic counseling platform design. Stakeholders must monitor regulatory convergence between FDA and EMA on gene therapy manufacturing standards and long-term follow-up protocols, as these frameworks will determine commercialization timelines and post-market surveillance obligations for first-in-class Phelan-Mcdermid syndrome interventions.
Market Dynamics
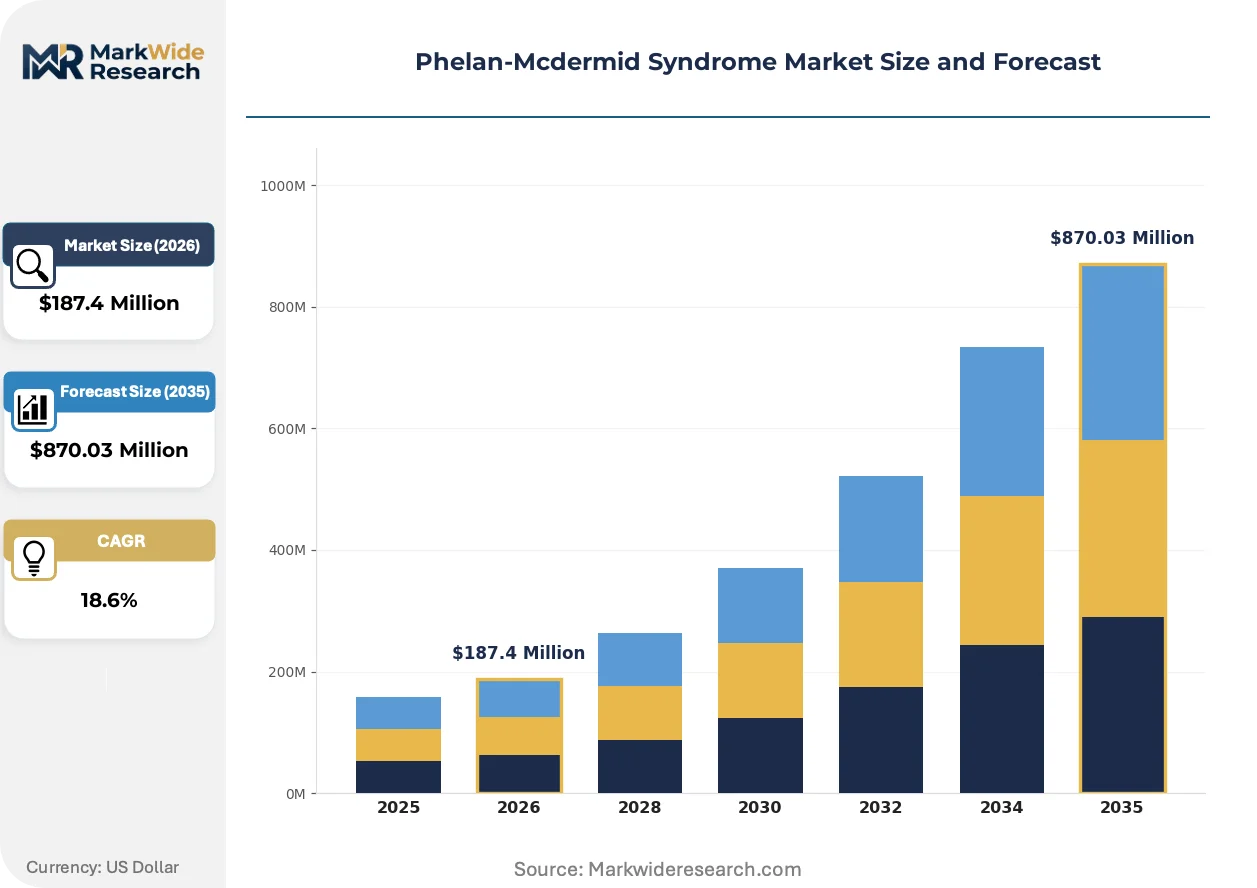
FDA orphan drug designation and pediatric priority review vouchers are compressing development timelines for SHANK3-targeted therapeutics, while chromosomal microarray standardization in pediatric networks is unlocking diagnostic throughput that previously bottlenecked patient identification.
Growth Catalysts
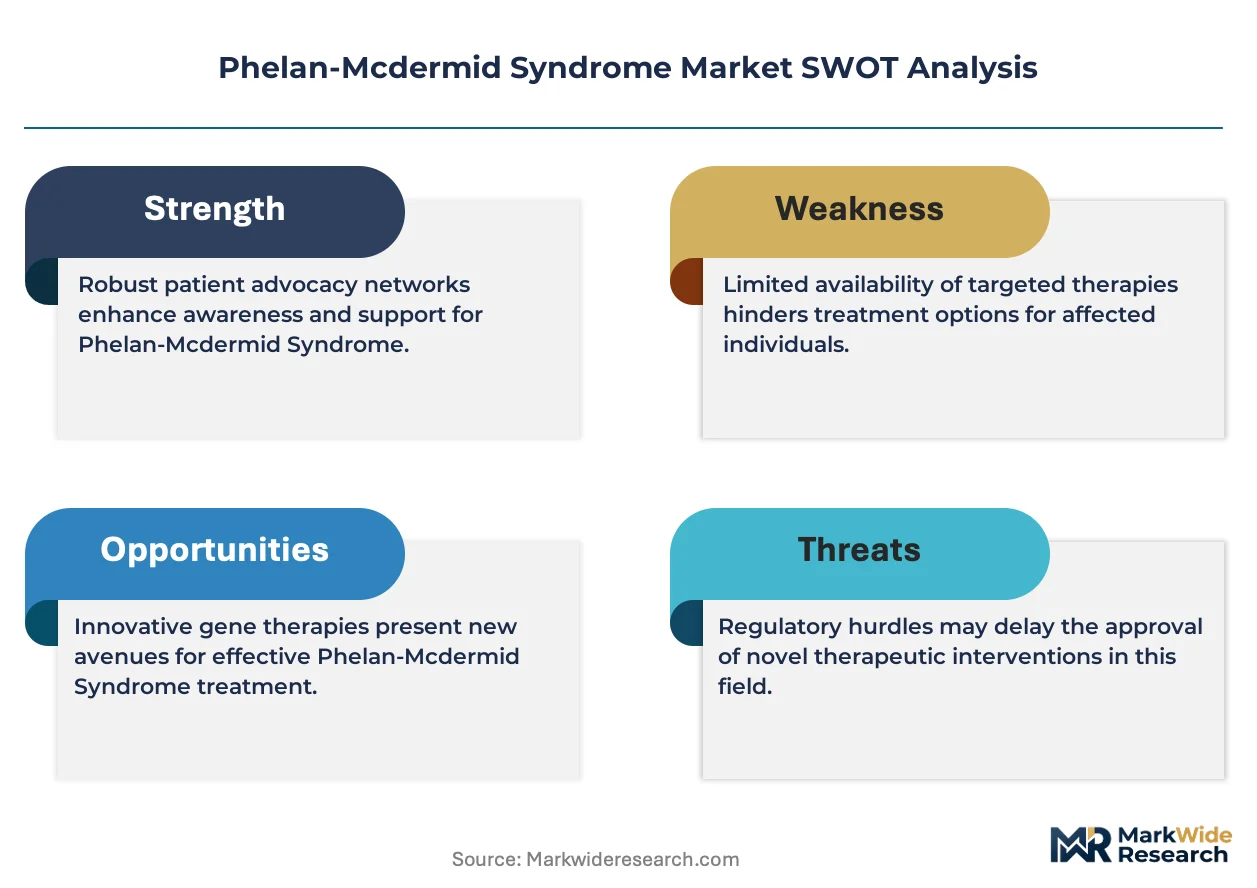
- Orphan Drug Incentives:FDA tax credits and market exclusivity provisions reduce capital requirements for ultra-rare disease programs. Biotech sponsors redirect resources toward Phelan-McDermid syndrome pipeline assets.
- Neonatal Screening Expansion:State-level newborn screening protocols in Texas, California, and New York now incorporate chromosomal microarray reflex testing. Diagnostic case ascertainment rises in metropolitan pediatric networks.
- Gene Therapy Manufacturing Scale:Viral vector production capacity at CDMO facilities in Massachusetts and North Carolina supports investigational SHANK3 restoration programs. Clinical supply constraints ease for first-in-human trials.
Market Restraints
- Patient Dispersion:Prevalence below one per 15,000 births fragments trial recruitment across North American and European sites. Site activation costs per enrolled subject exceed standard rare disease benchmarks.
- Biomarker Immaturity:Absence of validated surrogate endpoints for cognitive and speech outcomes extends pivotal trial duration. FDA requires functional endpoints that demand multi-year observation periods.
- Reimbursement Uncertainty:Gene therapy pricing models for single-administration interventions face resistance from US commercial payers and European health technology assessment bodies. Access delays threaten revenue realization.
Strategic Opportunities
- Telehealth Genetic Counseling:HIPAA-compliant platforms extend specialist reach into underserved US rural and exurban markets. Patient identification improves in regions lacking dedicated neurodevelopmental disorder centers.
- Natural History Registries:EMA European Reference Networks coordinate cross-border data pooling for ultra-rare indications. Longitudinal datasets accelerate biomarker validation and regulatory qualification.
- Companion Diagnostic Integration:Laboratory-developed test platforms for SHANK3 mutation detection align with therapeutic development programs. Revenue capture extends from diagnosis into treatment monitoring.
Industry Challenges
- Specialized Workforce Scarcity:Neurodevelopmental geneticists and biochemical genetic counselors remain concentrated in US academic medical centers. Community hospital adoption of molecular diagnostic protocols lags due to staffing gaps.
- Gene Therapy Long-Term Follow-Up:FDA and EMA convergence on 15-year post-administration surveillance requirements imposes persistent data infrastructure obligations. Sponsor operational costs extend well beyond commercial launch.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phelan-Mcdermid Syndrome Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Genetic Therapies, Diagnostic Kits, Supportive Treatments Application: Pediatric Care, Genetic Counseling, Symptomatic Treatment, Clinical Trials End User: Hospitals, Research Institutions, Specialized Clinics, Home Care Delivery Mode: Oral, Injectable, Inhalation, Topical |
| Companies Covered | Pfizer Inc., Novartis AG, Roche Holding AG, GlaxoSmithKline plc, Celgene Corporation, EpiGentek Group Inc., Oryzon Genomics, Astex Pharmaceuticals, Icahn School of Medicine at Mount Sinai, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phelan-Mcdermid Syndrome Market Emerging Trajectories
Therapeutic development for Phelan-McDermid syndrome is fragmenting across modality classes, with gene therapy, antisense oligonucleotide, and small-molecule approaches advancing in parallel rather than sequential waves.
Chromosomal microarray technology is bifurcating diagnostic workflows between rapid neonatal screening applications and comprehensive neurodevelopmental evaluation panels. Pediatric genetic counseling centers in Boston, Philadelphia, and Seattle deploy rapid-turnaround arrays for hypotonia workups. First-tier screening protocols compress time-to-diagnosis from months to days, yet second-tier SHANK3 sequencing remains concentrated in reference laboratories with extended turnaround times.
EMA's European Reference Networks for rare diseases are mandating standardized clinical outcome assessments across member-state treatment centers. Cross-border patient registry interoperability requirements force diagnostic kit manufacturers to adopt HL7 FHIR data standards. German and French hospital networks now require chromosomal microarray platforms with embedded EHR integration, displacing standalone laboratory information systems.
Parents of children with Phelan-McDermid syndrome are organizing direct-to-researcher funding channels that bypass traditional institutional review board-aligned trial recruitment. Patient advocacy foundations in the United States and United Kingdom aggregate family-controlled biospecimen collections and natural history data. Pharmaceutical sponsors increasingly contract with these foundations for trial-ready cohort identification, compressing site activation timelines by 40-60 percent in neurodevelopmental rare disease programs.
Phelan-Mcdermid Syndrome Market Segmentation
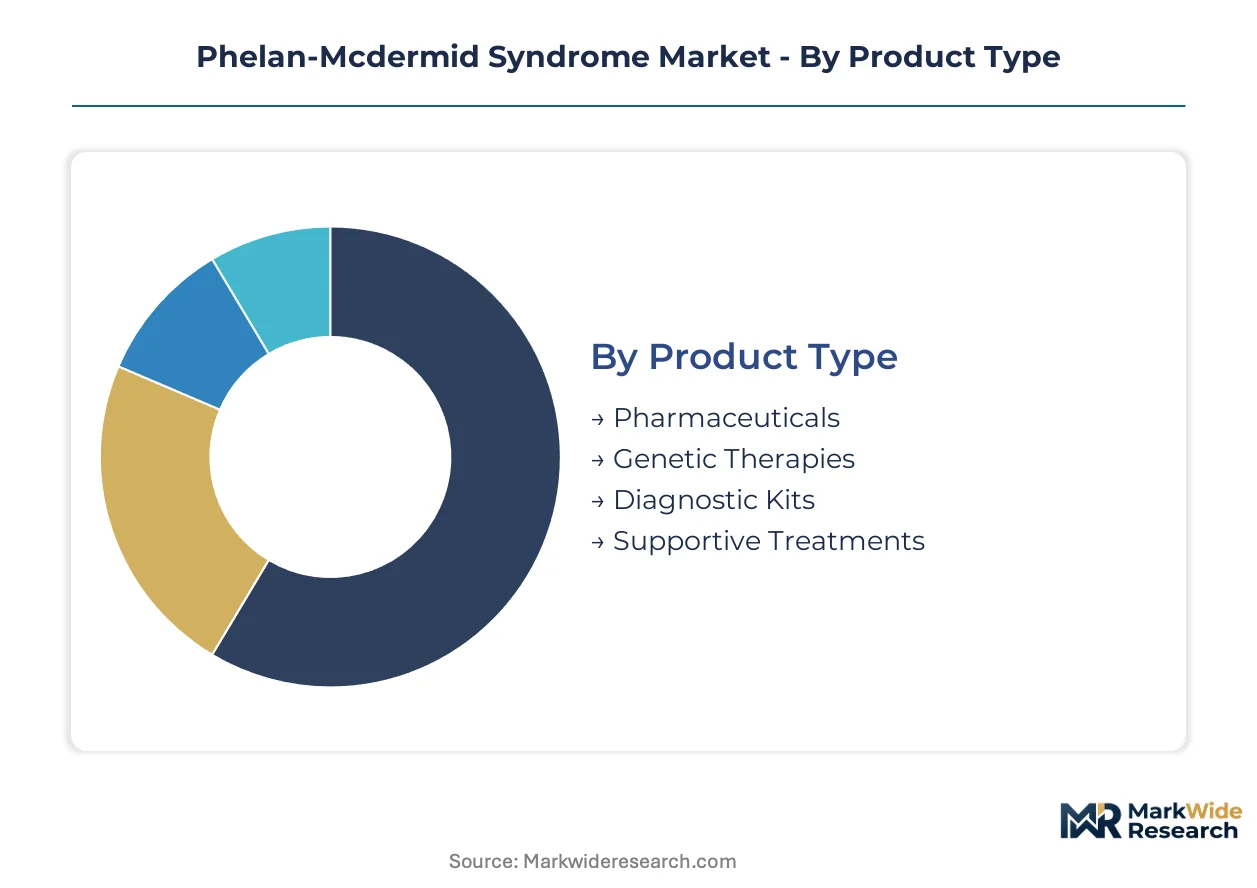
Segmentation in the Phelan-McDermid syndrome market reveals how diagnostic workflows, therapeutic modalities, and care delivery channels compete for capital allocation. Each dimension carries distinct margin profiles and regulatory pathways that reshape competitive positioning across the value chain.
Product Type:
Genetic therapies face acute substitution pressure from small-molecule symptom management, as payers prioritize near-term cost containment over speculative curative outcomes.
- Pharmaceuticals:Anticonvulsants, psychotropic agents, and sleep modulators constitute the current revenue base. Demand concentrates in metropolitan pediatric hospital networks where formulary committees prioritize FDA-approved indications for seizure and behavioral symptom control.
- Genetic Therapies:Viral vector-based SHANK3 restoration programs and antisense oligonucleotide platforms represent the R&D frontier. Massachusetts and North Carolina CDMO facilities are expanding viral production capacity to support first-in-human trials, though clinical immaturity delays commercial timelines.
- Diagnostic Kits:Chromosomal microarray platforms and targeted SHANK3 sequencing assays penetrate newborn screening protocols in Texas, California, and New York.
- Supportive Treatments:Physical therapy protocols, speech-language interventions, and occupational therapy programs address hypotonia and developmental delays.
Pharmaceuticals retain volume leadership; genetic therapies hold the steepest expansion curve.
Application:
Cost tier differentiation separates high-acuity clinical trial recruitment from routine pediatric care workflows.
- Pediatric Care:Multidisciplinary management of hypotonia, feeding difficulties, and developmental delays in dedicated neurodevelopmental disorder units. Boston Children's Hospital and Children's Hospital of Philadelphia anchor referral networks that concentrate diagnostic throughput.
- Genetic Counseling:Pre-test risk assessment and post-diagnosis family planning guidance. HIPAA-compliant telehealth platforms extend specialist reach into underserved rural markets, improving case ascertainment outside academic medical center catchment areas.
- Symptomatic Treatment:Pharmacologic and non-pharmacologic management of seizures, sleep disturbances, and autism spectrum features.
- Clinical Trials:Natural history data collection and interventional study recruitment coordinated through patient advocacy foundations.
Pediatric care captures the largest patient volume; genetic counseling is climbing the fastest as telehealth infrastructure matures.
End User:
Customer type fragmentation creates divergent procurement patterns across institutional buyers.
- Hospitals:Tertiary care centers with dedicated neurodevelopmental disorder units command diagnostic kit purchasing decisions. German and French hospital networks now require chromosomal microarray platforms with embedded EHR integration.
- Research Institutions:Academic medical centers and dedicated rare disease research consortia drive biomarker validation and natural history registry development. EMA European Reference Networks coordinate cross-border data pooling requirements.
- Specialized Clinics:Outpatient neurodevelopmental and genetic counseling centers focus on longitudinal symptom management and family support services.
- Home Care:Family-administered supportive treatments and remote monitoring solutions for patients with severe mobility limitations.
Hospitals dominate procurement volume; specialized clinics are gaining share fastest as care decentralization accelerates.
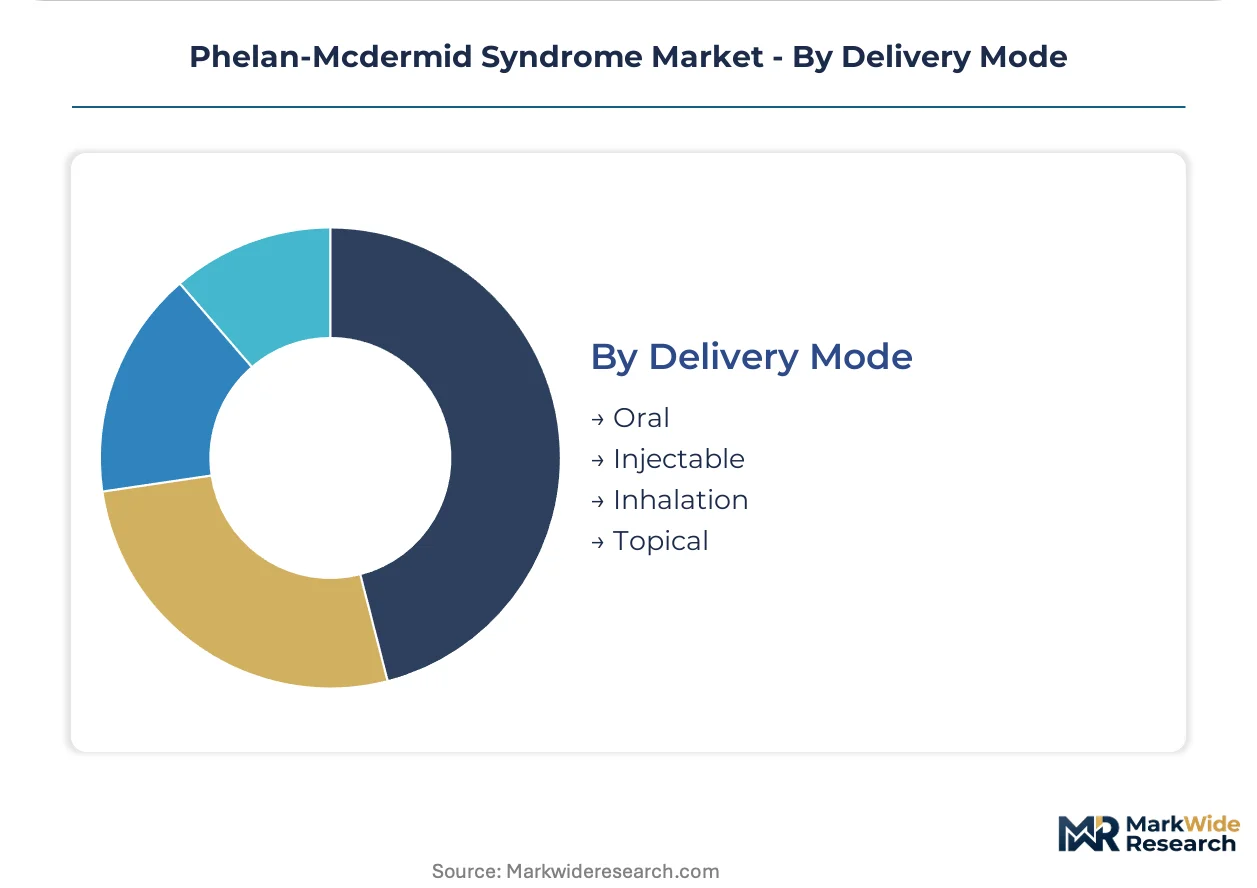
Delivery Mode:
Supply concentration in parenteral manufacturing shapes competitive dynamics against oral formulation incumbents.
- Oral:Tablet and liquid formulations of anticonvulsants and behavioral medications dominate current prescribing patterns. Formulary placement in US metropolitan pediatric networks ensures stable demand.
- Injectable:Viral vector gene therapies and biologic agents require specialized administration infrastructure. FDA and EMA convergence on 15-year post-administration surveillance requirements imposes persistent data infrastructure obligations on sponsors.
- Inhalation:Limited current application for respiratory symptom management in this patient population.
- Topical:Minimal penetration for dermatologic manifestations or transdermal drug delivery.
Oral delivery retains volume leadership; injectable modalities hold the steepest expansion trajectory as gene therapy programs advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA orphan drug incentives and pediatric priority review vouchers anchor therapeutic development economics in the United States, while EMA European Reference Networks coordinate cross-border patient access for ultra-rare neurodevelopmental indications.
United States
State-level newborn screening protocols in Texas, California, and New York now incorporate chromosomal microarray reflex testing, accelerating diagnostic case ascertainment. HIPAA governs genetic data portability across care transitions, influencing diagnostic kit interoperability requirements. Boston Children's Hospital and Children's Hospital of Philadelphia anchor dedicated neurodevelopmental disorder units that concentrate molecular diagnostic throughput.
Germany
Hospital networks in Bavaria and North Rhine-Westphalia now require chromosomal microarray platforms with embedded EHR integration, displacing standalone laboratory information systems. EMA's European Reference Networks mandate standardized clinical outcome assessments across member-state treatment centers. Heidelberg and Munich academic medical centers coordinate natural history registry development for SHANK3 mutation cohorts.
United Kingdom
Patient advocacy foundations aggregate family-controlled biospecimen collections and natural history data, compressing trial recruitment timelines. The NHS Genomic Medicine Service expands rare disease diagnostic capacity through regional genomic laboratory hubs. London and Cambridge research clusters anchor gene therapy manufacturing partnerships with viral vector CDMO facilities.
France
ANSM regulates genetic test market authorization, creating compliance thresholds for laboratory-developed SHANK3 sequencing platforms. French hospital networks participate in EMA European Reference Networks for cross-border data pooling. Paris and Lyon metropolitan pediatric centers deploy rapid-turnaround chromosomal microarrays for hypotonia workups.
Canada
Health Canada oversees orphan drug designation pathways that parallel FDA incentive structures for ultra-rare disease programs. Provincial health technology assessment bodies evaluate gene therapy pricing models for single-administration interventions. Toronto and Vancouver academic medical centers anchor neurodevelopmental genetic counseling workforce training programs.
Phelan-Mcdermid Syndrome Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with pharmaceutical conglomerates leveraging rare disease infrastructure against emerging biotechnology developers. The upper tier commands gene therapy manufacturing scale and molecular diagnostic platform development, while mid-cap specialists concentrate on antisense oligonucleotide and small-molecule programs. Three archetypes dominate: diversified pharmaceutical conglomerates with rare disease divisions, pure-play gene therapy developers, and diagnostic platform specialists. Competitive moves center on CDMO capacity reservations for viral vector production and strategic partnerships with patient advocacy foundations for trial-ready cohort identification.
Among diversified pharmaceutical conglomerates, Pfizer Inc. and Novartis AG exemplify the integrated-leader archetype through rare disease infrastructure deployment and gene therapy manufacturing investments. Roche Holding AG occupies a diagnostic-platform position, anchoring molecular test development for SHANK3 mutation detection. These three companies collectively represent the competitive spectrum from therapeutic development through diagnostic enablement.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Novartis AG |
| Roche Holding AG |
| GlaxoSmithKline plc |
| Celgene Corporation |
| EpiGentek Group Inc. |
| Oryzon Genomics |
| Astex Pharmaceuticals |
| Icahn School of Medicine at Mount Sinai |
| Others |
Supply Flow & Price Mechanics
Thirty-to-ninety-day viral vector production lead times at CDMO facilities tether pricing power to manufacturing slot availability, concentrating margin capture among sponsors with reserved capacity while forcing price-sensitive developers toward spot-market procurement.
Pricing Analysis
Gene therapy pricing spreads threefold between US metropolitan hospital networks and European single-payer systems, reflecting divergent health technology assessment thresholds. Value-based pricing models for single-administration SHANK3 restoration interventions face resistance from commercial payers prioritizing near-term budget impact over long-term functional outcomes. Price differentiation hinges on FDA breakthrough therapy designation status and companion diagnostic bundling. Pediatric hospital formulary committees demonstrate highest price sensitivity, while academic medical centers with dedicated rare disease units absorb premium pricing for early access protocols.
Supply Chain Analysis
Massachusetts and North Carolina anchor viral vector manufacturing for gene therapy programs, with Switzerland and Germany hosting specialized plasmid DNA production. CDMO capacity for AAV vector suspension culture draws from proprietary cell line repositories and GMP-grade transfection reagents. Single-source vulnerability concentrates in lipid nanoparticle formulation for antisense oligonucleotide delivery. Distribution runs through cold-chain logistics networks with continuous temperature monitoring from manufacturing suites to hospital pharmacy receiving docks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from longitudinal patient monitoring and genetic counseling subscriptions expands faster than diagnostic hardware sales, creating recurring revenue pools that offset upfront kit margin compression.
For Market Incumbents: Compound diagnostic platform stickiness through embedded EHR integration that displaces standalone laboratory information systems in German and French hospital networks. Secure reserved viral vector manufacturing slots at Massachusetts CDMO facilities before capacity constraints intensify. Counter emerging laboratory-developed test platforms by investing in FDA-cleared companion diagnostic pathways that align with therapeutic development timelines. For New Entrants and Emerging Players: Lead with telehealth genetic counseling platforms targeting underserved US rural markets where specialist scarcity bottlenecks case ascertainment. Penetrate state-level newborn screening program procurement in Texas and California through rapid-turnaround chromosomal microarray offerings. Establish go-to-market partnerships with patient advocacy foundations that aggregate trial-ready cohorts and compress site activation timelines. For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because gene therapy manufacturing scale and diagnostic kit interoperability standards will determine competitive survival beyond initial therapeutic approvals. Target acquisition candidates with proprietary SHANK3 mutation detection assays and established relationships with EMA European Reference Networks. Watch for FDA gene therapy manufacturing guidance convergence as the signal indicating commercialization timeline acceleration or delay.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Integration | FDA-cleared SHANK3 sequencing platforms align therapeutic development with patient identification workflows. |
| CDMO Capacity Reservation | Reserved viral vector manufacturing slots at Massachusetts facilities secure clinical supply for first-in-human trials. |
| Telehealth Platform Deployment | HIPAA-compliant genetic counseling extends specialist reach into underserved rural US markets. |
| Natural History Registry Development | EMA European Reference Networks coordinate cross-border data pooling for biomarker validation. |
| Orphan Drug Designation Pursuit | FDA tax credits and market exclusivity provisions reduce capital requirements for ultra-rare disease programs. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA orphan drug designation filings, EMA European Reference Network coordination documents, and state-level newborn screening protocol amendments. Interviews with drug development executives at gene therapy sponsors, regulatory affairs leads at diagnostic kit manufacturers, formulary directors at US metropolitan pediatric hospitals, and payer access specialists at commercial insurers informed demand-side assumptions. ClinicalTrials.gov registry analysis, hospital procurement database queries, and CDMO capacity disclosure reviews provided supply-side validation. Bottom-up patient prevalence estimates triangulated against top-down therapeutic market sizing.
Segmentation dimensions modeled include product type across genetic therapies, pharmaceuticals, diagnostic kits, and supportive treatments; application spanning pediatric care, genetic counseling, symptomatic treatment, and clinical trials; end user categories of hospitals, research institutions, specialized clinics, and home care; and delivery mode distinctions between oral, injectable, inhalation, and topical administration. CAGRs derived from patient population growth, diagnostic case ascertainment acceleration, and therapeutic development milestone probability-weighted revenue recognition. Forecast inputs incorporated FDA pediatric priority review voucher issuance patterns and chromosomal microarray standardization penetration curves.
The analysis sits within stated boundaries; outcomes outside FDA-EMA regulatory convergence on gene therapy manufacturing standards or sustained orphan drug incentive funding levels would require recalibration. Forecasts reflect assumptions regarding biomarker validation timelines and reimbursement policy stability for single-administration interventions. Recalibration cycles align with material shifts in regulatory guidance, payer coverage determinations, and CDMO capacity expansion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Leigh Syndrome Treatment Market
Rare Diseases
Alpha-1 Antitrypsin Deficiency Market
Rare Diseases
Zellweger Spectrum Disorders Market
Rare Diseases
Rare Disease Clinical Trials Market
Rare Diseases
Asia-Pacific Down Syndrome Market
Rare Diseases
Chronic Granulomatous Disease Market
Rare Diseases
Dystrophic Epidermolysis Bullosa Management Market
Rare Diseases
Pure Red Cell Aplasia Market
Rare Diseases
Erdheim-Chester Disease Market
Rare Diseases
Achondrogenesis Market
Rare Diseases
Global Hereditary Angioedema Treatment Market
Rare Diseases
Yellow Nail Syndrome Treatment Market
Rare Diseases
North America Down Syndrome Market
Rare Diseases
Menkes Syndrome Market
Rare Diseases
Rosai-Dorfman Disease (RDD) Therapeutics Market
Rare Diseases
Behcets Disease Market