
 Erdheim-Chester Disease Market | 2026-2036
Erdheim-Chester Disease Market Size, Share, and Industry Trends Forecast 2026-2036
Erdheim-Chester Disease Market Analysis
Aftermarket service revenue from patient monitoring and long-term toxicity management is narrowing as pharmaceutical margins compress toward front-line therapy pricing. Pfizer Inc. leverages its established oncology infrastructure to sustain distribution reach across academic medical centers. Novartis AG anchors its position through targeted therapy development programs in rare histiocytic disorders. Genentech Inc. differentiates via biomarker-driven patient stratification approaches that refine treatment eligibility.
Erdheim-Chester Disease is a rare non-Langerhans cell histiocytosis characterized by xanthogranulomatous tissue infiltration driven by BRAF V600E mutations in most cases, with primary clinical purpose being the suppression of systemic organ involvement and skeletal pain progression. The monoclonal antibodies segment occupies the dominant margin pool due to premium positioning and infusion-based administration protocols, while targeted therapies represent the fastest-expanding category as BRAF and MEK inhibitor combinations reshape first-line protocols. Immunotherapies remain emergent, with checkpoint inhibitor trials currently concentrated in refractory patient populations at major referral institutions.
The FDA orphan drug program shapes clinical trial economics by granting tax credits and market exclusivity incentives that lower development risk for ultra-rare indications. EMA's pediatric investigation plan requirements and the EU's ATMP classification framework govern how advanced therapy medicinal products access European markets. Stakeholders must monitor how payer evidence thresholds evolve for histiocytosis therapies as health technology assessment bodies tighten their scrutiny of single-arm trial data.
Market Dynamics
The BRAF V600E mutation testing infrastructure is concentrating diagnostic workflows into academic medical centers, creating gatekeeper effects that determine patient access to targeted therapy protocols and reshaping referral patterns across the treatment landscape.
Growth Catalysts
- FDA Orphan Drug Tax Credits:The incentive framework reduces effective development costs for ultra-rare histiocytosis indications, attracting biopharma investment into previously uneconomic therapeutic areas.
- Next-Generation Sequencing Panels:Multiplex genomic testing in hematology-oncology clinics is shortening time-to-diagnosis from months to weeks, expanding the addressable patient pool eligible for mutation-directed therapy.
- Academic Medical Center Clustering:The United States hosts the highest density of specialized histiocytosis treatment centers, creating concentrated expertise that accelerates clinical trial enrollment and protocol refinement.
Market Restraints
- Plasma-Derived Biologic Input Costs:Monoclonal antibody manufacturing depends on fractionation capacity concentrated in limited geographic regions, exposing margins to plasma collection volatility and processing bottlenecks.
- Single-Arm Trial Evidence Standards:Health technology assessment bodies in Germany and England are tightening scrutiny of non-randomized efficacy data, complicating reimbursement negotiations for novel histiocytosis therapies.
- Checkpoint Inhibitor Substitution Threat:Off-label PD-1/PD-L1 blockade in refractory cases competes with approved targeted therapies, fragmenting treatment protocols and pressuring protocol adherence.
Strategic Opportunities
- Japan's Sakigake Designation Pathway:The PMDA's priority review framework offers accelerated access for rare disease innovations, creating a regulatory tailwind for first-in-class histiocytosis entrants.
- MEK-BRAF Combination Protocols:Convergent kinase inhibitor regimens are opening first-line positioning opportunities that bypass resistance mechanisms observed in monotherapy settings.
- Telemedicine-Enabled Referral Networks:Virtual tumor board platforms are eroding geographic barriers to specialized care, enabling community oncology practices to channel appropriate cases to histiocytosis centers.
Industry Challenges
- Histiocytosis Pathology Subspecialist Scarcity:The diagnostic workforce capable of distinguishing ECD from Langerhans cell and non-histiocytic mimics remains concentrated in fewer than fifty North American institutions.
- Long-Term Toxicity Monitoring Infrastructure:Cardiac and endocrine surveillance protocols for BRAF inhibitor therapy require dedicated nursing capacity that stretches thin at high-volume referral centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Erdheim-Chester Disease Market |
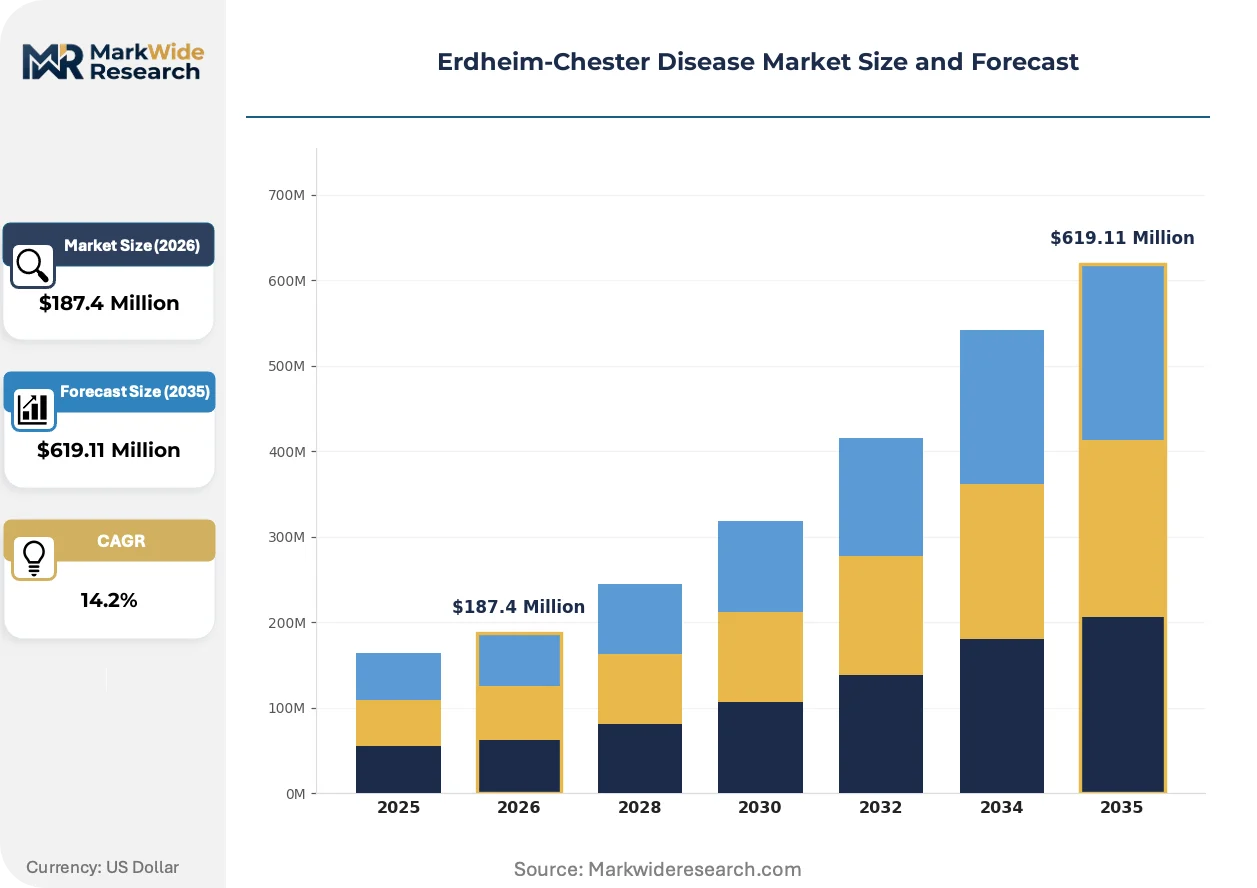
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Chemotherapy Agents, Targeted Therapies, Immunotherapies Delivery Mode: Intravenous, Subcutaneous, Oral, Topical End User: Hospitals, Clinics, Research Institutes, Homecare Settings Formulation: Liquid, Powder, Injectable, Tablet |
| Companies Covered | Pfizer Inc., Novartis AG, Genentech Inc., F. Hoffmann-La Roche Ltd., Incyte Corporation, Johnson & Johnson, AbbVie Inc., Bristol-Myers Squibb Company, AstraZeneca PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Erdheim-Chester Disease Market Emerging Trajectories
Histiocytosis treatment protocols are fragmenting across mutation status, organ involvement pattern, and prior therapy exposure, replacing empirical corticosteroid-based approaches with precision-matched therapeutic sequences.
Combination MEK-BRAF inhibition is migrating from salvage settings to front-line induction protocols for BRAF-mutant ECD. Academic medical centers in the United States and France are adopting concurrent dosing schedules that compress time-to-response metrics. This migration from sequential to parallel kinase blockade is compressing the window during which corticosteroid monotherapy remains standard-of-care.
EMA's pediatric investigation plan requirements are mandating age-appropriate formulation development for all novel histiocytosis drugs seeking European marketing authorization. The industrial consequence is expanded toxicology and pharmacokinetic burden for adult-predominant indications. Smaller biotechnology developers are responding by partnering with specialized formulation contractors rather than building in-house capabilities.
Hospital pharmacy and therapeutics committees are tightening prior authorization requirements for high-cost targeted therapies, replacing automatic approval with mutation confirmation and organ risk stratification documentation. This behavioral shift compresses prescribing autonomy for community oncologists and concentrates treatment initiation at centers with embedded molecular tumor boards. The pattern is most visible in United States integrated delivery networks where pharmacy benefit managers have implemented indication-specific prior authorization protocols.
Erdheim-Chester Disease Market Segmentation
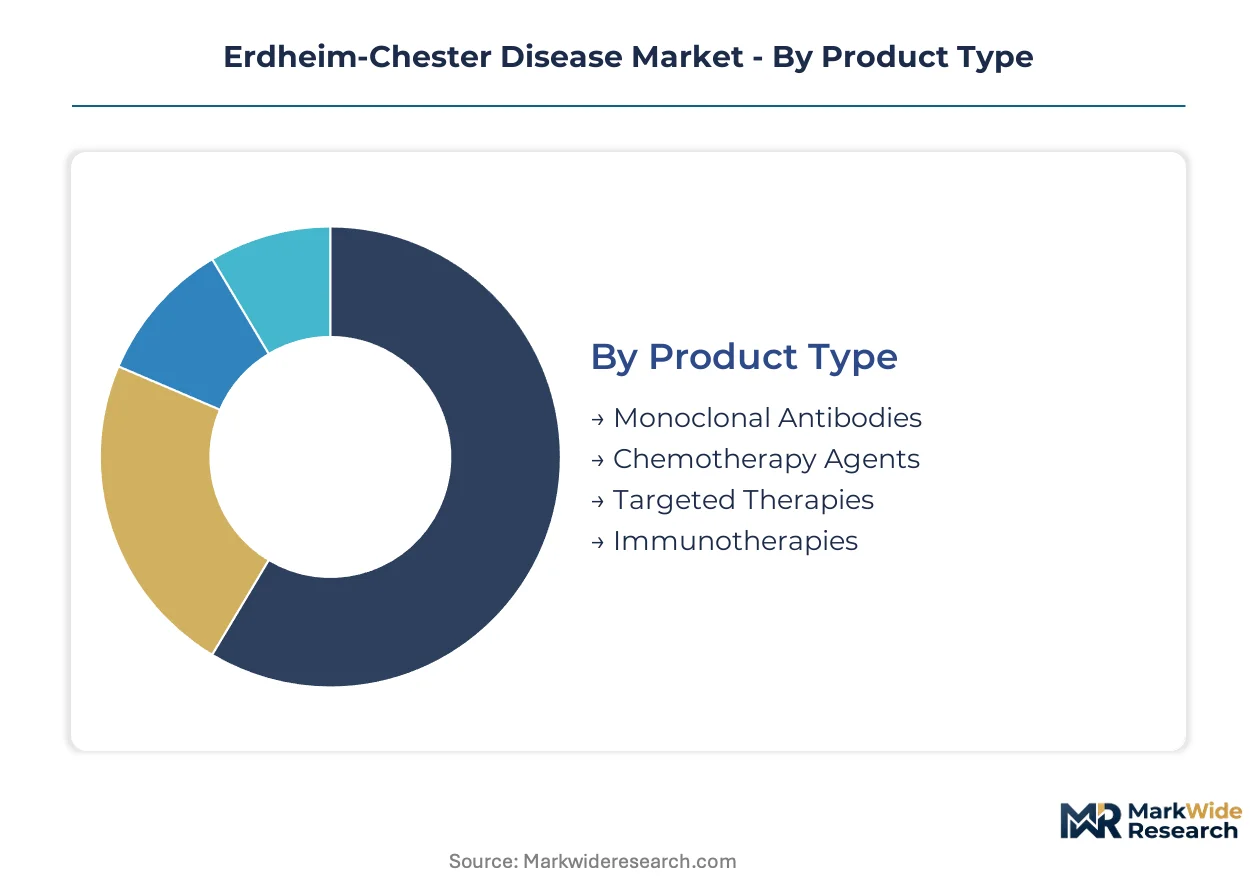
Precision segmentation in Erdheim-Chester Disease therapeutics determines reimbursement pathways, manufacturing scale decisions, and prescriber targeting strategies across ultra-rare indication economics. The mutation-driven treatment paradigm fragments commercial opportunity across modality, administration setting, and patient risk stratification variables.
Product Type:
Mature biologic platforms anchor current revenue while emerging modalities reshape first-line protocols through mechanism-of-action differentiation.
- Monoclonal Antibodies:Infusion-based biologics targeting CSF-1R and other histiocytic surface markers command premium positioning through orphan drug exclusivity and specialized administration infrastructure. Demand concentrates in United States academic medical centers where prior authorization pathways for high-cost biologics are most established.
- Targeted Therapies:Small-molecule BRAF and MEK inhibitors are displacing empirical corticosteroid approaches through mutation-matched efficacy data. France and United States referral networks are adopting combination kinase blockade as front-line induction, compressing time-to-response benchmarks against historical standards.
- Chemotherapy Agents:Cytotoxic salvage regimens retain utility in refractory, mutation-negative cases with aggressive organ involvement patterns.
- Immunotherapies:Checkpoint inhibitor trials in PD-1/PD-L1 refractory populations are concentrated at major referral institutions with embedded histiocytosis research programs.
Monoclonal antibodies handle the majority of throughput; targeted therapies are gaining share fastest as diagnostic testing infrastructure matures.
Delivery Mode:
Cost tier stratification separates hospital-dependent infusion services from self-administered oral alternatives that shift economic burden to pharmacy benefit structures.
- Intravenous:Infusion center administration captures the highest per-dose revenue through facility fees and nursing supervision requirements. United States hospital outpatient departments dominate this channel due to integrated prior authorization workflows.
- Oral:Kinase inhibitor tablets enable community oncology prescribing and reduce travel burden for patients with skeletal mobility limitations. Germany's outpatient specialty pharmacy networks are expanding oral oncology dispensing capacity to capture this shift.
- Subcutaneous:Self-injection formulations for select biologics are emerging through device-enabled delivery platforms that reduce infusion center dependency.
- Topical:Cutaneous lesion-directed therapy remains investigational with limited commercial penetration in histiocytosis indications.
Intravenous administration commands the premium pricing tier; oral delivery is climbing the fastest as combination targeted therapy protocols expand addressable prescriber bases.
End User:
Customer type concentration reflects where diagnostic complexity, treatment authorization, and toxicity monitoring capabilities co-locate.
- Hospitals:Integrated delivery networks with embedded molecular tumor boards control treatment initiation through mutation confirmation requirements and organ risk stratification protocols. United States health systems are tightening pharmacy and therapeutics committee oversight for high-cost histiocytosis therapies.
- Research Institutes:Academic medical centers with dedicated histiocytosis programs concentrate clinical trial enrollment and protocol refinement expertise. The United States hosts the highest density of such centers, creating referral gravity that shapes geographic access patterns.
- Clinics:Community oncology practices serve as diagnostic entry points with increasing reliance on telemedicine-enabled tumor board consultations for case triage.
- Homecare Settings:Oral therapy administration and remote monitoring protocols are expanding patient-managed care components for stable, responding patients.
Hospitals manage the majority of treatment initiations; research institutes are expanding fastest as clinical trial infrastructure attracts patient migration.
Formulation:
Supply concentration in sterile injectable manufacturing creates geographic dependencies that shape regional availability timelines.
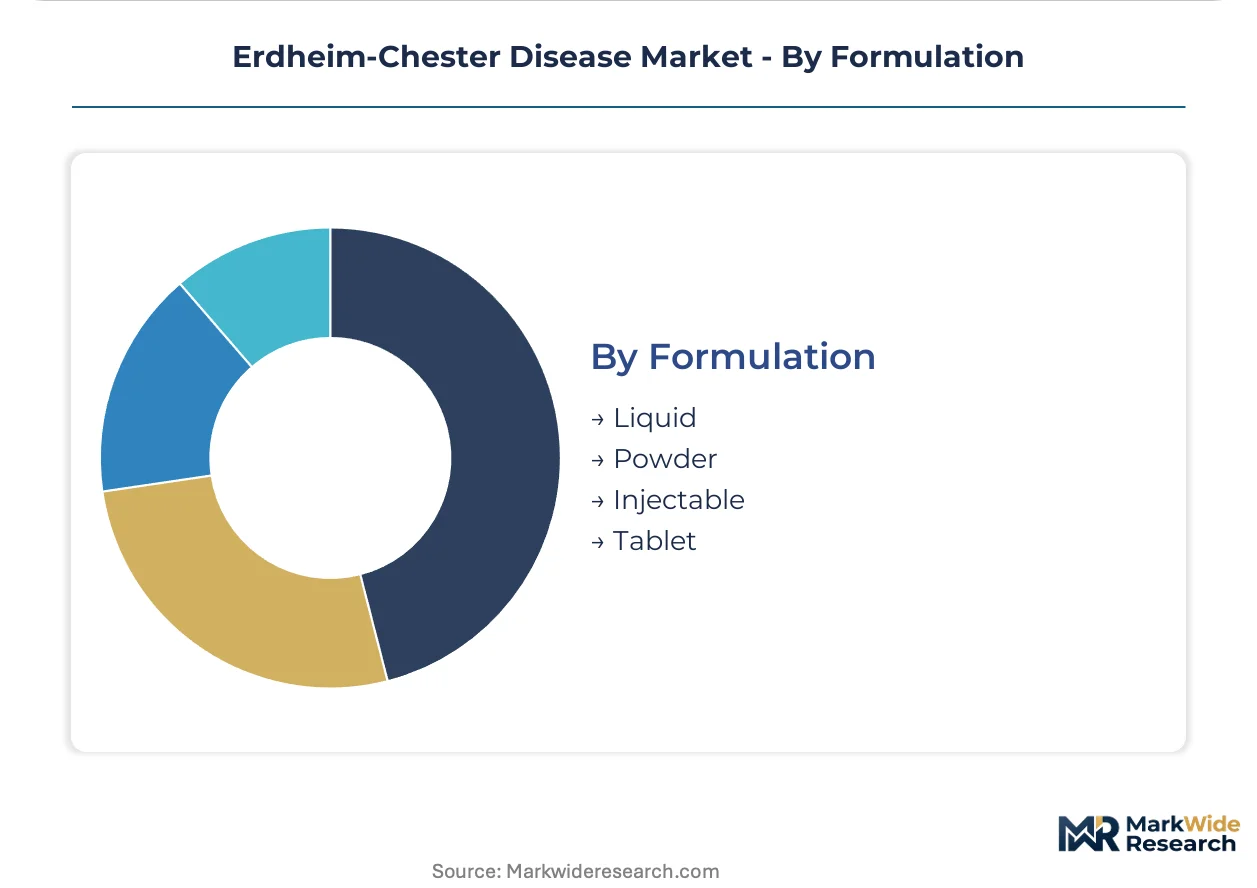
- Injectable:Sterile biologic formulations require specialized aseptic processing capacity concentrated in limited North American and European contract manufacturing organizations. Plasma-derived input dependencies expose this segment to fractionation capacity volatility.
- Liquid:Ready-to-use infusion solutions reduce pharmacy compounding burden in high-volume hospital settings.
- Powder:Lyophilized formulations extend shelf stability for distribution to lower-volume treatment centers with limited cold chain infrastructure.
- Tablet:Oral solid dosage forms enable decentralized dispensing through retail and specialty pharmacy channels.
Injectable formulations handle the majority of current volume; tablet formulations are expanding most quickly as oral targeted therapy protocols gain protocol adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States academic medical centers deploy mutation-directed protocols with the highest intensity globally, while European markets emphasize health technology assessment evidence thresholds that slow targeted therapy adoption despite comparable diagnostic infrastructure.
United States
FDA orphan drug tax credits concentrate biopharma investment in ultra-rare histiocytosis indications, with specialized treatment centers at Memorial Sloan Kettering and MD Anderson driving protocol refinement. The FDA's breakthrough therapy designation pathway accelerates BRAF inhibitor review timelines. Boston's Longwood Medical Area clusters histiocytosis pathology expertise that shortens diagnostic delays.
Germany
Outpatient specialty pharmacy networks expand oral oncology dispensing capacity for kinase inhibitor protocols. The country's national pharmaceutical regulator enforces stringent evidence standards through the Federal Joint Committee's benefit assessment process. Heidelberg and Berlin academic hospitals concentrate molecular tumor board capacity that determines targeted therapy access.
France
Reference center networks centralize ECD diagnosis through the National Rare Disease Plan, with Lyon and Paris hosting dedicated histiocytosis programs. ANSM's early access programs enable compassionate use of investigational targeted therapies. The Île-de-France region concentrates clinical trial enrollment for MEK-BRAF combination protocols.
Japan
PMDA's Sakigake designation pathway offers priority review for first-in-class histiocytosis entrants, attracting sponsor investment in Japanese clinical development. Tokyo and Osaka academic medical centers build BRAF V600E testing infrastructure that expands mutation-directed treatment eligibility. METI's regenerative medicine policies support advanced therapy development for refractory cases.
United Kingdom
NICE's highly specialized technologies program creates dedicated funding pathways for ultra-rare disease therapies. London's Royal Free Hospital and Oxford host histiocytosis referral networks that channel patients to molecularly matched trials. The MHRA's innovative licensing access pathway compresses time-to-market for combination kinase inhibitors.
Erdheim-Chester Disease Market Vendor Landscape
Capability concentration sits with specialized oncology divisions; scale advantage sits with diversified pharmaceutical conglomerates. The market structures around three tiers: established biopharma with orphan drug infrastructure, targeted therapy specialists with kinase inhibitor platforms, and immunotherapy developers with checkpoint inhibitor portfolios. Dominant competitive moves include strategic partnerships with academic medical centers for clinical trial access and portfolio diversification into combination regimen development.
Within the established biopharma tier, Pfizer Inc., Novartis AG, and Genentech Inc. occupy positions that exemplify divergent strategic archetypes. Pfizer represents scale-driven distribution reach across academic medical centers. Novartis anchors targeted therapy development programs in rare histiocytic disorders. Genentech exemplifies biomarker-driven patient stratification approaches that refine treatment eligibility criteria.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Novartis AG |
| Genentech Inc. |
| F. Hoffmann-La Roche Ltd. |
| Incyte Corporation |
| Johnson & Johnson |
| AbbVie Inc. |
| Bristol-Myers Squibb Company |
| AstraZeneca PLC |
| Others |
Supply Flow & Price Mechanics
Plasma fractionation capacity concentrated in the United States and Europe anchors monoclonal antibody production costs, concentrating margin capture downstream with hospital outpatient departments that command facility fees for infusion administration. This upstream bottleneck shapes where pharmaceutical pricing power accumulates across the Erdheim-Chester Disease therapeutic value chain.
Pricing Analysis
Long-term offtake agreements between academic medical centers and biopharma manufacturers dominate the contracting landscape for high-cost histiocytosis therapies, replacing spot purchasing with committed volume arrangements. Price differentiation rests on orphan drug exclusivity status and biomarker confirmation requirements, with mutation-negative cases facing steeper prior authorization scrutiny. Cost compression in the chemotherapy salvage tier is intensifying because checkpoint inhibitor off-label substitution erodes protocol adherence. Community oncology practices exhibit the highest price sensitivity due to thin margins on infused biologics, while integrated delivery networks leverage volume scale for preferential access terms.
Supply Chain Analysis
Tariff exposure between the United States and European Union threatens sterile injectable manufacturing economics for lyophilized biologic formulations. Active pharmaceutical ingredient production draws from Switzerland, Ireland, and Singapore for kinase inhibitor synthesis, while plasma-derived biologic inputs hinge on fractionation facilities in the United States and Germany. Single-source vulnerability pervades the contract manufacturing organization tier for aseptic fill-finish capacity. Distribution runs through hospital specialty pharmacy channels that capture administration margin through bundled reimbursement structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Erdheim-Chester Disease market is recovering from diagnostic infrastructure underinvestment as next-generation sequencing panel deployment accelerates patient identification and expands addressable treatment pools.
For Market Incumbents: Insulate orphan drug exclusivity positions through backward integration into companion diagnostic development, securing gatekeeper control over BRAF V600E testing workflows. Expand manufacturing capacity in Switzerland and Ireland to reduce exposure to plasma fractionation bottlenecks. Counter the checkpoint inhibitor substitution threat by embedding MEK-BRAF combination protocols in National Comprehensive Cancer Network guidelines. For New Entrants and Emerging Players: Establish a beachhead in Japan's Sakigake designation pathway, where PMDA priority review compresses regulatory timelines for first-in-class histiocytosis entrants. Target telemedicine-enabled referral networks as the most penetrable channel, partnering with virtual tumor board platforms to bypass geographic concentration barriers. Lead with oral kinase inhibitor formulations that shift prescribing autonomy toward community oncology. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed rare disease specialists holding Phase II checkpoint inhibitor data in refractory histiocytosis populations. Five-to-ten year viability hinges on successful navigation of EMA pediatric investigation plan requirements for adult-predominant indications. Watch for inflection in health technology assessment body acceptance of single-arm trial evidence as the signal for reimbursement risk recalibration.| Strategic Initiative | Industry Significance |
|---|---|
| MEK-BRAF Combination Protocol Development | Front-line positioning at Memorial Sloan Kettering and MD Anderson reshapes standard-of-care timelines. |
| Companion Diagnostic Co-Development | FDA breakthrough therapy designation pathways accelerate parallel review of drug-test combinations. |
| Japan Sakigake Designation Pursuit | PMDA priority review compresses time-to-market for mutation-directed histiocytosis entrants. |
| Telemedicine Tumor Board Partnership | Virtual referral networks erode geographic barriers to specialized histiocytosis center access. |
| Pediatric Formulation Investment | EMA pediatric investigation plan compliance enables European marketing authorization for adult-predominant drugs. |
Methodological Framework
A spread of perspectives from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers converged on the working assumptions underpinning this analysis. Primary interviews with payer access specialists and histiocytosis pathology subspecialists were cross-validated against FDA orphan drug designation filings, EMA submission documents, ClinicalTrials.gov records, and hospital procurement database extracts. Bottom-up patient pool estimates and top-down pharmaceutical revenue triangulation were reconciled through iterative sensitivity testing.
Demand-supply balance framing anchored the forecast framework, modeling patient diagnosis rates against manufacturing capacity constraints across the projection horizon. Segmentation dimensions included treatment line, administration route, mutation status, and regional regulatory cluster. CAGRs were derived from epidemiological trend extrapolation and therapy adoption curve analysis. Forecast inputs incorporated BRAF V600E testing penetration rates and prior authorization approval velocity by integrated delivery network type.
Stress conditions across plasma fractionation capacity utilization, single-arm trial evidence acceptance thresholds, and checkpoint inhibitor off-label substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about diagnostic infrastructure buildout and regulatory pathway timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Zellweger Spectrum Disorders Market
Rare Diseases
Canavan Disease Treatment Market
Rare Diseases
Pure Red Cell Aplasia Market
Rare Diseases
Global Neuromyelitis Optica Spectrum Disorder Market
Rare Diseases
Global Hereditary Angioedema Treatment Market
Rare Diseases
Aicardi Syndrome Market
Rare Diseases
Hairy Cell Leukemia Market
Rare Diseases
Creutzfeldt-Jakob Disease (CJD) Market
Rare Diseases
Global Gaucher Disease Market
Rare Diseases
Batten Disease Market
Rare Diseases
Churg Strauss Syndrome Market
Rare Diseases
Rosai-Dorfman Disease (RDD) Therapeutics Market
Rare Diseases
Malignant Infantile Osteopetrosis Market
Rare Diseases
Menkes Syndrome Market
Rare Diseases
Cowden Syndrome Market
Rare Diseases
Europe Down Syndrome Market